
 Global Health Caregiving Market | 2026-2036
Global Health Caregiving Market Size, Share, and Industry Trends Forecast 2026-2036
Global Health Caregiving Market Foresight
Modular service bundling is realigning how families and payers purchase caregiving, unbundling traditional full-time live-in packages into discrete blocks for medication management, mobility assistance, and social engagement. Honor Technology, Inc. leverages its technology platform to match caregivers with specific skill sets to individual client needs. Bayada Home Health Care anchors its competitive position through geographic density in key metropolitan corridors. Care.com, Inc. competes by offering transparent pricing and background-verified caregiver pools that reduce household search costs.
Health caregiving encompasses the organized provision of medical and non-medical support services to individuals requiring assistance with activities of daily living, typically delivered through regulated care plans with documented clinical protocols and scheduled wellness checks. Its primary commercial purpose is to substitute institutional care with supervised community-based or residential alternatives that reduce acute care utilization. In-Home Assistance commands the largest service volume due to persistent consumer preference for aging in place, while Remote Monitoring and Wearable Devices within Technology Utilization represent the fastest-expanding margin pools as insurers integrate biometric data into risk-adjusted payment models. Palliative Care and Companionship Services remain comparatively mature segments with slower growth but stable reimbursement profiles.
FDA digital health software guidance, EMA medical device regulations for wearable diagnostics, and Japan's METI standards for telecare interoperability collectively shape product development pathways and cross-border market access conditions for technology-enabled caregiving platforms. HIPAA compliance requirements in the United States and GDPR data protection rules in Europe constrain how caregiver platforms aggregate and share client health records across distributed networks. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring and decide whether to build proprietary compliance infrastructure or rely on third-party certification pathways.
Market Dynamics
Caregiver workforce shortages across developed economies are forcing rapid substitution toward technology-mediated care models, with biometric monitoring and algorithmic matching platforms compressing traditional agency structures.
Growth Catalysts
- Japan METI Telecare Standards:Interoperability mandates accelerate cross-platform data exchange, enabling seamless handoffs between hospital discharge and home-based monitoring networks.
- Geriatric Patient Preference:Aging cohorts in the United States and Germany resist institutionalization, sustaining demand for supervised in-home alternatives with documented clinical protocols.
- Wearable Diagnostics:Continuous glucose monitors and fall-detection sensors generate real-time biometric streams that insurers integrate into risk-adjusted payment models.
Market Restraints
- Caregiver Supply Concentration:Licensed nursing assistants cluster in metropolitan corridors, leaving rural and exurban markets chronically underserved despite reimbursement parity.
- GDPR-HIPAA Compliance Friction:Cross-border data flows between European and North American platforms require redundant infrastructure, elevating fixed costs for multi-territory operators.
- Substitution by Family Informal Care:Unpaid household caregivers absorb demand during economic downturns, compressing formal service volumes in price-sensitive segments.
Strategic Opportunities
- India Home Care Penetration:Urban middle-class expansion and nuclear family fragmentation create addressable demand for professional caregiving in Mumbai, Bangalore, and Delhi corridors.
- Remote Patient Monitoring Reimbursement Codes:Medicare CPT code expansions in the United States reimburse biometric data review, converting technology costs into billable clinical services.
- AI-Voice Interface Convergence:Natural language processing layered atop ambient sensors enables passive wellness monitoring without wearable compliance dependencies.
Industry Challenges
- Certified Nursing Assistant Pipeline Collapse:Training program completions lag attrition by double-digit margins in Texas, Florida, and California, forcing wage spirals that erode agency margins.
- EMR Integration Complexity:Home care platforms struggle to synchronize documentation with hospital Epic and Cerner instances, creating care continuity gaps and audit exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Health Caregiving Market |
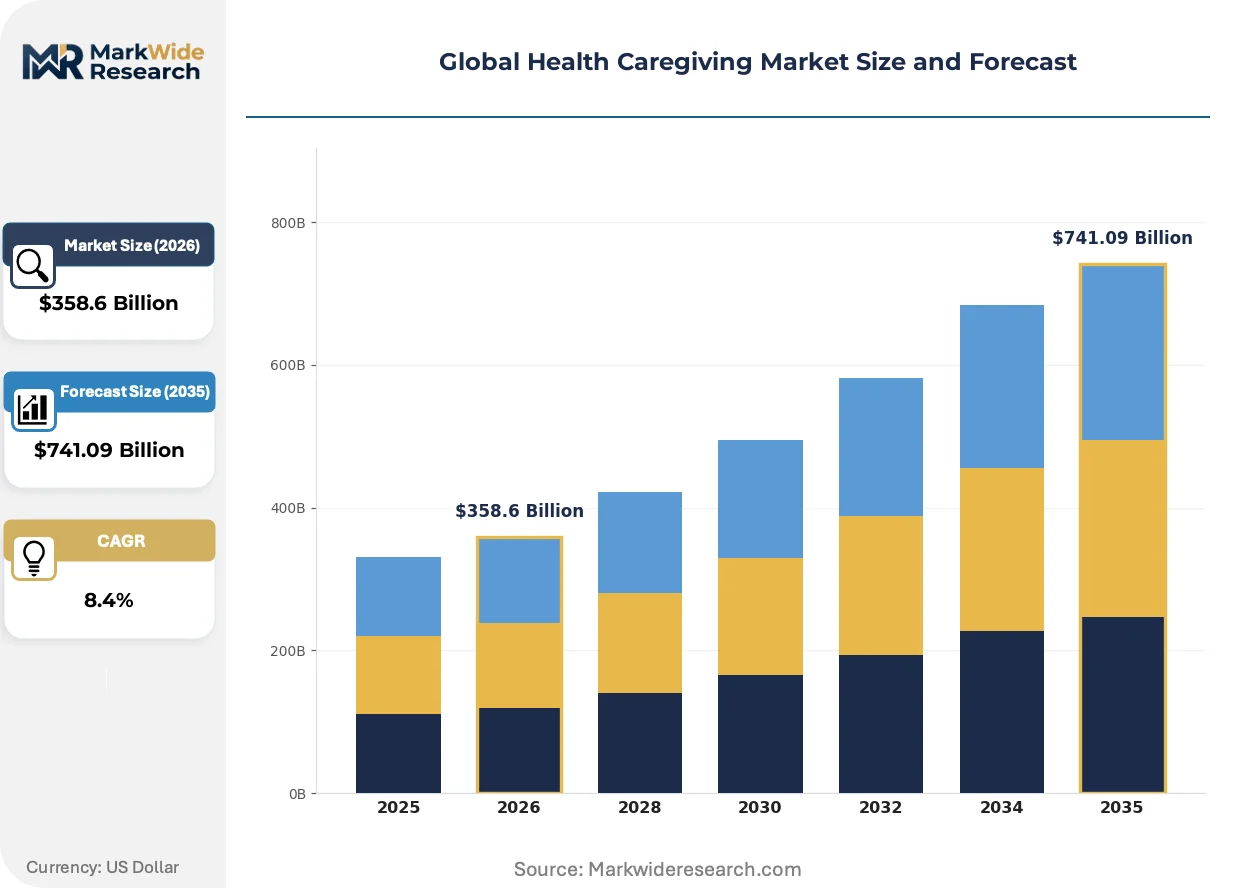
| Market Size in 2026 | $358.6 Billion |
| Market Size in 2035 | $741.09 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-Home Assistance, Palliative Care, Rehabilitation Support, Companionship Services, Adult Day Care Client Type: Geriatric Patients, Disabled Individuals, Postoperative Patients, Chronic Disease Cases, Terminally Ill Caregiver Role: Professional Nurses, Family Caregivers, Social Workers, Certified Nursing Assistants, Volunteer Aides Technology Utilization: Remote Monitoring, Mobile Health Apps, Wearable Devices, Electronic Health Records, Telecare Systems |
| Companies Covered | Honor Technology, Inc., Vesta Healthcare, Seniorlink, Inc., Cariloop, Inc., Care.com, Inc., HomeHero, Inc., UnaliWear, Inc., CareLinx, Inc., Bayada Home Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Health Caregiving Market Shifts & Advancements
Algorithmic workforce platforms are restructuring how care hours are sourced, scheduled, and quality-assured, displacing traditional branch-office staffing models with dynamic marketplace architectures.
Passive radar and millimeter-wave occupancy sensors are electrifying fall detection by eliminating wearable compliance dependencies. Medicare Advantage plans in Arizona and Pennsylvania pilot these installations in member households. The technology is electrifying competitive positioning for payers seeking to reduce emergency department utilization among high-risk enrollees.
EMA Medical Device Regulation (MDR) recertification timelines for wearable diagnostics compress product launch windows and elevate clinical evidence requirements. European home care technology vendors redirect R&D toward predicate device pathways rather than novel hardware submissions. Germany and France see delayed market entry for next-generation continuous monitoring patches as notified body backlogs extend.
Households increasingly unbundle care packages into discrete service blocks rather than purchasing comprehensive live-in arrangements. Platform marketplaces displace traditional agency relationship models in suburban United States markets where adult children coordinate care remotely. This pattern concentrates in tech-forward metropolitan clusters where smartphone penetration among family decision-makers exceeds ninety percent.
Global Health Caregiving Market Segmentation
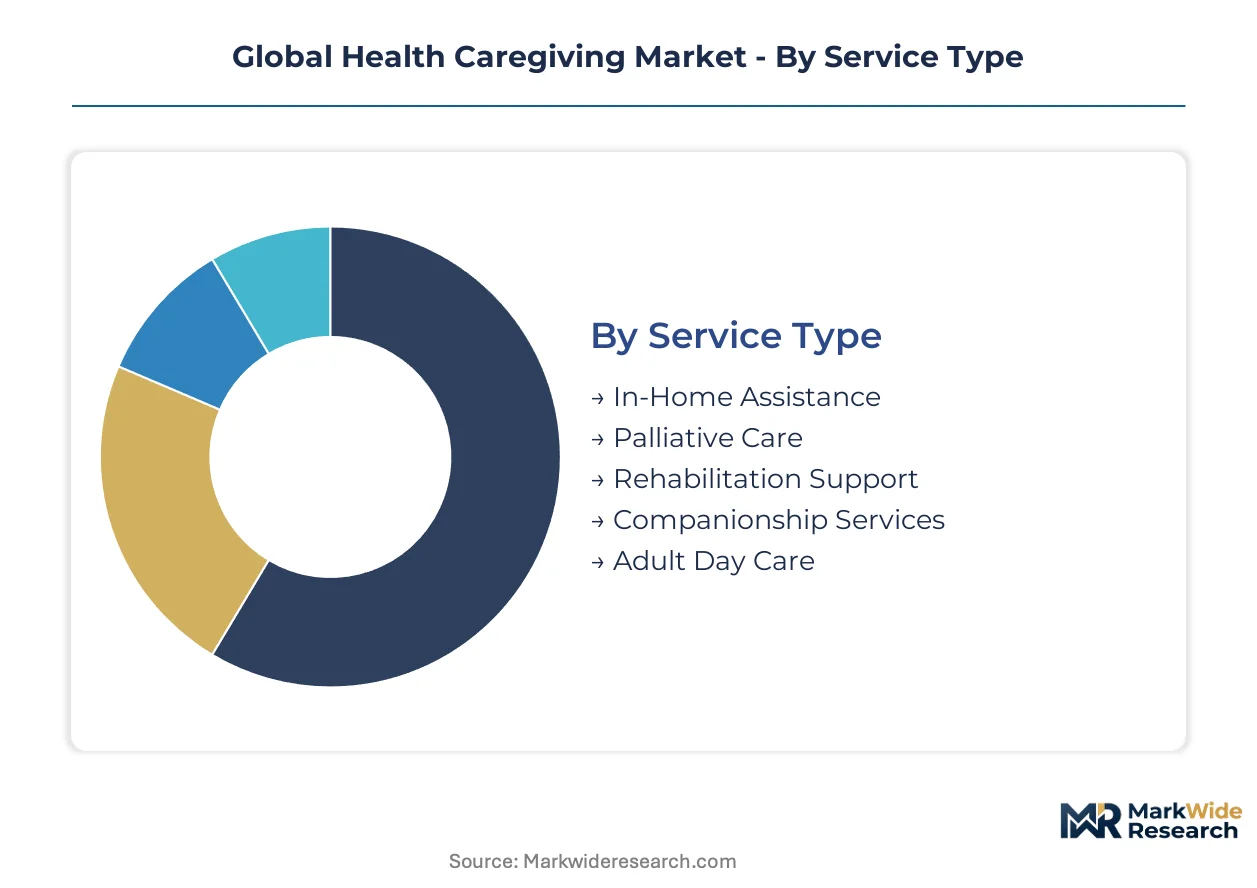
Segmentation in health caregiving reveals how service delivery fragments across care settings, patient acuity levels, and technology integration depth. Understanding these divisions exposes where margin pools concentrate and which configurations attract capital deployment.
Service Type:
Integration depth varies sharply across service categories, with some functioning as standalone revenue lines and others embedding within broader care continuums.
- In-Home Assistance:Encompasses medication management, mobility support, and activities of daily living delivered in residential settings. Demand clusters in suburban United States markets where aging homeowners resist facility relocation; reimbursement reforms in Germany and Japan accelerate formal substitution for informal family care.
- Palliative Care:Specialized symptom management and psychosocial support for serious illness, typically requiring physician oversight and documented care protocols. Hospice benefit expansions in Medicare and parallel programs in France and Australia sustain volume, though workforce certification bottlenecks constrain supply.
- Rehabilitation Support:Post-acute therapy and functional recovery services bridging hospital discharge to community reintegration.
- Companionship Services:Non-medical social engagement and supervision, often privately paid and falling outside regulated clinical frameworks.
- Adult Day Care:Structured daytime programming providing respite for family caregivers while delivering supervised activities and health monitoring.
Volume placements concentrate in In-Home Assistance; the faster expansion belongs to Palliative Care as payers seek cost-effective alternatives to repeated hospitalization.
Client Type:
Cost tier stratification separates acute-episode reimbursement from longitudinal chronic management and privately financed end-of-life support.
- Geriatric Patients:Adults aged 65+ requiring assistance with functional decline, polypharmacy coordination, and fall prevention. Japan's super-aged demographics and similar cohort shifts in Italy and South Korea concentrate demand; METI telecare standards enable technology-mediated monitoring at scale.
- Chronic Disease Cases:Individuals with diabetes, heart failure, or COPD needing ongoing symptom surveillance and care plan adherence. Remote patient monitoring CPT codes in United States Medicare convert biometric data review into billable services, attracting platform investment.
- Disabled Individuals:Working-age adults with physical or cognitive impairments requiring sustained personal assistance.
- Postoperative Patients:Short-term recovery support following surgical discharge, increasingly shifted from skilled nursing facilities to home settings under bundled payment pressures.
- Terminally Ill:End-of-life patients eligible for hospice benefits or privately financed comfort-focused care.
Revenue gravity sits with Geriatric Patients; Chronic Disease Cases are climbing the fastest as insurers integrate biometric streams into risk-adjusted contracts.
Caregiver Role:
Supply concentration and regulatory burden differentiate licensed clinical labor from informal and volunteer contributions.
- Certified Nursing Assistants:State-licensed paraprofessionals delivering hands-on personal care under nurse supervision. Training program completions lag attrition by double-digit margins in Texas, Florida, and California, forcing wage spirals that erode agency margins.
- Professional Nurses:Registered and licensed practical nurses executing clinical protocols, medication administration, and care coordination. Licensure reciprocity limitations between United States states and European Union member countries fragment workforce mobility.
- Family Caregivers:Unpaid household members absorbing demand during economic downturns, compressing formal service volumes in price-sensitive segments.
- Social Workers:Licensed professionals addressing psychosocial needs, care transitions, and resource navigation.
- Volunteer Aides:Community-based unpaid support providing companionship and light assistance, common in hospice and faith-based programs.
Headcount dominance belongs to Certified Nursing Assistants; Professional Nurses command the steepest expansion trajectory as acuity shifts toward home.
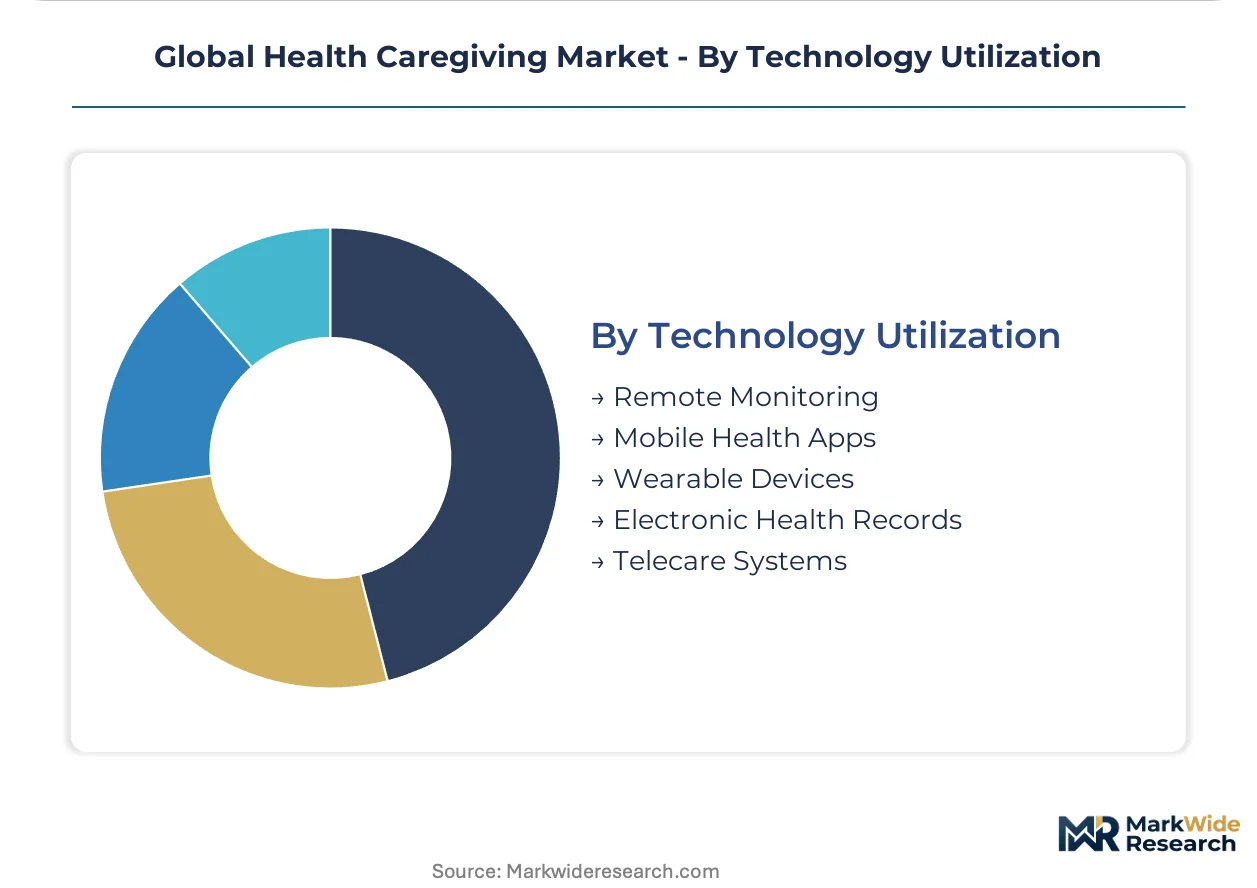
Technology Utilization:
Maturity gradients separate established documentation systems from emerging biometric and ambient monitoring modalities.
- Remote Monitoring:Continuous or periodic physiological data transmission enabling clinical oversight without physical presence. Medicare Advantage plans in Arizona and Pennsylvania pilot passive radar fall detection; EMA MDR recertification timelines compress European launch windows for next-generation patches.
- Wearable Devices:Consumer and medical-grade sensors capturing activity, sleep, glucose, or cardiac rhythm. GDPR-HIPAA compliance friction elevates fixed costs for multi-territory operators deploying cross-border data infrastructure.
- Telecare Systems:Integrated communication platforms connecting patients, caregivers, and clinicians.
- Mobile Health Apps:Smartphone-based tools for scheduling, medication reminders, and care coordination.
- Electronic Health Records:Digital documentation systems struggling to synchronize with hospital Epic and Cerner instances, creating care continuity gaps.
Deployment scale favors Electronic Health Records; Wearable Devices and Remote Monitoring together represent the fastest-expanding margin pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caregiving service production concentrates in metropolitan corridors where licensed workforce pools sustain agency operations, while consumption spreads across aging suburban and rural territories where informal family care still dominates formal substitution patterns.
United States
Medicare Advantage plans in Arizona and Pennsylvania pilot passive radar fall detection installations to reduce emergency department utilization among high-risk enrollees. HIPAA compliance requirements constrain how caregiver platforms aggregate and share client health records across distributed networks. The Southeast corridor spanning Florida and Georgia experiences severe certified nursing assistant pipeline collapse, with training program completions lagging attrition by double-digit margins.
Germany
Reimbursement reforms accelerate formal care substitution for informal family care as aging cohorts resist institutionalization. EMA Medical Device Regulation recertification timelines compress product launch windows for wearable diagnostics, elevating clinical evidence requirements. The Rhine-Ruhr metropolitan region sees delayed market entry for next-generation continuous monitoring patches as notified body backlogs extend.
Japan
Super-aged demographics concentrate demand for technology-mediated monitoring at scale. METI telecare standards mandate interoperability across platforms, enabling seamless handoffs between hospital discharge and home-based monitoring networks. The Kanto region surrounding Tokyo anchors service delivery innovation as platform vendors align with national telecare infrastructure requirements.
India
Urban middle-class expansion and nuclear family fragmentation create addressable demand for professional caregiving in Mumbai, Bangalore, and Delhi corridors. The country's national pharmaceutical regulator oversees quality standards for imported medical devices used in home care settings. Maharashtra and Karnataka states lead private home care agency formation as metropolitan hospital capacity strains under chronic disease management burdens.
United Kingdom
GDPR data protection rules constrain cross-border data flows between European and North American platforms, elevating fixed costs for multi-territory operators. The National Health Service pushes post-acute recovery support from skilled nursing facilities toward home settings under bundled payment pressures. Greater London and the Southeast corridor concentrate technology-enabled care coordination platforms serving aging homeowners.
Global Health Caregiving Market Competitive Landscape
The competitive structure tilts toward technology-mediated marketplace platforms over traditional branch-office agency models. Algorithmic workforce matching and biometric monitoring capabilities separate scalable operators from geographic density players. Two strategic archetypes dominate: dynamic marketplace platforms unbundling service packages into discrete blocks, and established agencies anchoring metropolitan corridors through licensed workforce concentration. Competitive moves center on M&A to acquire geographic density and strategic partnerships to integrate remote monitoring reimbursement codes.
Within the technology platform tier, Honor Technology, Inc. and Care.com, Inc. exemplify marketplace architectures that reduce household search costs through algorithmic matching and transparent pricing mechanisms. Bayada Home Health Care anchors a position among established agencies competing through geographic density in key metropolitan corridors. These three companies represent the spectrum from unbundled digital marketplaces to traditional workforce-intensive service delivery models.
| Leading Market Players |
|---|
| Honor Technology, Inc. |
| Vesta Healthcare |
| Seniorlink, Inc. |
| Cariloop, Inc. |
| Care.com, Inc. |
| HomeHero, Inc. |
| UnaliWear, Inc. |
| CareLinx, Inc. |
| Bayada Home Health Care |
| Others |
Supply & Pricing Matrix
FDA digital health software guidance gates qualified supply and premium-tier pricing access for technology-enabled caregiving platforms, separating HIPAA-compliant infrastructure investments from commodity service providers. Reimbursement code expansions for remote patient monitoring reward certified clinical documentation systems with billable service premiums, while non-compliant agencies absorb cost-down pressure from payers.
Pricing Analysis
Margin tightening in standard-tier personal care reflects certified nursing assistant wage spirals in Texas, Florida, and California. Three-tier pricing structure across premium, standard, and economy levels separates technology-integrated care plans from basic companionship and unskilled labor. Price differentiation traces to HIPAA certification grade and geographic density of licensed workforce pools. Family caregivers absorb demand during economic softness, making privately paid companionship segments most price-sensitive while Medicare-reimbursed clinical services show inelasticity.
Supply Chain Analysis
Biometric sensor supply rests on Taiwanese semiconductor foundries, South Korean display manufacturers, and Chinese battery cell producers for wearable diagnostics. Raw material dependencies include lithium-ion cells, millimeter-wave radar components, and medical-grade adhesives for continuous monitoring patches. Single-source vulnerability concentrates in EMA-notified body certification backlogs delaying European market entry. Distribution runs through Medicare Advantage plan procurement channels, hospital discharge coordination networks, and direct-to-household platform marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
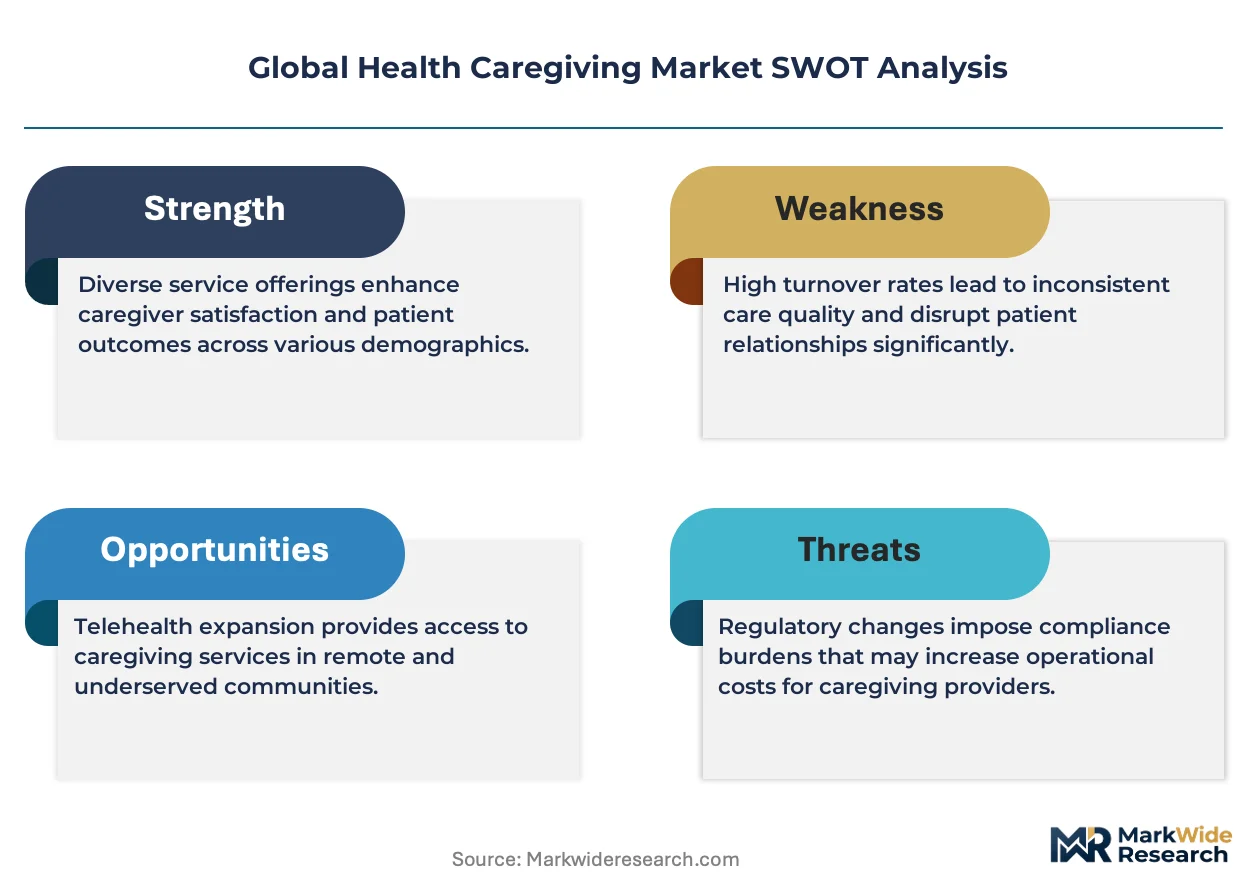
This market reads as a cost-of-compliance story where HIPAA and GDPR infrastructure investments create barrier-to-entry moats for platforms with certified cross-border data architectures.
For Market Incumbents: Extend geographic density in metropolitan corridors through certified nursing assistant pipeline partnerships with community colleges. Acquire remote monitoring reimbursement expertise to convert technology costs into billable clinical services before algorithmic matching platforms erode branch-office margins. For New Entrants and Emerging Players: Begin with India urban corridors where nuclear family fragmentation and hospital capacity strain create professional caregiving white space. Target Mumbai and Bangalore middle-class households with transparent pricing platforms that reduce household search costs for post-acute recovery support. For Investors and Strategic Acquirers: Medicare CPT code expansions for biometric data review are the leading indicator that technology-enabled care coordination platforms will capture margin pools from traditional agency models. Prioritize acquisition targets with proprietary HIPAA-GDPR compliance infrastructure and established hospital EMR integration pathways. Watch EMA MDR recertification timeline resolutions as the signal for European wearable diagnostics market entry windows.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Medicare CPT code alignment converts remote monitoring technology costs into billable clinical services. |
| Hospital System Partnership | Epic and Cerner EMR integration closes care continuity gaps and reduces audit exposure for platforms. |
| Software Companion Development | AI-voice interfaces atop ambient sensors enable passive wellness monitoring without wearable compliance. |
| CE Marking Pathway | EMA MDR predicate device pathways accelerate European market entry amid notified body backlogs. |
| Geographic Expansion | India metropolitan corridor penetration captures nuclear family fragmentation demand before competitors consolidate. |
Research Methodology
CMS Medicare reimbursement databases, FDA 510(k) filings, and EMA medical device registration records formed the secondary backbone for market sizing and regulatory pathway mapping. Primary interviews with home health agency executives, Medicare Advantage plan medical directors, biomedical engineers at wearable device manufacturers, and GPO contracts managers validated service volume estimates and pricing dynamics. Bottom-up facility counts and top-down payer expenditure data were triangulated across the analysis window.
Historical trendline analysis of certified nursing assistant training completions, Medicare home health spending patterns, and technology platform funding rounds established baseline growth trajectories. The forecast framework modeled service type, client acuity tier, caregiver licensure level, and technology integration depth across the projection horizon. CAGR derivation incorporated METI telecare standard adoption curves, HIPAA-GDPR compliance cost trajectories, and biometric sensor price erosion assumptions.
Underlying measurement precision varies by segment; remote monitoring and wearable device revenue pools carry tighter precision than informal family care substitution estimates. Forecasts reflect assumptions around reimbursement code stability, workforce pipeline recovery, and cross-border data infrastructure deployment timelines. Caregiver supply concentration, EMA notified body capacity, and Medicare Advantage plan technology adoption rates warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
House Call Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Home Healthcare Market
Home Healthcare
Smart Pillow Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Global Home Infusion Therapy Market
Home Healthcare
Adult Day Care Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
Home Care Products Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
Smart Home Healthcare Market