
 US Home Infusion Therapy Market | 2026-2036
US Home Infusion Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
US Home Infusion Therapy Market Analysis
Hospital-to-home discharge channels is tilting toward specialized infusion networks that coordinate pharmacy compounding, nursing deployment, and remote monitoring in a single contract. Option Care Health Inc. anchors this shift through national scale and payer direct contracting. KabaFusion competes on oncology and rare-disease specialty protocols. Coram CVS Health leverages retail pharmacy density to extend last-mile logistics into patient homes.
Home infusion therapy encompasses the administration of medications, nutrients, or fluids directly into a patient's bloodstream through intravenous or subcutaneous routes outside acute-care facilities, typically requiring sterile compounding, pump-controlled flow rates between 0.1 and 999 mL per hour, and clinical monitoring for adverse reactions. Its primary purpose is to deliver complex biologics, antibiotics, and nutrition support that would otherwise require extended hospitalization. IV antibiotics occupies the largest volume share due to recurrent infection management in immunocompromised populations. Infusion pumps generates the steepest technology margin pool as smart pump connectivity and dose-error reduction software command premium pricing. Automated infusion is displacing manual and gravity-fed methods in high-acuity protocols where precise titration prevents readmission.
FDA 503B compounding standards, CMS home health prospective payment rules, and state board of pharmacy licensure requirements collectively determine which providers can compound sterile preparations and bill for in-home nursing supervision. HIPAA compliance for remote patient monitoring data and OSHA bloodborne pathogen standards add operational cost layers that favor scaled platforms over independent operators. Stakeholders must monitor whether CMS expands hospital-at-home waiver authority beyond the current demonstration period, as this single policy lever would reallocate substantial inpatient infusion volume to home settings.
Market Dynamics
CMS hospital-at-home waiver authority is reallocating inpatient infusion volume toward residential settings, forcing providers to integrate pharmacy compounding, nursing deployment, and remote monitoring under unified risk contracts.
Growth Catalysts
- FDA 503B compounding standards:Federal oversight of sterile preparation facilities has consolidated outsourcing capacity among accredited 503B pharmacies, reducing contamination risk and expanding eligible medication categories for home administration.
- Texas-Florida-California corridor:Concentrated aging demographics and mature home health infrastructure in these three states generate disproportionate referral volumes for antibiotic and biologic infusion protocols.
- Smart pump connectivity:Wireless dose-error reduction software embedded in ambulatory infusion devices enables real-time clinician oversight and reduces adverse event liability for payers.
Market Restraints
- Specialized nursing labor scarcity:Competency requirements for sterile technique, vascular access maintenance, and adverse reaction management limit the pool of deployable clinicians below demand growth in rural service territories.
- Reimbursement compression:CMS home health prospective payment rules impose fixed episode-based rates that compress margins on high-acuity protocols requiring extended nursing supervision hours.
- Biologic cold chain fragility:Temperature excursions during last-mile logistics invalidate compounded monoclonal antibody preparations, creating waste costs that independent operators cannot absorb at scale.
Strategic Opportunities
- Medicare Advantage penetration:Capitated plans in Florida and Arizona are expanding hospital-at-home benefit carve-outs, creating direct contracting opportunities outside traditional fee-for-service channels.
- Subcutaneous formulation migration:Pharmaceutical manufacturers are developing alternate delivery routes for IV biologics, enabling patient self-administration and reducing nursing dependency for maintenance dosing.
- Remote patient monitoring integration:HIPAA-compliant biometric streaming from infusion pumps to centralized command centers enables 24/7 oversight without continuous bedside presence.
Industry Challenges
- Multi-state licensure complexity:Pharmacist-in-charge credentials and nursing board reciprocity requirements create operational friction for platforms seeking contiguous geographic expansion.
- Legacy EHR interoperability:Home infusion documentation systems lack standardized APIs with acute-care discharge platforms, forcing manual data re-entry and delaying care initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Home Infusion Therapy Market |
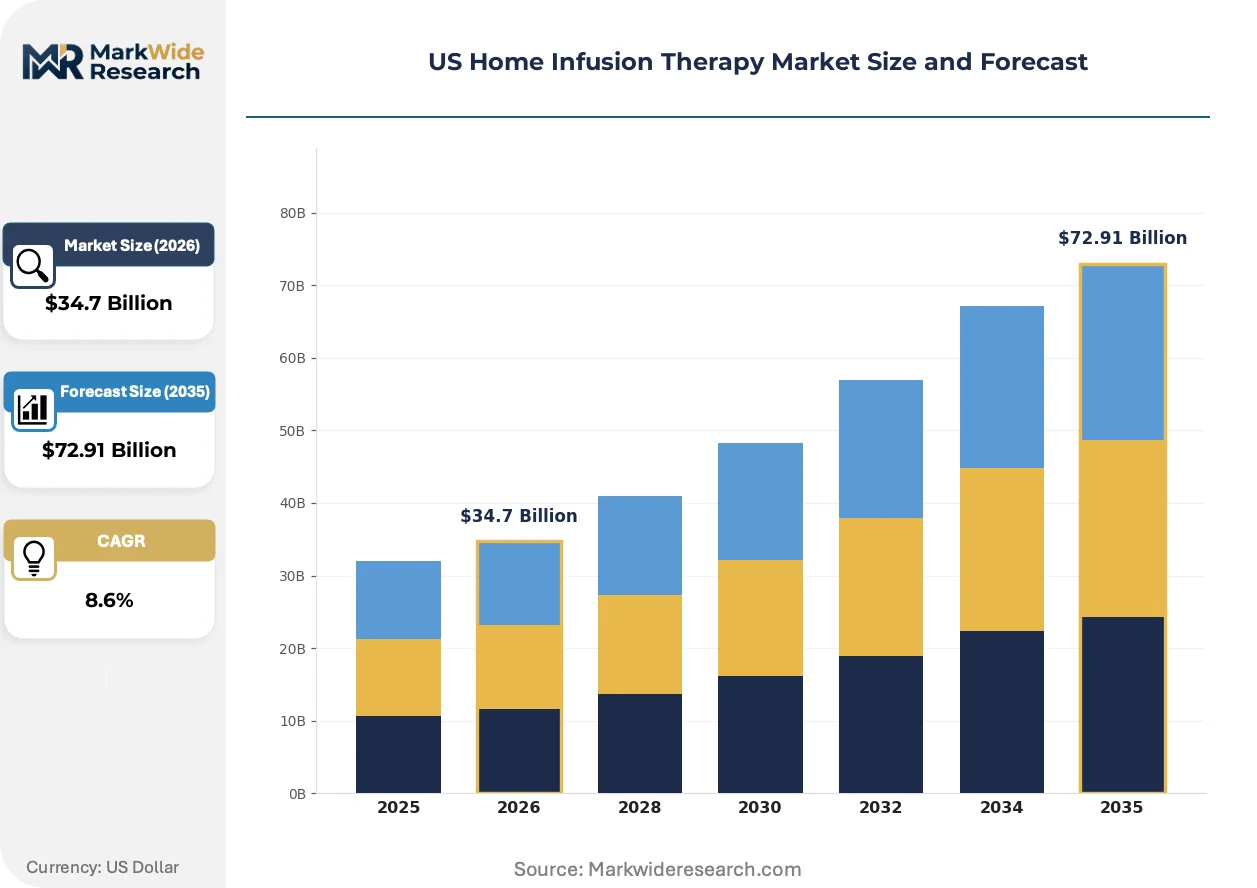
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
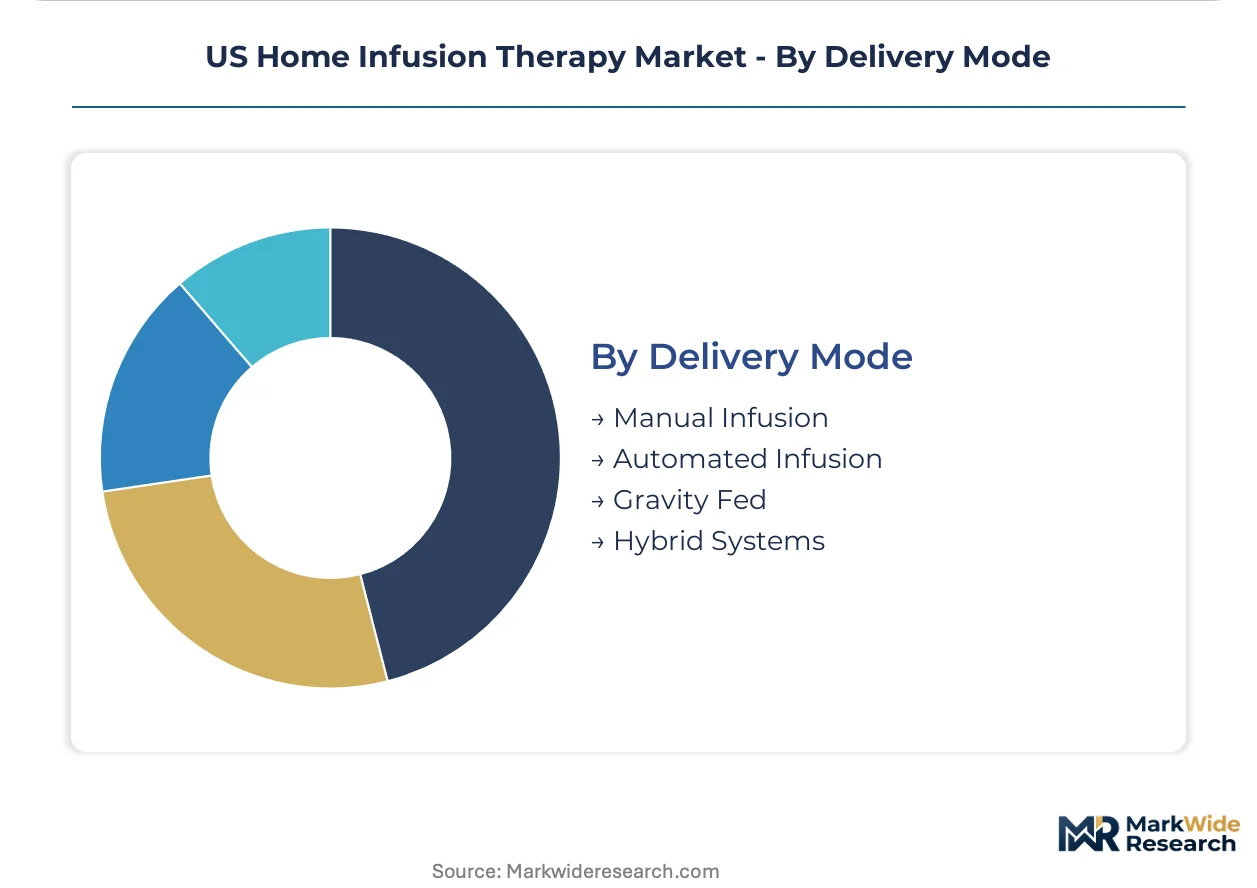
| Segmentation | Product Type: IV Antibiotics, Hormonal Therapies, Enteral Nutrition, Pain Management Technology: Infusion Pumps, Catheters, Portable Systems, Consumables End User: Patients at Home, Home Healthcare Providers, Family Caregivers, Nursing Services Delivery Mode: Manual Infusion, Automated Infusion, Gravity Fed, Hybrid Systems |
| Companies Covered | KabaFusion, B. Braun Medical, Option Care Health Inc., Becton Dickinson and Company, ICU Medical Inc., Optum Inc., Baxter International Inc., Coram CVS Health, CVS Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Home Infusion Therapy Market Emerging Trajectories
Technology convergence, regulatory recalibration, and payer contracting redesign are compressing the traditional hospital-to-home discharge timeline and redefining provider accountability for outcomes.
Smart infusion pump architecture is hybridizing mechanical precision with cloud-based dose-error analytics. Hospital-at-home programs in Arizona and Nevada are deploying these connected devices for high-risk antibiotic and parenteral nutrition protocols. The technology is hybridizing hardware reliability with software-defined safety nets that reduce readmission exposure for risk-bearing entities.
CMS demonstration authority for acute hospital care at home is reshaping site-of-service economics. Eligible conditions now include infusion-dependent infections and exacerbated chronic conditions previously requiring inpatient stays. Texas and Florida Medicaid managed care plans are piloting carve-out contracts with specialized infusion networks to capture shared savings from avoided bed days.
Payers are consolidating vendor panels around outcome guarantees rather than per-visit reimbursement. Medicare Advantage organizations in California are requiring infusion providers to assume readmission risk for 30-day episodes. This concentrates volume among platforms with integrated pharmacy-nursing-remote monitoring capabilities and marginalizes single-service operators.
US Home Infusion Therapy Market Segmentation
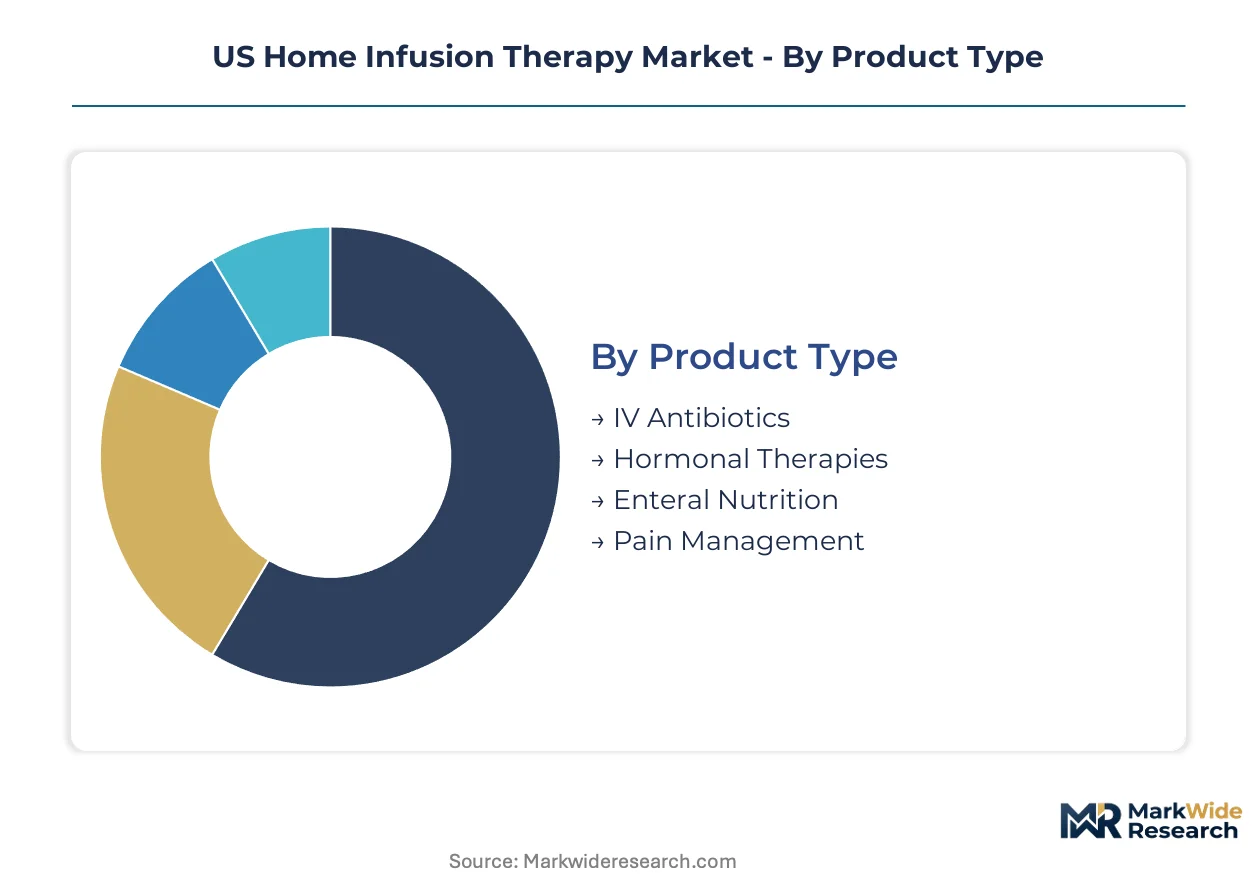
Segmentation in US home infusion therapy reveals how service intensity, device complexity, and care coordination requirements vary across patient populations. Each dimension shapes capital deployment, staffing models, and reimbursement capture differently.
Product Type:
After-sales service intensity varies sharply across therapeutic categories, with biologics requiring cold chain monitoring and antibiotic protocols demanding 24/7 nursing hotlines.
- IV Antibiotics:Broad-spectrum and targeted antimicrobial agents delivered via peripheral or central venous access for infection management in immunocompromised patients. Texas, Florida, and California generate concentrated referral volumes from oncology centers and transplant programs managing recurrent sepsis. Demand concentrates where hospital-at-home waivers have expanded eligible patient pools.
- Hormonal Therapies:Parenteral endocrine replacement and suppression protocols including testosterone, estrogen, and growth hormone formulations requiring precise titration schedules. Growth pace accelerates in Medicare Advantage plans covering gender-affirming and age-related hormone protocols.
- Enteral Nutrition:Liquid nutrient formulations delivered via nasogastric, gastrostomy, or jejunostomy tubes for patients with compromised gastrointestinal function.
- Pain Management:Opioid and non-opioid analgesic infusions including patient-controlled analgesia for palliative and chronic pain populations.
By volume, IV Antibiotics leads. By growth pace, Hormonal Therapies is expanding most quickly.
Technology:
Capital intensity and software dependency distinguish technology tiers, with connected devices commanding premium procurement budgets and multi-year service contracts.
- Infusion Pumps:Electromechanical devices controlling flow rates between 0.1 and 999 mL per hour with dose-error reduction software and wireless connectivity to centralized monitoring platforms. Smart pump adoption concentrates in hospital-at-home programs across Arizona and Nevada where remote oversight reduces readmission liability.
- Catheters:Peripheral IV, midline, peripherally inserted central catheter (PICC), and tunneled central venous access devices varying in dwell time and infection risk profiles.
- Portable Systems:Ambulatory infusion devices enabling patient mobility during chemotherapy, immunoglobulin, and parenteral nutrition administration.
- Consumables:Sterile tubing sets, syringes, needles, and dressing kits requiring FDA 503B-compliant sourcing for compounded medication compatibility.
By installed base, Consumables dominates. By margin contribution, Infusion Pumps generates the steepest technology returns.
End User:
Care coordination complexity escalates across the patient-to-professional spectrum, determining nursing deployment density and documentation burden per episode.
- Patients at Home:Self-administering populations trained in sterile technique and pump operation for maintenance dosing of subcutaneous biologics and simple antibiotic protocols. California's Medicare Advantage penetration drives fastest adoption of minimal-supervision models.
- Home Healthcare Providers:Licensed agencies delivering skilled nursing, pharmacy compounding, and remote monitoring under unified risk contracts with payers.
- Family Caregivers:Unpaid household members assisting with medication preparation, line maintenance, and adverse event recognition under clinician supervision.
- Nursing Services:Specialized infusion nurses deployed for high-acuity protocols including vesicant chemotherapy and parenteral nutrition requiring central line access.
By episode volume, Home Healthcare Providers captures the largest share. By expansion rate, Patients at Home is climbing fastest as self-administration protocols proliferate.
Delivery Mode:
Precision requirements and labor substitution potential differentiate automation levels, with error-sensitive biologics driving migration toward programmable control.
- Automated Infusion:Electronic pump-controlled delivery with programmable flow rates, bolus capabilities, and alarm systems for high-risk medications. Hospital-at-home programs in Texas and Florida mandate automated systems for antibiotic and parenteral nutrition protocols to meet payer outcome guarantees.
- Manual Infusion:Syringe-push or drip-rate techniques requiring continuous bedside presence for titration and adverse reaction monitoring.
- Gravity Fed:Simple roller-clamp flow regulation for low-risk hydration and electrolyte replacement without electronic components.
- Hybrid Systems:Configurations combining automated basal rates with manual bolus capacity for patient-controlled analgesia and intermittent antibiotic dosing.
By current utilization, Manual Infusion retains volume leadership in rural territories. By substitution momentum, Automated Infusion is gaining share fastest as CMS hospital-at-home criteria tighten safety requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas commands pricing premiums on antibiotic protocols that California providers cannot replicate due to lower nursing density costs. Florida Medicare Advantage penetration drives faster hospital-at-home adoption than Midwest markets. The Southwest corridor concentrates biologic cold chain infrastructure that reduces waste penalties.
Texas
Oncology centers and transplant programs in Houston and Dallas generate concentrated sepsis management referrals for IV antibiotic protocols. CMS hospital-at-home waivers expanded eligible patient pools faster here than in Northeast states. The Texas Medical Center anchors compounding pharmacy networks serving hospital-at-home discharges across the Gulf Coast.
Florida
Medicare Advantage capitated plans in Miami and Tampa are carving out hospital-at-home benefits outside fee-for-service channels. FDA 503B accreditation requirements favor scaled operators with centralized sterile preparation facilities. The I-4 corridor between Orlando and Tampa concentrates home health agencies with infusion nursing specialization.
California
Los Angeles and San Francisco Bay Area health systems deploy remote patient monitoring for biologic self-administration protocols. HIPAA compliance costs for biometric data streaming favor platforms with enterprise-scale IT infrastructure. Kaiser Permanente's integrated model in Northern California accelerates value-based contracting for infusion episodes.
Arizona
Phoenix and Tucson hospital-at-home programs mandate smart pump connectivity for high-risk parenteral nutrition protocols. Medicaid managed care pilots with shared savings arrangements attract specialized infusion networks from neighboring states. The Sun City retirement corridor drives demand for hormonal therapy maintenance dosing.
Nevada
Las Vegas health systems leverage lower real estate costs to build centralized compounding facilities serving remote patient populations. OSHA bloodborne pathogen compliance layers add operational friction that scaled platforms absorb more efficiently than independent operators. Rural counties depend on hub-and-spoke logistics from Salt Lake City and Phoenix networks.
US Home Infusion Therapy Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying pumps, catheters, and sterile consumables to integrated delivery networks. The market structures around three archetypes: national infusion platforms with unified pharmacy-nursing-remote monitoring contracts, diversified health systems with captive home health agencies, and pure-play device manufacturers supplying ambulatory pump technology. Consolidation momentum concentrates among platforms acquiring regional home health agencies to secure nursing labor pools. Licensing arrangements between pump manufacturers and software vendors accelerate dose-error reduction feature deployment.
Within the national platform tier, Option Care Health Inc. and Coram CVS Health exemplify scale-driven positioning through integrated service footprints. KabaFusion occupies a specialized position focused on oncology and rare-disease protocol expertise. These three entities represent divergent strategic paths: payer direct contracting, retail pharmacy density leverage, and therapeutic vertical specialization respectively.
| Leading Market Players |
|---|
| KabaFusion |
| B. Braun Medical |
| Option Care Health Inc. |
| Becton Dickinson and Company |
| ICU Medical Inc. |
| Optum Inc. |
| Baxter International Inc. |
| Coram CVS Health |
| CVS Health |
| Others |
Supply Flow & Price Mechanics
The Texas Medical Center's compounding pharmacy networks anchor national sterile preparation capacity, concentrating upstream supply power that translates into premium pricing leverage for high-acuity antibiotic protocols. This geographic clustering of FDA 503B-accredited facilities shapes downstream reimbursement negotiations with Medicare Advantage plans seeking hospital-at-home carve-outs.
Pricing Analysis
Configured-to-order pricing for patient-specific biologic compounding commands substantial premiums over standard antibiotic protocols. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 503B certification status, cold chain integrity guarantees, and bundled nursing supervision hours. Cost compression in the standard tier is intensifying because Medicare Advantage plans are consolidating vendor panels around outcome guarantees. Independent operators in rural territories exhibit highest price sensitivity due to fixed episode-based rate exposure, while integrated platforms with captive pharmacy-nursing capabilities maintain pricing power through risk-bearing contracts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for electronic infusion pump components and disposable tubing sets. Manufacturing concentration centers on the United States, Germany, and China for precision pump mechanisms, with Mexico emerging as a nearshore alternative for sterile consumables assembly. Raw material dependencies include medical-grade plastics, lithium-ion battery cells, and semiconductor chips for wireless connectivity modules. Single-source vulnerability in smart pump software licensing creates procurement bottlenecks for mid-tier operators. Distribution runs through specialized medical device distributors serving hospital-at-home networks, with direct-to-provider logistics gaining share among scaled platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists across this market as CMS hospital-at-home waiver expansion creates specialized niches for regional platforms with targeted therapeutic expertise. The shift from fee-for-service toward risk-bearing contracts fragments volume among operators with distinct capability bundles rather than concentrating share among national giants.
For Market Incumbents: Insulate margin position by deepening backward integration into sterile compounding capacity in the Texas-Florida corridor and securing exclusive nursing labor pools through acquisition of regional home health agencies. The threat of subcutaneous formulation migration reducing nursing dependency demands preemptive investment in remote patient monitoring infrastructure to maintain care coordination revenue streams. For New Entrants and Emerging Players: Rural counties in Nevada and Arizona represent the most penetrable entry point where hub-and-spoke logistics from distant compounding hubs create service gaps. Specialized oncology protocol expertise in secondary Texas markets offers a defensible niche against national platforms. A direct contracting angle with Medicaid managed care pilots seeking shared savings arrangements provides faster credentialing than Medicare fee-for-service enrollment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platforms with integrated pharmacy-nursing-remote monitoring capabilities over pure-play device manufacturers facing pump commoditization. Long-term viability across the next decade hinges on hospital-at-home waiver permanence and Medicare Advantage penetration rates. The signal to watch is CMS demonstration authority conversion to permanent reimbursement policy, which would reallocate substantial inpatient infusion volume and validate platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 503B Accreditation Investment | Enables sterile compounding for biologic protocols and qualifies providers for hospital-at-home contracts. |
| Smart Pump Connectivity Deployment | Wireless dose-error reduction software reduces payer liability and commands premium procurement pricing. |
| Regional Home Health Acquisition | Captures scarce infusion nursing labor pools and secures referral relationships with discharge planners. |
| Medicare Advantage Direct Contracting | Bypasses traditional fee-for-service channels and locks in capitated revenue streams with outcome guarantees. |
| Remote Patient Monitoring Integration | HIPAA-compliant biometric streaming enables 24/7 oversight without continuous bedside nursing presence. |
Methodological Framework
A spread of perspectives from infusion pharmacy directors, Medicare Advantage contracting officers, home health agency administrators, and FDA regulatory consultants converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against CMS Medicare data, hospital procurement databases, GPO contracts, and FDA 503B facility registration records. Bottom-up triangulation across state-level home health licensing data and top-down reconciliation with national health expenditure trends anchored volume estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, modeling patient population growth, hospital-at-home waiver expansion, and nursing labor availability constraints. Segmentation dimensions included therapeutic category, technology tier, end-user type, and delivery mode complexity. CAGRs were derived from fitted growth curves calibrated to historical referral pattern data and payer policy shift timelines. Forecast inputs incorporated Medicare Advantage penetration trajectories and subcutaneous formulation pipeline advancement.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting health system capital expenditure or shifts in federal healthcare spending authorization would shift the trajectory of hospital-at-home infrastructure deployment. Forecasts reflect documented assumptions regarding regulatory permanence and technology adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
Portable Toilet for Elderly Market
Home Healthcare
US House Calls Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Home Care Service Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Home Care Products Market
Home Healthcare
Global Home Infusion Therapy Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Home Healthcare Market
Home Healthcare
Senior in-Home Care Services Market