
 Outpatient Home Therapy Market | 2026-2036
Outpatient Home Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Outpatient Home Therapy Market Analytics
North America is tilting toward decentralized rehabilitation infrastructure as payers prioritize cost containment. Athletico Physical Therapy leverages its clinic-to-home care continuum to sustain patient retention across episodes. PIVOT Physical Therapy anchors its growth strategy on employer-direct contracts, while SPI ProHealth Limited Hong Kong competes through specialized musculoskeletal programs in dense urban corridors.
Outpatient home therapy encompasses skilled therapeutic interventions delivered in residential settings rather than institutional facilities, typically involving licensed clinicians who administer exercise protocols, mobility training, and adaptive equipment instruction using portable modalities and patient-specific treatment plans. Physical therapy dominates product type revenue due to orthopedic procedure volumes and joint replacement recovery protocols, while teletherapy within delivery mode exhibits the fastest structural expansion as synchronous video platforms gain reimbursement parity. Home health agencies represent the most concentrated end-user margin pool because they aggregate payer contracts and coordinate multi-disciplinary care teams.
FDA oversight governs medical devices used in home therapeutic settings, while HIPAA mandates govern remote data transmission, and CMS reimbursement rules directly determine service viability through physician fee schedules and home health prospective payment systems. Stakeholders must monitor evolving site-neutral payment policies and state-level scope-of-practice expansions that could redraw competitive boundaries between traditional clinics and home-based providers.
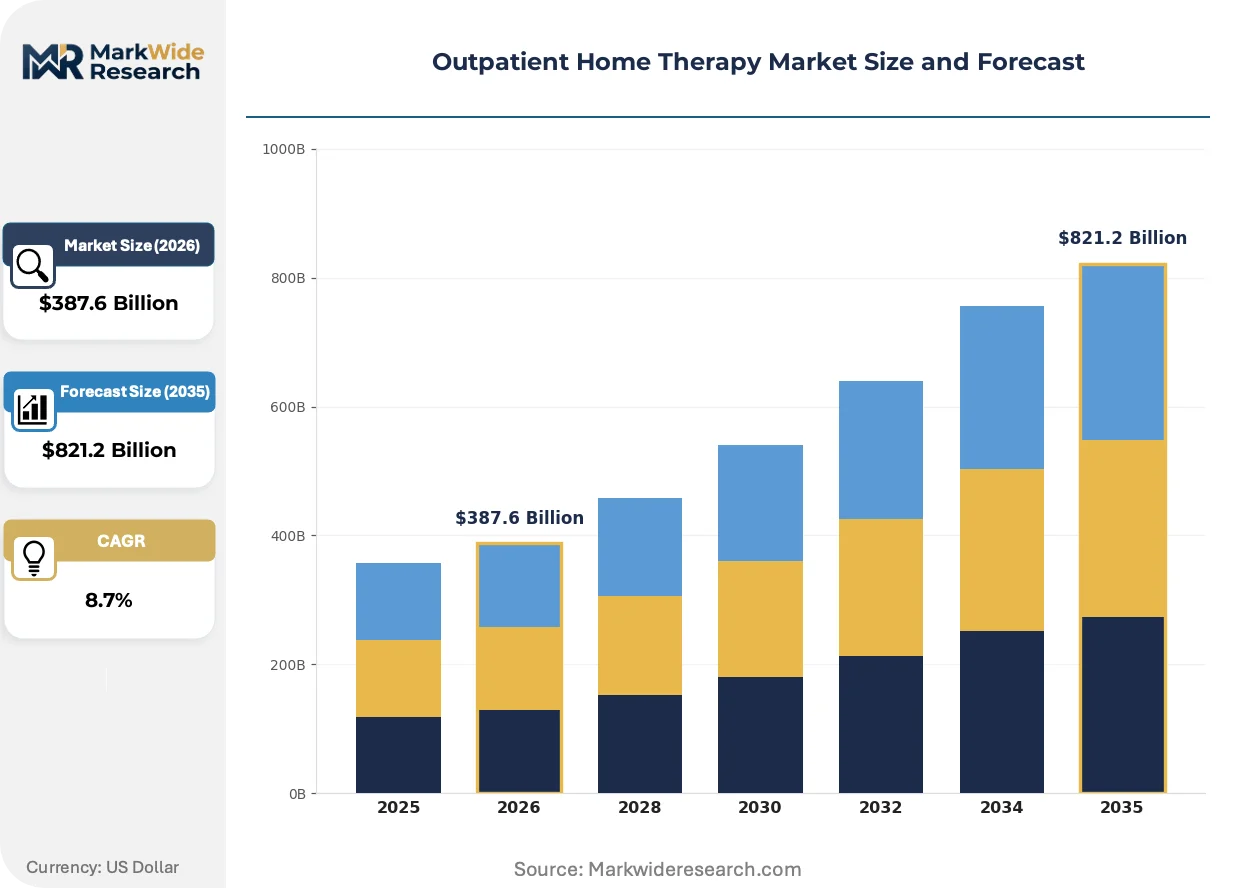
Market Dynamics
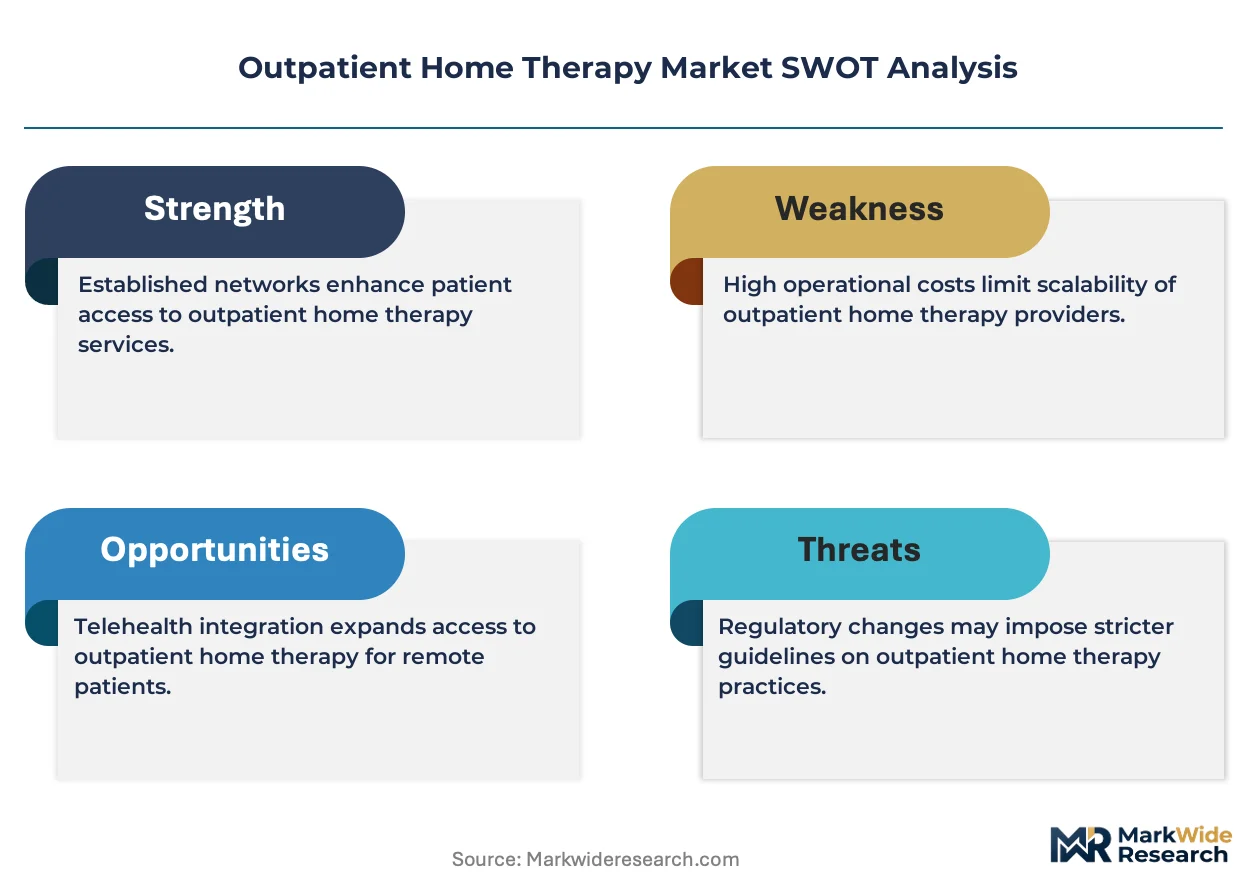
Site-neutral payment policies are dismantling the institutional reimbursement advantage that hospitals and skilled nursing facilities have held for decades, forcing capital deployment toward home-based delivery infrastructure and remote monitoring capabilities.
Growth Catalysts
- CMS Home Health Prospective Payment System:Reimbursement parity for home-based physical therapy removes financial barriers that previously steered patients toward facility-based care in the United States.
- Remote Patient Monitoring:Wearable sensors and synchronous video platforms enable real-time gait analysis and exercise compliance tracking without clinic visits.
- Aging Demographics:Joint replacement volumes among Medicare beneficiaries concentrate demand for post-acute rehabilitation that can be delivered outside institutional settings.
Market Restraints
- Clinician Supply Constraints:Licensed physical therapists remain concentrated in urban corridors, creating access deserts in rural and exurban territories where home therapy demand is rising fastest.
- Technology Integration Costs:HIPAA-compliant data infrastructure and telehealth platform licensing impose fixed cost burdens that disadvantage smaller home health agency operators.
- Reimbursement Velocity Risk:Medicare Advantage plans and state Medicaid programs lag CMS fee schedules, creating payment uncertainty that constrains capital planning for multi-state providers.
Strategic Opportunities
- Employer-Direct Contracting:Self-insured employers in the United States are bypassing traditional payer networks to negotiate bundled musculoskeletal care that includes home-based rehabilitation.
- Artificial Intelligence and Motion Capture:Computer vision algorithms analyzing smartphone camera feeds enable automated form correction, reducing per-session clinician time while maintaining outcomes accountability.
- State Scope-of-Practice Expansion:Physical therapy direct access laws in jurisdictions like Colorado and Louisiana eliminate physician referral requirements, accelerating patient entry into home-based care pathways.
Industry Challenges
- Interoperability Friction:Electronic health record systems used by referring physicians rarely integrate with home health agency scheduling and documentation platforms, creating information gaps that delay care initiation.
- Workforce Credentialing Complexity:Multi-state licensure requirements and varying continuing education mandates complicate clinician deployment across service territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outpatient Home Therapy Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Therapy, Occupational Therapy, Speech Therapy, Behavioral Therapy Delivery Mode: In-Home Visits, Teletherapy, Mobile Applications, Community Programs End User: Patients, Caregivers, Healthcare Providers, Home Health Agencies Service Type: Assessment Services, Treatment Sessions, Follow-Up Care, Support Services |
| Companies Covered | Olean Physical Therapy, Central and Stanley Wellness, Athletico Physical Therapy, Graceville Physiotherapy, Therapy Solutions Inc., PIVOT Physical Therapy, FullMotion Physical Therapy, SPI ProHealth Limited Hong Kong, AmeriCare Physical Therapy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outpatient Home Therapy Market Evolving Landscape
Digital therapeutics and asynchronous care models are compressing the traditional clinic visit into distributed touchpoints that blend human expertise with automated intervention protocols.
Synchronous video platforms with integrated motion tracking is virtualizing the physical therapy assessment, enabling licensed clinicians to evaluate range of motion and exercise form through standard consumer devices. Large home health agencies are deploying these platforms to extend specialist reach into territories where recruiting on-site staff proves economically unworkable. The technology is virtualizing geographic constraints that previously limited market entry for specialized musculoskeletal programs.
CMS site-neutral payment mandates are eliminating facility-based reimbursement premiums that historically subsidized hospital outpatient department overhead. Home health agencies with established remote monitoring infrastructure capture margin expansion as episode payments equalize across delivery settings. Post-acute care providers in Medicare Advantage-dominant markets are restructuring contractual relationships to emphasize home-based episodes over institutional referrals.
Patients recovering from orthopedic procedures increasingly expect on-demand scheduling flexibility that traditional clinic models cannot accommodate. Digital-native entrants are unbundling the therapy relationship into discrete video consultations, automated exercise prescription, and asynchronous messaging channels that reduce per-episode clinician contact hours. This behavioral shift concentrates in metropolitan markets where consumer technology adoption rates outpace rural territories by substantial margins.
Outpatient Home Therapy Market Segmentation
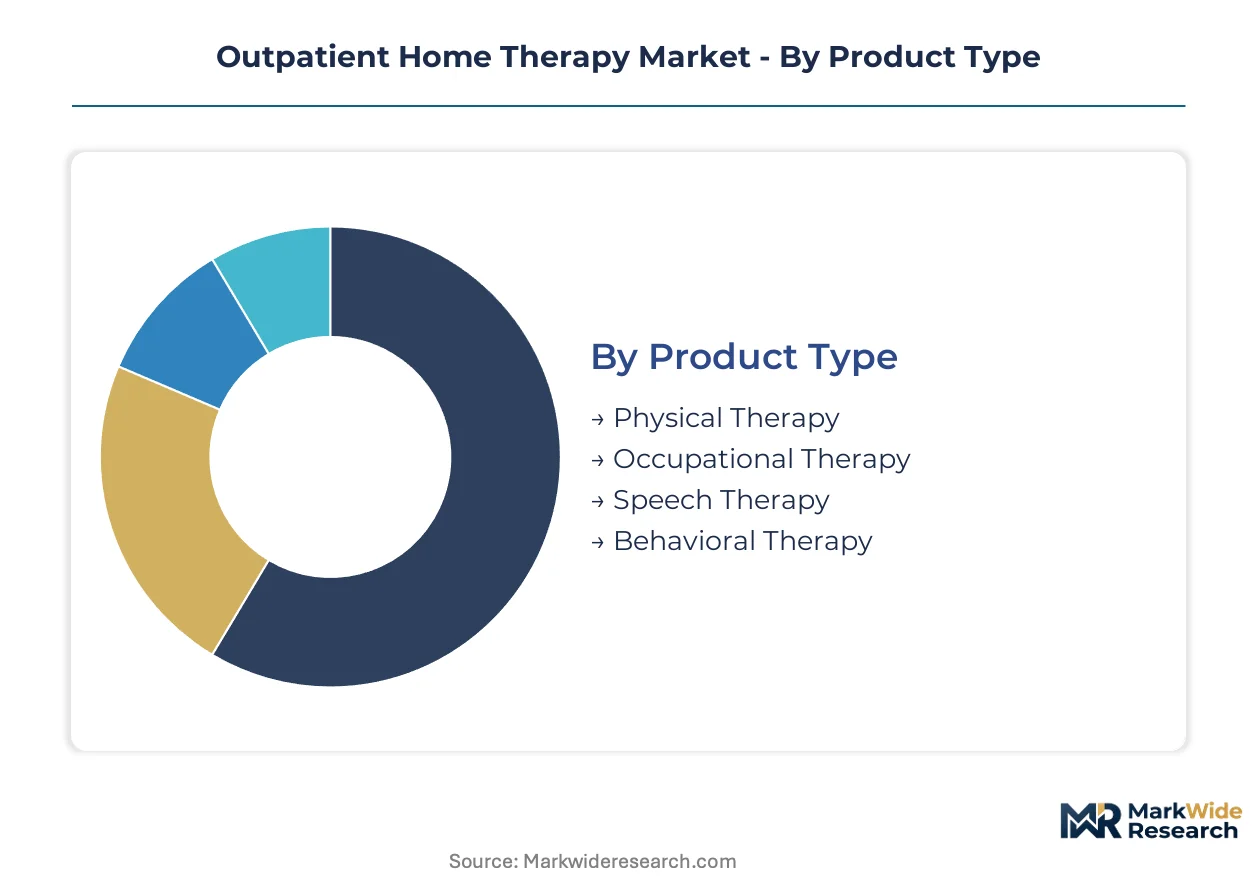
Segmentation in outpatient home therapy reveals how reimbursement structures, technology maturity, and workforce distribution concentrate margin across distinct service configurations. Understanding these partitions enables stakeholders to align capital deployment with the specific regulatory and demand characteristics governing each category.
Product Type:
Mature clinical modalities with established reimbursement codes anchor revenue stability, while emerging specialties face credentialing and payment parity hurdles that constrain near-term scaling.
- Physical Therapy:Exercise protocols, gait training, and joint mobilization delivered by licensed PTs using portable modalities. Demand clusters around post-surgical orthopedic recovery in Medicare Advantage-dominant states, driven by site-neutral payment mandates that equalize home and facility reimbursement.
- Occupational Therapy:Activities of daily living retraining, adaptive equipment fitting, and home safety modifications. Growth concentrates in employer-direct musculoskeletal contracts where return-to-work metrics justify premium pricing for functional restoration programs.
- Speech Therapy:Swallowing rehabilitation and cognitive-linguistic intervention for stroke and neurodegenerative patients.
- Behavioral Therapy:Mental health and substance use interventions adapted for residential settings.
Physical Therapy retains volume leadership; Behavioral Therapy holds the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates capital-intensive synchronous platforms from lightweight asynchronous tools, with reimbursement velocity determining which configurations achieve sustainable unit economics.
- In-Home Visits:Licensed clinicians conducting face-to-face interventions at patient residences using transportable equipment. Volume concentrates in dense suburban corridors where clinician travel time remains economically viable under prospective payment systems.
- Teletherapy:Real-time video consultation with integrated motion tracking and remote patient monitoring. Expansion accelerates in states with direct-access physical therapy laws that eliminate physician referral bottlenecks.
- Mobile Applications:Asynchronous exercise prescription and compliance tracking through consumer smartphones.
- Community Programs:Group-based interventions delivered in non-clinical residential settings.
In-Home Visits dominate current episode volume; Teletherapy is climbing the fastest as CMS extends reimbursement parity.
End User:
Customer type segmentation exposes divergent procurement authority, with institutional aggregators commanding superior payer contract terms versus individual patient decision-making.
- Home Health Agencies:Multi-disciplinary organizations coordinating therapy within broader post-acute care episodes. These entities aggregate Medicare and Medicare Advantage contracts, capturing margin through scale efficiencies in documentation and billing infrastructure.
- Healthcare Providers:Physician practices and hospital systems referring patients to home-based therapy. Demand concentrates in value-based care arrangements where readmission penalties create accountability for post-discharge functional outcomes.
- Patients:Individuals accessing therapy through self-pay or direct insurance channels.
- Caregivers:Family members coordinating therapy on behalf of dependent patients.
Home Health Agencies command the largest contract value; Healthcare Providers are gaining share fastest through bundled payment expansion.
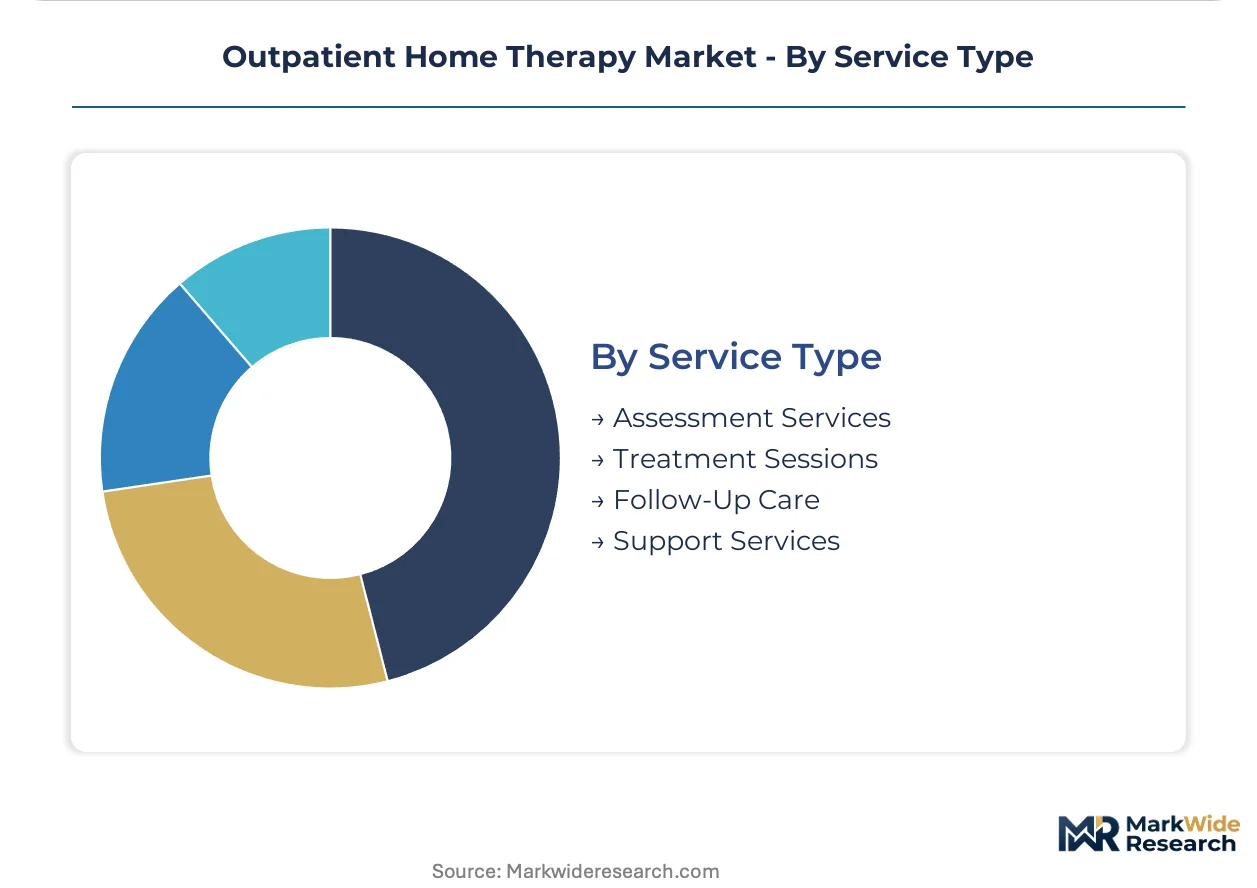
Service Type:
Application-stage differentiation separates episodic revenue events from recurring relationship economics, with initial assessments functioning as gateway transactions to longitudinal care.
- Assessment Services:Initial functional evaluations, home safety inspections, and care plan development. These services concentrate in joint replacement recovery protocols where hospitals require documented post-acute handoffs to satisfy CMS readmission metrics.
- Treatment Sessions:Scheduled therapeutic interventions comprising the core revenue unit. Demand concentrates in urban and suburban markets with sufficient clinician density to support same-week scheduling commitments.
- Follow-Up Care:Periodic reassessment and plan modification visits.
- Support Services:Equipment maintenance, caregiver training, and care coordination.
Treatment Sessions generate the highest absolute revenue; Assessment Services are expanding most quickly as hospitals seek documented post-acute partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare's site-neutral payment mandates anchor United States market expansion, while reimbursement parity for telehealth services unlocks capital deployment across decentralized delivery networks. CMS infrastructure underwrites patient migration from institutional settings toward residential rehabilitation corridors.
United States
Joint replacement volumes among Medicare beneficiaries concentrate demand in suburban corridors where home health agencies deploy remote monitoring platforms. CMS Home Health Prospective Payment System revisions equalize reimbursement across facility and residential settings. Texas and Florida metro clusters attract multi-state providers seeking scale efficiencies in documentation infrastructure.
Germany
Aging demographics and statutory health insurance integration create structural demand for post-acute residential rehabilitation. EMA medical device oversight governs wearable sensors deployed in home therapeutic settings. Bavaria and North Rhine-Westphalia host dense networks of outpatient therapy providers restructuring around value-based care contracts.
Japan
Super-aging population dynamics and hospital bed reduction policies redirect rehabilitation demand toward community-based delivery. METI digital health initiatives accelerate telehealth platform adoption for musculoskeletal intervention. Tokyo-Osaka corridor providers integrate motion capture technology to address clinician supply constraints in rural prefectures.
Australia
Medicare Benefits Schedule expansion for home-based allied health services reduces facility dependency in post-surgical recovery. TGA medical device regulation ensures wearable therapeutic equipment compliance for residential deployment. New South Wales and Victoria concentrate private health insurer contracting for bundled musculoskeletal care episodes.
United Kingdom
NHS Long Term Plan commitments to out-of-hospital care shift rehabilitation capacity toward community settings. NICE guidelines on digital therapeutics create reimbursement pathways for remote physical therapy assessment. London and Southeast England clusters attract technology-enabled providers targeting integrated care system contracts.
Outpatient Home Therapy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying portable modalities and software infrastructure. Market structure tilts toward regional consolidation as multi-site clinic networks acquire home health agency capabilities to capture episode payments. Three archetypes dominate: clinic-to-home continuum operators, employer-direct contract specialists, and telehealth-native platforms. M&A activity concentrates on acquiring remote monitoring infrastructure; strategic partnerships with wearable device manufacturers accelerate technology integration timelines.
Among United States-based clinic networks, Athletico Physical Therapy and PIVOT Physical Therapy exemplify contrasting scale strategies, while SPI ProHealth Limited Hong Kong occupies a position representing Asia-Pacific urban specialization. These entities anchor competitive dynamics across reimbursement environments where site-neutral payment policies redraw margin boundaries between institutional and residential delivery settings.
| Leading Market Players |
|---|
| Olean Physical Therapy |
| Central and Stanley Wellness |
| Athletico Physical Therapy |
| Graceville Physiotherapy |
| Therapy Solutions Inc. |
| PIVOT Physical Therapy |
| FullMotion Physical Therapy |
| SPI ProHealth Limited Hong Kong |
| AmeriCare Physical Therapy |
| Others |
Value Network & Pricing Analysis
Dallas-Fort Worth metroplex capacity in remote patient monitoring infrastructure concentrates pricing leverage among home health agencies deploying synchronous video platforms at scale. CMS site-neutral payment mandates compress facility-based premiums, redirecting margin capture toward providers with established HIPAA-compliant data architecture and multi-state clinician networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs outpatient home therapy reimbursement. Premium tiers attach to specialized musculoskeletal programs with motion capture integration and direct-access physical therapy credentials; standard tiers cover conventional in-home visits under Medicare Advantage contracts; economy tiers serve Medicaid-managed populations with asynchronous mobile application delivery. Price differentiation hinges on clinician credential tier and geographic delivery cost, with rural territories commanding travel-time surcharges that urban providers absorb into base rates. Cost compression in standard-tier episodes is intensifying because Medicare Advantage plans lag CMS fee schedule velocity, squeezing multi-state operators. Self-insured employers exhibit least price sensitivity, prioritizing return-to-work metrics over per-session cost.
Supply Chain Analysis
Contract manufacturing concentration for wearable therapeutic sensors rests with EMS providers in Taiwan, South Korea, and Malaysia holding FDA-registered medical device production lines. Hardware components draw from semiconductor foundries in Taiwan and South Korea for motion-tracking chipsets, lithium-cell suppliers in China for portable modality power systems, and optical sensor specialists in Japan for camera-based gait analysis modules. Single-source vulnerability concentrates in Taiwan semiconductor capacity for AI-enabled form correction processors. Distribution runs through home health agency procurement consortia and GPO contracts aggregating demand from multi-site clinic networks, with direct OEM relationships emerging among telehealth-native platforms seeking hardware-software integration control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed physical therapist density in rural corridors represents the binding constraint on market expansion, with workforce pipeline gaps limiting home health agency scaling regardless of capital availability or technology deployment.
For Market Incumbents: Harden clinician retention through backward integration into physical therapy education partnerships and captive training pipelines in underserved states like Montana and Wyoming. Expand remote monitoring infrastructure to offset travel-time economics in exurban territories where competitor entry remains prohibitive. Defensive priority centers on locking exclusive Medicare Advantage contracts before regional competitors achieve multi-state licensure scale. For New Entrants and Emerging Players: Employer-direct musculoskeletal contracts in manufacturing-heavy Midwest metros represent the most penetrable entry point, bypassing traditional payer network credentialing requirements. Teletherapy-native platforms targeting direct-access physical therapy states like Colorado and Louisiana avoid physician referral bottlenecks that constrain incumbent workflows. Go-to-market leverage rests on AI motion capture integration reducing per-session clinician time while maintaining outcomes accountability for self-insured employers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors home health agencies with established remote patient monitoring infrastructure and multi-state licensure compliance. Long-term viability over the next decade hinges on site-neutral payment policy durability and Medicare Advantage penetration rates. Acquisition target archetype: regional clinic networks with clinic-to-home care continuum capabilities and existing CMS certification. Signal to watch: state-level scope-of-practice expansion legislation accelerating patient entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Monitoring Infrastructure Deployment | CMS reimbursement parity for synchronous video platforms enables margin capture previously reserved for facility-based providers. |
| Multi-State Clinician Licensure Expansion | Regulatory compliance across state lines unlocks geographic scaling for home health agencies targeting Medicare Advantage contracts. |
| AI Motion Capture Integration | Computer vision algorithms reduce per-session clinician time while maintaining functional outcome metrics for employer-direct contracts. |
| Employer-Direct Contracting | Self-insured employers bypass traditional payer networks, negotiating bundled musculoskeletal care with premium pricing for return-to-work guarantees. |
| Physical Therapy Education Partnerships | Captive workforce pipelines address licensed clinician supply constraints in rural and exurban territories with fastest demand growth. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CMS Medicare data, hospital procurement databases, GPO contracts, and state-level physical therapy licensure records. Primary interviews engaged home health agency executives, licensed physical therapists, Medicare Advantage plan medical directors, and biomedical engineers developing wearable therapeutic devices. Secondary validation drew from FDA 510(k) filings for home therapeutic devices, HIPAA compliance audit reports, and state direct-access physical therapy legislation tracking. Bottom-up sizing triangulated clinician supply estimates against episode volume projections; top-down validation cross-referenced CMS expenditure data against home health agency revenue disclosures.
Forecast inputs incorporate aging demographic trajectories, joint replacement volume projections, site-neutral payment policy implementation timelines, and telehealth reimbursement parity expansion across state Medicaid programs. Segmentation modeling spans product type, delivery mode, end user, and service type dimensions, with geographic regulatory cluster differentiation for Medicare Advantage penetration rates and direct-access physical therapy law adoption. CAGRs derive from regression analysis of historical episode volume growth against explanatory variables including beneficiary population expansion and technology adoption curves.
Practitioners should monitor CMS Home Health Prospective Payment System revision schedules and Medicare Advantage plan rate-setting negotiations for early signals of reimbursement velocity shifts. Forecasts reflect assumptions regarding site-neutral payment policy durability and clinician workforce pipeline recovery. Quarterly review of state-level scope-of-practice legislation and telehealth parity statute adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Global Elderly Care Market
Home Healthcare
Global Home Health Hub Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Elder Care Products Market
Home Healthcare
Home Care Products Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Home Care Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Global Home Infusion Therapy Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
US House Calls Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market