
 Home Care Products Market | 2026-2036
Home Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Home Care Products Market Analysis
European surfactant producers is shifting capacity toward plant-derived feedstocks to meet tightening chemical safety mandates. Procter & Gamble leverages its global manufacturing footprint to sustain cost advantages across laundry detergent categories. Unilever anchors its portfolio in concentrated and refillable formats, competing on sustainability credentials. Henkel differentiates through specialized industrial and institutional cleaning solutions alongside its consumer base.
Home care products encompass formulated chemical solutions designed for residential and light commercial sanitation, typically containing surfactants, solvents, builders, and fragrances engineered for specific surface compatibility and microbial efficacy. These formulations undergo batch processing with controlled pH adjustment and stability testing to ensure performance across water hardness variations and storage conditions. Laundry detergents and cleaning agents command the largest share of value given their high purchase frequency and essential household status, while air fresheners represent the fastest-expanding margin pool as consumers prioritize sensory home environments. Online retail channels are gaining structural importance as warehouse clubs face pressure from subscription-based replenishment models and direct-to-consumer specialization.
EPA registration requirements under the Federal Insecticide, Fungicide, and Rodenticide Act govern disinfectant claims in the United States, while REACH compliance in Europe mandates full chemical substance registration and hazard communication. The EU Green Deal and associated CSRD reporting obligations are forcing transparency on carbon intensity and packaging circularity across supply chains. Stakeholders must monitor evolving state-level chemical disclosure laws in California and New York alongside federal preemption debates that will determine compliance fragmentation or harmonization.
Market Dynamics
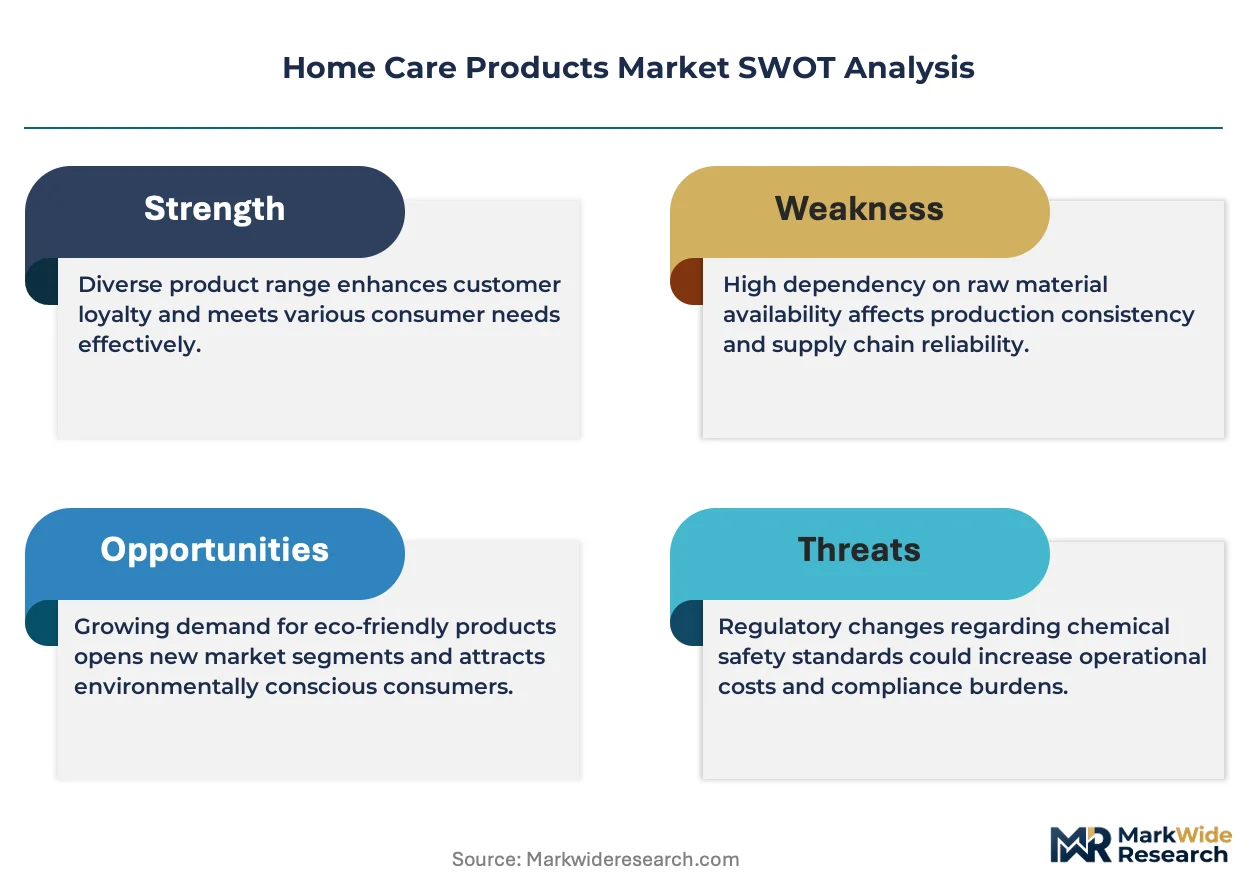
REACH chemical registration mandates and EPA safety protocols are forcing surfactant producers to rebuild formulation pipelines around bio-based feedstocks, compressing legacy petrochemical supply chains while opening capacity for enzymatic cleaning technologies.
Growth Catalysts
- Urban household formation:Concentrated residential development in India and Brazil is generating sustained pull for compact, multi-surface cleaning formats designed for smaller living spaces.
- EU Green Deal packaging mandates:The Circular Economy Action Plan is accelerating refill station infrastructure across German and French retail networks, creating captive demand for concentrated refills.
- Enzymatic stabilization:Cold-water washing enzymes are expanding addressable energy savings for utility-conscious consumers in Nordic markets.
Market Restraints
- Palm kernel oil volatility:Lauryl sulfate precursors face price instability tied to Malaysian and Indonesian export policy fluctuations.
- Disinfectant claim registration:EPA FIFRA timelines stretch 12-18 months for novel antimicrobial actives, freezing pipeline innovation for sanitizing subcategories.
- Concentrate dilution behavior:Consumer overdosing of ultra-concentrated detergents erodes per-wash cost advantages and triggers premature repurchase cycles.
Strategic Opportunities
- Rural Indian penetration:Sachet-format distribution through kirana stores remains underdeveloped against organized retail concentration in Tier-1 cities.
- Subscription replenishment:Direct-to-consumer auto-ship models are displacing warehouse club bulk purchasing among millennial households in the United States.
- Sensor-activated dispensing:IoT-enabled dosage systems are converging with private-label smart home ecosystems to lock in recurring consumable revenue.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with bio-based surfactant expertise command premium compensation in European labor markets.
- Legacy ERP integration:Batch manufacturing execution systems require costly retrofitting to track CSRD-mandated carbon intensity at SKU level.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Care Products Market |
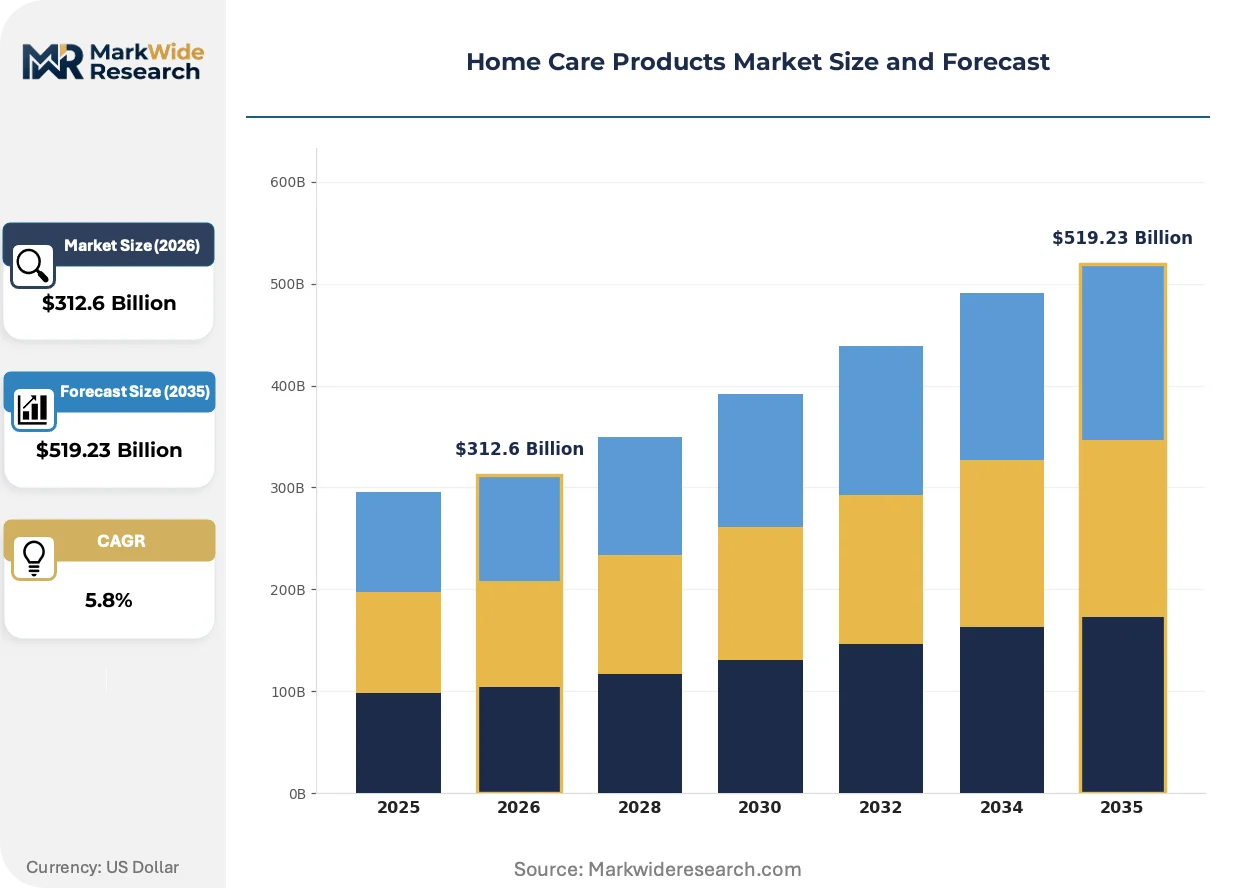
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleaning Agents, Air Fresheners, Laundry Detergents, Dishwashing Products Consumer Segment: Families, Singles, Seniors, Caregivers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Warehouse Clubs Usage Frequency: Daily, Weekly, Monthly, As Needed |
| Companies Covered | Procter & Gamble, Unilever, Henkel, Reckitt Benckiser Group, Church & Dwight, S.C. Johnson & Son, The Clorox Company, Kao Corporation, Godrej Consumer Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Care Products Market Emerging Trajectories
Formulation science and distribution architecture are diverging sharply as chemical safety mandates collide with convenience expectations, producing three distinct vectors of competitive investment.
Biodegradable chelating agents derived from glutamic acid are replacing EDTA in European laundry formulations. German and Dutch detergent manufacturers are adopting these alternatives at scale to preempt ECHA substance restriction proposals. The shift is integrating plant-derived sequestration chemistry into standard powder and liquid production lines previously optimized for petrochemical inputs.
California's Cleaning Product Right to Know Act is compelling ingredient disclosure down to 0.01% concentration thresholds. Manufacturers serving the United States market are restructuring supply chain documentation systems to satisfy both state-level mandates and pending federal harmonization debates. Private-label brands targeting sustainability-conscious buyers in New York and Massachusetts are accelerating compliance investments ahead of anticipated regulatory expansion.
Refill infrastructure is migrating from specialty zero-waste boutiques into conventional supermarket formats. French and British retailers are dedicating aisle space to bulk dispensing systems for dish and surface cleaners, displacing pre-packaged SKUs in premium urban locations. German drugstore chains report highest adoption density among households with children under age twelve, where packaging waste sensitivity concentrates purchasing decisions.
Home Care Products Market Segmentation
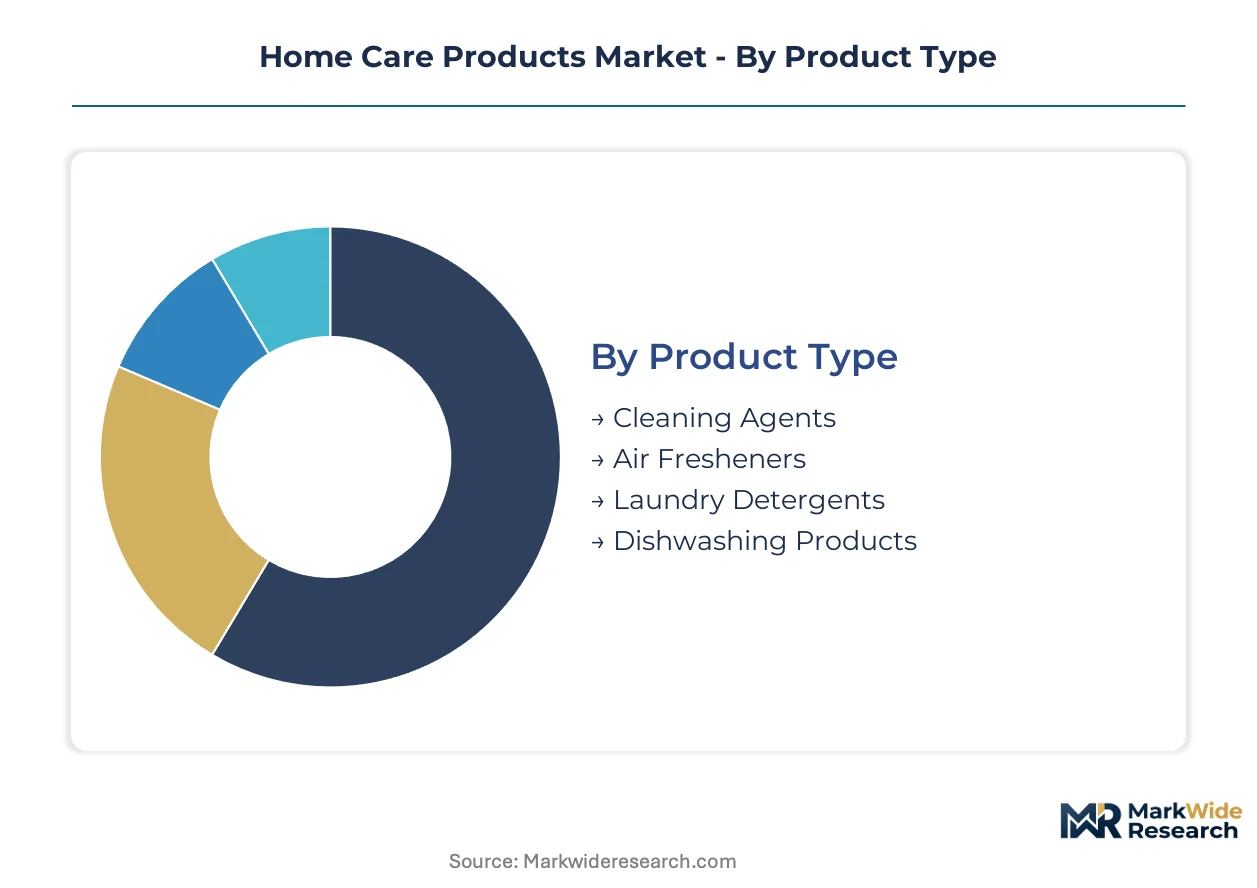
Segmentation in home care products determines formulation intensity, packaging format, and channel economics. Purchase cycles vary dramatically across household types and usage contexts, forcing manufacturers to maintain parallel SKU architectures.
Product Type:
Replacement cycles and upgrade triggers differ sharply across cleaning categories, with laundry commanding the most predictable replenishment patterns while air care follows discretionary refresh schedules.
- Laundry Detergents:Enzymatic formulations with cold-water activation dominate new product development. Concentrated liquids and unit-dose pods are displacing powders in German and United States households where machine ownership nears saturation. Water hardness compatibility and fabric-specific variants sustain premium tier differentiation.
- Cleaning Agents:Multi-surface sprays and specialized bathroom/kitchen formulations contain quaternary ammonium compounds or plant-derived surfactants depending on disinfection claims. Urban Indian households in Mumbai and Bangalore drive demand for compact aerosol formats suited to smaller storage spaces.
- Air Fresheners:Gel, spray, and plug-in delivery systems target sensory customization preferences.
- Dishwashing Products:Hand dish liquids and automatic dishwasher tablets serve distinct mechanical contexts with incompatible formulation requirements.
Volume placements concentrate in laundry detergents; the faster expansion belongs to air fresheners.
Consumer Segment:
Household composition dictates bundle size preference, price sensitivity, and sustainability trade-off willingness across all product categories.
- Families:Bulk purchasing and subscription replenishment dominate, with child safety packaging and hypoallergenic claims driving selection criteria. German and United States households with children under twelve show highest adoption of refill station formats.
- Singles:Compact formats and single-serve sachets align with limited storage and lower consumption velocity. Urban Indian Tier-1 cities see concentrated demand for trial-size laundry and dish products.
- Seniors:Ergonomic packaging and simplified dosing mechanisms address dexterity constraints.
- Caregivers:Institutional procurement patterns blend with residential requirements in home healthcare settings.
Family households generate the largest absolute volume; single-person units are climbing the fastest as urbanization restructures household formation patterns.
Distribution Channel:
Channel selection determines margin capture, with direct-to-consumer models extracting intermediation costs that fund subscription discounting.
- Supermarkets:Aisle placement and promotional slotting fees structure competitive access. French and British retailers are converting shelf space to refill infrastructure, compressing pre-packaged SKU facings.
- Online Retail:Auto-ship subscriptions and algorithmic replenishment recommendations are displacing warehouse club bulk purchasing among millennial households in the United States. Direct-to-consumer brands bypass traditional wholesale margins entirely.
- Convenience Stores:Emergency replenishment and impulse air freshener purchases sustain foot traffic economics.
- Warehouse Clubs:Volume-tier pricing and multi-pack bundling serve stock-up shopping missions.
Supermarket placements retain the deepest volume base; online channels are gaining share fastest as replenishment automation locks in recurring revenue.
Usage Frequency:
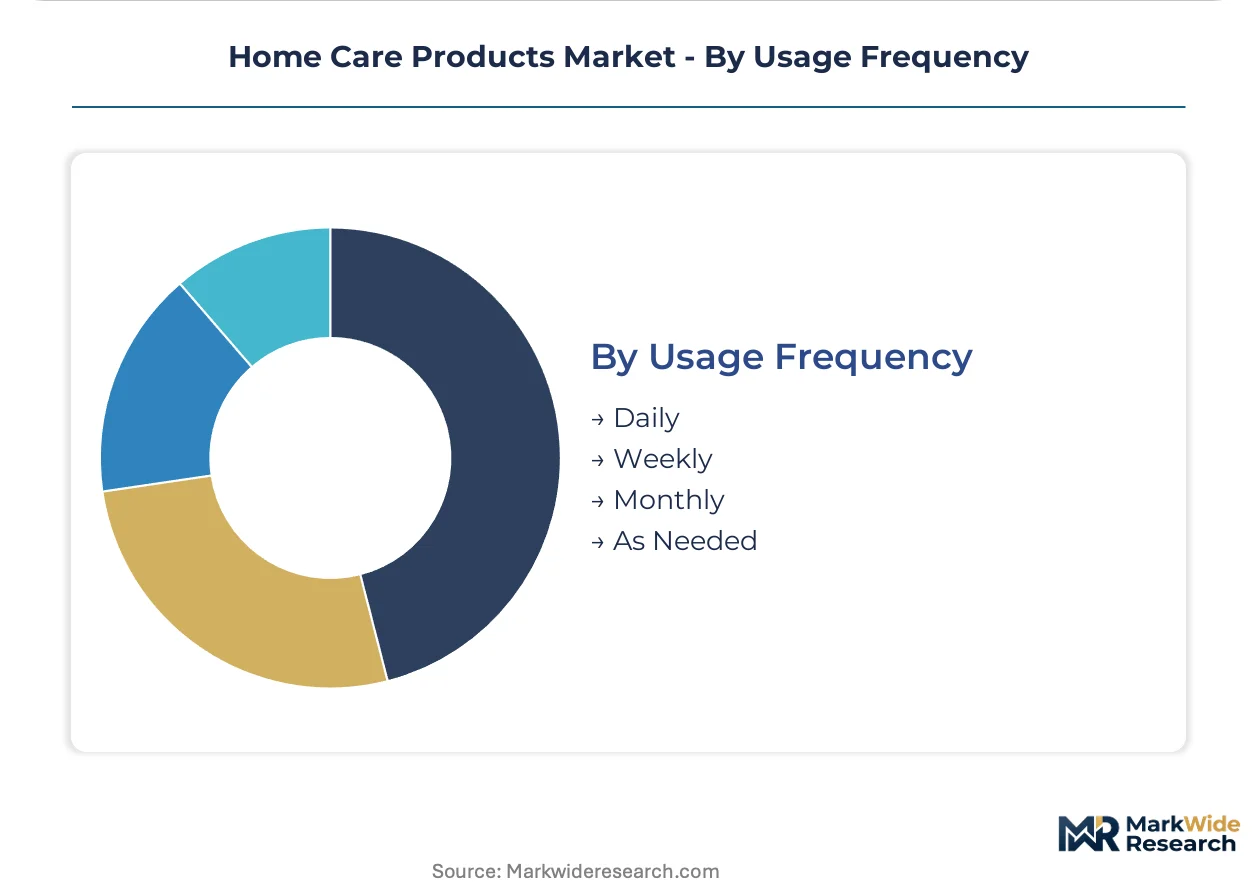
Frequency segmentation separates maintenance categories from episodic interventions, with implications for inventory turnover and promotional calendar design.
- Daily:Hand dishwashing and surface wiping products follow rigid consumption rhythms with minimal elasticity. Indian kirana store distribution networks optimize for this replenishment velocity in dense urban neighborhoods.
- Weekly:Laundry cycles concentrate demand into predictable weekend purchasing windows.
- Monthly:Deep cleaning and specialized treatments follow seasonal or event-driven triggers.
- As Needed:Stain removers and odor eliminators exhibit highly variable demand patterns.
Daily-use categories anchor manufacturer volume forecasts; as-needed segments show the steepest expansion trajectory as problem-specific formulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Palm kernel oil plantations in Malaysia and Indonesia supply surfactant precursors to formulators across Germany, the United States, and India. Chemical safety mandates in Europe and North America are redirecting procurement toward plant-derived feedstocks. Urban household formation in Brazil and India is compressing product formats for smaller living spaces.
United States
Millennial households are abandoning warehouse clubs for subscription auto-ship models that lock in recurring detergent purchases. EPA FIFRA registration timelines stretch 12-18 months for novel antimicrobial claims, freezing innovation pipelines for sanitizing products. Cincinnati and Chicago host concentrated manufacturing footprints where Procter & Gamble and Church & Dwight operate legacy batch processing facilities.
Germany
Refill station infrastructure is displacing pre-packaged SKUs in Berlin and Hamburg drugstore chains, with highest adoption among families with children under twelve. REACH compliance and the EU Green Deal mandate full chemical substance registration and carbon intensity transparency across supply chains. Düsseldorf and Frankfurt anchor Henkel's specialized industrial cleaning operations alongside consumer detergent production.
India
Tier-1 cities Mumbai and Bangalore drive demand for compact aerosol formats suited to apartment storage constraints. BIS standards and DGFT export policies shape formulation requirements for domestic and international markets. Kirana store networks in Maharashtra and Gujarat remain underpenetrated for sachet-format laundry and dish products against organized retail concentration.
Brazil
Concentrated residential development in São Paulo and Rio de Janeiro generates pull for multi-surface cleaning formats designed for smaller living spaces. ANVISA regulates antimicrobial claims and ingredient safety for household chemical products. São Paulo's industrial corridor hosts regional manufacturing clusters serving Mercosur distribution networks with localized fragrance and packaging adaptations.
Japan
Cold-water washing enzymes are expanding adoption among utility-conscious consumers in Tokyo and Osaka metropolitan areas. METI energy efficiency standards and JIS quality benchmarks shape formulation requirements for domestic manufacturers. Kao Corporation anchors production in the Kansai region, where concentrated unit-dose formats dominate machine-ownership-saturated households.
Home Care Products Market Vendor Landscape
Global majors compete with regional champions across formulation technology and sustainability credentials, producing a tiered structure where scale advantages collide with local adaptation speed. The vendor base separates into three archetypes: multinational conglomerates with integrated surfactant supply chains, regional specialists with deep distribution in emerging markets, and private-label platforms leveraging direct-to-consumer channels. M&A activity concentrates on bio-based ingredient startups and refill infrastructure technology. Strategic partnerships between retailers and formulators are securing exclusive shelf space for concentrated refill formats.
Among multinational conglomerates, Procter & Gamble, Unilever, and Henkel exemplify the scale-driven archetype with global manufacturing footprints and portfolio breadth across laundry, surface care, and air freshener categories. These Cincinnati-, London-, and Düsseldorf-based entities occupy positions where sustainability credentials and concentrated format innovation determine competitive standing against regional challengers.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| Henkel |
| Reckitt Benckiser Group |
| Church & Dwight |
| S.C. Johnson & Son |
| The Clorox Company |
| Kao Corporation |
| Godrej Consumer Products |
| Others |
Supply Flow & Price Mechanics
Enzymatic cold-water tiers command 40-60% premiums over legacy petrochemical formulations while sourcing from entirely different supplier bases. REACH-compliant bio-surfactant grades draw from Malaysian and Indonesian palm kernel plantations with ESG certification gating, whereas commodity lauryl sulfates flow through spot markets with minimal traceability. This bifurcation concentrates margin capture among formulators with backward-integrated oleochemical capabilities while compressing pricing power for buyers dependent on spot surfactant markets.
Pricing Analysis
Service bundling separates subscription auto-ship models from transactional retail, with Unilever and P&G embedding algorithmic replenishment into pricing architecture. Three-tier pricing structure across premium enzymatic, standard petrochemical, and economy private-label levels reflects certification grade and cold-water performance claims. Pricing pressure stems from palm kernel oil volatility tied to Malaysian export policy fluctuations, eroding per-wash cost advantages for concentrated formats. Family households with children under twelve show lowest price sensitivity given packaging waste concerns, while single-person urban units in India prioritize sachet affordability over performance tier.
Supply Chain Analysis
EU Green Deal CSRD certification gates supplier qualification, forcing documentation of carbon intensity at SKU level for German and French retail networks. Geographic concentration centers on Malaysia and Indonesia for palm-derived surfactant precursors, Germany and Netherlands for enzymatic formulation technology, and India for sachet-format packaging substrates. Raw material dependencies include lauryl sulfate precursors, glutamic acid chelating agents, and cold-water enzyme stabilizers. Single-source vulnerability runs through Malaysian palm kernel oil exports subject to biodiesel policy diversion. Distribution runs through supermarket refill infrastructure in Germany, kirana store networks in India, and direct-to-consumer auto-ship in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized bio-surfactant capacity constraints prop pricing premiums as REACH registration timelines stretch 18-24 months for novel plant-derived actives. This supply bottleneck protects margin pools for incumbents with qualified feedstock pipelines while elevating entry costs for commodity challengers.
For Market Incumbents: Deploy backward integration into certified palm kernel supply bases to lock in ESG-compliant feedstock access. Secure exclusive refill station partnerships with German drugstore chains and French supermarket networks before shelf space saturation. Counter direct-to-consumer subscription threats by embedding IoT-enabled dispensing systems into private-label smart home ecosystems, capturing recurring consumable revenue through hardware lock-in.
For New Entrants and Emerging Players: Rural Indian kirana store networks remain underserved by organized sachet-format distribution against Tier-1 city retail concentration. Tier-2 and Tier-3 households in Maharashtra and Gujarat present penetrable white space with localized fragrance adaptations and vernacular packaging. Partner with regional FMCG distributors possessing established kirana relationships rather than building parallel logistics infrastructure.
For Investors and Strategic Acquirers: Re-rating potential sits with bio-based surfactant specialists given REACH substance restriction proposals accelerating plant-derived substitution timelines. Long-term viability favors formulators with integrated enzymatic stabilization capabilities and CSRD-compliant carbon accounting systems. Watch EPA FIFRA registration acceleration for novel antimicrobial actives as inflection signal—timeline compression from 18 to 12 months would unlock sanitizing subcategory innovation pipelines and expand addressable margin pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Refill Infrastructure Expansion | French and British supermarket aisle conversion to bulk dispensing systems displaces pre-packaged SKU economics. |
| Backward Integration into Oleochemicals | Captive supply of Malaysian and Indonesian palm kernel derivatives insulates against export policy volatility. |
| Enzymatic Cold-Water Formulation | Nordic utility-conscious households drive adoption of energy-saving washing technologies with premium pricing power. |
| Direct-to-Consumer Auto-Ship Launch | Millennial United States households abandon warehouse club bulk purchasing for algorithmic replenishment lock-in. |
| CSRD Compliance System Deployment | German manufacturers retrofit batch manufacturing execution systems to track carbon intensity at SKU level for EU Green Deal transparency. |
Methodological Framework
Independent corroboration across formulation chemists at European surfactant producers, procurement leads at German retailers, and regulatory affairs directors navigating REACH compliance underwrites the qualitative findings. Primary interviews with plant managers at Malaysian oleochemical facilities, category buyers at French supermarket chains, and supply planners at United States direct-to-consumer brands combined with secondary validation from ECHA substance restriction proposals, customs trade data on palm kernel oil flows, and SEC 10-K disclosures from listed home care manufacturers. Bottom-up SKU-level volume modeling and top-down category value triangulation anchored the market sizing framework.
Comparable historical reference periods spanning conventional petrochemical dominance through bio-surfactant transition enabled projection anchoring across the analysis window. Segmentation dimensions modeled include product type, household composition, distribution channel, and usage frequency alongside regional regulatory cluster differentiation. CAGRs derived from volume trajectory analysis incorporating urban household formation rates, machine ownership saturation curves, and refill infrastructure penetration assumptions. Industry-specific forecast inputs encompassed REACH registration pipeline timelines and EPA FIFRA approval velocity for novel antimicrobial actives.
Revisions become necessary when Malaysian or Indonesian export policy shifts materially alter palm kernel oil availability, or when EPA FIFRA timelines compress or extend beyond modeled assumptions. Forecasts reflect documented assumptions regarding enzymatic stabilization technology adoption curves and refill station retail economics. A model refresh is warranted upon material change in EU Green Deal packaging mandate enforcement intensity or CSRD carbon accounting requirement implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
House Call Market
Home Healthcare
US Home Infusion Therapy Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
Home Care Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Global Home Infusion Therapy Market