
 Home Healthcare Market | 2026-2036
Home Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Home Healthcare Market Intelligence
Software-defined telehealth consultations as a service model is expanding the scope of care delivery beyond traditional hardware sales. Philips leverages its expertise in connected devices to offer integrated solutions for remote patient monitoring. ResMed specializes in respiratory care, providing cloud-connected devices for managing conditions like sleep apnea and COPD from home. Amedisys focuses on providing a wide spectrum of in-home services, including skilled nursing and hospice care.
Home healthcare involves the delivery of clinical and non-clinical services to individuals in their place of residence. It utilizes portable medical equipment, such as remote patient monitoring devices, and telehealth platforms to manage health conditions outside of institutional settings. The primary purpose is to improve patient outcomes, manage chronic illnesses, and support post-acute recovery. Remote patient monitoring devices represent the fastest-growing product segment, driven by the need for continuous data in chronic disease management. Skilled nursing services remain a foundational component, especially for complex post-operative care and rehabilitation therapy.
Regulatory frameworks from bodies like the US FDA, Europe's EMA, and China's NMPA set the standards for device safety and efficacy. These regulations, alongside data privacy laws like GDPR and HIPAA, govern market access and product design for home health technologies. Reimbursement policies from public and private payers are a critical determinant of service adoption. Success for providers depends on demonstrating improved patient outcomes and cost-effectiveness to navigate these evolving payment structures.
Market Dynamics
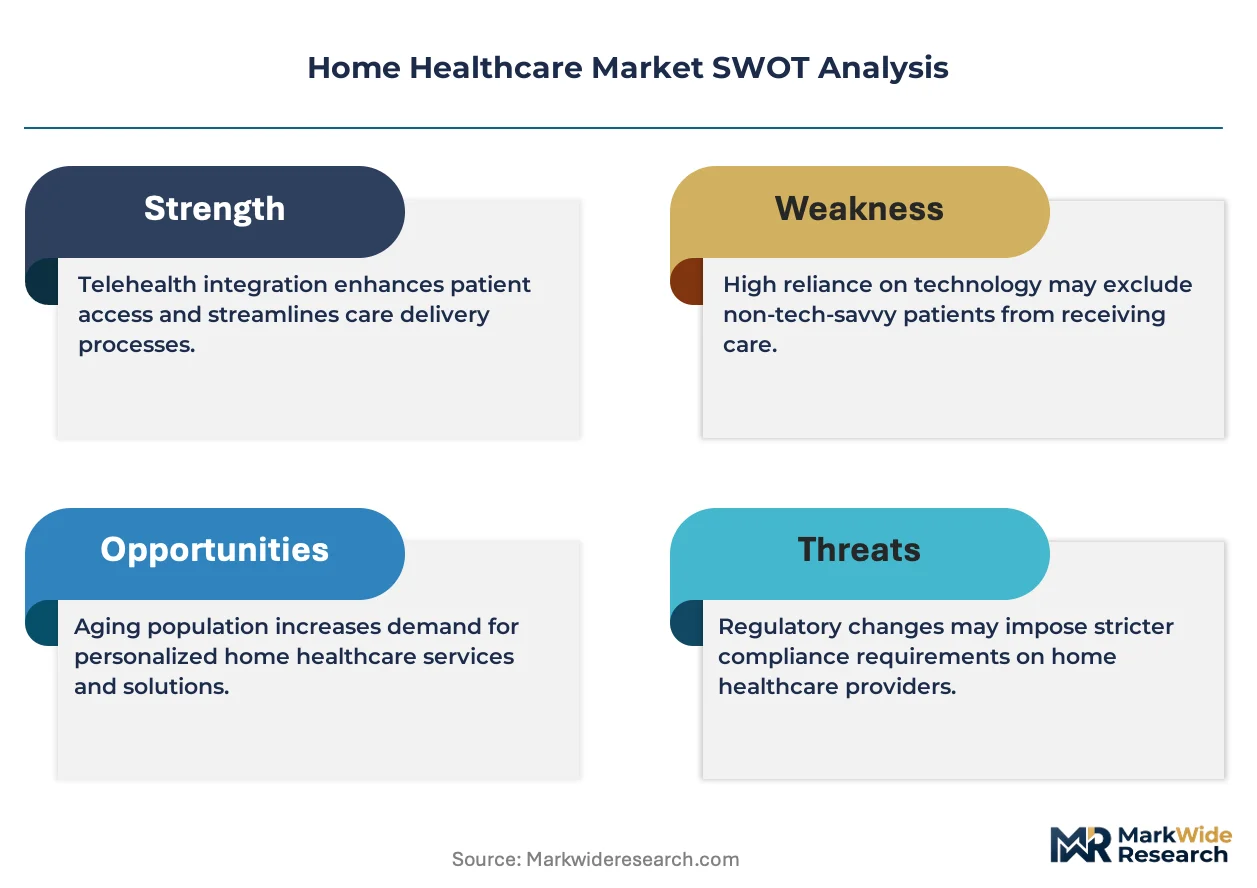
The integration of remote patient monitoring technology and telehealth platforms is reshaping the home healthcare market, driven by the need to manage chronic diseases in aging populations and shift care away from costly institutional settings.
Growth Catalysts
- Reimbursement Expansion:Favorable payment structures for home-based care in countries like Germany provide a stable financial foundation, encouraging service adoption.
- Aging Demographics:The growing elderly population in nations like Japan creates sustained structural demand for in-home chronic disease management and skilled nursing.
- Device Connectivity:IoT integration enables more reliable remote patient monitoring, improving data quality and timeliness for clinicians to use in diagnostics.
Market Restraints
- Data Interoperability:Lack of standardized data formats between home health platforms and hospital EHR systems creates significant barriers to seamless information exchange.
- Regulatory Fragmentation:Disparate data privacy laws, such as Europe's GDPR and the US's HIPAA, complicate the design of unified telehealth platforms.
- Workforce Shortages:A persistent shortage of skilled nurses and aides trained in telehealth technologies limits service expansion capacity in many regions.
Strategic Opportunities
- Preventative Care Models:Expanding services beyond chronic disease management into proactive wellness and preventative monitoring represents a significant area for new service development.
- Emerging Geographies:Underpenetrated regions like Southeast Asia offer growth potential as digital infrastructure improves and healthcare spending increases.
- Technology Convergence:Integrating consumer wearables with clinical-grade remote monitoring systems can create a more holistic view of patient health status.
Industry Challenges
- System Integration Complexity:Integrating new home health software with legacy electronic health record (EHR) systems in hospitals is a major technical and operational hurdle for providers.
- Clinician Training and Adoption:Ensuring healthcare professionals are adequately trained and willing to adopt new digital tools and workflows is critical for successful implementation of telehealth services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Healthcare Market |
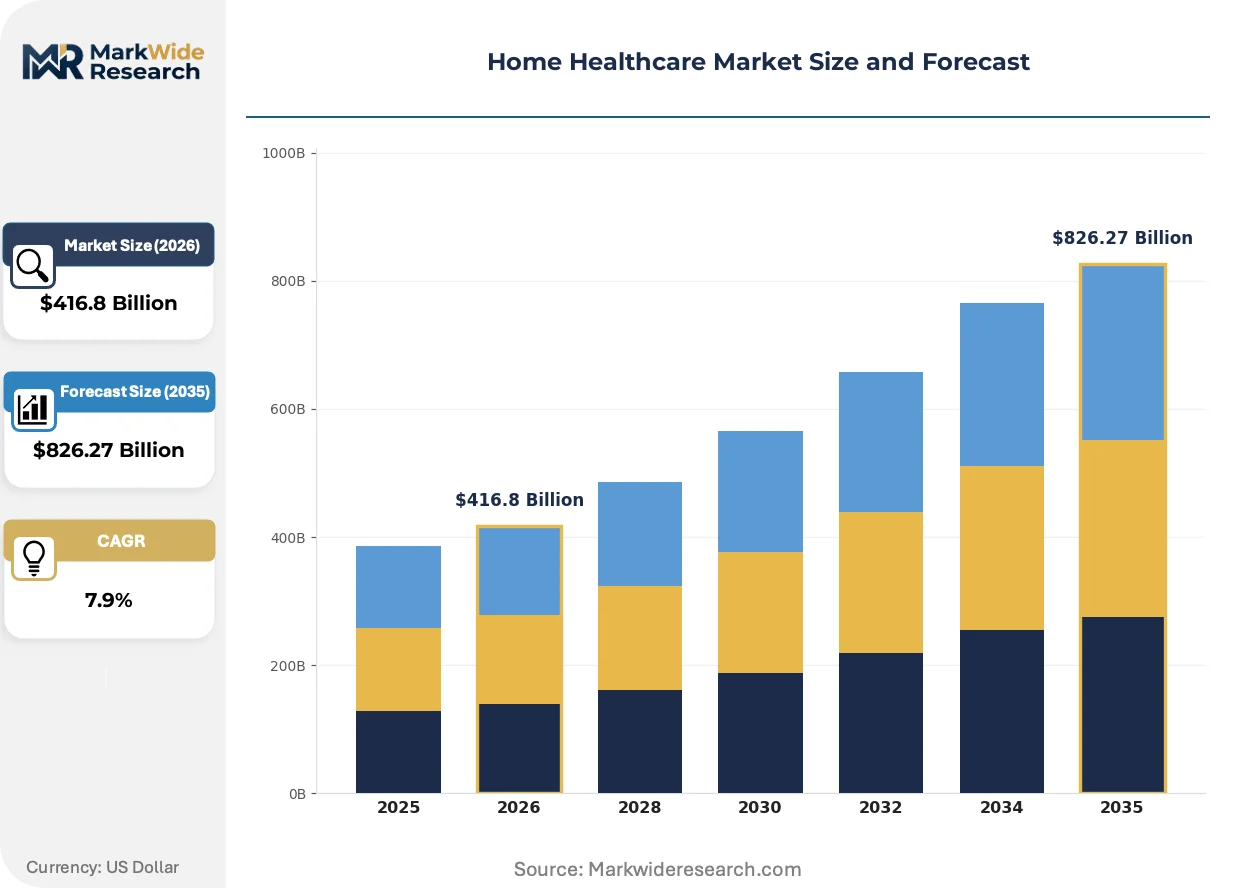
| Market Size in 2026 | $416.8 Billion |
| Market Size in 2035 | $826.27 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Patient Monitoring Devices, Mobility Aids, Respiratory Equipment, Personal Emergency Response Systems, Wound Care Products Application: Chronic Disease Management, Post-Operative Care, Elderly Care, Rehabilitation Therapy, Palliative Care End User: Home Health Agencies, Hospice Providers, Assisted Living Facilities, Family Caregivers, Private Duty Nurses Service Model: Skilled Nursing Services, Physical Therapy, Telehealth Consultations, Medication Management, Medical Social Services |
| Companies Covered | Philips, Abbott, Fresenius Medical Care, ResMed, Medtronic, Baxter International, Amedisys, B. Braun Melsungen, Omron Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Healthcare Market Strategic Shifts & Innovations
Software-driven intelligence is transforming home healthcare from a reactive, event-based service into a proactive and predictive model of continuous care. This shift prioritizes early intervention and personalized patient management through constant data analysis.
Artificial intelligence analytics platforms are being integrated with remote patient monitoring devices to analyze continuous physiological data streams. Chronic care management providers are the primary adopters, seeking efficiency in overseeing large patient populations. This technology is automating the detection of early warning signs and the triage of clinical alerts, enabling staff to focus on high-risk individuals.
The European Union’s Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance on home health devices. This measure increases the compliance burden and development costs for manufacturers of connected medical equipment. Consequently, device makers targeting the European market must now invest more heavily in clinical trials and robust quality management systems.
Service delivery models are evolving from one-time hardware sales to subscription-based arrangements for telehealth and remote monitoring. This change disrupts traditional durable medical equipment sales channels, favoring direct relationships between service providers and payers. This trend is most pronounced in North American and European markets where predictable operational expenditures are valued over large capital outlays.
Home Healthcare Market Segmentation
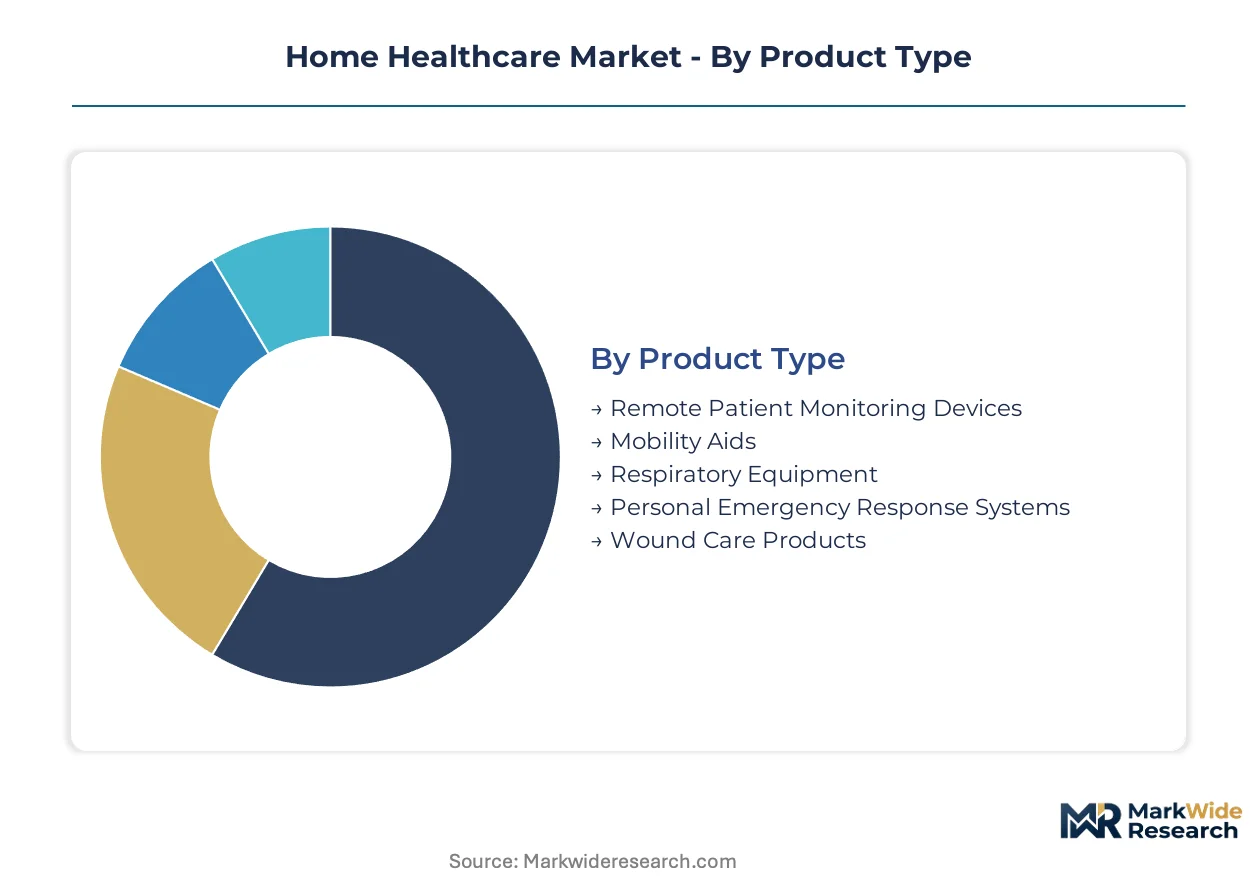
Market segmentation provides a structured view of the home healthcare landscape, highlighting distinct areas of service and product delivery. Understanding these segments is crucial for providers to tailor offerings and for payers to optimize reimbursement strategies. This detailed classification helps stakeholders identify key growth vectors and specific patient needs.
Product Type:
Product selection for home healthcare is often driven by the specific medical needs and daily living support required by patients.
- Remote Patient Monitoring Devices:These technologies continuously collect physiological data, such as blood pressure or glucose levels, transmitting it to clinicians for proactive health management. Demand is concentrating in chronic disease management for aging populations in countries like Germany, where integrated care models are well-supported.
- Respiratory Equipment:This category includes devices like oxygen concentrators, CPAP machines, and ventilators, essential for managing chronic respiratory conditions from a patient's home. Demand is significant among individuals with COPD and sleep apnea, particularly in North American and European markets.
- Mobility Aids:Assistive devices such as wheelchairs, walkers, and crutches support independent movement and prevent falls for patients with physical limitations.
- Personal Emergency Response Systems:These systems offer immediate assistance during falls or medical emergencies, providing a critical safety net for elderly individuals living alone.
- Wound Care Products:Specialized dressings, bandages, and topical agents are essential for managing complex wounds and promoting healing in a home setting.
Volume sits with Mobility Aids; growth tilts toward Remote Patient Monitoring Devices.
Application:
The application dictates the scope and intensity of home care services, directly impacting resource allocation and specialized personnel requirements.
- Chronic Disease Management:This application involves continuous monitoring, medication adherence support, and lifestyle guidance for long-term conditions like diabetes, heart failure, or hypertension. Demand is prevalent in regions with high elderly populations and structured reimbursement, such as Germany, where integrated care improves patient outcomes.
- Elderly Care:This segment encompasses comprehensive support services including personal care, medication assistance, companionship, and household help for older adults to maintain independence at home. Demand is increasing significantly in countries like Japan due to pronounced demographic shifts and a preference for in-home aging.
- Post-Operative Care:This application focuses on recovery support, pain management, and wound care after surgical procedures, facilitating patient recuperation outside of institutional settings.
- Rehabilitation Therapy:Physical, occupational, and speech therapies are delivered at home to help patients regain function, mobility, and independence following injury, stroke, or illness.
- Palliative Care:Palliative services provide comfort, symptom management, and emotional support for individuals with serious illnesses, aiming to improve their quality of life.
Chronic Disease Management accounts for the largest share, with Elderly Care gaining share fastest.
End User:
The end-user segment determines the primary point of service delivery and care coordination, influencing operational models and partnership strategies.
- Home Health Agencies:These organizations provide a wide range of medical and non-medical services directly to patients' residences, often coordinating multiple care disciplines. Home Health Agencies are central to care coordination in the US market due to established reimbursement models and regulatory frameworks.
- Family Caregivers:Informal support networks, typically family members, provide essential daily care and assistance, often leveraging technology for remote guidance and support. Family Caregivers are critical in many Asian markets where familial responsibility for elders is culturally strong and healthcare infrastructure is developing.
- Hospice Providers:These specialized agencies offer comfort, pain management, and emotional support for individuals nearing the end of life, focusing on dignity and quality of remaining time.
- Assisted Living Facilities:These facilities provide housing, personal care, and some health services for residents who require daily assistance but not complex medical care.
- Private Duty Nurses:Individual nurses offer personalized, one-on-one medical care in a patient's home, often addressing complex needs or providing continuous skilled observation.
Home Health Agencies capture significant revenue, as Family Caregivers drive volume in emerging economies.
Service Model:
The service model defines the specific type of care intervention delivered to patients, impacting staffing requirements and technological integration.
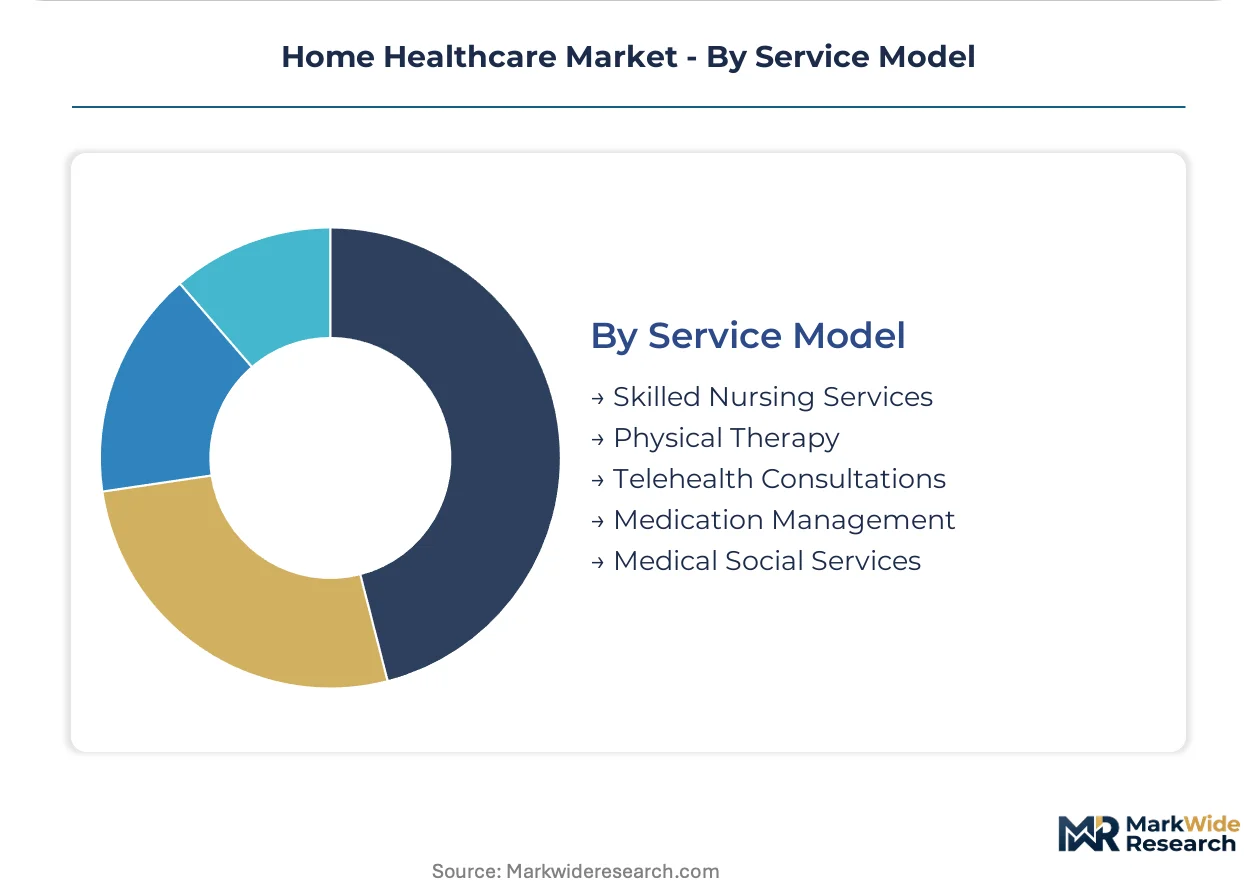
- Skilled Nursing Services:These services encompass direct medical care provided by licensed nurses, including medication administration, wound care, catheter care, and patient education. Skilled nursing is foundational for post-acute recovery and complex chronic disease management in markets like Europe, where demand for in-home medical expertise is high.
- Telehealth Consultations:This model involves the remote delivery of healthcare services via digital platforms, enabling virtual doctor visits, specialist consultations, and ongoing patient monitoring. Telehealth Consultations are rapidly increasing across North America and Europe due to their convenience, cost-effectiveness, and ability to expand access to care.
- Physical Therapy:Therapists provide exercises and interventions at home to improve mobility, strength, and function following injury, surgery, or neurological conditions.
- Medication Management:This service ensures patients take their prescribed medications correctly and on schedule, preventing adverse drug events and improving treatment adherence.
- Medical Social Services:Social workers offer emotional support, resource coordination, and guidance for patients and their families, addressing social determinants of health and facilitating access to community programs.
Skilled Nursing Services remain a core component, while Telehealth Consultations are on the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption of home healthcare services frequently outpaces domestic production capabilities in many advanced economies. Demand for in-home care is particularly high in countries with aging populations, driving significant market expansion across various segments. This structural imbalance necessitates targeted policy interventions and technological integration to meet evolving patient needs effectively.
Germany
Demand for home-based care in Germany stems from its aging population and strong emphasis on integrated care models. Favorable payment structures for home-based care, supported by the national health insurance system, provide a stable financial foundation. Berlin and Munich are centers for digital health startups developing new telehealth platforms for remote patient monitoring.
Japan
Japan's rapidly aging demographics create sustained structural demand for in-home chronic disease management and skilled nursing services. The Ministry of Health, Labour and Welfare (MHLW) actively promotes community-based integrated care systems. Tokyo and Osaka are hubs for advanced robotics and assistive technologies enhancing elderly care at home.
United States
The United States experiences significant demand for post-acute recovery and chronic disease management in home settings. Regulatory frameworks like HIPAA govern data privacy, while Medicare and Medicaid policies influence reimbursement for home health services. California and Florida exhibit high concentrations of home health agencies serving diverse patient populations.
United Kingdom
Aging populations and a focus on reducing hospital readmissions drive demand for home healthcare services across the United Kingdom. The National Health Service (NHS) increasingly funds community-based care initiatives and telehealth programs. London and Manchester are developing smart home technologies and digital platforms for remote patient support.
Home Healthcare Market Key Industry Players
Capital-heavy producers of medical devices compete with asset-light service providers in the home healthcare market. The market exhibits a tiered structure, with established medical device manufacturers alongside specialized telehealth platforms and comprehensive home health agencies. Strategic archetypes include integrated solution providers, niche technology specialists, and broad-spectrum service operators. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and service offerings.
Specialized technology developers and comprehensive service providers define distinct segments within the competitive landscape. Philips, a Netherlands-based technology company, exemplifies an integrated solution provider, leveraging its connected device expertise to offer holistic remote patient monitoring solutions. ResMed, an Australian-American medical equipment company, represents a niche technology specialist, focused on cloud-connected respiratory care devices for conditions like sleep apnea and COPD. Amedisys, a US-based healthcare company, occupies the broad-spectrum service operator archetype, delivering a wide array of skilled nursing and hospice care services directly to patients' homes.
| Leading Market Players |
|---|
| Philips |
| Abbott |
| Fresenius Medical Care |
| ResMed |
| Medtronic |
| Baxter International |
| Amedisys |
| B. Braun Melsungen |
| Omron Healthcare |
| Others |
Cost & Logistics Intelligence
The regulatory certification ladder for medical devices creates a clear performance gap in home healthcare, manifesting in premium pricing for compliant technologies and specialized supply chains for certified components.
Pricing Analysis
Price erosion across basic home healthcare devices traces to increased competition from Asian manufacturers and commoditization. Value-based pricing models are gaining traction for integrated solutions, alongside subscription-based arrangements for telehealth and remote monitoring services. Price differentiation stems from device certification, such as NMPA approval in China, and comprehensive after-sales service bundles. Family caregivers demonstrate high price sensitivity for non-reimbursed equipment, while Home Health Agencies prioritize clinical efficacy and reliable support for complex patient needs.
Supply Chain Analysis
Single-source vulnerability sits with specialized sensor manufacturers located primarily in China and Taiwan for remote patient monitoring devices. The global home healthcare supply chain draws from manufacturing hubs in Germany for precision medical equipment and the US for advanced software platforms. Key dependencies include microcontrollers, medical-grade plastics, and specialized battery cells. Geopolitical tensions affecting component availability represent a structural risk. Distribution runs through established medical distributors and direct-to-agency channels for integrated solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home healthcare market presents a significant cost-of-compliance story. Europe’s Medical Device Regulation (MDR) creates a substantial barrier-to-entry moat for device manufacturers, demanding rigorous clinical evidence and post-market surveillance.
For Market Incumbents: Anticipate continued pressure from software-defined telehealth platforms displacing traditional hardware sales. Incumbents must deepen vertical integration into software development and invest in AI analytics for predictive care models. This strategy defends against margin compression from niche technology specialists and extends market reach through outcome-based service contracts.
For New Entrants and Emerging Players: A significant price-point gap exists for accessible, user-friendly remote monitoring solutions targeting underserved populations in emerging geographies. Target preventative care models in Southeast Asia, leveraging improving digital infrastructure. Focus on integrating consumer wearables with clinical-grade systems to offer holistic health views. A direct-to-consumer subscription model, emphasizing affordability and ease of use, provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with integrated solution providers given the shift to value-based care and subscription models. Long-term viability favors companies demonstrating superior patient outcomes and cost-effectiveness in chronic disease management over the next decade. Target mid-cap technology specialists with proprietary AI analytics platforms or strong regional telehealth penetration. The signal to watch is the expansion of favorable reimbursement policies for remote patient monitoring in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen AI-driven predictive analytics | Enables early detection of health deterioration, improving patient outcomes for chronic conditions. |
| Expand telehealth consultation services | Increases access to care for remote populations and reduces institutional healthcare costs. |
| Pursue CE Marking and FDA clearance | Ensures market access for connected medical devices in European and US markets. |
| Form strategic partnerships with payers | Secures long-term contracts and aligns incentives for value-based care delivery. |
| Invest in skilled nursing workforce training | Addresses critical labor shortages and enhances the quality of in-home medical expertise. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary research involved interviews with home health agency executives, medical device manufacturers, and payer representatives. These insights were triangulated with data from the US FDA, Europe’s EMA, and China’s NMPA, along with academic literature. A robust bottom-up and top-down approach ensured comprehensive market sizing and validation.
Market sizing was modeled at a granular level across product type, application, end-user, and service model segments. The analytical framework integrated historical growth trends with projected demand drivers over the projection horizon. Compound Annual Growth Rates were derived from an assessment of technological advancements and evolving regulatory landscapes. Key inputs included demographic shifts in aging populations and healthcare expenditure forecasts.
Inputs from published reports and industry interviews were available through the study window; gaps in real-time patient adoption data introduce uncertainty bands. Forecasts reflect assumptions regarding technological integration and reimbursement policy evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Global Nursing Care Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
Global Home Infusion Therapy Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Home Care Service Market
Home Healthcare
Elder Care Products Market
Home Healthcare
Home Care Products Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Global Health Caregiving Market