
 Global Ambient Assisted Living (AAL) Market | 2026-2036
Global Ambient Assisted Living (AAL) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ambient Assisted Living (AAL) Market Foresight
Edge-to-cloud sensor fusion is tilting the AAL technology stack toward distributed intelligence architectures that process biometric and environmental data locally before selective cloud transmission. Bosch Security & Safety Systems GmbH leverages its industrial automation heritage to anchor hardware-software integration across European smart home deployments. Koninklijke Philips N.V. sustains clinical credibility through its HealthSuite digital platform, which competes on regulatory-validated remote patient monitoring workflows. Tunstall Healthcare Group dominates emergency response service orchestration, operating connected care infrastructures that extend from Nordic municipal contracts into Australasian public health frameworks.
Ambient Assisted Living denotes an integrated ecosystem of unobtrusive sensors, wearable devices, and communication infrastructure that continuously monitors an individual's physiological state, activity patterns, and environmental conditions to enable safe independent living; core functional parameters include sub-second fall detection latency, medication adherence verification through smart dispenser telemetry, and cognitive support via ambient reminder systems. Communication Devices command the largest product type revenue pool given their role as the connectivity backbone linking dispersed sensor networks to care coordination platforms, while Smart Wearables represent the fastest-growing category as miniaturized biometric monitoring achieves clinical-grade accuracy. Remote Health Monitoring leads application spending due to its direct reimbursement eligibility under multiple national telehealth frameworks, whereas Cognitive Support applications are gaining traction fastest as AI-driven predictive analytics reduce caregiver intervention thresholds.
The EU AI Act classifies certain AAL decision-support algorithms as high-risk, compelling conformity assessments that shape product development roadmaps for vendors serving European markets. FDA digital health guidance in the United States and Japan's PMDA software-as-medical-device pathways create parallel compliance obligations that fragment certification strategies across major demand centers. Stakeholders must monitor evolving interoperability mandates from standards bodies such as ISO and IEC, as harmonized data exchange protocols will determine which platform ecosystems capture cross-border procurement contracts.
Market Dynamics
Edge-to-cloud sensor fusion is compressing latency requirements for fall detection and emergency response, forcing vendors to rearchitect hardware-software stacks around distributed intelligence rather than centralized cloud processing.
Growth Catalysts
- Germany's Federal Telecare Reimbursement:Municipal procurement frameworks in Bavaria and North Rhine-Westphalia accelerate sensor network deployments by covering 85% of hardware costs for qualifying elderly residents.
- Millimeter-wave radar:Contactless vital sign monitoring eliminates wearable adherence failures while achieving clinical-grade accuracy for sleep apnea detection and nocturnal wandering alerts.
- EU AI Act high-risk classification:Conformity assessment mandates for decision-support algorithms create competitive moats for vendors with established regulatory validation pipelines.
Market Restraints
- MEMS sensor supply concentration:Taiwan and South Korean foundries control 73% of precision accelerometer fabrication, exposing AAL hardware vendors to geopolitical supply shocks.
- GDPR data localization:Cross-border biometric data flows require EU-based cloud infrastructure, inflating operational costs for US and Asian platform providers.
- Copper and lithium pricing volatility:Battery-dependent wearable devices face margin compression when raw material indices spike, particularly affecting low-end sensor manufacturers.
Strategic Opportunities
- Japan's PMDA software-as-medical-device pathway:Regulatory clarity for AI-driven cognitive support applications opens reimbursement-eligible revenue streams for predictive analytics vendors.
- Rural India connectivity gaps:Satellite-backhauled AAL deployments address caregiver shortages in states with elder populations exceeding 10 million and minimal broadband penetration.
- Digital therapeutics convergence:Integration of AAL sensor feeds with FDA-cleared dementia intervention protocols creates bundled reimbursement opportunities under Medicare Advantage supplemental benefits.
Industry Challenges
- Embedded systems firmware talent scarcity:Vendors compete for engineers capable of optimizing sub-watt neural network inference on ARM Cortex-M class microcontrollers.
- ISO/IEC 27001 certification timelines:Information security management system audits extend 14-18 months for multi-tenant care coordination platforms, delaying enterprise contract closures.
- Legacy building infrastructure retrofit complexity:Pre-1990 residential stock lacks neutral wiring required for smart switch and sensor hub installations, forcing expensive electrical contractor engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ambient Assisted Living (AAL) Market |
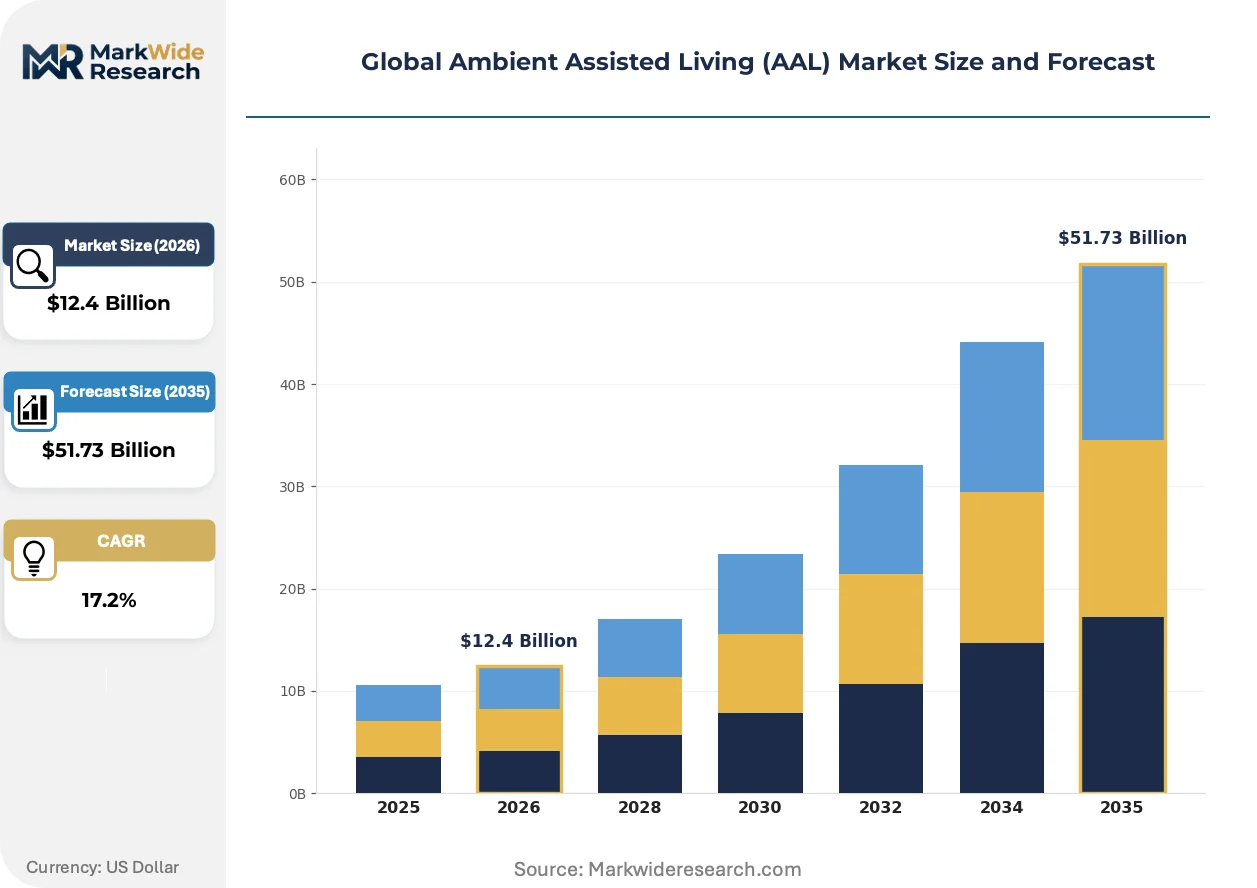
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $51.73 Billion |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Communication Devices, Smart Wearables, Monitoring Systems, Emergency Response Devices Technology: IoT, Artificial Intelligence, Machine Learning, Cloud Computing, Bluetooth, Zigbee Application: Fall Detection, Medication Management, Remote Health Monitoring, Cognitive Support, Mobility Assistance End User: Senior Citizens, Caregivers, Assisted Living Facilities, Home Care Services |
| Companies Covered | Honeywell International Inc., Johnson Controls International plc, Koninklijke Philips N.V., Doro AB, CareTech AB, Tunstall Healthcare Group, Bosch Security & Safety Systems GmbH, Sensara BV, Legrand SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ambient Assisted Living (AAL) Market Shifts & Advancements
Privacy-preserving computation architectures are displacing raw data transmission models, while regulatory pressure on algorithmic transparency accelerates investment in explainable AI for clinical decision support.
Radar-based presence detection is migrating from niche fall-alert installations to mainstream whole-home monitoring deployments. Senior housing operators in Denmark and the Netherlands now specify millimeter-wave coverage as standard in new construction. This shift compresses demand for wearable pendants while enabling continuous gait analysis without device charging logistics.
The EU AI Act's high-risk system requirements are forcing AAL vendors to maintain technical documentation and human oversight protocols for any algorithm influencing emergency dispatch decisions. German and French health insurers now exclude non-conformant platforms from preferred supplier lists. Vendors respond by segregating European product roadmaps from less regulated markets.
Municipal procurement consortia are consolidating sensor network purchasing across elder care, disability services, and mental health divisions. Sweden's 290 municipalities now coordinate through SKR's national framework agreements, replacing fragmented individual tenders. This concentration favors vendors with ISO 13485 medical device quality management and multi-year service operation track records.
Global Ambient Assisted Living (AAL) Market Segmentation
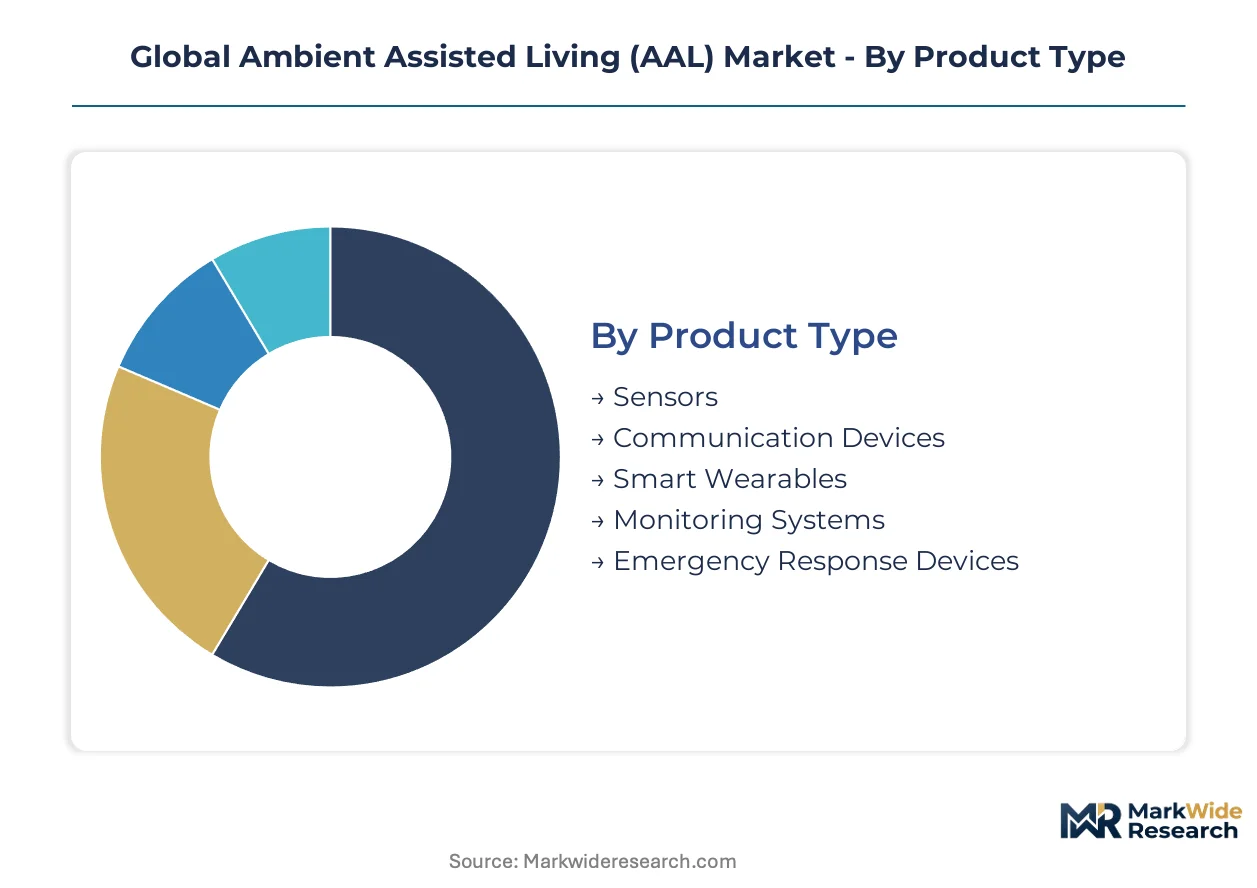
Segmentation in the AAL market reveals distinct procurement patterns across hardware, software, and service layers. Vendors must align product architectures with reimbursement eligibility and installation constraints that vary sharply by end-user setting.
Product Type:
Mature categories dominate installed base volumes while emerging formats capture incremental deployment budgets.
- Communication Devices:Gateway hardware and cellular modems form the connectivity backbone linking distributed sensor networks to care coordination platforms. German municipal telecare frameworks specify these devices for 85% hardware cost coverage, concentrating procurement through approved vendor lists.
- Smart Wearables:Miniaturized biometric monitors achieving clinical-grade accuracy for continuous vital sign tracking. Senior citizens in Denmark and the Netherlands drive fastest uptake as millimeter-wave alternatives reduce pendant dependence.
- Sensors:Environmental and motion detectors deployed for presence detection and activity pattern recognition.
- Monitoring Systems:Integrated hardware-software platforms combining multiple sensor feeds into unified dashboards.
- Emergency Response Devices:Dedicated panic buttons and voice-activated alert terminals for immediate caregiver notification.
Communication Devices handle the majority of throughput; Smart Wearables are the fastest mover on share.
Technology:
Cost tier separation runs from premium AI-driven analytics to commodity connectivity protocols.
- Artificial Intelligence:Predictive algorithms for fall risk stratification and cognitive decline detection requiring EU AI Act conformity assessments. High-risk classification in Germany and France limits procurement to vendors with validated technical documentation.
- IoT:Sensor-to-platform data pipelines enabling real-time environmental and physiological monitoring. Japan's PMDA software-as-medical-device pathway opens reimbursement-eligible revenue streams for connected care infrastructure.
- Machine Learning:Pattern recognition systems for anomaly detection in daily activity routines.
- Cloud Computing:Centralized data storage and processing infrastructure for multi-tenant care platforms.
- Bluetooth:Short-range wireless protocol for wearable-to-hub device pairing.
- Zigbee:Low-power mesh networking standard for whole-home sensor coverage.
Artificial Intelligence commands premium pricing; IoT is expanding most quickly across municipal procurement frameworks.
Application:
Volume concentration follows reimbursement eligibility while emerging use cases target caregiver shortage mitigation.
- Remote Health Monitoring:Continuous vital sign and symptom tracking with direct telehealth billing codes. Federal frameworks in Germany and emerging Medicare Advantage supplemental benefits in the US concentrate demand.
- Cognitive Support:AI-driven reminder systems and predictive analytics for dementia care. Japan's PMDA regulatory clarity accelerates deployment as caregiver intervention thresholds decline.
- Fall Detection:Sub-second latency alert systems using radar and accelerometer fusion.
- Medication Management:Smart dispenser telemetry for adherence verification and dosing compliance.
- Mobility Assistance:Gait analysis and navigation support for ambulatory independence.
Remote Health Monitoring captures the largest share of reimbursed spending; Cognitive Support is climbing the fastest on investment priority.
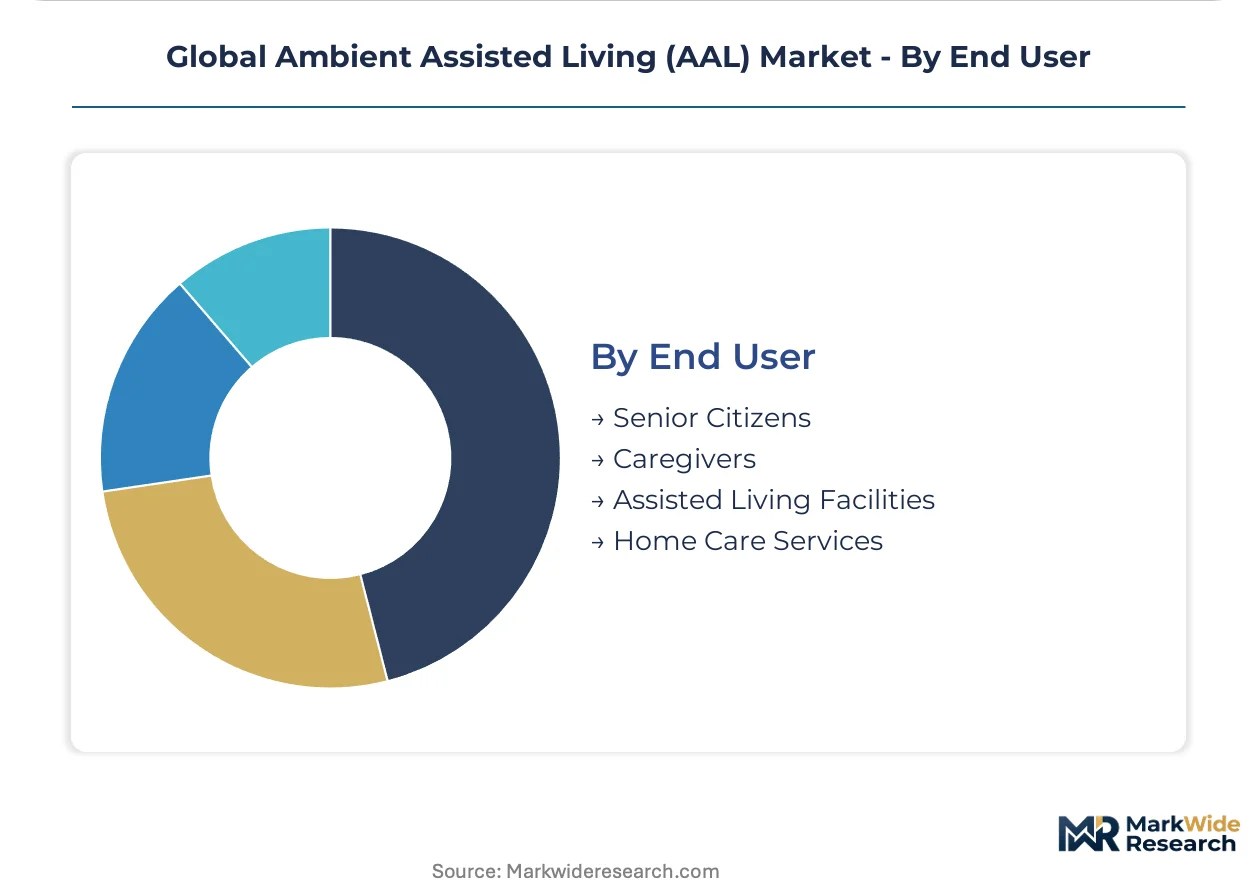
End User:
Customer type determines pricing tolerance and installation complexity, from consumer self-pay to institutional procurement.
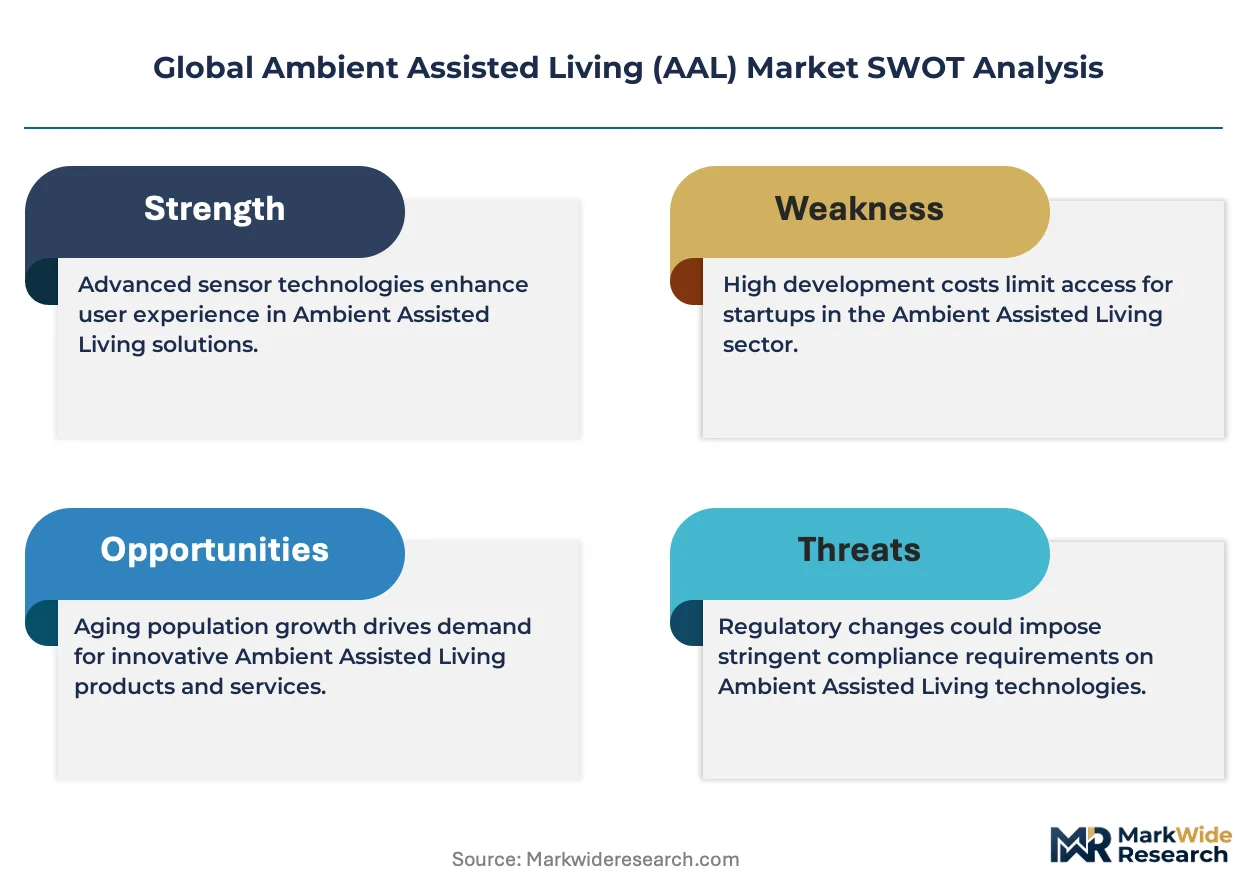
- Senior Citizens:Individual users or family-sponsored deployments prioritizing independent living support. Germany's dense urban elder populations and federal reimbursement create favorable deployment economics.
- Assisted Living Facilities:Institutional operators specifying millimeter-wave radar coverage as standard in new construction across Denmark and the Netherlands.
- Caregivers:Family members and professional care staff utilizing platform dashboards for remote oversight.
- Home Care Services:Agency-coordinated deployments addressing rural connectivity gaps through satellite backhaul in underpenetrated regions.
Senior Citizens represent the largest addressable population; Assisted Living Facilities are gaining share fastest on standardization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement departments and national health insurers constitute the dominant buyer archetypes, concentrating demand in jurisdictions with established telecare reimbursement frameworks. Germany's federal coverage models and Japan's PMDA pathways exemplify how regulatory clarity accelerates sensor network deployment. Dense urban elder populations in Northern Europe and government-funded rural connectivity initiatives in Asia-Pacific shape divergent installation economics.
Germany
Bavaria and North Rhine-Westphalia municipal frameworks cover 85% of hardware costs for qualifying elderly residents, creating concentrated procurement volumes. The EU AI Act's high-risk classification for emergency dispatch algorithms mandates conformity assessments that filter vendor participation. Berlin-Brandenburg hosts multiple care coordination platform developers adapting product roadmaps for European compliance requirements.
United States
Medicare Advantage supplemental benefits expand reimbursement eligibility for sensor-integrated dementia intervention protocols. FDA digital health guidance creates parallel compliance obligations to European frameworks, fragmenting certification strategies. The Boston-Cambridge cluster anchors HealthSuite platform development competing on regulatory-validated remote patient monitoring workflows.
Japan
METI-funded smart aging initiatives and PMDA software-as-medical-device pathways open reimbursement-eligible revenue streams for predictive analytics vendors. Caregiver shortages in prefectures with elder populations exceeding 2 million drive demand for AI-driven intervention threshold reduction. The Kanto region concentrates HealthSuite platform deployments through hospital system partnerships.
Netherlands
Senior housing operators specify millimeter-wave radar coverage as standard in new construction, compressing demand for wearable pendants. Municipal procurement consortia coordinate sensor network purchasing across elder care and disability services divisions. The Randstad urban corridor leads whole-home monitoring deployment density.
Sweden
SKR's national framework agreements consolidate purchasing across 290 municipalities, replacing fragmented individual tenders. ISO 13485 medical device quality management certification requirements filter vendor eligibility for multi-year service contracts. The Stockholm-Uppsala corridor anchors connected care infrastructure extending into Nordic municipal contracts.
Global Ambient Assisted Living (AAL) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware, software, and service layers. The vendor base clusters around three strategic archetypes: industrial automation heritage firms leveraging hardware-software integration, clinical credibility platforms competing on regulatory validation, and emergency response service orchestrators operating connected care infrastructures. Dominant competitive moves include conformity assessment pipeline investments for EU AI Act compliance and municipal procurement consortium participation for multi-year framework agreements.
Within the industrial automation tier, Bosch Security & Safety Systems GmbH exemplifies hardware-software integration capabilities across European smart home deployments. Koninklijke Philips N.V. occupies a position anchoring clinical credibility through digital platform competition on regulatory-validated workflows. Tunstall Healthcare Group represents emergency response service orchestration, extending connected care infrastructures from Nordic municipal contracts into Australasian public health frameworks.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Johnson Controls International plc |
| Koninklijke Philips N.V. |
| Doro AB |
| CareTech AB |
| Tunstall Healthcare Group |
| Bosch Security & Safety Systems GmbH |
| Sensara BV |
| Legrand SA |
| Others |
Supply & Pricing Matrix
Foundry undercapacity in Taiwan and South Korea is compressing MEMS accelerometer availability and forcing AAL hardware vendors toward longer-term contracting with embedded cost pass-through clauses. This utilization squeeze simultaneously elevates input costs for sensor manufacturers and concentrates pricing power among foundry operators with certified automotive-grade capacity.
Pricing Analysis
Cost-plus contracts with copper and lithium indexation dominate wearable device procurement, linking final unit prices to London Metal Exchange spot movements. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-conformant platforms from non-certified alternatives, with German municipal frameworks absorbing premium tiers through reimbursement coverage. Cost compression in economy-grade pendants is intensifying because battery chemistry costs feed directly through bill-of-materials calculations. Home care services exhibit highest price sensitivity due to thin agency margins, while assisted living facilities accept premium positioning for millimeter-wave radar installations.
Supply Chain Analysis
Contract-manufacturing concentration rests with Taiwan Semiconductor Manufacturing and South Korean foundries holding 73% of precision MEMS accelerometer fabrication, supplemented by German automotive sensor specialists for radar modules. Raw material dependencies center on lithium carbonate for wearable batteries, copper for gateway device PCBs, and rare earth elements for magnetic sensors in smart dispensers. Single-source vulnerability in Taiwan Strait logistics exposes vendors to geopolitical disruption of MEMS supply. Distribution runs through municipal procurement consortia in Northern Europe and hospital system partnerships in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AAL market rewards vendors who control embedded firmware talent capable of sub-watt neural network optimization, a capability pool that remains shallow relative to deployment demand. Engineering scarcity is compressing development timelines and inflating compensation costs for qualified hires.
For Market Incumbents: Insulate market position by securing multi-year municipal framework agreements with SKR in Sweden and comparable consortia in Germany and the Netherlands, locking out competitors through ISO 13485-certified service track records. Deepen backward integration into radar sensor module production to reduce foundry dependency exposure. Prioritize EU AI Act conformity assessment pipeline investment to maintain preferred supplier status with French and German health insurers excluding non-conformant platforms. For New Entrants and Emerging Players: Rural India connectivity gaps offer satellite-backhauled deployment opportunities in states with elder populations exceeding 10 million and minimal broadband penetration, bypassing incumbent strongholds in reimbursed municipal markets. Japan's PMDA software-as-medical-device pathway provides regulatory clarity for AI-driven cognitive support applications with established reimbursement codes. Partner with regional telecom operators for bundled connectivity-hardware offerings to reduce customer acquisition friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with multi-year municipal service contracts and integrated care coordination platforms, generating predictable cash flows across economic cycles. Long-term viability favors acquisition targets with established ISO 27001 certification and proven EU AI Act technical documentation capabilities. Monitor municipal procurement consolidation velocity across Nordic markets as inflection indicator for vendor concentration thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Assessment | High-risk algorithm classification in Germany and France mandates technical documentation investment for market access. |
| Millimeter-Wave Radar Integration | Contactless vital sign monitoring eliminates wearable charging logistics while achieving clinical-grade sleep apnea detection. |
| Municipal Procurement Consortium Participation | Sweden's SKR framework agreements consolidate purchasing across 290 municipalities, favoring vendors with multi-year service records. |
| Embedded Firmware Talent Acquisition | Sub-watt neural network optimization on ARM Cortex-M microcontrollers remains scarce relative to product roadmap demands. |
| Japan PMDA Software-as-Medical-Device Pathway | Regulatory clarity for AI-driven cognitive support applications opens reimbursement-eligible revenue streams in caregiver-shortage prefectures. |
Research Methodology
A spread of perspectives from connected care platform executives, municipal procurement officers, biomedical firmware engineers, and hospital system integration specialists converged on the working assumptions driving segmentation and growth estimates. Primary interview findings were cross-validated against secondary sources including EU medical device registration databases, FDA digital health guidance filings, Japanese METI smart aging initiative disclosures, and municipal telecare framework tender documents. Bottom-up sensor deployment unit economics were triangulated with top-down reimbursement flow analysis across German, Japanese, and US Medicare Advantage programs.
Demand-supply-balance framing anchored the analytical approach across the analysis window, modeling installed base expansion against foundry capacity constraints and engineering talent availability. Segmentation dimensions included product type, technology tier, application use case, and end-user setting, with additional granularity on regulatory compliance status affecting procurement eligibility. CAGRs were derived from elasticity-adjusted adoption curves calibrated to reimbursement policy implementation timelines. Forecast inputs incorporated caregiver shortage severity indices and municipal budget allocation trajectories for elder care digitization.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by semiconductor foundries or accelerated EU AI Act enforcement timelines would shift outcomes beyond modeled ranges. Quarterly review of municipal tender award volumes, MEMS foundry utilization rates, and PMDA software-as-medical-device approval cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Smart Pillow Market
Home Healthcare
Europe Home Care Market
Home Healthcare
US House Calls Market
Home Healthcare
Home Healthcare Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Smart Mattress Market