
 Europe Home Care Market | 2026-2036
Europe Home Care Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Care Market Intelligence
Professional cleaning services is realigning the end-use mix as commercial contracts shift toward specialized sanitation protocols. DomusVi Group sustains geographic dominance across French and Iberian home nursing networks. Air Liquide leverages its medical gas infrastructure to anchor respiratory therapy delivery in patient homes. Siemens Healthineers AG competes through connected diagnostic platforms that extend hospital-grade monitoring into domiciliary settings.
Europe home care encompasses products and services delivered in residential settings to maintain hygiene, manage chronic conditions, and support independent living for aging or recovering individuals. Formulations typically feature surfactant concentrations between 15-30% for surface cleaners, with pH buffers adjusted for skin-safe application on high-touch household areas. Household Cleaning leads product type revenue pools due to frequency of purchase and brand loyalty, while Online Retail represents the fastest-growing distribution channel as subscription replenishment models displace supermarket stock-up trips. Senior-focused end user segments command premium pricing through personalized care plans and regulatory compliance overhead.
REACH mandates from ECHA govern chemical substance registration and restrict persistent organic compounds in household formulations. The EU Green Deal drives packaging waste reduction targets that favor concentrated refills and pouches over conventional bottles. EMA guidelines on remote patient monitoring shape reimbursement eligibility for connected home health devices. Stakeholders must track evolving national interpretations of these frameworks to anticipate compliance costs and channel investment toward biodegradable chemistry and digital care infrastructure.
Market Dynamics
Institutional-to-home transitions are compressing hospital length-of-stay timelines and redirecting chronic care budgets toward domiciliary infrastructure across European healthcare systems.
Growth Catalysts
- Aging Demographics:Germany, France, and the United Kingdom exhibit accelerating demand for senior home nursing as birth rates decline and life expectancy extends beyond 80 years.
- REACH Chemical Reformulation:ECHA mandates on biodegradable surfactants are pulling R&D investment toward phosphate-reduced household cleaners that meet environmental release standards.
- Remote Patient Monitoring:Connected diagnostic platforms are integrating with national reimbursement frameworks, expanding reimbursable home health device categories.
Market Restraints
- Labor Cost Escalation:Qualified domiciliary nursing wages in France and the Netherlands are rising faster than public reimbursement rate adjustments.
- Raw Material Concentration:Linear alkylbenzene sulfonate supply chains concentrate in Belgian and German petrochemical clusters, exposing formulators to localized disruption risk.
- Regulatory Fragmentation:Divergent national interpretations of EMA remote monitoring guidelines create compliance overhead for cross-border service providers.
Strategic Opportunities
- Subscription Replenishment Models:Online retail channels in Spain and Italy remain underpenetrated for concentrated refill pouches versus conventional bottle formats.
- Respiratory Therapy at Home:Medical gas infrastructure operators can extend cylinder-to-home delivery networks into Portugal and Eastern European markets.
- EU Green Deal Packaging Targets:Concentrated chemistry formats qualify for reduced waste levies under evolving extended producer responsibility schemes.
Industry Challenges
- Caregiver Certification Bottlenecks:National nursing registries in Germany and France impose 6-12 month credential recognition delays for cross-border workforce mobility.
- Legacy System Integration:Hospital electronic health record platforms require middleware development to synchronize with home-based monitoring devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Care Market |
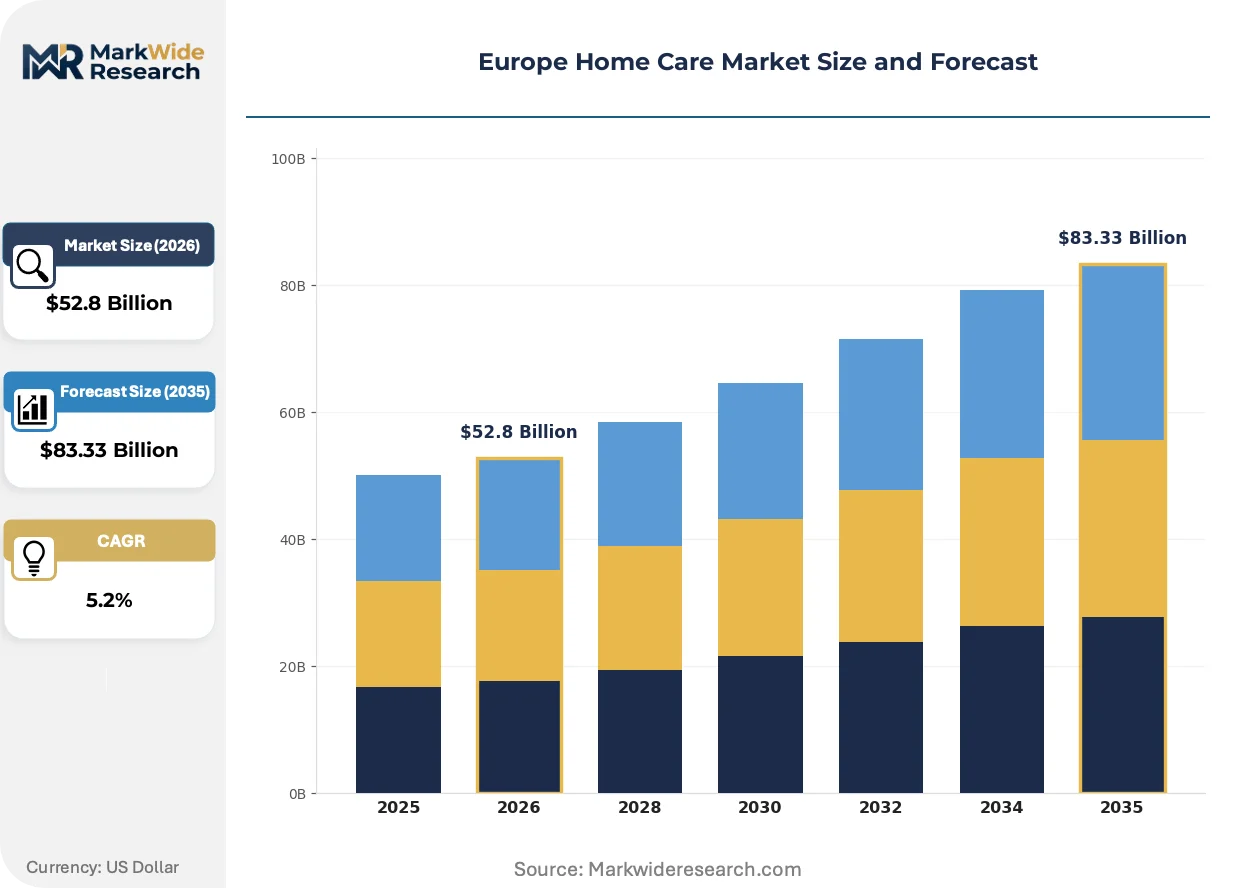
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $83.33 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Household Cleaning, Laundry Care, Dishwashing, Surface Care End User: Households, Seniors, Caregivers, Professional Cleaning Services Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Packaging Type: Bottles, Pouches, Tubes, Cans |
| Companies Covered | DomusVi Group, BAYADA Home Health Care, Siemens Healthineers AG, Air Liquide, OMRON Corporation, Medtronic, Healthcare at Home, Cera, Mears Group PLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Care Market Strategic Shifts & Innovations
Digital care infrastructure and sustainable chemistry are converging to redefine product-service boundaries across European home care markets.
Enzymatic cleaning formulations are integrating into professional sanitation protocols as hospitality and healthcare facilities seek cold-water wash compatibility. Commercial cleaning contractors in the Netherlands and Belgium are adopting lipase-amylase blends to reduce thermal energy consumption. This chemistry is integrating with concentrated pouch delivery systems that cut transport emissions and packaging mass.
REACH authorization requirements are tightening restrictions on per- and polyfluoroalkyl substances in stain-resistant surface treatments. Formulators must phase out fluorinated chemistry by 2025 for non-essential applications. Household cleaning manufacturers in Germany and France are accelerating substitution toward silicone-based and plant-derived alternatives.
Subscription-based replenishment is displacing supermarket stock-up behavior among urban dual-income households. E-commerce platforms in the United Kingdom and Scandinavia are capturing recurring purchase commitments through auto-replenishment algorithms. This channel shift concentrates brand loyalty and reduces price comparison frequency.
Europe Home Care Market Segmentation
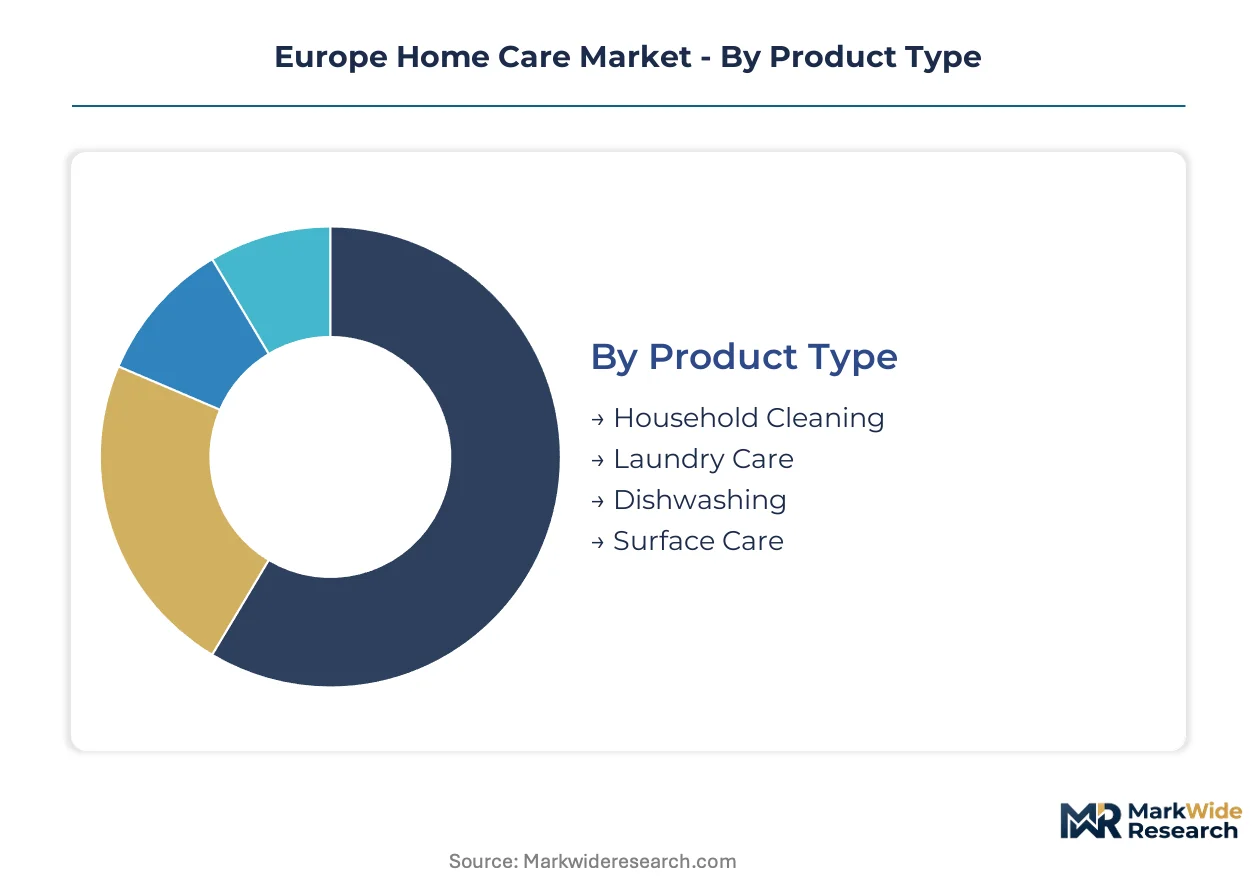
Segmentation in the Europe Home Care Market reveals how product chemistry, care delivery models, and channel infrastructure interlock. Understanding these divisions exposes where biodegradable formulation investments concentrate and which patient populations trigger reimbursement-driven demand.
Product Type:
Standalone surface cleaners dominate routine residential maintenance, while embedded enzymatic systems penetrate professional sanitation contracts requiring cold-water efficacy.
- Household Cleaning:Formulations carry surfactant loads between 15-30% with pH buffers calibrated for skin-safe contact on high-touch surfaces. German and French households drive recurring purchase frequency through brand loyalty to phosphate-reduced compositions meeting REACH environmental release standards.
- Laundry Care:Concentrated refill pouches displace conventional bottles in Scandinavian markets as EU Green Deal packaging targets reshape extended producer responsibility calculations. Enzymatic cold-water compatibility is penetrating Dutch commercial laundry contracts seeking thermal energy reduction.
- Dishwashing:Manual and automatic formulations split between gel concentrates and tablet formats.
- Surface Care:Specialized treatments for wood, glass, and stainless steel carry premium positioning in Iberian markets.
Household Cleaning leads volumes today; Laundry Care is gaining share fastest.
End User:
Cost tier stratification separates premium-priced personalized care plans from mass-market hygiene maintenance.
- Seniors:Personalized care plans command premium pricing through regulatory compliance overhead and domiciliary nursing certification requirements. Germany, France, and the United Kingdom exhibit accelerating demand as life expectancy extends beyond 80 years and institutional-to-home transitions compress hospital length-of-stay timelines.
- Professional Cleaning Services:Commercial contracts are shifting toward specialized sanitation protocols integrating enzymatic cold-water systems. Dutch and Belgian hospitality operators adopt lipase-amylase blends to reduce thermal energy consumption while meeting sustainability procurement criteria.
- Households:Dual-income urban families drive subscription replenishment adoption in United Kingdom and Scandinavian markets.
- Caregivers:Formal and informal care networks purchase assistive hygiene products through reimbursement channels in France and the Netherlands.
Seniors dominate revenue concentration today; Professional Cleaning Services is expanding most quickly.
Distribution Channel:
Volume concentration in traditional retail is fragmenting as digital infrastructure captures recurring purchase commitments.
- Online Retail:Auto-replenishment algorithms concentrate brand loyalty and reduce price comparison frequency among urban dual-income households. United Kingdom and Scandinavian e-commerce platforms lead subscription model penetration while Spain and Italy remain underpenetrated for concentrated refill pouches.
- Supermarkets:Stock-up behavior persists in rural and older demographics with lower digital engagement.
- Specialty Stores:Pharmacies and medical supply retailers anchor reimbursable home health device distribution in German and French markets.
- Convenience Stores:Emergency replenishment and travel-size formats capture impulse purchases in high-footfall urban locations.
Supermarkets retain volume leadership today; Online Retail shows the steepest expansion trajectory.
Packaging Type:
Margin structure favors concentrated formats that qualify for reduced waste levies under evolving extended producer responsibility schemes.
- Pouches:Concentrated chemistry formats cut transport emissions and packaging mass while qualifying for EU Green Deal packaging waste reduction incentives. Refill systems are displacing conventional bottles in Netherlands and Belgian professional cleaning supply chains.
- Bottles:Conventional rigid packaging retains household familiarity but faces rising material cost pressure from petroleum-derived resin volatility.
- Tubes:Squeeze formats dominate personal care and specialty surface treatment applications.
- Cans:Aerosol and pressurized containers persist in specific disinfectant and air care segments despite regulatory scrutiny on propellant chemistry.
Bottles maintain installed base dominance today; Pouches is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance cost differentials are redirecting concentrated chemistry production toward Benelux and German chemical corridors, while service delivery networks expand where national reimbursement frameworks mature fastest.
Germany
Aging demographics and institutional-to-home care transitions drive demand for domiciliary nursing and connected monitoring devices. EMA guidelines on remote patient monitoring shape reimbursement eligibility for home health technologies. The North Rhine-Westphalia chemical cluster anchors phosphate-reduced surfactant production for REACH-compliant household formulations.
France
Senior home nursing networks expand as life expectancy exceeds 80 years and hospital length-of-stay timelines compress. ANSM interprets EMA remote monitoring guidelines for national reimbursement frameworks. The Paris-Île-de-France region concentrates professional cleaning service contracts adopting enzymatic cold-water sanitation protocols.
United Kingdom
Subscription replenishment models displace supermarket stock-up behavior among urban dual-income households. The UK Medicines and Healthcare products Regulatory Agency aligns with EMA guidelines for connected home health devices. London and Southeast England anchor e-commerce platform development for auto-replenishment algorithms.
Netherlands
Commercial cleaning contractors adopt lipase-amylase enzymatic blends to reduce thermal energy consumption. The EU Green Deal packaging waste reduction targets favor concentrated refill pouches over conventional bottles. The Rotterdam-Antwerp chemical corridor supplies linear alkylbenzene sulfonate for biodegradable surfactant formulations.
Spain
Online retail channels remain underpenetrated for concentrated refill pouches versus conventional bottle formats. Spanish interpretations of REACH environmental release standards lag German and French enforcement timelines. Catalonia and Madrid concentrate professional cleaning service networks expanding into specialized sanitation protocols.
Europe Home Care Market Key Industry Players
Geographic expansion dominates the current landscape as service providers extend nursing networks across national borders and chemical formulators relocate production toward REACH-compliant corridors. The market structures around three tiers: integrated healthcare conglomerates with medical gas infrastructure, specialized domiciliary nursing networks, and connected diagnostic platform vendors. Two strategic archetypes predominate: infrastructure-anchored respiratory therapy delivery and digital care platforms extending hospital-grade monitoring. M&A activity concentrates in home nursing network consolidation, while capacity expansion focuses on concentrated chemistry manufacturing for EU Green Deal packaging compliance.
Within the integrated healthcare tier, Air Liquide and Siemens Healthineers AG exemplify divergent infrastructure strategies. Air Liquide occupies a position anchored in medical gas cylinder-to-home delivery networks. Siemens Healthineers AG sits within the connected diagnostic segment, representing the platform archetype that extends hospital-grade monitoring into residential settings. DomusVi Group exemplifies the specialized nursing network model, anchoring geographic dominance across French and Iberian domiciliary care markets.
| Leading Market Players |
|---|
| DomusVi Group |
| BAYADA Home Health Care |
| Siemens Healthineers AG |
| Air Liquide |
| OMRON Corporation |
| Medtronic |
| Healthcare at Home |
| Cera |
| Mears Group PLC |
| Others |
Cost & Logistics Intelligence
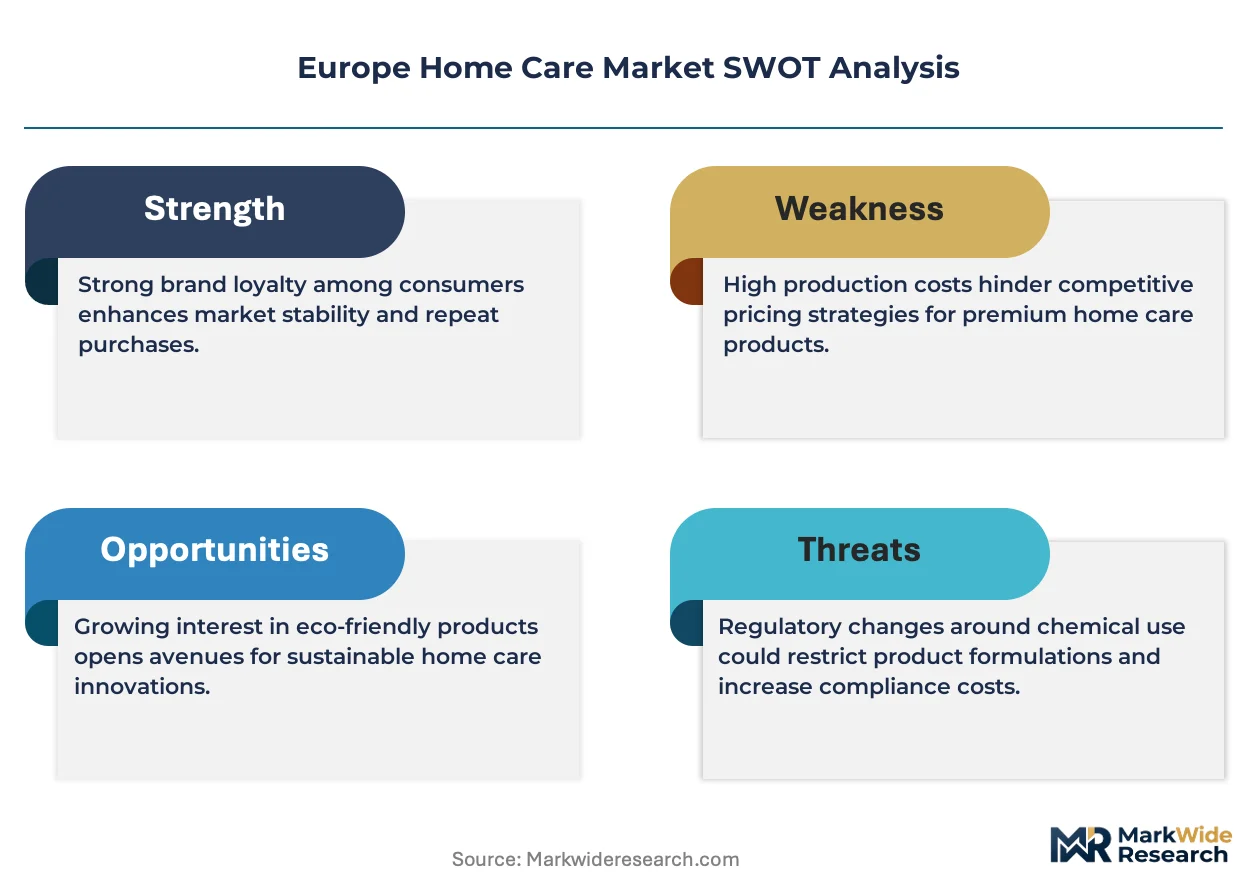
Linear alkylbenzene sulfonate spot prices in the Rotterdam-Antwerp chemical corridor cascade through surfactant formulator margins into three distinct pricing tiers for REACH-compliant household cleaners, with concentrated pouch formats capturing premium positioning against conventional bottle stock-keeping units.
Pricing Analysis
Retailer markup layers in German and French supermarket channels stratify pricing across premium phosphate-reduced formulations, standard biodegradable surfactant blends, and economy-tier conventional chemistry. Certification overhead for ECHA REACH registration and EU Green Deal packaging compliance drives 15-30% price differentiation between tiered product lines. Cost compression in economy-tier manual dishwashing gels intensifies as private-label entrants erode brand loyalty in Iberian markets. Dual-income urban households in Scandinavia exhibit lowest price sensitivity through subscription replenishment commitments, while rural Spanish and Italian demographics remain most responsive to promotional discounting.
Supply Chain Analysis
Single-source vulnerability sits with Belgian and German petrochemical clusters for linear alkylbenzene sulfonate feedstock, exposing formulators to localized disruption risk from Rhine logistics bottlenecks. Raw material dependencies center on petroleum-derived surfactant precursors, phosphate-based builders, and enzymatic additive imports from Danish biotechnology suppliers. Regulatory restriction risk emanates from divergent national timelines for REACH environmental release standard enforcement. Distribution runs through Rotterdam-Antwerp chemical corridor concentration into Benelux professional cleaning supply chains, with e-commerce direct-to-consumer platforms fragmenting traditional retail concentration in United Kingdom and Scandinavian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance cost arbitrage between German strict-enforcement zones and Spanish lagging-adoption markets creates geographic expansion incentives for concentrated chemistry producers seeking margin protection.
For Market Incumbents: Anchor market position through backward integration into biodegradable surfactant production at North Rhine-Westphalia chemical cluster sites, defending against private-label erosion in economy-tier segments. DomusVi Group and Air Liquide should extend cylinder-to-home respiratory therapy infrastructure into Portuguese and Eastern European markets before reimbursement frameworks mature, locking in first-mover network density. For New Entrants and Emerging Players: The 40% price-point gap between premium personalized senior care plans and mass-market hygiene maintenance opens white-space opportunity for mid-tier subscription services targeting urban dual-income households in underpenetrated Spanish and Italian e-commerce channels. Concentrated refill pouch formats in professional cleaning supply chains offer fastest penetration path, leveraging EU Green Deal packaging waste reduction incentives to offset customer acquisition costs. For Investors and Strategic Acquirers: Asymmetric upside sits with connected diagnostic platform vendors integrating hospital-grade monitoring into reimbursable home health device categories. Five-to-ten-year viability favors specialized domiciliary nursing networks with cross-border credential recognition capabilities and digital care infrastructure deployment. Watch for EMA guideline harmonization across French ANSM and German BfArM interpretations as inflection signal for scalable reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Surfactant Capacity Expansion | North Rhine-Westphalia chemical cluster investment secures REACH-compliant feedstock supply for phosphate-reduced formulations. |
| Subscription Replenishment Platform Launch | Auto-replenishment algorithms in United Kingdom and Scandinavian markets concentrate brand loyalty and reduce customer churn. |
| Cross-Border Nursing Network Consolidation | M&A activity across French and Iberian markets builds geographic density for institutional-to-home care transitions. |
| Connected Diagnostic CE Marking Pathway | EMA guideline alignment for remote patient monitoring devices unlocks reimbursable home health categories in German and French markets. |
| Concentrated Pouch Manufacturing Joint Venture | Benelux production partnerships capture EU Green Deal packaging waste reduction incentives for professional cleaning supply chains. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with home nursing network operators, surfactant formulator R&D directors, hospital procurement committees, e-commerce platform category managers, and ECHA regulatory affairs specialists with secondary validation through customs trade data, Cefic chemical industry reports, SEC 10-K filings of listed healthcare conglomerates, and national reimbursement framework documentation. Bottom-up patient population modeling and top-down chemical consumption estimates triangulated volume and value outputs.
Comparable-period anchoring tied projection assumptions to historical reference periods across the analysis window, with segmentation modeling across product chemistry tiers, care delivery modalities, distribution channel infrastructure, and patient population risk profiles. CAGRs derived from surfactant consumption intensity correlations with aging demographic projections and reimbursement eligibility expansion timelines for connected home health devices.
Caveats apply where EMA guideline harmonization delays, Rhine logistics disruption, or REACH authorization timeline accelerations could materially shift the outlook. Forecasts reflect documented assumptions about institutional-to-home care transition velocity and biodegradable surfactant cost convergence trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Home Care Products Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
Home Care Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Home Care Service Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Elder Care Products Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
Global Home Health Hub Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
US House Calls Market