
 Pet Diabetes Care Devices Market | 2026-2036
Pet Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Diabetes Care Devices Market Analysis
Buyer concentration among veterinary hospital chains is decoupling from the traditional independent clinic distribution model, forcing device manufacturers to restructure channel partnerships. Zoetis leverages its direct veterinary relationships to sustain premium positioning in insulin delivery systems. Becton, Dickinson and Company anchors North American supply through its specialized animal health division, while TaiDoc Technology Corporation competes on cost-engineered glucose meters for price-sensitive home care segments.
Pet diabetes care devices encompass calibrated glucose monitoring systems, insulin delivery apparatus, and connected health platforms engineered for companion animal physiology with species-specific reference ranges and anti-fur interference sampling mechanisms. These instruments enable precise glycemic control in diabetic dogs and cats, reducing secondary complications and extending quality-adjusted life years. Continuous glucose monitoring systems lead technology adoption due to real-time data streams that minimize hypoglycemic events, while smart devices and mobile apps represent the fastest-expanding segment as pet owners demand remote visibility into glucose trends. Test strips retain the largest volume share but face margin compression from commoditization in human-diabetes supply chains.
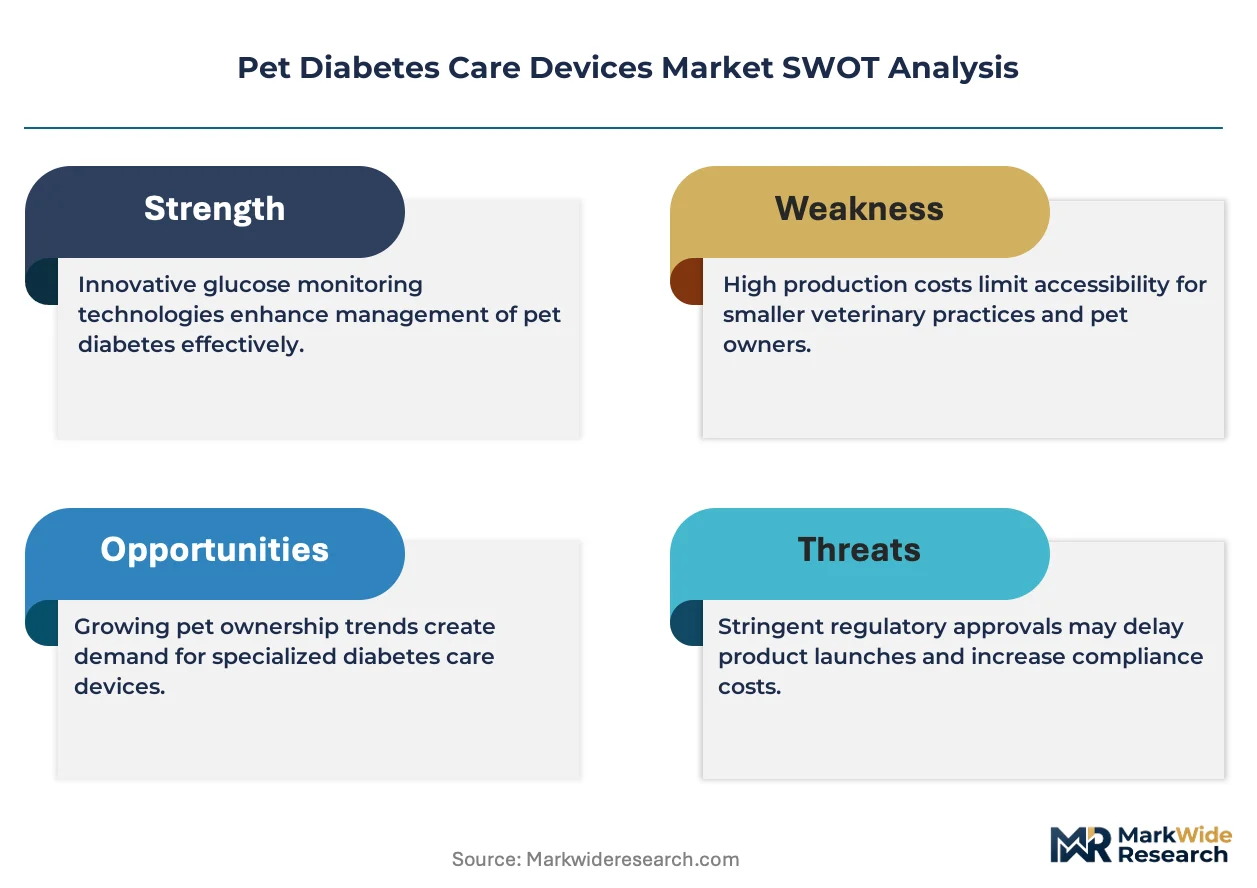
FDA Center for Veterinary Medicine and USDA Animal and Plant Health Inspection Service govern device safety claims and manufacturing quality, while ISO 10993 biocompatibility standards shape materials selection for implantable sensors. Compliance with FDA 21 CFR Part 820 quality system regulations determines market access for foreign manufacturers. Stakeholders must monitor evolving telemedicine prescribing rules that could expand home-based insulin titration authority beyond licensed veterinary premises.
Market Dynamics
Veterinary hospital chains are consolidating procurement authority, decoupling device sourcing from independent clinic distributors and forcing manufacturers to restructure channel partnerships around direct enterprise contracts.
Growth Catalysts
- Pet insurance expansion:Chronic condition coverage in the United States now includes continuous glucose monitoring systems, broadening patient access beyond out-of-pocket payment constraints.
- FDA 21 CFR Part 820 compliance:Quality system regulations for animal health devices are tightening manufacturing standards, filtering out subscale competitors and elevating incumbent positioning.
- Continuous glucose monitoring adoption:Real-time data streams from wearable sensors are displacing episodic testing protocols in specialty veterinary practices, reducing hypoglycemic emergency rates.
Market Restraints
- Test strip commoditization:Margin compression from human-diabetes supply chain spillover is eroding profitability in conventional glucose monitoring consumables.
- Biocompatibility certification costs:ISO 10993 materials testing requirements for implantable sensors impose fixed cost burdens that disadvantage smaller device developers.
- Single-source sensor dependence:Concentrated supply of calibrated enzyme reagents for species-specific reference ranges creates vulnerability to input disruption.
Strategic Opportunities
- Home care telemedicine expansion:Evolving prescribing rules for insulin titration authority beyond licensed veterinary premises could unlock remote patient management revenue pools.
- Mobile health platform integration:Connected apps paired with Bluetooth-enabled meters are capturing data-rich relationships with pet owners outside clinic walls.
- Anti-fur interference sampling:Species-optimized lancet and strip designs for thick-coated breeds represent untapped product differentiation space in companion animal segments.
Industry Challenges
- Veterinary endocrinology specialization gaps:Shortage of diplomate-trained specialists limits protocol standardization for complex diabetic case management in general practice settings.
- Cross-species validation complexity:Canine and feline glucose kinetic differences require separate clinical trial investments, fragmenting R&D resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Diabetes Care Devices Market |
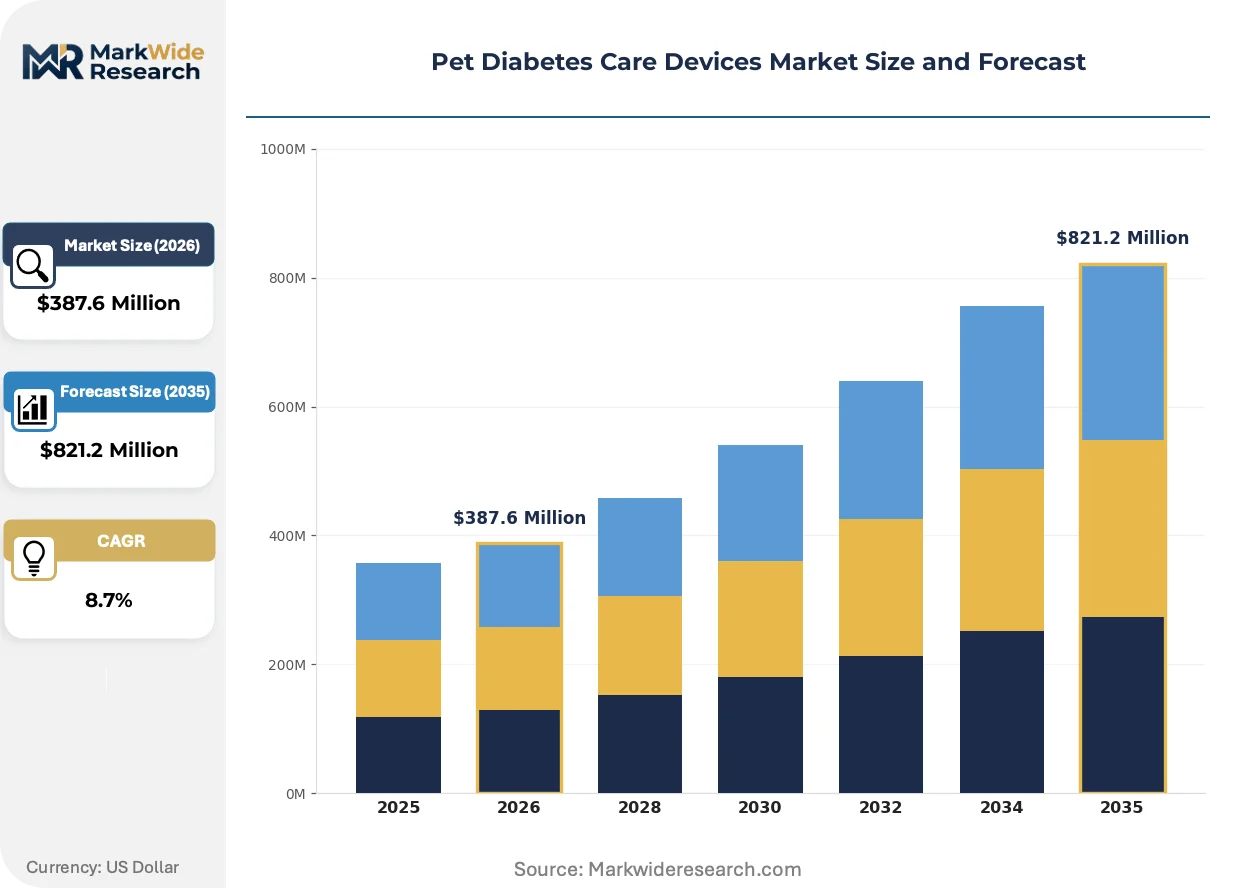
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucose Meters, Insulin Pumps, Continuous Glucose Monitors, Test Strips End User: Pet Clinics, Veterinary Hospitals, Home Care, Animal Shelters Technology: Blood Glucose Testing, Continuous Glucose Monitoring, Smart Devices, Mobile Apps Application: Routine Monitoring, Glucose Level Management, Insulin Administration, Education & Training |
| Companies Covered | Merck Animal Health, Zoetis, Becton, Dickinson and Company, Boehringer Ingelheim, Henry Schein Animal Health, Allison Medical, TaiDoc Technology Corporation, i-SENS, UltiMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Diabetes Care Devices Market Emerging Trajectories
Device architectures are pivoting from episodic measurement toward continuous data streams, with software layers capturing disproportionate value as hardware commoditizes.
Implantable biosensor technology is converging with cloud-based analytics platforms to enable predictive glycemic alerts. Large specialty hospital groups in the United States are piloting these systems for hospitalized diabetic patients. This convergence is compressing the window between glucose excursion detection and clinical intervention, shifting competitive advantage toward data infrastructure owners.
USDA Animal and Plant Health Inspection Service oversight of manufacturing quality claims is intensifying documentation requirements for imported devices. Foreign manufacturers face extended approval timelines as facility inspections resume post-pandemic backlog. European and Asian suppliers are responding by establishing domestic contract manufacturing partnerships to bypass cross-border inspection dependencies.
Pet owners are demanding remote visibility into glucose trends, unbundling after-sales service from clinic-based consultations. Subscription models for data analytics are displacing transactional device sales in the home care channel. This behavioral shift is most visible in United States metropolitan markets where pet insurance penetration exceeds national averages.
Pet Diabetes Care Devices Market Segmentation
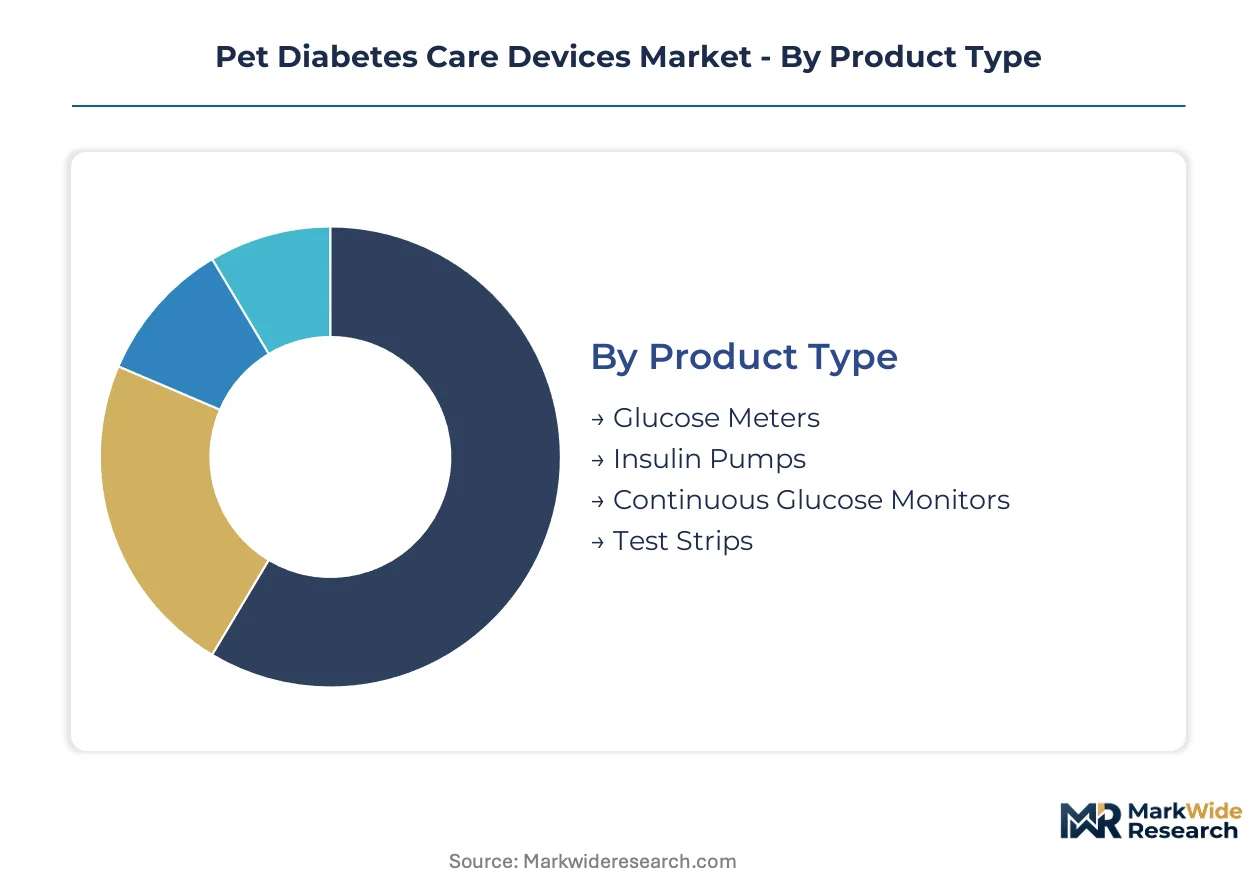
Pet diabetes care devices fragment across four distinct classification axes, each capturing different value pools in the care continuum. Understanding these divisions reveals where technology premiums concentrate versus where commoditization pressures dominate procurement decisions.
Product Type:
Device architecture separates portable point-of-care instruments from implantable sensor systems, with each tier commanding different margin structures and replacement cycles.
- Glucose Meters:Handheld electrochemical analyzers with species-calibrated reference ranges and anti-fur interference sampling ports. Demand clusters in United States veterinary hospital chains seeking standardized fleet deployments for in-house glycemic screening.
- Continuous Glucose Monitors:Wearable interstitial fluid sensors transmitting real-time glucose data to cloud dashboards. United States specialty practices lead adoption as pet insurance reimbursement expands coverage for hospitalized diabetic patients.
- Insulin Pumps:Programmable infusion devices delivering basal and bolus insulin dosing. Concentrated in academic veterinary centers managing complex diabetic ketoacidosis cases.
- Test Strips:Single-use enzymatic reagent strips for capillary blood sampling. Volume leader facing margin compression from human-diabetes supply chain spillover.
Mature deployment sits with test strips. Newer deployment is concentrated in continuous glucose monitors.
End User:
Procurement authority concentrates differently across institutional versus consumer channels, reshaping how manufacturers structure sales coverage and service contracts.
- Veterinary Hospitals:Multi-specialty institutions with in-house endocrinology services and centralized device procurement. United States hospital chains are consolidating vendor contracts around enterprise pricing agreements.
- Home Care:Pet owners managing chronic diabetes outside clinical settings. This segment is expanding most quickly as Bluetooth-enabled meters and subscription data analytics displace clinic-dependent monitoring.
- Pet Clinics:Independent general practice facilities with episodic diabetes case exposure. Price sensitivity drives preference for cost-engineered glucose meters over premium continuous monitoring systems.
- Animal Shelters:Non-profit facilities with sporadic diabetic animal intake and limited diagnostic budgets. Minimal device penetration outside large municipal operations.
Revenue concentration favors veterinary hospitals. Volume growth accelerates in home care.
Technology:
Data capture modality determines competitive moat durability, with software-layer differentiation increasingly separating winners from hardware commoditization.
- Continuous Glucose Monitoring:Implantable biosensors with predictive analytics and automated alert thresholds. United States specialty groups pilot cloud-integrated platforms for hospitalized patient surveillance.
- Mobile Apps:Smartphone-connected interfaces for glucose trend visualization and remote veterinary consultation. This segment shows the steepest expansion trajectory as pet owners demand visibility outside clinic walls.
- Smart Devices:Bluetooth-enabled meters with automated data logging and insulin dose calculators. Mid-tier pricing bridges professional and consumer channels.
- Blood Glucose Testing:Conventional episodic measurement with manual log-keeping. Legacy installed base retains volume share but loses growth momentum to connected alternatives.
Technology leadership resides in continuous glucose monitoring. Consumer adoption momentum centers on mobile apps.
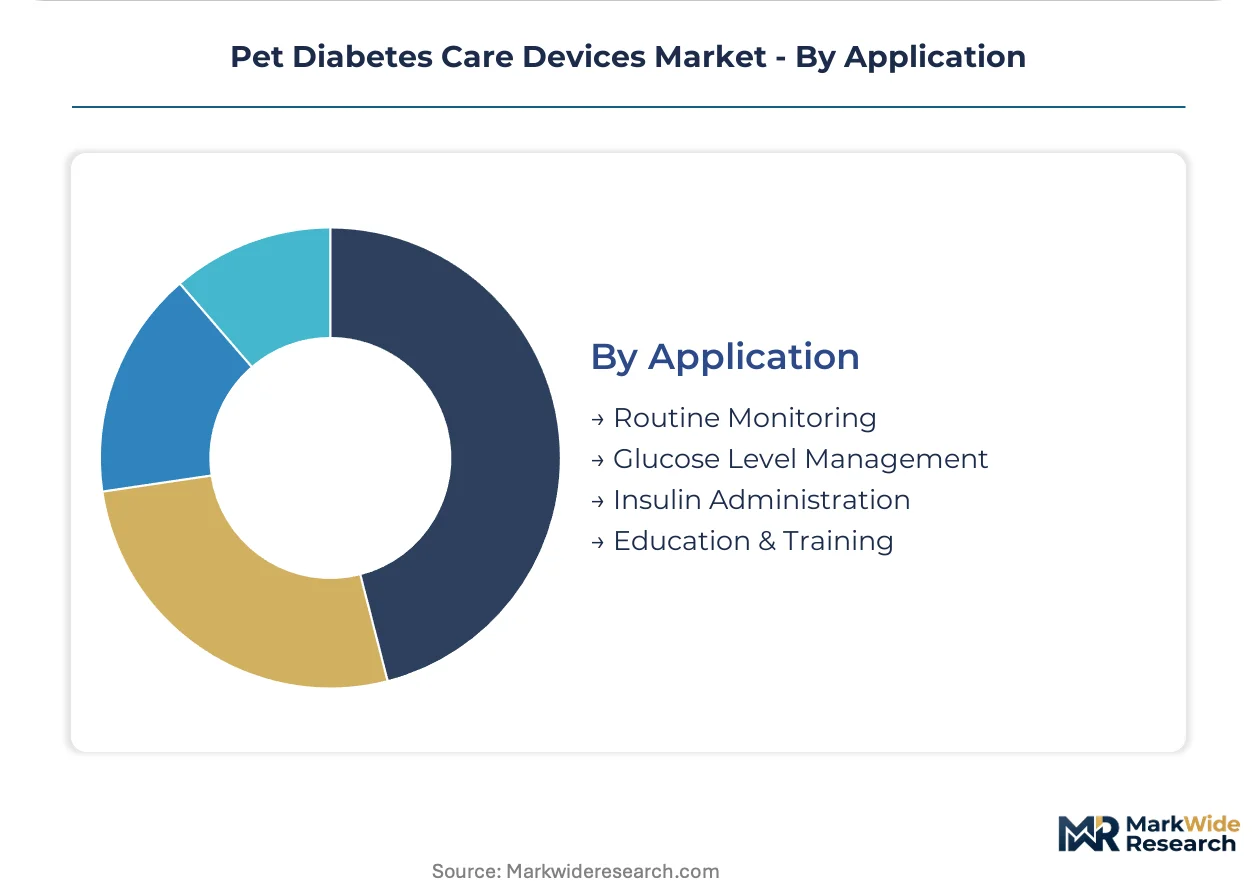
Application:
Use case segmentation tracks the clinical workflow from diagnosis through chronic management, with each stage presenting distinct device requirements and reimbursement conditions.
- Routine Monitoring:Scheduled glucose surveillance for stabilized diabetic patients. United States general practices favor standardized meter protocols for efficiency.
- Glucose Level Management:Dynamic insulin titration based on real-time glycemic data. Demand concentrates in specialty hospitals with 24-hour intensive care capabilities.
- Insulin Administration:Precision delivery devices for hormone replacement therapy. Syringe and pen systems dominate, with pump adoption limited to refractory cases.
- Education & Training:Simulation tools and instructional platforms for pet owner self-management. Emerging category with subscription revenue potential.
Clinical value capture concentrates in glucose level management. Commercial expansion opportunity sits with education and training.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States veterinary hospital chains concentrate procurement authority for glucose monitoring systems, while European and Asian manufacturers navigate divergent regulatory pathways to access these high-value accounts.
United States
Pet insurance reimbursement for continuous glucose monitoring systems now covers chronic diabetes management, removing cost barriers for specialty veterinary practices. FDA Center for Veterinary Medicine enforces 21 CFR Part 820 quality system regulations that filter out subscale device manufacturers. North Carolina's Research Triangle hosts contract manufacturing partnerships where Asian suppliers establish domestic production to bypass cross-border inspection delays.
Germany
Veterinary clinic consolidation across Bavaria and North Rhine-Westphalia drives enterprise-level procurement contracts for standardized glucose meter fleets. EU Medical Device Regulation (MDR) and CE marking requirements shape biocompatibility documentation for implantable sensors entering the companion animal market. Baden-Württemberg's precision engineering clusters supply specialized lancet components optimized for thick-coated breed sampling.
Japan
Metropolitan Tokyo and Osaka veterinary specialists pilot cloud-integrated continuous monitoring platforms for hospitalized diabetic patients. Pharmaceutical and Medical Devices Agency (PMDA) oversees manufacturing quality claims for imported animal health devices. Aichi Prefecture's automotive sensor manufacturers are repurposing interstitial fluid detection technologies for veterinary biosensor applications.
United Kingdom
London and Southeast England specialty practices lead adoption of subscription-based mobile health analytics for remote pet owner engagement. Veterinary Medicines Directorate aligns device safety standards with EU MDR transitional arrangements post-Brexit. Cambridge life sciences clusters host veterinary telemedicine platforms integrating Bluetooth-enabled glucose meters into chronic care workflows.
Australia
Sydney and Melbourne metropolitan markets show elevated pet insurance penetration driving demand for home-based continuous monitoring systems. Therapeutic Goods Administration (TGA) regulates glucose meter accuracy claims for veterinary applications. Queensland's agricultural technology corridor develops species-calibrated reference ranges for tropical breed glucose kinetics.
Pet Diabetes Care Devices Market Vendor Landscape
United States-based animal health conglomerates anchor the premium-tier insulin delivery segment; Asian electronics specialists hold cost-engineered positions in home care glucose meters. Market structure tilts toward consolidated procurement authority as veterinary hospital chains centralize vendor negotiations. Three archetypes dominate: diversified pharmaceutical-animal health hybrids, dedicated diabetes device manufacturers, and contract electronics assemblers. Competitive moves center on direct enterprise contracting with hospital chains and mobile health platform integration to capture recurring subscription revenue.
Within the pharmaceutical-animal health hybrid tier, Merck Animal Health and Zoetis occupy positions shaped by direct veterinary relationships and established distribution infrastructure. Boehringer Ingelheim represents the European-centered archetype with companion animal health portfolios extending into metabolic disease management. TaiDoc Technology Corporation exemplifies the Asia-based cost-engineering specialist competing on price-accessible glucose meters for price-sensitive home care segments. These three anchors illustrate how geographic origin and corporate structure map to distinct competitive vectors in procurement negotiations.
| Leading Market Players |
|---|
| Merck Animal Health |
| Zoetis |
| Becton, Dickinson and Company |
| Boehringer Ingelheim |
| Henry Schein Animal Health |
| Allison Medical |
| TaiDoc Technology Corporation |
| i-SENS |
| UltiMed |
| Others |
Supply Flow & Price Mechanics
Calibrated enzyme reagents for species-specific glucose reference ranges flow from concentrated Asian chemical synthesis clusters through three distinct pricing tiers before reaching end users. Input costs for these reagents cascade downstream through implantable sensor manufacturers, veterinary hospital procurement departments, and home care retail channels, with each tier capturing margin based on certification burden and volume scale.
Pricing Analysis
Volume concentrates in test strips while margins pool in continuous glucose monitoring systems and subscription analytics platforms. Price differentiation stems from FDA 21 CFR Part 820 quality system certification tier and bundled after-sales service intensity. Cost compression in conventional glucose meters is intensifying because human-diabetes supply chain spillover commoditizes enzymatic reagent strips. Home care pet owners exhibit highest price sensitivity, while United States veterinary hospital chains prioritize accuracy certification over unit cost.
Supply Chain Analysis
FDA 21 CFR Part 820 and ISO 10993 biocompatibility certifications gate market access for foreign manufacturers, extending approval timelines and elevating compliance fixed costs. Supply concentrates in Taiwan for electrochemical sensor components, Germany for precision lancet engineering, and the United States for cloud analytics infrastructure. Raw material dependencies include noble metal electrodes, medical-grade silicone adhesives, and species-calibrated enzyme formulations. Single-source vulnerability sits with concentrated Asian suppliers of glucose oxidase reagents. Distribution runs through direct enterprise contracts with veterinary hospital chains alongside traditional independent clinic distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 10993 biocompatibility testing capacity constraints prop premium pricing for implantable sensors, as qualified laboratory slots remain backlogged and foreign manufacturers face extended domestic facility qualification timelines.
For Market Incumbents: Deepen backward integration into species-specific enzyme reagent production to insulate margin from single-source supply disruption. Fortify direct enterprise contracting with United States veterinary hospital chains before procurement authority consolidates further. Prioritize cloud analytics platform development to capture recurring subscription revenue as hardware commoditization accelerates. For New Entrants and Emerging Players: Launch via mobile health platform partnerships targeting United States metropolitan home care segments where pet insurance penetration exceeds national benchmarks. Penetrate the Bluetooth-enabled meter tier bridging professional and consumer channels. Exploit anti-fur interference sampling design gaps for thick-coated breed differentiation. For Investors and Strategic Acquirers: FDA 21 CFR Part 820 compliance timeline extensions for Asian manufacturers are the leading indicator that domestic contract manufacturing partnerships will command scarcity premiums. Five-to-ten-year viability favors data infrastructure owners over hardware assemblers. Target acquisition archetypes: veterinary telemedicine platforms with installed glucose meter connectivity. Watch pet insurance reimbursement policy expansions for continuous monitoring systems as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Health Platform Integration | Captures data-rich subscription relationships with pet owners outside clinic walls. |
| Domestic Contract Manufacturing Partnership | Bypasses FDA cross-border inspection delays for Asian sensor suppliers. |
| Species-Specific Biocompatibility Certification | Unlocks implantable CGM market access under ISO 10993 and FDA 21 CFR Part 820. |
| Veterinary Hospital Chain Enterprise Contract | Secures volume commitment as procurement authority consolidates in United States. |
| Anti-Fur Interference Sampling R&D | Differentiates product portfolio for thick-coated companion animal segments. |
Methodological Framework
SEC 10-K filings, FDA 510(k) premarket notification databases, and veterinary hospital procurement records formed the secondary backbone of this analysis. Primary interviews with veterinary endocrinologists, biomedical device engineers, GPO contracts managers, and pet insurance reimbursement specialists validated quantitative assumptions. Bottom-up and top-down triangulation reconciled manufacturer shipment data with end-user adoption surveys.
Bottom-up modeling tracked device unit shipments across glucose meters, continuous glucose monitors, insulin pumps, and test strips through the projection horizon. Segmentation dimensions included product architecture, end-user channel, data capture technology, and clinical application stage. CAGRs were derived from installed base growth curves and replacement cycle analysis. Forecast inputs incorporated pet insurance penetration trajectories and FDA regulatory approval pipeline status.
Regulatory enforcement intensity shifts, pet insurance reimbursement policy revisions, and veterinary endocrinology specialist supply constraints are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in FDA 21 CFR Part 820 inspection backlog resolution timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
Diabetic Ketoacidosis Treatment Market
Diabetes Care
Philippines Diabetes Drugs and Devices Market
Diabetes Care
Continuous Glucose Monitoring Market
Diabetes Care
New Zealand Oral Anti-Diabetic Drug Market
Diabetes Care
APAC Insulin Infusion Pumps Market
Diabetes Care
Asia-Pacific Insulin Delivery Devices Market
Diabetes Care
Diabetes Monitors Market
Diabetes Care
United Kingdom Blood Glucose Monitoring Market
Diabetes Care
France Continuous Glucose Monitoring Market
Diabetes Care
New Zealand Self-Monitoring Blood Glucose Market
Diabetes Care
Global Type 1 Diabetes (T1D) Market
Diabetes Care
Japan Continuous Glucose Monitoring Devices Market
Diabetes Care
Alternatives for Injectable Diabetes Care Market
Diabetes Care
Canada Continuous Glucose Monitoring Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Asia-Pacific Diabetes Care Devices Market