
 US Home Healthcare Services Market | 2026-2036
US Home Healthcare Services Market Size, Share, and Industry Trends Forecast 2026-2036
US Home Healthcare Services Market Intelligence
Telehealth platforms are pivoting from supplemental tools to core care delivery infrastructure, compressing per-visit costs while extending clinical reach. Amedisys leverages its hospice-skilled nursing hybrid model to sustain margin stability across episodic and chronic care episodes. Visiting Angels anchors its competitive stance through non-medical personal care specialization, while LHC Group dominates Medicare-certified home health admissions across rural hospital networks. Addus HomeCare extends its position in personal care services through state Medicaid program partnerships.
US Home Healthcare Services encompass skilled nursing, therapeutic intervention, and personal assistance delivered in residential settings under clinical supervision, typically coordinated through licensed agencies that maintain patient-specific care plans with defined visit frequencies and outcome metrics. The primary purpose is substituting institutional care with cost-effective, patient-preferred alternatives that reduce hospital readmission exposure. Skilled Nursing commands the largest revenue share due to reimbursement premiums for wound care, infusion therapy, and post-acute monitoring, while Personal Care generates volume through Medicaid-funded long-term support services for aging-in-place populations. Payment Model dynamics reveal Medicare as the dominant payer for short-term medical episodes, though Managed Care Plans are capturing growing share through Medicare Advantage expansion and bundled payment contracts.
CMS conditions of participation govern licensure, staffing ratios, and quality reporting thresholds for Medicare-certified providers, while state Medicaid agencies set distinct personal care benefit parameters that vary by eligibility category and service hour limits. OSHA bloodborne pathogen standards and HIPAA privacy requirements impose operational compliance costs that differentiate licensed agencies from informal caregiver arrangements. Stakeholders must monitor CMS innovation center demonstrations for hospital-at-home waivers and telehealth reimbursement permanency rulings that could restructure site-of-care economics.
Market Dynamics
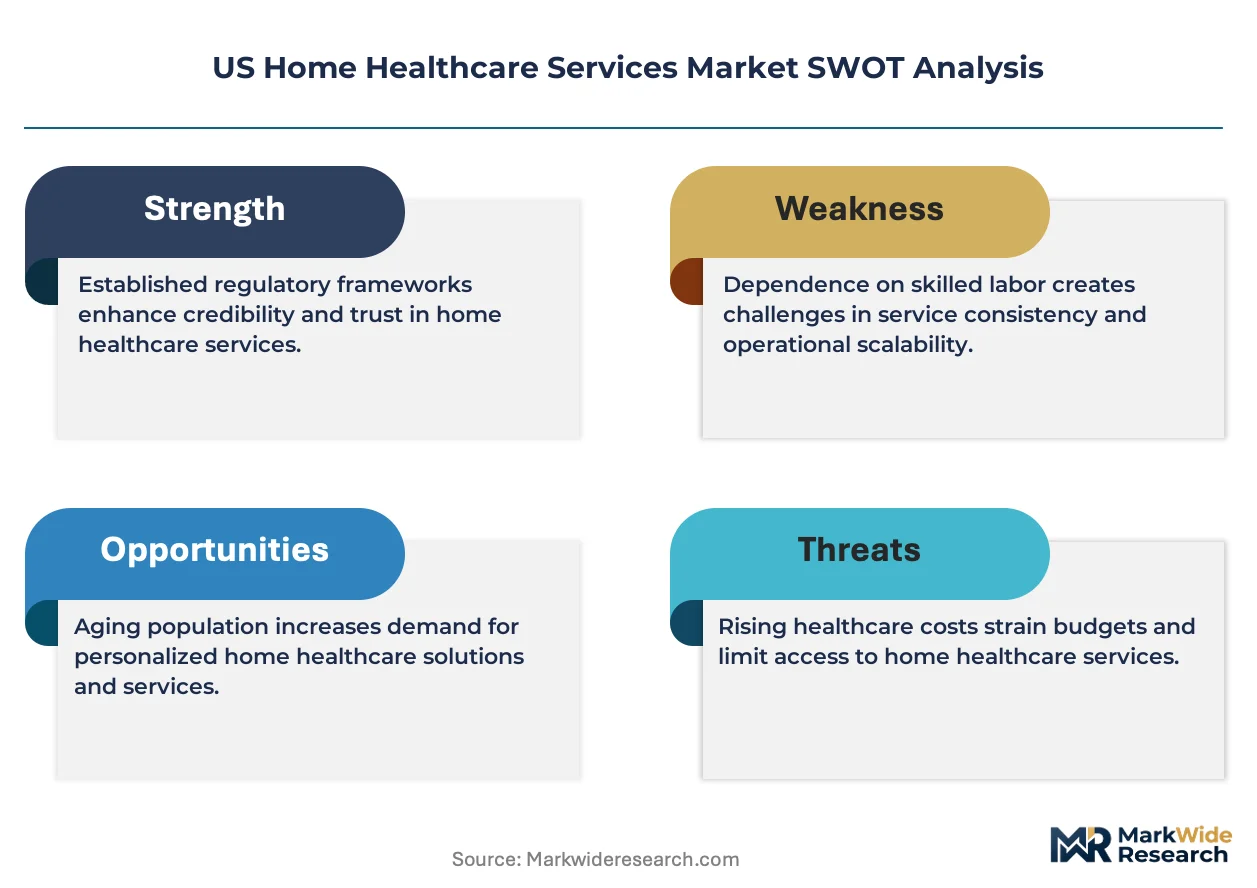
Medicare's mandatory shift to value-based reimbursement through the Home Health Value-Based Purchasing model is compressing margins while forcing providers to restructure around outcome metrics rather than visit volume.
Growth Catalysts
- Hospital-at-Home Waivers:CMS Innovation Center demonstrations extending acute-level care into residential settings reduce institutional bed demand while expanding addressable service territory for certified agencies.
- Medicare Advantage Penetration:Managed care plans now cover over half of eligible beneficiaries, creating bundled payment contracts that favor integrated home health networks over episodic fee-for-service models.
- Remote Patient Monitoring:Bluetooth-enabled biometric devices and FDA-cleared wearables allow continuous vital tracking between nursing visits, extending clinical surveillance without proportional labor cost expansion.
Market Restraints
- Workforce Compression:Licensed practical nurse vacancy rates exceed twenty percent in rural Texas and Florida markets, constraining admission capacity regardless of demand signals.
- Reimbursement Compression:The 2022 CMS rate rebasing reduced standardized episode payments by eight percent, eliminating margin buffer for agencies with above-average therapy utilization.
- Regulatory Compliance Burden:OASIS-E documentation requirements impose forty-five additional minutes per admission assessment, converting fixed administrative overhead into variable cost drag.
Strategic Opportunities
- Medicaid Personal Care Expansion:California's IHSS program and New York's Consumer Directed Personal Assistance Program create volume anchors through state-funded long-term support services.
- Telehealth-Triage Integration:Video-based physician consultation layered onto skilled nursing visits reduces emergency department utilization while capturing professional fee revenue streams.
- Social Determinant Navigation:Medicare Advantage supplemental benefits for transportation and nutrition create partnership openings between home health agencies and community-based organizations.
Industry Challenges
- Clinical Documentation Burden:OASIS-E timing and functional assessment protocols require specialized coding expertise that commands thirty percent wage premiums over general administrative staff.
- EHR Interoperability Friction:PointClickCare and Homecare Homebase system silos obstruct real-time data exchange with hospital admission-discharge-transfer platforms, delaying care transition handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Home Healthcare Services Market |
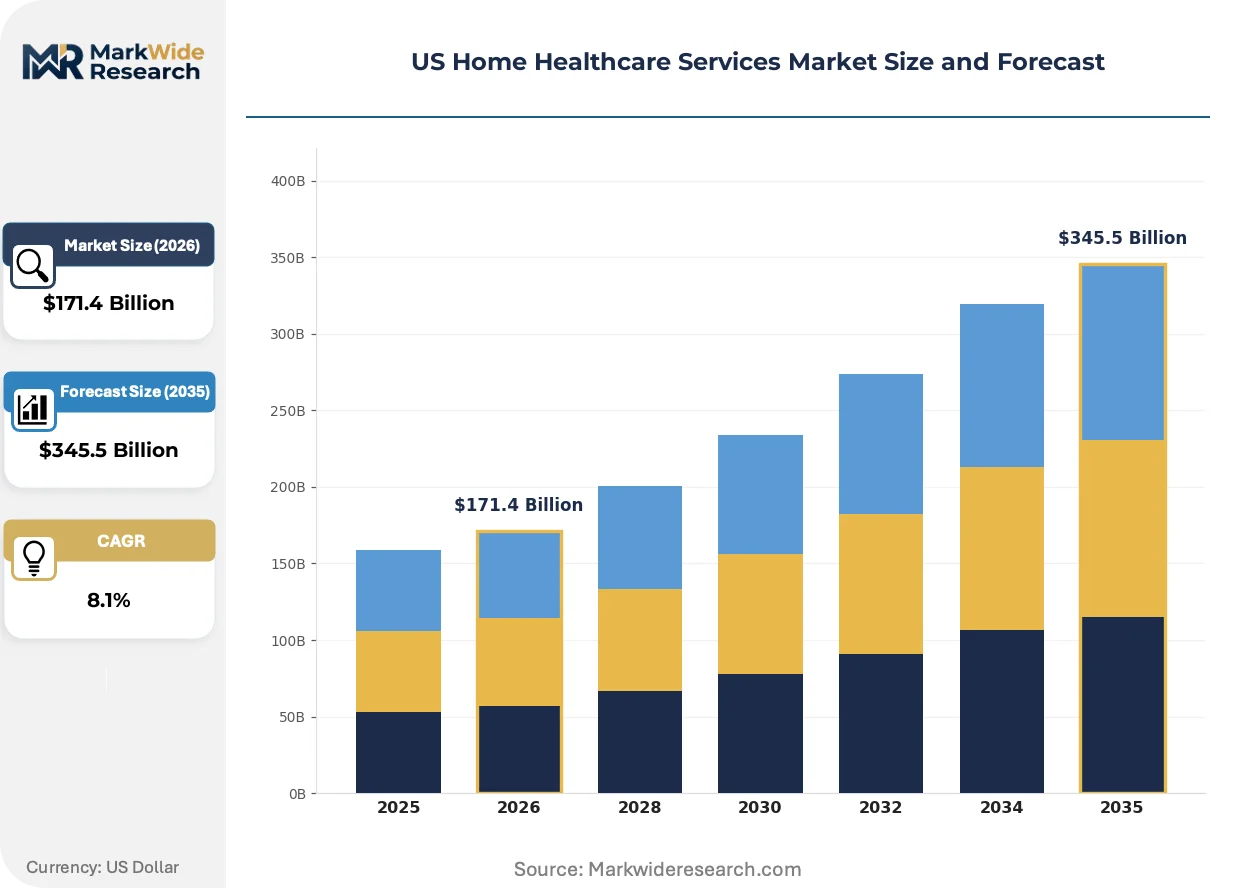
| Market Size in 2026 | $171.4 Billion |
| Market Size in 2035 | $345.5 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Skilled Nursing, Physical Therapy, Medical Social Services, Personal Care, Home Health Aide, Occupational Therapy Care Recipient Age Group: Geriatric, Pediatric, Adult, Post-Surgical, Chronic Condition, Palliative Payment Model: Medicare, Medicaid, Private Insurance, Out-of-Pocket, Managed Care Plans, Veterans Benefits Provider Type: Licensed Home Health Agencies, Independent Practitioners, Hospice Providers, Rehabilitation Centers, Community Clinics, Faith-Based Organizations |
| Companies Covered | Addus HomeCare, Visiting Angels, Amedisys, Apria Healthcare, Interim HealthCare, LHC Group, Almost Family, AccentCare, Encompass Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Home Healthcare Services Market Strategic Shifts & Innovations
Technology convergence between remote monitoring hardware and artificial intelligence triage algorithms is compressing the clinical workforce required per patient episode while extending supervisory ratios.
Remote patient monitoring infrastructure is modularizing care delivery architecture. Cellular-enabled pulse oximeters, weight scales, and blood pressure cuffs transmit threshold alerts to centralized nursing dashboards. Medicare Advantage plans in Florida and Texas are deploying these device bundles to high-risk CHF cohorts. The technology is modularizing the traditional visit-based model into continuous surveillance layers that reduce unplanned acute events.
CMS conditions of participation now mandate standardized quality reporting through the Home Health Compare portal, with star ratings directly influencing referral patterns from hospital discharge planners. Agencies failing to maintain four-star thresholds face exclusion from preferred provider networks. Skilled nursing segments in California and New York are responding by dedicating quality improvement staff to OASIS accuracy and patient satisfaction scripting.
Beneficiary preference for aging-in-place is redirecting post-acute spend away from skilled nursing facilities toward residential recovery settings. Hospital discharge planners in Medicare Advantage-dominant markets now default to home health for joint replacement and cardiac recovery episodes. This channel rotation is most visible in Arizona and Nevada retirement corridors where new retiree inflows concentrate demand for community-based alternatives to institutional rehab.
US Home Healthcare Services Market Segmentation
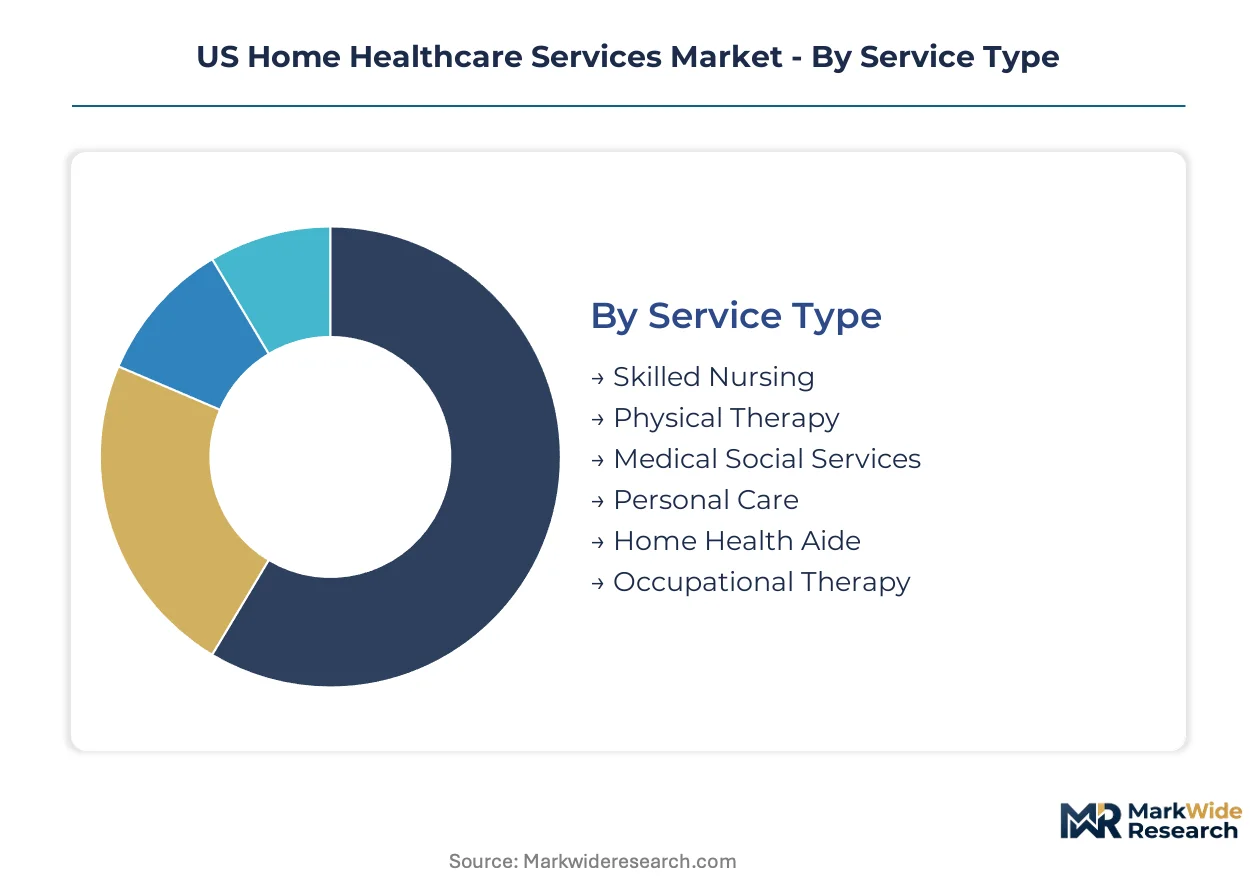
Service configuration in US home healthcare hinges on reimbursement eligibility, clinical acuity thresholds, and state-level benefit design. Understanding segment boundaries reveals where margin pools concentrate versus where volume scales through public program expansion.
Service Type:
Buyer selection prioritizes clinical necessity certification and episode-based reimbursement rates over discretionary preference.
- Skilled Nursing:Registered nurses deliver wound care, infusion therapy, and post-acute monitoring under physician orders with defined visit frequencies. Demand concentrates in Florida and Texas where aging demographics intersect with high Medicare Advantage penetration and hospital-at-home waiver adoption.
- Personal Care:Non-medical assistance with activities of daily living including bathing, meal preparation, and mobility support, typically funded through state Medicaid programs. California's IHSS program and New York's CDPAP create volume anchors through consumer-directed service models.
- Physical Therapy:Rehabilitation services restoring functional mobility after orthopedic surgery or stroke, reimbursed under Medicare Part B when medically necessary and physician-prescribed.
- Medical Social Services:Assessment and coordination addressing psychosocial factors affecting recovery, including community resource linkage and caregiver support education.
- Home Health Aide:Paraprofessional support under nurse supervision for personal care and light household tasks, distinct from independently operating personal care workers.
- Occupational Therapy:Adaptive equipment training and environmental modification to restore independence in daily living activities, commonly bundled with post-surgical recovery episodes.
Volume sits with Skilled Nursing; growth tilts toward Personal Care.
Care Recipient Age Group:
Service intensity and episode duration vary dramatically across life-stage cohorts, with pediatric segments requiring specialized clinical competencies that constrain provider supply.
- Geriatric:Adults aged 65 and older requiring chronic disease management, post-acute recovery, or functional support to maintain independent living. Medicare and Medicaid fund the majority of services for this cohort across all US states.
- Post-Surgical:Patients discharged from inpatient settings requiring wound care, medication management, and rehabilitation to prevent readmission. Hospital discharge planners in Arizona and Nevada retirement corridors increasingly default to home-based recovery.
- Chronic Condition:Individuals with heart failure, COPD, or diabetes needing ongoing monitoring and self-management education to reduce acute exacerbations.
- Pediatric:Children with complex medical needs including technology dependence and congenital conditions, served by specialized agencies with pediatric nurse training.
- Adult:Working-age individuals with disabilities or acute injuries requiring temporary or long-term home-based support.
- Palliative:Patients with serious illness focusing on symptom relief and quality of life, often overlapping with hospice-eligible populations but distinct in prognosis requirements.
Clinical capacity concentrates in Geriatric; specialized margins attract Pediatric.
Payment Model:
Reimbursement source determines service authorization protocols, documentation requirements, and allowable visit frequencies.
- Medicare:Federal program covering short-term skilled services for homebound beneficiaries following hospitalization or skilled nursing facility stay. CMS conditions of participation mandate OASIS-E assessment protocols and quality reporting through Home Health Compare.
- Managed Care Plans:Medicare Advantage and Medicaid managed care organizations utilizing bundled payments and prior authorization to control utilization. These plans now cover over half of eligible Medicare beneficiaries in Florida and Texas markets.
- Medicaid:State-administered programs funding long-term personal care services with eligibility and benefit parameters varying by state.
- Private Insurance:Employer-sponsored and individual market plans covering skilled nursing and therapy with varying cost-sharing structures.
- Out-of-Pocket:Direct consumer payment for non-medical personal care services exceeding public program hour limits or ineligibility categories.
- Veterans Benefits:VA-funded home health and personal care services for eligible veterans through contracted community providers.
Episode volume flows through Medicare; value-based contracting accelerates through Managed Care Plans.
Provider Type:
Regulatory licensure status and care coordination capabilities shape referral network inclusion and payer contract access.
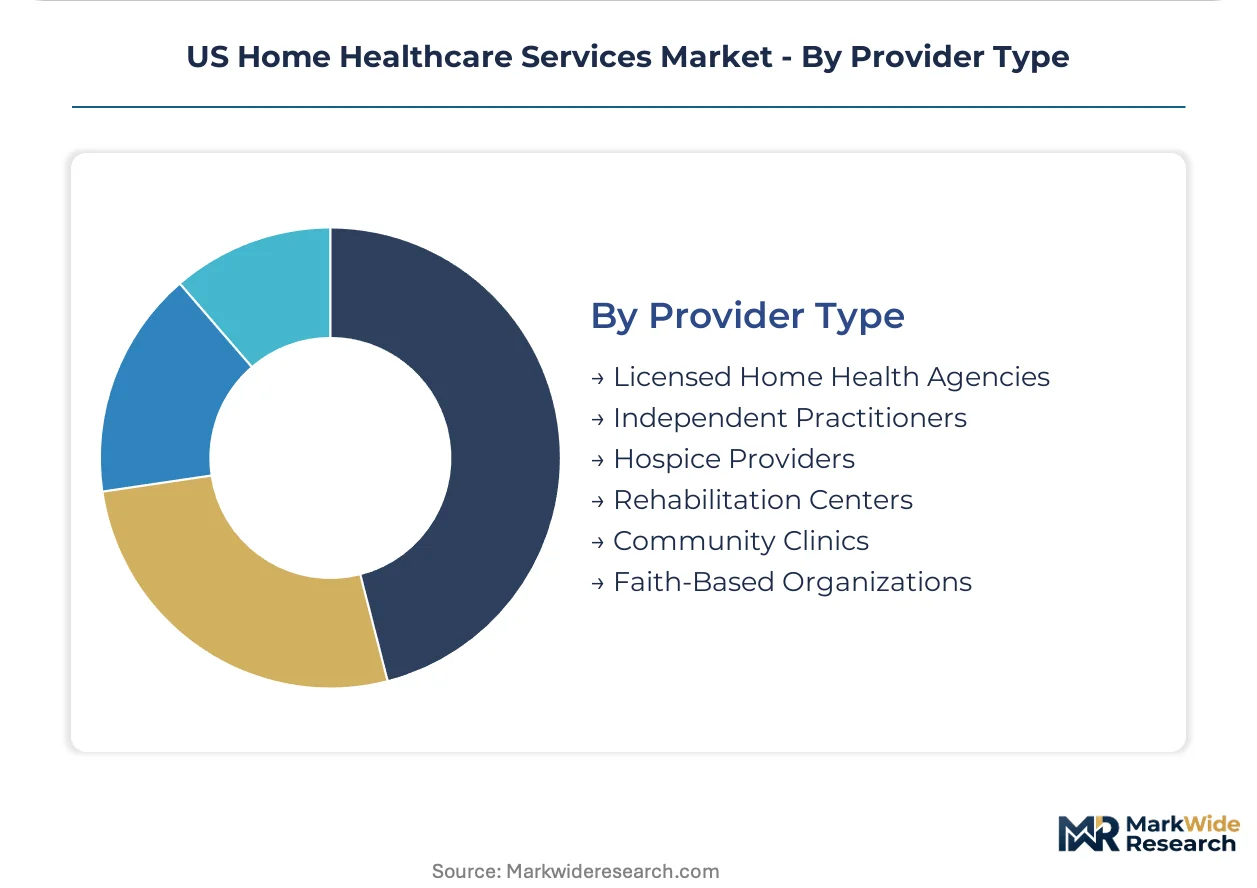
- Licensed Home Health Agencies:Medicare-certified organizations meeting federal conditions of participation for skilled nursing and therapy services. These agencies dominate Medicare-certified admissions across rural hospital networks.
- Hospice Providers:Organizations delivering palliative and end-of-life care under Medicare hospice benefit, often operating hybrid models with home health divisions.
- Independent Practitioners:Self-employed nurses, therapists, or aides operating outside agency structures, typically serving private-pay clients.
- Rehabilitation Centers:Outpatient therapy providers extending services into home settings for patients unable to travel.
- Community Clinics:Federally qualified health centers and rural health clinics offering limited home visiting programs.
- Faith-Based Organizations:Nonprofit entities delivering volunteer-supported personal care and companionship services.
Certified capacity clusters in Licensed Home Health Agencies; community-based expansion emerges through Faith-Based Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Florida, Texas, and California where aging demographics and chronic disease prevalence converge with Medicare Advantage expansion and hospital-at-home waiver adoption.
Florida
Snowbird migration patterns and retiree concentration drive geriatric service demand across the peninsula. CMS Innovation Center hospital-at-home waivers extend acute-level care into residential settings from Miami-Dade to the Villages. Tampa and Orlando anchor Medicare Advantage network development for integrated home health delivery.
Texas
Rapid population aging in Houston and Dallas-Fort Worth metroplexes strains licensed practical nurse availability below twenty percent vacancy thresholds. State Medicaid personal care benefit parameters create volume anchors through STAR+PLUS managed care contracts. Rural hospital networks in the Panhandle and West Texas dominate Medicare-certified admission pathways.
California
In-Home Supportive Services program scale creates the nation's largest state-funded personal care volume anchor. Los Angeles and San Francisco Bay Area discharge planners default to home health for joint replacement recovery. OASIS-E quality reporting requirements drive four-star rating competition among licensed agencies.
New York
Consumer Directed Personal Assistance Program enrollment exceeds traditional agency models in the five boroughs and Long Island. Upstate rural counties face workforce compression comparable to Texas border markets. Buffalo and Rochester hospital systems pilot bundled payment contracts with integrated home health networks.
Arizona
Retiree inflow corridors through Phoenix and Tucson concentrate demand for community-based alternatives to institutional rehab. Medicare Advantage penetration rates exceed national averages, rotating post-acute spend toward residential recovery settings. Flagstaff and Prescott discharge planners leverage remote patient monitoring for high-risk CHF cohorts.
US Home Healthcare Services Market Key Industry Players
Strategic partnerships dominate the current landscape as providers seek integrated network positioning against Medicare Advantage bundling requirements. The vendor base organizes around three tiers: national scale platforms with hospice-skilled nursing hybrids, regional specialists in personal care or therapy verticals, and state Medicaid-focused personal care operators. Two archetypes command attention: episodic fee-for-service consolidators and value-based care integrators. M&A activity and telehealth-triage capability acquisition represent the dominant competitive vectors reshaping market structure.
Within the national platform tier, Amedisys occupies a position exemplifying hospice-skilled nursing hybrid stability, while LHC Group anchors Medicare-certified admission dominance across rural hospital networks. Visiting Angels represents the personal care specialization archetype through non-medical service focus.
| Leading Market Players |
|---|
| Addus HomeCare |
| Visiting Angels |
| Amedisys |
| Apria Healthcare |
| Interim HealthCare |
| LHC Group |
| Almost Family |
| AccentCare |
| Encompass Health |
| Others |
Cost & Logistics Intelligence
Licensed practical nurse concentration in rural Texas and Florida markets creates labor-cost differentials that widen pricing-tier spreads between Medicare-certified skilled nursing and Medicaid-funded personal care services. Agencies absorbing twenty percent vacancy premiums in these regions pass elevated wage costs through to episode rates, while personal care operators in California's IHSS program leverage state wage floors to compress margin variance.
Pricing Analysis
Volume concentrates in Medicare-certified skilled nursing where CMS episode rates set baseline benchmarks, while margin pools concentrate in personal care services through state Medicaid hour-maximum structures. Price differentiation separates four-star rated agencies commanding preferred network placement from sub-threshold competitors facing referral exclusion. Pricing pressure stems from the 2022 CMS rate rebasing that eliminated margin buffers for therapy-heavy providers. Managed care plans exhibit lowest price sensitivity through bundled payment acceptance, while private-pay personal care buyers demonstrate highest elasticity to hourly rate adjustments.
Supply Chain Analysis
Dual-sourcing requirements from Medicare Advantage plans mandate multi-agency qualification for hospital discharge planner networks, preventing single-provider lock-in across episode types. Labor supply concentrates in Philippines-trained nurse pipelines, Mexican border-state aide networks, and domestic community college certification programs. Equipment dependencies rest on cellular-enabled biometric device manufacturers, FDA-cleared wearable producers, and EHR platform vendors including PointClickCare and Homecare Homebase. Single-source vulnerability sits with specialized OASIS-E coding talent commanding thirty percent wage premiums. Distribution runs through hospital discharge planning offices, state Medicaid agency referral portals, and Medicare Advantage care coordinator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Licensed practical nurse vacancy rates exceeding twenty percent in core markets prop pricing power for agencies with captive workforce pipelines, constraining supply expansion regardless of demand signals. Capacity bottlenecks in clinical documentation expertise further tighten service authorization velocity.
For Market Incumbents: Extend hospice-skilled nursing hybrid capabilities to capture bundled payment contracts from Medicare Advantage plans displacing episodic fee-for-service models. Acquire telehealth-triage platforms to reduce per-episode labor intensity while maintaining outcome metrics. Cement hospital discharge planner relationships through four-star Home Health Compare ratings that secure preferred network inclusion against emerging competitors. For New Entrants and Emerging Players: Rural Texas and Florida counties with workforce compression but unmet admission demand present white-space targets for personal care operators with alternative staffing models. Consumer-directed Medicaid programs in California and New York offer lower regulatory barriers than Medicare certification pathways. Target state Medicaid agency contracts through IHSS and CDPAP enrollment infrastructure rather than competing directly for Medicare-certified skilled nursing volume. For Investors and Strategic Acquirers: The window for entry favors regional personal care specialists with established state Medicaid relationships ahead of Medicare Advantage bundling consolidation. Long-term viability centers on agencies with demonstrated OASIS-E accuracy and workforce retention metrics outperforming market benchmarks. Watch CMS Innovation Center rulings on hospital-at-home waiver permanency as the signal for acute-level care site-of-care economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth-Triage Integration | Video-based physician consultation layered onto nursing visits captures professional fee revenue while reducing ED utilization. |
| Workforce Pipeline Development | Community college partnerships and Philippines recruitment networks address LPN vacancy rates exceeding twenty percent. |
| Four-Star Quality Investment | OASIS-E accuracy and patient satisfaction scripting secure preferred network placement from hospital discharge planners. |
| Medicaid Personal Care Expansion | State program partnerships through IHSS and CDPAP create volume anchors with lower regulatory compliance burdens. |
| Remote Patient Monitoring Deployment | Bluetooth-enabled device bundles extend clinical surveillance without proportional labor cost expansion for CHF cohorts. |
Research Approach
CMS Medicare cost reports, state Medicaid program enrollment data, and Home Health Compare quality metrics formed the secondary backbone, supplemented by SEC 10-K filings from publicly traded agencies. Primary interviews with hospital discharge planners, Medicare Advantage care coordinators, state Medicaid program administrators, and licensed agency operations directors validated demand and supply assumptions. Bottom-up episode volume modeling and top-down payer expenditure analysis enabled triangulation across data sources.
Historical trendline analysis of Medicare reimbursement rates, Medicaid benefit parameter changes, and workforce vacancy patterns established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated service type, care recipient age group, payment model, and provider licensure status dimensions. CAGRs were derived from payer-specific volume projections weighted by reimbursement rate evolution, with OASIS-E documentation burden and telehealth reimbursement permanency rulings as key forecast inputs.
Revisions become necessary when CMS innovation center demonstrations expand hospital-at-home waivers beyond current geographic scope, or when state Medicaid agencies alter personal care hour maximums and wage floor structures. Deviation in licensed practical nurse pipeline availability or Medicare Advantage bundled payment penetration rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Europe Home Care Market
Home Healthcare
Global Home Infusion Therapy Market
Home Healthcare
Home Care Service Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Home Care Market
Home Healthcare
Home Healthcare Market
Home Healthcare
Portable Toilet for Elderly Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Global Home Health Hub Market