
 UK Home Healthcare Market | 2026-2036
UK Home Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
UK Home Healthcare Market Intelligence
A consolidation among private care providers in the UK is restructuring the competitive landscape for home healthcare services. Large established entities like Care UK leverage their extensive network and brand recognition. In contrast, Home Instead specializes in a relationship-focused care model for elderly clients. Technology-driven providers such as Cera are gaining traction by integrating digital platforms to manage care delivery and improve efficiency.
UK home healthcare involves providing clinical and non-clinical support within a patient's residence, reducing reliance on hospitals. This model utilizes technologies like patient monitoring systems to manage chronic conditions remotely. While personal care services for elderly patients represent significant market volume, skilled nursing and rehabilitation therapy command higher price points. The adoption of advanced diagnostic equipment is enabling more complex procedures to be performed at home.
The Care Quality Commission (CQC) sets the primary regulatory framework, conducting inspections and rating providers on safety and effectiveness. Separately, guidelines from the National Institute for Health and Care Excellence (NICE) influence the standards for treatments and technologies used in home settings. Providers must navigate the dual challenge of meeting stringent CQC standards while investing in digital health tools to enhance care delivery and operational efficiency.
Market Dynamics
The strategic expansion of NHS virtual wards and Integrated Care Systems is the central force shaping the UK market. This policy shift accelerates demand for home-based clinical services, moving care delivery away from traditional hospital settings and towards preventative, technology-enabled models.
Growth Catalysts
- NHS Policy Expansion:The national directive to increase virtual ward capacity creates a direct demand pull for technology-enabled home healthcare, particularly for post-acute and chronic disease management.
- Demographic Concentration:A significant and aging population in South East England, combined with higher disposable income, drives sustained demand for both private and publicly funded home care services.
- Technological Advancement:Adoption of remote patient monitoring and telehealth platforms enables more complex clinical interventions to be delivered safely and efficiently within a patient's home, expanding service scope.
Market Restraints
- Workforce Scarcity:A persistent shortage of qualified nurses and trained care workers across the UK restricts the capacity of providers to meet escalating service demand, especially for skilled nursing.
- Regulatory Burden:The rigorous inspection and compliance standards set by the Care Quality Commission (CQC) impose significant administrative and operational costs on providers, impacting profitability.
- Fragmented Commissioning:Inconsistent funding and procurement processes across different NHS Trusts and local authorities create complexity and unpredictability for providers seeking public contracts.
Strategic Opportunities
- Specialized Care Niches:There is an underserved market for highly specialized home care, such as for complex neurological conditions or pediatric care, offering higher-margin opportunities beyond general elderly support.
- Regional Expansion:Markets outside of the densely populated South East, particularly in the North of England and Scotland, present opportunities for providers to establish a presence in less saturated areas.
- Integrated Care Partnerships:Collaborating directly with Primary Care Networks (PCNs) to provide preventative and step-down care offers a strategic route to secure patient flow and embed services within local health ecosystems.
Industry Challenges
- Digital Literacy Gaps:A significant portion of the existing care workforce lacks the necessary digital skills to effectively utilize new care management platforms and remote monitoring tools, requiring substantial investment in training.
- System Interoperability:Integrating proprietary provider software with diverse NHS electronic patient record systems presents a major technical and logistical hurdle, hindering seamless data sharing and coordinated care delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Home Healthcare Market |
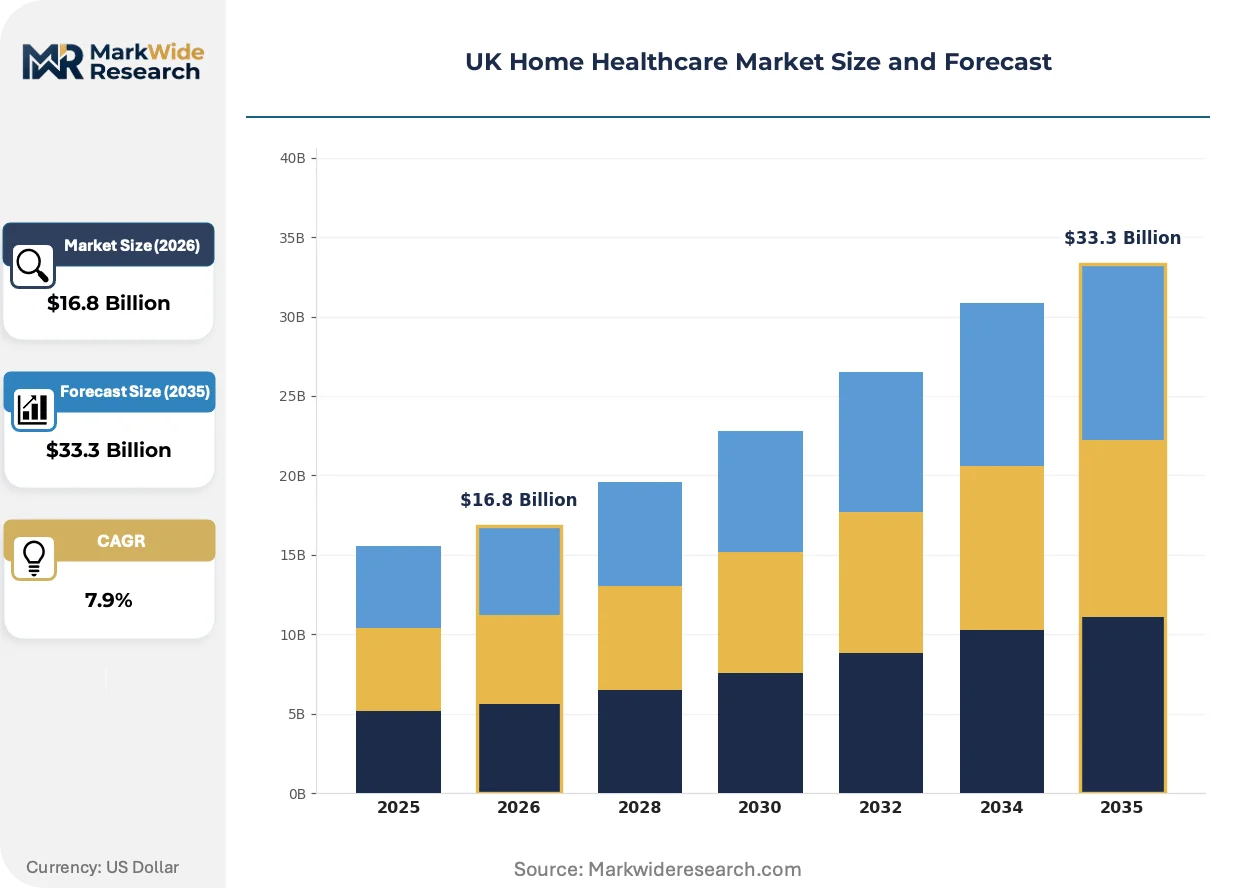
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $33.3 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobility Aids, Respiratory Devices, Patient Monitoring Systems, Wound Care Products, Diagnostic Equipment Care Setting: Private Residence, Assisted Living Facilities, Community Care Centers, Hospice Care, Remote Care Monitoring Service Type: Skilled Nursing, Personal Care, Rehabilitation Therapy, Medical Social Services, Nutritional Support End User: Elderly Patients, Chronically Ill Individuals, Post-operative Patients, Disabled Persons, Pediatric Patients |
| Companies Covered | Care UK, Home Instead, HC-One, Bluebird Care, Cera, Barchester Healthcare, Avery Healthcare, Caremark, Bupa, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Home Healthcare Market Strategic Shifts & Innovations
Digitalization is transforming home healthcare from a reactive, task-based service into a proactive, data-driven model. This evolution focuses on preventative interventions and integrated care pathways, enabled by a new generation of connected health technologies that improve both efficiency and patient outcomes.
Remote patient monitoring (RPM) systems provide real-time physiological data to clinical teams. Chronic disease management programs within the NHS are the primary adopters, using these tools to track conditions like heart failure or COPD. This technology-led approach is overtaking intermittent, in-person visits for routine check-ups, allowing for earlier intervention and more efficient use of clinical staff.
The establishment of Integrated Care Systems (ICSs) across England formalizes the mandate for collaboration between hospitals, community services, and home care providers. This policy drives the creation of unified care pathways that span different settings. Home healthcare providers are most affected, as they must now forge deeper partnerships and demonstrate their value within a broader, integrated health economy.
A fundamental shift towards person-centered care models is changing service expectations, particularly in the private-pay market. This disrupts the traditional model of delivering discrete, task-based services in favor of holistic, relationship-focused support. This trend is most prominent in dementia care and long-term companionship services, where continuity and personalization are primary purchasing criteria.
UK Home Healthcare Market Segmentation
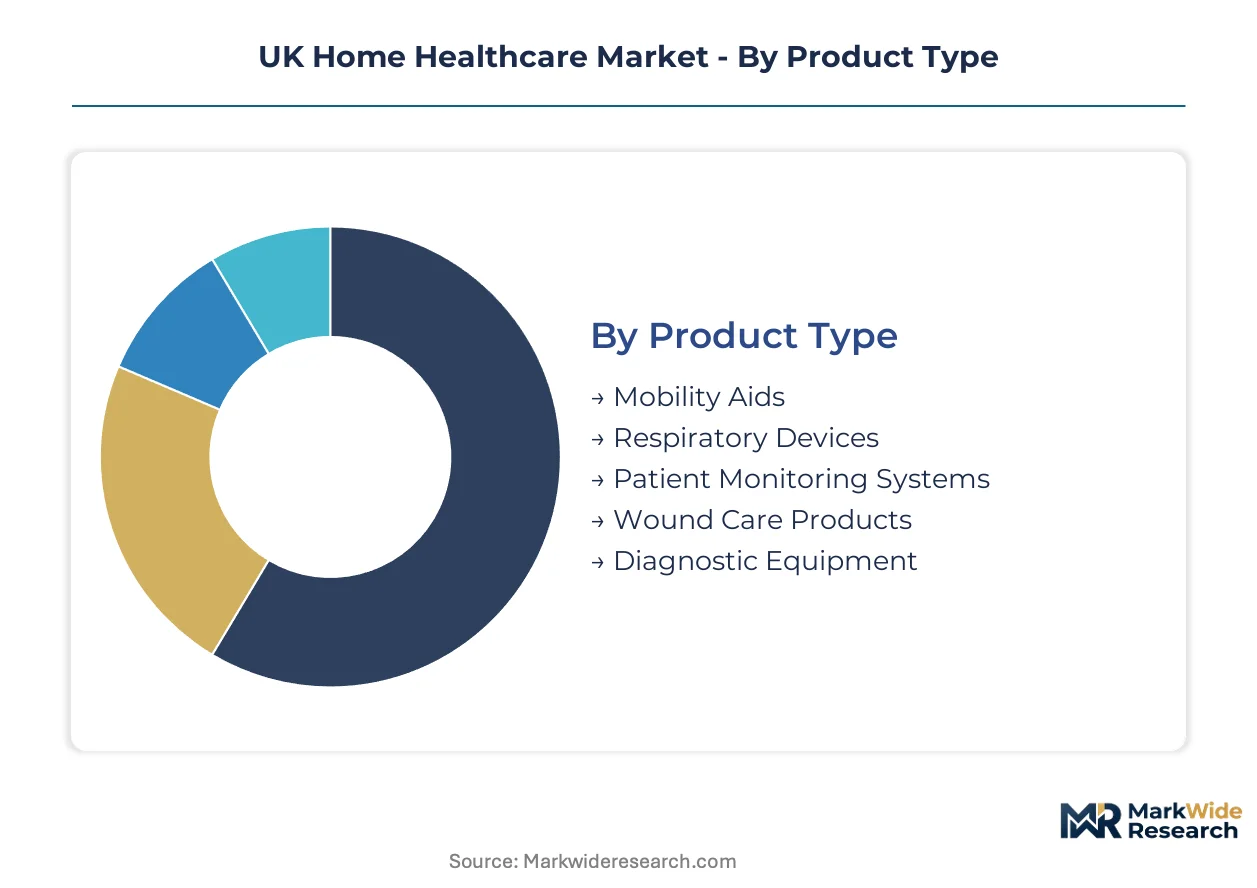
The UK home healthcare market provides a diverse range of services and products tailored to patient needs. Understanding this segmentation clarifies where investment is concentrating and which areas offer the most significant growth potential. This detailed breakdown highlights the evolving landscape of care delivery within patient residences.
Product Type:
The integration depth of products varies significantly, from standalone assistive devices to sophisticated embedded monitoring systems. Providers must balance ease of use for patients with the complexity required for effective clinical management.
- Patient Monitoring Systems:These technologies provide real-time physiological data, including vital signs and glucose levels, directly to clinical teams. Demand is concentrating among chronically ill individuals in South East England, driven by NHS virtual ward expansion for conditions like heart failure and COPD.
- Diagnostic Equipment:This category includes devices enabling complex procedures and assessments at home, such as portable ultrasound or advanced blood analyzers. Demand is accelerating as healthcare shifts from hospitals, allowing earlier intervention and reducing clinic visits.
- Mobility Aids:Products like wheelchairs, walkers, and crutches facilitate movement and independence for patients within their homes.
- Respiratory Devices:This segment includes nebulizers, oxygen concentrators, and CPAP machines for managing chronic respiratory conditions at home.
- Wound Care Products:Dressings, bandages, and antiseptic solutions are essential for managing post-operative or chronic wounds in a home setting.
Mobility Aids leads volumes today; Patient Monitoring Systems is gaining share fastest.
Care Setting:
The application of home healthcare services extends across various residential environments, each presenting unique operational and logistical requirements. Service providers adapt their models to the specific infrastructure and support systems available in each setting.
- Private Residence:Care delivered directly within a patient's own home, encompassing a wide spectrum of clinical and personal support. This setting represents the core of home healthcare provision, particularly for elderly and long-term care patients across the UK.
- Remote Care Monitoring:This involves continuous oversight of patient health data from a central location, reducing the need for physical visits. Its application is expanding rapidly within NHS Integrated Care Systems for managing chronic diseases.
- Assisted Living Facilities:Services provided to residents within purpose-built facilities offering a blend of independence and support.
- Community Care Centers:Local hubs offering day services, therapy, and social interaction, often complementing home-based care.
- Hospice Care:Specialized palliative care services delivered in a home environment for individuals nearing the end of life.
Private Residence dominates service delivery; Remote Care Monitoring exhibits the steepest expansion trajectory.
Service Type:
The volume of services provided varies significantly across different care types, reflecting both patient needs and reimbursement structures. Some services are high-volume necessities, while others are specialized interventions with higher price points.
- Personal Care:Assistance with daily living activities such as bathing, dressing, and meal preparation, often a high-volume service for elderly patients. This segment forms a significant portion of the market volume, particularly in densely populated areas like South East England.
- Skilled Nursing:Clinical interventions performed by licensed nurses, including medication administration, wound care, and disease management. This service commands higher price points due to the specialized training required, despite workforce scarcity.
- Rehabilitation Therapy:Physical, occupational, and speech therapy services delivered at home to restore function and independence.
- Medical Social Services:Support for patients and families navigating healthcare systems, accessing resources, and addressing social determinants of health.
- Nutritional Support:Dietary counseling and assistance with meal planning or specialized feeding for patients with specific health needs.
Personal Care accounts for the largest service volume; Skilled Nursing demonstrates the most rapid market expansion.
End User:
Customer types are defined by specific demographic and health characteristics, influencing the nature and intensity of home care required. Each end-user group presents distinct challenges and opportunities for providers.
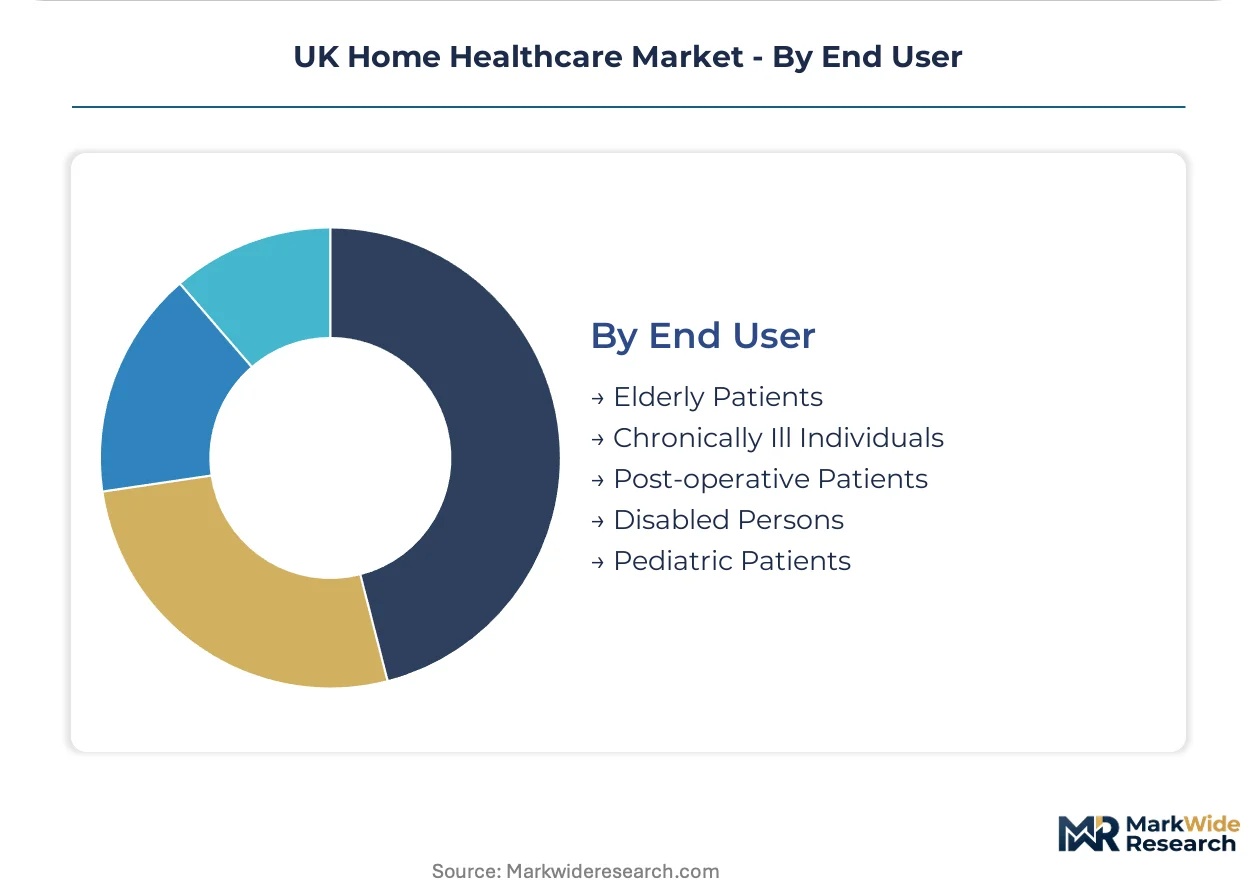
- Elderly Patients:Individuals typically aged 65 and above, requiring assistance with daily living or long-term chronic condition management. This customer type drives substantial demand across the UK, particularly in regions with high aging populations.
- Chronically Ill Individuals:Patients with long-term conditions like diabetes, heart disease, or COPD, benefiting from continuous monitoring and managed care at home. The NHS's focus on virtual wards specifically targets this customer segment.
- Post-operative Patients:Individuals recovering from surgery who require temporary support with wound care, pain management, and mobility.
- Disabled Persons:Individuals with physical or intellectual disabilities requiring long-term support to live independently at home.
- Pediatric Patients:Children with complex medical needs or chronic conditions receiving specialized care within their family home.
Elderly Patients represent the largest end-user group; Chronically Ill Individuals shows the quickest market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The varied regulatory interpretations and operational cost structures across the UK's constituent regions influence the strategic deployment of home healthcare services. Providers often weigh local commissioning frameworks against workforce availability when planning expansion. This creates distinct regional market dynamics for care delivery.
South East England
South East England experiences significant demand from its large elderly population and higher disposable incomes. Local NHS Integrated Care Systems actively commission advanced home care services, particularly for post-acute and chronic disease management. The London metropolitan area sees intense competition among providers. These firms often focus on technology-enabled remote patient monitoring solutions.
Midlands
The Midlands region observes steady demand for chronic disease management and post-operative support, driven by an aging demographic. Adherence to NICE guidelines significantly shapes the delivery of rehabilitation therapy services and specialized nursing. Major cities like Birmingham are developing community care hubs to integrate home-based support more effectively. This integration aims to reduce hospital readmissions.
North England
North England presents opportunities for highly specialized home care services beyond general elderly support. Providers here must meet stringent CQC quality and safety standards for all clinical interventions. Cities such as Manchester and Leeds are actively investing in digital health tools to enhance care delivery efficiency. This includes remote monitoring and telehealth platforms.
Scotland
Scotland focuses on remote patient monitoring to serve its geographically dispersed populations and promote preventative health. NHS Scotland policies strongly support shifting care away from hospitals to home settings for long-term conditions. Glasgow and Edinburgh are fostering integrated care partnerships with Primary Care Networks. These collaborations secure patient flow and embed services within local health ecosystems.
UK Home Healthcare Market Key Industry Players
Established producers occupy the standard tier, focusing on broad personal care services; emerging entrants pursue technology-enabled remote care. The UK home healthcare market exhibits a tiered structure, with large entities leveraging brand recognition and specialized providers targeting niche segments. Archetypes include extensive network providers, relationship-focused specialists, and technology-driven integrators. Strategic partnerships with NHS Integrated Care Systems and investment in digital platforms represent dominant competitive moves.
Within the established network tier, Care UK exemplifies a large entity leveraging an extensive network and brand recognition across the UK, providing a broad range of services. Home Instead occupies a position as a specialist, focusing on a relationship-centered care model primarily for elderly clients, emphasizing continuity and personalization of support. Technology-driven integrators like Cera are gaining traction, representing the integration of digital platforms to manage care delivery and improve efficiency in home settings, particularly for chronic condition management and virtual wards. These distinct approaches highlight the varied strategies employed by providers to capture market share and adapt to evolving patient needs.
| Leading Market Players |
|---|
| Care UK |
| Home Instead |
| HC-One |
| Bluebird Care |
| Cera |
| Barchester Healthcare |
| Avery Healthcare |
| Caremark |
| Bupa |
| Others |
Cost & Logistics Intelligence
Semiconductor component pricing, a key input for remote patient monitoring devices, cascades through the UK home healthcare supply chain, directly influencing the cost structure for technology-enabled services. This dynamic shapes the final pricing tiers offered to both public and private sector buyers.
Pricing Analysis
Distributor margins on medical devices and service contracts significantly influence overall pricing. The dominant pricing structure combines contract-based agreements for NHS-commissioned services with value-based pricing for specialized private care. Price differentiation stems from the level of CQC compliance, the specialized training of care staff, and the integration of advanced digital platforms. Pricing pressure stems from NHS budget constraints and the high operational costs associated with stringent CQC regulatory standards. Chronically ill individuals relying on publicly funded services exhibit higher price sensitivity, while private-pay clients seeking relationship-focused dementia care are less price-sensitive.
Supply Chain Analysis
CE marking and ISO certifications gate access for medical device manufacturers into the UK market. Geographic supply concentration for critical medical technology components centers on China, Germany, and the United States. Key raw material dependencies include medical-grade plastics, advanced sensor arrays, and specialized battery cells. A structural supply chain risk is single-source vulnerability for highly specialized diagnostic equipment. Distribution runs through a combination of direct sales to large home care providers and specialized medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK Home Healthcare Market presents a late-cycle quality story, as demand shifts toward premium specifications for technology-enabled remote patient monitoring and specialized clinical interventions at home.
For Market Incumbents:
Hedge against workforce scarcity by investing heavily in accredited training programs and digital upskilling for existing staff. Consolidate smaller, regional providers to achieve economies of scale and expand geographic reach. Form strategic partnerships with technology firms to integrate advanced digital platforms, enhancing care coordination and operational efficiency. Focus on retaining highly skilled nursing staff to mitigate the threat of specialized care shortages.
For New Entrants and Emerging Players:
Underserved pediatric patients requiring complex home care represent a significant white-space target. Focus on highly specialized care niches, such as neurological rehabilitation or palliative support, which command higher margins. The North of England offers a less saturated market for regional expansion, particularly for technology-enabled services. An effective go-to-market angle involves collaborating directly with Primary Care Networks to embed preventative and step-down care services within local health ecosystems.
For Investors and Strategic Acquirers:
Asymmetric upside sits with technology-driven integrators capable of scaling digital care platforms across diverse patient populations. The market offers long-term viability, supported by strong demographic tailwinds and sustained NHS policy shifts toward home-based care. Acquisition targets should prioritize entities with robust digital infrastructure and established partnerships within Integrated Care Systems. A key signal to watch as an inflection indicator is the rate of NHS virtual ward capacity expansion and associated commissioning frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Streamlines care delivery and enhances remote patient monitoring capabilities for providers. |
| Workforce Upskilling Programs | Addresses the critical shortage of digitally literate and specialized care workers across the UK. |
| Regional Market Expansion | Captures demand in less saturated areas outside of South East England, diversifying revenue streams. |
| Integrated Care Partnerships | Secures patient flow and embeds services within local NHS health ecosystems, ensuring sustained demand. |
| Specialized Service Development | Unlocks higher-margin opportunities beyond general elderly support, meeting complex patient needs. |
Research Approach
Multiple input streams — primary interviews, secondary validation, and quantitative market data — were reconciled to construct a comprehensive market view. This involved engaging home care executives, CQC officials, NHS commissioners, and clinical leads across the UK. Secondary data sources included CQC inspection reports, NICE guidelines, NHS England publications, and relevant industry association reports, triangulated through bottom-up and top-down analyses.
The analytical framework reconciled disparate data streams across the analysis window to project market trajectories. Segmentation dimensions modeled included product type, service type, end-user, regional demand patterns, and technology adoption rates. Compound annual growth rates were derived from historical trends and projected impacts of evolving NHS policies and demographic shifts, using NHS funding allocations and specific demographic shifts as key inputs.
Underlying measurement precision varies by segment; elderly patients and chronically ill individuals carry tighter precision than others. Forecasts reflect assumptions regarding workforce availability, NHS policy stability, and digital infrastructure investment. Deviation in significant shifts in government healthcare spending would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
US House Calls Market
Home Healthcare
Home Healthcare Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Smart Mattress Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
House Call Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Global Home Health Hub Market
Home Healthcare
US Home Infusion Therapy Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Smart Home Healthcare Market