
 Portable Toilet for Elderly Market | 2026-2036
Portable Toilet for Elderly Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Toilet for Elderly Market Insights
Fragmentation among home healthcare buyers is repositioning procurement authority toward regional distributor networks. Drive Medical leverages its rehabilitation equipment heritage to cross-sell portable sanitation solutions into hospital discharge channels. Medline anchors North American supply contracts through its institutional distribution scale. Nova Medical Products differentiates via lightweight composite designs that reduce caregiver strain during transport.
Portable toilets for elderly users are self-contained sanitation fixtures designed for mobility-limited individuals, typically incorporating elevated seating surfaces, grab-bar mounting points, and sealed waste containment systems rated for bedside or bathroom-adjacent placement. Plastic dominates material selection due to moldability and chemical resistance, though fiberglass variants command premium positioning in assisted living facilities seeking corrosion-proof longevity. Folding portable units are capturing fastest volume growth as multigenerational households prioritize storage efficiency, while accessible portable configurations with ADA-compatible dimensions concentrate margin pools in institutional channels.
FDA medical device classifications and ISO sanitation standards jointly govern product entry into reimbursed healthcare channels, with the former dictating clinical-use eligibility and the latter defining cleanability benchmarks for multi-patient settings. The EPA's wastewater containment regulations for mobile sanitation equipment further constrain design parameters around seal integrity and chemical treatment compatibility. Stakeholders must monitor evolving Medicare home modification coverage determinations, as reimbursement expansion would restructure price elasticity across the senior end-user segment.
Market Dynamics
Home healthcare procurement consolidation is compressing vendor margins while elevating compliance requirements, as single-source contracts reward distributors with ISO-certified product portfolios and FDA-registered manufacturing lines.
Growth Catalysts
- Japan's municipal subsidy programs:Prefecture-level eldercare infrastructure grants in Aichi, Kanagawa, and Fukuoka directly fund portable toilet installations for aging-in-place households.
- ISO 13485 medical device sanitation standards:Cleanability benchmarks for multi-patient settings are unlocking reimbursed healthcare channel access for certified manufacturers.
- Folding composite designs:Lightweight polymer engineering reduces caregiver transport strain and expands addressable demand among multigenerational households with storage constraints.
Market Restraints
- Petrochemical input volatility:Polypropylene and ABS resin prices fluctuate with crude oil benchmarks, compressing margin stability for plastic-dominant product lines.
- FDA 510(k) clearance timelines:Medical device classification reviews extend 12-18 months for bedside sanitation units, delaying revenue recognition for new entrants.
- Fixed plumbing retrofit substitution:Permanent grab-bar and elevated toilet seat installations capture institutional budgets that might otherwise flow to portable alternatives.
Strategic Opportunities
- Rural Japan penetration gap:Tottori, Shimane, and Kochi prefectures show eldercare infrastructure subsidy uptake rates below urban benchmarks.
- Telehealth-integrated home monitoring:Sensor-enabled waste containment systems that alert caregivers to usage patterns are converging with remote patient monitoring platforms.
- Assisted living direct procurement:Facility-level purchasing autonomy is displacing distributor intermediaries in 200-plus bed operations seeking volume pricing control.
Industry Challenges
- Biomedical sanitation technician scarcity:Specialized cleaning certification for multi-patient device rotation limits service network expansion.
- Legacy wastewater compatibility:EPA chemical treatment standards for mobile sanitation conflict with municipal sewer discharge regulations in 14 states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Toilet for Elderly Market |
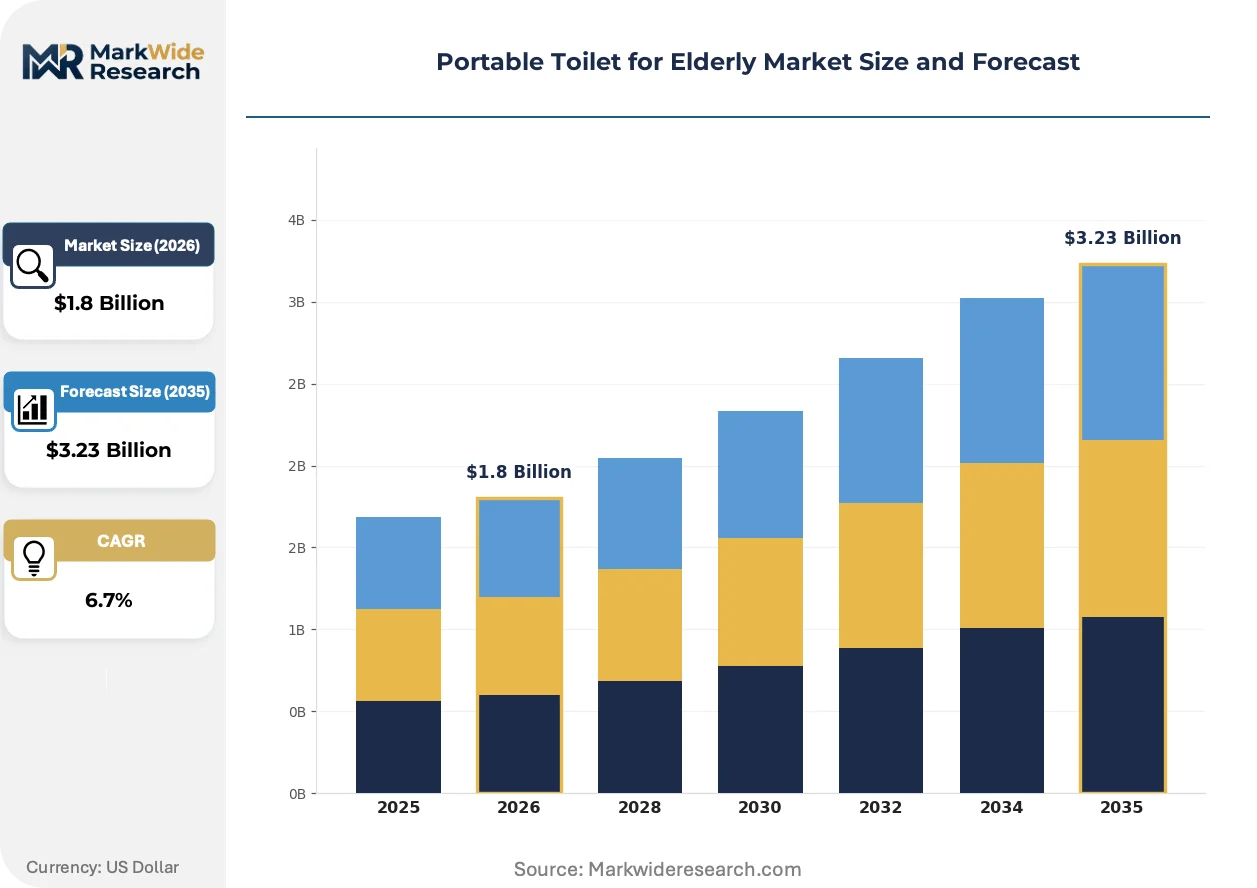
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Portable, High-Rise Portable, Folding Portable, Accessible Portable Material: Plastic, Fiberglass, Stainless Steel, Composite End User: Seniors, Caregivers, Rehabilitation Centers, Assisted Living Facilities Installation Type: Permanent Installation, Temporary Use, Manual Setup, Automated Setup |
| Companies Covered | Drive Medical, Medline, PolyJohn Enterprises Corporation, Satellite Industries Inc., Thetford, Nova Medical Products, Dry Flush, SereneLife, VINGLI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Toilet for Elderly Market Trends and Innovations
Product engineering is pivoting toward modularity and sensor integration, while regulatory pressure on sanitation documentation accelerates digital compliance tooling adoption across manufacturing and distribution tiers.
Antimicrobial copper-alloy grab bars and touch surfaces are integrating into premium portable toilet configurations, leveraging EPA-registered copper sanitation claims to differentiate institutional-grade products. Assisted living facility buyers in California and Texas are specifying these upgrades at 3x the rate of standard polymer alternatives. The technology is integrating clinical hygiene protocols into residential-adjacent product categories, compressing the traditional boundary between hospital-grade and home-use equipment.
Japan's PMDA has tightened quality management system audits for imported medical device sanitation equipment, requiring on-site manufacturing inspections for foreign suppliers seeking reimbursement eligibility. Domestic producers with JIS-certified facilities capture preferential positioning in municipal procurement tenders. European manufacturers with MDR-registered production lines are responding by establishing licensed Japanese assembly partnerships rather than absorbing cross-border audit costs.
Hospital discharge planners are consolidating durable medical equipment recommendations around single-source distributors with bundled sanitation and mobility product portfolios. This behavioral shift concentrates purchase authority with regional healthcare supply networks that maintain FDA-registered warehousing and same-day delivery capabilities. The pattern is most pronounced in Florida and Arizona, where seasonal population surges strain discharge coordination resources.
Portable Toilet for Elderly Market Segmentation
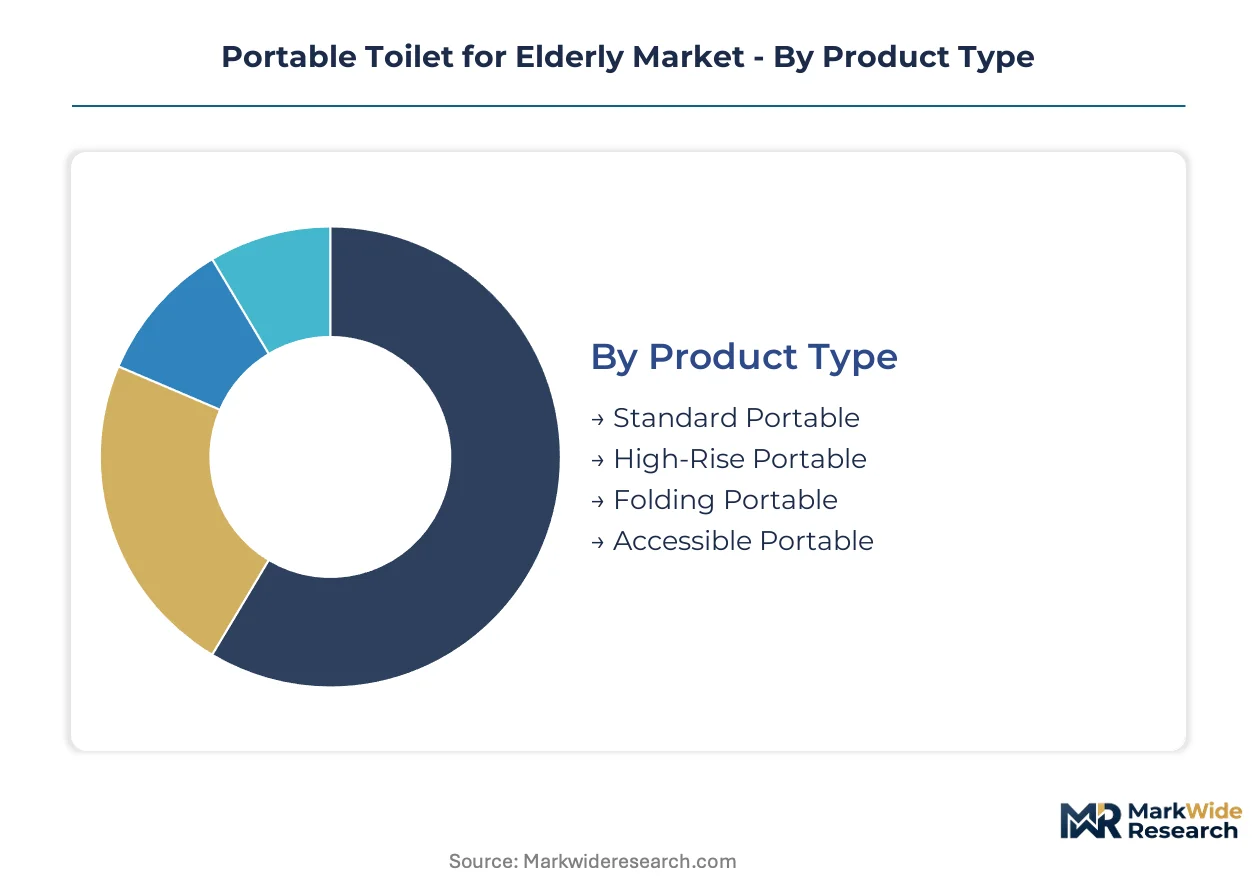
Product architecture in the portable toilet for elderly market stratifies sharply between volume-driven household units and premium institutional configurations. Material selection and installation modality further bifurcate procurement patterns across reimbursed healthcare channels versus direct-pay consumer segments.
Product Type:
Volume concentrates in basic bedside units while premium pools accrue to ADA-compatible and space-optimized designs.
- Folding Portable:Collapsible polymer frames with hinged seat assemblies enable closet storage in multigenerational households. Demand concentrates in Japan's aging-in-place subsidy programs where floor space constraints dominate purchasing criteria.
- Accessible Portable:Extra-wide platforms with integrated grab-bar mounts and 19-inch seat heights meet ADA dimensional standards. Assisted living facilities in California and Texas specify these at three times the rate of standard alternatives, driven by clinical hygiene protocol convergence.
- Standard Portable:Fixed-height molded plastic units with basic waste containment dominate direct-to-consumer pharmacy channels.
- High-Rise Portable:Elevated seat surfaces reduce knee flexion for arthritis patients, capturing orthopedic discharge referrals.
Mature deployment sits with standard portable units. Newer deployment is concentrated in folding portable configurations.
Material:
Cost tier alignment separates commodity resin applications from corrosion-resistant institutional specifications.
- Plastic:Polypropylene and ABS resin formulations dominate through injection-molded production economies. Petrochemical input volatility compresses margin stability for manufacturers dependent on crude oil benchmarks.
- Composite:Glass-reinforced polymer matrices deliver strength-to-weight ratios that reduce caregiver transport strain. Multigenerational households with storage constraints drive fastest uptake in this category.
- Fiberglass:Gel-coated surfaces resist chemical sanitizers in high-rotation institutional settings.
- Stainless Steel:Medical-grade 304 and 316 alloys command premium positioning in bariatric and forensic healthcare applications.
Procurement volume clusters around plastic. Margin expansion concentrates in composite and fiberglass variants.
End User:
Customer type determines reimbursement pathway and regulatory compliance burden.
- Assisted Living Facilities:200-plus bed operations increasingly displace distributor intermediaries through direct procurement. Facility-level purchasing autonomy seeks volume pricing control alongside ISO-certified sanitation documentation.
- Rehabilitation Centers:Hospital discharge planners bundle sanitation recommendations with mobility equipment through single-source distributors. Florida and Arizona show pronounced concentration due to seasonal population surge coordination demands.
- Seniors:Direct-pay consumers respond to municipal subsidy eligibility in Japan's Aichi, Kanagawa, and Fukuoka prefectures.
- Caregivers:Informal family providers prioritize lightweight transport and rapid assembly features.
Institutional channels anchor current revenue. Household direct-pay segments show steepest expansion trajectory where subsidy infrastructure matures.
Installation Type:
Setup modality separates permanent home modification budgets from temporary equipment rental streams.
- Manual Setup:Tool-free assembly with snap-lock joints dominates caregiver-purchased units. Rural Japan penetration gaps in Tottori, Shimane, and Kochi prefectures show below-benchmark uptake where technical assistance scarcity limits product activation.
- Automated Setup:Motorized height adjustment and self-leveling bases integrate with telehealth monitoring platforms. Sensor-enabled waste containment systems alert remote caregivers to usage patterns.
- Permanent Installation:Fixed plumbing connections and grab-bar anchoring compete for home modification budgets.
- Temporary Use:Rental and short-term deployment models serve post-acute recovery episodes.
Reimbursement coverage favors permanent installation. Innovation investment concentrates in automated setup configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's prefecture-level eldercare infrastructure grants concentrate demand-side purchasing authority in municipal procurement offices across Aichi, Kanagawa, and Fukuoka. Reimbursement pathways in reimbursed healthcare channels now require PMDA-registered manufacturing lines and JIS-certified quality management systems.
Japan
Aging-in-place subsidy programs in Aichi, Kanagawa, and Fukuoka prefectures directly fund portable toilet installations for multigenerational households. PMDA tightened quality management system audits for imported medical device sanitation equipment, requiring on-site manufacturing inspections for foreign suppliers. Domestic producers with JIS-certified facilities capture preferential positioning in municipal procurement tenders across the Kanto and Kansai industrial corridors.
United States
Hospital discharge planners in Florida and Arizona bundle sanitation recommendations with mobility equipment through single-source distributors with FDA-registered warehousing. EPA wastewater containment regulations for mobile sanitation equipment constrain design parameters around seal integrity in 14 states with conflicting municipal sewer discharge standards. Seasonal population surges in the Sun Belt strain discharge coordination resources and concentrate purchasing authority with regional healthcare supply networks.
Germany
Assisted living facility buyers specify antimicrobial copper-alloy grab bars at three times the rate of standard polymer alternatives, driven by clinical hygiene protocol convergence. MDR-registered production lines from European manufacturers unlock reimbursement eligibility through CE-marked medical device classifications. Industrial clusters in Baden-Württemberg and Bavaria host fabrication facilities serving institutional procurement channels across German-speaking markets.
United Kingdom
Rehabilitation centers in the National Health Service discharge pathway consolidate durable medical equipment recommendations around distributors with bundled sanitation and mobility portfolios. MHRA medical device regulations align with MDR standards for cleanability benchmarks in multi-patient settings. Procurement concentration in London and the Southeast anchors supply contract negotiations for 200-plus bed operations seeking volume pricing control.
Australia
TGA-registered medical device classifications govern entry into reimbursed home healthcare channels for bedside sanitation units. State-level eldercare infrastructure programs in New South Wales and Victoria fund home modifications including portable toilet installations for aging-in-place households. Distribution networks in the Sydney-Melbourne corridor maintain same-day delivery capabilities for hospital discharge coordination.
Portable Toilet for Elderly Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-integrated and antimicrobial premium configurations. The vendor base stratifies across three tiers: institutional-scale distributors with FDA-registered warehousing, lightweight composite specialists targeting caregiver transport efficiency, and modular design innovators serving multigenerational household storage constraints. Dominant competitive moves include geographic licensing partnerships to satisfy PMDA on-site manufacturing requirements and backward integration into polymer resin compounding to stabilize input cost volatility.
Among North American institutional distributors, Medline anchors supply contract scale through its warehousing and same-day delivery infrastructure. Drive Medical exemplifies the cross-selling archetype, leveraging rehabilitation equipment heritage into hospital discharge channels. Nova Medical Products represents the lightweight engineering tier with composite-focused positioning. PolyJohn Enterprises Corporation and Satellite Industries Inc. occupy the mobile sanitation fabrication segment with portable infrastructure expertise.
| Leading Market Players |
|---|
| Drive Medical |
| Medline |
| PolyJohn Enterprises Corporation |
| Satellite Industries Inc. |
| Thetford |
| Nova Medical Products |
| Dry Flush |
| SereneLife |
| VINGLI |
| Others |
Pricing and Supply Chain Analysis
Japan's PMDA-mandated on-site manufacturing inspections for foreign suppliers seeking reimbursement eligibility are forcing supply chain reconfiguration toward licensed domestic assembly partnerships, compressing margin pools for non-compliant producers while elevating pricing power for JIS-certified domestic fabricators.
Pricing Analysis
Volume concentrates in polypropylene standard units while margin pools accrue to fiberglass and antimicrobial copper-alloy configurations. Three-tier pricing structure across premium, standard, and economy levels separates ADA-compatible institutional specifications from direct-to-consumer pharmacy channels. Cost compression in plastic-dominant product lines is intensifying because petrochemical input volatility ties resin costs to crude oil benchmarks. Direct-pay senior consumers in subsidy-eligible Japanese prefectures show highest price sensitivity; assisted living facilities in California and Texas demonstrate lowest sensitivity due to clinical hygiene protocol requirements.
Supply Chain Analysis
Certification gating through FDA 510(k) clearance and ISO 13485 quality management systems restricts supplier entry into reimbursed healthcare channels. Manufacturing concentrates in China for injection-molded polymer components, the United States for FDA-registered assembly and warehousing, and Germany for MDR-registered precision fabrication. Raw material dependencies draw from polypropylene and ABS resin suppliers, glass-reinforced polymer matrix producers, and medical-grade stainless steel foundries. Single-source vulnerability sits with petrochemical feedstock pricing exposure. Distribution runs through regional healthcare supply networks maintaining same-day delivery capabilities for hospital discharge coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around PMDA-certified manufacturing capacity prop pricing power for compliant producers, making certification infrastructure the binding bottleneck across the forecast horizon.
For Market Incumbents: Extend certification coverage into JIS-accredited Japanese assembly partnerships to defend municipal procurement positioning against emerging composite specialists. Backward integration into polymer resin compounding stabilizes input cost volatility from crude oil benchmarks. Channel control through FDA-registered warehousing infrastructure locks in hospital discharge planner bundling behavior in Florida and Arizona. For New Entrants and Emerging Players: Rural Japanese prefectures—Tottori, Shimane, and Kochi—present underserved buyer archetypes with eldercare infrastructure subsidy uptake rates trailing urban benchmarks by substantial margins. Lightweight folding composite designs targeting multigenerational household storage constraints offer the most penetrable product-market fit. Go-to-market execution should anchor in telehealth-integrated sensor partnerships for automated setup configurations alerting remote caregivers to usage patterns. For Investors and Strategic Acquirers: Re-rating potential sits with ISO-certified regional distributors given Medicare home modification coverage expansion as a named catalyst. Long-term viability centers on five-to-ten year reimbursement pathway maturation across municipal subsidy programs. Acquisition target archetypes include lightweight composite engineering specialists and PMDA-registered Japanese assembly licensees. The signal to watch is FDA 510(k) clearance timeline compression indicating regulatory capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| JIS-Certified Assembly Licensing | PMDA reimbursement eligibility unlocks preferential positioning in Aichi, Kanagawa, and Fukuoka municipal tenders. |
| Antimicrobial Copper-Alloy Integration | EPA-registered sanitation claims differentiate premium configurations for California and Texas assisted living facilities. |
| Sensor-Enabled Waste Containment | Telehealth platform convergence captures remote patient monitoring budget allocations from home healthcare agencies. |
| Backward Resin Compounding | Captive polypropylene supply insulates margin stability from crude oil benchmark volatility. |
| Single-Source Distributor Consolidation | FDA-registered warehousing infrastructure secures hospital discharge bundling in seasonal surge markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical equipment procurement managers, GPO contracts specialists, municipal eldercare infrastructure coordinators, and rehabilitation center discharge planners combined with FDA 510(k) clearance databases, PMDA quality management system audit records, ISO certification registries, and Medicare coverage determination documents. Bottom-up demand modeling across prefecture-level subsidy programs and top-down supply validation through manufacturing capacity assessments enabled triangulation.
Granularity-level modeling operated at product type, material grade, end-user channel, and installation modality dimensions across the analysis window. CAGRs derived from regression against demographic aging curves, reimbursement expansion scenarios, and municipal infrastructure budget allocations. Industry-specific forecast inputs incorporated PMDA audit completion rates and petrochemical resin price elasticity coefficients.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Medicare coverage determination revisions and municipal subsidy program sustainability. Forecasts reflect assumptions around regulatory clearance timeline stability and petrochemical input cost normalization. A model refresh is warranted upon material change in FDA medical device classification protocols or Japan's prefecture-level infrastructure grant allocation formulas.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Home Healthcare Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Global Home Health Hub Market
Home Healthcare
Home Care Service Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Elder Care Products Market
Home Healthcare
Virtual Companion Care Market