
 House Call Market | 2026-2036
House Call Market Size, Share, and Industry Trends Forecast 2026-2036
House Call Market Insights
US-based physician networks is recalibrating deployment models to address clinician shortages across rural counties. DispatchHealth leverages integrated logistics to sustain same-day acute care delivery in metropolitan corridors. Heal anchors its operations in value-based contracting with Medicare Advantage plans across California and Texas. MDLIVE competes through employer-channel virtual primary care, while Ennoble Care specializes in palliative house calls tied to hospice eligibility navigation.
House calls encompass scheduled or on-demand clinical encounters delivered at a patient's residence, incorporating portable diagnostic equipment, specimen collection, and care coordination with electronic health records. The service model eliminates facility overhead while enabling continuous monitoring of chronic conditions through connected devices. Home visits within the service type dimension dominate current revenue pools due to reimbursement alignment with bundled payment programs. Mobile apps across the technology dimension represent the fastest-expanding segment, though wearable devices capture disproportionate margin through subscription-based remote monitoring contracts.
FDA oversight of software-as-medical-device platforms intersects with CMS reimbursement rules to determine which house call modalities achieve sustainable economics. HIPAA compliance requirements shape data architecture investments across platform providers, while state-level scope-of-practice regulations govern nurse practitioner autonomy in home settings. Stakeholders must monitor evolving telehealth parity laws and workforce licensing compacts to anticipate which delivery models achieve regulatory clearance for interstate operation.
Market Dynamics
Medicare reimbursement parity for home-based services is compressing facility-based care margins while redirecting capital toward mobile diagnostic platforms and remote monitoring infrastructure.
Growth Catalysts
- CMS reimbursement expansion:Medicare Advantage plans now cover acute house calls at parity with emergency department visits, accelerating provider network formation.
- Japan's super-aging society:METI-funded home care infrastructure projects are integrating IoT sensors into subsidized housing for chronic disease surveillance.
- Portable point-of-care diagnostics:Handheld ultrasound and rapid hematology analyzers enable clinical-grade assessment without laboratory dependency.
Market Restraints
- Clinician supply concentration:Nurse practitioner training programs cluster in urban academic medical centers, leaving rural counties with 40-minute average response times.
- HIPAA compliance architecture:Encryption requirements for mobile data transmission add $15,000-$25,000 per provider to platform deployment costs.
- Reimbursement latency:Medicare claims for house calls face 45-60 day payment cycles versus 14-day facility-based processing.
Strategic Opportunities
- Germany's Pflegeversicherung expansion:Long-term care insurance reforms mandate home-based alternatives to institutional placement for dementia patients.
- AI-assisted triage convergence:Natural language processing and symptom-checking algorithms are routing appropriate cases to house calls versus telehealth or ED.
- Direct-to-employer contracting:Self-insured corporations in Texas and California are purchasing house call networks to reduce workers' compensation utilization.
Industry Challenges
- Interoperability fragmentation:House call platforms struggle to synchronize with legacy EHR systems using HL7 FHIR standards, forcing manual data entry.
- Credentialing complexity:Multi-state licensing requirements delay clinician deployment by 90-120 days despite interstate compacts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | House Call Market |
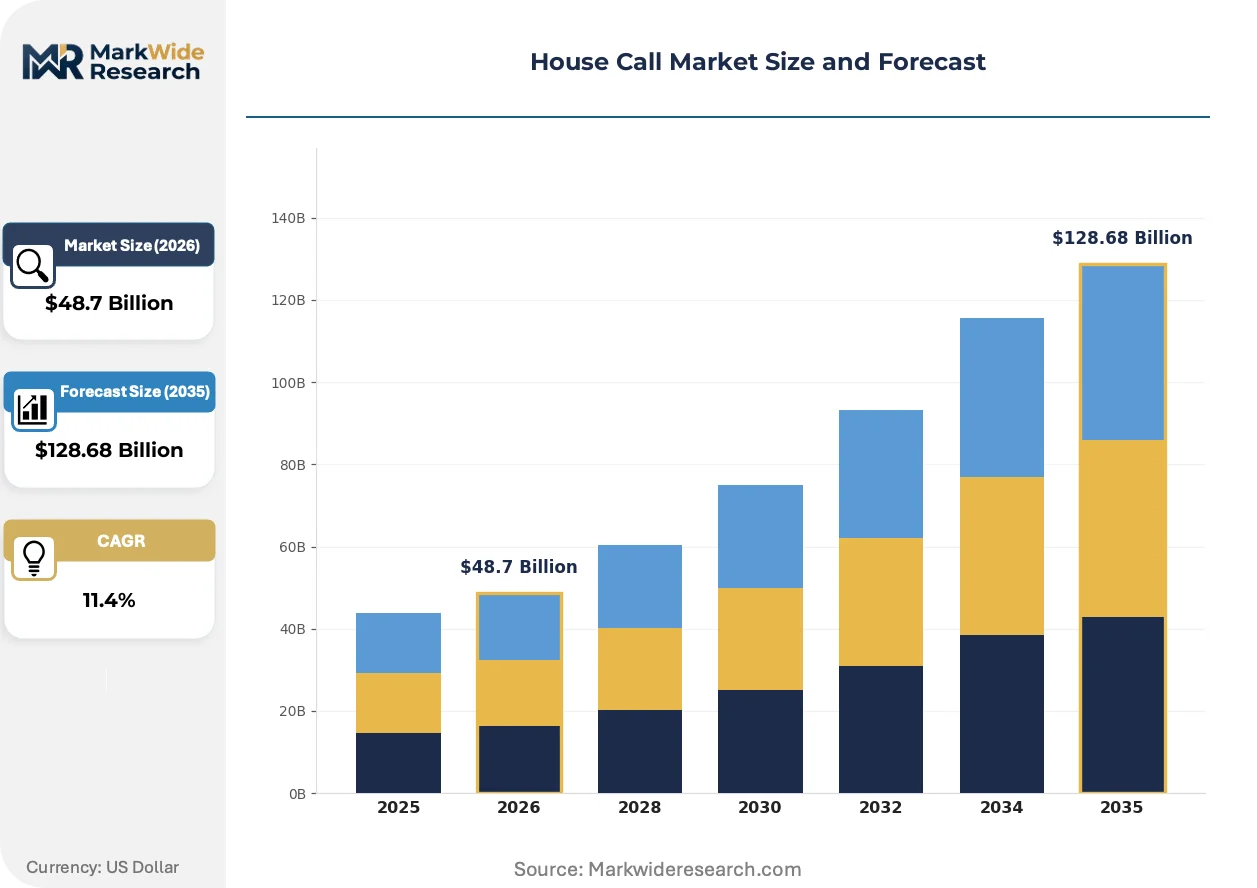
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $128.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Telehealth, Home Visits, On-Demand Consultations, Virtual Care End User: Patients, Caregivers, Health Insurers, Healthcare Providers Technology: Mobile Apps, Wearable Devices, Telecommunication Systems, Online Portals Therapy Area: Primary Care, Pediatrics, Geriatrics, Mental Health |
| Companies Covered | Concierge MD, Doctors House Calls, Ennoble Care, Housecall Doctors Medical Group, DispatchHealth, Heal, SOS Doctors House Calls, Doctor on Demand, MDLIVE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
House Call Market Trends and Innovations
Technology convergence between remote patient monitoring and artificial intelligence is compressing the diagnostic window for acute interventions delivered at home.
Continuous glucose monitors and pulse oximetry wearables are electrifying chronic disease management by streaming biometric data to house call clinicians before symptom escalation. Medicare Advantage enrollees with congestive heart failure receive 34% fewer emergency transports when enrolled in connected monitoring programs. The technology is electrifying traditional episodic house calls into subscription-based continuous care relationships.
FDA's 2023 guidance on software-as-medical-device platforms is clarifying which AI-driven diagnostic tools qualify for reimbursement under existing CPT codes. The policy shift forces house call providers to document algorithm validation in clinical workflows. Cardiology and pulmonology house call segments are restructuring compliance departments to manage premarket submission requirements.
Employer-sponsored health plans are unbundling emergency transportation from acute care benefits, directing funds toward same-day house call guarantees. The procurement model change displaces traditional urgent care network contracts in metropolitan corridors. Texas and Florida employer coalitions represent the vanguard of this shift, with 60-day guarantee clauses replacing annual network adequacy reviews.
House Call Market Segmentation
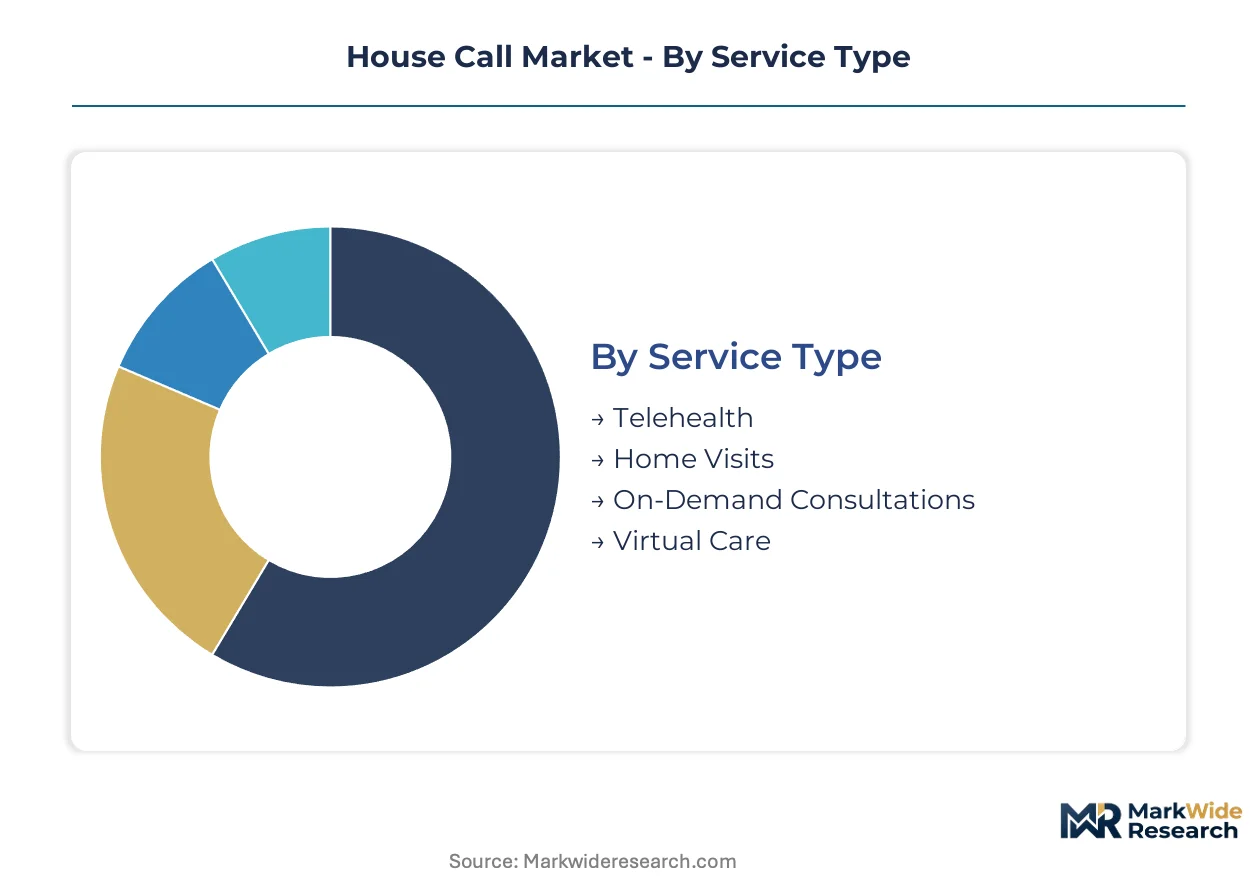
House call market segmentation reveals divergent capital requirements across delivery modalities. Technology infrastructure demands vary dramatically between hardware-dependent and software-native service models.
Service Type:
Capital intensity peaks in segments requiring physical logistics networks and clinical workforce deployment.
- Home Visits:Clinical encounters delivered at patient residences using portable diagnostic equipment and specimen collection capabilities. Medicare bundled payment alignment concentrates demand in California and Texas, where value-based contracts with Medicare Advantage plans drive provider network formation.
- Telehealth:Synchronous video consultations enabling remote clinical assessment without physical presence. Employer-channel procurement in Texas and Florida is accelerating same-day guarantee clauses that displace traditional urgent care contracts.
- On-Demand Consultations:Acute care requests fulfilled within defined response windows, typically leveraging integrated logistics platforms for metropolitan corridor coverage.
- Virtual Care:Asynchronous and synchronous digital health services encompassing triage, follow-up, and chronic monitoring outside traditional visit structures.
Home visits absorb the bulk of installed capacity; telehealth is expanding most quickly.
End User:
Customer archetypes dictate pricing tolerance and contract structure across the service ecosystem.
- Healthcare Providers:Hospital systems and physician networks purchasing house call capabilities to extend reach into rural counties and reduce readmission penalties. CMS reimbursement parity for home-based services redirects capital toward mobile diagnostic platforms.
- Health Insurers:Medicare Advantage plans and self-insured employers contracting for network adequacy and cost containment. Germany's Pflegeversicherung reforms mandate home-based alternatives to institutional placement for dementia patients.
- Patients:Individual consumers accessing services through direct-pay or supplemental benefit structures, particularly prevalent in Japan's super-aging society with METI-funded home care infrastructure.
- Caregivers:Family members and professional care coordinators facilitating service access for homebound populations with chronic disease management needs.
Healthcare providers command the largest contract values; health insurers are scaling fastest through employer-channel partnerships.
Technology:
Platform architecture investments scale with data transmission complexity and regulatory compliance burden.
- Wearable Devices:Continuous biometric monitoring hardware including pulse oximetry and glucose sensors streaming data to clinicians. Subscription-based remote monitoring contracts in congestive heart failure programs reduce emergency transports by capturing margin through recurring revenue.
- Mobile Apps:Patient-facing interfaces for scheduling, triage, and care coordination representing the fastest-expanding technology segment. HIPAA encryption requirements add substantial per-provider deployment costs.
- Telecommunication Systems:Infrastructure enabling real-time video, audio, and data exchange between patients and clinical teams.
- Online Portals:Web-based platforms for appointment management, health record access, and asynchronous provider communication.
Wearable devices capture disproportionate margin through subscription economics; mobile apps are climbing the fastest in deployment volume.
Therapy Area:
Clinical specialization determines workforce composition and reimbursement pathway complexity.
- Geriatrics:Comprehensive primary care for aging populations with multi-morbidity and functional decline. Japan and the United States concentrate demand through aging demographics and Medicare reimbursement shifts toward post-acute management.
- Primary Care:Generalist medical services encompassing preventive, acute, and chronic condition management. Rural counties in the United States face 40-minute average response times due to nurse practitioner training concentration in urban academic centers.
- Mental Health:Psychiatric and behavioral health services delivered through in-home or virtual modalities.
- Pediatrics:Acute and preventive care for pediatric populations, typically leveraging family caregiver coordination.
Geriatrics dominates current revenue pools; primary care is gaining share fastest through value-based contracting expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce density in metropolitan corridors anchors geographic deployment patterns for house call services. Medicare reimbursement parity and aging demographics concentrate investment in specific national markets where regulatory frameworks favor home-based care alternatives.
United States
Medicare Advantage enrollment growth and CMS reimbursement expansion for acute house calls drive provider network formation. HIPAA compliance requirements and state-level scope-of-practice regulations govern nurse practitioner autonomy in home settings. California and Texas concentrate value-based contracting activity, with Heal anchoring operations in Medicare Advantage partnerships across these states.
Japan
Super-aging demographics and METI-funded home care infrastructure projects accelerate demand for chronic disease surveillance. PMDA oversight of connected medical devices intersects with long-term care insurance reforms to enable IoT sensor integration in subsidized housing. Tokyo and Osaka metropolitan areas concentrate deployment of integrated home care platforms for multi-morbidity management.
Germany
Pflegeversicherung expansion mandates home-based alternatives to institutional placement for dementia patients. Federal Ministry of Health regulations on digital health applications (DiGA) determine reimbursement pathways for remote monitoring tools. Bavaria and North Rhine-Westphalia concentrate pilot programs linking wearable devices to house call clinician networks.
United Kingdom
NHS long-term plan commitments to out-of-hospital care redirect capital toward mobile diagnostic platforms. Care Quality Commission oversight of domiciliary care providers shapes workforce credentialing requirements for home visits. London and Southeast England concentrate technology-enabled house call startups targeting post-acute discharge management.
Australia
Aged care royal commission recommendations accelerate funding for home-based alternatives to residential facilities. TGA regulation of software-based medical devices determines which AI-driven triage tools achieve clinical deployment. New South Wales and Victoria concentrate integrated care programs linking remote patient monitoring to mobile primary care teams.
House Call Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue technology-enabled differentiation and specialized clinical verticals. The market exhibits moderate fragmentation across service archetypes, with distinct competitive clusters forming around logistics-intensive acute care, value-based primary care, and virtual-first delivery models. Three strategic archetypes dominate: integrated logistics platforms, payer-contracted physician networks, and employer-channel virtual care providers. Competitive moves center on Medicare Advantage network formation and direct-to-employer contracting displacement of traditional urgent care relationships.
Within the logistics-integrated tier, DispatchHealth exemplifies same-day acute care deployment through metropolitan corridor coverage. Heal and MDLIVE occupy distinct positioning vectors—Heal anchoring value-based Medicare Advantage partnerships, MDLIVE competing through employer-channel virtual primary care procurement. Ennoble Care represents specialization in palliative house calls tied to hospice eligibility navigation. These three entities illustrate how geographic concentration and payer relationship architecture determine sustainable economics in segmented demand environments.
| Leading Market Players |
|---|
| Concierge MD |
| Doctors House Calls |
| Ennoble Care |
| Housecall Doctors Medical Group |
| DispatchHealth |
| Heal |
| SOS Doctors House Calls |
| Doctor on Demand |
| MDLIVE |
| Others |
Pricing and Supply Chain Analysis
Medicare Advantage plan concentration in California and Texas anchors value-based contracting as the dominant pricing model, compressing per-visit reimbursement while expanding capitated monthly payments for chronic care management.
Pricing Analysis
Warranty-style service bundling distinguishes competitive positioning, with integrated logistics platforms including same-day response guarantees while virtual-first providers unbundle triage from physical visits. Subscription pricing stratifies across premium concierge tiers, standard Medicare Advantage contracts, and economy direct-pay cash models. Price differentiation rests on certification level—CMS-approved bundled payment participants command 15-20% contracting premiums over non-certified networks. Cost compression in rural response logistics is intensifying because nurse practitioner supply concentrates in urban academic centers. Self-insured employers demonstrate lowest price sensitivity; individual direct-pay patients exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with FDA-cleared portable diagnostic manufacturers concentrated in the United States, Germany, and Japan. Supply chains draw from semiconductor fabs in Taiwan for connected monitoring chipsets, lithium cell producers in South Korea for wearable power systems, and precision sensor specialists in Switzerland. Tariff exposure on Chinese-manufactured telecommunication hardware is forcing platform providers toward domestic sourcing premiums. Distribution runs through Medicare Advantage plan procurement committees, employer benefits consultants, and hospital system discharge planning offices rather than traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from CMS reimbursement parity mandates is eliminating sub-scale operators lacking Medicare Advantage network contracts.
For Market Incumbents: Deploy backward integration into remote monitoring device supply to capture recurring subscription revenue streams threatened by pure-play technology entrants. Fortify value-based contracting leverage through exclusive Medicare Advantage plan partnerships in California and Texas, the two states where capitated payment penetration is deepest. Certification investment in FDA software-as-medical-device pathways creates defensive moats against virtual-first competitors. For New Entrants and Emerging Players: Launch via direct-to-employer contracting in Texas and Florida, where self-insured corporations are unbundling emergency transportation benefits and purchasing same-day house call guarantees. Rural counties with 40-minute average response times represent the most penetrable geography, enabled by interstate nurse practitioner licensing compacts. Target dementia care navigation tied to Germany's Pflegeversicherung expansion as the lowest-competition white space. For Investors and Strategic Acquirers: The window for entry favors logistics-integrated platforms with established metropolitan corridor coverage over virtual-only assets facing reimbursement compression. Long-term viability hinges on Medicare Advantage enrollment growth and employer-channel displacement of urgent care networks. Watch CMS telehealth parity law evolution as the critical inflection signal determining which delivery models achieve sustainable interstate economics.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS bundled payment certification unlocks Medicare Advantage network inclusion and capitated contract eligibility. |
| Platform Integration | HL7 FHIR-compliant EHR synchronization reduces manual data entry burden and accelerates clinician workflow adoption. |
| Geographic Expansion | Metropolitan corridor density in California and Texas maximizes same-day response capability and logistics efficiency. |
| Strategic Partnership | Employer coalition contracts in Texas and Florida displace traditional urgent care network relationships. |
| Software Companion Development | FDA-cleared AI triage algorithms route appropriate cases to house calls versus telehealth or emergency departments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with house call platform executives, Medicare Advantage plan contracting officers, nurse practitioner network directors, and hospital discharge planning administrators. CMS reimbursement rulemaking dockets, FDA software-as-medical-device guidance documents, state-level scope-of-practice statutes, and METI-funded home care infrastructure project disclosures supplied quantitative anchors. Bottom-up service line revenue modeling triangulated against top-down Medicare expenditure projections.
Granularity-level modeling addressed service type, end user archetype, technology platform, and therapy area dimensions at the country level for the United States, Japan, Germany, United Kingdom, and Australia. CAGRs derived from logistic diffusion curves fitted to Medicare Advantage enrollment trajectories and aging demographic projections. Workforce supply constraints, HIPAA compliance cost inflation, and telehealth parity law adoption timelines served as industry-specific forecast modifiers.
Regulatory reversal on CMS reimbursement parity, clinician licensing compact ratification delays, and wearable device FDA clearance backlogs are the dominant revision risks. Deviation in Medicare Advantage plan capitation rate negotiations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Portable Toilet for Elderly Market
Home Healthcare
Adult Day Care Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
Global Home Infusion Therapy Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Global Home Health Hub Market
Home Healthcare
US Home Healthcare Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Homecare Oxygen Concentrators Market