
 Germany Home Healthcare Market | 2026-2036
Germany Home Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Home Healthcare Market Intelligence
The distribution channel mix for home healthcare products in Germany is tilting away from traditional pharmacies toward integrated home delivery services and online retailers. B. Braun Melsungen leverages its extensive hospital network to secure direct-to-patient supply contracts for postoperative care. Fresenius Medical Care dominates the renal care segment through its service and product delivery model. Coloplast specializes in chronic care products, building strong brand loyalty through direct patient support programs.
Germany's home healthcare encompasses medical equipment, services, and supplies prescribed for patients recovering or managing conditions outside of a hospital setting. These products, such as continuous glucose monitors or negative pressure wound therapy systems, enable clinical-level care within private residences. Wound care and monitoring instruments represent significant product categories, driven by postoperative and chronic care needs. Within applications, chronic disease management for conditions like diabetes and COPD constitutes the largest and most established segment, commanding substantial reimbursement.
The German Medical Devices Act (MPG), which aligns with the EU's Medical Device Regulation (MDR), governs product safety and market access for all equipment. Reimbursement policies set by the Federal Joint Committee (G-BA) directly influence the economic viability of new home care technologies and services. Navigating the G-BA's complex approval and reimbursement pathways for digital health applications remains a critical challenge for device manufacturers and service providers.
Market Dynamics
The primary structural force is the regulatory framework, specifically Germany's Digital Healthcare Act (DVG). This legislation is actively creating a formal pathway for digital health applications, fundamentally altering service delivery models from hospital-centric to home-based care.
Growth Catalysts
- Digital Healthcare Act (DVG):Germany’s law provides a fast-track reimbursement process for digital health applications (DiGA), boosting telehealth and remote monitoring services.
- Chronic Disease Burden:Rising incidence of conditions like COPD and diabetes in an aging population sustains demand for home-based disease management programs.
- Urban Infrastructure:Advanced healthcare networks in states like North Rhine-Westphalia enable efficient logistics and service delivery for home healthcare providers.
Market Restraints
- G-BA Reimbursement Hurdles:The Federal Joint Committee's (G-BA) complex approval process is a significant barrier to market entry for novel home care technologies.
- High Labor Costs:Germany's competitive market for qualified nurses inflates operational costs for home healthcare service providers, constraining margins.
- Data System Fragmentation:Poor interoperability between digital health tools and legacy hospital IT systems inhibits the creation of seamless patient care pathways.
Strategic Opportunities
- Predictive Analytics Integration:Combining AI with remote monitoring data can proactively manage patient conditions and reduce hospital readmissions.
- Rural Market Expansion:Developing telehealth and logistics models to serve underpenetrated rural regions of Germany presents a significant growth opportunity.
- Subscription-Based Supply Models:Creating subscription services for chronic care consumables builds direct patient relationships and secures recurring revenue streams.
Industry Challenges
- Specialized Talent Scarcity:A shortage of nurses trained in digital health tools hinders the scaling of technology-enabled home care services in Germany.
- GDPR Compliance Burden:Adhering to the General Data Protection Regulation for patient data from connected devices represents a significant operational complexity and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Home Healthcare Market |
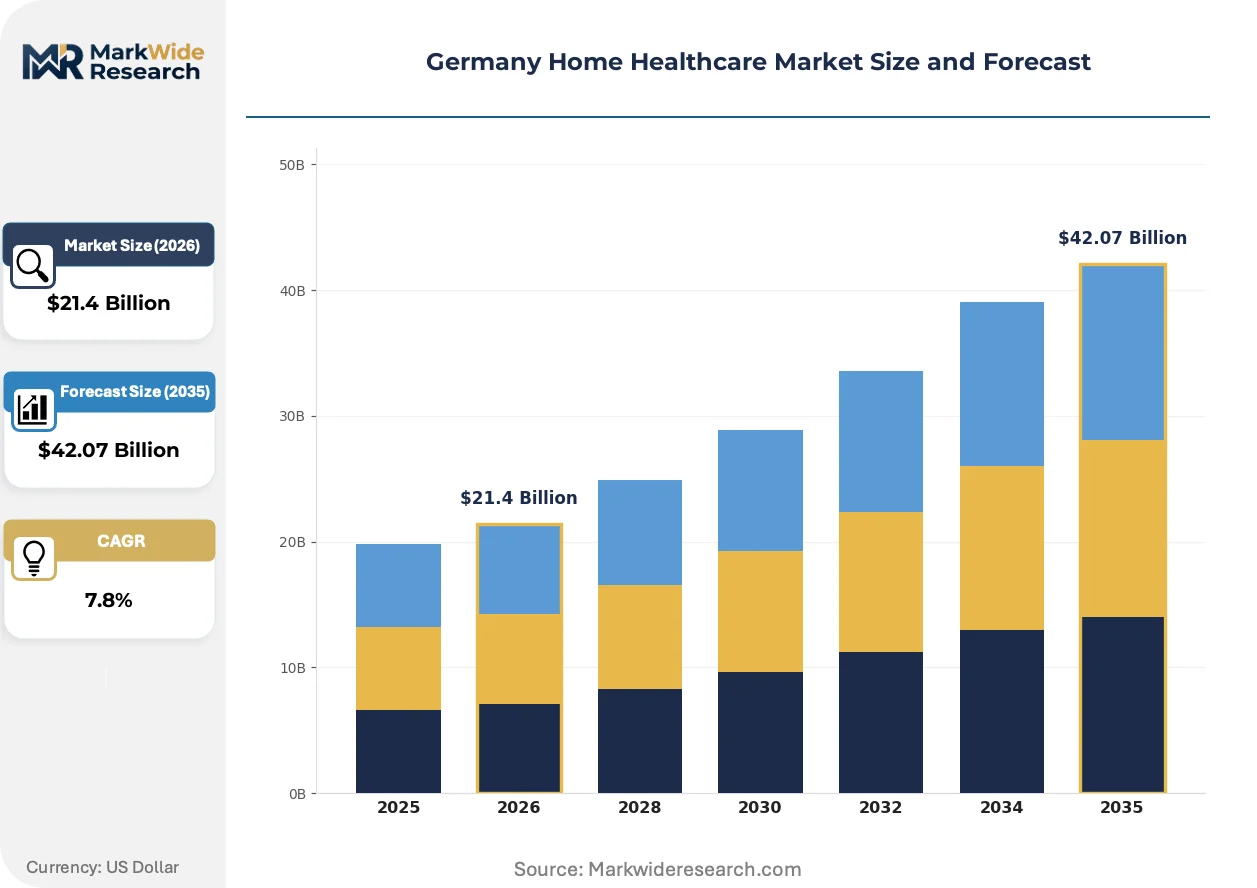
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $42.07 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobility Aids, Wound Care, Respiratory Devices, Monitoring Instruments, Personal Care Equipment Application: Chronic Disease Management, Postoperative Care, Elderly Support, Pediatric Care, Palliative Care Care Setting: Private Residences, Assisted Living Facilities, Community Nursing, Hospice, Rehabilitation Centers Distribution Channel: Pharmacies, Medical Supply Stores, Online Retailers, Home Delivery Services, Direct Sales |
| Companies Covered | Smith & Nephew, ConvaTec Group, Fresenius Medical Care, Acelity, Molnlycke Healthcare, B. Braun Melsungen, Medline Industries, Hollister, Coloplast, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Home Healthcare Market Strategic Shifts & Innovations
The market's evolution centers on a fundamental shift from reactive, episodic care to proactive, continuous health management within the patient's home. This transition is enabled by the convergence of connected devices, data analytics, and patient-centric service models.
Wearable biosensors provide real-time streams of physiological data for remote patient monitoring. Patients with chronic conditions like diabetes or heart disease are the primary adopters, driven by reimbursement for digital health applications. This constant data flow is rendering obsolete the traditional model of relying on infrequent, in-clinic appointments for disease management.
Germany's Medical Devices Act (MPG), harmonized with the EU's Medical Device Regulation (MDR), elevates compliance requirements. It mandates more rigorous clinical evidence and post-market surveillance for all home healthcare equipment. This most affects manufacturers of complex devices like infusion systems, who now face higher costs and extended timelines to achieve market access.
A clear behavioral shift is underway towards direct-to-patient supply models, particularly for postoperative and chronic care management. This model disintermediates traditional pharmacies in favor of integrated services that bundle equipment, supplies, and patient support. The trend is most pronounced in major urban centers like Berlin, where logistics networks are highly efficient.
Germany Home Healthcare Market Segmentation
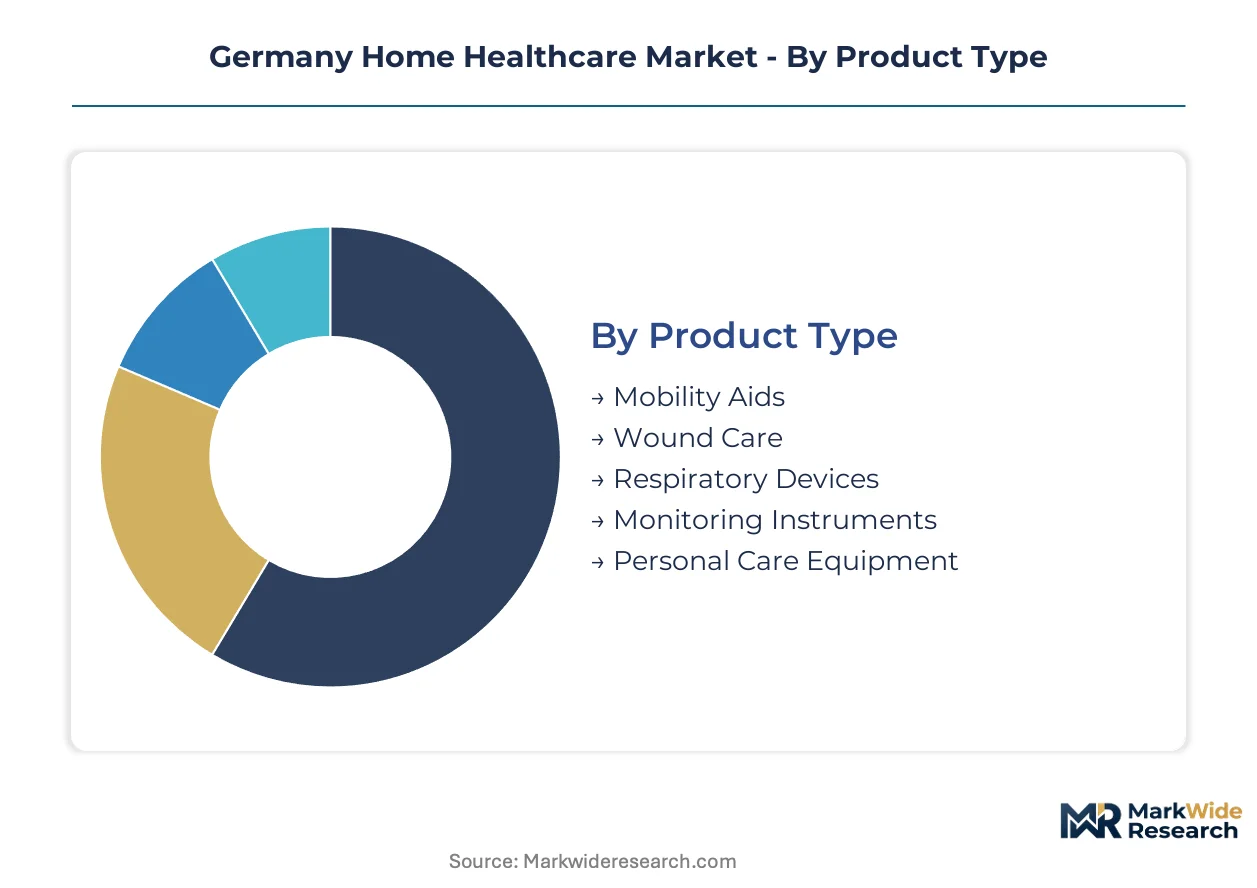
Segmentation reveals the diverse needs within Germany's home healthcare market, allowing providers to tailor services and products effectively. Understanding these distinct segments helps manufacturers and service providers optimize resource allocation, navigate regulatory pathways, and address specific patient demographics across the country. This granular view is crucial for strategic planning.
Product Type:
The maturity spectrum for home healthcare product types in Germany shows varying levels of market penetration and technological advancement.
- Wound Care:Advanced dressings, negative pressure wound therapy systems, and antimicrobial agents comprise this segment, facilitating complex wound healing at home. Demand concentrates in urban centers like North Rhine-Westphalia due to high postoperative patient volumes and chronic wound prevalence.
- Monitoring Instruments:Continuous glucose monitors, blood pressure cuffs, and pulse oximeters enable real-time physiological data collection for remote patient management. This segment sees significant demand from patients with chronic conditions, driven by Germany's Digital Healthcare Act (DVG) reimbursement for digital health applications.
- Mobility Aids:Wheelchairs, walkers, and patient lifts assist individuals with impaired movement, enhancing independence within private residences.
- Respiratory Devices:Oxygen concentrators and nebulizers support patients with chronic respiratory conditions like COPD, improving quality of life at home.
- Personal Care Equipment:Items such as commodes and bath aids facilitate daily living activities for elderly and disabled individuals.
Wound Care handles the majority of throughput; Monitoring Instruments is the fastest mover on share.
Application:
Patient needs define the core applications within Germany's home healthcare landscape, influencing service design and product development.
- Chronic Disease Management:This application focuses on long-term care for conditions like diabetes, COPD, and heart failure, integrating remote monitoring and medication management. Demand is consistently high across all German states, sustained by the country's aging population and the rising incidence of non-communicable diseases.
- Elderly Support:Services and products catering to the daily living and medical needs of seniors, including personal care assistance and fall prevention systems. This segment experiences significant demand in regions with high elderly populations such as Bavaria, driven by a preference for aging in place.
- Postoperative Care:Provides medical and rehabilitative services to patients recovering from surgery, facilitating faster and safer recuperation at home.
- Pediatric Care:Addresses the specific medical needs of children at home, including complex medical equipment and skilled nursing services.
- Palliative Care:Focuses on providing comfort and support to patients with serious illnesses, enhancing quality of life during advanced stages of disease.
Chronic Disease Management applications command the largest share, while Pediatric Care is expanding its service offerings.
Care Setting:
The delivery of home healthcare services in Germany varies significantly across different care settings, reflecting diverse patient requirements and infrastructure.
- Private Residences:Patients receive medical equipment, supplies, and services directly in their own homes, offering comfort and familiarity. This setting represents the largest volume of home healthcare delivery, particularly in densely populated urban areas where logistics are efficient.
- Assisted Living Facilities:These residential settings provide a blend of housing, support services, and healthcare assistance for individuals who require help with daily activities. Demand for integrated home healthcare within these facilities is strong, driven by the increasing number of seniors seeking semi-independent living solutions.
- Community Nursing:Skilled nursing services delivered in community-based clinics or directly to patients' homes, supporting wound care and medication administration.
- Hospice:Dedicated facilities or home-based programs offering end-of-life care, focusing on pain management and emotional support for patients and families.
- Rehabilitation Centers:Provide intensive therapy and medical supervision to help patients recover from injury, surgery, or illness before returning home.
Private Residences remain the dominant care setting, with Assisted Living Facilities demonstrating consistent growth in integrated care models.
Distribution Channel:
The distribution landscape for home healthcare products in Germany is undergoing a strategic transformation, favoring efficiency and direct patient access.
- Online Retailers:E-commerce platforms offer a wide range of home healthcare products, providing convenience and competitive pricing for consumers. This channel is experiencing rapid expansion, particularly for consumables and non-prescription items, driven by digital adoption across Germany.
- Home Delivery Services:Integrated logistics providers deliver medical equipment and supplies directly to patient homes, often bundled with installation and support. This channel is increasingly favored for postoperative and chronic care products, especially in urban areas like Berlin where efficiency is paramount.
- Pharmacies:Traditional retail outlets dispensing medical supplies and devices, often serving as a primary point of contact for patients with minor needs.
- Medical Supply Stores:Specialized retail locations offering a broad selection of medical equipment, from mobility aids to respiratory devices, with expert consultation.
- Direct Sales:Manufacturers or specialized providers engage directly with patients or healthcare institutions to supply specific high-value or complex medical devices.
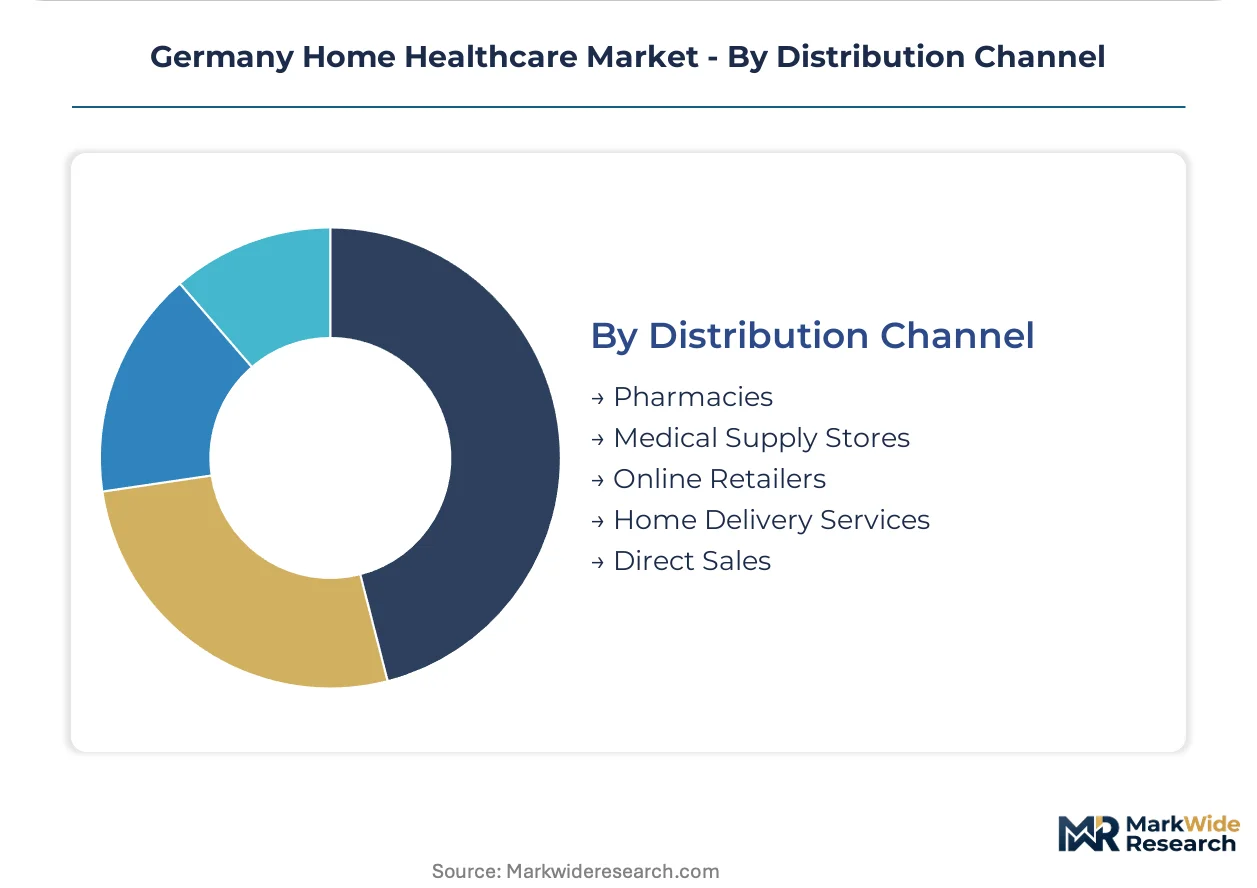
Online Retailers and Home Delivery Services are reshaping market access, while traditional pharmacies adapt their offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced digital infrastructure, particularly its high-speed broadband networks, underwrites the nation's leadership in home healthcare technology adoption. This robust connectivity facilitates the widespread implementation of telehealth and remote monitoring services across various regions. Regional disparities in demographic profiles and healthcare infrastructure significantly shape demand patterns across German states.
Bavaria
Demand for elderly support services is particularly high in Bavaria due to its significant aging population and preference for aging in place. The state benefits from federal initiatives like the Digital Healthcare Act (DVG), which actively promotes reimbursement for digital health applications. Munich, a major urban center, drives innovation in medical technology and provides efficient logistics for specialized home care providers.
North Rhine-Westphalia
North Rhine-Westphalia experiences substantial demand for wound care and postoperative services, driven by its large, densely populated urban areas. The state's advanced healthcare network actively integrates remote monitoring solutions to improve patient outcomes and reduce readmissions. Cologne and Düsseldorf serve as key hubs for advanced medical device distribution and specialized home nursing services.
Berlin-Brandenburg
Berlin-Brandenburg shows strong growth in digital health applications and subscription-based supply models, fueled by a tech-savvy population. GDPR compliance frameworks rigorously guide data protection for connected health devices deployed across the region. Berlin’s dynamic startup ecosystem fosters innovation in telehealth platforms and efficient direct-to-patient logistics for chronic care products.
Hesse
Hesse's demand for chronic disease management programs is sustained by its diverse patient demographics and robust healthcare system. The Federal Joint Committee (G-BA) policies significantly influence reimbursement pathways for novel home care technologies in the state. Frankfurt, a central economic hub, supports efficient distribution networks and specialized medical supply stores for comprehensive home healthcare needs.
Germany Home Healthcare Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing essential medical devices and consumables. This market exhibits a tiered structure, with large multinational corporations coexisting with specialized regional providers. Strategic archetypes include comprehensive service providers, niche product manufacturers, and digital health platform developers. Key competitive moves involve strategic partnerships for integrated care solutions and targeted acquisitions to expand product portfolios.
Within the comprehensive service provider archetype, Fresenius Medical Care, a GmbH, dominates the renal care segment through its integrated service and product delivery model. B. Braun Melsungen AG represents a major player leveraging its extensive hospital network to secure direct-to-patient supply contracts for postoperative care. Coloplast, specializing in chronic care products, builds strong brand loyalty through direct patient support programs, exemplifying a niche product manufacturer. These entities anchor distinct segments of the German home healthcare market.
| Leading Market Players |
|---|
| Smith & Nephew |
| ConvaTec Group |
| Fresenius Medical Care |
| Acelity |
| Molnlycke Healthcare |
| B. Braun Melsungen |
| Medline Industries |
| Hollister |
| Coloplast |
| Others |
Cost & Logistics Intelligence
Germany's advanced manufacturing clusters, particularly around Bavaria and North Rhine-Westphalia, influence home healthcare product availability and cost structures. Their production capacity for medical devices and consumables directly impacts market pricing power.
Pricing Analysis
Volume-discount tiering structures characterize pricing for many home healthcare products, especially consumables and monitoring instruments. Price differentiation stems from product complexity and after-sales service bundles, such as installation and technical support. Pricing softness is evident in high-volume, commoditized segments due to intense competition among suppliers. Hospitals and large care networks, benefiting from bulk purchasing, represent the least price-sensitive buyers, while individual patients for non-reimbursed items exhibit higher sensitivity.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the flow of medical devices from manufacturers to providers. Geographic supply concentration for complex medical equipment draws from Germany, Switzerland, and the Netherlands. Raw material dependencies include specialized polymers for wound dressings and microelectronics for monitoring instruments. Single-source vulnerability for critical components represents a structural supply chain risk. Distribution runs through integrated logistics providers and direct-to-patient channels, particularly for chronic care.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany home healthcare market requires a strong substitution defense, as hospital-based care models continue to evolve towards home settings. Incumbents must navigate the threat of disintermediation by direct-to-patient digital health platforms.
For Market Incumbents:Build integrated service moats by bundling medical equipment with comprehensive patient support programs. Incumbents like B. Braun Melsungen can leverage their hospital networks to secure direct-to-patient supply contracts, countering the threat from specialized online retailers. Investing in digital health R&D for remote monitoring platforms provides a critical lever against emerging tech-first competitors. Expanding clinical education for home care nurses also reinforces service quality differentiation.
For New Entrants and Emerging Players:Establish a beachhead in underpenetrated rural regions of Germany by developing efficient telehealth and logistics models. The elderly support segment, with its growing demand for non-medical assistance and monitoring, presents a penetrable white-space opportunity. Focusing on subscription-based supply models for chronic care consumables offers a clear go-to-market angle. Leveraging AI for predictive analytics in patient management provides a distinctive value proposition.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized digital health platform developers with proven reimbursement pathways. The long-term viability of this market depends on continuous innovation in remote monitoring and AI-driven predictive care over the next five to ten years. Acquisition targets should include firms with strong DiGA certifications and established patient data management systems. A signal to watch is the G-BA's expanding reimbursement scope for novel home care technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: AI-powered Diagnostic Tool | Offers proactive patient management, reducing hospital readmissions. |
| Hospital System Partnership | Secures direct patient access for postoperative and chronic care services. |
| Reimbursement Strategy: Accelerate DiGA Certification | Unlocks significant revenue streams through Germany's Digital Healthcare Act. |
| Geographic Expansion: Target Rural Areas | Addresses unmet demand and diversifies revenue streams beyond urban centers. |
| Subscription-Based Supply Models | Builds direct patient relationships and ensures stable, recurring revenue. |
Research Approach
Operator-level perspectives from clinicians, hospital procurement managers, digital health developers, and patient advocacy groups anchored the qualitative base. Primary interviews were triangulated with extensive secondary validation, drawing from G-BA policy documents, DVG legislation, EU MDR compliance reports, and national health statistics. This approach ensured a robust understanding of market dynamics, leveraging both bottom-up insights from practitioners and top-down regulatory frameworks.
Scenario-bracketing informed the quantitative forecast model, accounting for optimistic and conservative market trajectories across the analysis window. Segmentation dimensions included product type, application, care setting, distribution channel, and regional adoption patterns. Compound annual growth rates were derived from historical data trends and projected demand drivers. Key forecast inputs included Germany's aging population demographics and digital health reimbursement rates.
Sensitivities concentrate around regulatory shifts, particularly G-BA policy updates and DVG amendments. Forecasts reflect assumptions about technology adoption rates and healthcare labor cost stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Smart Mattress Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
UK Home Healthcare Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
US House Calls Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Global Nursing Care Market