
 Canada Home Healthcare Market | 2026-2036
Canada Home Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Home Healthcare Market Outlook
Ontario's home nursing infrastructure is expanding across the Greater Toronto Area as provincial health authorities redirect post-acute capacity from institutional settings. ParaMed leverages its established personal support worker network to dominate community-based service delivery in Ontario and Quebec. B. Braun sustains its position through specialized infusion therapy equipment designed for residential clinical environments. Koninklijke Philips competes on connected care platforms that integrate ventilator and sleep therapy data into provincial electronic health records.
Canada home healthcare encompasses medical devices, therapeutic equipment, digital health platforms, and skilled clinical services delivered in residential settings rather than institutional facilities. Products must meet Health Canada's Class II-IV medical device licensing requirements, including electrical safety standards for home oxygen concentrators and biocompatibility protocols for wound care supplies. Home monitoring devices represent the fastest-expanding product category as provincial health networks deploy pulse oximeters and blood pressure cuffs with cellular connectivity to reduce emergency department readmissions. Telehealth solutions capture concentrated margin pools where platforms integrate with existing provincial electronic medical record architectures. Rehabilitation equipment remains a mature segment with stable replacement cycles driven by occupational therapy prescriptions.
Health Canada and the Canadian Agency for Drugs and Technologies in Health jointly shape market access through health technology assessments that determine provincial reimbursement eligibility for home-based interventions. Provincial health authorities in Ontario, British Columbia, and Alberta operate distinct tendering frameworks that fragment procurement standards across jurisdictions. The Canada Health Act establishes the universal coverage foundation, while PMRA pesticide and antimicrobial residue limits indirectly affect wound care product formulations. Stakeholders must monitor how provincial digital health strategies reconcile interoperability mandates with existing vendor lock-in across legacy hospital information systems.
Market Dynamics
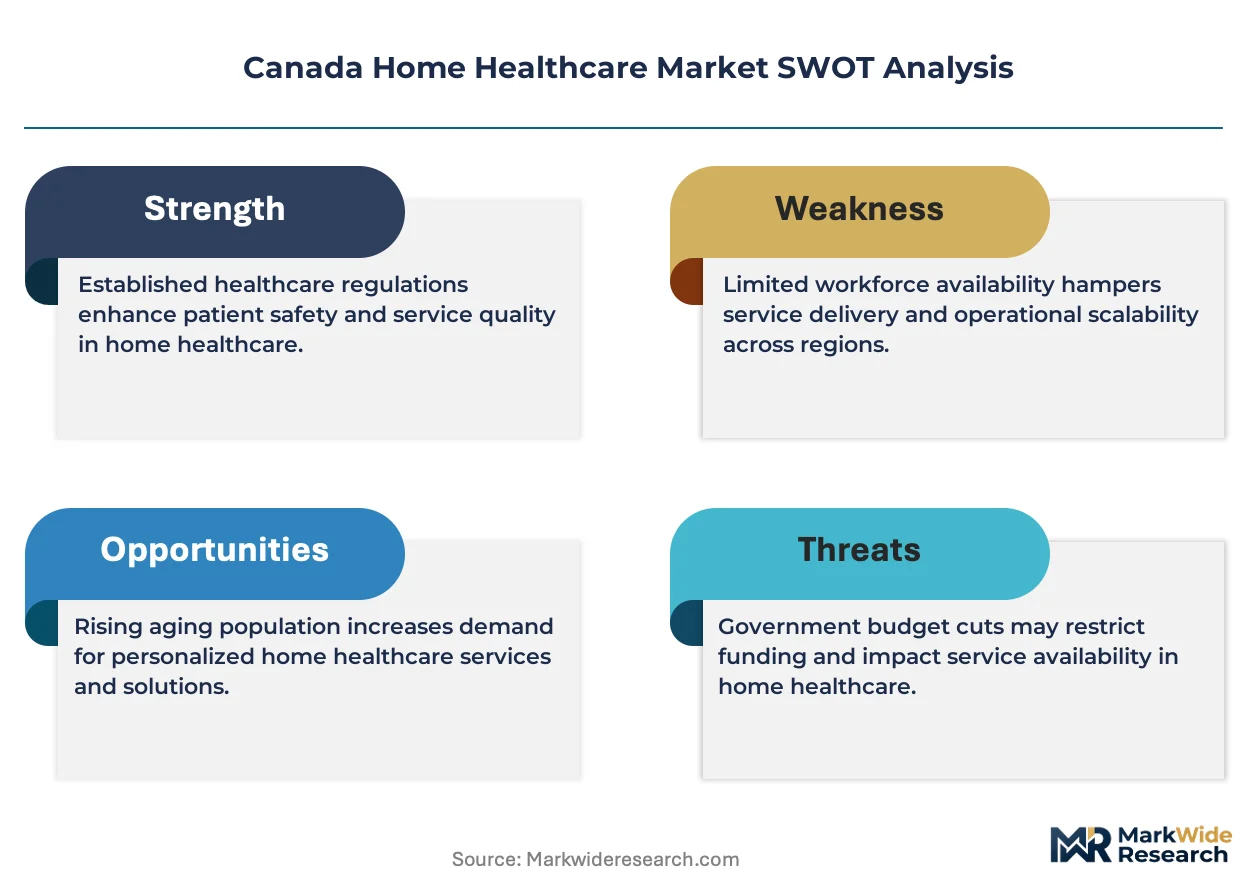
Provincial health authorities in Ontario, British Columbia, and Alberta are redirecting post-acute care capacity from hospitals to residential settings, creating structural demand for connected monitoring devices and skilled nursing services delivered at home.
Growth Catalysts
- Hospital-at-home expansion:Ontario's Ministry of Health is funding acute-level care delivery in residential settings for COPD and heart failure patients, eliminating institutional bed constraints.
- Remote patient monitoring reimbursement:British Columbia's provincial health plan now covers cellular-connected pulse oximeters and blood pressure cuffs for chronic disease management.
- Aging demographic concentration:The Greater Toronto Area and Metro Vancouver are experiencing concentrated growth in patients over 75 requiring post-surgical wound care and infusion therapy at home.
Market Restraints
- Interoperability fragmentation:Ontario's eHealth Ontario, British Columbia's HealthLinkBC, and Alberta's Netcare operate incompatible electronic medical record architectures that prevent seamless data flow for home monitoring devices.
- Personal support worker supply constraints:Community care providers face recruitment gaps in rural Quebec and Atlantic Canada where wage competition from institutional settings drains talent pools.
- Class III device licensing timelines:Health Canada's 12-18 month review cycle for ventilators and infusion pumps delays market entry for manufacturers of next-generation home respiratory equipment.
Strategic Opportunities
- Indigenous community networks:Northern Ontario and remote British Columbia reserves lack home nursing infrastructure, creating white space for mobile health units paired with telehealth diagnostics.
- Provincial digital health mandates:Ontario's Digital First for Health strategy requires vendor interoperability with its ONE ID patient authentication system, favoring platforms built on open API architectures.
- Rehabilitation-at-home protocols:Alberta Health Services is piloting remote physiotherapy monitoring for total joint replacement patients, expanding the addressable market for motion-sensing rehabilitation equipment.
Industry Challenges
- Clinical workforce credentialing variance:Registered nurses licensed in Ontario require additional provincial registration to deliver services in Quebec, fragmenting cross-border staffing for national home care providers.
- Legacy hospital information system integration:Toronto's University Health Network and Vancouver Coastal Health operate on Cerner and Epic installations that resist third-party home monitoring data ingestion without costly custom interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Home Healthcare Market |
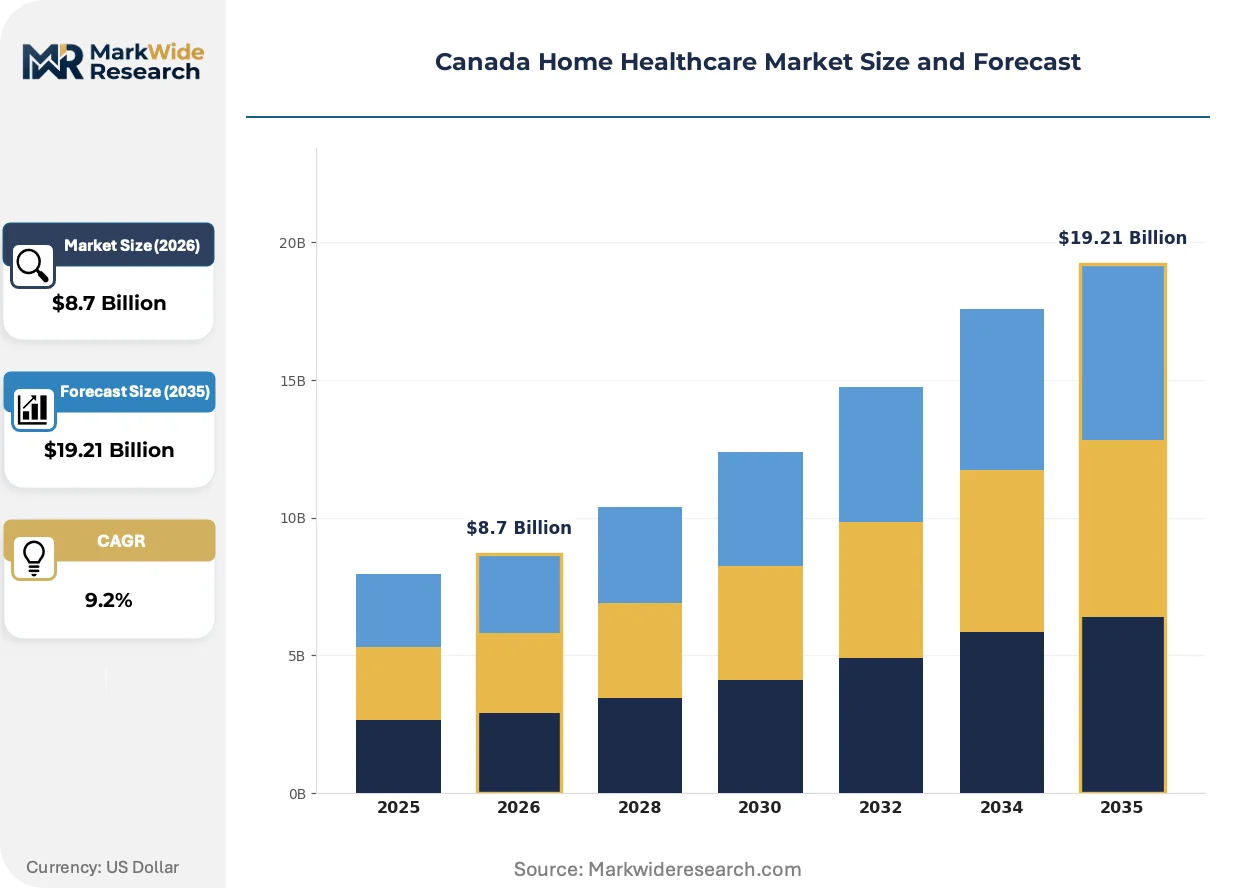
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.21 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Supplies, Home Monitoring Devices, Rehabilitation Equipment, Mobility Aids End User: Patients, Caregivers, Healthcare Providers, Family Members Technology: Telehealth Solutions, Remote Patient Monitoring, Wearable Devices, Healthcare Software Service Type: Home Nursing Services, Physiotherapy, Occupational Therapy, Palliative Care |
| Companies Covered | UnitedHealth Group, B. Braun, ParaMed, Koninklijke Philips, Abbott Laboratories, SE Health, Medtronic, Fresenius Medical Care, Extendicare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Home Healthcare Market Strategic Shifts
Connected care platforms are fragmenting into specialized modules that target specific clinical workflows rather than comprehensive enterprise deployments, compressing implementation cycles and lowering buyer switching costs.
Remote patient monitoring hardware is modularizing around condition-specific kits—COPD bundles with spirometers and pulse oximeters, cardiac recovery sets with blood pressure cuffs and weight scales—rather than universal multi-parameter devices. Ontario's hospital-at-home programs are adopting these kits fastest, with Toronto's University Health Network deploying 400 cardiac monitoring bundles since 2024. This modularity is compressing procurement decisions from enterprise-wide tenders to departmental purchasing authority.
Health Canada's regulatory modernization for medical devices is accelerating licensing pathways for software-as-medical-device platforms that perform diagnostic analysis on patient-generated data. The amended Medical Device Regulations now permit predicate device referencing for algorithm updates, reducing submission burdens for AI-enabled monitoring tools. Remote ECG interpretation and fall-risk prediction algorithms are benefiting most, with three Ontario-based vendors receiving priority review designations in 2024.
Buying patterns among provincial health authorities are fragmenting from centralized tendering to program-specific procurement. British Columbia's regional health authorities now issue separate contracts for wound care supplies, respiratory equipment, and digital health platforms rather than consolidated home care bundles. This disintermediation favors specialized vendors with narrow product depth over diversified distributors, particularly in Vancouver's Fraser Health and Island Health regions where procurement autonomy has devolved to clinical program directors.
Canada Home Healthcare Market Segmentation
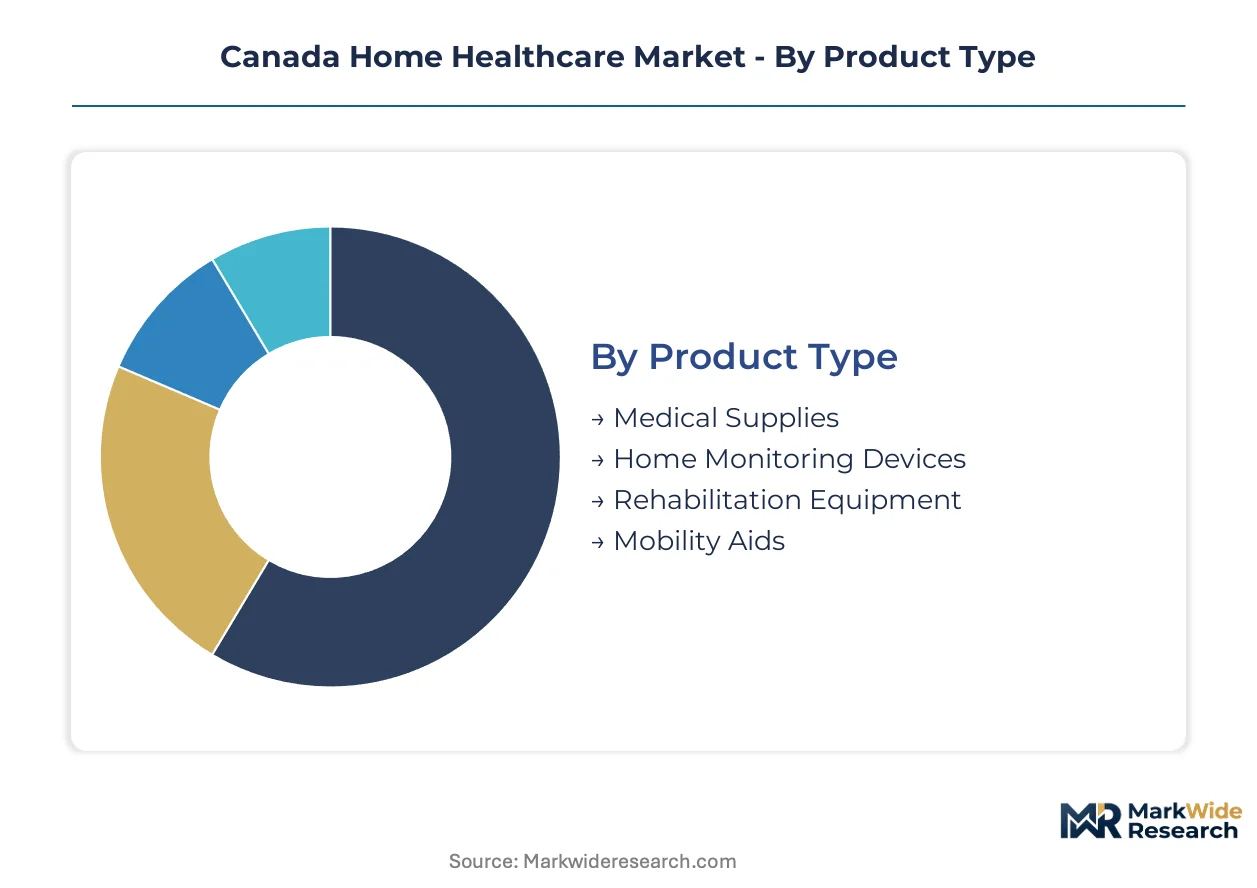
Canada's home healthcare market segments along four critical dimensions that determine regulatory pathways, procurement channels, and reimbursement eligibility across provincial health systems. Understanding these divisions reveals where Health Canada licensing burdens concentrate and which segments command premium pricing through clinical validation requirements.
Product Type:
Health Canada Class II-IV medical device certifications create tiered compliance burdens across product categories, with electrical safety and biocompatibility standards varying by risk classification.
- Medical Supplies:Wound care dressings, ostomy products, and disposable clinical consumables face moderate regulatory scrutiny under Class II device rules. Demand clusters in Ontario's hospital-at-home programs where post-surgical patients require sterile dressing changes. PMRA antimicrobial residue limits constrain formulation options for adhesive bandages and antiseptic wipes.
- Home Monitoring Devices:Cellular-connected pulse oximeters, blood pressure cuffs, and glucometers carry Class III licensing requirements for data transmission security. British Columbia's provincial reimbursement for chronic disease management is accelerating deployment in Vancouver's integrated community care networks. Health Canada's 12-18 month review cycle for algorithm-enabled diagnostics creates entry barriers for AI-powered interpretation tools.
- Rehabilitation Equipment:Resistance bands, therapeutic putty, and home exercise stations operate under lighter Class I oversight as non-powered therapeutic aids.
- Mobility Aids:Walkers, wheelchairs, and transfer benches require mechanical safety certification but minimal clinical validation for home use authorization.
Home Monitoring Devices sits at the top of the volume ranking, with Medical Supplies climbing the fastest.
End User:
Procurement authority and reimbursement eligibility diverge sharply across user categories, with provincial health plans covering institutional referrals while private payment dominates direct-to-consumer channels.
- Patients:Direct recipients of home healthcare services whose eligibility for provincial coverage depends on medical necessity assessments by Ontario's Local Health Integration Networks or British Columbia's regional health authorities. Toronto's aging demographic over 75 drives concentrated demand for wound care and infusion therapy at home.
- Caregivers:Personal support workers and home health aides employed by community care providers like ParaMed, whose services are funded through provincial budgets in Ontario and Quebec. Rural Quebec and Atlantic Canada face acute recruitment gaps as institutional wage competition drains talent pools.
- Healthcare Providers:Hospital discharge planners and community nurses who authorize home care referrals and prescribe specific equipment brands.
- Family Members:Unpaid informal caregivers who purchase retail mobility aids and monitoring devices without provincial reimbursement support.
Patients command the largest addressable base, though Caregivers represent the fastest-expanding procurement influence as provincial authorities professionalize home-based service delivery.
Technology:
Software-as-medical-device regulations are reshaping competitive dynamics, with Health Canada's amended Medical Device Regulations accelerating pathways for algorithm updates while maintaining clinical validation standards.
- Telehealth Solutions:Video consultation platforms and virtual care portals that integrate with provincial electronic health records. Ontario's Digital First for Health strategy mandates ONE ID patient authentication compatibility, favoring vendors with open API architectures. Vancouver Coastal Health's Epic installation resists third-party data ingestion without costly custom interfaces.
- Remote Patient Monitoring:Cloud-connected physiological sensors transmitting to clinical dashboards for chronic disease management. Alberta Health Services is piloting remote physiotherapy monitoring for total joint replacement patients, expanding the addressable market for motion-sensing rehabilitation equipment.
- Wearable Devices:Consumer-grade fitness trackers and medical-grade continuous glucose monitors with varying degrees of clinical validation.
- Healthcare Software:Care coordination platforms and medication management applications subject to Health Canada software-as-medical-device classification.
Telehealth Solutions retains volume leadership, while Remote Patient Monitoring gains share fastest through provincial chronic disease management mandates.
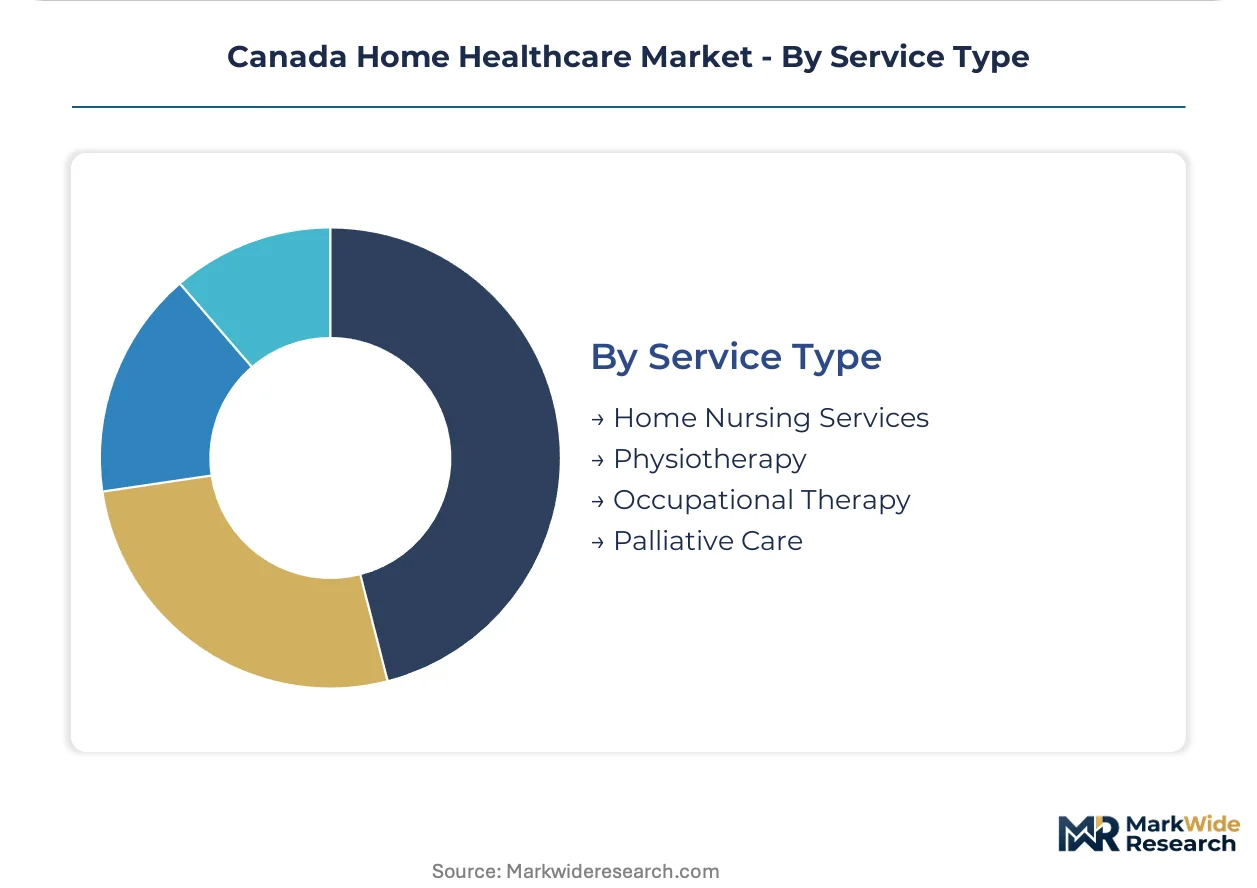
Service Type:
Clinical workforce credentialing variance fragments service delivery across provincial borders, with registered nurses requiring separate registration for cross-jurisdictional practice.
- Home Nursing Services:Skilled clinical care including wound dressing, medication administration, and post-surgical monitoring delivered by registered nurses and licensed practical nurses. Ontario's Ministry of Health is funding acute-level care delivery in residential settings for COPD and heart failure patients, eliminating institutional bed constraints.
- Physiotherapy:Movement rehabilitation and pain management delivered in residential settings, increasingly paired with remote monitoring technology for total joint replacement recovery protocols.
- Occupational Therapy:Home safety assessments and adaptive equipment prescription to maintain independent living capacity.
- Palliative Care:End-of-life symptom management and family support services delivered through interdisciplinary teams.
Home Nursing Services dominates by volume, with Physiotherapy showing the steepest expansion trajectory through rehabilitation-at-home pilot programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario commands deeper home nursing infrastructure than British Columbia, yet both provinces are racing to expand hospital-at-home capacity as aging demographics strain institutional beds.
Ontario
Toronto's hospital-at-home programs for COPD and heart failure patients are eliminating institutional bed constraints across the Greater Toronto Area. The Ministry of Health funds acute-level residential care delivery through Local Health Integration Networks. ParaMed leverages its established personal support worker network to dominate community-based service delivery throughout the province.
British Columbia
Metro Vancouver's integrated community care networks are experiencing concentrated growth in patients over 75 requiring post-surgical wound care at home. The provincial health plan now covers cellular-connected pulse oximeters and blood pressure cuffs for chronic disease management. Vancouver Coastal Health's Epic installation resists third-party home monitoring data ingestion without costly custom interfaces.
Alberta
Alberta Health Services is piloting remote physiotherapy monitoring for total joint replacement patients, expanding demand for motion-sensing rehabilitation equipment. Netcare operates the provincial electronic medical record architecture that fragments interoperability with home monitoring devices. Calgary and Edmonton clusters are redirecting post-acute capacity from hospitals to residential settings.
Quebec
Rural Quebec faces acute personal support worker recruitment gaps as institutional wage competition drains community care talent pools. Registered nurses licensed in Ontario require additional provincial registration to deliver cross-border services, fragmenting staffing for national home care providers. Montreal's aging demographic drives demand for home infusion therapy and skilled nursing services.
Atlantic Canada
New Brunswick and Nova Scotia are experiencing slower home healthcare infrastructure deployment due to dispersed rural populations and limited provincial digital health investment. The region lacks the cellular connectivity density required for remote patient monitoring at scale. Halifax represents the primary concentration of home nursing services, though capacity remains constrained relative to Ontario and British Columbia.
Canada Home Healthcare Market Competitive Environment
United States-based healthcare conglomerates anchor one tier; European medical device specialists and Canadian community care providers hold differentiated positions in equipment and service delivery respectively. The vendor base stratifies across three tiers: diversified health systems with integrated payer-provider models, pure-play medical device manufacturers with Health Canada Class III-IV licensing capabilities, and regional nursing services operators with provincial contract concentration. Strategic archetypes include platform-integrated device vendors, personal support worker network operators, and acute-care-at-home program managers. Competitive moves center on provincial digital health procurement mandates and interoperability certification with legacy hospital information systems.
Within the diversified health systems tier, UnitedHealth Group exemplifies the payer-provider integration model that is displacing standalone service operators in Ontario and British Columbia. Among European medical device specialists, Koninklijke Philips and B. Braun occupy positions defined by connected care platform capabilities and specialized infusion therapy equipment respectively. ParaMed represents the Canadian community care archetype, anchoring personal support worker network density across Ontario and Quebec. These three entities collectively illustrate how market position depends on alignment with provincial procurement frameworks and Health Canada regulatory pathways.
| Leading Market Players |
|---|
| UnitedHealth Group |
| B. Braun |
| ParaMed |
| Koninklijke Philips |
| Abbott Laboratories |
| SE Health |
| Medtronic |
| Fresenius Medical Care |
| Extendicare |
| Others |
Value Chain & Pricing Dynamics
Class III device certification tiers bifurcate the Canadian home healthcare market into premium-priced connected monitoring platforms and commoditized disposable supplies, with Health Canada's 12-18 month licensing timelines concentrating margin capture among established manufacturers while provincial tendering fragmentation forces price competition at the commodity end.
Pricing Analysis
Capacity additions in Ontario's hospital-at-home programs are reshaping price floors for cellular-connected monitoring bundles as Toronto's University Health Network deploys condition-specific kits at departmental purchasing authority. Subscription-based SaaS pricing dominates telehealth platforms integrating with provincial electronic health records, while per-unit transactional models govern wound care consumables. Price differentiation rests on Health Canada Class III certification status and interoperability with Epic and Cerner installations. Pricing pressure intensifies in medical supplies as British Columbia's regional health authorities disaggregate procurement into separate wound care, respiratory, and digital health contracts. Home nursing services show highest price sensitivity where personal support worker wage competition drains talent pools.
Supply Chain Analysis
Workforce availability constraints in Quebec and Atlantic Canada fragment service delivery capacity as institutional wage competition drains community care talent pools. Manufacturing concentration centers on the United States for connected monitoring hardware, Germany for infusion therapy equipment, and China for consumer-grade wearable components. Raw material dependencies include medical-grade polymers for wound dressings, lithium-ion cells for portable oxygen concentrators, and semiconductor chips for cellular connectivity modules. Supply chain risk concentrates in single-source vulnerability for Class III device predicate references approved by Health Canada. Distribution runs through provincial health authority tendering frameworks in Ontario and British Columbia, with direct-to-hospital contracting dominating acute-level home care deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's regulatory modernization for medical devices acts as a demand compounder, with amended Medical Device Regulations accelerating licensing pathways for software-as-medical-device platforms that perform diagnostic analysis on patient-generated data.
For Market Incumbents: To counter interoperability fragmentation across Ontario's eHealth Ontario, British Columbia's HealthLinkBC, and Alberta's Netcare architectures, prioritize open API development for ONE ID patient authentication compatibility. Backward integration into personal support worker training pipelines addresses workforce credentialing variance that fragments cross-provincial staffing. Certification investment in Health Canada priority review designation secures faster market entry for AI-enabled monitoring tools against algorithm-update submission burdens. For New Entrants and Emerging Players: Launch via mobile health unit partnerships in Northern Ontario and remote British Columbia reserves where Indigenous community networks lack home nursing infrastructure. Target Alberta's rehabilitation-at-home pilot programs for total joint replacement patients as the most penetrable entry point for motion-sensing equipment. White space concentrates in telehealth diagnostics paired with community care deployment where cellular connectivity density supports remote patient monitoring at scale. For Investors and Strategic Acquirers: Consolidation pressure builds where provincial digital health mandates favor platforms with pre-certified interoperability against legacy hospital information system resistance. Long-term viability over the next decade hinges on alignment with Ontario's Digital First for Health strategy and British Columbia's devolved procurement autonomy. Acquisition target archetypes include specialized vendors with narrow product depth in wound care or respiratory equipment rather than diversified distributors. Watch for Health Canada software-as-medical-device priority review designations as inflection indicators for algorithm-enabled diagnostic platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III Licensing Investment | Accelerates market entry for ventilators and infusion pumps through predicate device referencing pathways. |
| ONE ID Patient Authentication Integration | Aligns telehealth platforms with Ontario's Digital First for Health procurement mandates. |
| Personal Support Worker Network Expansion | Secures community care delivery capacity in Quebec and Atlantic Canada against institutional wage competition. |
| Epic and Cerner Custom Interface Development | Overcomes legacy hospital information system resistance in Toronto's University Health Network and Vancouver Coastal Health. |
| Condition-Specific Monitoring Kit Deployment | Captures departmental purchasing authority in Ontario's hospital-at-home programs for COPD and cardiac recovery. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital discharge planners, biomedical engineers, GPO contracts managers, and provincial health authority procurement leads with secondary validation against Health Canada medical device licensing databases, hospital procurement records, and provincial digital health strategy documents. Bottom-up equipment deployment estimates and top-down health expenditure allocations were triangulated to anchor market sizing.
Comparable historical periods anchored the forecast window across the analysis window, with segmentation modeled across product type, end user category, technology platform, and service delivery mode. CAGRs were derived from trend extrapolation of provincial health authority budget allocations and equipment procurement cycles. Industry-specific inputs included Health Canada Class II-IV licensing approval timelines and personal support worker workforce supply projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under shifts in provincial digital health interoperability mandates or Health Canada regulatory modernization pace. Forecasts reflect assumptions regarding continued hospital-at-home program expansion and remote patient monitoring reimbursement stability. Material deviation in Health Canada software-as-medical-device priority review volume or personal support worker recruitment gaps warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
US House Calls Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
Home Care Market
Home Healthcare
Global Home Health Care Services Market
Home Healthcare
Smart Pillow Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Smart Mattress Market
Home Healthcare
US Home Infusion Therapy Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Elder Care Products Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Home Care Products Market