
 Elderly Care Apps Market | 2026-2036
Elderly Care Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Elderly Care Apps Market Analytics
Market Context
Buyer concentration among Medicare Advantage plans and large home health networks is hardening, pushing smaller app developers toward niche specialization. Medisafe leverages its medication adherence platform to sustain pharmacy partnerships across North America. CareTap anchors its position in caregiver coordination tools for institutional clients. StoriiCare differentiates through life-story documentation features that appeal to memory care facilities.
Technical Definition and Segments
Elderly care apps comprise software applications designed to monitor health status, manage medication schedules, facilitate emergency communication, and sustain social connectivity for aging populations, typically operating on iOS and Android platforms with cloud-based data synchronization. Remote monitoring and medication management segments lead current revenue generation, while social engagement tools represent the fastest-growing category as isolation-related health risks gain clinical recognition. AI-powered functionality within these applications commands premium positioning, whereas basic mobile applications face margin compression from free alternatives distributed through app stores.
Regulatory Environment
The FDA oversees software-as-medical-device classifications for apps performing diagnostic or therapeutic functions, while HIPAA mandates encryption and access controls for any platform handling protected health information shared with healthcare providers. State-level Medicaid programs increasingly require interoperability certifications before reimbursing remote monitoring services, creating compliance barriers for single-feature vendors. Stakeholders must monitor evolving FDA guidance on AI-enabled predictive analytics, as algorithm transparency requirements could reshape development costs and competitive positioning.
Market Dynamics
Medicare Advantage plans are consolidating vendor relationships around platforms that integrate remote monitoring with care coordination, squeezing standalone medication adherence tools and forcing developers to bundle services or exit.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS reimbursement codes for RPM services under Medicare Advantage are pulling capital toward platforms that capture continuous vital sign data and transmit it to clinical dashboards.
- FDA Pre-Certification Pathway:The FDA's digital health pre-certification program is compressing clearance timelines for software-as-medical-device classifications, accelerating commercialization for predictive analytics modules.
- Social Isolation Recognition:Clinical validation of loneliness as a cardiovascular risk factor is expanding payer willingness to cover social engagement applications alongside traditional medical devices.
Market Restraints
- HIPAA Compliance Architecture:Encryption and access control requirements for protected health information impose fixed development costs that disproportionately burden single-feature vendors with limited engineering resources.
- State Medicaid Fragmentation:Interoperability certification requirements vary across state Medicaid programs, creating compliance complexity for developers seeking multi-state reimbursement eligibility.
- Free Application Substitution:Basic medication reminder and emergency alert functions available through smartphone native features and app store free alternatives are compressing pricing power at the low end of the market.
Strategic Opportunities
- AI-Enabled Predictive Triage:Machine learning algorithms analyzing longitudinal health data patterns are creating white space for platforms that anticipate acute events before symptom presentation.
- Memory Care Facility Penetration:Life-story documentation and cognitive engagement tools represent underpenetrated institutional channels where family purchasing influence remains strong.
- Pharmacy Network Integration:Medication synchronization programs through retail pharmacy chains are opening distribution partnerships that bypass traditional healthcare provider sales cycles.
Industry Challenges
- Geriatric UX Design Talent:Shortage of interface designers with specialized expertise in age-related visual, motor, and cognitive accessibility constraints is slowing product iteration cycles.
- Legacy EHR Integration:Proprietary data formats and API limitations within established electronic health record systems are forcing costly custom integration work for each health system deployment.
- Algorithm Transparency Requirements:Emerging FDA guidance on explainable AI for predictive analytics is extending validation timelines and increasing documentation burdens for machine learning features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elderly Care Apps Market |
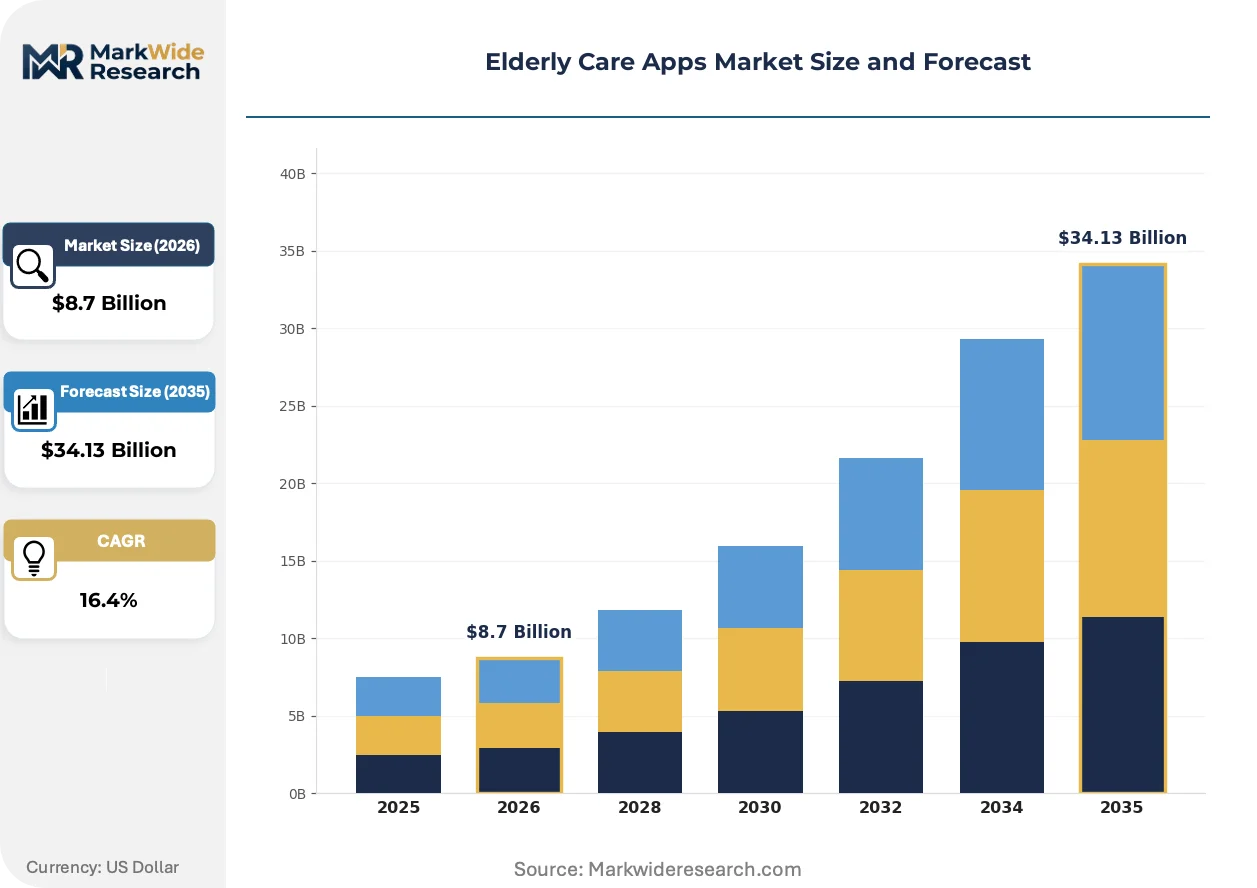
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Monitoring, Medication Management, Social Engagement, Emergency Response Technology: AI, Cloud Computing, IoT, Mobile Applications End User: Caregivers, Family Members, Healthcare Providers, Seniors Distribution Channel: App Stores, Direct Sales, Telehealth Platforms, Online Marketplaces |
| Companies Covered | Cariloop, Lotsa Helping Hands, Caily, CareTap, Medisafe, CareCommunityOS by DosePacker, StoriiCare, Ianacare, Caring Village, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elderly Care Apps Market Evolving Landscape
Voice-first interfaces and ambient sensing technologies are displacing touchscreen-dependent designs as the primary interaction paradigm for aging users with declining manual dexterity.
Passive radar and millimeter-wave sensing is expanding into fall detection and activity monitoring without wearable dependency. Home health agencies in the United States are piloting these systems to reduce caregiver dispatch costs for wellness checks. The technology is expanding into premium positioning for independent living facilities seeking to differentiate safety infrastructure.
The EU AI Act's risk classification framework for biometric and health-related artificial intelligence is reshaping development roadmaps for European market entry. Developers must now document training data provenance and algorithmic decision pathways before CE marking. Memory care applications employing emotion recognition are most affected, with several vendors delaying EU launches pending legal clarity on high-risk system obligations.
Family member purchasing influence is displacing direct-to-senior marketing as the dominant acquisition channel. Adult children researching solutions for aging parents are driving platform selection through employer-sponsored caregiver benefit programs and insurance add-ons. This shift is most visible in the United States, where employer benefits administrators are curating app portfolios for working caregivers.
Elderly Care Apps Market Segmentation
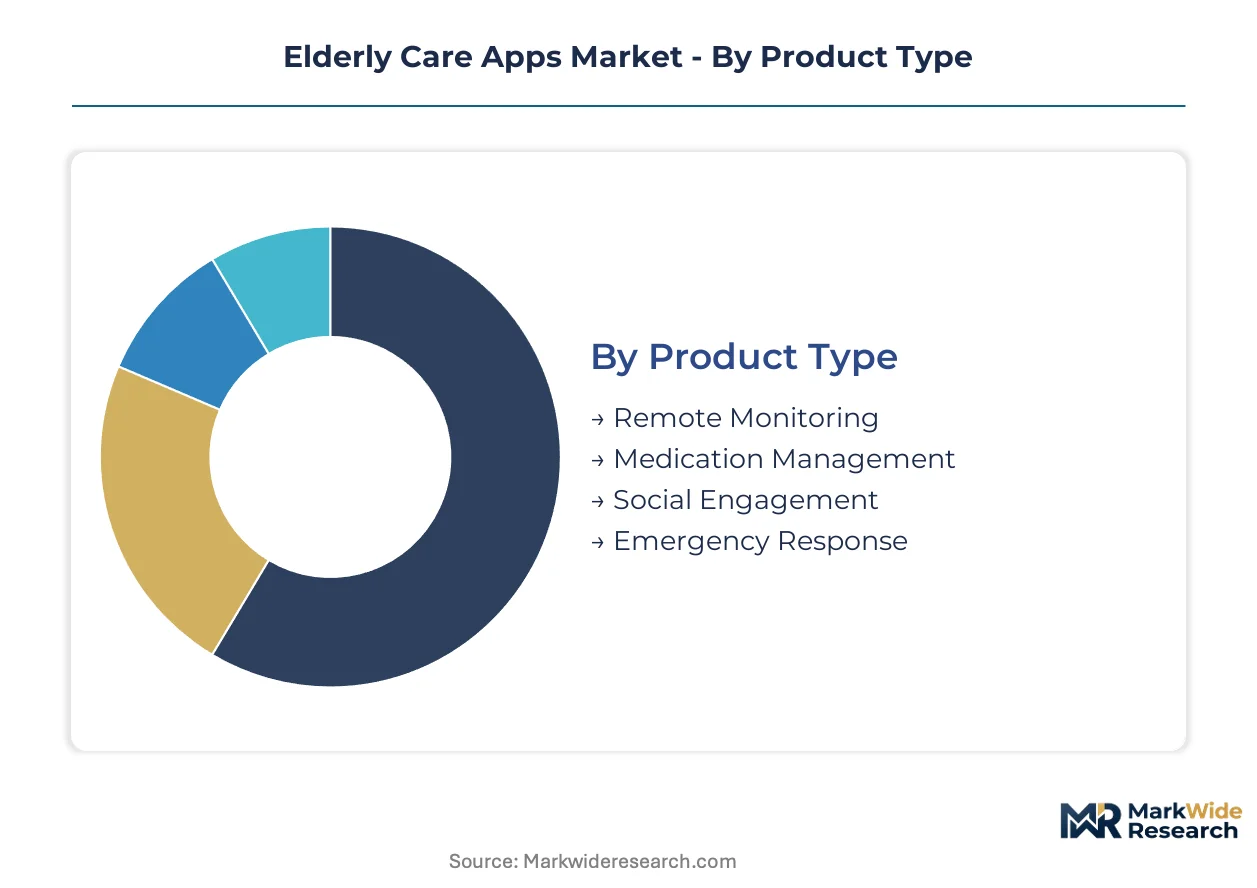
Segmentation in elderly care apps reveals how purchasing authority fragments across family members, institutional buyers, and seniors themselves. Each dimension—product functionality, underlying technology, end-user profile, and distribution pathway—creates distinct margin structures and competitive barriers.
Product Type:
Medicare Advantage procurement priorities are concentrating vendor selection around platforms that bundle multiple functions rather than standalone tools.
- Remote Monitoring:Continuous vital sign capture through connected devices feeds clinical dashboards for proactive intervention. United States home health agencies are expanding deployment of these platforms to reduce emergency department utilization among high-risk enrollees.
- Medication Management:Adherence tracking with pharmacy synchronization addresses polypharmacy complexity in aging populations. Retail pharmacy chains are integrating these tools into medication therapy management programs to improve star ratings.
- Social Engagement:Cognitive stimulation and video communication tools target isolation-related health risks. Clinical validation of loneliness as a cardiovascular factor is expanding reimbursement eligibility for these applications.
- Emergency Response:Fall detection and rapid alert systems provide safety net functionality for independent living. Premium positioning persists for voice-activated and ambient sensing variants that eliminate wearable dependency.
Remote monitoring leads on scale; social engagement leads on momentum.
Technology:
Development cost structures vary sharply by technical foundation, with AI-enabled features commanding premium pricing and extended validation timelines.
- AI:Predictive analytics modules anticipate acute events through pattern recognition in longitudinal health data. FDA pre-certification pathways are accelerating clearance timelines for machine learning features in diagnostic applications.
- Cloud Computing:Scalable infrastructure enables real-time data synchronization across distributed caregiver networks. HIPAA-compliant architecture requirements impose fixed engineering costs that favor platforms with enterprise-scale resources.
- IoT:Sensor networks and connected devices extend monitoring beyond smartphone boundaries. Passive radar and millimeter-wave sensing is displacing wearable-dependent designs for fall detection in premium installations.
- Mobile Applications:Native iOS and Android deployment remains the primary distribution mechanism for consumer-facing tools. Free alternatives distributed through app stores are compressing pricing power at the basic functionality tier.
Mobile applications dominate volume; AI commands margin expansion.
End User:
Family member purchasing influence is displacing direct-to-senior marketing as the dominant acquisition channel across all product categories.
- Caregivers:Professional and informal caregivers require coordination tools for task scheduling and status updates. Home healthcare agencies are procuring platforms that integrate with electronic visit verification systems.
- Family Members:Adult children researching solutions for aging parents drive platform selection through employer-sponsored benefit programs. United States employers are curating app portfolios as caregiver support benefits.
- Healthcare Providers:Physicians and care teams prioritize interoperability with existing electronic health record systems. Legacy EHR proprietary data formats are forcing costly custom integration work for each deployment.
- Seniors:Direct end-user adoption depends on interface designs addressing age-related visual, motor, and cognitive constraints. Geriatric UX design talent scarcity is slowing product iteration cycles for this segment.
Family members drive acquisition velocity; healthcare providers determine retention economics.
Distribution Channel:
Channel selection shapes customer acquisition costs and lifetime value through varying degrees of targeting precision and trust transfer.
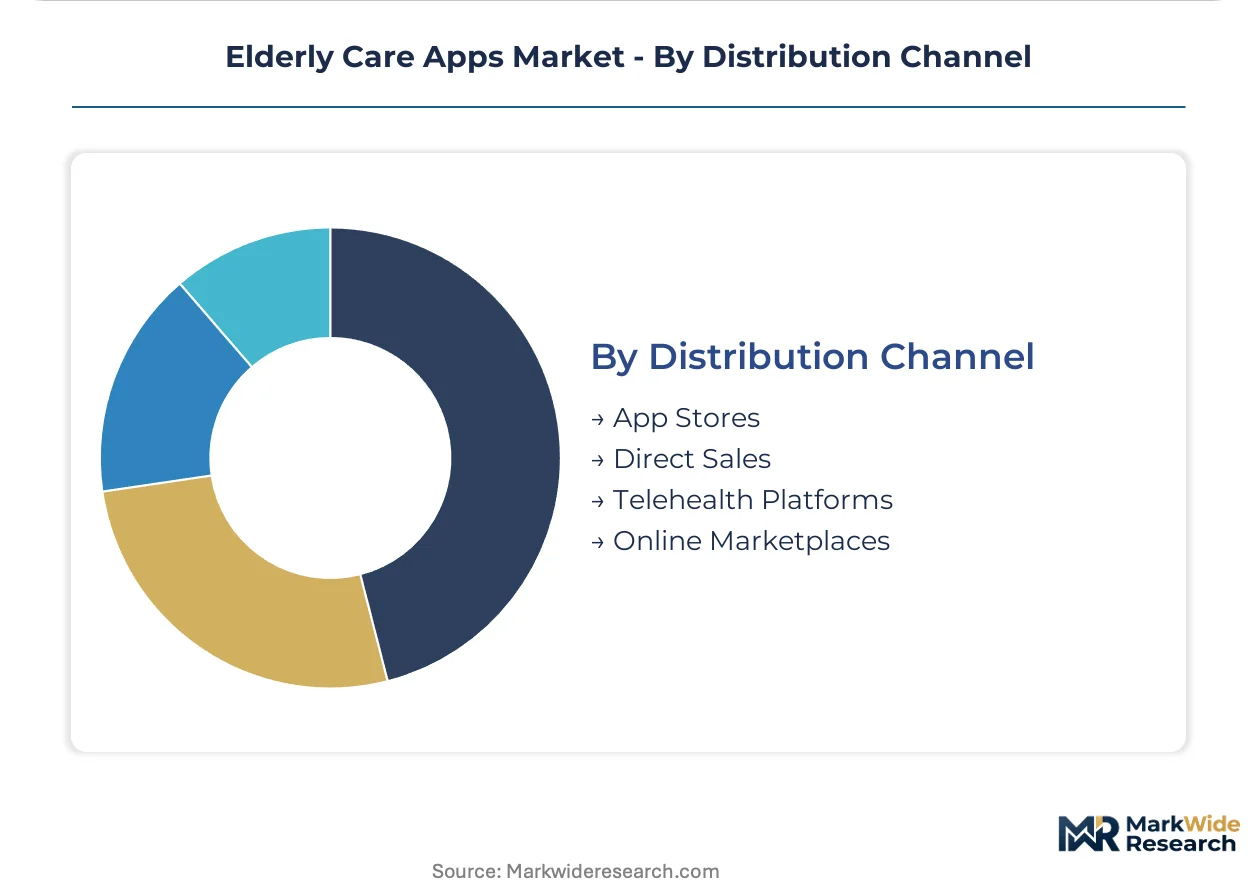
- App Stores:Apple App Store and Google Play provide broad reach with minimal distribution infrastructure. Discovery challenges and commission structures limit monetization for standalone developers without brand recognition.
- Direct Sales:Enterprise contracts with health systems and home health agencies bypass consumer marketing spend. Sales cycles extend due to procurement committee requirements and security review protocols.
- Telehealth Platforms:Integration with virtual care delivery creates embedded distribution for monitoring and engagement tools. Medicare Advantage plans are consolidating vendor relationships around platforms with telehealth connectivity.
- Online Marketplaces:Specialty aging and caregiving marketplaces offer curated discovery for family member purchasers. These channels capture higher intent traffic but require revenue-sharing arrangements with platform operators.
App Stores capture volume; telehealth platforms capture value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates Medicare Advantage procurement power while Germany's statutory health insurance funds pilot digital care applications through DiGA fast-track approvals. Japan's super-aged society drives demand for ambient monitoring systems in dense urban corridors.
United States
CMS reimbursement codes for remote patient monitoring pull capital toward platforms capturing continuous vital sign data. HIPAA mandates encryption and access controls for any platform handling protected health information shared with healthcare providers. Boston's health tech cluster hosts multiple startups integrating predictive analytics with electronic health record systems.
Germany
Statutory health insurance funds expand DiGA prescriptions for digital care applications targeting medication adherence and emergency response. The BfArM digital health applications directory requires clinical evidence submissions before permanent reimbursement listing. Berlin's startup ecosystem concentrates developers pursuing CE marking under MDR for software-as-medical-device classifications.
Japan
METI subsidies for smart home eldercare installations accelerate passive radar and millimeter-wave sensing deployment. The PMDA streamlines SaMD reviews for fall detection algorithms through pre-submission consultation pathways. Tokyo's Kanto region hosts integrated care system pilots linking municipal governments with sensor network operators.
United Kingdom
NHS England's digital-first primary care strategy embeds elderly care apps into social prescribing pathways for isolation-related health risks. MHRA guidance on AI-enabled medical devices requires algorithm transparency documentation for predictive triage features. London's health innovation districts attract venture capital toward platforms integrating with NHS App infrastructure.
Canada
Health Canada expedites medical device licenses for remote monitoring platforms through the Digital Health Review Pathway. Provincial health authorities in Ontario and British Columbia pilot reimbursement models for caregiver coordination tools. Toronto's MaRS Discovery District clusters startups pursuing interoperability certifications with provincial electronic health record systems.
Elderly Care Apps Market Competitive Landscape
United States developers anchor the platform tier; European specialists hold regulatory compliance advantages through MDR and DiGA familiarity. The vendor base stratifies across enterprise-scale integrators serving Medicare Advantage plans, pharmacy-aligned medication management platforms, and niche institutional specialists targeting memory care facilities. Dominant competitive moves include telehealth platform embedding and pharmacy network distribution partnerships.
Within the medication management archetype, Medisafe exemplifies pharmacy partnership sustainability across North American markets. CareTap occupies a position in caregiver coordination tools for institutional procurement committees. StoriiCare represents differentiation through life-story documentation features appealing to memory care facility operators seeking family engagement solutions.
| Leading Market Players |
|---|
| Cariloop |
| Lotsa Helping Hands |
| Caily |
| CareTap |
| Medisafe |
| CareCommunityOS by DosePacker |
| StoriiCare |
| Ianacare |
| Caring Village |
| Others |
Value Network & Pricing Analysis
Medicare Advantage procurement consolidation around bundled platforms is forcing single-feature developers to absorb integration costs or exit, compressing margins at the basic functionality tier while AI-enabled modules sustain premium positioning through FDA pre-certification pathways.
Pricing Analysis
Capacity additions in cloud infrastructure are reshaping price floors for SaaS-tiered subscription models across the elderly care apps landscape. Pricing stratifies across premium, standard, and economy tiers, with AI-powered predictive analytics commanding 40-60% premiums over basic medication reminder tools due to FDA clearance requirements and clinical validation burdens. Cost compression in the mobile-native tier is intensifying because smartphone native features and free app store alternatives eliminate willingness-to-pay for standalone alert functions. Family member purchasers through employer benefit programs exhibit lowest price sensitivity, while direct-to-senior acquisition channels face acute substitution pressure from no-cost alternatives.
Supply Chain Analysis
Freight costs for connected device hardware exert limited pressure on software-centric margins, though sensor component sourcing from Taiwan, South Korea, and China introduces tariff exposure for fall detection and ambient monitoring installations. Cloud computing infrastructure draws from hyperscaler data centers concentrated in the United States, Germany, and Japan, with HIPAA and GDPR compliance architecture imposing fixed engineering costs regardless of scale. Single-source vulnerability in millimeter-wave sensing chipsets threatens premium positioning for wearable-independent monitoring systems. Distribution runs through telehealth platform embedding and pharmacy network partnerships, bypassing traditional healthcare provider sales cycles for fastest commercialization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The elderly care apps market functions as a regulatory compounder where FDA digital health pre-certification and CMS reimbursement code expansions create accelerating returns for compliant platforms.
For Market Incumbents: Anticipate algorithm transparency requirements from emerging FDA guidance on explainable AI by pre-positioning documentation infrastructure and validation protocols for predictive triage features. Defensive consolidation through pharmacy network integration and telehealth platform embedding protects against standalone medication adherence tool displacement as Medicare Advantage plans consolidate vendor relationships around bundled offerings. For New Entrants and Emerging Players: Memory care facility operators represent an underserved buyer archetype with strong family purchasing influence and limited incumbent penetration for life-story documentation and cognitive engagement tools. White space targets include EU market entry leveraging DiGA fast-track familiarity and ambient sensing deployment for Japan's super-aged urban corridors. A direct sales model targeting institutional procurement committees bypasses consumer marketing spend and app store discovery challenges. For Investors and Strategic Acquirers: Asymmetric upside sits with platforms combining AI-enabled predictive analytics with established pharmacy distribution partnerships, as reimbursement tailwinds compound over extended validation timelines. Long-term viability centers on enterprise-scale integrators serving Medicare Advantage plans and niche institutional specialists with memory care differentiation. The signal to watch is FDA pre-certification pathway expansion for software-as-medical-device classifications indicating regulatory clarity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Accelerates clearance timelines for predictive analytics modules in diagnostic applications. |
| Pharmacy Network Integration | Opens distribution partnerships through retail medication therapy management programs. |
| Memory Care Facility Penetration | Captures family purchasing influence in underpenetrated institutional channels. |
| Telehealth Platform Embedding | Creates embedded distribution through Medicare Advantage vendor consolidation. |
| EU DiGA Fast-Track Entry | Secures permanent reimbursement listing through BfArM clinical evidence submissions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Medicare Advantage plan administrators, home health agency procurement directors, FDA regulatory consultants, geriatric UX design specialists, and memory care facility operators with secondary validation against CMS reimbursement databases, FDA 510(k) clearance filings, hospital procurement records, and pharmacy partnership disclosures. Bottom-up platform deployment tracking and top-down payer spend analysis provided triangulation across the analysis window.
Historical reference periods anchored the forecast framework to pre-pandemic baselines and CMS reimbursement expansion milestones, with projections extending across the modeling period through multi-dimensional segmentation by product functionality, underlying technology, end-user profile, and distribution pathway. CAGRs were derived from fitted growth curves incorporating FDA clearance velocity, Medicare Advantage enrollment shifts, and pharmacy network partnership formation rates as primary demand drivers.
Underlying measurement precision varies by segment; remote monitoring and medication management carry tighter precision than social engagement tools where clinical validation remains emergent. Forecasts reflect assumptions regarding CMS reimbursement code stability and FDA guidance continuity, with model refresh warranted upon material change in Medicare Advantage plan procurement consolidation patterns or algorithm transparency regulatory requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Home Care Service Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
Smart Pillow Market
Home Healthcare
Home Care Market
Home Healthcare
House Call Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Outpatient Home Therapy Market
Home Healthcare
Virtual Companion Care Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Europe Home Care Market
Home Healthcare
Global Home Health Care Services Market