
 US Home Healthcare Market | 2026-2036
US Home Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
US Home Healthcare Market Intelligence
Buyer concentration among Medicare Advantage plans and large hospital networks is realigning procurement power toward entities capable of managing total cost of care across episodes. Amedisys, Inc. leverages its joint venture structure with health systems to secure preferred-provider status in key metropolitan markets. CenterWell Home Health anchors its expansion strategy around senior-focused primary care integration, while Optum, Inc. competes through data analytics platforms that stratify patient risk for targeted intervention.
US home healthcare encompasses skilled medical and supportive services delivered in residential settings, encompassing wound care management, infusion therapy, physical rehabilitation, and palliative support through licensed nursing staff and certified home health aides. The sector operates under strict clinical protocols including OASIS documentation standards and 60-day certification periods that govern reimbursement eligibility. Home nursing services occupy the largest revenue pool within service type segmentation, reflecting sustained Medicare fee-for-service volumes and post-surgical recovery protocols. Telehealth solutions within technology segmentation are capturing disproportionate investment flow as remote patient monitoring achieves parity reimbursement under CMS guidelines. Hospice care represents a mature margin segment where per-diem rate structures and length-of-stay management determine profitability.
FDA oversight of connected diagnostic devices and CMS conditions of participation establish the dual regulatory perimeter shaping market access and service reimbursement for home healthcare providers. State-level licensure requirements through departments of health create additional compliance layers that vary across jurisdictions, with some states mandating specific staffing ratios and clinical supervisor qualifications. OSHA guidelines for home-based worker safety and HIPAA privacy protections for remote data transmission complete the regulatory architecture governing operational standards. Stakeholders must monitor evolving CMS demonstration models that test direct contracting with home health agencies bypassing traditional institutional intermediaries.
Market Dynamics
CMS value-based payment models are restructuring provider economics, forcing home health agencies to absorb episode-of-care risk while investing in remote patient monitoring infrastructure to qualify for quality bonuses and avoid readmission penalties.
Growth Catalysts
- Medicare Advantage penetration:MA plans now cover over half of eligible Medicare beneficiaries in key metropolitan markets, directing volume toward contracted home health networks with proven cost-control records.
- Remote patient monitoring parity:CMS reimbursement codes for RPM devices and virtual check-ins now match in-person visit rates, accelerating capital deployment into connected diagnostic platforms.
- Southeast nursing shortage:Hospital capacity constraints across Florida, Georgia, and the Carolinas are pushing acute care discharges into home settings faster than national averages.
Market Restraints
- Labor cost inflation:Licensed practical nurses and home health aides command wage premiums 15-25% above pre-pandemic baselines in competitive markets, compressing per-visit margins.
- CMS pre-claim review expansion:The Prior Authorization of Home Health Services demonstration in Illinois, Ohio, and Texas adds administrative burden and payment delay risk for providers operating across state lines.
- Hospital-owned substitute networks:Health systems are building captive home health capabilities to retain post-acute revenue, reducing referral flow to independent agencies.
Strategic Opportunities
- Hospital-at-home waivers:CMS Acute Hospital Care at Home program allows reimbursement for hospital-level services delivered residentially, opening new revenue pools for agencies with ICU-capable staffing.
- Palliative care upstream integration:Early palliative consultation embedded in oncology and cardiology practices creates referral pathways before hospice eligibility, extending relationship duration.
- Rural health clinic partnerships:Federally qualified health centers in underserved counties lack home health capacity, presenting first-mover advantages for agencies willing to operate at lower visit density.
Industry Challenges
- OASIS-E documentation burden:The expanded assessment instrument requires 30+ additional data elements per admission, stretching clinical supervisor bandwidth and increasing audit exposure.
- EHR interoperability gaps:Home health platforms often lack bidirectional data exchange with hospital EMRs, forcing manual reconciliation of medication lists and care plans at care transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Home Healthcare Market |
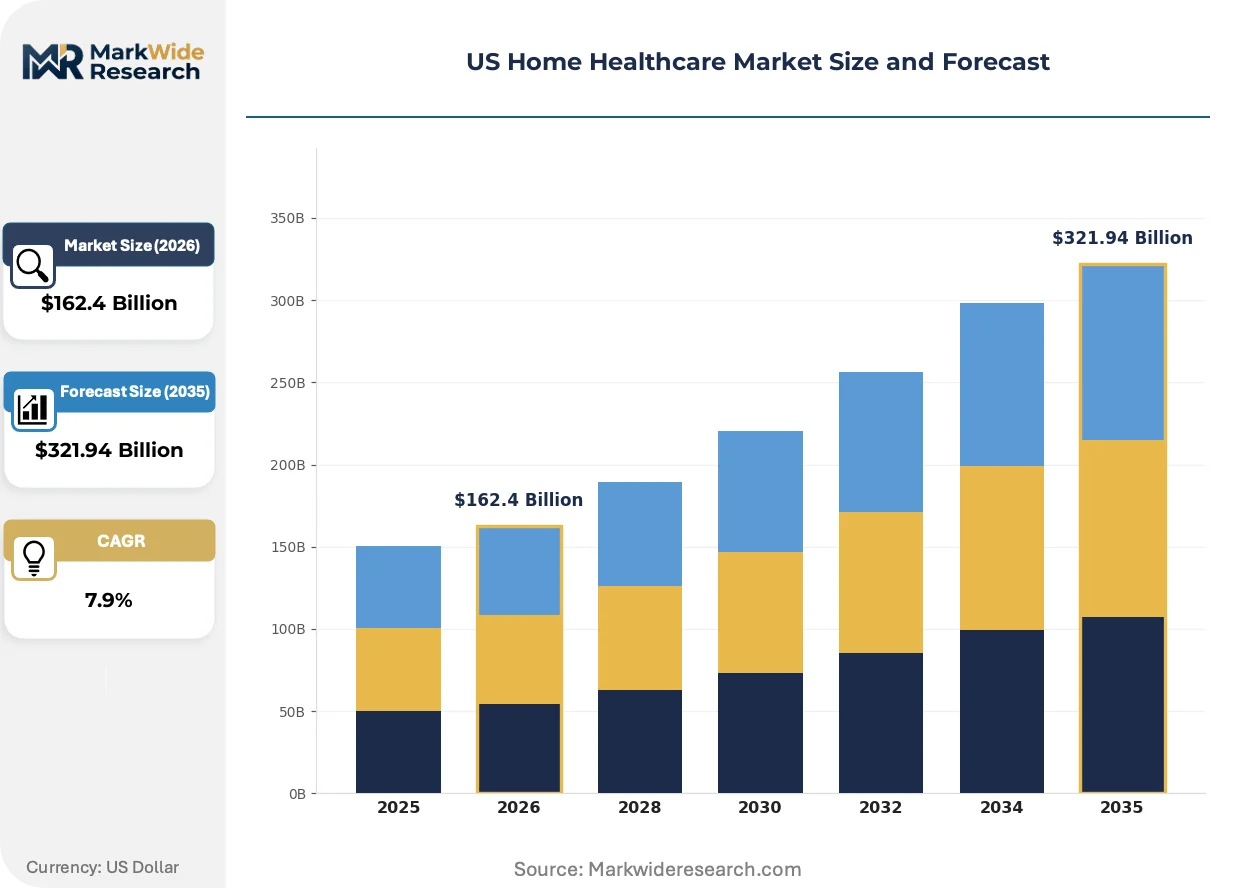
| Market Size in 2026 | $162.4 Billion |
| Market Size in 2035 | $321.94 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Nursing, Rehabilitation Services, Hospice Care, Personal Care Technology: Telehealth Solutions, Remote Monitoring Devices, Home Diagnostic Tools, Health Apps End User: Patients, Caregivers, Hospitals, Insurance Providers Delivery Mode: On-Demand Services, Scheduled Visits, Digital Consultations, Hybrid Care |
| Companies Covered | Amedisys, Inc., CenterWell Home Health, Optum, Inc., Enhabit Home Health & Hospice, LHC Group, Inc., BAYADA Home Health Care, Addus HomeCare Corporation, AccentCare, Inc., McKesson Medical-Surgical, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Home Healthcare Market Strategic Shifts & Innovations
Connected diagnostics and AI-enabled risk stratification are compressing the traditional 60-day episode model into continuous monitoring relationships, while regulatory pressure on readmissions accelerates technology adoption curves.
Artificial intelligence algorithms processing continuous glucose monitor and pulse oximetry feeds are rewriting how agencies identify deterioration before emergency department utilization. Medicare Advantage plans in competitive markets now require participating home health networks to deploy FDA-cleared predictive analytics platforms as a condition of preferred status. This capability compression is collapsing the distinction between skilled nursing facility and home-based monitoring intensity.
CMS conditions of participation now mandate real-time electronic visit verification through GPS-stamped mobile applications, eliminating paper timesheet fraud but imposing capital requirements on smaller regional agencies. The rule affects agencies serving dual-eligible populations most acutely, where state Medicaid agencies are layering additional EVV specifications atop federal requirements. Compliance has triggered consolidation among sub-500-visit agencies unable to absorb platform licensing costs.
Hospital procurement departments are unbundling post-acute contracting from bundled payment arrangements, negotiating direct home health rates outside Medicare Advantage intermediaries. This disintermediation concentrates volume with agencies willing to accept downside risk on 30-day readmission guarantees. The shift is most visible in Texas and Florida markets where health system concentration enables direct contracting leverage.
US Home Healthcare Market Segmentation
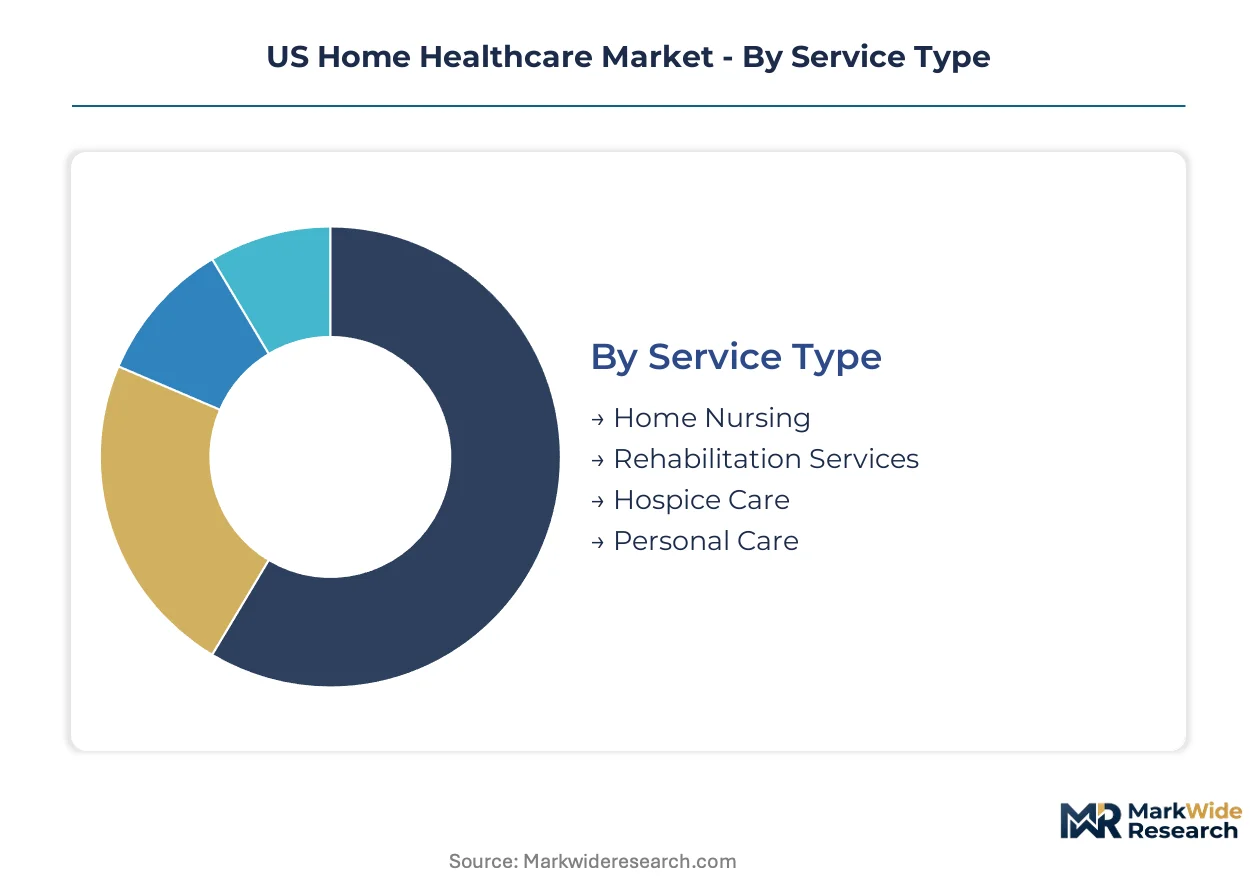
Service configuration in US home healthcare determines reimbursement pathways, staffing ratios, and technology infrastructure requirements. Understanding segment boundaries clarifies where capital deployment yields margin protection versus commodity exposure.
Service Type:
Volume concentrates in high-frequency, lower-acuity encounters while premium margins accrue to specialized clinical interventions requiring licensed credentialing.
- Home Nursing:Skilled services including wound care, medication administration, and post-surgical monitoring delivered by registered nurses and licensed practical nurses under physician orders. Demand clusters in Florida, Texas, and Georgia metropolitan corridors where hospital discharge velocity exceeds nursing home capacity expansion. Medicare fee-for-service reimbursement sustains visit density despite wage inflation pressures.
- Rehabilitation Services:Physical, occupational, and speech therapy protocols delivered residentially following orthopedic surgery, stroke, or cardiac events. Southeast health systems are embedding these services into joint venture structures to capture post-acute episodes. CMS functional improvement measures determine quality bonus eligibility.
- Hospice Care:End-of-life palliative services with per-diem rate structures and Medicare certification requirements.
- Personal Care:Non-medical assistance with activities of daily living including bathing, meal preparation, and mobility support.
Today's leader: Home Nursing. Tomorrow's challenger: Rehabilitation Services.
Technology:
Application intensity separates monitoring infrastructure from consumer-facing interfaces, with reimbursement parity driving capital allocation toward clinically validated platforms.
- Telehealth Solutions:Synchronous virtual visits connecting patients with physicians, nurse practitioners, and specialists through HIPAA-compliant video platforms. Rural health clinic partnerships in the Southeast are expanding fastest as federally qualified health centers seek to extend specialist reach without facility investment. CMS virtual check-in codes now match in-person evaluation rates.
- Remote Monitoring Devices:Continuous data capture through pulse oximeters, blood pressure cuffs, glucometers, and weight scales transmitting to clinical dashboards. Medicare Advantage plans in competitive markets mandate FDA-cleared predictive analytics integration as a network participation condition. Hospital-at-home waivers require ICU-capable monitoring thresholds.
- Home Diagnostic Tools:Point-of-care testing equipment for INR, HbA1c, and infectious disease screening deployed by visiting nurses.
- Health Apps:Patient-facing medication adherence, symptom tracking, and care plan engagement applications with variable clinical integration.
Telehealth Solutions anchor current procurement budgets. Remote Monitoring Devices are climbing the fastest as risk-bearing contracts proliferate.
End User:
Customer type dictates pricing power, with institutional purchasers extracting performance guarantees unavailable to individual consumers.
- Patients:Medicare beneficiaries and dual-eligibles selecting agencies through physician referral or plan network directories. Direct-to-consumer payment remains minimal outside concierge arrangements.
- Caregivers:Family members coordinating services and accessing training resources through agency portals.
- Hospitals:Health systems directing post-acute volume through owned, joint venture, or contracted agency relationships. Texas and Florida markets exhibit accelerating disintermediation as procurement departments negotiate direct rates outside Medicare Advantage intermediaries.
- Insurance Providers:Medicare Advantage plans and commercial payers establishing narrow networks based on cost-control records and quality metrics.
Insurance Providers command current procurement leverage. Hospitals are gaining share fastest through captive network development.
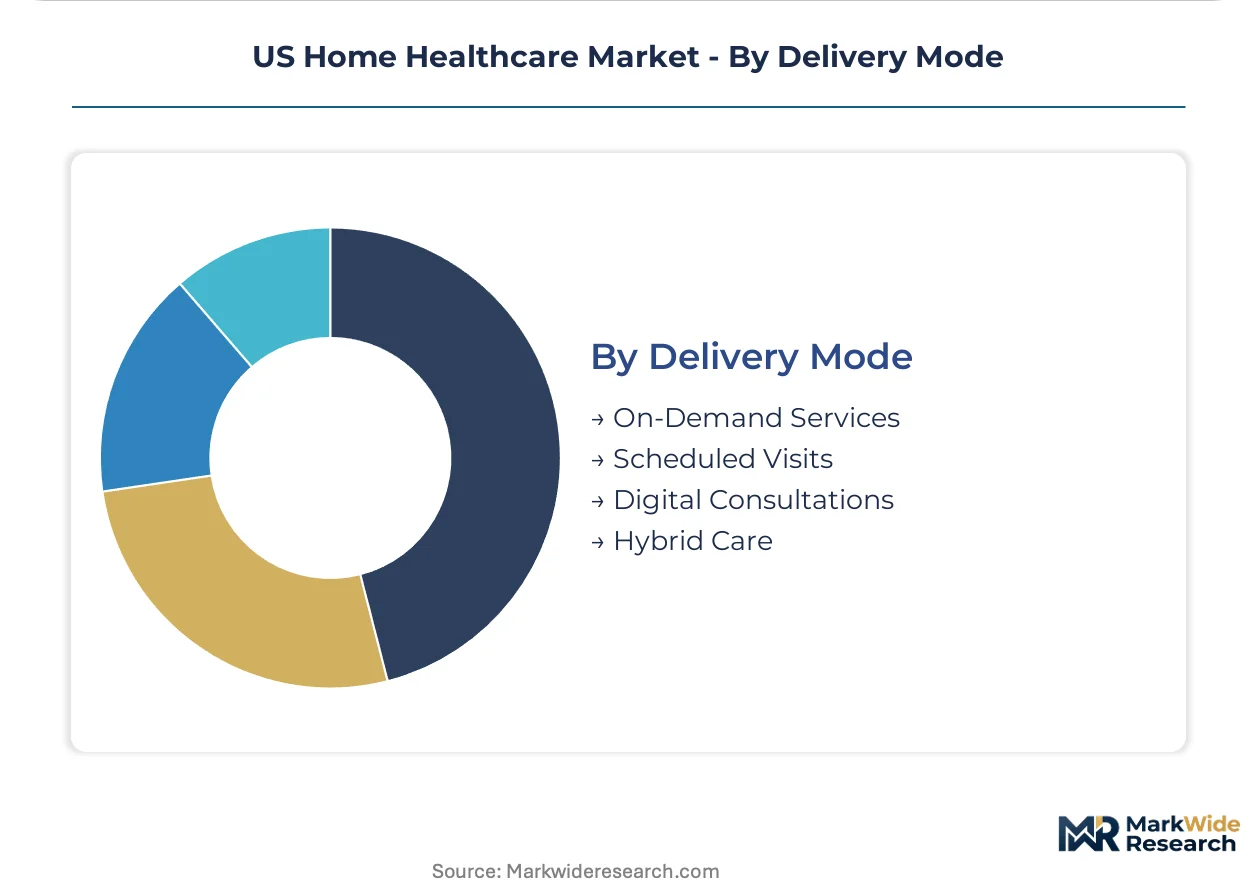
Delivery Mode:
Scheduling flexibility separates acute response capabilities from planned chronic disease management, with hybrid models capturing margin across both.
- On-Demand Services:Urgent response deployments for medication reactions, equipment failures, or acute symptom escalation requiring same-day nursing assessment.
- Scheduled Visits:Recurring appointments for wound care, therapy protocols, and chronic disease monitoring following 60-day certification periods.
- Digital Consultations:Asynchronous messaging and video encounters for medication titration and symptom triage without physical presence.
- Hybrid Care:Integrated protocols combining in-person nursing, remote monitoring, and virtual physician oversight. Southeast agencies are deploying this most aggressively to qualify for hospital-at-home waivers and CMS demonstration models testing direct contracting.
Scheduled Visits dominate current visit volume. Hybrid Care is expanding most quickly as episode-of-care risk shifts to providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's home healthcare infrastructure absorbs patient volumes at rates exceeding national benchmarks, while Texas health systems build captive networks that redirect referrals away from independent agencies.
Southeast
Hospital discharge velocity in Florida, Georgia, and the Carolinas exceeds nursing home capacity expansion, accelerating home-based recovery protocols. CMS Hospital-at-Home waivers enable ICU-capable staffing models in residential settings. Atlanta and Charlotte metropolitan corridors concentrate joint venture activity between health systems and home health agencies.
Texas
Health system concentration in Dallas-Fort Worth and Houston enables direct contracting leverage outside Medicare Advantage intermediaries. CMS Prior Authorization of Home Health Services demonstration adds administrative burden for cross-state providers. The Texas Medical Center corridor anchors disintermediation trends as procurement departments negotiate standalone post-acute rates.
Midwest
Illinois, Ohio, and Michigan face CMS pre-claim review expansion, delaying payment cycles for agencies operating across state lines. State Medicaid agencies layer electronic visit verification specifications atop federal requirements. Chicago and Detroit metropolitan areas exhibit consolidation among sub-500-visit agencies unable to absorb platform licensing costs.
Northeast
Greater Boston and New York Metro markets command wage premiums for licensed practical nurses and home health aides. HIPAA privacy protections for remote data transmission impose additional compliance layers on multi-state operators. The Northeast Corridor concentrates Medicare Advantage plan penetration, directing volume toward contracted networks with proven cost-control records.
Pacific
California's aging demographics and nursing shortages mirror Southeast intensity, though reimbursement rate compression limits margin expansion. OSHA guidelines for home-based worker safety drive capital allocation toward GPS-stamped mobile applications for electronic visit verification. Los Angeles and San Francisco Bay Area markets favor hybrid care models combining in-person nursing with remote monitoring infrastructure.
US Home Healthcare Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the US home healthcare market, creating tiered competitive dynamics based on capital access and risk-bearing capacity. National platforms with health system joint ventures secure preferred-provider status in metropolitan markets, while regional independents defend visit density through specialized clinical protocols. Two strategic archetypes dominate: scale-driven networks absorbing episode-of-care risk, and technology-enabled specialists deploying predictive analytics for Medicare Advantage contracting. Consolidation accelerates as electronic visit verification mandates trigger acquisition of sub-500-visit agencies, while hospital-owned substitute networks reduce external referral flow.
Among publicly traded platforms, Amedisys, Inc. and LHC Group, Inc. occupy positions within the scale-driven tier, representing archetypes capable of negotiating direct rates with health system procurement departments. CenterWell Home Health anchors the senior-focused primary care integration vector, exemplifying how payer-owned assets redirect post-acute volume toward captive capabilities. These three entities collectively illustrate competitive positioning around joint venture structures, risk-based contracting, and technology infrastructure deployment.
| Leading Market Players |
|---|
| Amedisys, Inc. |
| CenterWell Home Health |
| Optum, Inc. |
| Enhabit Home Health & Hospice |
| LHC Group, Inc. |
| BAYADA Home Health Care |
| Addus HomeCare Corporation |
| AccentCare, Inc. |
| McKesson Medical-Surgical, Inc. |
| Others |
Cost & Logistics Intelligence
Licensed practical nurse concentration across Florida, Georgia, and Texas metros drives labor-cost differentials that widen pricing-tier spreads between premium joint-venture networks and independent regional agencies. CMS reimbursement parity for remote patient monitoring compresses per-visit margins while creating tier separation based on technology infrastructure deployment.
Pricing Analysis
Capacity additions in Texas health system captive networks are reshaping price floors for post-acute services as procurement departments negotiate direct rates outside Medicare Advantage intermediaries. Three-tier pricing structure across premium joint-venture, standard contracted, and economy independent agency levels separates providers by ICU-capable staffing and predictive analytics certification. Price differentiation hinges on FDA-cleared remote monitoring integration and 30-day readmission guarantee acceptance. Cost compression in the economy tier is intensifying because electronic visit verification mandates trigger consolidation among sub-500-visit agencies unable to absorb platform licensing costs. Medicare Advantage plans exhibit lowest price sensitivity due to total-cost-of-care risk absorption, while dual-eligible populations through state Medicaid agencies face highest sensitivity to per-visit copay structures.
Supply Chain Analysis
Domestic-content mandates through CMS Buy American provisions for connected diagnostic devices are reshaping sourcing patterns for remote patient monitoring hardware. Supply concentrates in domestic FDA-registered device manufacturers, Mexican maquiladora assembly operations, and Taiwanese sensor component suppliers. Raw material dependencies include semiconductor chips for pulse oximetry devices, lithium-ion cells for portable infusion pumps, and medical-grade polymers for wound care supplies. Single-source vulnerability runs through FDA-cleared predictive analytics software platforms where Medicare Advantage network participation mandates create vendor lock-in. Distribution runs through health system procurement departments, GPO contracts, and direct-to-agency device leasing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
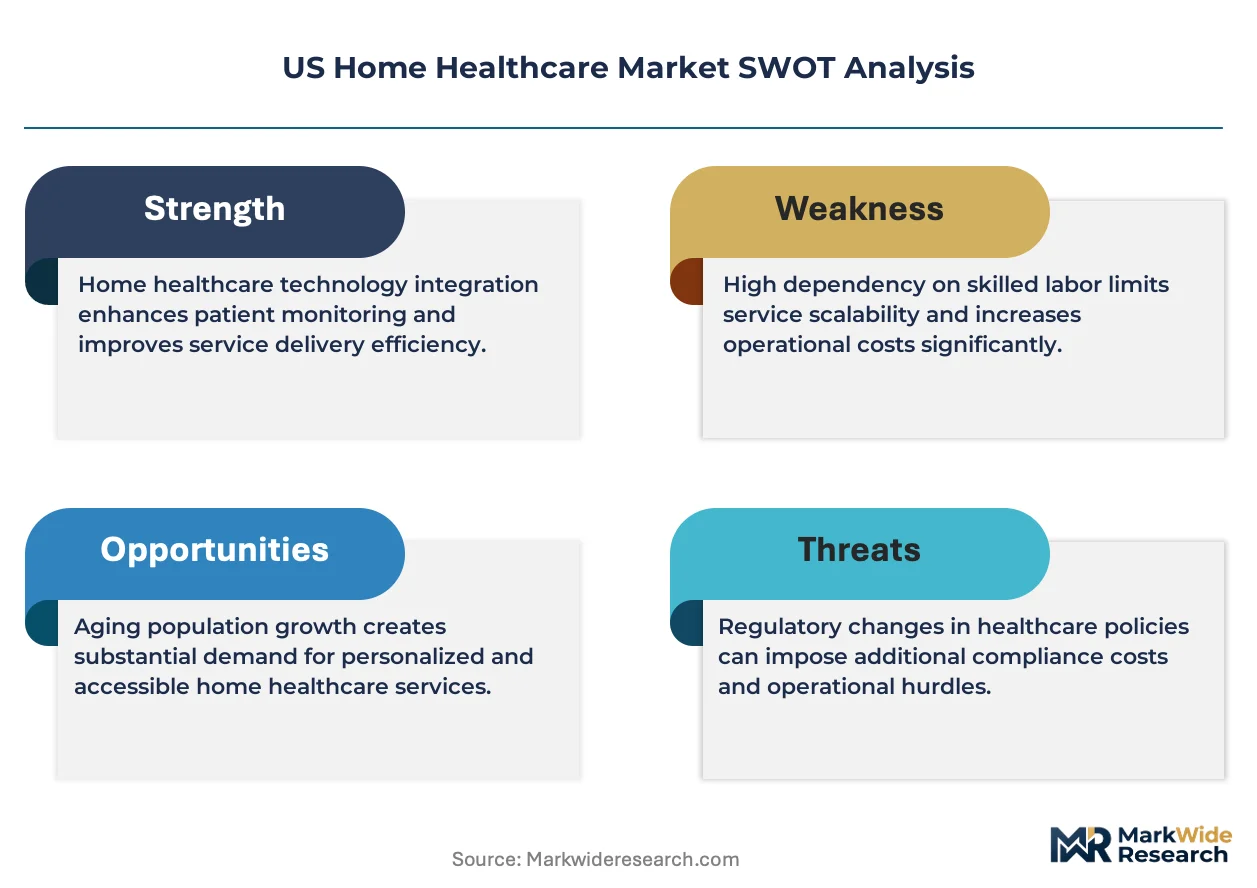
The US home healthcare market represents a late-cycle quality story where Medicare Advantage penetration shifts demand toward agencies with proven cost-control records and ICU-capable staffing credentials. Premium specifications now center on FDA-cleared predictive analytics integration as a network participation condition.
For Market Incumbents: Deepen joint venture structures with health systems to secure preferred-provider status in metropolitan corridors where hospital-owned substitute networks threaten referral flow. Invest in backward integration into remote monitoring device fleets to control per-patient technology costs and qualify for CMS quality bonuses. Electronic visit verification mandates favor scaled platforms with capital absorption capacity. For New Entrants and Emerging Players: AI-enabled risk stratification platforms offer a technology-first wedge into Medicare Advantage contracting where incumbent agencies lack predictive analytics certification. Target rural health clinic partnerships in Southeast counties where federally qualified health centers lack home health capacity and visit density requirements deter scaled competitors. Lead with hybrid care protocols combining remote monitoring with scheduled nursing to qualify for hospital-at-home waivers. For Investors and Strategic Acquirers: Health systems building captive post-acute capabilities are the most active acquirer in this space, driving valuation premiums for agencies with joint venture track records and direct contracting relationships. Long-term viability favors scaled platforms with episode-of-care risk absorption capacity and technology infrastructure deployment. Watch CMS demonstration models testing direct contracting with home health agencies as the inflection signal for disintermediation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Joint Venture | Secures preferred-provider status in metropolitan markets where procurement departments concentrate volume. |
| Remote Monitoring Platform Deployment | Qualifies agencies for Medicare Advantage network participation under FDA-cleared predictive analytics mandates. |
| ICU-Capable Staffing Investment | Enables CMS Hospital-at-Home waiver participation and premium reimbursement for acute-level residential care. |
| Electronic Visit Verification Compliance | Meets CMS conditions of participation and state Medicaid layering requirements for dual-eligible populations. |
| Direct Contracting Capability Buildout | Positions agencies for CMS demonstration models bypassing traditional Medicare Advantage intermediaries. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with home health agency executives, CMS policy specialists, Medicare Advantage plan contracting officers, and hospital procurement directors with secondary validation against CMS Medicare cost reports, FDA 510(k) device clearance databases, state licensure records, and GPO contract repositories. Bottom-up visit volume modeling triangulated against top-down reimbursement flow analysis.
Segment-weighting approaches applied service type, technology deployment, end-user concentration, and delivery mode as core dimensions across the projection horizon. CAGRs derived from visit volume trajectories, reimbursement rate indexing, and wage inflation modeling. Forecast inputs incorporated CMS demonstration model expansion scenarios and Medicare Advantage penetration curves by metropolitan statistical area.
The model holds under current CMS reimbursement parity for remote patient monitoring and steady Medicare Advantage growth; deviation in hospital-at-home waiver expansion velocity or pre-claim review demonstration rollout would shift volume projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Adult Day Care Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Home Care Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Global Home Healthcare Software Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
House Call Market
Home Healthcare
US Home Infusion Therapy Market
Home Healthcare
Global Home Health Hub Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Home Healthcare Market