
 Connected Healthcare Market | 2026-2036
Connected Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Healthcare Market Analysis
Hospital procurement of connected care platforms is consolidating around large integrated delivery networks that demand end-to-end interoperability. GE HealthCare Technologies Inc. leverages its imaging informatics backbone to anchor enterprise contracts with these consolidated buyers. Siemens Healthineers competes through its cloud-native teamplay digital health platform, while Medtronic Plc dominates cardiac remote monitoring with its implanted device-to-cloud data pipelines.
Connected healthcare encompasses the integration of digital technologies, networked medical devices, and data analytics platforms to enable real-time patient monitoring, clinical decision support, and care coordination across distributed settings. Systems typically employ FDA-cleared Class II medical devices transmitting encrypted biometric data through HIPAA-compliant cloud architectures to electronic health record systems. Wearable devices and remote monitoring together capture the largest share of current product revenue, though AI-powered analytics represents the fastest-expanding margin pool as health systems seek predictive risk stratification. Telehealth solutions have matured into a baseline infrastructure layer, while health apps remain fragmented across consumer and clinical-grade quality tiers.
The FDA regulates connected devices through its digital health pre-certification program and evolving software-as-a-medical-device framework, while HIPAA governs data exchange protocols between platforms and covered entities. The Centers for Medicare & Medicaid Services shapes adoption velocity through reimbursement policies for remote patient monitoring and chronic care management codes. Stakeholders must monitor how FDA artificial intelligence guidance and state-level telehealth parity laws converge to determine which platform architectures achieve sustainable reimbursement.
Market Dynamics
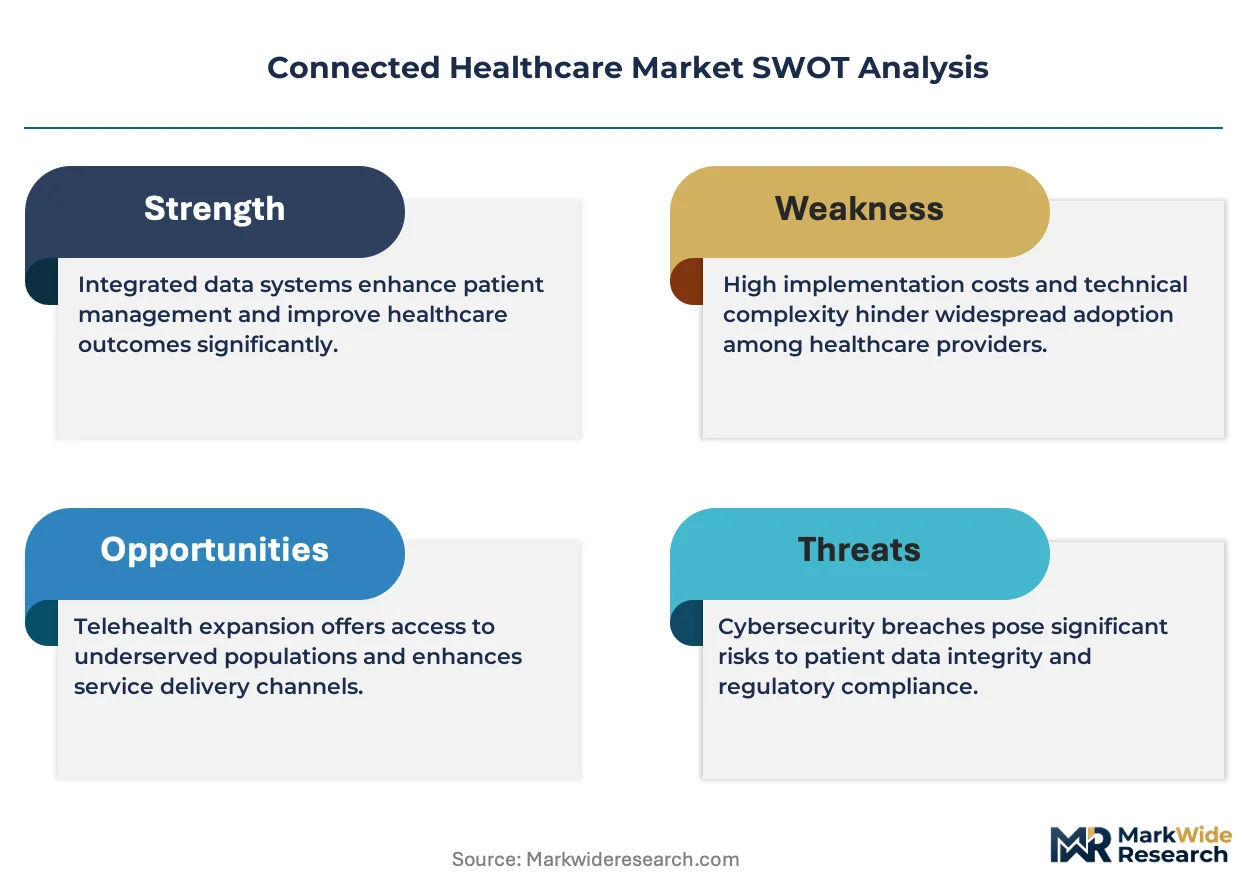
Hospital procurement consolidation around integrated delivery networks is forcing platform vendors to architect end-to-end interoperability rather than point solutions, compressing standalone device margins while expanding enterprise contract values.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage of remote therapeutic monitoring codes accelerates hospital deployment of chronic disease management platforms across cardiology and respiratory specialties.
- AI-powered risk stratification:Machine learning algorithms processing continuous biometric streams enable predictive interventions that reduce emergency department utilization in value-based care contracts.
- Cloud-native architecture migration:Health systems replacing on-premise infrastructure with HIPAA-compliant cloud deployments lower capital barriers to multi-site platform rollouts.
Market Restraints
- Interoperability fragmentation:Proprietary data formats from legacy medical device manufacturers create integration costs that stall multi-vendor platform deployments.
- Cybersecurity compliance burden:FDA guidance on post-market cybersecurity management demands continuous vulnerability monitoring that strains mid-cap device firms.
- Reimbursement code complexity:Variable state-level telehealth parity laws create billing uncertainty that slows rural health system adoption of remote monitoring programs.
Strategic Opportunities
- Post-acute care integration:Skilled nursing facilities and home health agencies represent underpenetrated endpoints for continuous monitoring platform extensions.
- FDA pre-certification pathway:The agency's streamlined software-as-a-medical-device framework offers faster clearance timelines for AI-enabled diagnostic algorithms.
- Behavioral health convergence:Digital therapeutics for mental health conditions are integrating with physiological monitoring to capture comorbidity reimbursement bundles.
Industry Challenges
- Clinical workflow integration:Alert fatigue from high-sensitivity monitoring algorithms requires health systems to redesign nursing protocols and escalation pathways.
- Data governance complexity:Multi-state patient populations trigger fragmented compliance obligations across state privacy laws beyond HIPAA baseline requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Healthcare Market |
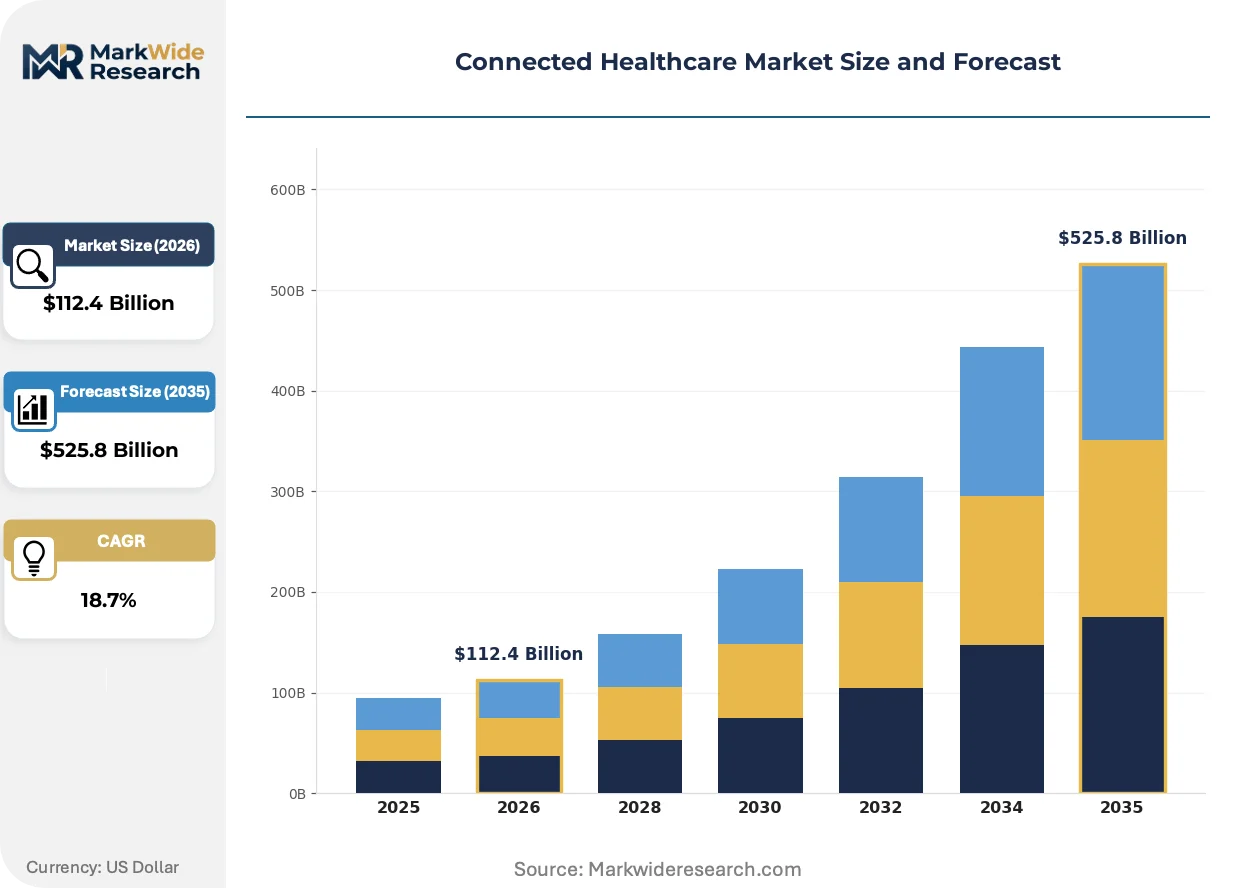
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $525.8 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Telehealth Solutions, Remote Monitoring, Health Apps Technology: AI-Powered Analytics, IoT Sensors, Cloud Computing, Blockchain End User: Patients, Healthcare Providers, Insurance Companies, Research Institutes Application: Chronic Disease Management, Preventive Care, Rehabilitation, Mental Health |
| Companies Covered | Koninklijke Philips NV, GE HealthCare Technologies Inc., Medtronic Plc, Cerner Corporation, International Business Machines Corporation, Apple Inc., Omron Corporation, Siemens Healthineers, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Healthcare Market Emerging Trajectories
Connected healthcare platforms are pivoting from data transmission infrastructure toward predictive intervention engines, embedding AI at the edge of clinical workflows rather than downstream analytics layers.
Continuous glucose monitoring technology is converging with insulin dosing algorithms to form closed-loop artificial pancreas systems. Endocrinology practices and pediatric diabetes centers are adopting these integrated platforms faster than traditional device replacement cycles. This convergence is compressing the distinction between diagnostic monitoring and therapeutic delivery in regulatory classification frameworks.
The FDA's evolving software pre-certification program is reshaping product development cycles for algorithm-based devices. Manufacturers must now demonstrate real-world performance monitoring capabilities prior to market entry rather than retrospective validation. Cardiac rhythm management and sleep apnea device categories are experiencing the most significant clearance pathway revisions under this framework.
Hospital purchasing committees are consolidating vendor relationships around platforms that bundle hardware, cloud infrastructure, and clinical decision support into single contracts. Standalone device manufacturers face displacement unless they embed their sensors within broader enterprise architectures. This pattern is most pronounced in United States health systems participating in Medicare accountable care organization contracts.
Connected Healthcare Market Segmentation
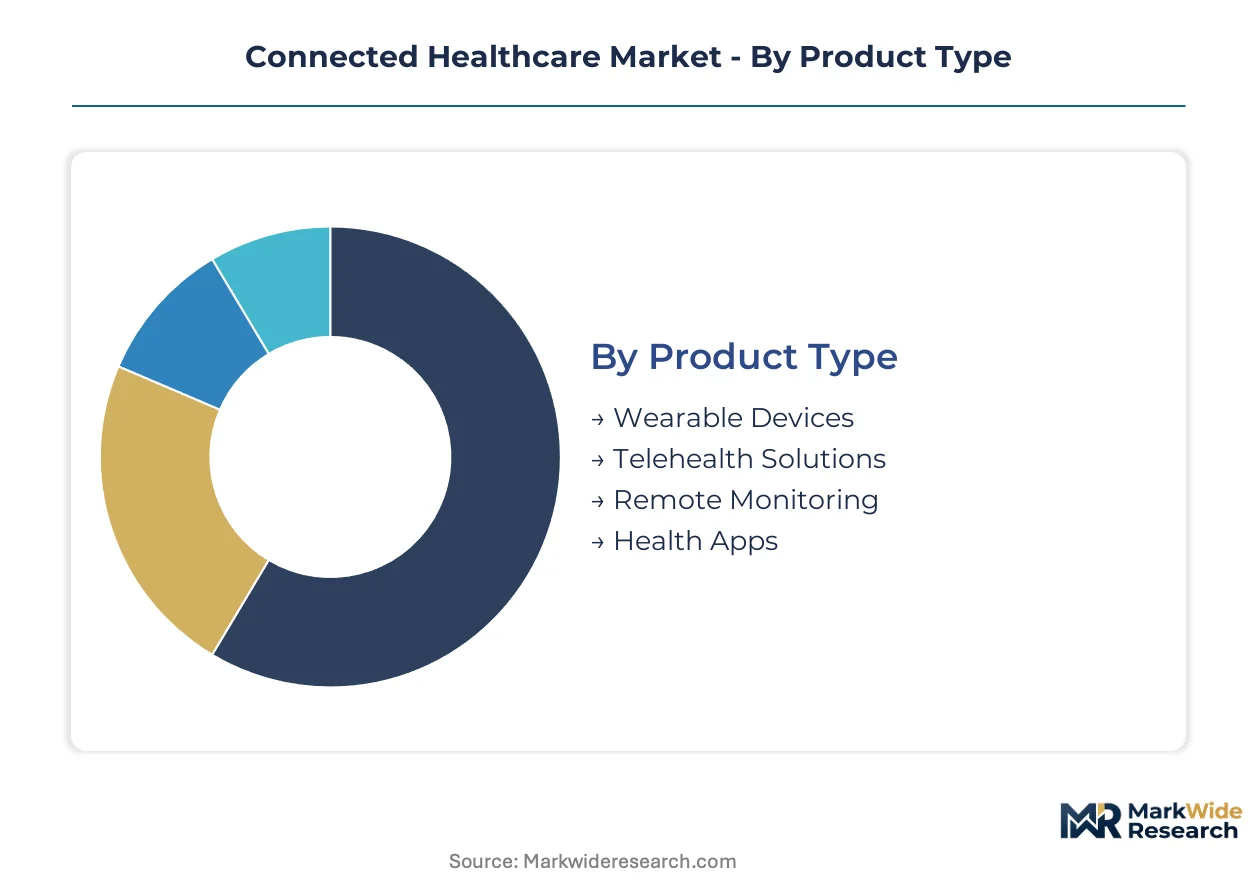
Connected healthcare procurement decisions split across hardware specifications, software capabilities, and reimbursement compatibility. Buyers prioritize segments that integrate with existing electronic health record infrastructure while satisfying FDA clearance requirements.
Product Type:
Hospital procurement committees evaluate capital expenditure against recurring revenue potential when selecting device categories.
- Wearable Devices:Continuous biometric sensors transmit encrypted physiological data through Bluetooth Low Energy protocols to HIPAA-compliant cloud gateways. United States cardiology practices deploy these for post-discharge arrhythmia surveillance under expanded Medicare reimbursement codes.
- Remote Monitoring:FDA-cleared Class II devices capture vital signs from distributed patient locations, enabling clinical intervention without facility admission. Integrated delivery networks in Texas and California consolidate vendor contracts around platforms bundling hardware with clinical decision support.
- Telehealth Solutions:Video consultation infrastructure matured into baseline connectivity layers during recent regulatory flexibility periods.
- Health Apps:Consumer-grade and clinical-grade quality tiers remain fragmented without standardized validation frameworks.
Wearable Devices leads on scale; Remote Monitoring leads on momentum.
Technology:
Platform architecture choices determine interoperability costs and cybersecurity compliance burdens across deployment scales.
- AI-Powered Analytics:Machine learning algorithms process streaming biometric data to generate predictive risk scores for clinical teams. Health systems in Medicare accountable care organization contracts deploy these tools to reduce emergency department utilization.
- Cloud Computing:HIPAA-compliant infrastructure replaces on-premise data centers, lowering capital barriers for multi-site health system rollouts. Migration velocity concentrates among United States regional hospital networks consolidating electronic health record environments.
- IoT Sensors:Embedded connectivity modules in legacy medical devices enable retrofit data transmission without full replacement.
- Blockchain:Distributed ledger applications address patient consent management and data provenance verification in multi-party care coordination.
Cloud Computing anchors current deployment volume; AI-Powered Analytics commands the steepest expansion trajectory.
End User:
Reimbursement pathway clarity determines adoption velocity across stakeholder categories with divergent budget cycles.
- Healthcare Providers:Hospital systems and physician practices purchase platforms through capital equipment budgets or subscription operating expenditures. Procurement committees prioritize FDA-cleared devices with demonstrated interoperability through HL7 FHIR standards.
- Insurance Companies:Payers negotiate value-based contracts requiring remote monitoring data streams to validate outcome metrics and adjust premium calculations.
- Patients:Direct-to-consumer purchases concentrate on wellness applications without clinical validation requirements.
- Research Institutes:Academic medical centers acquire platforms for clinical trial endpoints and real-world evidence generation.
Healthcare Providers dominates procurement volume; Insurance Companies drives fastest contract innovation.
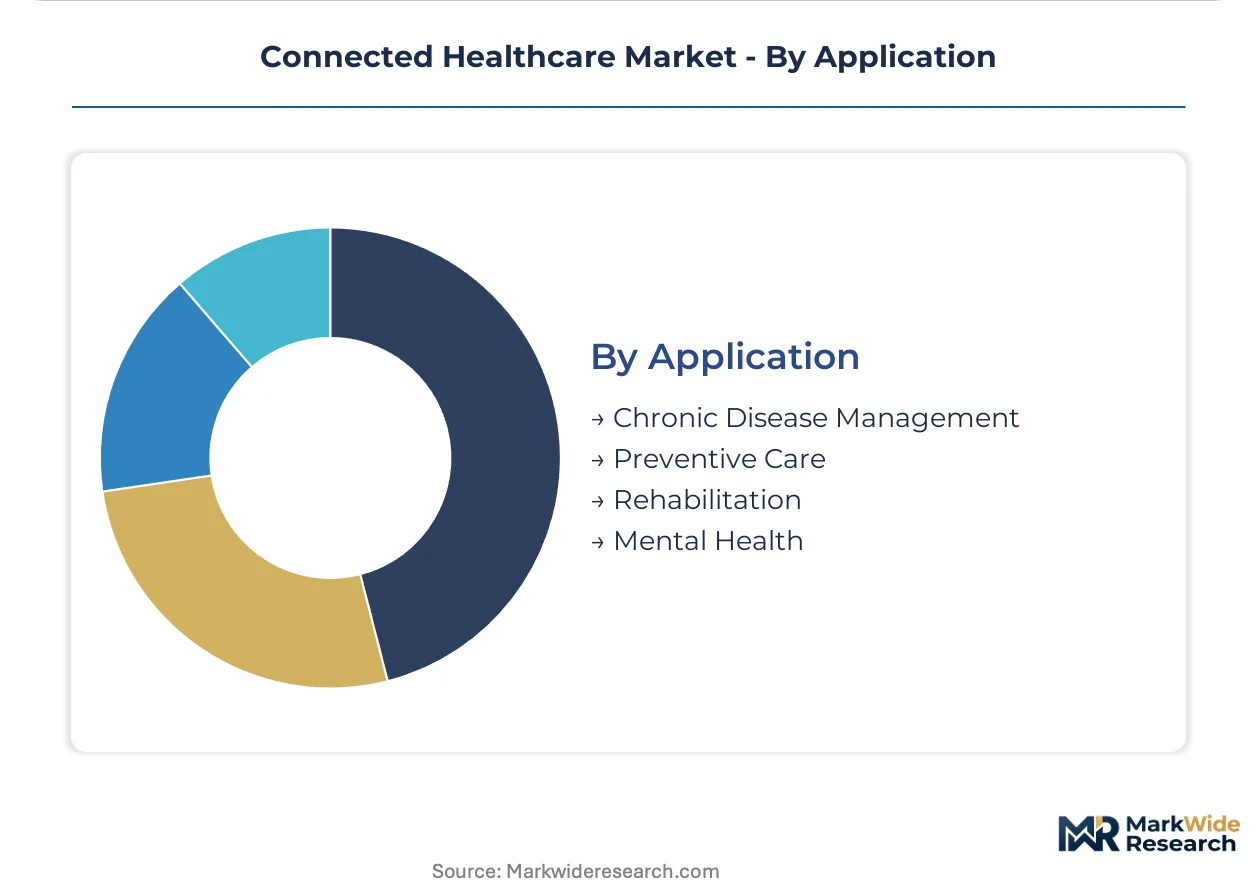
Application:
Clinical specialty reimbursement codes shape platform deployment priorities across therapeutic areas.
- Chronic Disease Management:Cardiology and endocrinology platforms capture continuous glucose and cardiac rhythm data for algorithmic intervention. Medicare remote therapeutic monitoring codes specifically cover these deployments.
- Mental Health:Digital therapeutics integrate physiological monitoring with cognitive behavioral therapy protocols to capture comorbidity reimbursement bundles. Behavioral health convergence accelerates in United States integrated delivery networks.
- Preventive Care:Population health programs deploy risk stratification tools to identify high-utilization patients before acute episodes.
- Rehabilitation:Post-acute care facilities adopt motion sensing platforms to track recovery metrics outside traditional therapy sessions.
Chronic Disease Management leads on reimbursement maturity; Mental Health gains share fastest through regulatory pathway evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys remote patient monitoring platforms at scale under Medicare reimbursement codes, while Germany's hospital digitization programs lag in connected care adoption despite robust medical device manufacturing.
United States
Hospital procurement committees at integrated delivery networks consolidate vendor contracts around end-to-end interoperability. CMS coverage of remote therapeutic monitoring codes accelerates deployment across cardiology and respiratory specialties. The Mayo Clinic and Cleveland Clinic anchor enterprise platform rollouts in Minnesota and Ohio.
Germany
Siemens Healthineers and other domestic manufacturers push cloud-native teamplay platforms into hospital digitization budgets. The EU Medical Device Regulation (MDR) and national reimbursement fragmentation slow adoption velocity versus North American benchmarks. Berlin-Brandenburg health systems pilot AI-powered analytics for chronic disease management.
Japan
Aging demographics drive demand for home-based monitoring solutions beyond traditional facility-centric care models. The PMDA's software-as-a-medical-device framework enables faster clearance for AI-enabled diagnostic algorithms. Tokyo and Osaka metropolitan hospitals lead cloud migration for multi-site platform deployments.
China
Domestic manufacturers retrofit legacy medical devices with IoT connectivity modules for hospital network integration. NMPA guidance on AI-enabled devices shapes product development cycles for algorithm-based diagnostics. The Yangtze River Delta and Pearl River Delta concentrate connected health platform development.
United Kingdom
NHS long-term plan targets shift hospital-at-home services through remote monitoring infrastructure. GDPR compliance obligations and post-Brexit regulatory divergence create data governance complexity for multi-national platform vendors. London and Greater Manchester integrated care systems pilot predictive risk stratification tools.
Connected Healthcare Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across connected healthcare platform categories. The market structure exhibits tiered consolidation around imaging informatics backbones, cardiac device-to-cloud pipelines, and cloud-native digital health platforms. Three archetypes dominate: diversified medical technology conglomerates with enterprise imaging footprints, pure-play remote monitoring specialists with FDA-cleared device portfolios, and technology platform vendors with cloud infrastructure scale. Competitive moves concentrate on strategic partnerships for interoperability certification and portfolio diversification into AI-powered analytics layers.
Among diversified medical technology conglomerates, Koninklijke Philips NV and GE HealthCare Technologies Inc. occupy positions anchoring enterprise contracts with consolidated hospital buyers. Medtronic Plc exemplifies the cardiac-focused pure-play archetype through its implanted device-to-cloud data pipeline dominance. Siemens Healthineers sits within the cloud-native platform tier competing on teamplay digital health infrastructure.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| GE HealthCare Technologies Inc. |
| Medtronic Plc |
| Cerner Corporation |
| International Business Machines Corporation |
| Apple Inc. |
| Omron Corporation |
| Siemens Healthineers |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Semiconductor price indices for biometric sensors cascade through connected healthcare supply chains, compressing margins on wearable hardware while expanding SaaS pricing power for cloud-native platform vendors serving integrated delivery networks.
Pricing Analysis
Capacity additions in China's IoT sensor foundries are reshaping price floors for Bluetooth-enabled biometric devices, forcing mid-tier manufacturers toward subscription revenue models. Three-tier pricing structure across enterprise, mid-market, and point-solution tiers separates FDA-cleared platforms with HL7 FHIR interoperability from uncertified wellness devices. Pricing pressure stems from hospital procurement consolidation demanding bundled hardware-software contracts rather than standalone device purchases. Regional hospital networks exhibit highest price sensitivity; Medicare ACO-affiliated systems demonstrate lowest sensitivity due to outcome-based contract structures.
Supply Chain Analysis
Regional distribution centers in Memphis and Rotterdam anchor hub-and-spoke fulfillment patterns for FDA-cleared Class II devices requiring temperature-controlled logistics. Manufacturing concentrates in China, Malaysia, and Mexico for sensor assembly, with final device integration in the United States and Germany to satisfy FDA and MDR regulatory proximity requirements. Supply chains draw from specialized semiconductor foundries, medical-grade polymers, and lithium-ion cell suppliers. Single-source vulnerability concentrates in advanced AI chip fabrication for edge-computing diagnostic algorithms. Distribution runs through GPO-contracted channels and direct-to-hospital logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected healthcare functions as a geographic-arbitrage play where FDA pre-certification timelines in the United States lag Japan's PMDA software-as-a-medical-device pathway by 8-12 months, creating first-mover advantages for algorithm developers domiciling initial submissions in Tokyo.
For Market Incumbents: Lock in enterprise imaging informatics contracts with consolidated integrated delivery networks before pure-play remote monitoring specialists achieve interoperability certification. Defend against cloud-native platform vendors by embedding legacy device fleets with IoT retrofit modules rather than replacement cycles. Prioritize backward integration into AI chip design to reduce dependency on external edge-computing suppliers. For New Entrants and Emerging Players: Capture skilled nursing facility endpoints for continuous monitoring platform extensions where incumbent presence remains underdeveloped. Behavioral health convergence with physiological monitoring offers the most penetrable reimbursement bundle under evolving Medicare remote therapeutic monitoring codes. Pursue hospital-at-home pilot partnerships with NHS integrated care systems in the United Kingdom to establish real-world performance datasets for FDA pre-certification. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap device manufacturers lack cloud infrastructure scale to satisfy hospital procurement committee demands for end-to-end platform bundles. Long-term viability favors targets with demonstrated FDA 510(k) clearance velocity and established HL7 FHIR interoperability certification. Monitor CMS reimbursement code expansion for mental health digital therapeutics as inflection indicator for behavioral health platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Pre-Certification Pathway | Streamlines software-as-a-medical-device clearance timelines for AI-enabled cardiac algorithms. |
| Hospital System Partnership | Secures multi-year enterprise contracts with integrated delivery networks demanding interoperability. |
| Software Companion Development | Transforms standalone hardware revenue into recurring SaaS margins through clinical decision support. |
| Reimbursement Strategy | Aligns platform architecture with CMS remote therapeutic monitoring codes for chronic disease management. |
| CE Marking Pathway | Unlocks EU MDR-compliant market access for cloud-native platforms targeting German hospital digitization budgets. |
Methodological Framework
Multiple input streams — hospital procurement database analysis, CMS reimbursement code tracking, and FDA 510(k) filing review — were reconciled with primary interviews across clinicians, biomedical engineers, GPO contracts managers, and health system CTOs. Secondary validation incorporated hospital capital expenditure records, medical device trade customs data, and regulatory submission databases. Bottom-up device shipment estimates and top-down health system IT spending analysis were triangulated to anchor market sizing.
Data-stream reconciliation across product type, technology architecture, end-user budget cycle, and clinical application specialty shaped the analytical framework throughout the forecast period. CAGRs were derived from segment-level adoption curves weighted by reimbursement pathway maturity and interoperability deployment velocity. Forecast inputs incorporated Medicare ACO penetration rates and cloud migration timelines for regional hospital networks.
Underlying measurement precision varies by segment; wearable device volumes and remote monitoring platform deployments carry tighter precision than emerging health app categories lacking standardized validation frameworks. Forecasts reflect documented assumptions regarding CMS code expansion and FDA guidance evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Pregnancy Management Software Market
Digital Health Solutions
Women Health Applications Market
Digital Health Solutions
Connected Health and Wellness Solutions Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Middle East and Africa Heart Failure Software Market
Digital Health Solutions
Lifestyle Diseases Apps Market
Digital Health Solutions
Asia-Pacific Heart Failure Software Market
Digital Health Solutions
Middle East and Africa Virtual Reality (VR) Health Market
Digital Health Solutions
Health Care Interoperability Solutions Market
Digital Health Solutions
Virtual Reality (VR) in Healthcare Market
Digital Health Solutions
Mhealth Applications Market
Digital Health Solutions
Long Term Post-Acute Care Software Market
Digital Health Solutions
Global Microservices in Healthcare Market
Digital Health Solutions
US Digital Therapeutics Market
Digital Health Solutions
Global Patient Centric Healthcare App Market
Digital Health Solutions
Europe Digital Health Market