
 Global Companion Animal Specialty Drugs Market | 2026-2036
Global Companion Animal Specialty Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Companion Animal Specialty Drugs Market Intelligence
Subscription-based medication delivery for chronic conditions is restructuring how specialty drugs are dispensed and monitored for companion animals. Zoetis Inc. leverages its extensive R&D pipeline to lead in immunologicals and dermatologicals. Elanco Animal Health competes with a broad portfolio, focusing on antiparasitics and pain management solutions. Boehringer Ingelheim Animal Health sustains its market position through specialization in cardiovascular and endocrine treatments.
Companion animal specialty drugs are prescription-based therapeutic agents, often biologics or advanced small molecules, designed to treat complex, chronic, or rare diseases in pets. These formulations, including monoclonal antibodies and targeted enzyme inhibitors, require precise dosing and administration under veterinary supervision for conditions like cancer or autoimmune disorders. The oncology drugs segment, while smaller, shows significant growth potential for cancer management applications. Veterinary clinics and animal hospitals remain the dominant end-user channels, capturing the majority of high-value prescriptions.
Market access and product approval pathways are governed by stringent regulatory bodies such as the FDA in the United States and the EMA in Europe. These agencies mandate rigorous clinical trials to ensure the safety and efficacy of new treatments, influencing development timelines and costs. Stakeholders must navigate the evolving landscape of cell and gene therapy regulations to secure future market access.
Market Dynamics
The evolution from acute care to chronic disease management is the central force shaping the companion animal specialty drug market. This shift necessitates advanced biologics and novel delivery systems to address long-term conditions like cancer and autoimmune disorders, fundamentally altering veterinary treatment paradigms and R&D priorities.
Growth Catalysts
- Monoclonal Antibody Innovation:Advances in monoclonal antibody (mAb) therapies are providing highly targeted, effective treatments for previously difficult-to-manage conditions like atopic dermatitis and osteoarthritis, driving adoption in veterinary clinics.
- Pet Humanization Trend:A cultural shift, particularly strong in the United States and Western Europe, where pets are viewed as family members, directly correlates with increased owner willingness to pay for expensive, life-extending specialty treatments.
- Regulatory Support for Rare Diseases:The FDA's Minor Use/Minor Species (MUMS) drug designation provides incentives for developing treatments for less common diseases, which helps de-risk R&D investment for niche but high-value therapeutic areas.
Market Restraints
- High Treatment Cost:The significant expense of developing and manufacturing biologics results in high-priced therapies, limiting access for a large portion of the pet-owning population and constraining market volume.
- Stringent Regulatory Hurdles:Rigorous and lengthy clinical trial mandates from regulatory bodies like the EMA and FDA increase development timelines and costs, creating a substantial barrier to entry for new therapeutics.
- Cold Chain Logistics:Many specialty biologics require uninterrupted refrigerated storage and transport, complicating distribution and increasing the risk of spoilage, particularly in regions with less developed veterinary supply chains.
Strategic Opportunities
- Geographic Expansion:Untapped demand in markets such as South Korea and Australia offers significant growth potential as rising disposable incomes and pet ownership rates converge with an increasing desire for advanced veterinary care.
- Personalized Medicine:The application of genomics and biomarker analysis to develop personalized treatment protocols for individual pets represents a major frontier, especially for complex diseases like cancer.
- Telemedicine Integration:The growth of veterinary telemedicine platforms creates an opportunity to build direct-to-consumer subscription channels for managing chronic medications, enhancing compliance and owner convenience.
Industry Challenges
- Specialist Veterinarian Scarcity:A shortage of board-certified veterinary specialists, including oncologists and immunologists, creates a bottleneck that limits the administration and proper monitoring of complex specialty drug regimens.
- Intellectual Property Complexity:Managing the patent lifecycle of first-generation biologics and navigating the intricate IP landscape for emerging cell and gene therapies presents significant legal and competitive challenges.
- Diagnostic Standardization Gaps:A lack of universally accepted diagnostic criteria and testing protocols for many rare and complex diseases leads to inconsistent treatment approaches and complicates clinical data aggregation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Companion Animal Specialty Drugs Market |
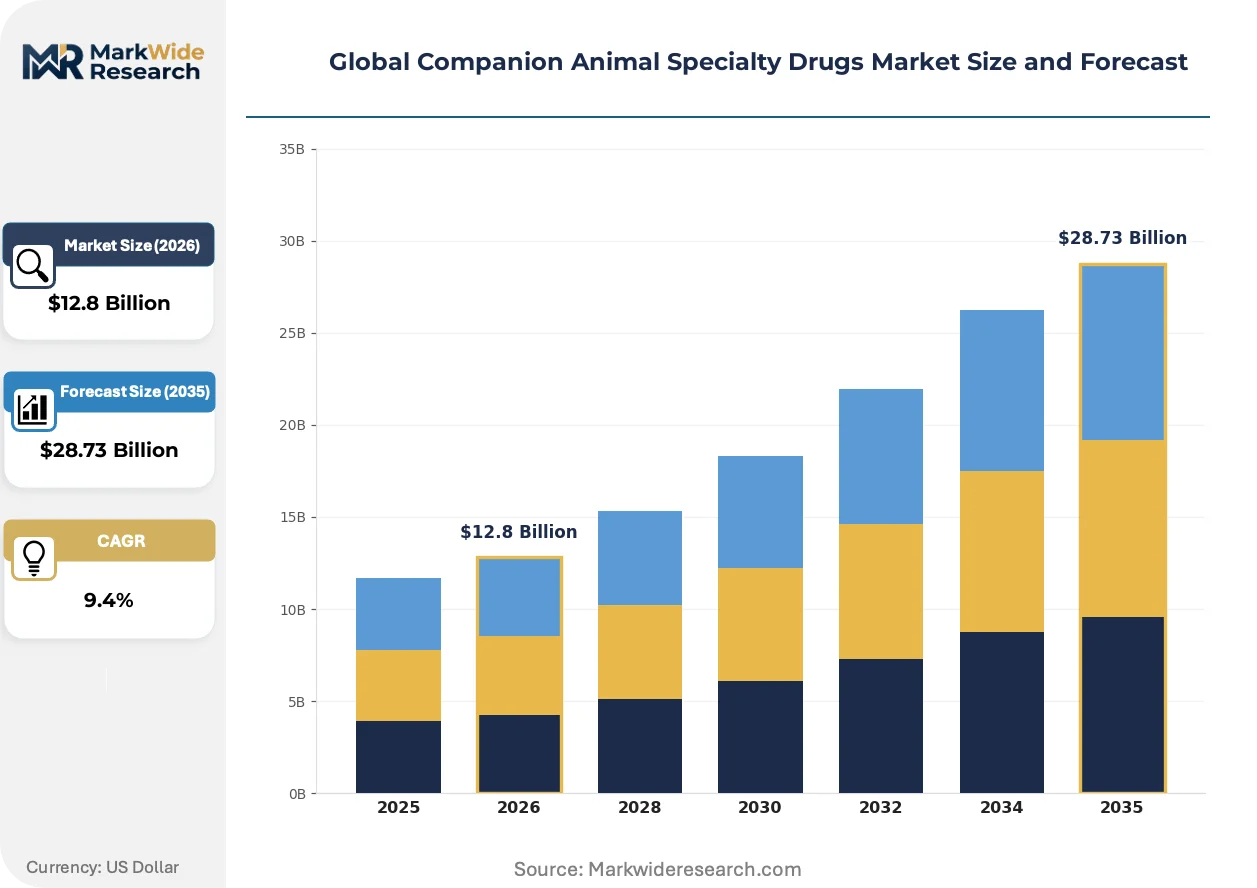
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiparasitics, Dermatologicals, Cardiovasculars, Oncology Drugs, Endocrine Treatments, Immunologicals Application: Infectious Diseases, Allergies, Cancer Management, Hormonal Disorders, Autoimmune Conditions, Pain Relief End User: Veterinary Clinics, Specialty Pharmacies, Animal Hospitals, Diagnostic Labs, Research Institutions, Breeders Distribution Channel: Direct Sales, Online Retailers, Wholesalers, Veterinary Distributors, Pharmacy Chains, Mail Order |
| Companies Covered | Zoetis Inc., Boehringer Ingelheim Animal Health, Elanco Animal Health, Merck Animal Health, Virbac, Dechra Pharmaceuticals, Ceva Santé Animale, Vetoquinol, Bayer Animal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Companion Animal Specialty Drugs Market Strategic Shifts & Innovations
The convergence of advanced diagnostics with targeted therapeutics is reshaping the market. This integration allows for more precise and effective interventions, moving veterinary medicine toward a more personalized standard of care for complex chronic illnesses in companion animals.
Companion diagnostics (CDx) are tests that identify specific biological markers to determine a patient's suitability for a particular specialty drug. Veterinary oncologists and internal medicine specialists are increasingly adopting these tools to guide treatment decisions. The use of CDx is unifying therapeutic selection with an animal's specific disease biology, moving the field away from generalized protocols and toward precision medicine.
Updated regulations from the European Medicines Agency (EMA) are influencing development priorities. Regulation (EU) 2019/6 for veterinary medicinal products seeks to improve drug availability while simultaneously combating antimicrobial resistance. This policy indirectly benefits the immunology drug segment by encouraging the development of non-antibiotic alternatives, such as immunomodulators, for treating inflammatory and immune-mediated conditions.
Subscription-based medication delivery is altering the dispensing model for chronic conditions. This approach is replacing single-purchase transactions at the veterinary clinic for pets with stable, long-term diseases requiring consistent medication. The trend is most visible in the United States and the United Kingdom, where pet owners value the convenience of home delivery for managing conditions like arthritis or allergies.
Global Companion Animal Specialty Drugs Market Segmentation
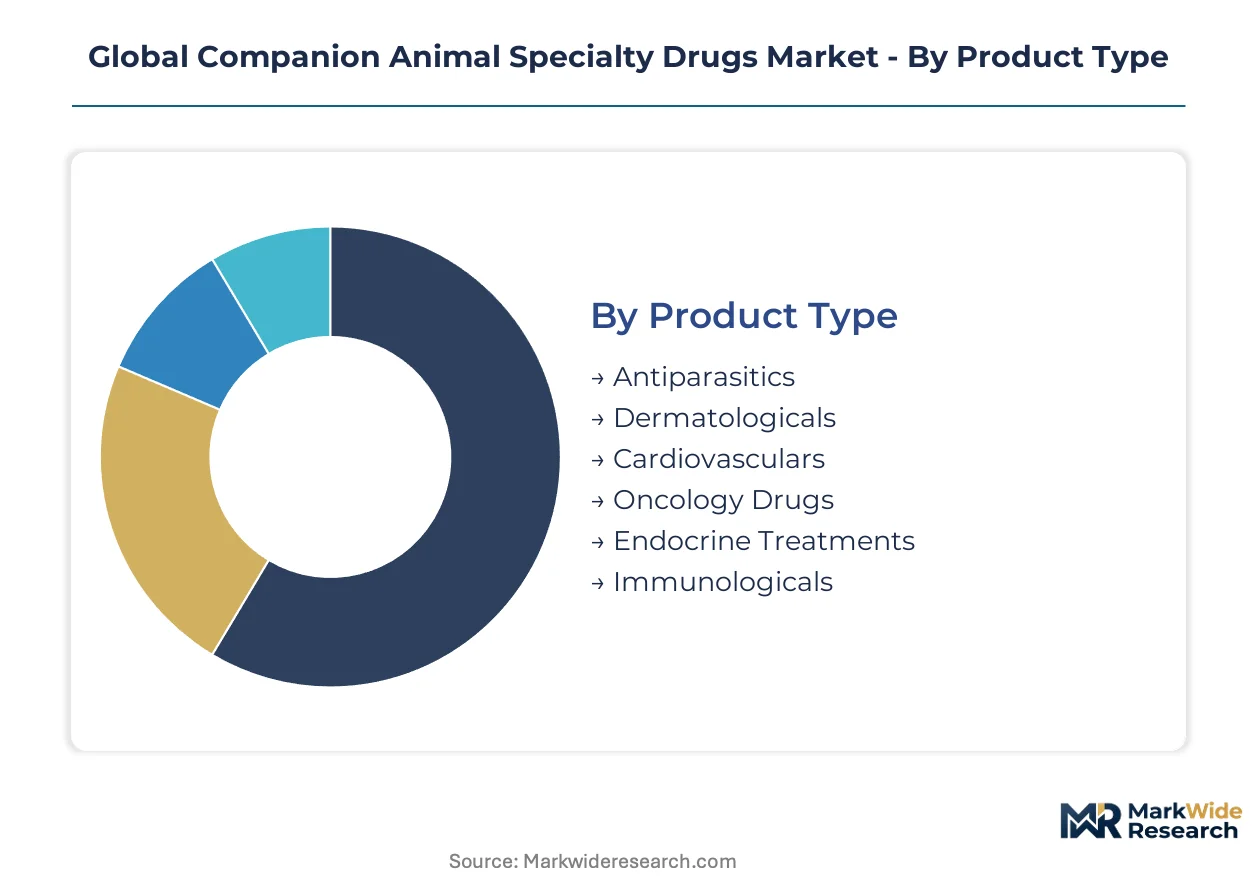
The companion animal specialty drugs market structures itself across diverse therapeutic areas and operational pathways. Understanding these segments reveals specific demand patterns, regulatory influences, and the strategic deployment of advanced veterinary treatments. This detailed breakdown highlights where investment and innovation converge for complex pet health conditions.
Product Type:
Pet owners' investment in advanced care drives demand for specific product types within this market.
- Oncology Drugs:These specialized pharmaceuticals target various cancers in companion animals, including chemotherapy agents and immunotherapies. Demand concentrates in advanced veterinary hospitals in the United States, driven by increasing pet owner expenditure on life-extending treatments.
- Immunologicals:This category encompasses biologics and small molecules modulating the immune system, often for autoimmune diseases or allergies. Innovations in monoclonal antibody therapies are creating new treatment paradigms for chronic inflammatory conditions across Europe.
- Antiparasitics:These drugs prevent and treat internal and external parasitic infestations in pets, representing a foundational segment.
- Dermatologicals:Formulations address various skin conditions, including allergies and infections, often requiring long-term management.
- Cardiovasculars:Medications manage heart conditions such as congestive heart failure and hypertension in aging companion animals.
- Endocrine Treatments:These drugs regulate hormonal imbalances, treating conditions like diabetes and hypothyroidism.
Volume sits with Antiparasitics; growth tilts toward Oncology Drugs.
Application:
Therapeutic application dictates development priorities and market penetration of companion animal specialty drugs.
- Cancer Management:This application involves advanced diagnostics and targeted therapies for various pet cancers, including chemotherapy and novel biologics. Demand is strongest in regions with high pet humanization, such as Germany, where owners seek extended quality of life for their pets.
- Autoimmune Conditions:Treatments for immune-mediated disorders, like atopic dermatitis and inflammatory bowel disease, often utilize novel monoclonal antibodies. The United States leads in the adoption of these innovative therapies due to advanced veterinary infrastructure.
- Infectious Diseases:This segment involves drugs combating bacterial, viral, and fungal infections, crucial for pet health.
- Allergies:Medications alleviate allergic reactions and their symptoms, a common and persistent issue for many companion animals.
- Hormonal Disorders:Therapies address endocrine imbalances, such as diabetes mellitus and hypothyroidism, requiring chronic medication.
- Pain Relief:This application includes NSAIDs, opioids, and other analgesics for managing acute and chronic pain in pets.
Infectious Diseases command the largest share; Autoimmune Conditions are expanding most quickly.
End User:
End-user channels determine care delivery and influence dispensing models for specialty medications.
- Veterinary Clinics:These facilities serve as the primary point of diagnosis, prescription, and administration for most specialty drugs in companion animals. They capture the majority of high-value prescriptions, particularly for complex treatments requiring direct veterinary supervision.
- Animal Hospitals:Larger facilities offering advanced diagnostics, surgical procedures, and specialized treatments, including oncology and internal medicine. These institutions often house board-certified specialists, facilitating the use of complex drug regimens for severe conditions.
- Specialty Pharmacies:These pharmacies focus on complex, high-cost medications, providing specialized support and direct-to-owner delivery.
- Diagnostic Labs:Facilities conduct tests to identify diseases and monitor treatment efficacy for specialty drug use.
- Research Institutions:Universities and private organizations conduct clinical trials, contributing to future specialty drug availability.
- Breeders:This segment utilizes specialty drugs for managing genetic conditions or specific health needs within breeding programs.
Veterinary Clinics remain primary access points; Specialty Pharmacies gain significant traction.
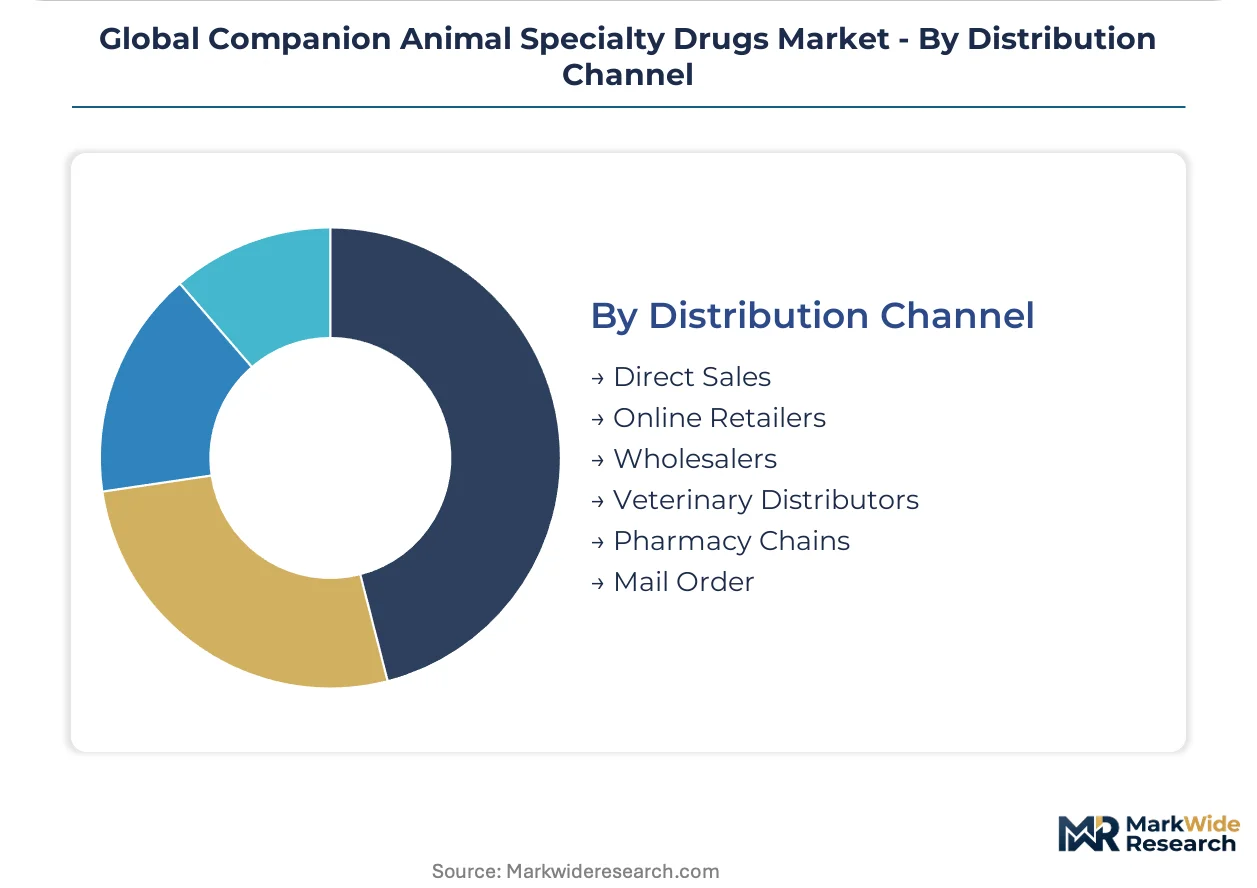
Distribution Channel:
Supply chain efficiency defines the effectiveness of distribution channels for specialty drugs.
- Online Retailers:E-commerce platforms provide convenient access to specialty medications, particularly for chronic conditions requiring repeat prescriptions. The growth of veterinary telemedicine platforms in the United Kingdom supports this channel for direct-to-consumer subscription models.
- Direct Sales:Manufacturers directly supply large veterinary groups or key opinion leaders, ensuring controlled distribution and product support. This channel is critical for new, high-value biologics that require specialized handling and training for veterinarians.
- Wholesalers:Entities purchase drugs in bulk from manufacturers, distributing to various veterinary outlets.
- Veterinary Distributors:Specialized distributors focus on the veterinary market, offering tailored logistics and inventory management.
- Pharmacy Chains:Traditional pharmacies with veterinary departments offer dispensing services for specialty drugs in urban areas.
- Mail Order:This channel delivers medications directly to pet owners for long-term chronic care management.
Veterinary Distributors handle bulk transactions; Online Retailers witness the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The companion animal specialty drugs market exhibits a clear divide between high-consumption regions and emerging R&D hubs. Advanced veterinary infrastructure and strong pet humanization trends in developed economies drive significant demand, while regulatory frameworks influence product innovation and market access across diverse geographies.
United States
High pet humanization and substantial pet care expenditure drive demand for advanced specialty drugs in the United States. The FDA's Minor Use/Minor Species (MUMS) drug designation provides incentives for developing treatments for less common pet diseases. Boston's biotech hub leads innovation in animal biologics research and development.
Germany
Germany showcases strong demand for extended quality of life treatments for companion animals, supported by robust veterinary care. European Medicines Agency (EMA) regulations significantly influence drug development and market availability for advanced veterinary products. The Rhine-Main region features numerous animal health research centers, fostering therapeutic advancements.
Japan
Japan's aging pet population creates specific demand for chronic disease management and advanced veterinary medicine. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees veterinary drug approvals, ensuring stringent safety and efficacy standards. Tokyo hosts specialized veterinary clinics, which are early adopters of novel immunotherapies.
South Korea
Rising disposable incomes and increasing pet ownership rates converge with a desire for advanced veterinary care in South Korea. The Ministry of Food and Drug Safety (MFDS) regulates animal health products, encouraging local research and development investment. Seoul's research parks are fostering new diagnostic and therapeutic solutions for companion animals.
Australia
Australia exhibits high rates of pet ownership and increasing expenditure on advanced treatments, supported by strong veterinary services. The Therapeutic Goods Administration (TGA) ensures rigorous evaluation of new specialty drugs before market entry. Melbourne's veterinary hospitals are early adopters of targeted oncology treatments and advanced pain management solutions.
Global Companion Animal Specialty Drugs Market Key Industry Players
Top-tier vendors anchor the global companion animal specialty drugs market, while mid-sized innovators and regional specialists compete for niche segments. The market structure features a tiered consolidation, with large multinational corporations dominating. Strategic archetypes include R&D-intensive biologics developers, broad-portfolio animal health providers, and disease-specific treatment specialists. Dominant competitive moves involve portfolio diversification through mergers and acquisitions and strategic partnerships for technology access.
Among global pharmaceutical players, Zoetis Inc. represents a leader in R&D-driven innovation for immunologicals and dermatologicals, leveraging its extensive pipeline. Boehringer Ingelheim Animal Health exemplifies a major European entity sustaining market position through specialization in cardiovascular and endocrine treatments. Elanco Animal Health, as a broad-portfolio animal health provider, competes effectively with its extensive range of antiparasitics and pain management solutions, serving a wide veterinary customer base.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Boehringer Ingelheim Animal Health |
| Elanco Animal Health |
| Merck Animal Health |
| Virbac |
| Dechra Pharmaceuticals |
| Ceva Santé Animale |
| Vetoquinol |
| Bayer Animal Health |
Cost & Logistics Intelligence
Biopharmaceutical input costs, particularly for complex cell culture media, cascade through the companion animal specialty drug supply chain, influencing premium pricing tiers for advanced biologics. This market sees a direct correlation between the sophistication of the therapeutic agent and its cost to veterinary clinics and pet owners.
Pricing Analysis
Margin tightening in the specialty biologics segment reflects increasing R&D investment and stringent clinical trial requirements. Value-based pricing models dominate, where efficacy in treating complex conditions like cancer or autoimmune disorders justifies higher costs. FDA and EMA certification provide significant brand premium, differentiating products in a competitive landscape. Pricing pressure also stems from owner willingness to pay thresholds, limiting market volume for the most expensive therapies. Pet owners prioritizing life-extending treatments for their companion animals exhibit lower price sensitivity, while a large segment of the pet-owning population remains highly price-sensitive.
Supply Chain Analysis
Logistics and freight costs for temperature-sensitive biologics impact the companion animal specialty drug supply chain, particularly for cold chain distribution. Geographic supply concentration for advanced biologics manufacturing centers in the United States, Germany, and Japan. The supply chain relies on specialized cell lines and recombinant proteins as critical raw material inputs. Cold chain integrity represents a significant structural risk, complicating distribution to diverse veterinary outlets. Distribution runs through specialized veterinary distributors and an expanding network of specialty pharmacies, ensuring appropriate handling and timely delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
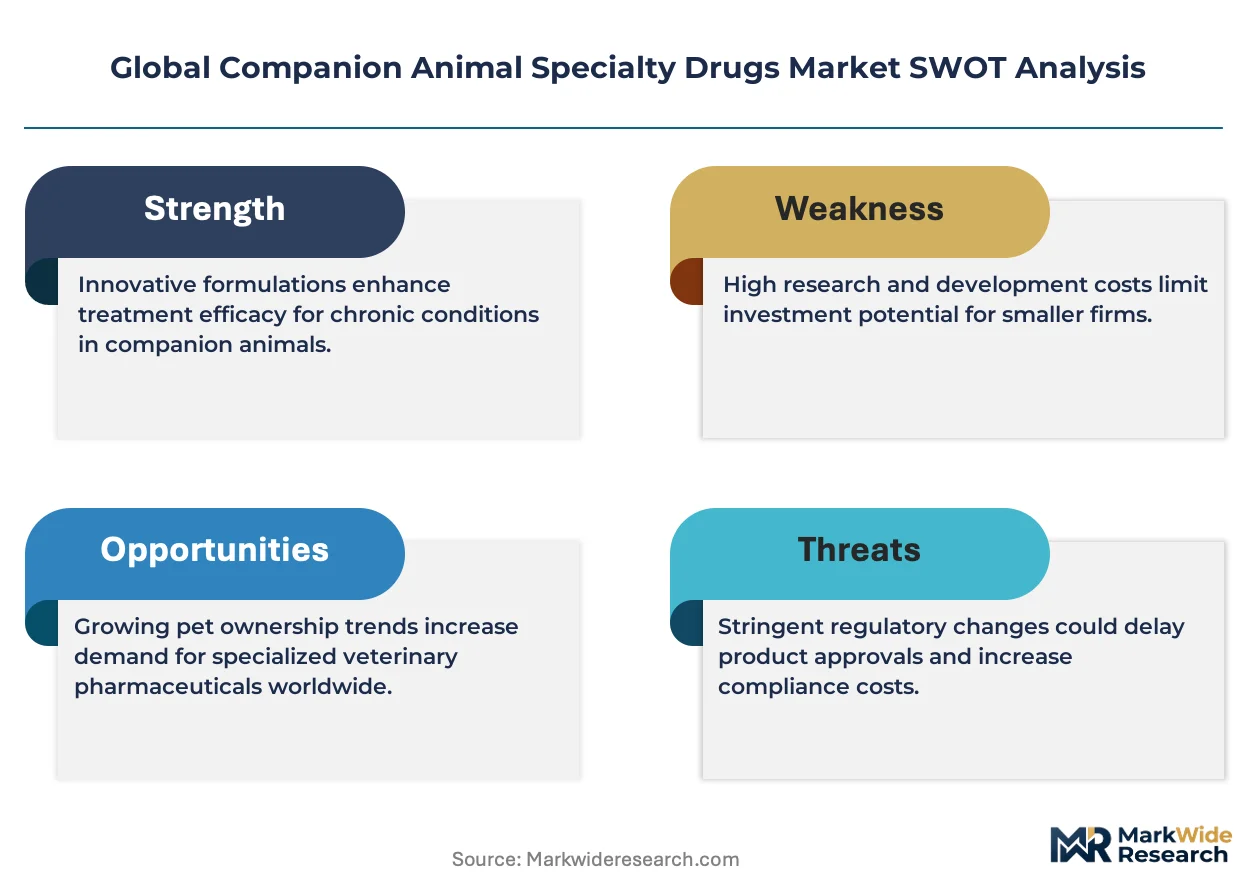
The companion animal specialty drugs market is poised for consolidation, driven by the immense capital requirements for R&D and stringent regulatory compliance.
For Market Incumbents:
Hedge against emerging therapeutic modalities by aggressively investing in gene and cell therapy research, especially for oncology applications. Diversify product portfolios to include companion diagnostics, enhancing the value proposition of existing drug lines. Control key distribution channels through strategic partnerships with large veterinary hospital networks, countering the threat from new market entrants. Secure intellectual property for first-generation biologics, maintaining market dominance against potential biosimilar competition.
For New Entrants and Emerging Players:
Advanced diagnostic platforms create a technology-first wedge for new entrants targeting precision medicine applications. Focus on underserved therapeutic areas or rare diseases, leveraging FDA's MUMS designation for de-risked R&D. Develop novel drug delivery systems that enhance pet owner convenience and compliance, creating a strong go-to-market angle. Target geographic white spaces in regions like South Korea and Australia, where demand for advanced veterinary care is rapidly expanding.
For Investors and Strategic Acquirers:
The window for entry favors strategic acquirers seeking niche technology platforms and specialized R&D capabilities. Long-term viability rests with companies possessing robust pipelines in biologics and advanced small molecules. Target R&D-intensive biologics developers with strong intellectual property portfolios, especially those in immunology or oncology. A key signal to watch is the successful regulatory approval of cell and gene therapy products, indicating market readiness for next-generation treatments.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel biologics, addressing unmet medical needs in companion animals. |
| Regulatory Approval Pathway | Secures market access for innovative therapies by navigating complex FDA and EMA mandates. |
| Licensing Agreement | Expands product portfolios and geographic reach without extensive in-house R&D investment. |
| Manufacturing Scale-Up | Ensures sufficient supply of high-demand specialty drugs, meeting growing veterinary clinic needs. |
| Pipeline Diversification | Reduces reliance on single therapeutic areas, spreading risk across multiple complex pet conditions. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with industry stakeholders. This study integrated insights from drug development executives, regulatory affairs leads, veterinary oncologists, and hospital procurement managers. Bottom-up and top-down triangulation validated market sizing and segmentation across various data points.
Data-stream reconciliation across multiple sources allowed for robust validation of market size and growth projections across the analysis window. The analytical framework segmented the market by treatment line, dosage form, patient population, and regional regulatory cluster. Compound Annual Growth Rates were derived from historical data trends and projected market dynamics, incorporating pet ownership rates and veterinary R&D investment as key inputs.
Several conditions sit outside the modeled scope, including specific insurance reimbursement policies and localized epidemiological outbreaks. Forecasts reflect assumptions regarding technological advancements and market acceptance. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Veterinary Software Market
Veterinary
Veterinary Antimicrobial Susceptibility Testing Market
Veterinary
Veterinary Lasers Market
Veterinary
Global Veterinary MRI Market
Veterinary
Global Veterinary Electrosurgery Market
Veterinary
Global Animal Intestinal Health Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
Veterinary Faecal Filters Market
Veterinary
Global Livestock Vaccines Market
Veterinary
Europe Dog Dewormers Market
Veterinary
Veterinary Progesterone Testing Market
Veterinary
Veterinary Parasiticides Market
Veterinary
Global Veterinary Grooming Aids Market
Veterinary
Global Veterinary Point of Care Market