
 Global Home Health Hub Market | 2026-2036
Global Home Health Hub Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Health Hub Market Foresight
Asset-light leasing models for remote monitoring hardware are reshaping competitive entry in home health hubs, allowing smaller telehealth platforms to scale without capital-intensive device procurement. Qualcomm Technologies sustains technology leadership through its cellular IoT chipset architecture, while KONINKLIJKE Philips N.V. dominates integrated platform deployments across European home care networks. Honeywell International Inc. leverages its building automation heritage to control smart home integration pathways for health data.
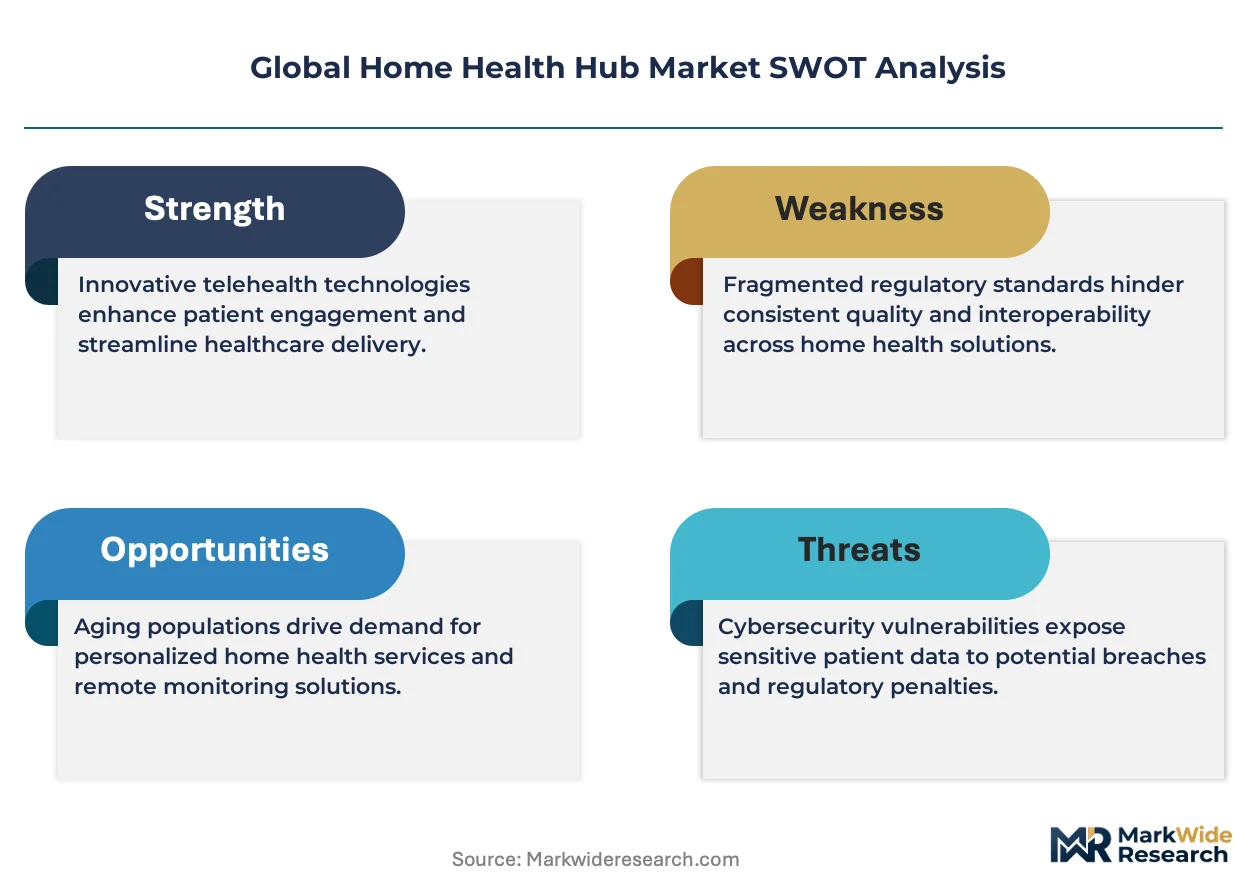
A home health hub functions as a centralized connectivity gateway that aggregates biometric data from multiple peripheral devices, typically supporting Bluetooth Low Energy and Zigbee protocols with local edge processing before cloud transmission. These systems serve primarily to enable continuous remote patient monitoring and care coordination outside institutional settings. Remote Monitoring Systems anchor the product mix due to recurring service revenue and clinical validation requirements, while Cellular IoT connectivity commands premium positioning as healthcare networks prioritize reliable failover over Wi-Fi dependency. Chronic Disease Management generates the deepest margin pools through long-term reimbursement contracts, whereas Elderly Care applications show the steepest adoption curve among assisted living operators seeking to delay facility transfers.
FDA software-as-a-medical-device oversight and the EU MDR cybersecurity annex are forcing platform developers to embed pre-market documentation and post-market surveillance into product lifecycles. Japan's PMDA has issued comparable guidance on algorithm transparency for AI-enabled diagnostic features in connected care devices. Stakeholders must decide whether to build compliance architectures that satisfy multiple regulatory regimes simultaneously or pursue sequential market entry with jurisdiction-specific certifications.
Market Dynamics
Cellular IoT connectivity is collapsing the historical Wi-Fi dependency of home health deployments, forcing platform architects to redesign failover architectures around Qualcomm's chipset roadmaps and carrier-grade reliability standards.
Growth Catalysts
- Statutory reimbursement expansion:Germany's statutory health insurance funds now cover remote patient monitoring for chronic heart failure, creating immediate volume pull-through for cellular-enabled hub deployments in Bavaria and North Rhine-Westphalia.
- FDA software-as-a-medical-device pathway:The FDA's 2022 guidance on pre-market documentation for algorithm-driven diagnostics accelerates commercialization timelines for AI-enabled risk stratification features.
- Edge computing integration:Local inference on ARM Cortex-M33 microcontrollers reduces cloud transmission costs and latency, enabling real-time arrhythmia detection without continuous connectivity.
Market Restraints
- Cellular module cost concentration:Qualcomm's dominance in LTE-M and NB-IoT baseband silicon creates single-source vulnerability for mid-tier hub manufacturers.
- EU MDR cybersecurity annex compliance:Post-market surveillance requirements for connected care devices extend certification timelines and legal liability exposure.
- Wi-Fi mesh substitution:Low-cost Thread and Matter protocols threaten premium positioning of cellular-first architectures in assisted living facilities with dense infrastructure.
Strategic Opportunities
- Japan's PMDA algorithm transparency pathway:The PMDA's 2023 guidance on explainable AI creates first-mover advantage for platforms with embedded clinical decision support.
- Behavioral health integration:Depression and anxiety monitoring through voice biomarker analysis opens reimbursement conversations with US Medicare Advantage plans.
- Asset-light hardware leasing:Subscription-based device provisioning allows telehealth startups to bypass capital barriers and scale patient panels faster.
Industry Challenges
- Interoperability certification backlog:HL7 FHIR R4 integration testing with Epic and Cerner EHR systems consumes 8-14 months of pre-launch engineering.
- Field engineering scarcity:Deployment technicians capable of configuring Zigbee mesh networks in rural patient homes command 40% wage premiums over standard IT support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Health Hub Market |
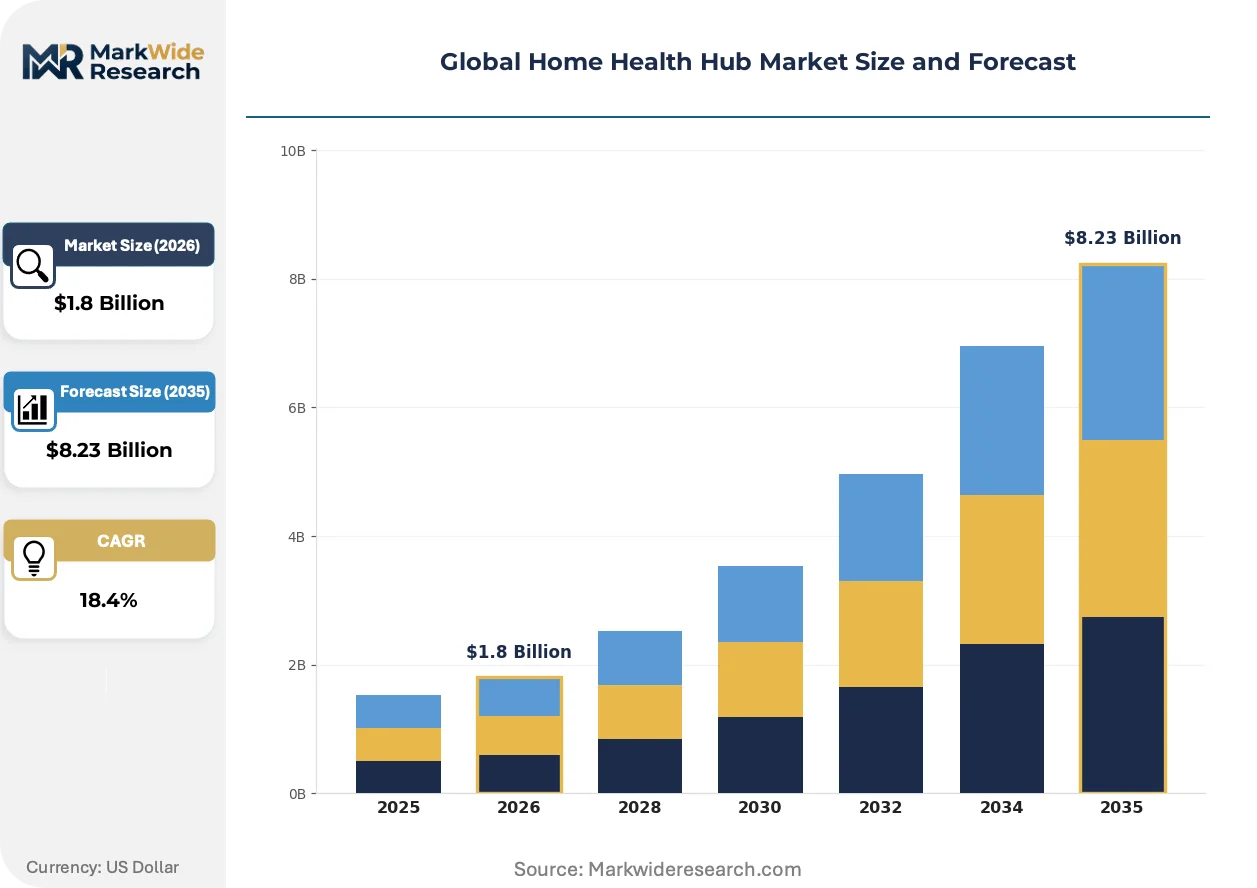
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Remote Monitoring Systems, Smart Medication Dispensers, Vital Sign Sensors Technology: Bluetooth, Wi-Fi, Zigbee, Cellular IoT, NFC Application: Chronic Disease Management, Elderly Care, Post-Operative Monitoring, Fitness Tracking, Sleep Analysis End User: Medical Clinics, Home Care Agencies, Assisted Living Facilities, Telehealth Providers |
| Companies Covered | Honeywell International Inc., Qualcomm Technologies Inc., Vivify Health Inc., AMC Health, iHealth Labs Inc., IDEAL LIFE Inc., Lamprey Networks, OnKöl, KONINKLIJKE Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Health Hub Market Shifts & Advancements
Platform architectures are fragmenting between cloud-native and edge-heavy designs, with regulatory pressure and connectivity economics pulling developers in opposing directions.
Edge AI inference on home health hubs is collapsing the latency requirements for acute event detection. Assisted living operators in Florida and Arizona are deploying hubs with local arrhythmia classification, eliminating the 3-8 second round-trip to AWS or Azure regions. This compression enables medication adherence interventions within 90 seconds of missed dose detection, fundamentally restructuring care coordinator staffing ratios.
The EU MDR cybersecurity annex and FDA's post-market surveillance guidance are converging on continuous vulnerability monitoring. Platform developers must now embed SBOM (Software Bill of Materials) generation and automated CVE scanning into CI/CD pipelines. European home care networks are demanding SOC 2 Type II attestation as a procurement gate, filtering out vendors without enterprise-grade security operations.
Hospital-at-home programs are consolidating purchasing authority into centralized procurement offices. Health systems in Texas and California are negotiating enterprise licenses covering 10,000+ hub deployments, displacing the traditional per-clinic acquisition pattern. This concentration shifts vendor sales investments toward clinical outcome guarantees and away from device feature differentiation.
Global Home Health Hub Market Segmentation
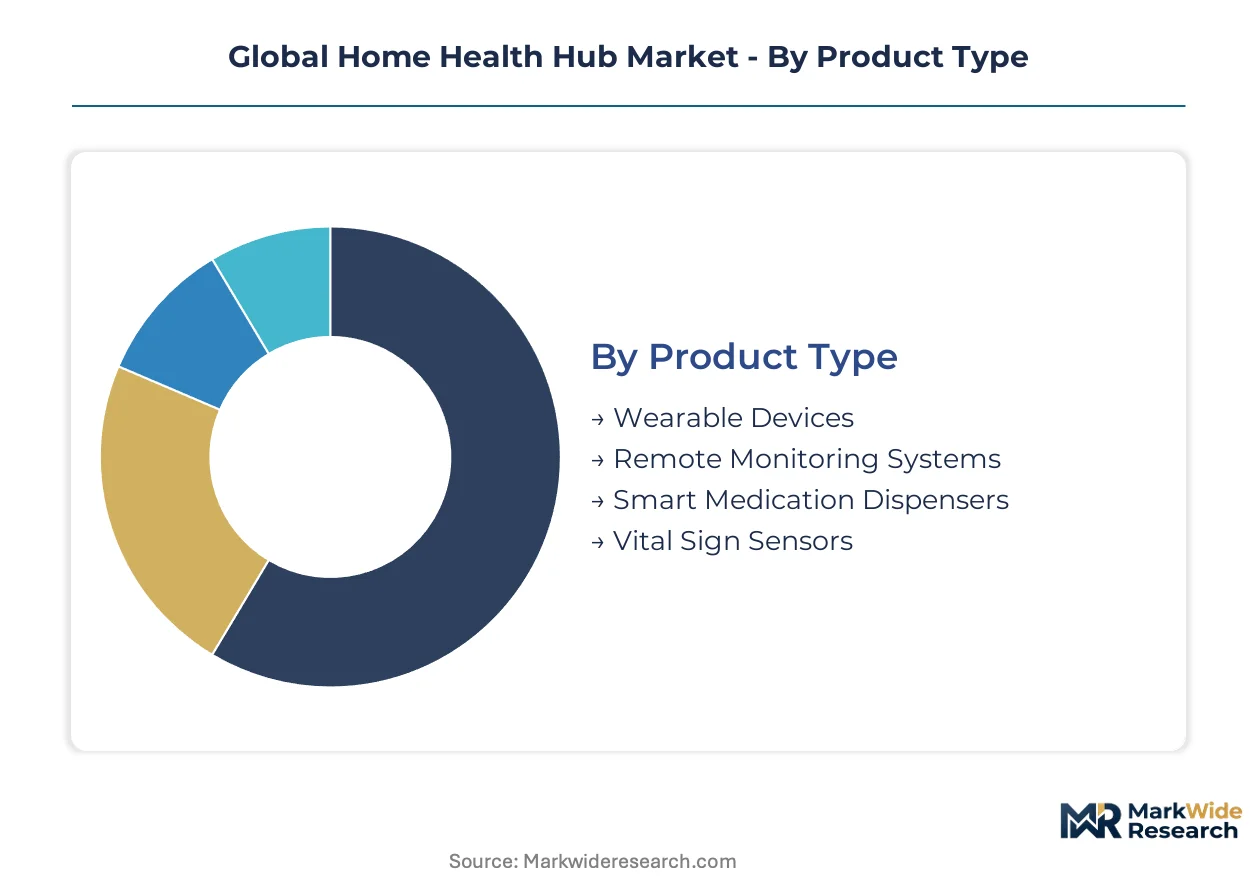
Segmentation in home health hubs reveals divergent technology maturity and reimbursement pathways that determine vendor investment priorities. Product architectures, connectivity protocols, clinical applications, and purchasing entities each impose distinct engineering and commercial constraints on platform developers.
Product Type:
The maturity spectrum spans established monitoring infrastructure to nascent medication adherence hardware.
- Remote Monitoring Systems:These platforms aggregate multi-parameter biometric streams through centralized gateways with local edge processing and encrypted cloud handoff. Hospital-at-home programs in Texas and California negotiate enterprise licenses covering thousands of deployments, displacing per-clinic procurement patterns.
- Wearable Devices:Continuous glucose monitors and pulse oximeters transmit via Bluetooth Low Energy to hub aggregators, creating recurring service revenue through long-term reimbursement contracts for chronic disease management.
- Smart Medication Dispensers:Locked pill dispensers with adherence logging and caregiver alerts serve assisted living operators seeking to delay facility transfers.
- Vital Sign Sensors:Blood pressure cuffs and weight scales with automated data capture support post-operative monitoring workflows in home care agency deployments.
Remote Monitoring Systems retain volume leadership; Smart Medication Dispensers hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium cellular architectures from commodity radio protocols.
- Cellular IoT:LTE-M and NB-IoT modules provide carrier-grade reliability independent of patient home Wi-Fi infrastructure. Germany's statutory health insurance funds now cover remote patient monitoring for chronic heart failure, creating immediate volume pull-through for cellular-enabled hub deployments in Bavaria and North Rhine-Westphalia.
- Bluetooth:Low-energy peripheral connectivity dominates wearable device pairing, though range limitations necessitate hub proximity within 10 meters.
- Wi-Fi:Legacy dependency persists in urban deployments with robust broadband infrastructure, though failover vulnerabilities drive replacement.
- Zigbee:Mesh networking protocols enable whole-home sensor coverage in multi-room assisted living units without cellular data costs.
- NFC:Tap-to-pair provisioning simplifies device onboarding for elderly patients with limited technical literacy.
Cellular IoT commands premium positioning; Zigbee shows the fastest volume climb in dense facility deployments.
Application:
Customer type differentiation separates clinically validated reimbursement pathways from consumer wellness segments.
- Chronic Disease Management:Heart failure and diabetes monitoring programs generate the deepest margin pools through long-term reimbursement contracts with US Medicare Advantage plans and German statutory insurers.
- Elderly Care:Fall detection and activity monitoring for aging-in-place populations shows the steepest adoption curve among assisted living operators in Florida and Arizona seeking to delay skilled nursing transfers.
- Post-Operative Monitoring:Surgical recovery tracking reduces readmission penalties for health systems managing total joint replacement and cardiac procedure patients at home.
- Fitness Tracking:Consumer-grade wellness metrics operate outside reimbursement frameworks, limiting enterprise health network procurement.
- Sleep Analysis:Respiratory and movement pattern detection serves niche diagnostic applications with limited payer coverage.
Chronic Disease Management anchors revenue concentration; Elderly Care expands most quickly among facility-based purchasers.
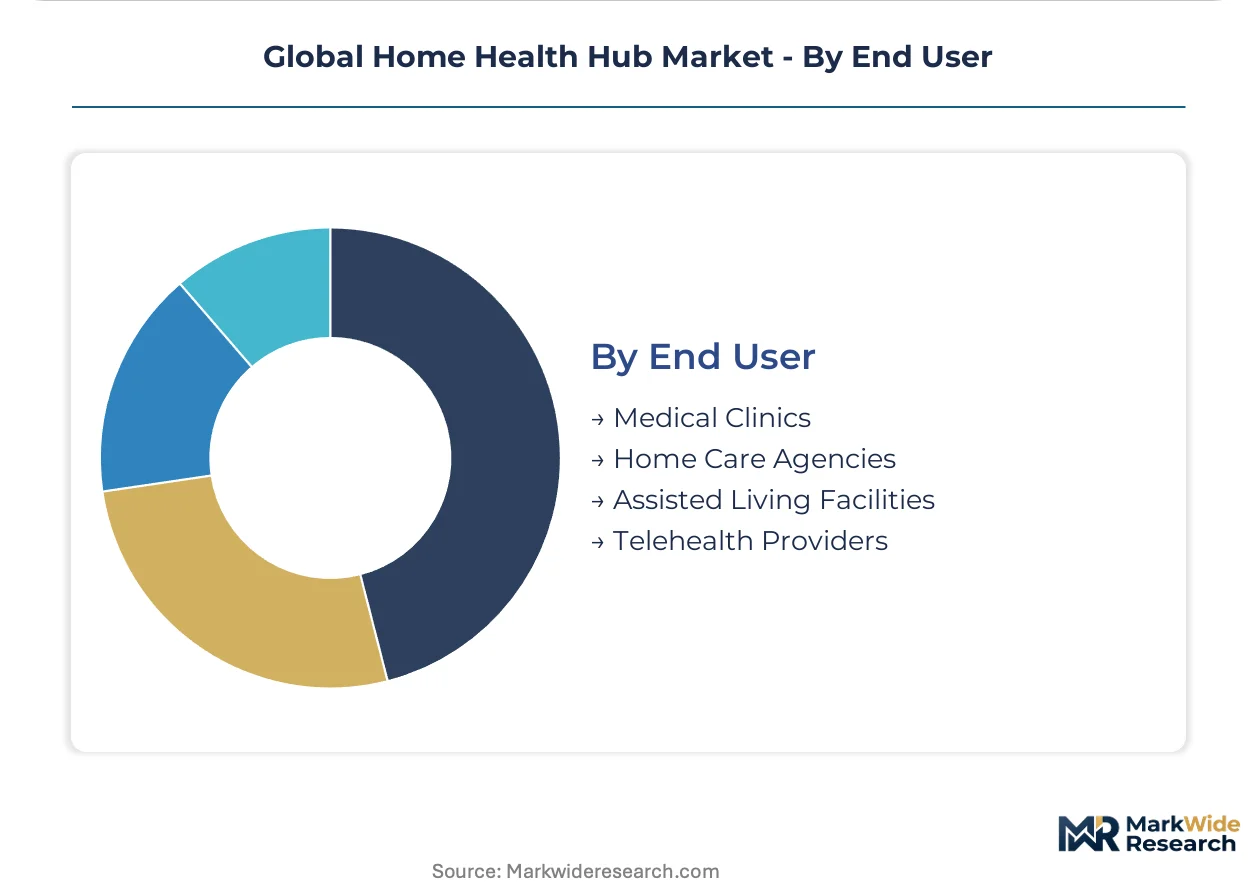
End User:
Geography of purchasing authority determines sales cycle complexity and outcome guarantee requirements.
- Telehealth Providers:Virtual-first care platforms deploy asset-light leasing models to scale patient panels without capital-intensive device procurement, accelerating competitive entry.
- Assisted Living Facilities:Dense infrastructure environments in Florida and Arizona favor Wi-Fi mesh and Zigbee protocols over cellular dependency, though cybersecurity requirements intensify.
- Home Care Agencies:Distributed rural deployments command 40% wage premiums for field technicians capable of configuring mesh networks in patient homes.
- Medical Clinics:Small-practice procurement is consolidating into health system centralized purchasing offices, shifting vendor investment toward clinical outcome guarantees.
Telehealth Providers drive the fastest volume expansion; Medical Clinics remain the largest installed base though procurement authority is migrating upward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory health insurance funds now reimburse remote patient monitoring for chronic heart failure, triggering immediate procurement acceleration across Bavaria and North Rhine-Westphalia. This policy template is reshaping competitive entry requirements in other jurisdictions.
United States
Hospital-at-home programs in Texas and California are consolidating purchasing authority into centralized procurement offices covering 10,000-plus hub deployments. The FDA's 2022 software-as-a-medical-device guidance accelerates commercialization timelines for AI-enabled risk stratification features. Florida and Arizona assisted living operators deploy edge-computing hubs with local arrhythmia classification to eliminate cloud latency.
Germany
Statutory health insurance reimbursement for remote patient monitoring creates immediate volume pull-through for cellular-enabled hub deployments. The EU MDR cybersecurity annex extends certification timelines and legal liability exposure for connected care devices. Bavaria and North Rhine-Westphalia health networks prioritize Qualcomm chipset architectures for carrier-grade reliability independent of patient home Wi-Fi.
Japan
Aging-in-place demand concentrates in Kanto and Kansai metropolitan corridors where assisted living operators seek to delay skilled nursing transfers. The PMDA's 2023 guidance on explainable AI creates first-mover advantage for platforms with embedded clinical decision support. Tokyo-based health networks demand algorithm transparency documentation for AI-enabled diagnostic features in connected care devices.
United Kingdom
NHS hospital-at-home initiatives drive enterprise-scale procurement for post-operative monitoring workflows. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance requirements comparable to EU MDR standards. London and Southeast England health systems negotiate outcome-based contracts with clinical guarantee provisions.
China
Chronic disease management programs accelerate adoption among telehealth providers serving aging urban populations. The NMPA issues guidance on software-as-a-medical-device oversight tightening data integrity requirements for connected care platforms. Yangtze River Delta and Pearl River Delta health networks deploy cellular IoT architectures to bypass unreliable residential broadband infrastructure.
Global Home Health Hub Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: semiconductor architects controlling baseband silicon, integrated platform vendors with European home care network relationships, and asset-light telehealth specialists scaling through hardware leasing. Strategic archetypes include cellular connectivity gatekeepers, clinical workflow integrators, and smart home automation extenders. Dominant competitive moves center on M&A to acquire FDA pre-market documentation portfolios and strategic partnerships with statutory insurers to secure reimbursement pathway access.
Within the integrated platform tier, KONINKLIJKE Philips N.V. and Honeywell International Inc. exemplify divergent heritage advantages: the Dutch entity anchors European home care network deployments while the US industrial conglomerate leverages building automation expertise for smart home health data integration. Qualcomm Technologies Inc. occupies the semiconductor architecture position, with its cellular IoT chipset roadmaps determining failover design constraints for mid-tier hub manufacturers. Vivify Health Inc. represents the asset-light telehealth archetype, scaling patient panels through subscription-based device provisioning rather than capital-intensive procurement.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Qualcomm Technologies Inc. |
| Vivify Health Inc. |
| AMC Health |
| iHealth Labs Inc. |
| IDEAL LIFE Inc. |
| Lamprey Networks |
| OnKöl |
| KONINKLIJKE Philips N.V. |
| Others |
Supply & Pricing Matrix
Qualcomm's silicon dominance in LTE-M and NB-IoT baseband modules creates single-source vulnerability that compresses mid-tier hub margins while amplifying premium spreads for vertically integrated platform vendors. This concentration forces manufacturers to choose between absorbing chipset cost volatility or passing through to health network purchasers with divergent reimbursement firepower.
Pricing Analysis
Certification grade creates the primary spread between FDA-cleared platforms and uncertified wellness devices, with EU MDR cybersecurity annex compliance adding substantial documentation premiums. Three-tier pricing structure separates enterprise health systems with outcome guarantees from regional telehealth providers on subscription models and direct-to-consumer wellness segments. Cost compression in the mid-tier is intensifying because statutory reimbursement pathways favor bundled service contracts over hardware margins. Telehealth startups leasing devices show highest price sensitivity; integrated platform vendors with European home care network relationships command lowest.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Jabil, and Flex holding capacity for cellular IoT module assembly and hub enclosure production. Semiconductor fabrication draws from Taiwan, South Korea, and USA for baseband silicon, while battery cell supply rests on China, South Korea, and Japan. Single-source vulnerability in Qualcomm's chipset roadmaps threatens continuity for manufacturers without alternative supplier qualifications. Distribution runs through health system centralized procurement offices, GPO contracts, and direct telehealth platform integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital-at-home procurement consolidation fragments vendor tiers, creating acquisition targets for platforms with embedded clinical workflow expertise and regulatory documentation portfolios.
For Market Incumbents: Pre-empt cellular module cost concentration by qualifying secondary chipset suppliers and securing long-term supply agreements with foundries. Lock in European home care network relationships through outcome-based contracts before statutory reimbursement expansion attracts new entrants. Vertical integration into edge computing silicon design differentiates against commodity hub assemblers. For New Entrants and Emerging Players: Establish a beachhead in Japan's PMDA algorithm transparency pathway, where explainable AI requirements filter out incumbent platforms lacking clinical decision support documentation. Target behavioral health integration through voice biomarker analysis as Medicare Advantage plans expand reimbursement conversations. Pursue asset-light hardware leasing to bypass capital barriers and scale patient panels faster than device procurement models allow. For Investors and Strategic Acquirers: FDA software-as-a-medical-device guidance reshapes the acquisition landscape toward platforms with pre-market documentation portfolios and post-market surveillance infrastructure. Five-to-ten year viability hinges on regulatory compliance architecture rather than device feature differentiation. Target acquisition archetype: telehealth platforms with embedded AI risk stratification and existing statutory insurer partnerships. Signal to watch: CMS reimbursement code expansion for remote physiological monitoring.| Strategic Initiative | Industry Significance |
|---|---|
| Cellular IoT Chipset Diversification | Reduces Qualcomm single-source dependency for mid-tier hub manufacturers facing margin compression. |
| EU MDR Cybersecurity Annex Compliance | Extends certification timelines but creates procurement gate for European home care network contracts. |
| Hospital System Partnership | Texas and California health systems consolidate 10,000-plus hub deployments into enterprise licenses. |
| Software Companion Development | FDA pathway for algorithm-driven diagnostics accelerates commercialization of AI-enabled risk stratification. |
| Reimbursement Strategy | Germany's statutory health insurance funds now cover chronic heart failure monitoring, pulling cellular-enabled volumes. |
Research Methodology
Desk research of FDA 510(k) filings, EU MDR technical documentation databases, and statutory health insurance reimbursement bulletins preceded structured interviews with telehealth platform CTOs, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers. Primary fieldwork validated secondary data from cellular carrier IoT deployment disclosures, semiconductor foundry capacity reports, and health system procurement databases. Bottom-up patient panel projections and top-down health network spending estimates were triangulated to constrain volume and value outputs.
Assumptions held fixed include statutory reimbursement expansion trajectories in Germany and FDA software-as-a-medical-device enforcement intensity; varied conditions include cellular module cost curves and Wi-Fi mesh substitution rates in assisted living facilities. The analytical framework segmented by product architecture, connectivity protocol, clinical application, and purchasing entity geography across the modeling period. CAGRs were derived from logistic adoption curves fitted to reimbursement policy inflection points and health system procurement cycle timing. Forecast inputs incorporated edge computing microcontroller cost trajectories and HL7 FHIR integration engineering timelines.
Stress conditions across cellular chipset supply disruption, EU MDR certification delay scenarios, and Wi-Fi mesh protocol adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and risk factors including regulatory enforcement variance and health system procurement consolidation pace. Quarterly review of statutory reimbursement code expansions, FDA pre-market submission volumes, and cellular IoT module spot pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
US Home Healthcare Market
Home Healthcare
Home Care Market
Home Healthcare
Global Health Caregiving Market
Home Healthcare
Home Care Products Market
Home Healthcare
Elder Care Products Market
Home Healthcare
Home Care Service Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
US House Calls Market
Home Healthcare
Canada Home Healthcare Market
Home Healthcare
Global Ambient Assisted Living (AAL) Market
Home Healthcare
Homecare Oxygen Concentrators Market
Home Healthcare
Global Nursing Care Market
Home Healthcare
Germany Home Healthcare Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Chemotherapy at Home Services Market
Home Healthcare
Elderly Care Apps Market