
 Smart Container Market | 2026-2036
Smart Container Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Container Market Intelligence
The EU Green Deal is hardening emissions accountability for maritime freight operators, compelling container lines to retrofit fleets with sensor-enabled assets. Maersk Line leverages its integrated logistics platform to deploy IoT-enabled units across transoceanic routes. CMA CGM Group anchors its competitive stance through proprietary Traxens technology partnerships. Nexxiot sustains R&D intensity in Switzerland, specializing in low-power asset tracking for intermodal networks.
Smart containers integrate embedded sensor arrays, satellite connectivity modules, and edge-computing processors to monitor location, temperature, humidity, shock, and door status in real time during transit. These units serve commercial freight operators by replacing manual inspection with automated exception alerts, reducing spoilage and theft exposure. IoT-enabled containers dominate current deployment volumes as cellular and satellite module costs decline, while temperature-controlled variants capture concentrated margin pools in pharmaceutical and perishable food verticals. Sensor-based solutions are displacing legacy barcode scanning across cold-chain applications, with RFID retaining relevance in yard-management and gate-automation workflows.
The EU F-Gas Regulation shapes refrigerant choices for temperature-controlled smart containers entering European ports, while the International Maritime Organization's emissions frameworks tighten retrofit deadlines for existing fleets. FDA guidelines on pharmaceutical distribution validate sensor-logging requirements that smart containers satisfy through continuous data capture. Stakeholders must weigh module standardization against proprietary ecosystem lock-in as carrier-specific platforms proliferate.
Market Dynamics
The EU Green Deal is hardening emissions accountability for maritime freight operators, compelling container lines to retrofit fleets with sensor-enabled assets that document carbon exposure across transoceanic routes.
Growth Catalysts
- Pharmaceutical cold-chain expansion:Temperature-sensitive biologics now require continuous environmental monitoring that IoT-enabled containers provide through embedded sensor arrays.
- EU F-Gas Regulation:Refrigerant phase-down mandates are accelerating replacement of conventional reefers with smart units using compliant cooling systems.
- Cellular cost collapse:Declining satellite and cellular module prices are removing connectivity barriers that previously constrained fleet-wide deployment.
Market Restraints
- Module standardization friction:Carrier-specific platforms create proprietary ecosystem lock-in that fragments interoperability across shipping lines.
- Capital intensity:Retrofitting existing container fleets requires substantial upfront hardware investment before operational savings materialize.
- RFID persistence:Legacy barcode and RFID systems retain cost advantages in yard-management workflows, slowing full sensor adoption.
Strategic Opportunities
- Perishable food verticals:Fresh produce exporters in Latin America and Southeast Asia represent underpenetrated demand for temperature-controlled smart units.
- Intermodal convergence:Integration of rail and road sensor networks with maritime containers creates end-to-end visibility platforms.
- IMO retrofit deadlines:International Maritime Organization emissions frameworks are mandating fleet upgrades that bundle sensor installation with efficiency improvements.
Industry Challenges
- Edge-computing integration:Embedding processors capable of real-time analytics requires specialized hardware engineering talent scarce in traditional container manufacturing.
- Data sovereignty complexity:Cross-border shipments trigger GDPR, state-level privacy laws, and port authority logging requirements that conflict on retention periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Container Market |
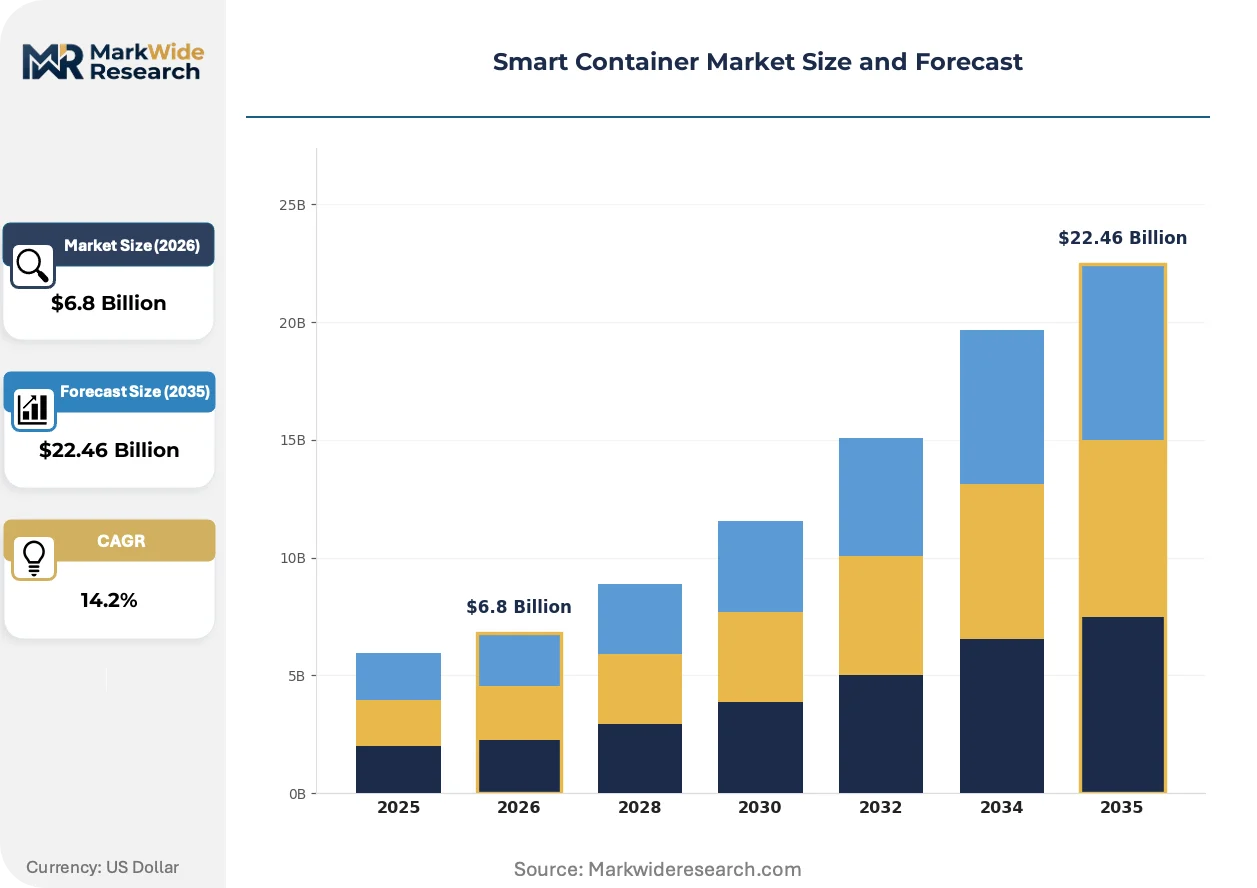
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Container, Passive Container, Temperature-Controlled Container, IoT-Enabled Container End User: Logistics Companies, Retailers, Food & Beverage, Pharmaceuticals Technology: RFID, GPS, Bluetooth, Sensor-Based Solutions Application: Shipping, Storage, Cold Chain, Hazardous Materials |
| Companies Covered | Nexxiot, Maersk Line, ORBCOMM, CMA CGM Group, Hapag-Lloyd AG, Traxens, CIMC Smart Technologies, Hoopo Systems Ltd., Globe Tracker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Container Market Strategic Shifts & Innovations
Sensor density is rising across container architectures as freight operators trade manual inspection for automated exception management. Three developments are compressing deployment timelines and reshaping competitive requirements.
Edge-computing processors with onboard analytics are overtaking cloud-dependent architectures in high-latency maritime corridors. These units process shock, temperature, and door-status data locally, transmitting only exception alerts via satellite. Pharmaceutical shippers with biologics cargo are adopting these systems fastest, compressing response windows for cold-chain breaches from hours to minutes.
EU F-Gas Regulation is forcing refrigerant transitions across temperature-controlled fleets entering European ports. Container operators must now document cooling-system specifications alongside cargo manifests. Reefer segments serving German pharmaceutical distribution hubs are retrofitting units with alternative refrigerants and integrated leak-detection sensors to satisfy Hamburg and Bremen port authority protocols.
Buyer consolidation among integrated logistics platforms is concentrating procurement power with carriers operating captive container fleets. Small and mid-sized freight forwarders face narrowing vendor options as Maersk and CMA CGM scale proprietary IoT deployments. This concentration is most visible in trans-Pacific lanes where carrier-controlled equipment now exceeds third-party leasing volumes.
Smart Container Market Segmentation
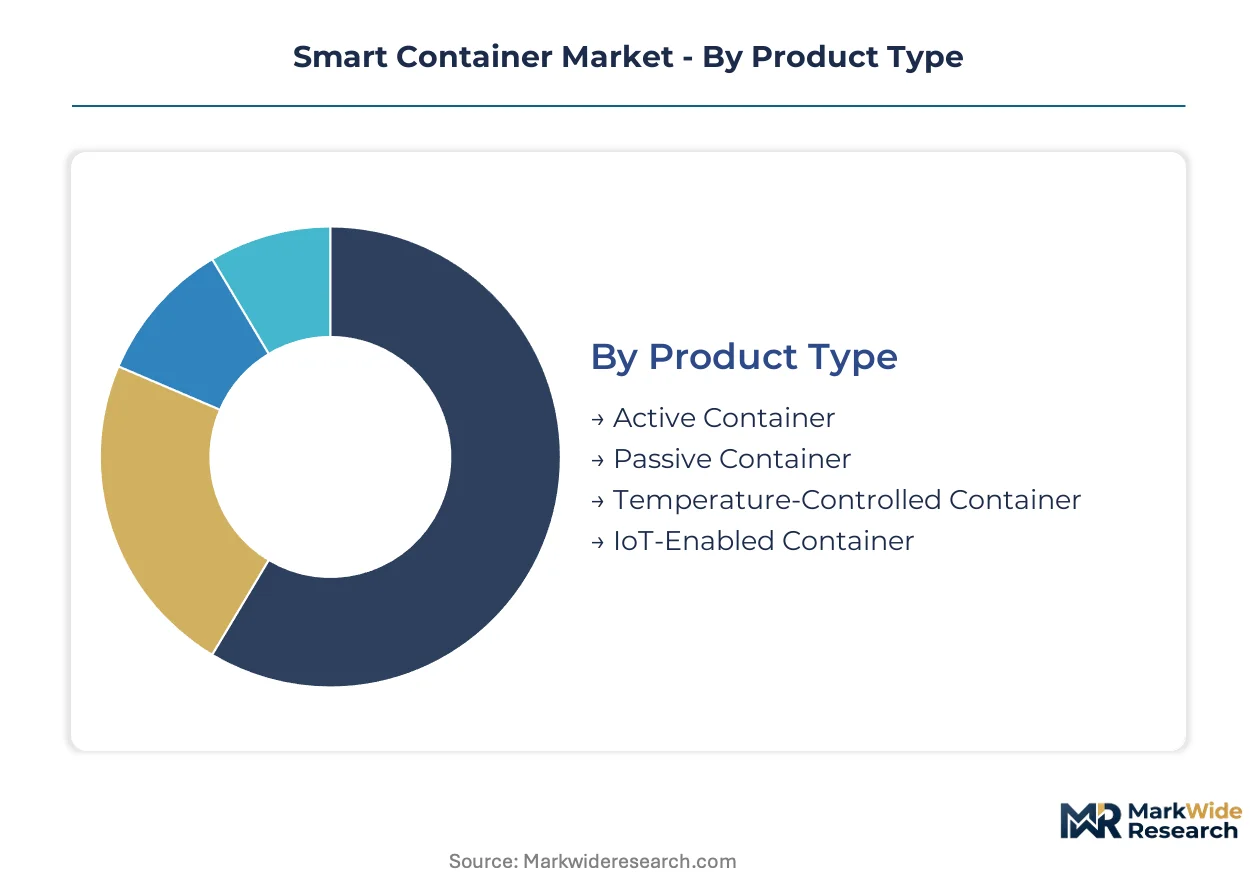
Smart container segmentation reveals how hardware specifications, connectivity protocols, and cargo requirements fragment procurement patterns across maritime logistics. Technology choices determine capital intensity and operational visibility, while end-use verticals dictate sensor density and compliance specifications.
Product Type:
Hardware architecture separates containers by power dependency and environmental control capability, with active systems commanding premium positioning against passive alternatives.
- Active Container:Self-powered refrigeration units with integrated compressor systems maintain precise thermal setpoints across extended transits. Pharmaceutical distributors in Germany deploy these for biologics moving through Hamburg port corridors, where EU F-Gas Regulation mandates refrigerant documentation alongside cargo manifests.
- IoT-Enabled Container:Embedded cellular and satellite modules transmit location, shock, and door-status data in real time, replacing manual inspection with automated exception alerts. Declining module costs are accelerating fleet-wide deployment across trans-Pacific lanes where carrier-controlled equipment now exceeds third-party leasing volumes.
- Passive Container:Insulated designs relying on phase-change materials or dry ice eliminate mechanical complexity for shorter transits. Fresh produce exporters in Latin America favor these for cost-sensitive routes where journey duration stays within thermal mass limits.
- Temperature-Controlled Container:Hybrid architectures combining active cooling with smart monitoring serve perishable verticals requiring both environmental stability and data capture. Reefer segments serving Bremen distribution hubs are retrofitting with alternative refrigerants to satisfy port authority protocols.
Mature deployment sits with Passive Container designs. Newer deployment is concentrated in IoT-Enabled Container architectures.
End User:
Procurement authority clusters with entities controlling cargo risk exposure and regulatory liability across cold-chain handoffs.
- Pharmaceuticals:Temperature-sensitive biologics manufacturers mandate continuous environmental monitoring with sensor-logging documentation that satisfies FDA distribution guidelines. These buyers drive specification intensity, requiring embedded arrays that capture temperature, humidity, and shock at sub-minute intervals.
- Logistics Companies:Integrated freight operators retrofit captive fleets with sensor-enabled assets to document carbon exposure and automate exception management. Maersk Line leverages its platform to deploy units across transoceanic routes, concentrating procurement power with carrier-controlled equipment.
- Food & Beverage:Perishable exporters in Southeast Asia represent expanding demand for temperature-controlled units with compliant cooling systems entering European ports. Fresh produce shippers balance spoilage risk against capital constraints in fragmented supplier bases.
- Retailers:Large-format grocery and omnichannel distributors deploy smart containers for high-value inventory moving through intermodal networks. These buyers prioritize end-to-end visibility platforms integrating rail and road sensor networks with maritime assets.
Specification leadership sits with Pharmaceuticals. Volume scaling is concentrated in Logistics Companies.
Technology:
Connectivity and identification protocols determine data latency, infrastructure dependency, and interoperability across carrier ecosystems.
- Sensor-Based Solutions:Dense arrays measuring temperature, humidity, shock, and door status are displacing legacy barcode scanning across cold-chain applications. Edge-computing processors with onboard analytics process data locally in high-latency maritime corridors, transmitting only exception alerts.
- GPS:Satellite positioning modules provide location tracking independent of cellular infrastructure, essential for transoceanic segments outside terrestrial network coverage. These units serve routes where continuous visibility justifies higher module costs.
- RFID:Passive and active radio-frequency identification retains cost advantages in yard-management and gate-automation workflows, slowing full sensor adoption in port terminal operations. RFID persists where read-range requirements align with fixed infrastructure deployment.
- Bluetooth:Short-range wireless protocols enable low-power data exchange between containers and terminal equipment during port calls. These systems support last-mile handoff verification without satellite transmission costs.
Established deployment sits with RFID. Steepest expansion trajectory is concentrated in Sensor-Based Solutions.
Application:
Use-case segmentation reflects cargo risk profiles and regulatory scrutiny intensity across transit and stationary modes.
- Cold Chain:Continuous thermal monitoring for pharmaceuticals and perishables demands integrated sensor arrays with automated breach alerting. EU F-Gas Regulation is forcing refrigerant transitions across temperature-controlled fleets entering Hamburg and Bremen ports.
- Shipping:Maritime transit applications prioritize satellite connectivity and shock detection for high-value cargo crossing transoceanic distances. IMO emissions frameworks are mandating fleet upgrades that bundle sensor installation with efficiency improvements.
- Storage:Stationary yard and warehouse deployments leverage cellular and Bluetooth protocols for inventory positioning and condition monitoring. These applications emphasize cost minimization over real-time alerting.
- Hazardous Materials:Specialized containers for chemical and flammable cargo integrate leak-detection sensors and pressure monitoring with stringent documentation requirements. Regulatory compliance drives specification intensity in this segment.
Regulatory pressure sits with Cold Chain. Technology refresh is concentrated in Shipping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for smart container hardware clusters in China and Switzerland, while deployment intensity concentrates at European port gateways and North American distribution hubs. Consumption patterns diverge sharply between mature cold-chain corridors and emerging perishable export zones.
Germany
Pharmaceutical cold-chain logistics drive sensor-enabled container deployment through Hamburg and Bremen port clusters. The EU F-Gas Regulation mandates refrigerant documentation for all temperature-controlled units entering German ports, accelerating reefer fleet retrofits. Hamburg's container terminals now require integrated leak-detection sensors for alternative refrigerant systems handling biologics cargo.
United States
FDA distribution guidelines validate sensor-logging requirements for pharmaceutical shipments, creating compliance-driven demand for continuous environmental monitoring. The EPA oversees refrigerant phase-down timelines that align with container fleet renewal cycles. California's Los Angeles-Long Beach port complex anchors Pacific Rim smart container deployment for temperature-sensitive imports.
China
Dual carbon goals under MEE oversight are pressuring state-owned shipping lines to retrofit fleets with emissions-tracking sensor arrays. Manufacturing scale for IoT modules and edge-computing processors concentrates in Yangtze River Delta industrial zones. Shanghai's container throughput volumes justify dedicated smart terminal infrastructure for automated gate verification.
Switzerland
Low-power asset tracking R&D concentrates around Zurich and Geneva technology clusters serving intermodal network operators. Swissmedic pharmaceutical distribution standards exceed baseline EU requirements, driving specification intensity for temperature-controlled units. Basel's pharmaceutical logistics hub demands sub-minute interval sensor logging for cross-border biologics shipments.
Singapore
Maritime transshipment volumes position the port as a deployment node for IoT-enabled containers crossing Southeast Asian trade lanes. The Maritime and Port Authority mandates digital documentation standards that align with sensor-based cargo tracking systems. Jurong Port's refrigerated container terminals are retrofitting with satellite-connected monitoring units for perishable re-exports.
Smart Container Market Key Industry Players
The competitive structure tilts toward integrated carrier platforms with captive fleet control, compressing vendor options for third-party freight forwarders. Consolidation dynamics concentrate procurement power with container lines operating proprietary IoT ecosystems. Three archetypes dominate: maritime carriers with vertical hardware integration, specialized sensor technology developers, and intermodal platform operators bundling visibility services. Dominant competitive moves include strategic technology licensing partnerships and fleet-wide retrofit programs timed to regulatory deadlines.
Among carrier-integrated platforms, Maersk Line and CMA CGM Group exemplify the captive fleet archetype, each deploying proprietary sensor networks across transoceanic routes. Nexxiot occupies a position within the specialized technology tier, anchoring low-power tracking development for intermodal applications. These three entities represent the structural divide between hardware-integrated shipping lines and component-focused solution providers.
| Leading Market Players |
|---|
| Nexxiot |
| Maersk Line |
| ORBCOMM |
| CMA CGM Group |
| Hapag-Lloyd AG |
| Traxens |
| CIMC Smart Technologies |
| Hoopo Systems Ltd. |
| Globe Tracker |
| Others |
Cost & Logistics Intelligence
The EU F-Gas Regulation gates qualified supply and premium-tier pricing access for temperature-controlled smart containers entering European ports, forcing refrigerant documentation and leak-detection sensor compliance that separates certified manufacturers from uncertified competitors.
Pricing Analysis
Value-based pricing anchored to cargo yield protection and spoilage prevention dominates pharmaceutical and perishable food verticals, with buyers paying premiums for sub-minute sensor intervals and automated breach alerting. Price differentiation hinges on certification grade for EU F-Gas refrigerant compliance and volume scale for fleet-wide retrofit programs. Pricing pressure stems from cellular module cost compression commoditizing basic IoT connectivity tiers. Small freight forwarders exhibit highest price sensitivity against integrated carriers with captive fleet economies.
Supply Chain Analysis
Certification and qualification gating for EU F-Gas refrigerant systems and FDA sensor-logging documentation concentrates qualified supply among established hardware-integrated carriers. Manufacturing clusters in China supply IoT modules and edge-computing processors, while Switzerland anchors low-power tracking R&D and Germany hosts pharmaceutical distribution hub deployment. Supply chain risk centers on single-source vulnerability for satellite connectivity modules. Distribution runs through carrier-controlled equipment pools and third-party leasing networks serving fragmented freight forwarder demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart container supply is tightening around qualified refrigerant-system manufacturers and certified sensor-integrators, with EU F-Gas retrofit deadlines compressing available production capacity and propping pricing for compliant units.
For Market Incumbents: Acquire specialized low-power tracking R&D capabilities to close intermodal visibility gaps against emerging platform competitors. Incumbent carriers must defend against proprietary ecosystem fragmentation by investing in backward integration of edge-computing processor design, securing hardware engineering talent scarce in traditional container manufacturing. Certification investment for EU F-Gas alternative refrigerant systems creates switching costs that lock pharmaceutical distributors into qualified supply relationships.
For New Entrants and Emerging Players: Direct-to-freight-forwarder digital sales channels bypass carrier-controlled equipment pools that now dominate trans-Pacific procurement. White-space opportunity concentrates in Latin American fresh produce exporters and Southeast Asian perishable re-export hubs where sensor-enabled cold-chain penetration lags pharmaceutical corridors. Target intermodal rail-road integration partnerships as the most penetrable application, offering end-to-end visibility platforms that maritime carriers have not yet bundled.
For Investors and Strategic Acquirers: IMO emissions framework retrofit deadline announcements are the leading indicator that fleet-wide sensor installation demand will concentrate procurement power with hardware-integrated shipping lines. Long-term viability favors carriers with captive container fleets and proprietary IoT platforms over component-focused solution providers vulnerable to platform commoditization. Watch for carrier consolidation signals that compress third-party vendor options and validate vertical integration thesis.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet-Wide Retrofit Program | EU F-Gas deadlines bundle sensor installation with refrigerant compliance across Hamburg and Bremen port corridors. |
| Backward Integration into Edge-Computing | Onboard analytics capability reduces satellite transmission costs and compresses cold-chain breach response windows. |
| Intermodal Platform Partnership | Rail and road sensor network integration creates end-to-end visibility that pharmaceutical shippers mandate. |
| Alternative Refrigerant Certification | EU F-Gas compliant cooling systems qualify carriers for German pharmaceutical distribution hub access. |
| Low-Power Tracking R&D Investment | Switzerland-based development serves intermodal networks where battery life determines deployment economics. |
Research Approach
Multi-period observation of cellular module cost trajectories, satellite connectivity adoption rates, and EU F-Gas retrofit compliance timelines anchored the trend analysis, supplemented by interviews with fleet operations directors at integrated carriers, pharmaceutical distribution logistics managers, port authority technology officers, and refrigerated container procurement leads. Secondary validation drew from IMO emissions framework documentation, EU refrigerant phase-down filings, FDA distribution guideline updates, and customs trade data for temperature-controlled container imports. Bottom-up unit deployment estimates triangulated against top-down carrier fleet size disclosures.
Input-output matrix modeling structured volume and value projections across product type, end user vertical, connectivity protocol, and application use-case dimensions throughout the forecast period. CAGRs were derived from segmented adoption curves weighted by regulatory deadline proximity and module cost elasticity. Industry-specific forecast inputs included pharmaceutical biologics pipeline expansion rates and perishable food export volume growth from Latin American and Southeast Asian origin markets.
Inputs from carrier fleet disclosure filings and port authority equipment registration databases were available through the study window; gaps in real-time deployment data from third-party leasing networks introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions regarding IMO retrofit timeline adherence and cellular cost compression continuity. A model refresh is warranted upon material change in EU F-Gas enforcement intensity or satellite connectivity pricing structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
New York Freight and Logistics Market
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
Real-Time Inventory-in-Transit Positioning Platforms Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Last-Mile Delivery Market
Logistics and Shipping
US Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
China Shipping Agency Services Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
Global Freight Broker Software Market
Logistics and Shipping
Germany Automotive 3PL Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
Italy Apparel Logistics Market
Logistics and Shipping
Germany Freight Forwarding Market