
 Italy Apparel Logistics Market | 2026-2036
Italy Apparel Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Apparel Logistics Market Insights
Premium same-day delivery specifications are collapsing the traditional three-day fulfillment window that once defined Italian apparel distribution. DHL Supply Chain Italy leverages its multi-user facility network near Milan Malpensa to sustain direct-to-consumer throughput for luxury brands. Geodis Italia anchors cross-border e-commerce flows through its Veneto hub, while Kuehne + Nagel Italy differentiates via temperature-controlled storage for delicate fabric categories.
Apparel logistics encompasses the specialized movement, storage, and fulfillment of clothing and textile products through temperature-regulated warehousing, barcode-level inventory tracking, and multi-modal transport coordination. Its primary commercial purpose is maintaining garment integrity from cut-make-trim facilities through to final consumer delivery while compressing cycle times. Transportation services dominate value capture given Italy's geographic elongation and reliance on Alpine corridor access, though warehousing is deepening automation penetration fastest as labor costs rise in Emilia-Romagna. Inventory management software is attracting disproportionate technology investment as RFID-enabled accuracy becomes mandatory for marketplace compliance.
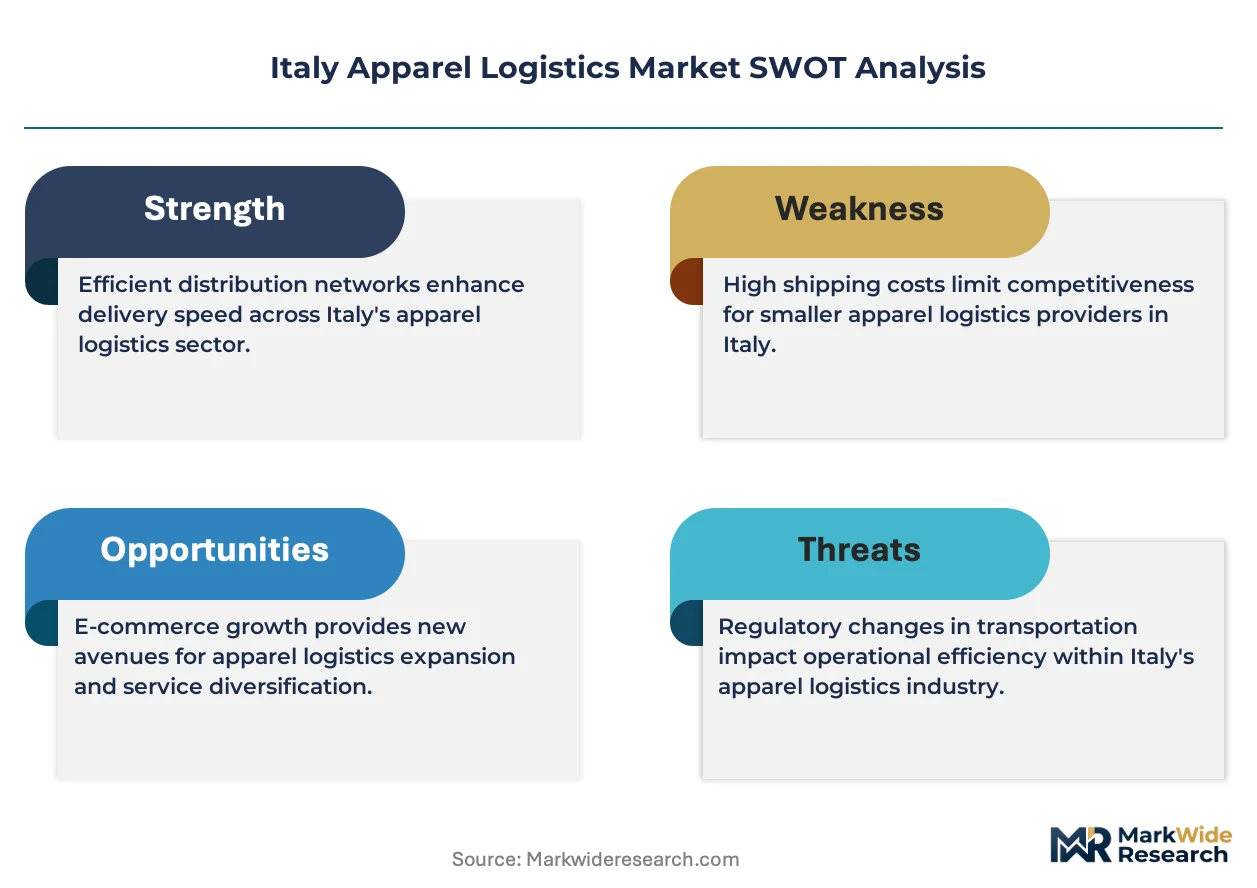
Italy's Ministry of Infrastructure and Transport governs road haulage licensing and driver qualification standards, while the EU Green Deal emissions targets are forcing fleet electrification timelines that reshape last-mile cost structures. CE marking requirements for textile handling equipment filter through to warehouse capital expenditure decisions. Stakeholders must weigh whether to build captive fulfillment capacity in the Po Valley or outsource to fourth-party operators as customs complexity intensifies with evolving EU trade defense instruments.
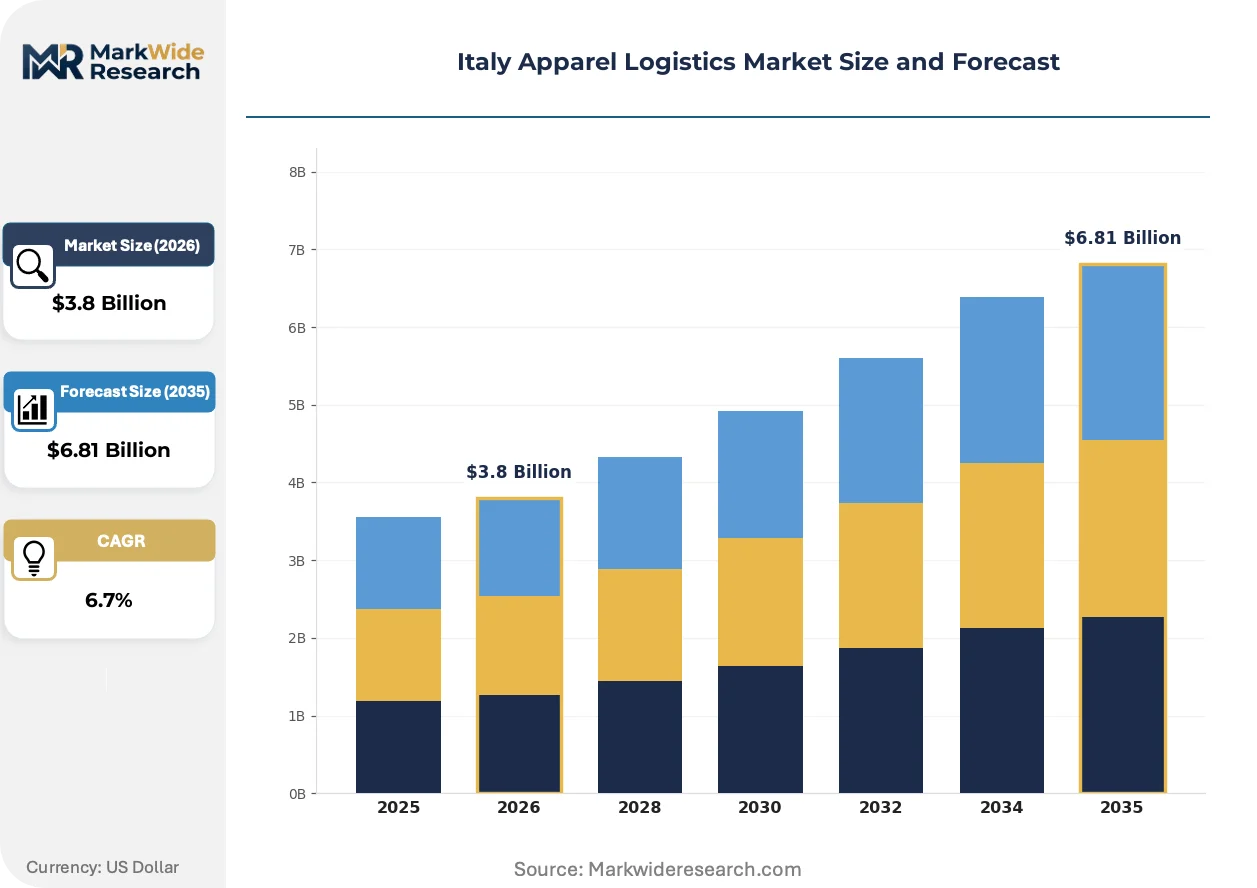
Market Dynamics
EU Green Deal emissions mandates are forcing Italian fleet operators into accelerated electrification timelines, compressing last-mile cost structures while luxury brands demand same-day fulfillment velocity that legacy three-day distribution windows cannot sustain.
Growth Catalysts
- Italy's National Recovery and Resilience Plan:Infrastructure investment channels into port modernization and digital logistics corridors, upgrading throughput capacity at Genoa and Trieste for apparel import-export flows.
- RFID-enabled inventory accuracy:Marketplace compliance mandates now require barcode-level tracking precision, driving technology adoption across Lombardy-Triveneto textile clusters.
- Omnichannel fulfillment expansion:Luxury fashion houses in Milan and Florence are building integrated direct-to-consumer networks that collapse traditional wholesale distribution layers.
Market Restraints
- Alpine corridor congestion:Brenner Pass bottlenecks create supply concentration risk for north-south freight flows, extending transit variability for time-sensitive garment deliveries.
- Battery cost volatility:Fleet electrification timelines collide with lithium-ion price instability, inflating total cost of ownership for temperature-controlled last-mile vehicles.
- CE marking compliance friction:Textile handling equipment certification delays warehouse capital deployment, particularly for automated storage systems in Emilia-Romagna.
Strategic Opportunities
- Sicily-Calabria logistics corridor:Underpenetrated southern distribution infrastructure offers first-mover positioning for brands seeking Mediterranean port access and lower labor cost bases.
- AI-driven demand forecasting:Machine learning convergence with warehouse management systems enables dynamic inventory positioning that cuts safety stock requirements for seasonal apparel.
- EU trade defense instrument adaptation:Evolving customs complexity creates white space for fourth-party logistics operators to capture compliance-intensive cross-border e-commerce flows.
Industry Challenges
- Automation technician scarcity:Warehouse robotics deployment in the Po Valley outpaces available mechatronics talent, forcing wage premiums that erode labor cost advantages.
- Legacy WMS integration friction:RFID and automated sortation systems require costly middleware development to interface with decades-old inventory platforms still operating in Veneto facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Apparel Logistics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Inventory Management, Packaging Client Type: Retailers, Wholesalers, Manufacturers, E-commerce Technology: RFID, Inventory Software, Cloud Solutions, Automation Distribution Channel: Direct, Third-Party Logistics, Dropshipping, Online Marketplace |
| Companies Covered | Kuehne + Nagel Italy, DSV Italy, Geodis Italia, Ceva Logistics Italy, UPS Supply Chain Solutions Italy, DHL Supply Chain Italy, Bollore Logistics Italy, FedEx Italy, DB Schenker Italy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Apparel Logistics Market Trends and Innovations
Digital warehouse automation is actively compressing fulfillment cycle times while regulatory emissions frameworks and shifting buyer procurement patterns simultaneously reshape capital allocation priorities across Italian logistics networks.
Autonomous mobile robots are fragmenting traditional warehouse labor models in Italy's apparel distribution centers. Mid-sized 3PL operators near Milan Malpensa are deploying AMR fleets for goods-to-person picking at twice the speed of manual cart-based workflows. This technology is fragmenting the competitive landscape by enabling smaller facilities to match the throughput volumes historically requiring mega-warehouse scale.
EU Green Deal fleet electrification mandates are restructuring Italian road haulage economics. CE marking requirements for charging infrastructure and battery thermal management systems are extending equipment procurement cycles. Temperature-controlled transport operators serving delicate fabric categories face the steepest compliance cost escalation, accelerating consolidation among specialized carriers.
Direct-to-consumer channel capture is compressing wholesale dependency among Italian luxury brands. Boutique e-commerce platforms and brand-owned apps are displacing traditional department store consignment models in the Lombardy manufacturing belt. This shift concentrates fulfillment investment in micro-fulfillment nodes within Milan's urban core, where real estate scarcity drives vertical storage innovation.
Italy Apparel Logistics Market Segmentation
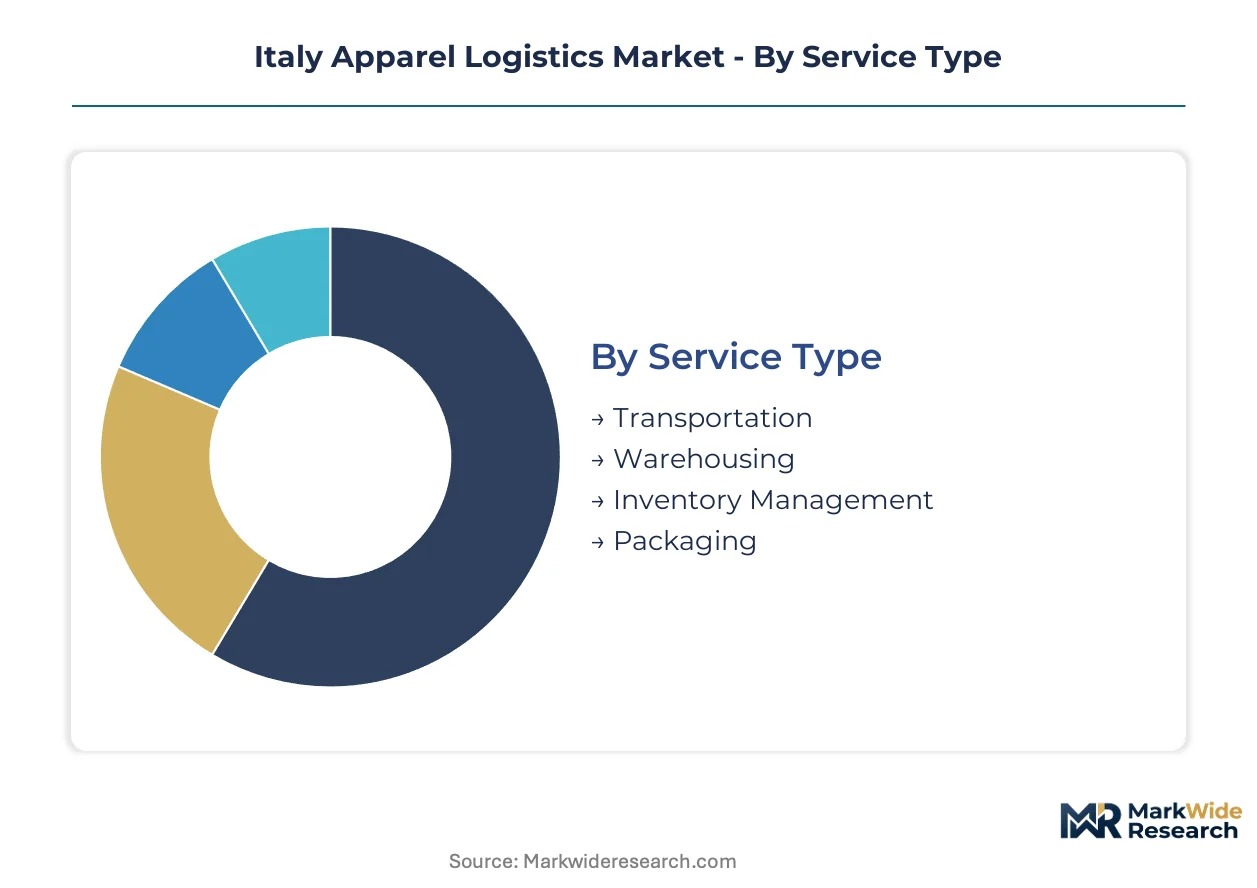
Service differentiation in Italian apparel logistics reflects divergent regulatory burdens and capital intensity requirements. Each segment category carries distinct compliance obligations under EU Green Deal mandates and Italy's infrastructure modernization programs.
Service Type:
EU Green Deal emissions frameworks impose differentiated compliance costs across service categories, with transportation facing the steepest electrification timelines.
- Transportation:Road haulage dominates value capture given Italy's geographic elongation and Alpine corridor dependence. Fleet operators serving the Lombardy-Triveneto manufacturing belt confront accelerated battery-electric conversion mandates that reshape total cost structures for temperature-controlled garment deliveries.
- Warehousing:Automated storage systems in Emilia-Romagna deepen robotics penetration fastest as labor costs rise. CE marking requirements for textile handling equipment extend procurement cycles, particularly for multi-user facilities near Milan Malpensa serving luxury brand direct-to-consumer networks.
- Inventory Management:Barcode-level tracking precision has become mandatory for marketplace compliance across Italian textile clusters.
- Packaging:Specialized garment protection systems maintain fabric integrity through cut-make-trim to final delivery.
Established volume favors transportation; emerging adoption favors warehousing automation.
Client Type:
Procurement scale and channel complexity determine logistics service configurations across buyer categories.
- Retailers:Department store consignment models in the Lombardy manufacturing belt are compressing as boutique networks displace traditional wholesale layers. Micro-fulfillment nodes within Milan's urban core concentrate investment for same-day delivery specifications.
- E-commerce:Direct-to-consumer channel capture is climbing the fastest among Italian luxury brands, with brand-owned apps and boutique platforms driving cross-border fulfillment complexity through Veneto hub infrastructure.
- Wholesalers:Traditional distribution intermediaries face margin pressure from omnichannel bypass strategies.
- Manufacturers:Cut-make-trim facilities in the Po Valley require integrated upstream logistics coordination.
Legacy volume anchors wholesale-retailer relationships; steepest expansion trajectory characterizes e-commerce direct fulfillment.
Technology:
Capital allocation priorities reflect regulatory mandates and labor scarcity pressures across Italian distribution networks.
- RFID:Tag-level inventory accuracy enables real-time positioning for seasonal apparel with compressed cycle times.
- Inventory Software:Middleware development costs burden Veneto facilities still operating decades-old warehouse management platforms.
- Cloud Solutions:Distributed data architecture supports multi-node coordination across fragmented Italian geography.
- Automation:Autonomous mobile robot deployment near Milan Malpensa achieves goods-to-person picking velocity at twice manual cart-based throughput, fragmenting competitive scale requirements.
Deployment maturity favors inventory software; capability scarcity sits with automation technician availability.
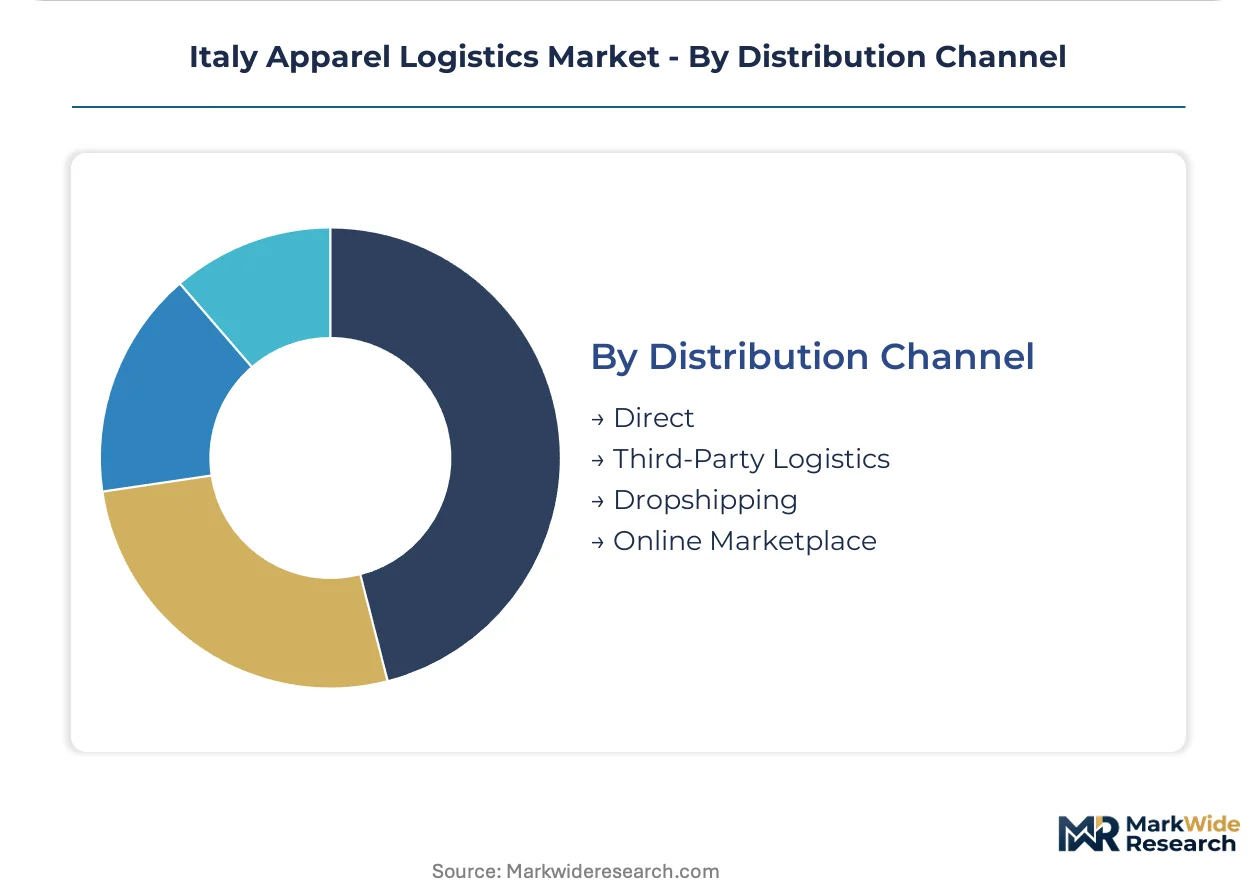
Distribution Channel:
Channel selection determines real estate strategy and customs compliance intensity for Italian apparel flows.
- Third-Party Logistics:Fourth-party operators capture compliance-intensive cross-border e-commerce as EU trade defense instruments evolve. Geodis Italia anchors international flows through Veneto hub positioning.
- Direct:Luxury fashion houses in Milan and Florence are building captive fulfillment capacity in the Po Valley to defend margin position against outsourcing premiums.
- Dropshipping:Inventory-light models reduce working capital requirements for emerging brand entrants.
- Online Marketplace:Platform compliance mandates drive RFID adoption across seller networks.
Scale concentration favors third-party logistics; strategic control priorities favor direct channel investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's apparel logistics flows reflect a structural export surplus in finished garments against raw material import dependence. The Lombardy-Triveneto belt generates outbound luxury volumes while Genoa and Trieste ports handle inbound textile feeds. Regional specialization concentrates capital allocation in the northern manufacturing corridor.
Lombardy
Milan anchors Italy's luxury fashion logistics with direct-to-consumer fulfillment nodes multiplying across the urban core. The EU Green Deal drives fleet electrification mandates for last-mile operators serving same-delivery specifications. RFID-enabled micro-fulfillment centers in the Malpensa corridor fragment traditional warehouse scale requirements.
Veneto
Cross-border e-commerce throughput climbs fastest through Veneto's hub infrastructure feeding Central European markets. CE marking compliance for automated textile handling equipment extends procurement cycles for regional 3PL operators. Treviso and Vicenza textile clusters demand temperature-controlled storage integration for delicate fabric categories.
Emilia-Romagna
Automation penetration deepens fastest here as labor cost escalation outpaces other northern regions. Italy's National Recovery and Resilience Plan channels infrastructure investment into Bologna's intermodal freight terminals. Warehouse robotics deployment confronts technician scarcity, forcing wage premiums that erode historical cost advantages.
Tuscany
Florence luxury houses expand captive fulfillment capacity to defend margin position against outsourcing premiums. The Brenner Pass bottleneck creates transit variability for time-sensitive garment deliveries to Alpine markets. Prato's textile district requires integrated upstream logistics coordination from cut-make-trim facilities.
Sicily
Underpenetrated southern distribution infrastructure offers first-mover positioning for Mediterranean port access. Palermo and Catania terminals remain below capacity utilization versus northern counterparts. Lower labor cost bases attract brands seeking to diversify supply concentration risk from the Po Valley.
Italy Apparel Logistics Market Competitive Landscape
Concentration sits with integrated global 3PL operators possessing multi-user facility networks and customs brokerage depth. The vendor base spans three tiers: global integrated logistics providers, regional specialists with vertical expertise, and niche last-mile operators. Scale advantages accrue to players with captive air freight capacity at Milan Malpensa and Genoa port terminals. Competitive moves center on automation capital deployment and strategic partnerships with luxury brand houses for captive fulfillment contracts.
Among global integrated providers, DHL Supply Chain Italy, Kuehne + Nagel Italy, and Geodis Italia represent the dominant archetype. DHL Supply Chain Italy exemplifies multi-user facility scale near Milan Malpensa. Kuehne + Nagel Italy occupies a position differentiated by temperature-controlled storage capabilities. Geodis Italia anchors cross-border flows through Veneto hub positioning, reflecting the regional specialization pattern visible across the competitive set.
| Leading Market Players |
|---|
| Kuehne + Nagel Italy |
| DSV Italy |
| Geodis Italia |
| Ceva Logistics Italy |
| UPS Supply Chain Solutions Italy |
| DHL Supply Chain Italy |
| Bollore Logistics Italy |
| FedEx Italy |
| DB Schenker Italy |
| Others |
Pricing and Supply Chain Analysis
Three-day fulfillment windows collapsing to same-day specifications concentrate pricing power among operators with Milan Malpensa air freight access and automated last-mile fleets. This compression rewards integrated providers while squeezing margin pools for asset-light intermediaries dependent on third-party capacity.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across temperature-controlled transport tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU Green Deal fleet mandates and volume scale commitments. Cost compression in last-mile electrification is intensifying because lithium-ion battery price volatility inflates total cost of ownership for specialized garment vehicles. Boutique e-commerce platforms exhibit highest price sensitivity given working capital constraints, while captive luxury brand networks demonstrate lowest sensitivity due to margin preservation priorities.
Supply Chain Analysis
China, Bangladesh, and Vietnam anchor upstream textile and cut-make-trim production feeding Italian finishing facilities. The Lombardy-Triveneto manufacturing belt draws from raw cotton, synthetic fiber, and dye chemical inputs sourced through Genoa and Trieste port terminals. Single-source vulnerability concentrates in Alpine corridor dependence for north-south freight flows, where Brenner Pass bottlenecks create transit variability. Distribution runs through multi-user 3PL facilities near Milan Malpensa for direct-to-consumer fulfillment, with cross-border e-commerce flows anchoring through Veneto hub infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nearshoring acceleration from Balkan and North African production zones threatens Italian apparel logistics incumbents with volume diversion and corridor bypass. Substitution defense requires automation differentiation and southern corridor preemption.
For Market Incumbents: Compound automation capital deployment in Emilia-Romagna to offset technician scarcity wage premiums. Secure captive fulfillment contracts with Florence luxury houses before southern corridor infrastructure matures. Vertical integration into Sicily-Calabria port terminals addresses supply concentration risk from Po Valley dependence. For New Entrants and Emerging Players: Anchor in underpenetrated southern distribution infrastructure where Palermo and Catania terminals operate below capacity. Target temperature-controlled storage specialization for delicate fabric categories where Kuehne + Nagel Italy's incumbent position leaves service gaps. Pursue fourth-party logistics positioning for EU trade defense instrument compliance as customs complexity intensifies. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automation scale requirements fragment mid-tier operator viability while global 3PLs capture compliance-intensive cross-border flows. Acquisition targets cluster among regional specialists with vertical expertise in luxury garment handling and Veneto hub positioning. The signal to watch is southern corridor infrastructure commitment levels under Italy's National Recovery and Resilience Plan.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Capital Deployment | AMR fleet installation near Milan Malpensa doubles goods-to-person picking velocity versus manual workflows. |
| Southern Corridor Infrastructure | Sicily-Calabria port modernization under NRRP channels captures Mediterranean access and labor cost arbitrage. |
| Temperature-Controlled Fleet Electrification | Battery-electric conversion for delicate fabric transport meets EU Green Deal mandates while defending specialized carrier margins. |
| Captive Fulfillment Contracting | Direct-to-consumer network integration with Florence luxury houses collapses wholesale distribution layer dependency. |
| Fourth-Party Logistics Positioning | Customs brokerage depth captures evolving EU trade defense instrument complexity for cross-border e-commerce flows. |
Research Methodology
Desk research of customs trade databases, EU regulatory filings, and infrastructure investment disclosures preceded structured interviews with 3PL operations directors, luxury brand supply chain managers, textile cluster procurement leads, and port authority planning officers. Primary fieldwork across Lombardy-Triveneto facilities triangulated against secondary validation from Italy's Ministry of Infrastructure and Transport publications and National Recovery and Resilience Plan progress reports. Bottom-up segment sizing converged with top-down macroeconomic anchoring.
Variance decomposition across service type, client category, technology adoption, and distribution channel dimensions structured the analytical framework throughout the forecast period. CAGRs derived from logistic growth curve fitting to historical throughput data at Milan Malpensa and Genoa terminals, with sensitivity testing against EU Green Deal fleet conversion timelines and RFID adoption curves in Veneto textile clusters.
Material uncertainties — Alpine corridor congestion escalation, lithium-ion price volatility, and CE marking compliance delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding infrastructure investment continuity and luxury brand omnichannel commitment levels. Recalibration cycles align with material shifts in NRRP disbursement schedules and EU trade defense instrument final determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Qatar Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
ISO Shipping Container Market
Logistics and Shipping
Europe Courier, Express and Parcel (CEP) Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Hazardous Goods Logistics Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Russia Third-Party Logistics (3PL) Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Last Mile Delivery Market
Logistics and Shipping
Global Sea Air Logistics Market
Logistics and Shipping
Texas Freight and Logistics Market