
 Global Automated Container Terminal Market | 2026-2036
Global Automated Container Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Container Terminal Market Analysis
Chinese crane manufacturing capacity is hardening as domestic producers expand output for automated port infrastructure. Shanghai Zhenhua Heavy Industries leverages integrated ship-to-shore crane production to dominate Asian terminal retrofits. Liebherr Group anchors European demand with precision-engineered automated stacking cranes built at its Rostock and Killarney plants. Konecranes Plc competes through software-integrated crane fleets that reduce container handling variability across Nordic and Baltic terminals.
Automated container terminals integrate robotic cargo handling, real-time positioning systems, and terminal operating software to move containers between vessel, yard, and gate with minimal human intervention. Primary systems achieve horizontal transport speeds exceeding five meters per second and positioning accuracy within two centimeters to sustain vessel turnaround targets below twenty-four hours. Automated Stacking Cranes and Automated Guided Vehicles lead capital deployment as port operators prioritize yard density and labor reduction over remote-control alternatives. Sensor-Based Systems represent the fastest-expanding segment as lidar and radar fusion enables all-weather autonomous navigation in congested terminal environments.
The International Maritime Organization's carbon intensity regulations and the EU Green Deal's port electrification requirements are reshaping equipment procurement toward shore-power-ready and battery-assisted crane systems. China's MIIT enforces GB standards for automated port machinery safety and electromagnetic compatibility, creating compliance barriers for non-domestic suppliers. Stakeholders must monitor how port authorities balance fully automated terminal investments against semi-autimated retrofits that preserve operational flexibility during trade volume volatility.
Market Dynamics
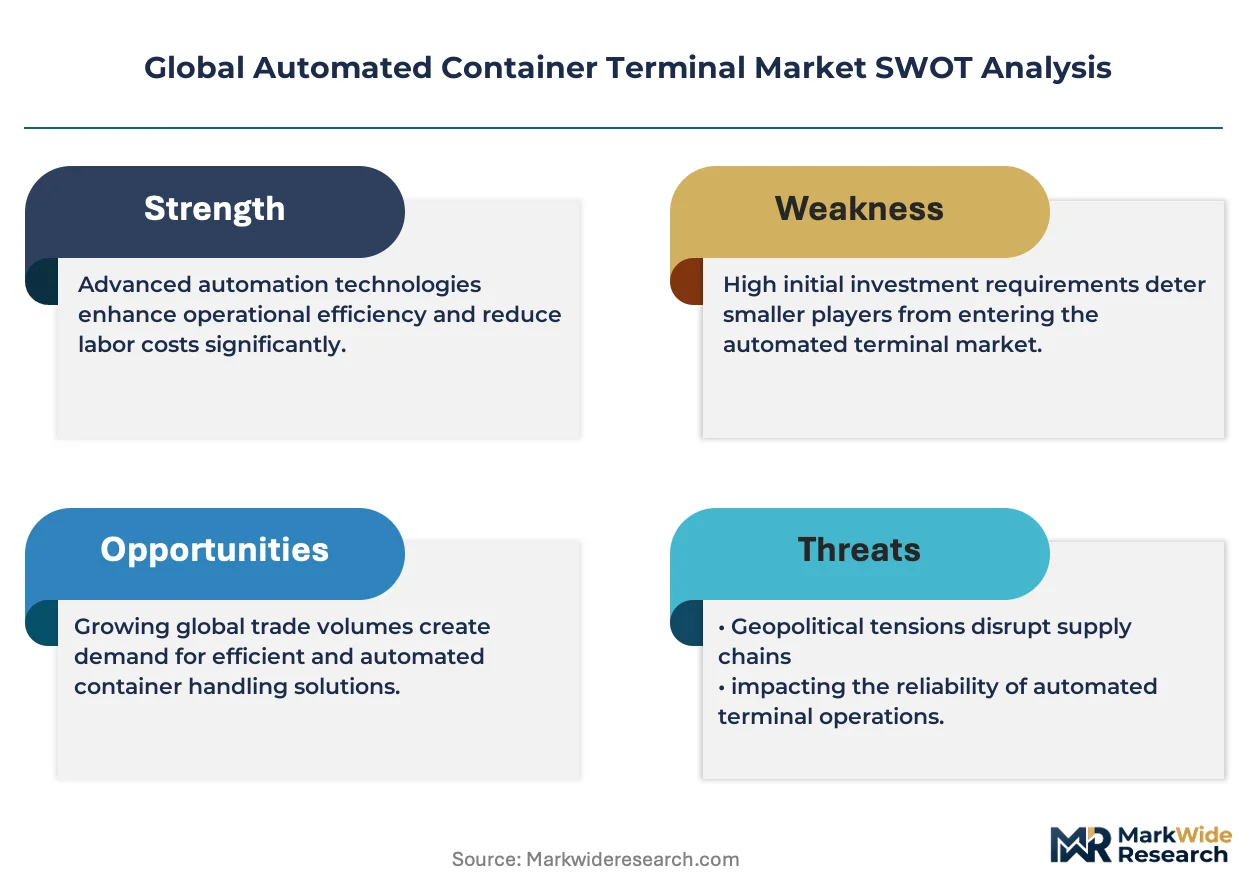
Port electrification mandates and vessel upsizing are compressing terminal design cycles, forcing operators to choose between full automation and modular retrofits within single investment windows.
Growth Catalysts
- EU Green Deal port electrification:Shore-power mandates at EU core ports are accelerating crane electrification retrofits and battery-assisted yard equipment procurement.
- Ultra-large container vessel deployment:Carriers operating 24,000+ TEU vessels require automated berth systems to sustain sub-24-hour turnaround targets at high-volume terminals.
- Horizontal transport robotics:Automated Guided Vehicles with lidar-radar fusion are automating yard shuttle operations previously handled by manned straddle carriers.
Market Restraints
- High-voltage grid infrastructure:Shore-power integration requires substation upgrades that strain port authority capital budgets and utility coordination timelines.
- Chinese crane supply concentration:Domestic manufacturers control automated stacking crane output, creating procurement bottlenecks for non-Chinese terminal operators.
- Legacy terminal footprints:Dense urban port sites lack expansion clearance for automated yard block configurations, constraining retrofit economics.
Strategic Opportunities
- Southeast Asia greenfield terminals:Vietnam and Indonesia port developments are adopting fully automated designs without legacy system integration burdens.
- AI-driven predictive maintenance:Machine learning platforms analyzing crane sensor data are reducing unplanned downtime in high-throughput terminals.
- US Inflation Reduction Act port credits:Clean energy incentives for cargo handling electrification are improving project returns at California and East Coast gateways.
Industry Challenges
- Terminal operating system integration:Synchronizing automated equipment fleets with legacy TOS platforms requires extensive middleware development and testing cycles.
- Electromechanical technician shortage:Ports compete for scarce talent capable of maintaining hybrid diesel-electric and fully electric crane systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Container Terminal Market |
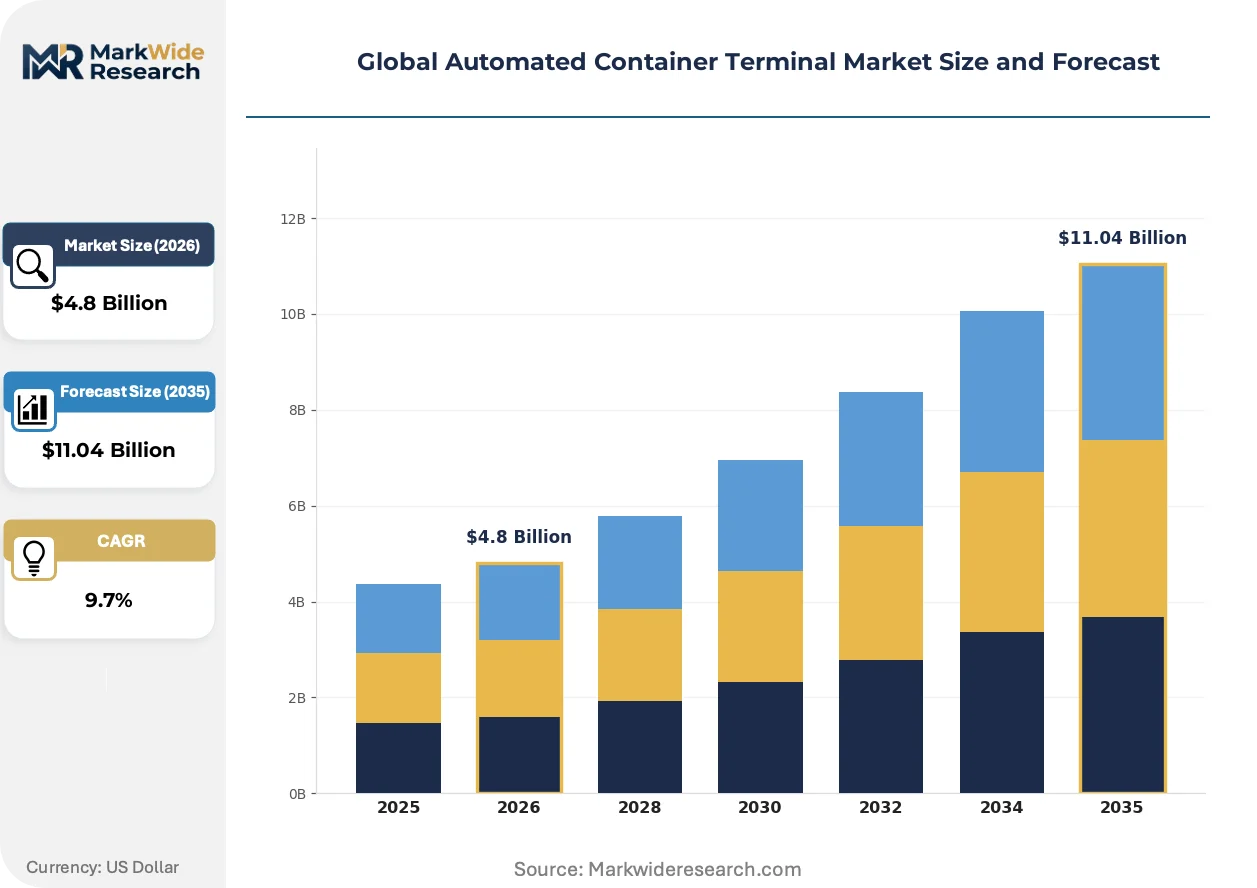
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automated Stacking Cranes, Automated Guided Vehicles, Remote Operated Terminals, Sensor-Based Systems End User: Shipping Lines, Port Authorities, Freight Forwarders, Logistics Providers Operational Type: Fully Automated, Semi-Automated, Manual Override, Remote-Controlled Service Type: Maintenance, Software Development, Consulting, Integration Solutions |
| Companies Covered | Shanghai Zhenhua Heavy Industries Co., Ltd., Liebherr Group, Konecranes Plc, Cargotec Corporation, ABB Ltd., Künz GmbH, CyberLogitec, Siemens AG, IDENTEC SOLUTIONS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Container Terminal Market Emerging Trajectories
Digital twin platforms and sensor fusion architectures are compressing commissioning timelines for automated terminals while enabling real-time optimization of vessel-to-yard workflows.
Lidar-radar fusion systems are automating all-weather navigation for Automated Guided Vehicles in congested yard environments. Terminal operators at Rotterdam and Singapore are deploying these sensor arrays to maintain throughput during precipitation and low-visibility conditions. The technology is automating safety envelope management around manned equipment and pedestrian zones, reducing incident-related operational pauses.
China's MIIT GB standards for automated port machinery safety and electromagnetic compatibility are reshaping equipment certification requirements. Domestic manufacturers gain compliance advantages while foreign suppliers face extended testing protocols. European and Japanese crane builders are responding with dedicated China certification engineering teams and localized electromagnetic testing facilities.
Performance-based service contracts are displacing traditional time-and-material maintenance agreements at major transshipment hubs. Carriers and terminal operators in the Middle East and Mediterranean are contracting equipment availability guarantees rather than component replacement schedules. This shift transfers operational risk to OEM service organizations and accelerates predictive analytics adoption.
Global Automated Container Terminal Market Segmentation
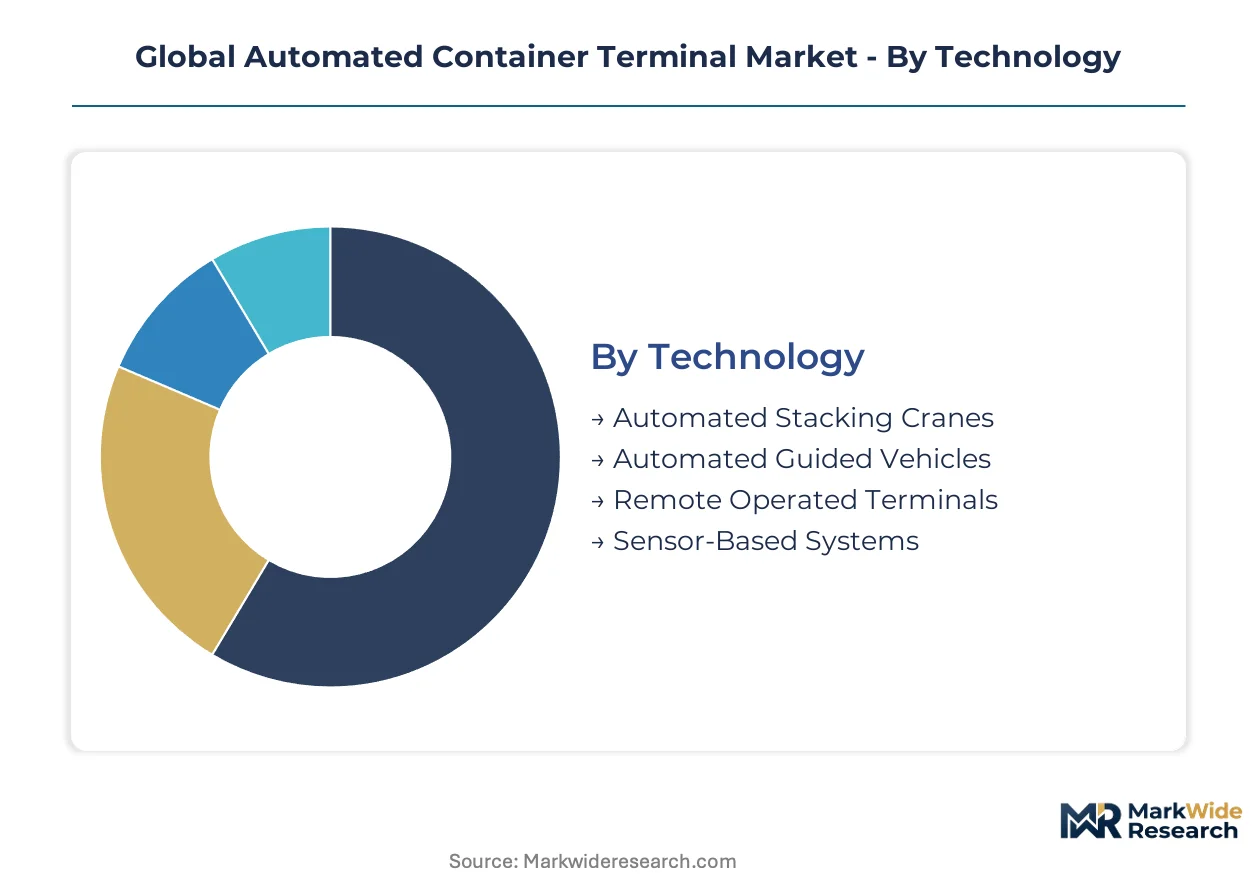
Terminal operators select automation technologies based on yard density targets, labor cost structures, and vessel size profiles. Procurement decisions cascade through technology choice, operational model, and service architecture, each tier constraining downstream options.
Technology:
Capital allocation intensity and yard throughput requirements determine equipment selection across berth and stack operations.
- Automated Stacking Cranes:These rail-mounted gantry systems stack containers up to five-high in dense yard blocks. Port authorities at Ningbo-Zhoushan and Shanghai are deploying these systems at scale to maximize land utilization against rising land costs.
- Automated Guided Vehicles:Battery-powered horizontal transport units navigate yard corridors using lidar-radar fusion. Demand concentrates at Rotterdam and Singapore terminals seeking all-weather throughput maintenance during precipitation events.
- Remote Operated Terminals:Crane operations shift to centralized control rooms with camera-assisted human oversight. European terminals favor this hybrid model to preserve operational flexibility during trade volume volatility.
- Sensor-Based Systems:Lidar, radar, and camera arrays enable autonomous navigation and collision avoidance. These systems are expanding most quickly as OEMs integrate multi-sensor fusion into new equipment platforms.
Automated Stacking Cranes lead on scale; Sensor-Based Systems lead on momentum.
End User:
Stakeholder risk tolerance and asset control patterns shape procurement authority and vendor relationships.
- Shipping Lines:Container carriers operating 24,000+ TEU vessels drive berth automation requirements to sustain sub-24-hour turnaround commitments. Maersk and MSC are specifying automated crane availability in terminal concession agreements.
- Port Authorities:Public landlords balance automation investment against long-term concession revenue and employment impacts. Hamburg and Los Angeles port authorities are negotiating automation clauses with terminal operators.
- Freight Forwarders:These intermediaries influence gate automation and data integration requirements to accelerate cargo release. Their procurement role concentrates on software interfaces rather than heavy equipment.
- Logistics Providers:Integrated supply chain operators seek terminal data feeds for inventory visibility. DHL and Kuehne+Nagel are embedding real-time container positioning into their control tower platforms.
Port Authorities dominate capital deployment; Shipping Lines set performance specifications.
Operational Type:
Automation depth reflects trade volume predictability, labor market conditions, and legacy infrastructure constraints.
- Fully Automated:Human intervention is limited to exception handling and maintenance. Greenfield terminals in Vietnam and Indonesia are adopting this model without retrofit burdens.
- Semi-Automated:Selective automation of stacking or transport functions preserves operational flexibility. Dense urban ports in Japan and South Korea favor this approach given land constraints.
- Manual Override:Automated systems retain human takeover capability for safety-critical operations. Regulatory requirements in Germany and France mandate this redundancy for crane operations.
- Remote-Controlled:Equipment operates from off-site control centers via low-latency networks. This model is gaining traction at Australian and Middle Eastern terminals seeking to decouple operator residence from port location.
Fully Automated terminals show steepest expansion trajectory; Semi-Automated retains largest installed base.
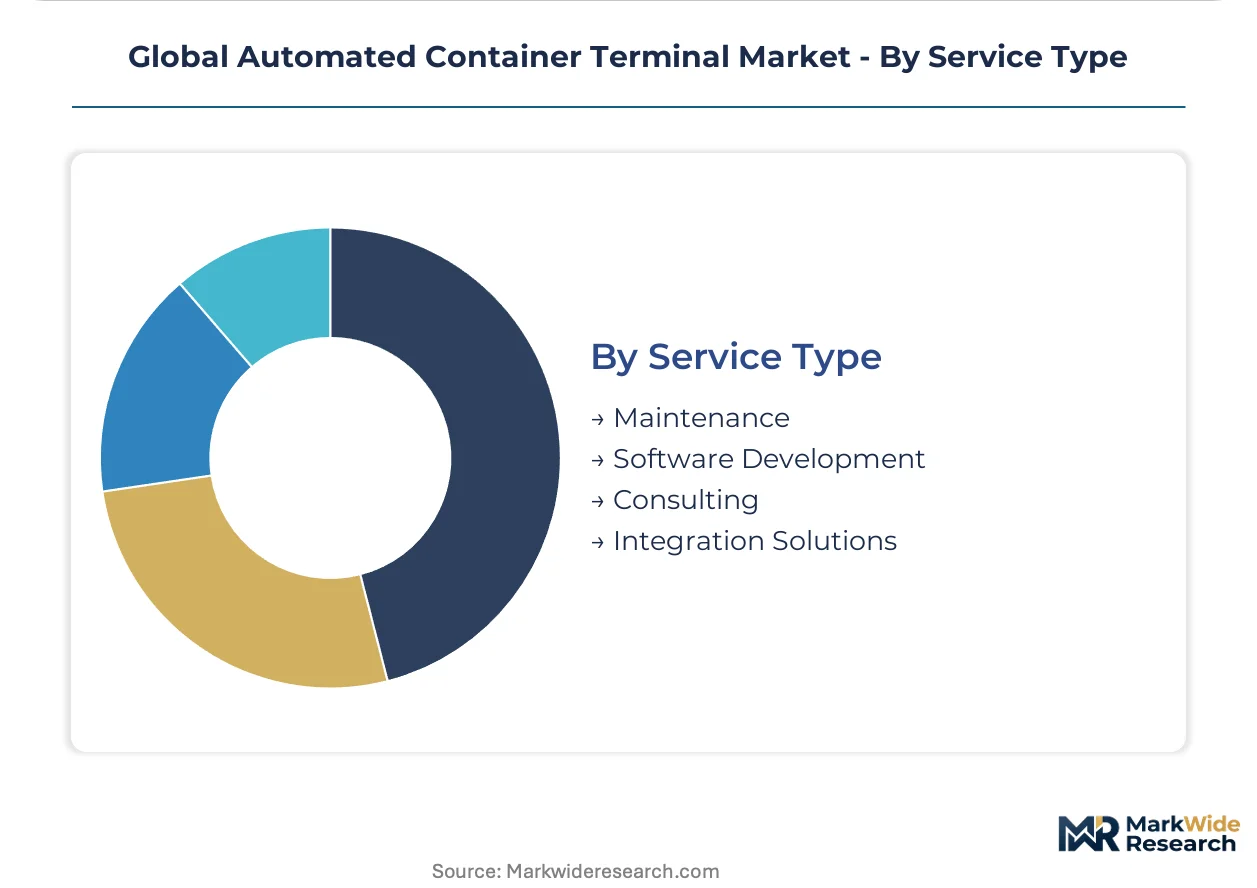
Service Type:
Post-deployment service models are shifting from time-based maintenance to outcome-based availability guarantees.
- Maintenance:Predictive service contracts analyzing crane sensor data are displacing scheduled component replacement. Middle East transshipment hubs are contracting equipment availability rather than spare parts coverage.
- Software Development:Custom terminal operating system modules integrate automated equipment fleets with legacy platforms. Vendors are embedding AI-driven optimization algorithms into standard offerings.
- Consulting:Engineering firms advise on automation feasibility, yard layout optimization, and regulatory compliance. Demand concentrates in Europe where EU Green Deal electrification mandates require specialized guidance.
- Integration Solutions:Turnkey project delivery spans equipment installation, software deployment, and commissioning. Chinese OEMs are bundling these services to accelerate overseas market penetration.
Maintenance commands recurring revenue share; Integration Solutions capture project value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting automated terminal equipment procurement toward jurisdictions with electrification subsidies and streamlined permitting. Port authorities in East Asia leverage domestic crane manufacturing scale, while European operators absorb EU Green Deal compliance costs that deter new market entrants.
China
Ningbo-Zhoushan and Shanghai ports are deploying fully automated stacking systems at scale to handle 24,000+ TEU vessels. MIIT enforces GB standards for automated port machinery safety and electromagnetic compatibility, creating compliance barriers for foreign suppliers. Domestic manufacturers at Yangshan Deep Water Port are integrating shore-power-ready crane systems under dual carbon goals mandates.
Germany
Hamburg port authority negotiates automation clauses with terminal operators while balancing employment impacts against throughput targets. EU Green Deal shore-power mandates at core ports accelerate crane electrification retrofits. Liebherr Group's Rostock engineering cluster anchors European demand for precision-engineered automated stacking cranes.
United States
California and East Coast gateways are capturing US Inflation Reduction Act port credits for cargo handling electrification projects. Los Angeles port authority structures long-term concession agreements with automation investment requirements. Pacific Northwest terminals are piloting battery-assisted yard equipment to meet state-level decarbonization timelines.
Singapore
PSA terminals deploy lidar-radar fusion AGV fleets to maintain all-weather throughput during tropical precipitation events. Maritime and Port Authority regulations mandate collision-avoidance system redundancy for autonomous yard operations. Tuas Port development is integrating fully automated berth-to-gate workflows without legacy system retrofit burdens.
Netherlands
Rotterdam terminal operators are deploying multi-sensor fusion arrays for AGV navigation in congested yard environments. EU Green Deal port electrification requirements drive shore-power infrastructure investment across Maasvlakte terminals. Dutch engineering consultancies are advising European port authorities on terminal operating system integration for automated fleets.
Global Automated Container Terminal Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue software-integrated service contracts and predictive maintenance platforms. The vendor base separates into three archetypes: integrated heavy machinery manufacturers with captive ship-to-shore production, precision-engineered crane specialists serving retrofit markets, and automation software providers bridging equipment fleets with terminal operating systems. Dominant competitive moves include strategic partnerships between crane OEMs and sensor technology suppliers, plus capacity expansion into Southeast Asian greenfield terminal projects.
Within the integrated machinery tier, Shanghai Zhenhua Heavy Industries Co., Ltd. exemplifies scale-driven production anchoring Asian terminal retrofits. Liebherr Group and Konecranes Plc represent precision-engineered and software-integrated archetypes respectively, with the former occupying position in European retrofit markets and the latter sitting within Nordic and Baltic terminal automation deployments. These three entities illustrate how geographic manufacturing concentration and service model differentiation stratify competitive positioning across procurement cycles.
| Leading Market Players |
|---|
| Shanghai Zhenhua Heavy Industries Co., Ltd. |
| Liebherr Group |
| Konecranes Plc |
| Cargotec Corporation |
| ABB Ltd. |
| Künz GmbH |
| CyberLogitec |
| Siemens AG |
| IDENTEC SOLUTIONS |
| Others |
Supply Flow & Price Mechanics
Steel price indices on the Shanghai Futures Exchange cascade through crane fabrication costs, compressing margins for European and Japanese OEMs while amplifying pricing power for integrated Chinese producers serving automated terminal retrofits.
Pricing Analysis
Distributor margins at regional equipment dealers absorb the primary margin compression from crane OEMs, with project-based contracting dominating procurement for fully automated terminal deployments. Price differentiation rests on software integration depth and shore-power certification tier, with EU Green Deal compliance adding premium tiers for electrification-ready systems. Pricing pressure stems from Chinese domestic oversupply of automated stacking cranes, forcing non-Chinese suppliers toward value-added service bundling. Terminal operators in Southeast Asia greenfield projects exhibit highest price sensitivity, while Middle Eastern transshipment hubs prioritize equipment availability guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles coordinate hub-and-spoke delivery patterns for oversized crane components requiring specialized heavy-lift logistics. Manufacturing concentrates in China, Germany, and Finland, with Chinese producers controlling automated stacking crane output and European specialists anchoring precision-engineered retrofit systems. Raw material dependencies span high-grade structural steel, rare-earth magnets for crane motors, and lidar sensor arrays. Single-source vulnerability in Chinese crane supply creates procurement bottlenecks for non-domestic terminal operators. Distribution runs through OEM-direct channels for major port authority contracts, with regional distributors serving smaller retrofit projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal electrification mandates impose compliance costs that deter new entrants, while Chinese producers leverage domestic steel and labor cost advantages to undercut European pricing.
For Market Incumbents: Extend predictive maintenance service contracts to capture recurring revenue from automated terminal operators seeking equipment availability guarantees. Deepen software integration capabilities to defend against automation software specialists encroaching on crane fleet management. Anchor production capacity in Rostock and Killarney engineering clusters to preserve proximity advantages for European retrofit demand. For New Entrants and Emerging Players: The mid-tier price gap between premium European engineered systems and economy Chinese production creates white-space opportunity for hybrid offerings with certified safety systems and modular software architectures. Target Southeast Asian greenfield terminals in Vietnam and Indonesia where legacy system integration burdens are absent. Enter through performance-based contracting models that transfer operational risk from terminal operators. For Investors and Strategic Acquirers: Asymmetric upside sits with automation software platforms bridging equipment fleets with terminal operating systems, as hardware commoditization accelerates across crane manufacturing. Long-term viability favors vendors with captive AI-driven optimization algorithms and established port authority relationships. Monitor MIIT GB standards enforcement as inflection indicator for Chinese market access barriers affecting foreign supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lidar Sensor Production | Reduces AGV procurement costs for OEMs serving Rotterdam and Singapore terminals. |
| Shore-Power Certification Program | Unlocks EU Green Deal compliance premiums at Hamburg and Los Angeles port authorities. |
| Predictive Maintenance Platform Launch | Captures recurring revenue from Middle Eastern transshipment hubs contracting availability guarantees. |
| Joint Venture with Terminal Operating System Vendor | Accelerates commissioning timelines for greenfield projects in Vietnam and Indonesia. |
| Regional Distribution Center Expansion | Compresses delivery lead times for Pacific Northwest battery-assisted yard equipment pilots. |
Methodological Framework
Multiple input streams — structured interviews with port authority planning officers, crane OEM procurement teams, and terminal operating system integration specialists — were reconciled against customs trade data, SEC equipment manufacturer filings, and EU port electrification mandate documentation. Secondary validation drew from Lloyd's List port development databases, International Maritime Organization regulatory filings, and national maritime administration statistics. Bottom-up equipment deployment tallies were triangulated with top-down terminal automation investment estimates across the analysis window.
Data-stream reconciliation anchored volume and value outputs across technology segments, operational types, and service architectures, with particular attention to electrification equipment versus conventional diesel-hybrid systems. CAGRs were derived from equipment shipment trajectories and port authority capital expenditure disclosures, incorporating vessel size class evolution and shore-power infrastructure buildout schedules as terminal automation demand drivers.
Caveats apply where MIIT regulatory enforcement intensity or EU Green Deal subsidy allocation shifts could materially shift the outlook for equipment procurement patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Netherlands Cold Chain Logistics Market
Logistics and Shipping
Saudi Arabia Integrated Cold Chain Logistics Market
Logistics and Shipping
Colombia Freight and Logistics Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
United States Digital Freight Forwarding Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
Cross-Border Logistics Services Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
Australia Mining Logistics Market