
 Europe Domestic Courier Market | 2026-2036
Europe Domestic Courier Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Domestic Courier Market Insights
Poland is tilting toward automated sortation hubs and expanded road networks to capture east-west transit flows. DHL Group leverages its integrated land-air network to dominate German corridors. La Poste Group sustains rural coverage density through its bicycle and electric fleet deployment. FedEx competes on time-definite express services for corporate shippers.
Europe domestic courier services encompass the collection, transport, and delivery of documents, parcels, and pallets within national borders, utilizing land-based vehicles, aircraft, and bicycles with tracking systems and route-optimization algorithms. These services function as the circulatory infrastructure for business-to-business contracts, e-commerce fulfillment, and individual correspondence. Same-day delivery occupies the premium tier where margin pools are deepest, though next-day delivery anchors overall volume across most country markets. E-commerce retailers represent the fastest-expanding customer type, while scheduled delivery retains structural importance for industrial supply chains managing just-inventory.
The EU Green Deal and national regulators such as Germany's KBA enforce emissions standards that accelerate fleet electrification and bicycle deployment in urban zones. The EU AI Act introduces algorithmic transparency requirements for automated routing and pricing systems, affecting technology investments across carriers. Stakeholders must weigh compliance costs against operational efficiency gains as regulatory frameworks tighten around carbon intensity and data governance.
Market Dynamics
Fleet electrification mandates under the EU Green Deal are compressing capital deployment timelines while last-mile density requirements reshape hub placement strategies across national networks.
Growth Catalysts
- E-commerce fulfillment networks:Retailers are building captive distribution infrastructure that outsources trunk movements to domestic carriers while retaining last-mile control.
- EU Green Deal mandates:Emissions standards accelerate bicycle and electric van deployment in urban zones, creating new operational templates for dense delivery corridors.
- Automated sortation:Hub automation reduces per-parcel handling costs and enables later cutoff times for next-day service commitments.
Market Restraints
- Electric vehicle capital intensity:Fleet replacement cycles compress as KBA enforcement tightens, straining mid-tier carrier balance sheets.
- Driver availability constraints:HGV license acquisition timelines extend across Germany, Poland, and France, capping volume expansion in peak periods.
- Urban access restrictions:Low-emission zones in Paris, London, and Berlin fragment route planning and increase deadhead mileage.
Strategic Opportunities
- Polish corridor expansion:East-west transit volumes through Poland remain underpenetrated relative to throughput potential at automated hubs near border crossings.
- Scheduled delivery for industrial supply chains:Just-inventory management creates demand for time-definite pallet movements that command premium pricing.
- EU AI Act compliance services:Algorithmic transparency requirements for routing systems create advisory and software revenue streams for technology vendors.
Industry Challenges
- Legacy warehouse management integration:Automated sortation systems require API reconfiguration with customer ERP platforms, extending implementation timelines.
- Electrical infrastructure gaps:Depot charging capacity constraints in older urban facilities delay full fleet electrification despite regulatory deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Domestic Courier Market |
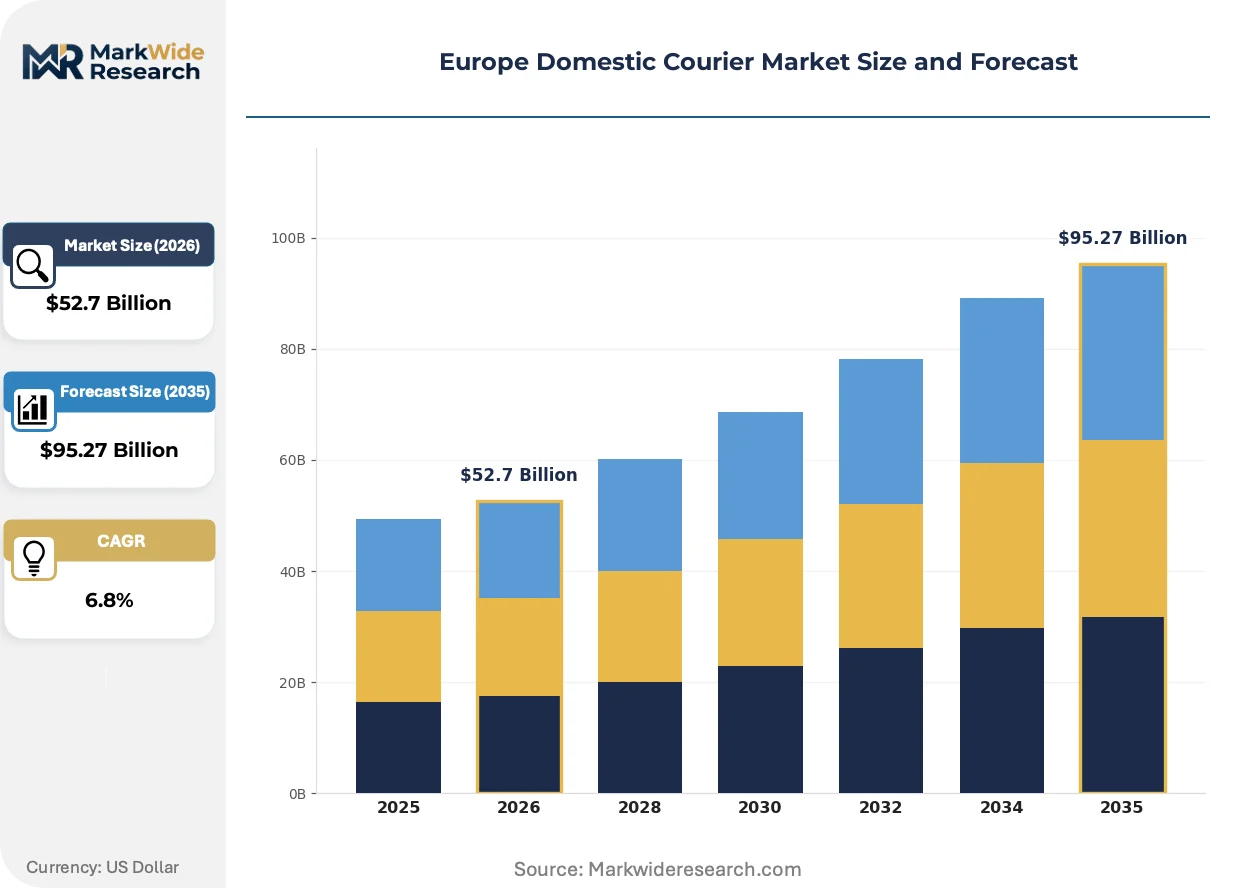
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, Express Delivery Customer Type: Individuals, Small Businesses, E-commerce Retailers, Corporations Package Type: Documents, Parcels, Pallets, Oversized Items Delivery Method: Land, Air, Sea, Bicycle |
| Companies Covered | DHL Group, International Distributions Services, La Poste Group, United Parcel Service of America, FedEx, DPDgroup, General Logistics Systems, PostNL, Bpost, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Domestic Courier Market Trends and Innovations
Digital twin technology is virtualizing network planning while regulatory pressure on emissions intensifies hardware refresh cycles. Buyer expectations for delivery precision continue compressing service windows.
Dynamic route optimization software is virtualizing traditional dispatch functions. Mid-size carriers deploy these platforms to match incumbent density without comparable fixed infrastructure. The technology compresses planning cycles from hours to minutes, enabling same-day service expansion beyond premium tiers.
The EU AI Act imposes algorithmic transparency requirements on automated pricing and routing systems. Carriers must document decision logic for regulatory audit, increasing compliance overhead. German operators face the steepest implementation curves given KBA overlap with emissions enforcement.
Scheduled delivery contracts are displacing spot-market parcel movements for industrial shippers. Manufacturers consolidate vendor relationships around carriers offering guaranteed pallet capacity and real-time inventory visibility. German automotive supply corridors exhibit the strongest migration toward contracted capacity models.
Europe Domestic Courier Market Segmentation
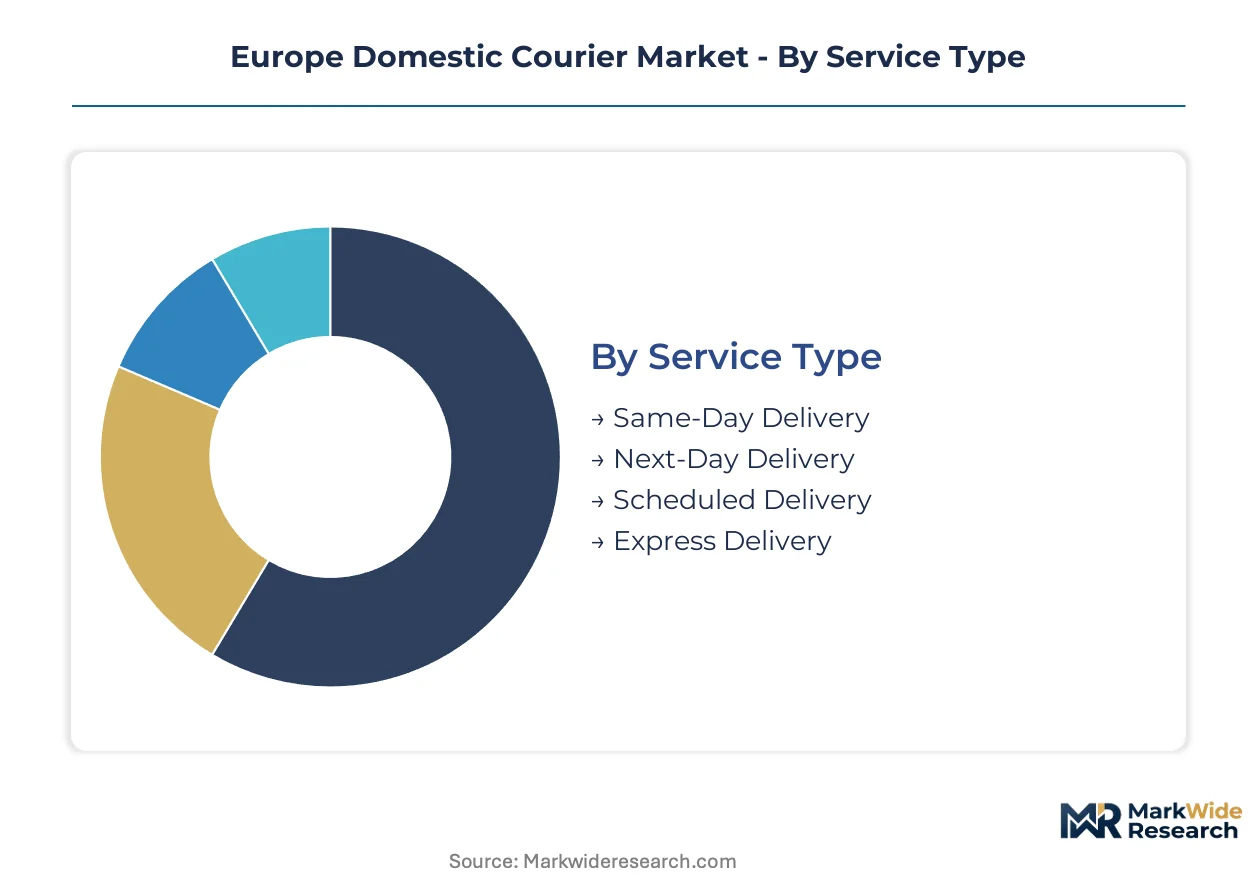
Service differentiation in Europe's domestic courier market determines capital intensity, fleet composition, and regulatory exposure. Each segment category reflects distinct operational economics that shape carrier strategy across German industrial corridors and Polish transit hubs.
Service Type:
Mature next-day networks anchor volume throughput while emerging same-day capabilities capture premium margin pools in dense urban zones.
- Same-Day Delivery:Time-critical shipments completed within hours through dedicated courier networks and dynamic route optimization. German automotive supply chains and Paris fashion retailers concentrate demand here, driven by just-inventory compression and consumer impatience penalties.
- Next-Day Delivery:Standard expedited service承诺ing delivery by the following business day via hub-and-spoke networks with automated sortation. E-commerce fulfillment centers across Poland and the Netherlands feed volume into these lanes, constrained by evening cutoff times and depot density requirements.
- Scheduled Delivery:Pre-arranged time-definite shipments for industrial supply chains managing production line feeds. German manufacturers leverage these contracts for inbound parts coordination.
- Express Delivery:Premium expedited service with guaranteed delivery windows and proactive exception management. Corporate shippers in Frankfurt and Munich sustain this tier.
Next-day delivery handles the majority of throughput; same-day delivery is gaining share fastest as urban density improves.
Customer Type:
Cost tier differentiation separates high-volume contractual relationships from transactional spot-market engagements.
- E-commerce Retailers:Digital-native merchants operating captive fulfillment infrastructure that outsources trunk movements while retaining last-mile control. Amazon and Zalando fulfillment networks across Germany and the Netherlands drive parcel density requirements, compressing carrier margins through volume concentration.
- Corporations:Large enterprises with contracted capacity agreements, dedicated account management, and integrated ERP connections. German automotive and pharmaceutical clusters in Bavaria and Baden-Württemberg anchor this segment with scheduled delivery requirements.
- Small Businesses:Mid-size enterprises with regular shipping needs but insufficient volume for dedicated contracts. These customers populate carrier retail networks and online booking platforms.
- Individuals:Occasional shippers using retail drop-off points or residential collection services. Price sensitivity here is acute.
Corporations lock in the majority of contracted revenue; e-commerce retailers are expanding most quickly as a share of total volume.
Package Type:
Application logic separates document flows from physical goods, with pallet movements commanding distinct infrastructure investments.
- Parcels:Standardized packages under 30kg moving through automated sortation hubs with barcode tracking and last-mile van delivery. E-commerce growth across German urban corridors and Polish distribution centers concentrates demand here, though dimensional weight pricing compresses yields on bulky lightweight items.
- Documents:Time-critical paper shipments requiring signature confirmation and chain-of-custody documentation. Legal and financial services in Frankfurt, London, and Zurich sustain this declining but high-yield category.
- Pallets:Unitized freight movements requiring tail-lift vehicles and dock-height infrastructure. Industrial supply chains in the Ruhr Valley and Silesian manufacturing zones drive scheduled capacity here.
- Oversized Items:Non-conforming freight exceeding standard parcel dimensions, requiring specialized handling equipment and two-person delivery crews. Furniture and appliance merchants dominate this niche.
Parcels absorb the majority of network capacity; pallets follow the steepest expansion trajectory as manufacturers consolidate vendor relationships.
Delivery Method:
Geography and regulatory pressure determine modal selection, with land dominance giving way to bicycle penetration in emission-restricted city centers.
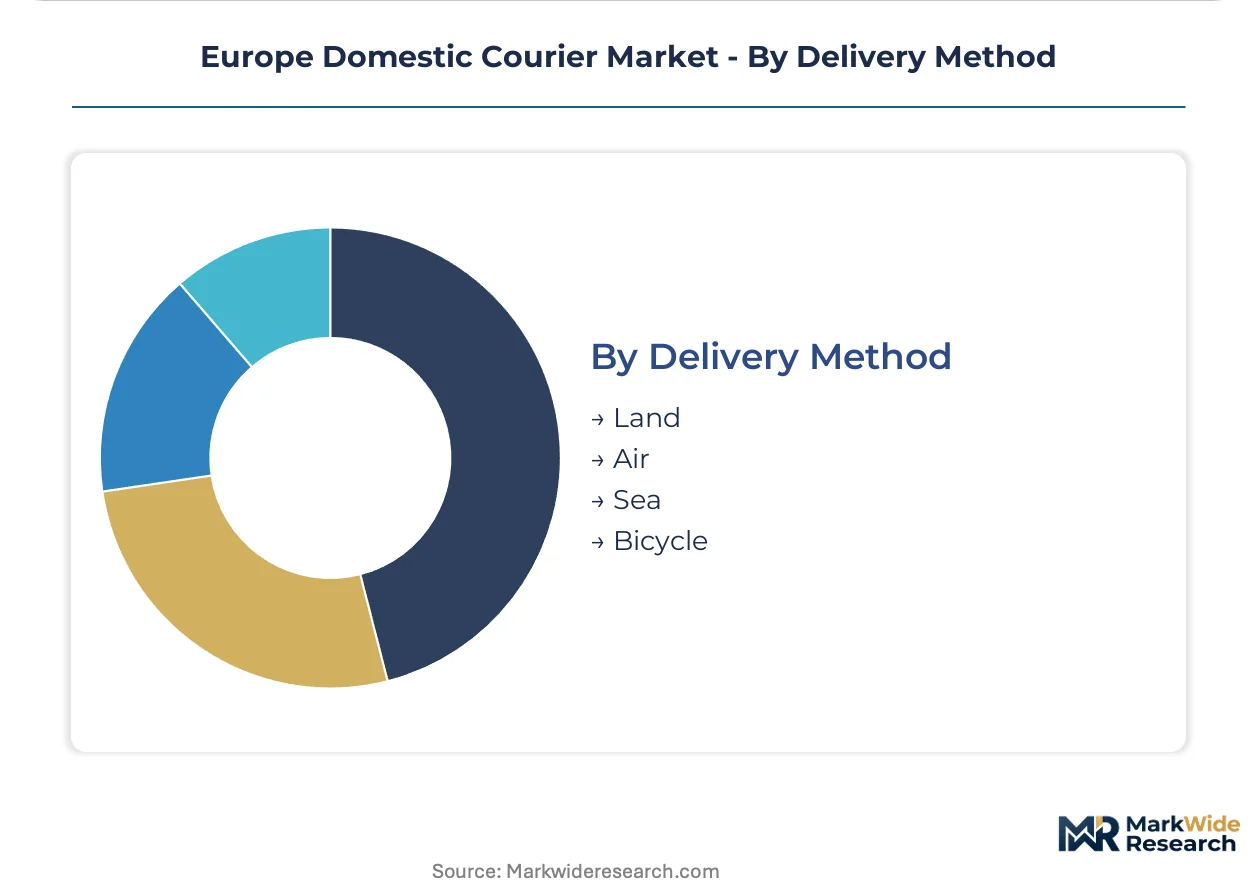
- Land:Road-based delivery via van, truck, and motorcycle fleets covering trunk, line-haul, and last-mile movements. The entire European network runs on this foundation, though KBA emissions enforcement and LEZ fragmentation in Berlin, Paris, and London accelerate fleet refresh costs.
- Bicycle:Human-powered and electric-assisted cargo bikes operating within urban low-emission zones with parking advantages and traffic immunity. Dutch and Danish cities pioneered density here; German and French regulators now mandate expansion through EU Green Deal implementation.
- Air:Domestic air freight for extreme time-critical shipments between distant metropolitan pairs. Limited applicability within compact European geography.
- Sea:Coastal and inland waterway movements for non-urgent bulk freight. Negligible share in domestic courier markets.
Land movements handle virtually all throughput; bicycle delivery is climbing the fastest as LEZ coverage expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor's rail freight arteries and the Oder-Neisse highway network underpin Europe's domestic courier density, channeling parcel flows between industrial clusters and urban consumption centers.
Germany
Automotive supply chains in Bavaria and pharmaceutical distribution from Baden-Württemberg sustain premium express volumes. KBA emissions enforcement accelerates electric van procurement timelines for carriers operating Berlin and Munich depots. The Ruhr Valley's manufacturing density supports scheduled pallet contracts with guaranteed capacity commitments.
Poland
East-west transit corridors through Silesia and Greater Poland absorb cross-border e-commerce fulfillment flows from Asian manufacturing sources. EU Cohesion Fund infrastructure grants expand automated sortation capacity at Poznań and Wrocław hubs. Warsaw's urban zone mandates bicycle delivery quotas under national Green Deal implementation.
France
Paris fashion retail and Lyon pharmaceutical clusters drive same-day service premiums in dense urban corridors. ANSM-aligned transport regulations for temperature-controlled shipments reshape fleet specifications for healthcare logistics operators. Île-de-France low-emission zones now cover 79 municipalities, fragmenting last-mile route economics.
Netherlands
Rotterdam port hinterland distribution and Amsterdam e-commerce fulfillment centers concentrate parcel density in the Randstad megalopolis. National climate agreements mandate zero-emission urban delivery zones by 2025, accelerating cargo bike fleet deployment. Eindhoven's high-tech manufacturing corridor sustains time-definite component movements for electronics supply chains.
United Kingdom
London's financial services document flows and Midlands e-commerce fulfillment warehouses anchor carrier network investments. OFCOM delivery service regulations impose minimum service standards on last-mile operators. Manchester and Birmingham logistics parks expand automated sortation capacity to handle peak-period volume surges.
Europe Domestic Courier Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The European domestic courier market exhibits consolidated structure at the national level, with three to four carriers typically controlling majority volume in each major economy. Strategic archetypes separate integrated postal incumbents with universal service obligations from asset-light technology platforms and specialized time-definite operators. Competitive moves concentrate on hub automation investments and electric fleet conversion timelines driven by regulatory deadlines.
Within the integrated postal tier, DHL Group and La Poste Group occupy positions exemplifying divergent geographic strategies—German land-air network density versus French rural coverage sustainability. FedEx represents the time-definite specialist archetype competing on service precision rather than volume scale. These three anchors illustrate how carrier positioning splits between infrastructure-heavy universal service models and premium express specialization.
| Leading Market Players |
|---|
| DHL Group |
| International Distributions Services |
| La Poste Group |
| United Parcel Service of America |
| FedEx |
| DPDgroup |
| General Logistics Systems |
| PostNL |
| Bpost |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine corridor's electrified rail-haul economics compress trunk movement costs while concentrating pricing power among carriers with depot density in German industrial clusters. EU Green Deal mandates feed through to price differentiation between emission-compliant fleets and legacy diesel operations, with KBA enforcement tightening the cost spread.
Pricing Analysis
Volume-discount tiering structures separate e-commerce retailers commanding pallet-rate negotiations from small businesses paying retail parcel tariffs. Three-tier pricing stratifies across same-day premium, next-day standard, and economy deferred service levels. Pricing pressure stems from Amazon and Zalando captive fulfillment networks squeezing carrier margins on trunk movements. E-commerce retailers exhibit acute price sensitivity; corporate scheduled delivery contracts show lowest sensitivity due to just-inventory penalty costs.
Supply Chain Analysis
Export-control regime scrutiny on automated sortation technology limits hub equipment flows from Chinese manufacturers, compressing procurement timelines for Polish corridor expansions. Supply concentration rests on German electric van production, Dutch cargo bike manufacturing, and Polish automated conveyor systems. Lithium-ion battery cells, aluminum chassis components, and routing software licenses anchor component dependencies. Single-source vulnerability sits with charging infrastructure providers for depot electrification. Distribution runs through hub-and-spoke networks with automated sortation at Poznań, Wrocław, and Ruhr Valley facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal fragmentation creates white-space opportunities as mid-tier carriers struggle with simultaneous fleet conversion and automation investments. E-commerce fulfillment outsourcing is splitting demand between trunk specialists and last-mile platforms.
For Market Incumbents: Build electrified depot density as the defensive moat against asset-light technology platforms. DHL Group and La Poste Group should accelerate Poznań and Warsaw hub automation ahead of Polish corridor volume surges. Secure exclusive charging infrastructure partnerships with municipal utilities in Berlin, Paris, and Amsterdam low-emission zones to lock out competitor fleet conversion. For New Entrants and Emerging Players: Polish east-west transit corridors offer underpenetrated volume pools relative to automated hub capacity at border crossings. Target scheduled delivery contracts for German automotive supply chains in Bavaria and Baden-Württemberg, where incumbent capacity constraints create service gaps. Deploy dynamic route optimization software to match incumbent density without comparable fixed infrastructure investment. For Investors and Strategic Acquirers: Regional bicycle-courier specialists with EU Green Deal compliance infrastructure represent the priority acquisition archetype. Long-term viability hinges on carriers navigating simultaneous KBA emissions enforcement and EU AI Act algorithmic transparency requirements. Monitor Warsaw and Berlin municipal bicycle delivery quota enforcement as inflection signals for cargo bike fleet valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Municipal charging infrastructure agreements in LEZ cities secure conversion timelines against KBA deadlines. |
| Hub Automation Investment | Polish corridor sortation capacity captures east-west e-commerce flows from Asian manufacturing sources. |
| Scheduled Delivery Contracting | Just-inventory agreements with German automotive OEMs lock in premium pallet capacity commitments. |
| Algorithmic Compliance Service | EU AI Act documentation tools create software revenue streams from transparency audit requirements. |
| Cargo Bike Fleet Expansion | Amsterdam and Rotterdam zero-emission zone mandates accelerate last-mile density without diesel restrictions. |
Research Methodology
Desk research of EU regulatory filings, national transport authority enforcement records, and carrier sustainability disclosures preceded structured interviews with fleet operations directors, e-commerce logistics procurement managers, and automated sortation equipment vendors. Primary fieldwork with DHL Group and La Poste Group network planners supplemented secondary validation through KBA emissions compliance databases and EU Cohesion Fund infrastructure grant records. Bottom-up parcel volume modeling triangulated against top-down GDP-correlation approaches.
Assumption sets held EU Green Deal enforcement timelines and KBA emissions standards fixed while varying e-commerce penetration rates and industrial inventory compression intensity across the analysis window. Segmentation dimensions modeled include service type, customer archetype, package category, and delivery modality. CAGRs derived from logistic curve fitting to historical parcel throughput data, with electric vehicle cost curves and automated sortation productivity gains as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in German industrial production indices or Polish manufacturing wage inflation would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and battery technology cost decline curves. Material shifts in EU AI Act implementation timelines or KBA zero-emission zone expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Freight Forwarding Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
Hong Kong Container Transshipment Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Europe less-Than Container Load Market
Logistics and Shipping
France Cold Chain Logistics Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Saudi Arabia Last Mile Delivery Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Roll Trailer Market
Logistics and Shipping
Hungary Freight and Logistics Market
Logistics and Shipping
Netherlands Last Mile Delivery Market
Logistics and Shipping
North America Logistics Automation Market