
 Smart Ports Market | 2026-2036
Smart Ports Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Ports Market Intelligence
A shortage of marine systems engineers familiar with AI-integrated terminal operating systems is redrawing competitive boundaries across the Smart Ports landscape. Siemens leverages its industrial automation heritage to anchor large-scale European retrofit programs. Cargotec Corporation dominates crane-to-shore connectivity through its specialized port equipment portfolio. IBM competes in the analytics layer, sustaining cloud-based vessel scheduling deployments across multiple continents.
Smart ports encompass digitally integrated maritime logistics hubs where IoT sensors, 5G connectivity, and AI analytics coordinate vessel berthing, cargo handling, and intermodal transfers in real time. These installations typically process telemetry from thousands of edge devices per terminal to optimize quay crane movements and reduce vessel turnaround intervals below twenty-four hours for ultra-large container carriers. IoT Sensors and AI Analytics represent the fastest-expanding technology pairing, as predictive maintenance algorithms cut unplanned equipment downtime by detecting bearing failures in rubber-tired gantry cranes before operational failure. Cloud-Based deployment models capture disproportionate margin pools among mid-tier ports seeking to avoid capital-intensive on-premise infrastructure while retaining scalability for seasonal volume spikes.
The EU Green Deal and F-Gas Regulation constrain refrigerant choices in cold-chain port zones while mandating shore power infrastructure for berthed vessels, directly shaping equipment procurement specifications across Rotterdam, Hamburg, and Antwerp. China's MEE enforces dual carbon goals that require Ningbo-Zhoushan and Shanghai port clusters to report granular emissions data, creating compliance-driven demand for environment monitoring application suites. Stakeholders must weigh automation capex cycles against regulatory compliance timelines as port authorities face simultaneous pressure to cut emissions intensity and expand throughput capacity without proportional labor expansion.
Market Dynamics
The collision between EU Green Deal mandates and terminal automation capex cycles is compressing investment timelines for port authorities already facing berth congestion and emissions intensity targets.
Growth Catalysts
- EU F-Gas Regulation:Cold-chain port zones in Rotterdam and Hamburg must phase down hydrofluorocarbon refrigerants, triggering equipment replacement waves that embed IoT monitoring by default.
- Shore power infrastructure mandates:China's MEE requires Ningbo-Zhoushan and Shanghai port clusters to install high-voltage connection systems for berthed vessels, creating bundled demand for power management software.
- Ultra-large container carrier proliferation:Vessels exceeding 24,000 TEU capacity require sub-twenty-four-hour turnaround protocols that only AI-coordinated crane movements can reliably deliver.
Market Restraints
- Marine systems engineer scarcity:Terminal operating systems with AI-integrated modules require specialized talent pools concentrated in Northern European and East Asian labor markets.
- Copper and rare earth magnet volatility:Electrified port equipment depends on commodity inputs subject to supply concentration from specific mining jurisdictions.
- 5G spectrum allocation friction:Mid-band licenses for private industrial networks face auction delays and coverage gaps in secondary port cities.
Strategic Opportunities
- Southeast Asian greenfield terminals:Vietnam's Cai Mep and Indonesia's Kuala Tanjung seek cloud-based deployment models to bypass capital-intensive on-premise infrastructure buildouts.
- Predictive maintenance convergence:Bearing vibration sensors fused with crane telemetry streams enable condition-based replacement protocols that compress spare parts inventory requirements.
- India's PLI scheme for electronics manufacturing:Component localization incentives attract IoT sensor assembly investments serving nearby Colombo and Jawaharlal Nehru Port Trust retrofit programs.
Industry Challenges
- Interoperability with legacy terminal operating systems:Proprietary data formats from 1990s-era mainframe deployments resist API integration with modern analytics platforms.
- Certification timeline compression:Cybersecurity frameworks for operational technology networks require recertification cycles that overlap with peak shipping seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Ports Market |
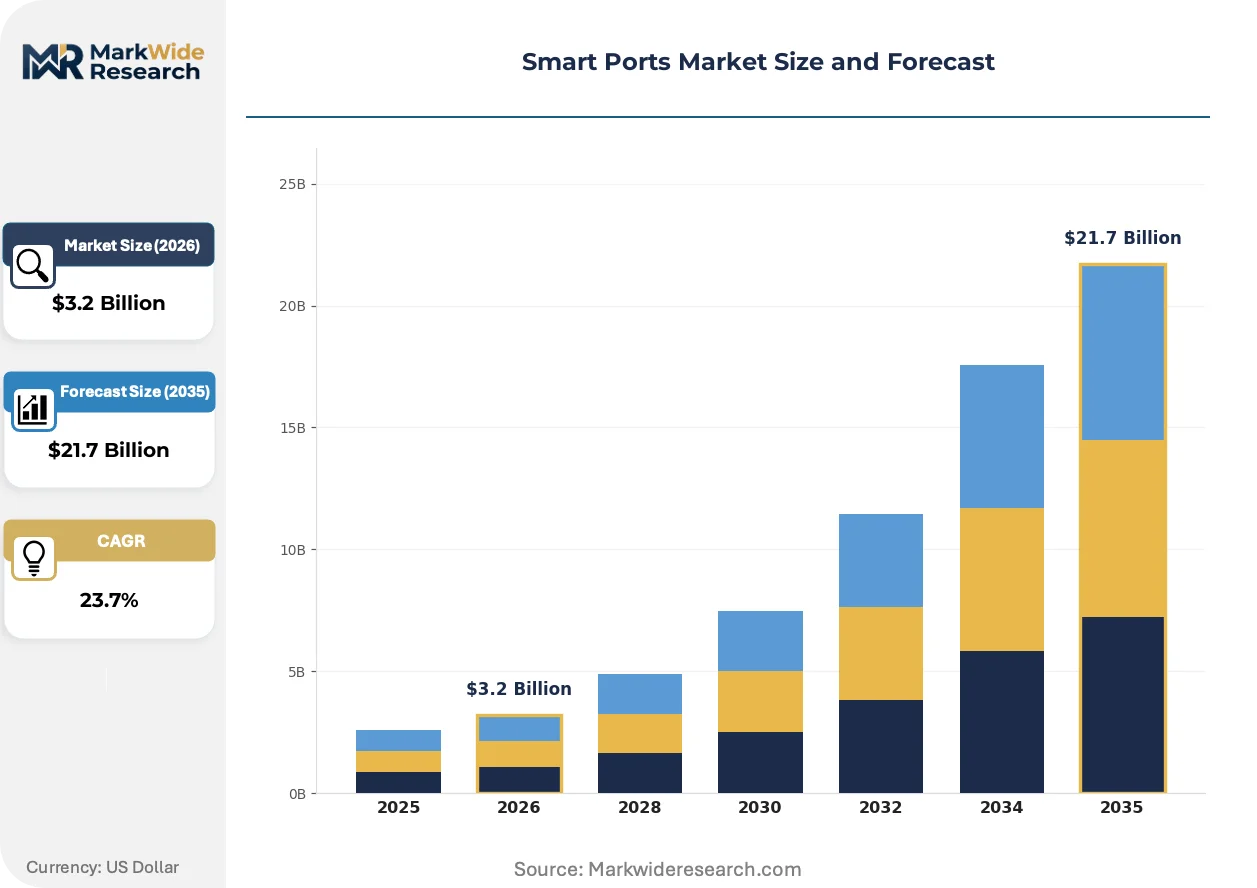
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $21.7 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, 5G Connectivity, AI Analytics, Blockchain, Robotics, Cloud Computing Application: Cargo Handling Automation, Vessel Traffic Management, Port Security, Environment Monitoring, Equipment Maintenance, Supply Chain Optimization End User: Port Authorities, Terminal Operators, Shipping Lines, Logistics Providers, Customs Agencies, Freight Forwarders Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Edge Computing |
| Companies Covered | IBM, Accenture, Siemens, ABB, GE Vernova, Royal HaskoningDHV, Trelleborg, Cargotec Corporation, Konecranes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Ports Market Strategic Shifts & Innovations
Edge-native AI inference is migrating decision latency from cloud data centers to quay-side compute nodes, enabling millisecond-scale crane coordination that batch-processed analytics cannot match.
Digital twin architectures for terminal layout simulation are supplanting static CAD-based planning tools in Singapore and Rotterdam expansion projects. Engineering consultancies now mandate real-time physics modeling for berth deepening and yard reconfiguration studies. This technology is compressing capital project approval cycles from eighteen months to under six months.
China's MEE enforcement of dual carbon goals requires Ningbo-Zhoushan and Shanghai port clusters to submit granular emissions data through standardized reporting interfaces. Equipment procurement specifications now embed continuous monitoring capabilities as mandatory technical clauses. Terminal operators respond by consolidating environment monitoring suites into single-vendor platform contracts.
Service unbundling now separates predictive maintenance algorithms from hardware supply agreements. Mid-tier ports in Malaysia and Thailand purchase crane-mounted sensor arrays from equipment vendors while subscribing to third-party analytics providers for algorithmic maintenance scheduling. This decoupling is most visible in secondary hub ports lacking captive engineering departments.
Smart Ports Market Segmentation
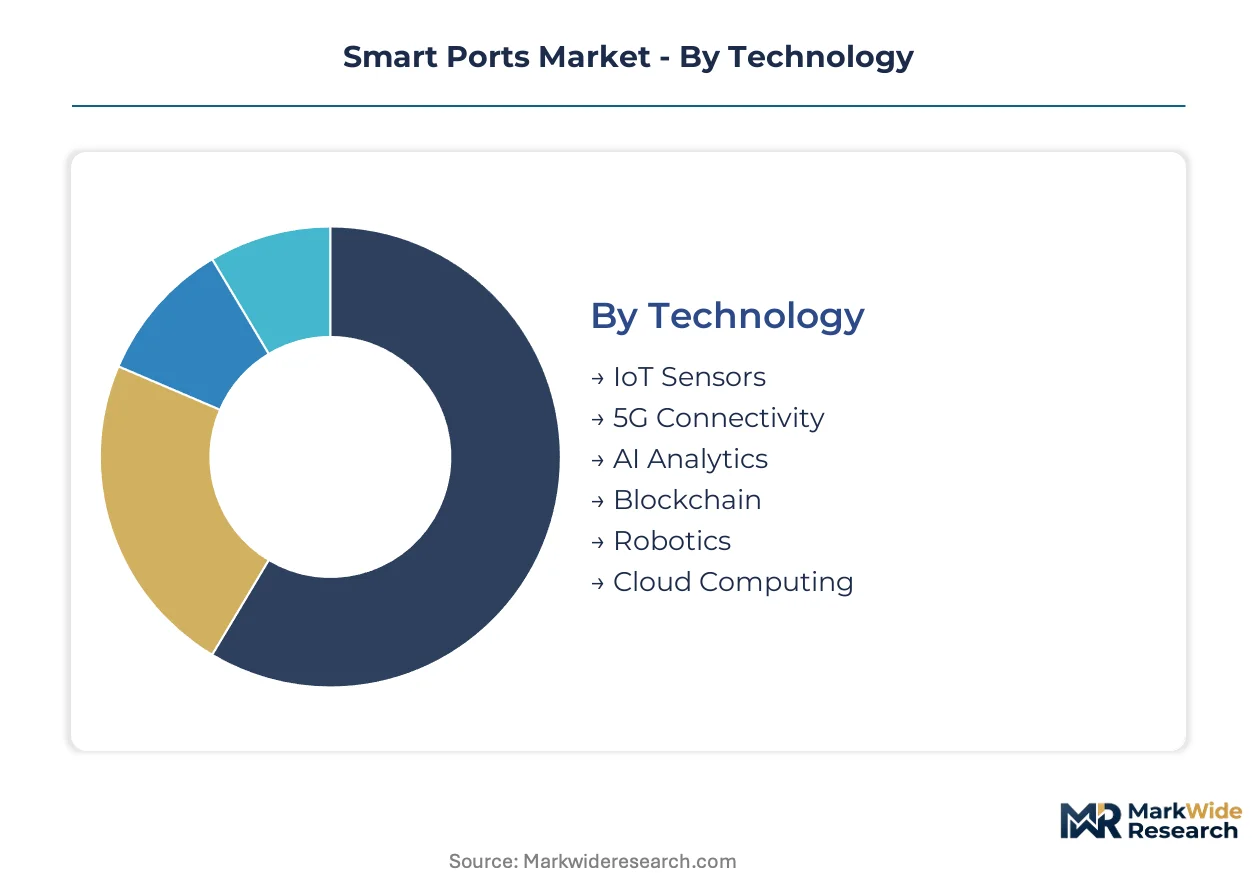
Smart ports require precise segmentation because technology choices cascade through regulatory compliance, capital intensity, and operational interoperability. Procurement committees weigh deployment models against EU F-Gas mandates and China's MEE emissions reporting requirements.
Technology:
EU Green Deal and MEE enforcement create divergent technology priorities across Rotterdam, Hamburg, Ningbo-Zhoushan, and Shanghai clusters.
- IoT Sensors:Temperature, vibration, and emissions monitoring devices embedded in rubber-tired gantry cranes and reefers. Rotterdam and Hamburg terminal operators deploy these under F-Gas Regulation mandates for hydrofluorocarbon phase-down tracking in cold-chain zones.
- AI Analytics:Predictive maintenance algorithms and vessel berthing optimization engines process telemetry streams from thousands of edge devices. Singapore and Rotterdam drive demand as ultra-large container carriers force sub-twenty-four-hour turnaround protocols.
- 5G Connectivity:Private industrial networks enabling millisecond-scale crane coordination. Spectrum allocation friction in secondary port cities constrains rollout velocity.
- Blockchain:Distributed ledger systems for customs documentation and cargo provenance tracking. Pilot deployments concentrate in Dubai and Singapore free trade zones.
- Robotics:Autonomous guided vehicles and automated stacking cranes for yard operations. Greenfield terminals in Vietnam and Indonesia favor these for labor cost arbitrage.
- Cloud Computing:Scalable infrastructure for seasonal volume spikes without capital-intensive on-premise buildouts. Mid-tier ports in Malaysia and Thailand subscribe to third-party analytics overlays.
IoT Sensors handle the majority of throughput; AI Analytics is gaining share fastest among technology pairings.
Application:
Application priorities reflect the collision between automation capex cycles and compressed regulatory compliance timelines.
- Cargo Handling Automation:AI-coordinated quay crane movements and automated yard stacking. East Asian hub ports in Singapore and Ningbo-Zhoushan deploy these to manage 24,000 TEU vessel calls without proportional labor expansion.
- Environment Monitoring:Continuous emissions tracking and refrigerant leak detection suites. China's MEE mandates granular reporting from Shanghai port clusters, embedding monitoring as mandatory procurement clauses.
- Vessel Traffic Management:Real-time berth allocation and anchorage optimization systems. Rotterdam deploys these to reduce congestion during peak shipping seasons.
- Port Security:Perimeter surveillance and container screening automation. Compliance with customs agency protocols drives adoption at Jawaharlal Nehru Port Trust.
- Equipment Maintenance:Condition-based replacement protocols using bearing vibration sensors. Service unbundling lets mid-tier ports purchase hardware from vendors while subscribing to third-party algorithmic scheduling.
- Supply Chain Optimization:Intermodal transfer coordination and dwell time reduction. Logistics providers in Colombo integrate these with hinterland rail connections.
Cargo Handling Automation commands the largest capital allocation; Environment Monitoring is expanding most quickly on regulatory compulsion.
End User:
End user procurement authority determines whether deployments prioritize throughput maximization or compliance documentation.
- Terminal Operators:Direct control of crane-to-shore connectivity and yard automation. Cargotec-equipped terminals in Singapore and Rotterdam drive standardization.
- Port Authorities:Infrastructure investment and regulatory enforcement mandates. Hamburg and Antwerp authorities specify shore power and emissions monitoring as procurement conditions.
- Shipping Lines:Vessel scheduling and berth priority negotiations. Maersk and MSC demand API integration with terminal operating systems for fleet-wide visibility.
- Logistics Providers:First- and last-mile coordination with hinterland networks. DHL and Kuehne+Nagel pilot blockchain documentation pilots in Dubai.
- Customs Agencies:Risk-based inspection targeting and duty collection automation. India's DGFT interfaces drive data format standardization at Jawaharlal Nehru Port Trust.
- Freight Forwarders:Shipment visibility and documentation aggregation. Smaller forwarders rely on cloud-based platforms to avoid IT infrastructure investment.
Terminal Operators deploy the heaviest technology stacks; Port Authorities are the fastest-moving segment on regulatory-driven procurement.
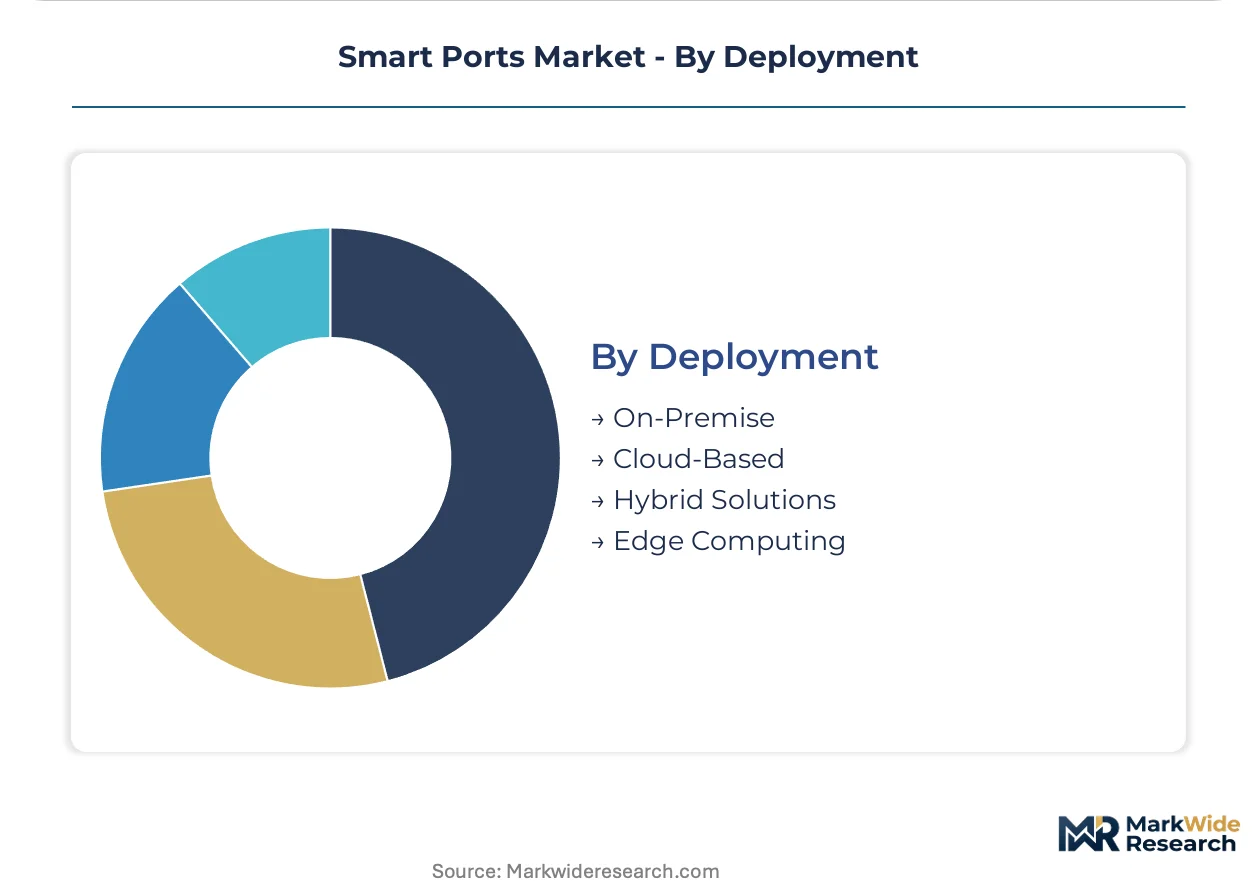
Deployment:
Deployment model selection hinges on capital availability, data sovereignty requirements, and latency sensitivity for crane coordination.
- Cloud-Based:Subscription models eliminating upfront infrastructure investment. Vietnam's Cai Mep and Indonesia's Kuala Tanjung select these to bypass on-premise buildouts while retaining scalability.
- Edge Computing:Quay-side compute nodes enabling millisecond-scale AI inference for crane coordination. Singapore's Tuas terminal deploys these where batch-processed cloud analytics cannot meet latency requirements.
- On-Premise:Captive data centers for ports with sovereignty concerns or legacy system dependencies. Hamburg maintains these for integration with 1990s-era terminal operating systems.
- Hybrid Solutions:Partitioned workloads with sensitive operations on-premise and analytics in cloud. Rotterdam uses these to balance MEE reporting compliance with operational data control.
Cloud-Based deployments capture disproportionate margin pools among mid-tier ports; Edge Computing is climbing fastest on ultra-large container carrier proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian hub ports command premium pricing for smart terminal retrofits while European greenfield installations absorb cost premiums from EU Green Deal compliance layering. This asymmetry concentrates vendor margins in Singapore and Rotterdam while compressing returns in secondary Southeast Asian markets.
China
Ningbo-Zhoushan and Shanghai port clusters anchor Asia-Pacific automation deployment as ultra-large container carriers force sub-twenty-four-hour turnaround protocols. MEE enforcement of dual carbon goals mandates granular emissions reporting through standardized interfaces, embedding environment monitoring suites into procurement specifications. Yangtze River Delta terminal operators consolidate single-vendor platform contracts to satisfy compliance timelines.
Singapore
Tuas terminal's greenfield buildout drives edge-native AI inference adoption where millisecond-scale crane coordination exceeds cloud analytics latency thresholds. The Maritime and Port Authority specifies digital twin architectures for berth deepening studies, compressing capital project approvals from eighteen months to under six. PSA International's equipment procurement favors autonomous guided vehicles for yard labor arbitrage.
Netherlands
Rotterdam terminal operators deploy IoT sensor networks under F-Gas Regulation mandates tracking hydrofluorocarbon phase-down in cold-chain zones. Shore power infrastructure requirements for berthed vessels create bundled demand for power management software across Maasvlakte expansion zones. Port Authority procurement specifications now embed continuous emissions monitoring as mandatory technical clauses.
Germany
Hamburg port authorities face compressed investment timelines as EU Green Deal mandates collide with terminal automation capex cycles and berth congestion pressures. Shore power infrastructure specifications for Elbe river terminals trigger equipment replacement waves that embed IoT monitoring by default. Legacy terminal operating systems from 1990s-era mainframe deployments resist API integration with modern analytics platforms.
Vietnam
Cai Mep terminal operators select cloud-based deployment models to bypass capital-intensive on-premise infrastructure buildouts while retaining scalability for seasonal volume spikes. Service unbundling separates predictive maintenance algorithms from hardware supply agreements as mid-tier ports purchase crane-mounted sensor arrays from equipment vendors. India's PLI scheme for electronics manufacturing attracts IoT sensor assembly investments serving nearby retrofit programs.
Smart Ports Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the Smart Ports landscape. Siemens and IBM occupy distinct competitive positions based on industrial automation heritage versus cloud-native analytics capabilities. Three archetypes dominate: industrial conglomerates with captive port equipment portfolios, pure-play software vendors with vessel scheduling platforms, and engineering consultancies with terminal simulation expertise. Strategic moves concentrate on vertical integration into sensor manufacturing and geographic expansion through Southeast Asian greenfield terminal partnerships.
Among industrial automation specialists, Siemens and ABB exemplify the integrated-systems archetype anchoring large-scale European retrofit programs. IBM and Accenture occupy positions within the analytics-layer tier, sustaining cloud-based deployments across multiple continents without captive hardware manufacturing. Cargotec Corporation represents the equipment-centric model dominating crane-to-shore connectivity through specialized port machinery portfolios.
| Leading Market Players |
|---|
| IBM |
| Accenture |
| Siemens |
| ABB |
| GE Vernova |
| Royal HaskoningDHV |
| Trelleborg |
| Cargotec Corporation |
| Konecranes |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation compliance gates supplier qualification for cold-chain IoT sensor networks while simultaneously stratifying price tiers based on refrigerant monitoring certification levels. Rotterdam and Hamburg terminal operators pay premiums for vendors bearing CE-marked emissions tracking hardware, compressing margins for uncertified alternatives.
Pricing Analysis
East Asian hub ports command 30-40% premiums over Southeast Asian mid-tier terminals for equivalent AI analytics suites. Pricing stratifies across premium, standard, and economy tiers keyed to latency sensitivity—edge-native inference commands top rates from Singapore's Tuas terminal, while cloud-based subscriptions serve Vietnam's Cai Mep. Cost compression in the standard tier is intensifying because India's PLI scheme for electronics manufacturing enables localized sensor assembly. Mid-tier ports in Malaysia and Thailand exhibit highest price sensitivity; Singapore terminal operators show least.
Supply Chain Analysis
China and South Korea anchor rare earth magnet processing and 5G base station manufacturing for port electrification equipment. Electrified crane motors draw from neodymium supply chains concentrated in Jiangxi province and Korean smelters. Single-source vulnerability runs through Malaysian wafer packaging facilities serving edge-compute chipsets. Distribution runs through Hamburg and Rotterdam as European retrofit demand aggregation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Ports market is exiting a capital expenditure trough as ultra-large container carrier proliferation forces terminal automation refresh cycles. Berth congestion and regulatory compliance timelines are compressing procurement decisions simultaneously.
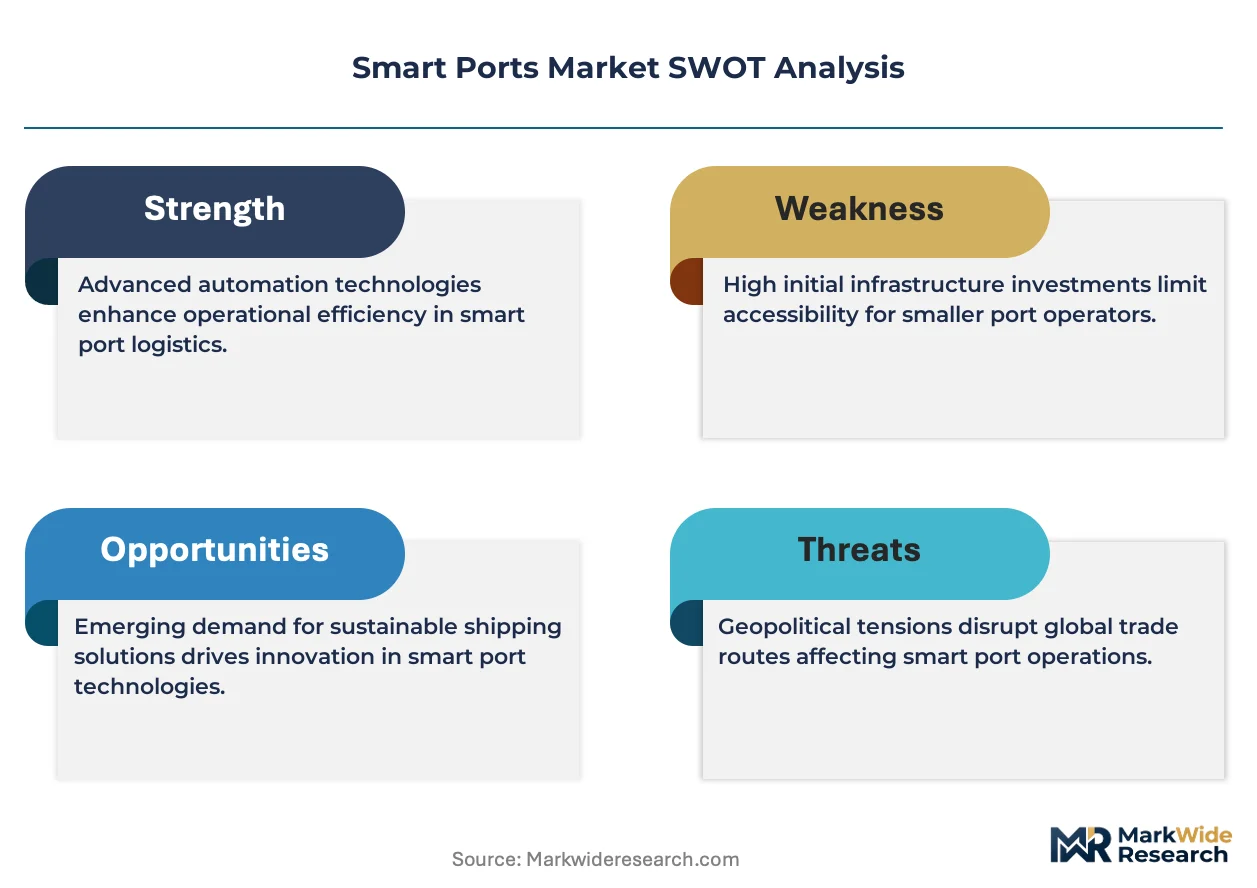
For Market Incumbents: Compound defensive moats by embedding predictive maintenance algorithms into long-term equipment lease structures, locking out third-party analytics providers. Siemens and ABB should deepen backward integration into sensor manufacturing to capture margin pools currently flowing to component vendors. Shore power infrastructure mandates across EU and Chinese ports threaten equipment-centric revenue models; incumbents must bundle power management software with hardware contracts.
For New Entrants and Emerging Players: Anchor in Southeast Asian greenfield terminals where cloud-based deployment models bypass incumbent legacy system integration advantages. Vietnam's Cai Mep and Indonesia's Kuala Tanjung present lowest competitive density for vessel traffic management platforms lacking captive engineering departments. Target service unbundling opportunities—sell crane-mounted sensor arrays while partnering with third-party algorithmic maintenance schedulers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed engineering consultancies holding digital twin simulation expertise for terminal layout optimization. Long-term viability hinges on 5-10 year automation capex cycles aligned with EU Green Deal compliance timelines. Watch MEE enforcement intensity in Shanghai and Ningbo-Zhoushan as inflection indicator—accelerated emissions reporting mandates signal consolidated platform procurement waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native AI Inference Deployment | Singapore's Tuas terminal achieves millisecond-scale crane coordination exceeding cloud latency thresholds. |
| Digital Twin Architecture Adoption | Rotterdam engineering consultancies compress capital project approvals from eighteen months to under six. |
| Service Unbundling Separation | Malaysian mid-tier ports purchase hardware from Cargotec while subscribing to IBM analytics overlays. |
| Backward Integration into Sensors | Siemens captures IoT margin pools currently flowing to third-party temperature monitoring vendors. |
| Cloud-Based Deployment Expansion | Vietnam's Cai Mep bypasses on-premise infrastructure buildouts through subscription scalability. |
Research Approach
The analysis maps IoT sensor networks, AI analytics platforms, 5G connectivity infrastructure, and digital twin architectures, each validated through terminal operating system engineers, port authority procurement officers, maritime systems integrators, and crane equipment maintenance directors. Primary interviews with these stakeholders combined with secondary validation from customs trade databases, EU F-Gas Regulation compliance filings, China's MEE emissions reporting interfaces, and SEC 10-K disclosures from listed port equipment manufacturers. Bottom-up equipment shipment tracking and top-down port automation capex surveys triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology pairings, deployment models, application priorities, and end-user procurement authority as segmentation dimensions. CAGRs were derived from equipment replacement cycle analysis and regulatory compliance timeline compression. Forecast inputs incorporated 24,000 TEU vessel proliferation rates and EU Green Deal shore power infrastructure mandates.
Decision-makers should treat outputs as directional under sustained ultra-large container carrier deployment and MEE enforcement intensity; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in F-Gas Regulation phase-down schedules and 5G spectrum auction completions in secondary port cities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Connected Parking Solutions Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Smart Roads Market
Smart Transportation Solutions
Big Data Analytics in Transportation Market
Smart Transportation Solutions
Parking Management Solutions Market
Smart Transportation Solutions
Global IoT in Transportation Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
North America Fleet Management Solutions Market
Smart Transportation Solutions
Automated Parking Systems Market