
 China less than-Truck-Load (LTL) Market | 2026-2036
China less than-Truck-Load (LTL) Market Size, Share, and Industry Trends Forecast 2026-2036
China less than-Truck-Load (LTL) Market Insights
Licensed commercial drivers with hazardous-material endorsements is reorganizing capacity allocation across China's LTL sector, tightening availability for temperature-controlled and chemical freight lanes. Deppon Logistics Co., Ltd. leverages its hub-and-spoke terminal network to dominate long-haul standard LTL corridors. SF Express (KEX-SF) anchors premium expedited shipping through integrated air-ground intermodal assets. JD Logistics controls last-mile fulfillment density via proprietary warehouse-to-depot routing algorithms.
China less than-Truck-Load (LTL) freight denotes consolidated shipments typically weighing between 50 kilograms and 3,000 kilograms, loaded alongside unrelated cargo in shared trailer space and routed through regional sorting terminals before final delivery. This logistics mode serves manufacturers and wholesalers seeking cost efficiency below full-truckload thresholds while maintaining scheduled transit reliability. Standard LTL occupies the deepest margin pool due to volume density and repeatable lane economics, though temperature-controlled services command premium rate structures from pharmaceutical and fresh-food shippers. E-commerce companies are driving fastest growth in expedited shipping segments demanding sub-48-hour provincial coverage.
SAMR enforces freight pricing transparency rules that limit predatory rate undercutting among national carriers, while MIIT mandates real-time GPS and emissions monitoring systems for cross-provincial fleets under GB standards compliance. The dual carbon goals from MEE are pressuring terminal operators to electrify yard tractors and retrofit diesel line-haul equipment. Stakeholders must weigh capital deployment toward automated sorting infrastructure against regulatory timelines for fleet decarbonization.
Market Dynamics
MIIT's real-time fleet telematics mandates are compressing operational margins for provincial LTL operators while forcing accelerated capital deployment into GPS-enabled vehicles and emissions monitoring infrastructure.
Growth Catalysts
- E-commerce freight consolidation:Mid-size parcel volumes from JD.com and Pinduoduo vendors are saturating LTL networks with scheduled pickup density that rewards hub-and-spoke terminal investments.
- Dual carbon goals:MEE electrification mandates for yard equipment are unlocking state subsidy pools for terminal operators retrofitting diesel tractors with battery-electric alternatives.
- Yangtze River Delta clustering:Manufacturing concentration across Shanghai, Jiangsu, and Zhejiang generates repeatable lane economics that amortize sorting automation across high-frequency corridors.
Market Restraints
- Licensed hazmat driver scarcity:Commercial endorsements for temperature-controlled and chemical freight are tightening capacity allocation across pharmaceutical lanes.
- GB standards compliance costs:Cross-provincial fleets face mandatory real-time GPS and emissions hardware retrofits that strain balance sheets of mid-tier operators.
- Full-truckload substitution pressure:Consolidators with captive trucking assets are poaching shippers above 1,500-kilogram thresholds that previously defaulted to LTL.
Strategic Opportunities
- Western China corridor penetration:Sichuan and Chongqing manufacturing zones remain underserved by premium expedited networks, creating whitespace for temperature-controlled lane development.
- Automated sorting convergence:Robotic parcel handling combined with AI-driven load optimization is compressing terminal dwell times for e-commerce freight.
- SAMR pricing transparency enforcement:Anti-predatory rate regulations are stabilizing margin pools for compliant national carriers against undercutting by unlicensed regional players.
Industry Challenges
- Telematics integration complexity:Legacy dispatch systems at provincial terminals require costly middleware development to interface with MIIT-mandated real-time monitoring platforms.
- Electrification capex intensity:Battery-electric line-haul tractors and charging infrastructure demand upfront deployment that conflicts with automated sorting investment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China less than-Truck-Load (LTL) Market |
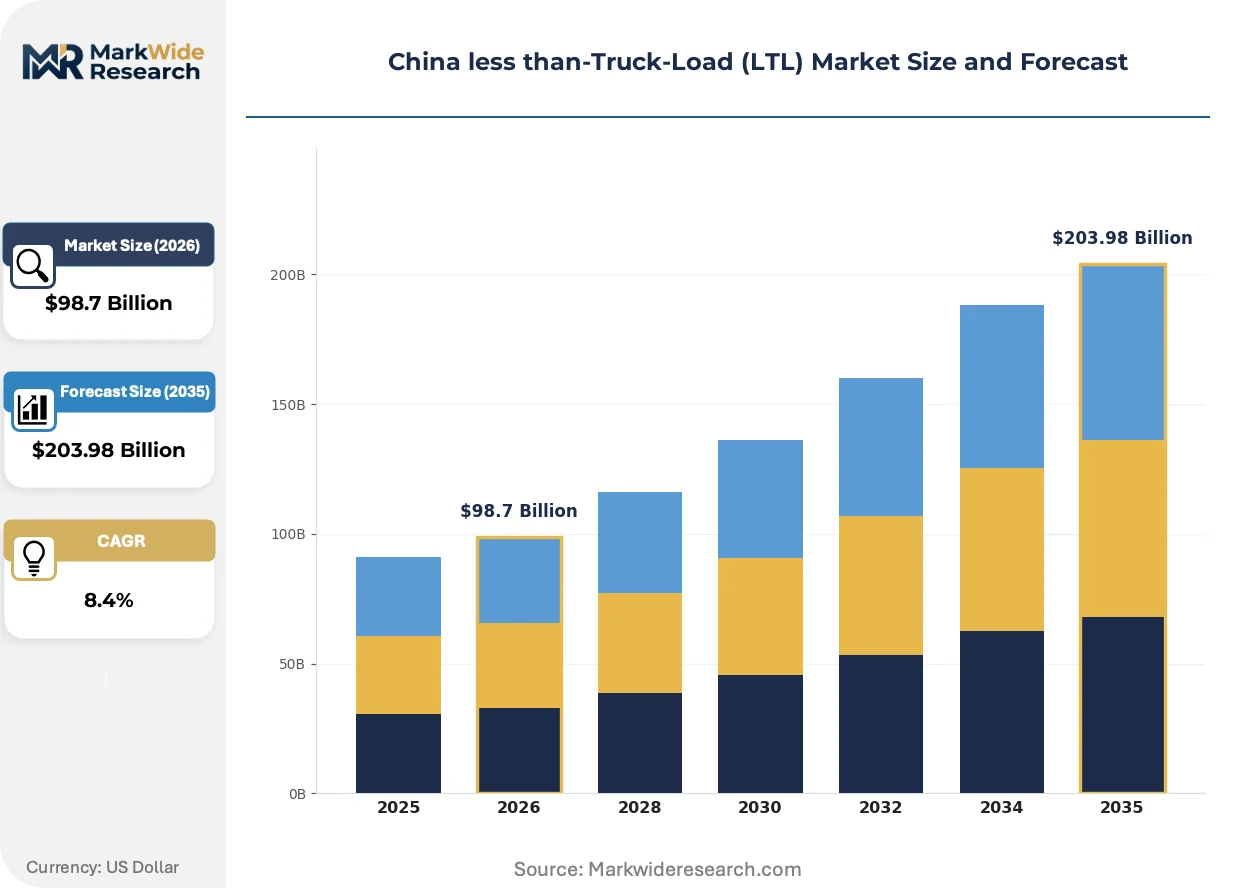
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $203.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard LTL, Expedited Shipping, Dry Van, Temperature-Controlled Customer Type: Manufacturers, Retailers, E-commerce Companies, Wholesalers Delivery Mode: Road Freight, Intermodal, Rail Delivery, Last Mile Package Type: Pallets, Boxes, Crates, Bulk |
| Companies Covered | SF Express (KEX-SF), Deppon Logistics Co., Ltd., ZTO Express, JD Logistics, Yimi Dida Supply Chain Group Co., Ltd., STO Express Co., Ltd., Shanghai Aneng Juchuang Supply Chain Management Co., Ltd., CMA CGM Group, Changjiu Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China less than-Truck-Load (LTL) Market Trends and Innovations
Digital freight matching platforms and autonomous yard vehicles are compressing traditional operational workflows while regulatory pressure on emissions accelerates equipment replacement cycles.
Edge-computing load optimization software is miniaturizing terminal decision latency. Third-party logistics providers serving automotive component manufacturers are deploying these systems at sorting hubs across Jiangsu province. The technology is miniaturizing dwell-time variance that previously required manual dispatcher intervention.
MIIT's GB standards for real-time GPS and emissions monitoring are mandating hardware retrofits across cross-provincial fleets. Terminal operators must now integrate telematics data streams with provincial regulatory reporting portals. Heavy-haul corridors connecting Guangdong manufacturing zones to inland distribution centers face the steepest compliance cost absorption.
Shippers are consolidating vendor relationships around carriers with integrated air-ground intermodal assets. Pharmaceutical distributors previously sourcing through fragmented regional brokers are now mandating single-source contracts with operators owning proprietary warehouse-to-depot routing capabilities. This concentration is most visible in Zhejiang province where fresh-food exporters demand sub-48-hour provincial coverage guarantees.
China less than-Truck-Load (LTL) Market Segmentation
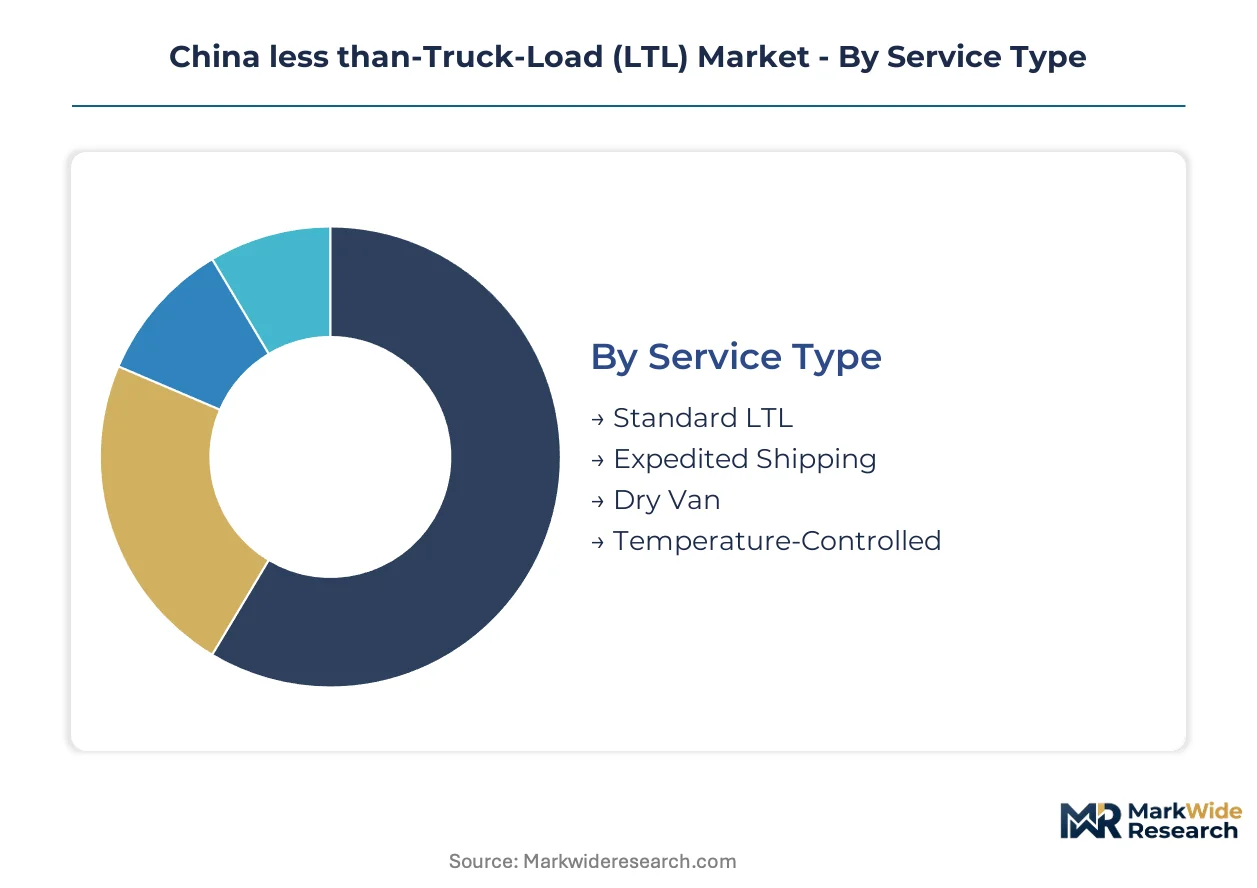
China's LTL market fragments across service tiers, customer verticals, and delivery infrastructure that determine capital allocation and margin capture. Segment boundaries shift as e-commerce consolidation and MIIT telematics mandates reshape operational requirements.
Service Type:
Domestic corridors dominate Standard LTL and Dry Van volumes, while Temperature-Controlled services feed export pharmaceutical and fresh-food lanes from Zhejiang and Jiangsu ports.
- Standard LTL:Consolidated shipments between 50 and 3,000 kilograms move through hub-and-spoke terminal networks with repeatable lane economics. Deppon Logistics leverages this density across Yangtze River Delta manufacturing clusters where scheduled pickup frequency amortizes sorting automation.
- Temperature-Controlled:Hazmat-endorsed drivers and refrigerated trailer assets serve pharmaceutical distributors and fresh-food exporters. Licensed driver scarcity tightens capacity allocation across Shanghai-Jiangsu chemical freight corridors under SAMR safety protocols.
- Expedited Shipping:SF Express anchors sub-48-hour provincial coverage through integrated air-ground assets for e-commerce fulfillment.
- Dry Van:Non-refrigerated enclosed trailers handle general merchandise with lower capital intensity than temperature-controlled alternatives.
Standard LTL commands the established base. The steepest expansion runs through Expedited Shipping.
Customer Type:
Volume concentration tilts toward manufacturers and e-commerce platforms, with procurement patterns diverging by shipment frequency and service-level requirements.
- E-commerce Companies:JD.com and Pinduoduo vendors generate mid-size parcel density that saturates LTL networks with scheduled pickup demands. JD Logistics controls last-mile fulfillment through proprietary warehouse-to-depot routing algorithms that compress terminal dwell times.
- Manufacturers:Automotive and electronics producers in Jiangsu province source LTL for component replenishment below full-truckload thresholds. Edge-computing load optimization systems at third-party logistics hubs miniaturize decision latency for these shippers.
- Retailers:Department store chains and specialty retailers consolidate inbound freight from fragmented supplier bases.
- Wholesalers:Distribution intermediaries serving provincial markets rely on cost-efficient standard LTL for inventory replenishment cycles.
Manufacturers anchor the revenue base. E-commerce Companies are climbing the fastest as platform vendors shift from express parcel to consolidated LTL modes.
Delivery Mode:
Road Freight and Last Mile absorb domestic volume, while Intermodal and Rail Delivery concentrate on long-haul corridors where infrastructure investment unlocks cost efficiency.
- Road Freight:Cross-provincial trucking under MIIT GB standards compliance dominates tonnage moved. Real-time GPS and emissions monitoring hardware retrofits strain balance sheets of mid-tier operators on Guangdong-inland corridors.
- Last Mile:Proprietary depot networks and algorithmic routing control fulfillment density in urban clusters. SF Express and JD Logistics deploy these capabilities to guarantee sub-48-hour coverage across Zhejiang province.
- Intermodal:Air-ground integration supports premium expedited segments with higher rate structures.
- Rail Delivery:Containerized rail freight serves bulk commodity movements on select long-haul lanes.
Road Freight holds the volume base. Last Mile is gaining share fastest as e-commerce platforms internalize fulfillment infrastructure.
Package Type:
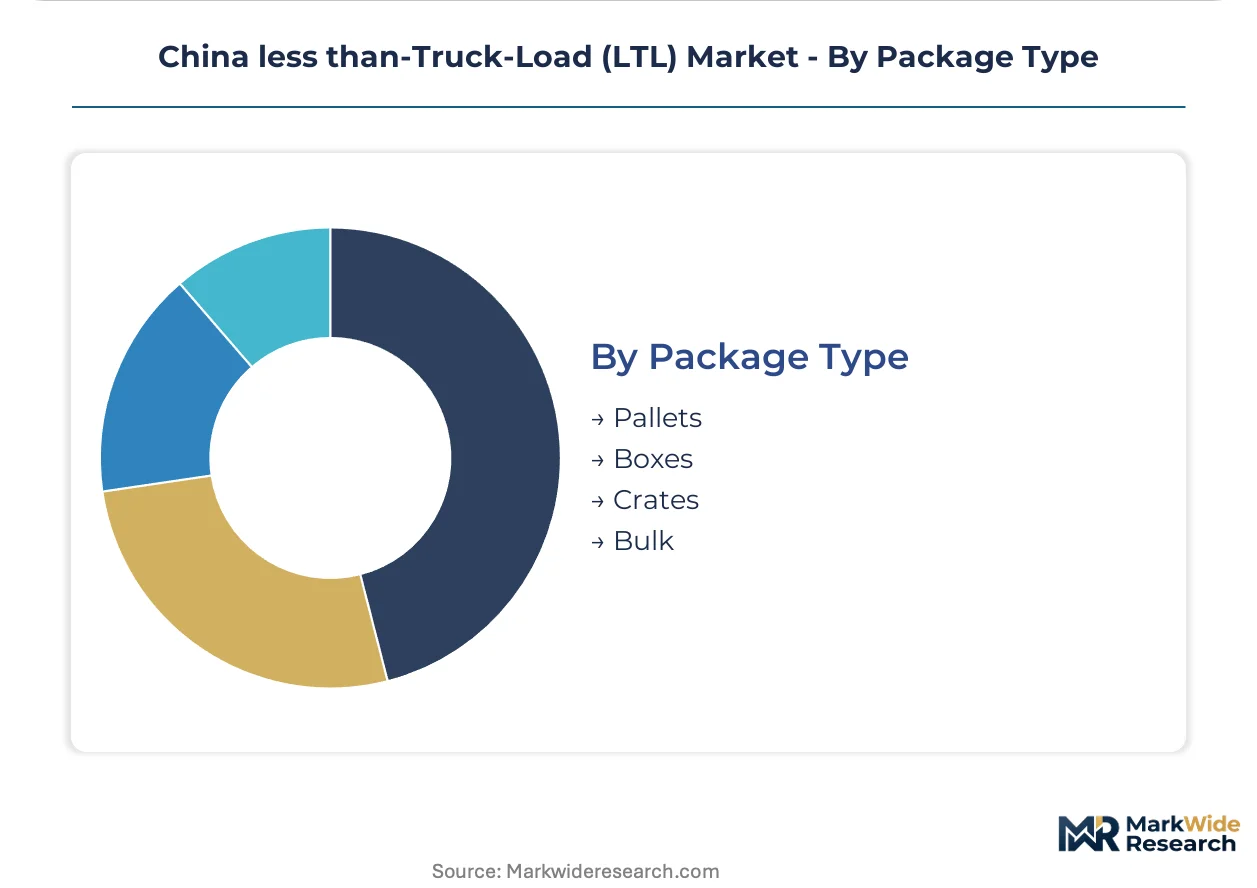
Handling infrastructure and terminal automation investments diverge by unit load, with palletized freight rewarding standardized mechanized sorting.
- Pallets:Unitized loads enable mechanized handling at regional sorting terminals. Robotic parcel handling systems across Jiangsu province compress dwell-time variance for automotive component manufacturers.
- Boxes:Parcel-scale shipments from e-commerce vendors drive automated sorting capex with higher throughput per square meter.
- Crates:Rigid containers protect fragile or high-value merchandise through multi-terminal routing.
- Bulk:Loose-loaded commodities require manual handling and occupy lower automation tiers.
Pallets represent the established infrastructure anchor. Boxes are expanding most quickly as e-commerce parcel density reshapes terminal design specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
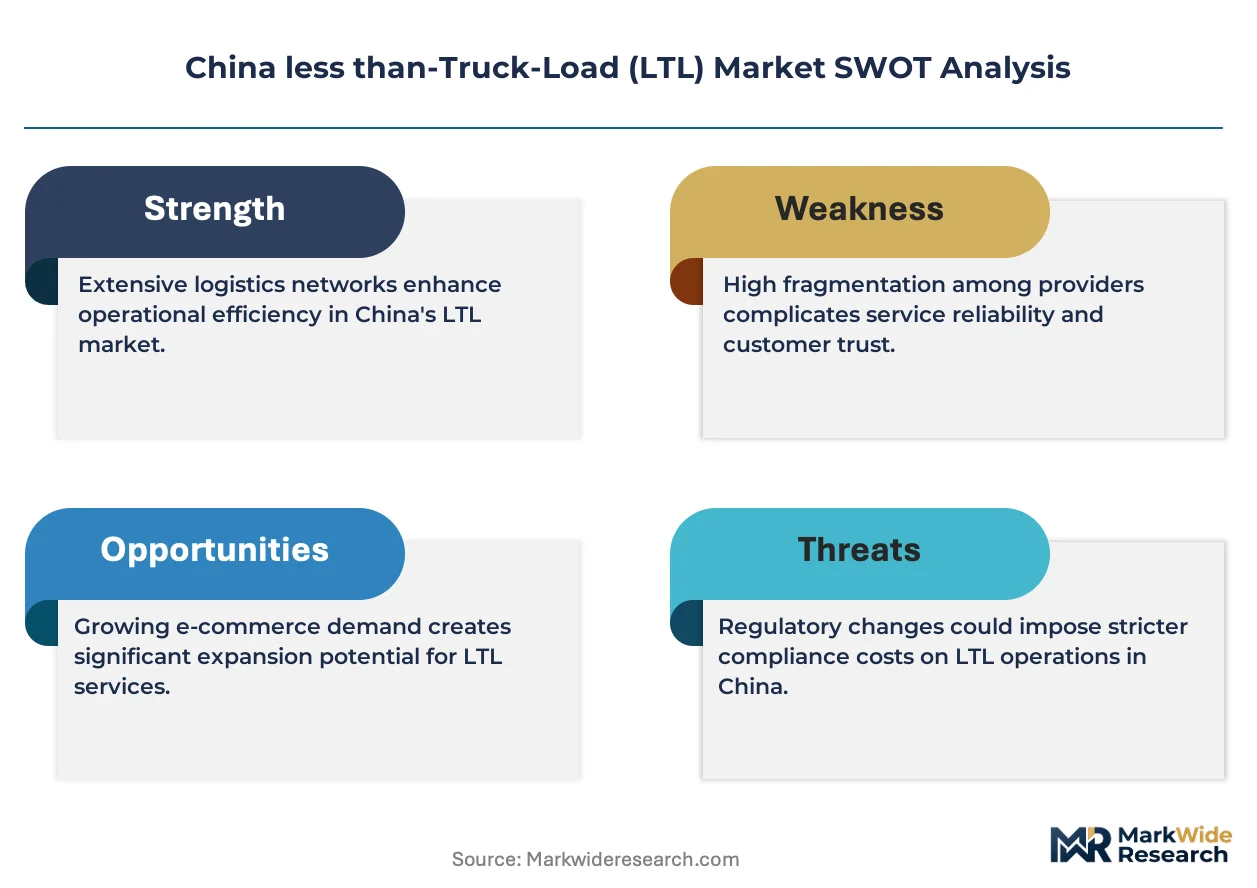
MIIT's GB standards compliance requirements concentrate operational pressure on Yangtze River Delta terminals, where manufacturing density generates the highest freight consolidation volumes in China.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang manufacturing clusters saturate LTL networks with automotive and electronics component freight. SAMR pricing transparency enforcement stabilizes margin pools for national carriers against predatory undercutting. Suzhou and Hangzhou terminals deploy automated sorting infrastructure to absorb e-commerce parcel density from JD.com and Pinduoduo vendors.
Pearl River Delta
Guangdong export manufacturing generates heavy-haul corridors connecting Shenzhen and Dongguan zones to inland distribution centers. MIIT-mandated GPS and emissions hardware retrofits strain mid-tier operator balance sheets on cross-provincial lanes. Guangzhou hub terminals face steepest compliance cost absorption while serving pharmaceutical exporters requiring temperature-controlled capacity.
Beijing-Tianjin-Hebei
Capital region logistics demand concentrates on premium expedited services for government and enterprise procurement. MEE dual carbon goals pressure terminal operators to electrify yard tractors and retrofit diesel line-haul equipment. Tianjin port-linked corridors feed automotive supply chains with scheduled component replenishment below full-truckload thresholds.
Sichuan-Chongqing
Western China manufacturing zones remain underserved by premium expedited networks, creating whitespace for temperature-controlled lane development. Provincial operators face telematics integration complexity as legacy dispatch systems require costly middleware to interface with MIIT-mandated monitoring platforms. Chengdu and Chongqing hubs attract capital deployment for automated sorting convergence.
Shandong Peninsula
Qingdao and Yantai port cities anchor chemical and fresh-food export corridors requiring licensed hazmat driver capacity. SAMR safety protocols tighten availability for temperature-controlled pharmaceutical lanes serving Japan and South Korea markets. Jinan terminals consolidate freight from provincial industrial zones into Yangtze River Delta distribution networks.
China less than-Truck-Load (LTL) Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with national carriers controlling hub-and-spoke density against regional players on fragmented lanes. The upper tier deploys proprietary routing algorithms and air-ground intermodal assets to guarantee sub-48-hour coverage. Three archetypes dominate: integrated express-LTL hybrids, pure-play hub-and-spoke operators, and e-commerce captive logistics arms. Competitive moves center on automated sorting capex races and strategic partnerships for western corridor penetration.
Within the integrated hybrid tier, SF Express anchors premium expedited positioning through proprietary air-ground assets, while Deppon Logistics exemplifies hub-and-spoke density play across Yangtze River Delta manufacturing clusters. JD Logistics occupies the e-commerce captive archetype, controlling last-mile fulfillment through warehouse-to-depot routing algorithms that compress terminal dwell times.
| Leading Market Players |
|---|
| SF Express (KEX-SF) |
| Deppon Logistics Co., Ltd. |
| ZTO Express |
| JD Logistics |
| Yimi Dida Supply Chain Group Co., Ltd. |
| STO Express Co., Ltd. |
| Shanghai Aneng Juchuang Supply Chain Management Co., Ltd. |
| CMA CGM Group |
| Changjiu Logistics |
| Others |
Pricing and Supply Chain Analysis
Hub-and-spoke terminal density across Yangtze River Delta manufacturing clusters generates scale economies that compress per-unit handling costs while establishing price floors that mid-tier provincial operators cannot match. SAMR pricing transparency enforcement stabilizes margin pools for national carriers by limiting predatory undercutting, yet MIIT telematics mandates force capital deployment that widens the cost-structure gap between integrated leaders and fragmented regional players.
Pricing Analysis
Shanghai-Jiangsu corridors command premium rate structures 15-20% above Sichuan-Chongqing lanes due to manufacturing density and expedited service guarantees. Three-tier pricing structure across premium, standard, and economy levels separates SF Express air-ground intermodal from Deppon hub-and-spoke standard service and unlicensed regional brokerages. Cost compression in standard LTL is intensifying because e-commerce volume density rewards automated sorting investments that amortize across high-frequency lanes. Wholesalers and provincial distributors exhibit highest price sensitivity, while pharmaceutical shippers accepting temperature-controlled premiums show least elasticity.
Supply Chain Analysis
Just-in-time replenishment preferences among Jiangsu automotive component manufacturers compress inventory buffers and mandate sub-48-hour delivery guarantees that favor carriers with proprietary routing algorithms. Supply concentration centers on China for trailer manufacturing and telematics hardware, South Korea for advanced emissions monitoring sensors, and Japan for precision sorting automation components. Single-source vulnerability runs through domestic battery-electric tractor chassis suppliers facing MEE dual carbon procurement mandates. Distribution runs through hub-and-spoke terminal networks with regional sorting density determining last-mile fulfillment economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's LTL market operates as a defensive-moat story where hub-and-spoke terminal density creates network effects that compound with each incremental sorting automation deployment. SAMR regulatory entrenchment raises compliance barriers that protect scaled incumbents from undercapitalized regional challengers.
For Market Incumbents: Compound terminal density advantages by accelerating automated sorting capex in Yangtze River Delta clusters where JD.com and Pinduoduo volume saturates pickup networks. Defend against full-truckload substitution above 1,500-kilogram thresholds by integrating captive warehousing assets that offer inventory postponement services unavailable to pure transport competitors. Prioritize backward integration into battery-electric yard tractor fleets to capture MEE subsidy pools before compliance deadlines tighten.
For New Entrants and Emerging Players: Lead with temperature-controlled lane development in Sichuan-Chongqing manufacturing zones where pharmaceutical and fresh-food exporters face licensed hazmat driver scarcity that constrains incumbent capacity allocation. Target western corridor penetration through partnerships with provincial operators possessing legacy dispatch relationships but lacking telematics integration capabilities. Position automated sorting convergence as the go-to-market differentiator that compresses terminal dwell times below hub-and-spoke incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors carriers with deployed robotic handling infrastructure and proprietary load optimization software rather than asset-heavy line-haul operators facing electrification capex intensity. Long-term viability across the next decade hinges on algorithmic routing density that amortizes fixed terminal costs across e-commerce volume growth. Watch MIIT enforcement intensity on real-time GPS compliance as the inflection signal determining which mid-tier operators exit versus consolidate.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Infrastructure Deployment | Robotic parcel handling at Jiangsu terminals compresses dwell-time variance for automotive component manufacturers. |
| Battery-Electric Fleet Electrification | MEE dual carbon subsidies unlock state funding pools for yard tractor retrofits ahead of compliance deadlines. |
| Western Corridor Network Expansion | Sichuan-Chongqing temperature-controlled lane development captures pharmaceutical exporter demand underserved by premium networks. |
| Telematics Platform Integration | Middleware development connects legacy dispatch systems to MIIT-mandated real-time monitoring portals for provincial operators. |
| Air-Ground Intermodal Asset Integration | Proprietary cargo capacity guarantees sub-48-hour provincial coverage that pharmaceutical distributors now mandate in contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with logistics procurement managers at JD.com and Pinduoduo vendor networks, terminal operations directors across Yangtze River Delta hubs, licensed hazmat drivers serving pharmaceutical lanes, and SAMR regulatory compliance officers. Secondary validation drew from MIIT GB standards documentation, MEE dual carbon policy filings, customs freight movement records, and carrier fleet telematics disclosure reports. Bottom-up volume modeling triangulated against top-down manufacturing output projections across Shanghai, Jiangsu, and Zhejiang industrial zones.
Across the analysis window, forecasts applied segment-specific growth coefficients to service type, customer vertical, and delivery mode dimensions with particular weighting for e-commerce freight consolidation velocity and temperature-controlled lane development potential. CAGRs derived from historical tonnage growth patterns adjusted for MIIT regulatory implementation timelines and MEE electrification mandate phase-ins. Industry-specific inputs included cross-provincial fleet telematics adoption curves and automated sorting infrastructure deployment schedules reported by leading terminal operators.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce volume growth, SAMR enforcement continuity, or MEE subsidy program extension would require recalculation. Forecasts reflect documented assumptions regarding hazmat driver license issuance rates and battery-electric tractor total-cost-of-ownership parity timelines. Revision becomes warranted when full-truckload substitution pressure accelerates above current thresholds or when western corridor manufacturing investment crosses inflection points that reshape lane economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Malaysia Freight and Logistics Market
Logistics and Shipping
United Arab Emirates (UAE) Third-Party Logistics (3PL) Market
Logistics and Shipping
Fine Art Logistics Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
United States FTL Freight Brokerage Market
Logistics and Shipping
Multicarrier Shipping Software Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Singapore Chemical Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Europe FMCG Logistics Market
Logistics and Shipping
Peru Road Freight Transport Market