
 Germany Freight Forwarding Market | 2026-2036
Germany Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Freight Forwarding Market Insights
AEO certification is collapsing the field of qualified freight forwarding providers in Germany, as customs authorities tighten security standards for cross-border operators. DB Schenker leverages its captive rail network through Deutsche Bahn AG to sustain intermodal dominance across Central European corridors. Kuehne + Nagel competes through specialized pharmaceutical cold-chain capabilities that meet GDP compliance requirements. Dachser Group SE & Co. KG anchors its position with dense European road networks and controlled temperature logistics for automotive parts.
Germany freight forwarding encompasses the coordination and management of cargo movement across multiple transport modes, requiring customs documentation, carrier negotiation, and shipment consolidation typically governed by FIATA-standardized bills of lading. The practice serves industrial supply chains by reducing transit complexity and optimizing load factors across fragmented carrier markets. Road freight retains the largest volume share due to Germany's central European geography and Autobahn density, though rail freight is gaining structural ground as the EU Green Deal tightens emission accounting for long-haul trucking. Express delivery commands premium margins from automotive and pharmaceutical manufacturers with just-in-production schedules, while cloud-based platforms are displacing legacy TMS installations among mid-sized forwarders seeking real-time visibility.
KBA vehicle approval standards and EU ETS carbon pricing rules are reshaping fleet investment decisions, pushing forwarders toward electric and hydrogen-powered trucks for domestic distribution. BSI supply chain security guidelines and AEO mutual recognition agreements determine which operators can clear goods at reduced inspection rates across German border points. Stakeholders must weigh whether to build captive green fleets or rely on carrier partnerships as emission regulations tighten and carbon border adjustments expand.
Market Dynamics
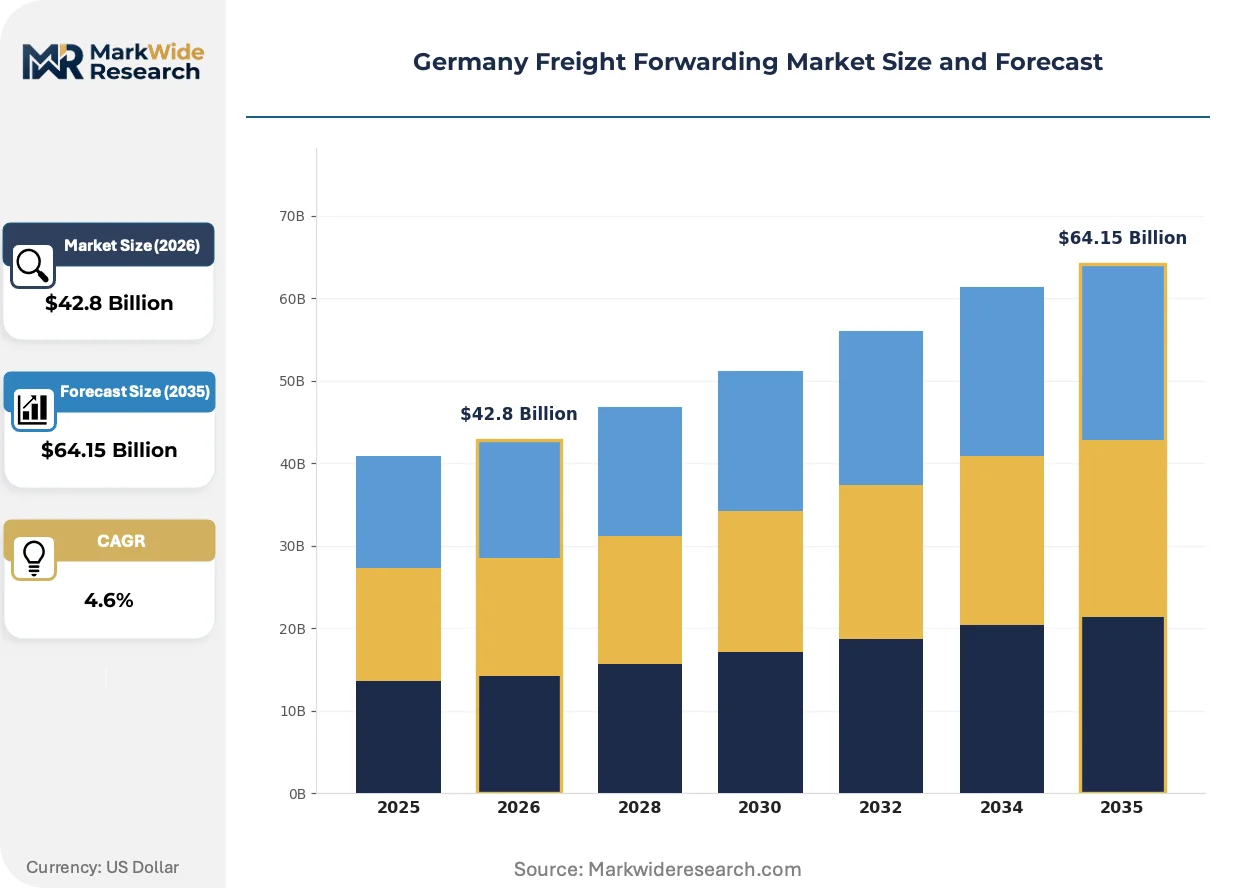
The EU Green Deal's emissions trading requirements for transport are compressing operational margins across German freight forwarding networks while simultaneously unlocking intermodal infrastructure investment. Forwarders face immediate fleet replacement decisions as carbon pricing mechanisms tighten.
Growth Catalysts
- Rhine-Ruhr corridor concentration:Port connectivity and dense rail infrastructure create cost advantages for high-volume automotive and chemical shippers seeking consolidated distribution points.
- AEO certification requirements:Customs authorities tightening security standards for cross-border operators are consolidating qualified provider pools and reducing inspection friction for certified forwarders.
- Nearshoring restructuring:Supply chain reconfiguration around Central European manufacturing is expanding logistics outsourcing from Bavarian and Baden-Württemberg automotive producers.
Market Restraints
- EU ETS carbon pricing:Emission accounting requirements for long-haul trucking are elevating fuel cost structures and compressing margins on traditional road freight operations.
- KBA vehicle approval standards:Stringent certification timelines for electric and hydrogen-powered trucks are extending fleet modernization cycles and freezing capital deployment.
- Rail infrastructure bottlenecks:Capacity constraints on key north-south corridors limit intermodal scalability despite regulatory pressure to shift volume from road.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:GDP compliance requirements for temperature-controlled logistics are opening specialized service tiers with premium margin structures.
- Bavaria-Black Forest corridor:Dense automotive supplier networks in southern Germany present consolidation opportunities for just-in-production express services.
- Cloud-based TMS platforms:Real-time visibility systems are displacing legacy installations among mid-sized forwarders seeking operational transparency.
Industry Challenges
- AEO compliance timelines:Security certification processes are extending onboarding cycles and freezing smaller operators out of cross-border tenders.
- Driver qualification gaps:Hazardous goods handling and intermodal coordination competencies are in short supply across German logistics labor markets.
- Fleet electrification capex:Charging infrastructure deployment and vehicle procurement are demanding capital commitments that strain mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Freight Forwarding Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Road Freight, Rail Freight End User: Manufacturers, Retailers, Wholesalers, Importers Delivery Mode: Express Delivery, Standard Delivery, Same-Day Delivery, Scheduled Delivery Technology: Tracking Systems, Automated Solutions, Inventory Management, Cloud-Based Platforms |
| Companies Covered | DB Schenker, Kuehne + Nagel, Deutsche Post AG, Forto, sennder, Deutsche Bahn AG, DHL Global Forwarding, Smartlane GmbH, Dachser Group SE & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Freight Forwarding Market Trends and Innovations
Digital freight platforms and clean fleet technologies are restructuring how German forwarders coordinate multimodal movements and price carbon exposure into customer contracts.
Sensor-based cargo monitoring systems are miniaturizing. Pharmaceutical manufacturers with GDP-mandated temperature tracking are deploying battery-powered IoT devices at pallet-level granularity. Real-time condition data is compressing insurance premiums and enabling outcome-based freight contracts that shift liability based on verified chain-of-custody records.
KBA approval frameworks for alternative drivetrains are accelerating fleet diversification timelines. Forwarders must now sequence electric and hydrogen vehicle procurement against EU ETS compliance deadlines. Domestic distribution networks serving retail and automotive verticals face the steepest capital reallocation pressures.
Automotive OEMs are unbundling after-sales logistics from manufacturing contracts. Tier-one suppliers in Stuttgart and Munich are contracting directly with forwarders for spare parts distribution, bypassing captive logistics divisions. This procurement fragmentation is most visible in premium vehicle segments where service-level agreements specify two-hour response windows for production-critical components.
Germany Freight Forwarding Market Segmentation
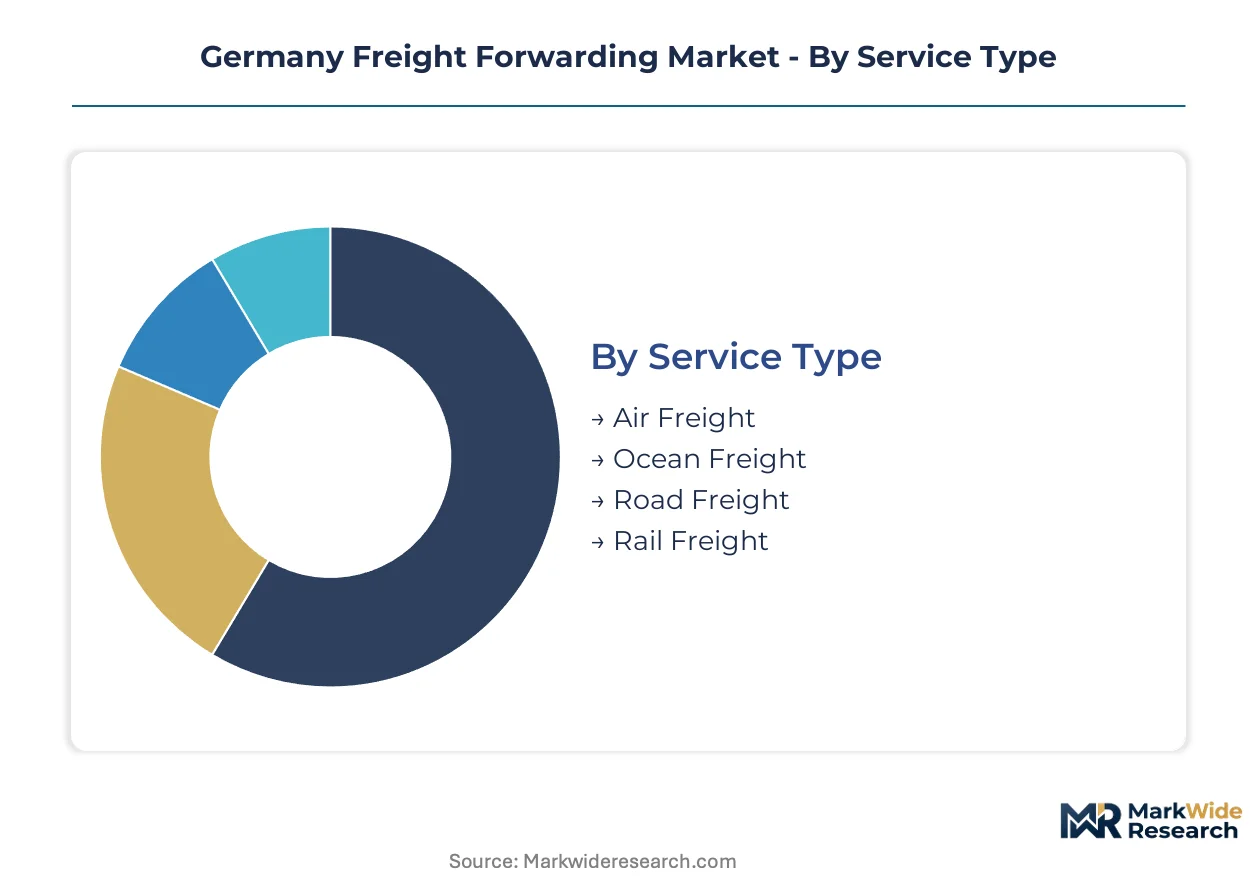
Service differentiation in German freight forwarding increasingly tracks carbon exposure and customs clearance velocity. Forwarders now price contracts around AEO certification status and intermodal flexibility rather than pure transport mode selection.
Service Type:
Road freight captures the deepest margin pools through dense Autobahn coverage and last-mile control, while rail freight is climbing fastest on EU ETS compliance pressure.
- Road Freight:Dominates domestic distribution through Germany's 13,000-kilometer Autobahn network and captive fleet ownership. Bavarian automotive suppliers and Rhine-Ruhr chemical producers concentrate demand here, though EU ETS carbon pricing is compressing margins on long-haul routes.
- Rail Freight:Gaining structural ground as Deutsche Bahn AG expands intermodal terminal capacity across Central European corridors. Forwarders with captive rail access capture premium pricing on north-south automotive component flows.
- Air Freight:Serves pharmaceutical and high-value electronics manufacturers with GDP-compliant cold-chain infrastructure at Frankfurt and Munich hubs.
- Ocean Freight:Concentrates in Hamburg and Bremerhaven port hinterlands, handling bulk chemical and automotive exports to global markets.
Road freight holds installed capacity. Rail freight is rotating up the share rankings.
End User:
Procurement sophistication varies sharply: manufacturers demand outcome-based contracts with carbon accounting, while retailers prioritize cost-per-unit metrics.
- Manufacturers:Automotive OEMs in Stuttgart and Munich unbundle logistics contracts to access specialized just-in-production express services. KBA vehicle approval standards and EU ETS compliance requirements force forwarders to document chain-of-custody carbon exposure.
- Retailers:Omnichannel distribution networks in Berlin and Hamburg require flexible last-mile orchestration with real-time inventory visibility. Cloud-based TMS adoption concentrates among this segment.
- Wholesalers:Consolidated procurement across mid-tier industrial distributors favors established forwarders with AEO certification and reduced customs inspection rates.
- Importers:Cross-border e-commerce flows through Frankfurt air hub and Duisburg rail terminal demand customs brokerage integration with last-mile handoff.
Manufacturers command pricing power through volume concentration. Retailers are expanding service requirements fastest.
Delivery Mode:
Speed tier selection directly maps to inventory carrying cost tradeoffs in German industrial supply chains.
- Express Delivery:Two-hour response windows for production-critical automotive components command 3-5x standard freight multiples. Tier-one suppliers in Baden-Württemberg contract directly with forwarders, bypassing captive logistics divisions.
- Same-Day Delivery:Emerging in pharmaceutical cold-chain where GDP temperature compliance must synchronize with hospital and pharmacy receiving windows.
- Standard Delivery:Bulk chemical and industrial machinery movements through Rhine-Ruhr corridor rely on scheduled consolidation and intermodal handoffs.
- Scheduled Delivery:Retail distribution centers negotiate fixed-slot arrivals to optimize warehouse labor scheduling and dock door utilization.
Express delivery holds rate premiums. Same-day delivery is climbing the fastest.
Technology:
Capital deployment here determines which forwarders can meet AEO security standards and pharmaceutical GDP documentation requirements.
- Tracking Systems:Pallet-level IoT sensors with battery-powered temperature logging enable outcome-based freight contracts. Pharmaceutical manufacturers deploy these for GDP-mandated chain-of-custody verification.
- Cloud-Based Platforms:Displacing legacy TMS installations among mid-sized forwarders seeking real-time visibility without capital-intensive on-premise infrastructure.
- Inventory Management:Warehouse management system integration allows forwarders to offer vendor-managed inventory services for automotive and retail verticals.
- Automated Solutions:Robotic process automation for customs documentation and carrier selection reduces manual processing costs at high-volume border crossings.
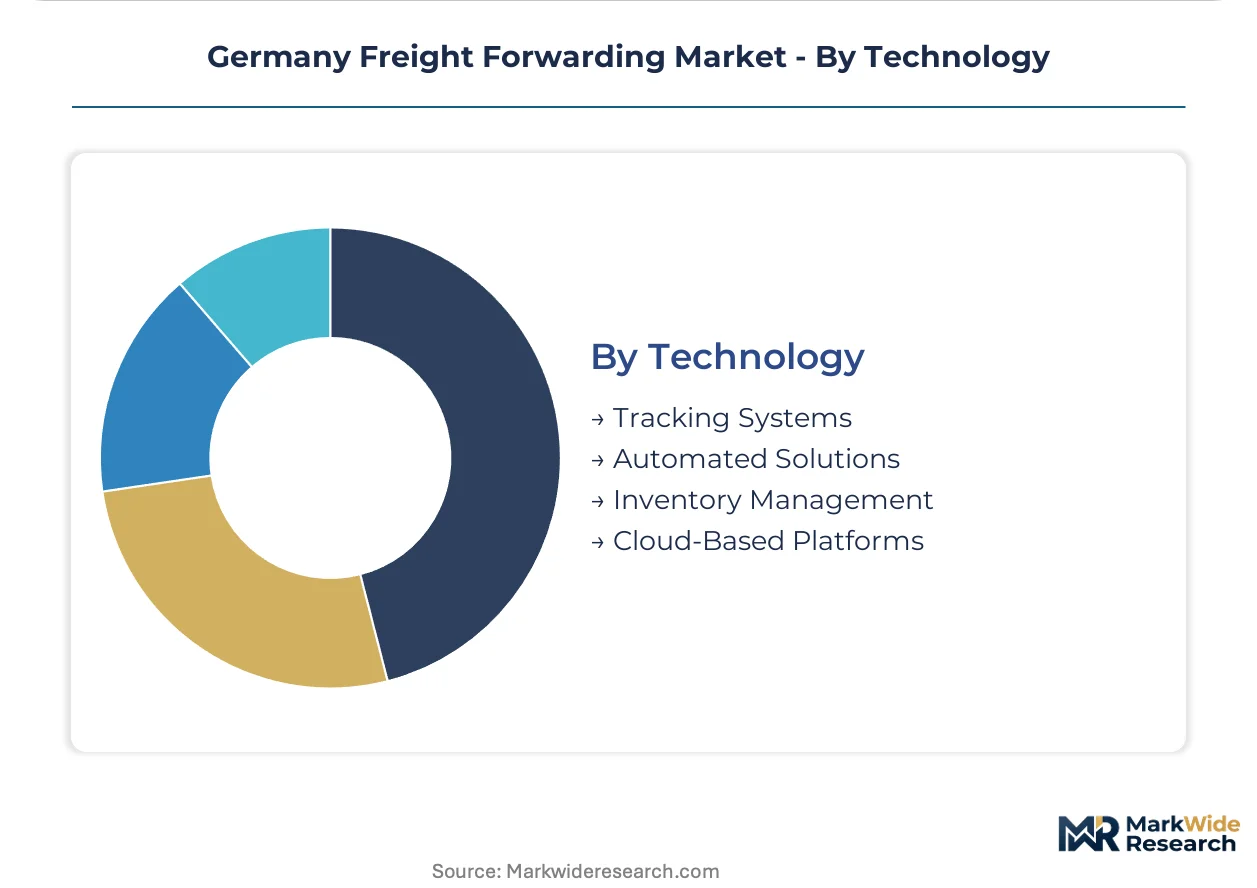
Tracking systems hold compliance-critical installed base. Cloud-based platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive manufacturers and chemical producers dominate freight forwarding procurement across German industrial corridors, with concentration varying sharply between southern precision manufacturing clusters and northern port hinterlands.
Bavaria
Munich-based automotive OEMs and aerospace suppliers drive express freight demand for just-in-production components. KBA vehicle approval standards shape fleet procurement timelines for forwarders serving this corridor. The Ingolstadt-Augsburg manufacturing belt concentrates premium vehicle logistics contracts requiring two-hour response windows.
North Rhine-Westphalia
Rhine-Ruhr chemical producers and steel manufacturers generate high-volume bulk movements through Duisburg intermodal terminals. EU ETS carbon pricing accelerates rail freight adoption on north-south corridors. Cologne-Düsseldorf logistics parks anchor consolidated distribution for retail and industrial shippers.
Baden-Württemberg
Stuttgart automotive suppliers unbundle after-sales logistics from manufacturing contracts, creating direct forwarder relationships. AEO certification requirements filter qualified providers for cross-border component flows. The Black Forest precision engineering cluster demands temperature-controlled express services for production-critical parts.
Hamburg
Port hinterland movements connect Bremerhaven automotive exports with Central European distribution networks. EU Green Deal emission accounting pushes terminal operators toward electric yard tractors. The Hamburg-Berlin corridor concentrates ocean freight consolidation for chemical and machinery exporters.
Hesse
Frankfurt air freight hub serves pharmaceutical manufacturers with GDP-compliant cold-chain infrastructure. BSI supply chain security guidelines determine customs clearance velocity at Rhine-Main border points. The Frankfurt-Darmstadt biotech corridor drives pallet-level IoT tracking adoption for temperature-sensitive shipments.
Germany Freight Forwarding Market Competitive Landscape
Player mix skews toward diversified logistics conglomerates with captive infrastructure, though digital-native challengers are compressing margins on spot freight procurement. Consolidation pressure intensifies as AEO certification requirements and EU ETS compliance costs freeze smaller operators out of cross-border tenders. Strategic archetypes divide between rail-integrated incumbents, pharmaceutical cold-chain specialists, and cloud-based freight platforms. Dominant competitive moves include intermodal capacity expansion and vertical integration into customs brokerage services.
Within the rail-integrated tier, DB Schenker leverages captive network access through Deutsche Bahn AG, while Kuehne + Nagel occupies a position among pharmaceutical GDP-compliant specialists. Digital challengers exemplified by Forto and sennder sit within the cloud-native segment, representing freight platform archetypes that displace legacy TMS procurement among mid-sized shippers.
| Leading Market Players |
|---|
| DB Schenker |
| Kuehne + Nagel |
| Deutsche Post AG |
| Forto |
| sennder |
| Deutsche Bahn AG |
| DHL Global Forwarding |
| Smartlane GmbH |
| Dachser Group SE & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Intermodal rail substitution for long-haul trucking is simultaneously redrawing freight corridor economics and compressing road freight rate premiums across German industrial belts. EU ETS carbon pricing accelerates this shift, forcing forwarders to rebalance fleet deployment between emission-intensive road segments and rail-integrated alternatives.
Pricing Analysis
Cost-plus contracts with diesel price indexation dominate long-haul road freight agreements, though EU ETS allowance costs are increasingly passed through as separate line items. Price differentiation separates AEO-certified operators with reduced customs inspection rates from non-certified competitors facing border delays. Pricing pressure stems from digital freight platforms compressing spot market margins through algorithmic load matching. Retail distributors exhibit highest price sensitivity due to volume consolidation and multi-forwarder tendering, while pharmaceutical manufacturers prioritize GDP compliance over rate negotiation.
Supply Chain Analysis
Just-in-production inventory strategies among Stuttgart and Munich automotive OEMs demand two-hour response windows for production-critical components, eliminating strategic stockpiles from tier-one supplier networks. Component supply concentrates in Germany, Czech Republic, and Poland for precision-engineered automotive parts, with battery cell inputs drawing from South Korea and China. Single-source vulnerability runs through specialized temperature-controlled packaging for pharmaceutical cold-chain. Distribution runs through Rhine-Ruhr intermodal terminals and Frankfurt air hub consolidation points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German freight forwarding is recovering through automotive production restocking cycles and nearshoring-driven logistics outsourcing from Bavarian manufacturing clusters.
For Market Incumbents: Consolidate intermodal terminal access along north-south corridors to defend against digital freight platforms eroding spot market share. Deepen captive rail partnerships as EU ETS compliance costs freeze smaller road-only operators out of cross-border tenders. Prioritize AEO certification investments to maintain customs clearance velocity at Rhine-Main border points. For New Entrants and Emerging Players: Mid-sized pharmaceutical cold-chain gaps present white-space opportunities where GDP compliance requirements filter established providers. Target Baden-Württemberg precision engineering clusters with pallet-level IoT tracking services bypassing legacy TMS installations. Deploy cloud-native freight platforms with real-time visibility APIs to capture disaffected mid-tier shipper accounts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional forwarders holding dense Bavarian road networks but lacking intermodal scale. Long-term viability favors operators with captive rail access and AEO certification moats. Watch EU ETS allowance price trajectories as the inflection signal determining fleet modernization capex requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Intermodal Capacity Expansion | Captures EU ETS-driven modal shift from road to rail across Rhine-Ruhr corridors. |
| AEO Certification Investment | Secures reduced customs inspection rates at KBA-regulated German border points. |
| Pharmaceutical Cold-Chain Buildout | Opens GDP-compliant service tiers with premium margins from Frankfurt biotech manufacturers. |
| Cloud-Based TMS Deployment | Displaces legacy installations among mid-sized forwarders seeking real-time visibility. |
| Electric Fleet Procurement | Positions operators ahead of KBA approval timelines for zero-emission domestic distribution. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with freight forwarding executives, automotive procurement managers, and pharmaceutical supply chain directors; and secondary validation through EU ETS regulatory filings, KBA vehicle approval databases, and FIATA-standardized trade documentation. Primary fieldwork captured operational metrics from Rhine-Ruhr intermodal terminals and Frankfurt air freight hubs. Secondary sources included Deutsche Bahn AG infrastructure disclosures, customs authority AEO certification registries, and pharmaceutical GDP compliance audits. Bottom-up volume modeling triangulated against top-down corridor flow estimates.
Across the analysis window, forecasts employed service type, end user vertical, delivery mode speed tier, and technology adoption segmentation. CAGRs derived from historical modal share shifts, EU ETS carbon price trajectory assumptions, and automotive production cycle correlations. Industry-specific inputs incorporated KBA alternative drivetrain approval timelines and AEO certification penetration curves among mid-tier forwarders.
Forecasts assume regulatory continuity in EU ETS implementation and KBA vehicle standards; material policy shifts would require re-modeling. Specific risks include rail infrastructure capacity constraints freezing intermodal scalability and driver qualification gaps limiting hazardous goods handling expansion. Revision becomes warranted when EU ETS allowance prices cross thresholds triggering accelerated fleet retirement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Spain Pharmaceutical Logistics Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
Estonia Freight and Logistics Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
Vehicle Routing and Scheduling Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
ASEAN Courier, Express, and Parcel (CEP) Market