
 Last-Mile Delivery Market | 2026-2036
Last-Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Last-Mile Delivery Market Outlook
Market Dynamics
Chinese courier networks is decoupling from pure volume expansion toward margin-focused capacity discipline. Amazon leverages its captive logistics infrastructure to control fulfillment economics across dense urban zones. DHL sustains cross-border last-mile dominance through bonded warehouse integration and customs pre-clearance systems. FedEx competes on time-definite express segments where premium pricing anchors operational returns.
Segmentation Analysis
Last-mile delivery encompasses the final transportation leg from distribution hub to end recipient, typically spanning distances under 50 kilometers and requiring real-time visibility through GPS-enabled tracking systems and dynamic route optimization algorithms. Same-day delivery is capturing disproportionate investment as consumer tolerance for waiting periods compresses, while autonomous vehicle delivery remains nascent due to regulatory fragmentation and infrastructure gaps. Ground transportation still occupies the bulk of fulfillment volume, though bicycle fleets are gaining share in European city centers where emissions restrictions tighten.
Regulatory Environment
The EU Green Deal and F-Gas Regulation are pressuring fleet decarbonization, while the FAA in the United States governs drone delivery airspace access with evolving beyond-visual-line-of-sight rules. India's BIS standards and PLI scheme for electric mobility are accelerating EV adoption among domestic courier operators. Stakeholders must weigh regulatory compliance costs against automation dividends as labor availability tightens in key metropolitan corridors.
Market Dynamics
E-commerce fulfillment economics are compressing delivery windows toward same-day and two-hour guarantees, forcing asset-light platform operators to build captive logistics infrastructure or surrender margin to integrated carriers.
Growth Catalysts
- Urban Emissions Mandates:The EU Green Deal and F-Gas Regulation are accelerating fleet electrification across European metro zones, creating procurement pull for electric vans and cargo bicycles.
- Hyperlocal Infrastructure Investment:India's metro cities are deploying micro-fulfillment centers within 5 kilometers of dense residential clusters, reducing last-mile transit distances and enabling scheduled delivery windows.
- Real-Time Visibility Platforms:GPS-enabled tracking systems coupled with dynamic route optimization algorithms are compressing delivery ETAs and reducing failed delivery attempts in high-density corridors.
Market Restraints
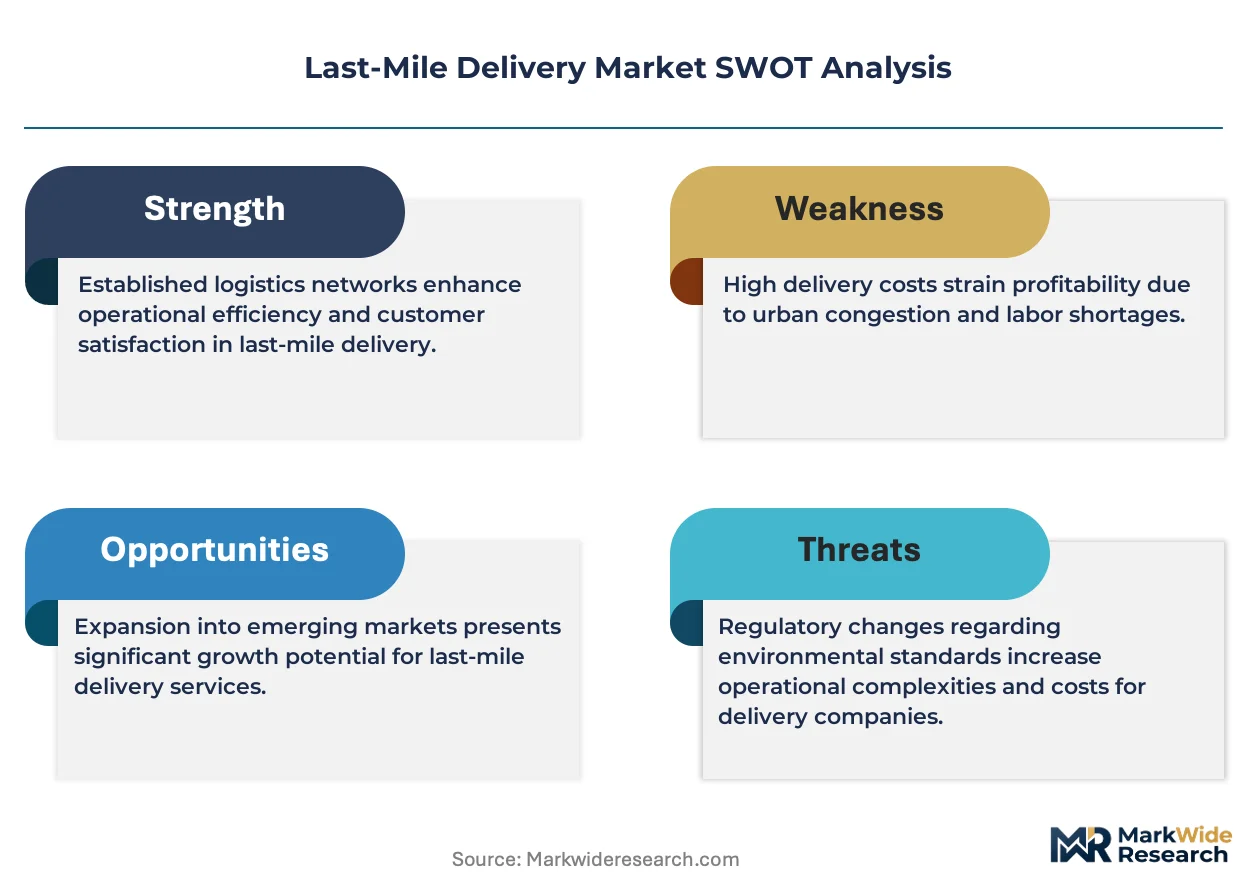
- Labor Availability Constraints:Courier workforce shortages in key metropolitan corridors are inflating per-delivery labor costs and capping fulfillment capacity during peak windows.
- Regulatory Fragmentation:The FAA's evolving beyond-visual-line-of-sight rules for drone delivery are creating airspace access uncertainty, delaying autonomous vehicle deployment timelines.
- Substitution by Click-and-Collect:Retailer-operated pickup points and parcel locker networks are displacing home delivery for non-urgent shipments, particularly in German and French urban centers.
Strategic Opportunities
- India's PLI-Accelerated EV Adoption:India's PLI scheme for electric mobility is subsidizing domestic courier operator fleet conversions, creating first-mover advantages for integrated logistics platforms.
- Bonded Warehouse Integration:Cross-border e-commerce growth is opening demand for customs pre-clearance systems and bonded last-mile infrastructure in high-volume trade corridors.
- Autonomous-Bicycle Convergence:The pairing of electric cargo bicycles with sidewalk delivery robots is expanding into European city centers where emissions restrictions and congestion charges favor micro-mobility.
Industry Challenges
- Route Optimization Talent Scarcity:Operations research specialists capable of deploying machine learning-driven dispatch systems command premium compensation, constraining mid-tier operator technology adoption.
- Legacy Warehouse Management Integration:Enterprise resource planning systems at established retailers require costly API reconfiguration to synchronize with real-time last-mile visibility platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Last-Mile Delivery Market |
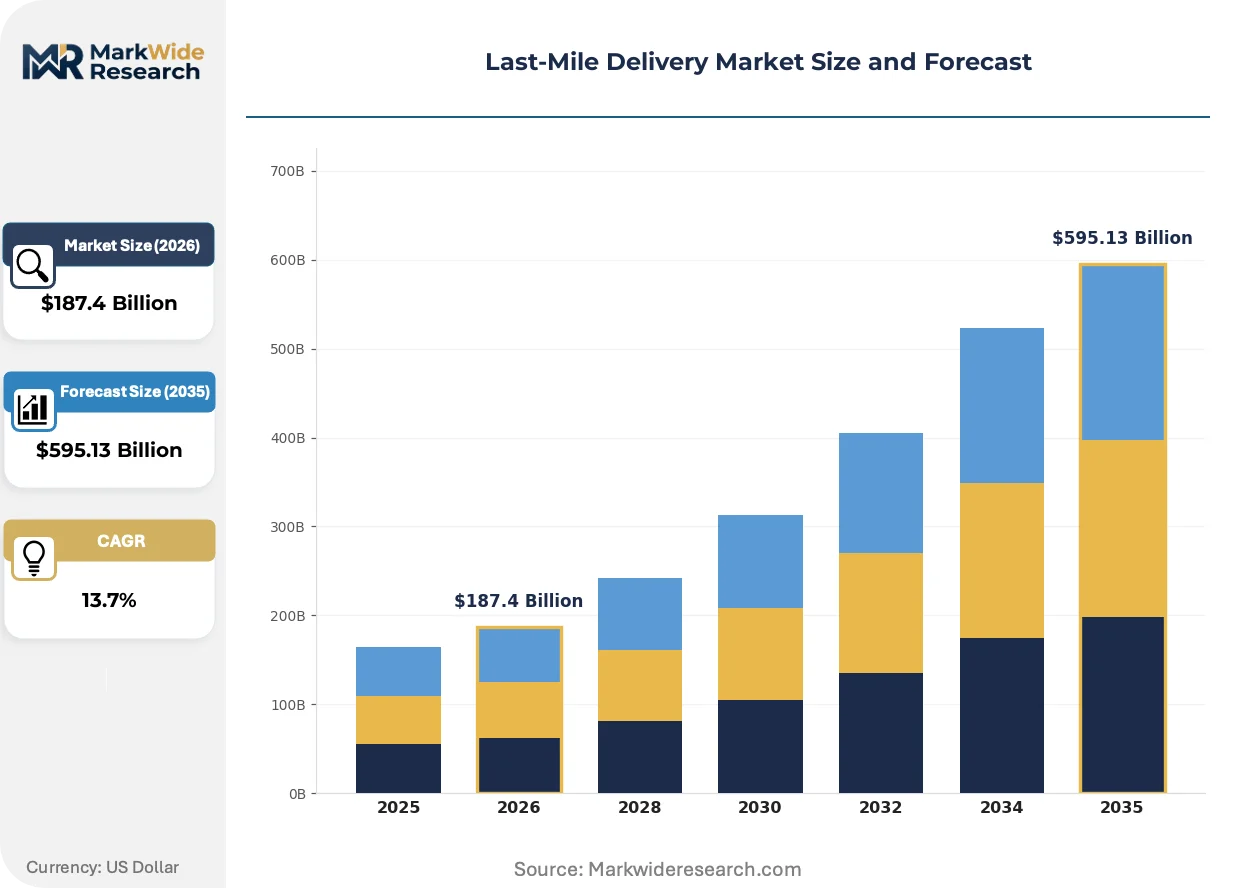
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $595.13 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Delivery, Same-Day Delivery, Next-Day Delivery, Scheduled Delivery Delivery Mode: Ground, Drone, Bicycle, Autonomous Vehicle Customer Type: Retail Customers, Businesses, E-commerce Platforms, Third-Party Logistics Technology: Mobile Apps, Route Optimization Software, Tracking Systems, AI Algorithms |
| Companies Covered | SF Express, Kuehne + Nagel, Amazon, Nippon Express, USPS, DHL, FedEx, GEODIS, DSV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Last-Mile Delivery Market Strategic Shifts
Operational technology deployment is bifurcating between asset-heavy integrated carriers building captive automation and platform-dependent operators outsourcing fulfillment to variable-cost networks.
Dynamic route optimization software is expanding into mid-tier courier operations previously dependent on static dispatch schedules. Regional grocery chains and specialty retailers are adopting cloud-based fleet management platforms at accelerating pace. This technology is expanding into segments where delivery density previously failed to justify dedicated optimization investment, compressing the operational gap between national integrators and local operators.
The EU Green Deal's fleet decarbonization mandates are binding across member state implementations with varying subsidy intensity. Operators face compliance cost structures diverging between countries with dense charging infrastructure and those with deployment gaps. Cold chain and time-definite express segments are most affected, with carriers reconfiguring vehicle mix toward electric vans in German, Dutch, and Danish urban zones while maintaining combustion fleets in peripheral markets.
Buyer tolerance for delivery window uncertainty is collapsing across grocery, pharmaceutical, and high-value electronics verticals. Scheduled delivery slots with one-hour precision are displacing all-day windows as the default expectation in premium urban markets. This compression is most visible in Indian metro corridors and Chinese tier-one cities, where platform competition has normalized sub-two-hour fulfillment for non-perishable categories.
Last-Mile Delivery Market Segmentation
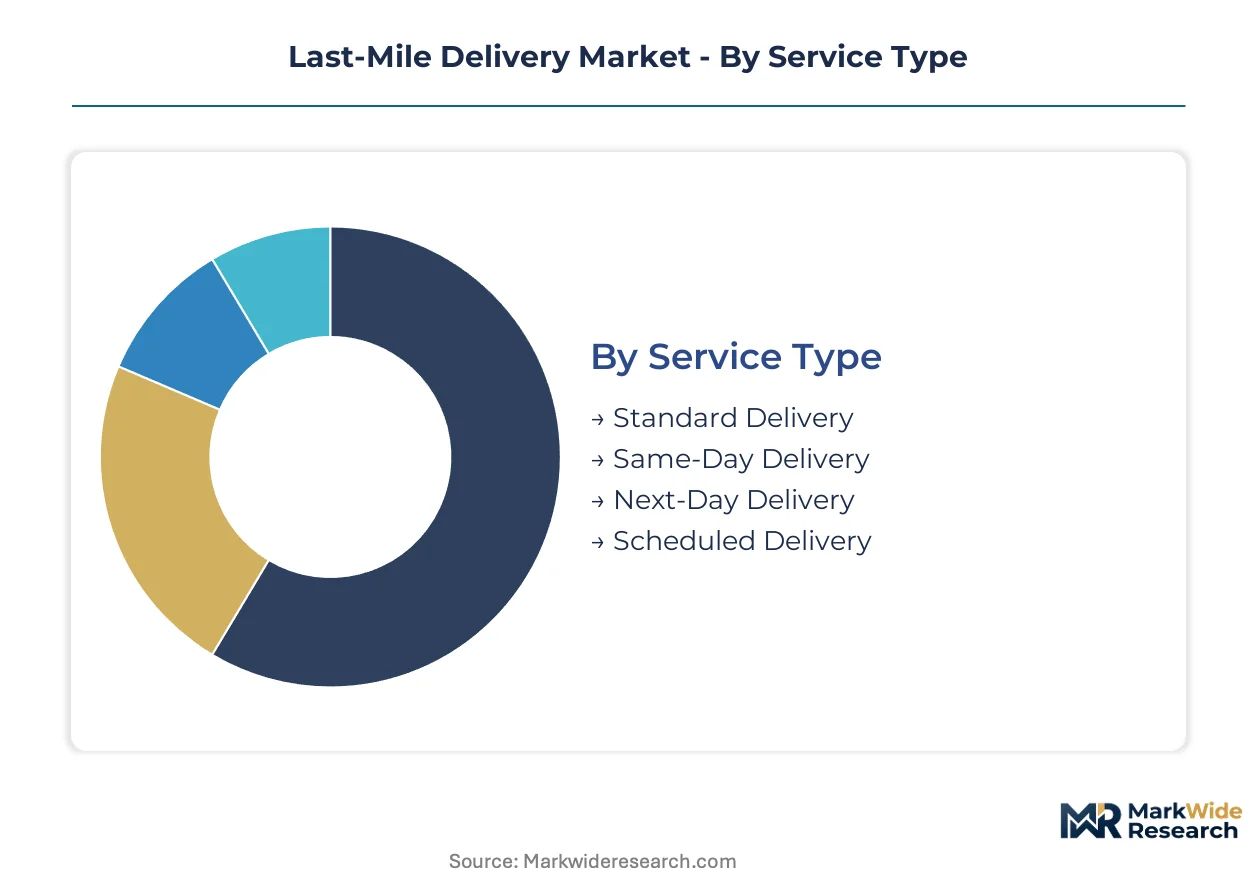
Last-mile delivery segmentation reveals how operators align service architecture with fulfillment economics. Distinct technology stacks and delivery modes create divergent margin profiles across customer types.
Service Type:
Upgrade cycles in consumer expectations are collapsing delivery windows from multi-day to sub-hour guarantees, forcing infrastructure reinvestment across all tiers.
- Same-Day Delivery:Two-hour and four-hour guarantees now anchor premium positioning in dense urban corridors. Indian metro markets and Chinese tier-one cities concentrate demand, where platform competition has normalized sub-two-hour fulfillment for non-perishable categories.
- Scheduled Delivery:One-hour precision slots displace all-day windows in grocery, pharmaceutical, and high-value electronics verticals. European operators leverage this format to optimize fleet utilization during off-peak windows while meeting tightening buyer tolerance for uncertainty.
- Standard Delivery:Two-to-three-day economy tier serves non-urgent shipments where cost minimization outweighs speed.
- Next-Day Delivery:Overnight guarantees retain relevance in B2B corridors and premium residential zones with predictable demand patterns.
Standard delivery sits at the top of the volume ranking, with same-day delivery climbing the fastest.
Delivery Mode:
Cost tier differentiation separates asset-heavy infrastructure from variable-cost network models, with electrification mandates accelerating fleet reconfiguration.
- Ground:Vans and trucks retain bulk volume share across suburban and intercity corridors. Combustion fleets persist in peripheral markets where charging infrastructure gaps and vehicle procurement subsidies diverge between EU member states.
- Bicycle:Electric cargo bicycles gain share in European city centers where emissions restrictions and congestion charges favor micro-mobility. Dutch, Danish, and German urban zones lead deployment density.
- Drone:Regulatory fragmentation around beyond-visual-line-of-sight rules delays scaled deployment despite pilot programs in select corridors.
- Autonomous Vehicle:Sidewalk delivery robots paired with bicycle fleets expand in controlled campus and downtown environments, though full autonomy awaits infrastructure and liability framework maturation.
Ground transportation dominates current fulfillment volume, with bicycle fleets expanding most quickly in regulated European zones.
Customer Type:
Application-specific requirements drive divergent technology investments, with e-commerce platforms building captive logistics to escape margin erosion.
- E-commerce Platforms:Amazon and integrated marketplace operators construct proprietary fulfillment networks to control economics across dense urban zones. Real-time visibility platforms and dynamic route optimization become competitive necessities rather than differentiators.
- Third-Party Logistics:DHL and FedEx compete on cross-border bonded warehouse integration and customs pre-clearance systems, anchoring operational returns in time-definite express segments.
- Businesses:B2B shipments concentrate in scheduled delivery windows with palletized handling requirements distinct from parcel operations.
- Retail Customers:Individual residential delivery faces displacement by click-and-collect and parcel locker networks in German and French urban centers.
E-commerce platforms command the steepest infrastructure investment trajectory, while third-party logistics providers retain margin advantages in cross-border complexity.
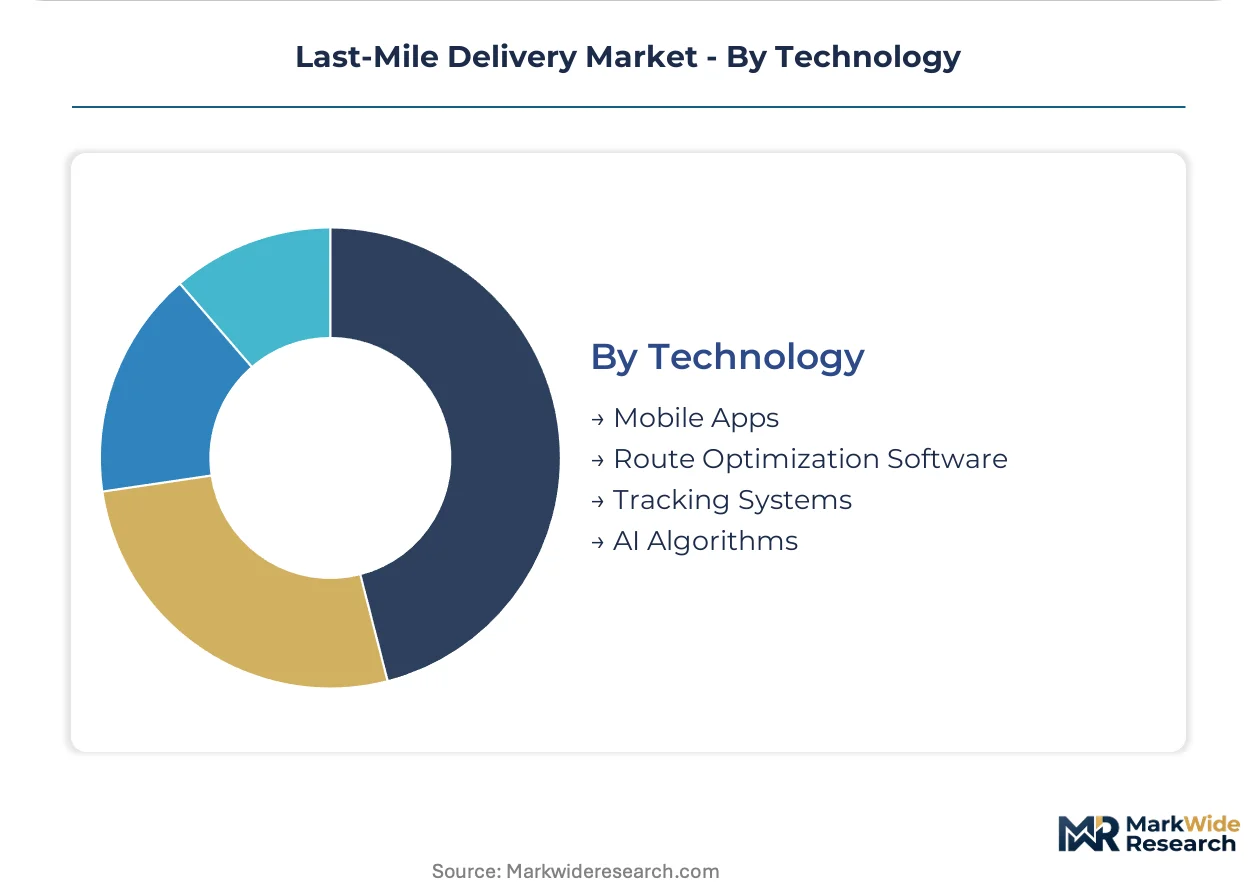
Technology:
Maturity gaps separate enterprise-grade deployments from mid-tier operator adoption constraints, with talent scarcity limiting diffusion of optimization capabilities.
- Route Optimization Software:Machine learning-driven dispatch systems compress ETAs and reduce failed delivery attempts in high-density corridors. Operations research specialists capable of deploying these systems command premium compensation, constraining technology access for regional operators.
- Tracking Systems:GPS-enabled real-time visibility platforms synchronize warehouse management systems with last-mile execution, though legacy ERP reconfiguration costs delay adoption at established retailers.
- Mobile Apps:Consumer-facing interfaces standardize across platforms, with differentiation shifting to backend integration depth.
- AI Algorithms:Predictive demand modeling and dynamic capacity allocation remain concentrated among integrated carriers with sufficient data volume for model training.
Tracking systems represent the most widely deployed technology layer, with route optimization software gaining share fastest among mid-tier operators previously dependent on static dispatch schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's hyperlocal fulfillment networks are expanding faster than Germany's cargo bicycle infrastructure, yet both markets face tightening emissions mandates that reshape fleet economics. Regulatory divergence between Asian metro corridors and European urban zones creates divergent investment priorities for operators.
United States
E-commerce volume concentration in New York, Los Angeles, and Chicago corridors is forcing platform operators to build captive logistics infrastructure. The FAA governs drone delivery airspace access with evolving beyond-visual-line-of-sight rules that delay autonomous deployment. Amazon's fulfillment density in Seattle and Dallas anchors proprietary network economics.
Germany
Parcel locker networks and click-and-collect points in Berlin and Hamburg are displacing home delivery for non-urgent shipments. The EU Green Deal and F-Gas Regulation accelerate fleet electrification mandates across urban zones. DHL's bonded warehouse integration in Frankfurt anchors cross-border last-mile dominance.
India
Metro cities including Mumbai, Bangalore, and Delhi-NCR are deploying micro-fulfillment centers within 5 kilometers of dense residential clusters. The BIS standards and PLI scheme for electric mobility subsidize domestic courier operator fleet conversions. Platform competition has normalized sub-two-hour fulfillment for non-perishable categories.
China
Courier networks in Shanghai, Beijing, and Shenzhen are decoupling from pure volume expansion toward margin-focused capacity discipline. SAMR and dual carbon goals pressure fleet decarbonization timelines. SF Express anchors tier-one city coverage density.
Netherlands
Electric cargo bicycle deployment in Amsterdam and Rotterdam leads European micro-mobility adoption. EU Green Deal implementation creates procurement pull for zero-emission last-mile fleets. GEODIS leverages Dutch port infrastructure for bonded warehouse integration.
Last-Mile Delivery Market Competitive Environment
United States-based platform operators anchor one tier; European integrated carriers and Asian courier networks hold specialized positions in cross-border and hyperlocal segments. The market structure concentrates around asset-heavy integrators with captive infrastructure and asset-light platforms dependent on variable-cost networks. Three archetypes dominate: e-commerce platforms building proprietary fulfillment, third-party logistics providers competing on customs complexity, and regional specialists optimizing for density. Competitive moves center on M&A for technology acquisition and micro-fulfillment center deployment.
Within the integrated carrier tier, DHL and FedEx exemplify cross-border bonded warehouse strategies, while Amazon occupies a position as the captive infrastructure archetype. These three anchors represent divergent responses to delivery window compression, with each betting on distinct asset configurations to defend margin structures.
| Leading Market Players |
|---|
| SF Express |
| Kuehne + Nagel |
| Amazon |
| Nippon Express |
| USPS |
| DHL |
| FedEx |
| GEODIS |
| DSV |
| Others |
Value Chain & Pricing Dynamics
Captive logistics infrastructure anchors both supply positioning and pricing power for integrated carriers. E-commerce platforms building proprietary fulfillment networks in Indian metro corridors and Chinese tier-one cities extract margin control that asset-light operators surrender to variable-cost networks.
Pricing Analysis
Capacity additions in India and China are reshaping price floors across same-day delivery tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery window precision and urban density. Cost compression in standard delivery is intensifying because platform competition normalizes sub-two-hour guarantees. Small-format retailers exhibit highest price sensitivity, while pharmaceutical and high-value electronics buyers absorb premium scheduling fees.
Supply Chain Analysis
Dual-sourcing requirements for electric van and cargo bicycle fleets are mandating multi-supplier qualification across European procurement teams. Manufacturing concentrates in China, Germany, and the Netherlands for last-mile vehicle production. Battery cell supply, telematics hardware, and carbon-fiber frame materials feed from specialized tier-two suppliers. Single-source vulnerability in semiconductor-based route optimization chips threatens fleet management platform rollouts. Distribution runs through bonded warehouse networks in Frankfurt and Amsterdam for cross-border e-commerce corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The last-mile delivery market functions as a regulatory compounder. The EU Green Deal's fleet decarbonization mandates are accelerating procurement pull for zero-emission vehicles across member state implementations.
For Market Incumbents: Acquire micro-fulfillment center real estate within five kilometers of dense residential clusters in Mumbai, Bangalore, and Delhi-NCR. Integrate backward into electric van and cargo bicycle production through India's PLI scheme subsidies. Courier workforce shortages in key metropolitan corridors threaten fulfillment capacity during peak windows. For New Entrants and Emerging Players: Capture scheduled delivery slots with one-hour precision in European grocery and pharmaceutical verticals where incumbent fleet utilization gaps persist. Target German and French urban centers where click-and-collect networks displace home delivery for non-urgent shipments. Partner with cloud-based fleet management platforms to bypass route optimization talent scarcity. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists optimizing for density because delivery window compression favors micro-fulfillment infrastructure over national hub-and-spoke networks. Five-to-ten year viability hinges on bonded warehouse integration capabilities and customs pre-clearance system deployment. Monitor FAA beyond-visual-line-of-sight rule finalization as inflection indicator for autonomous vehicle delivery scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Center Deployment | Reduces last-mile transit distances below five kilometers in Indian metro corridors. |
| Electric Fleet Conversion | Aligns with EU Green Deal mandates and India's PLI scheme subsidy windows. |
| Dynamic Route Optimization Implementation | Compresses ETAs through machine learning-driven dispatch systems in high-density zones. |
| Bonded Warehouse Integration | Enables customs pre-clearance for cross-border e-commerce through Frankfurt and Amsterdam hubs. |
| Real-Time Visibility Platform Rollout | Synchronizes GPS-enabled tracking with warehouse management systems for failed delivery reduction. |
Study Parameters
Bottom-up e-commerce fulfillment modeling reconciled against top-down fleet operator tracking forms the analytical core. Primary interviews with logistics platform executives, courier operations managers, fleet procurement directors, and urban planning officials combine with secondary validation from EU regulatory filings, FAA airspace rule dockets, Indian BIS standards documentation, and customs trade databases. Top-down shipment volume estimates from national postal regulators cross-check against bottom-up capacity deployments from integrated carrier disclosures.
Input-output matrices map delivery mode adoption against urban emissions mandate compliance timelines across the analysis window. Segmentation dimensions include service type, delivery mode, customer archetype, and technology stack maturity. CAGRs derive from logistic curve fitting of fleet electrification penetration and micro-fulfillment center density trajectories. Forecast inputs incorporate charging infrastructure buildout schedules and beyond-visual-line-of-sight regulatory milestone probabilities.
Regulatory delay, labor availability constraints, and autonomous vehicle liability framework uncertainty are the dominant revision risks. Forecasts reflect assumptions on EU member state subsidy intensity divergence and Indian metro infrastructure investment pacing. Deviation in FAA rule finalization timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Global Automated Container Terminal Market
Logistics and Shipping
United States Contract Logistics Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global 3PL Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
GCC Finished Vehicle Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
Global Port Logistics Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
Iraq Freight and Logistics Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Poland Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market