
 In-Car Wireless Charging Market | 2026-2036
In-Car Wireless Charging Market Size, Share, and Industry Trends Forecast 2026-2036
In-Car Wireless Charging Market Outlook
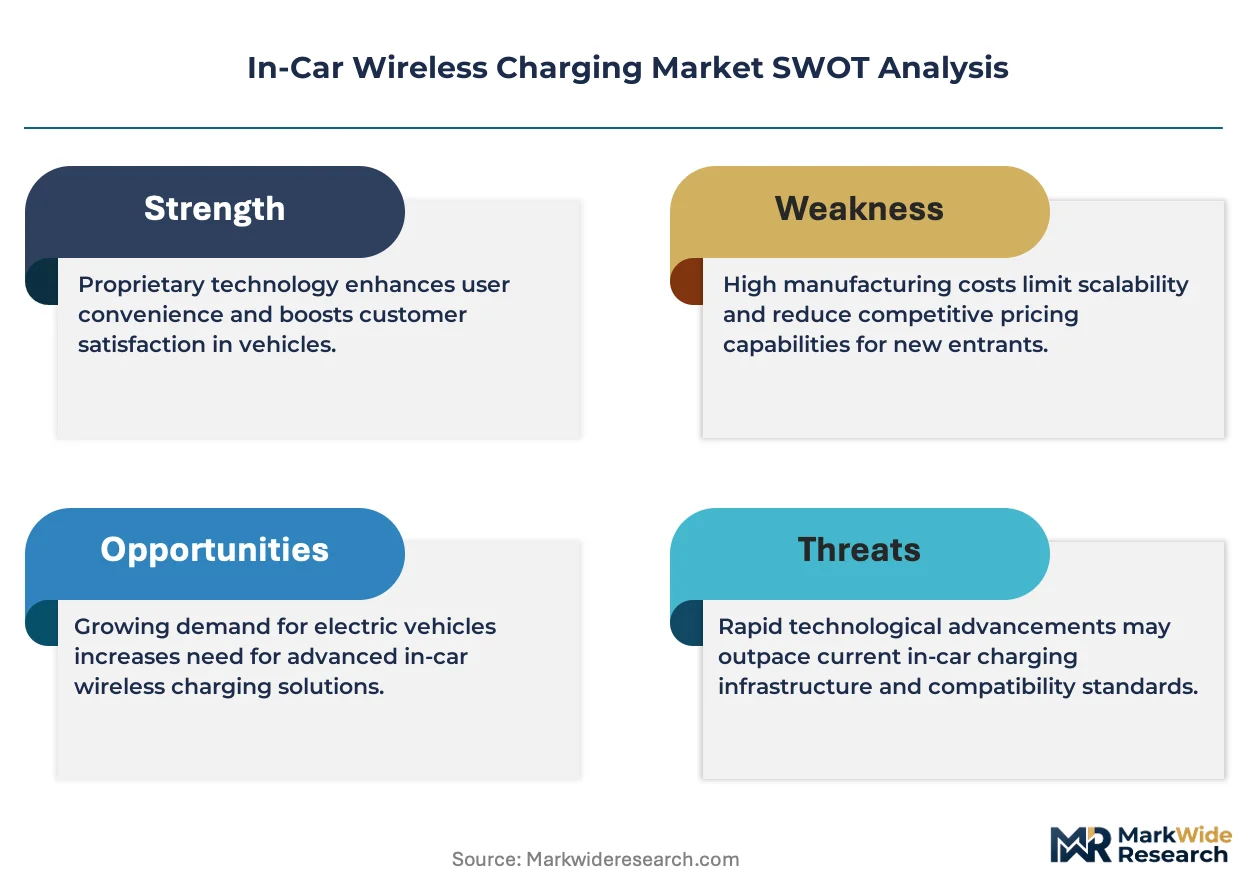
Qi2 certification from the Wireless Power Consortium is rotating the competitive landscape toward suppliers capable of meeting magnetic alignment and power transfer consistency thresholds. WiTricity Corporation leverages its magnetic resonance intellectual property to sustain technology leadership in high-power automotive applications. Qualcomm Technologies anchors the semiconductor layer with chipset solutions that integrate power management and near-field communication protocols. ENRX competes through its inductive charging infrastructure heritage extended into passenger vehicle environments.
In-car wireless charging denotes a cabin-integrated power transfer system that uses electromagnetic induction or magnetic resonance to replenish device batteries without physical connector insertion, typically operating at frequencies between 110-205 kHz with power outputs up to 50W in premium configurations. Its primary commercial purpose is to eliminate cable clutter while ensuring continuous device readiness for navigation, entertainment, and emergency communication during vehicle operation. Integrated solutions dominate current OEM fitment programs because they embed charging coils directly into center consoles and armrests during vehicle assembly. Inductive charging technology leads installed base volumes due to its maturity and Qi standard compatibility, though resonant charging is gaining traction for its spatial tolerance advantages in moving vehicles. Electric vehicles represent the fastest-growing vehicle type segment as battery-electric architectures natively accommodate higher-capacity auxiliary power circuits.
FCC Part 18 regulations in the United States govern electromagnetic field emissions from wireless power transmitters, while the EU Radio Equipment Directive mandates CE marking for all in-vehicle radio-frequency devices sold across member states. China's MIIT issues type-approval certificates for wireless charging modules integrated into domestically manufactured vehicles. Stakeholders must monitor evolving thermal management requirements and interoperability test protocols as regulatory bodies synchronize standards across major automotive production jurisdictions.
Market Dynamics
Qi2 magnetic alignment protocols from the Wireless Power Consortium are forcing component suppliers to retool coil manufacturing lines and recertify existing automotive programs, compressing margins for tier-two electronics vendors while rewarding early standard adopters.
Growth Catalysts
- EV Auxiliary Power Architecture:Battery-electric vehicles ship with higher-capacity 48V and 400V auxiliary circuits that natively support 15-50W wireless charging outputs without dedicated DC-DC conversion hardware.
- China MIIT Type-Approval Streamlining:China's Ministry of Industry and Information Technology consolidated wireless module certification into vehicle-level homologation, reducing time-to-market for domestic OEM integrated programs.
- Cabin Digitization Mandates:Premium German automakers now specify wireless charging as standard equipment across executive vehicle segments, pulling component demand through tier-one cockpit integration contracts.
Market Restraints
- Copper Coil Supply Concentration:High-purity copper winding stock for automotive-grade transmitter coils concentrates among East Asian metal processors, exposing OEMs to commodity price volatility and logistics disruption.
- Qi2 Retooling Capex:Magnetic ring array production requires precision ferrite stamping equipment that tier-two suppliers cannot finance without OEM volume guarantees, consolidating supply among capitalized incumbents.
- Inductive Efficiency Ceiling:Electromagnetic induction systems face theoretical power transfer limits below 50W without thermal runaway, constraining charging speed competitiveness against cabled USB-PD alternatives.
Strategic Opportunities
- Indian Domestic Manufacturing:India's PLI scheme for automotive electronics offers 4-6% incentive offsets on local wireless charging module production, attracting tier-one suppliers to Chennai and Pune industrial corridors.
- Magnetic Resonance Convergence:Resonant charging technology paired with dynamic vehicle positioning systems enables spatially tolerant charging pads for autonomous shuttle fleets in controlled-access zones.
- FCC Part 18 Harmonization:Proposed US regulatory alignment with EU Radio Equipment Directive emission thresholds would eliminate dual-certification costs, opening transatlantic component sourcing arbitrage.
Industry Challenges
- Qi2 Certification Bottlenecks:Wireless Power Consortium test lab capacity constraints extend pre-production validation timelines by 8-14 weeks, delaying SOP dates for MY2027 vehicle programs.
- Multiphysics Simulation Talent Scarcity:Coil thermal-electromagnetic co-design requires rare cross-trained engineers capable of optimizing ferrite core geometries against eddy current losses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Car Wireless Charging Market |
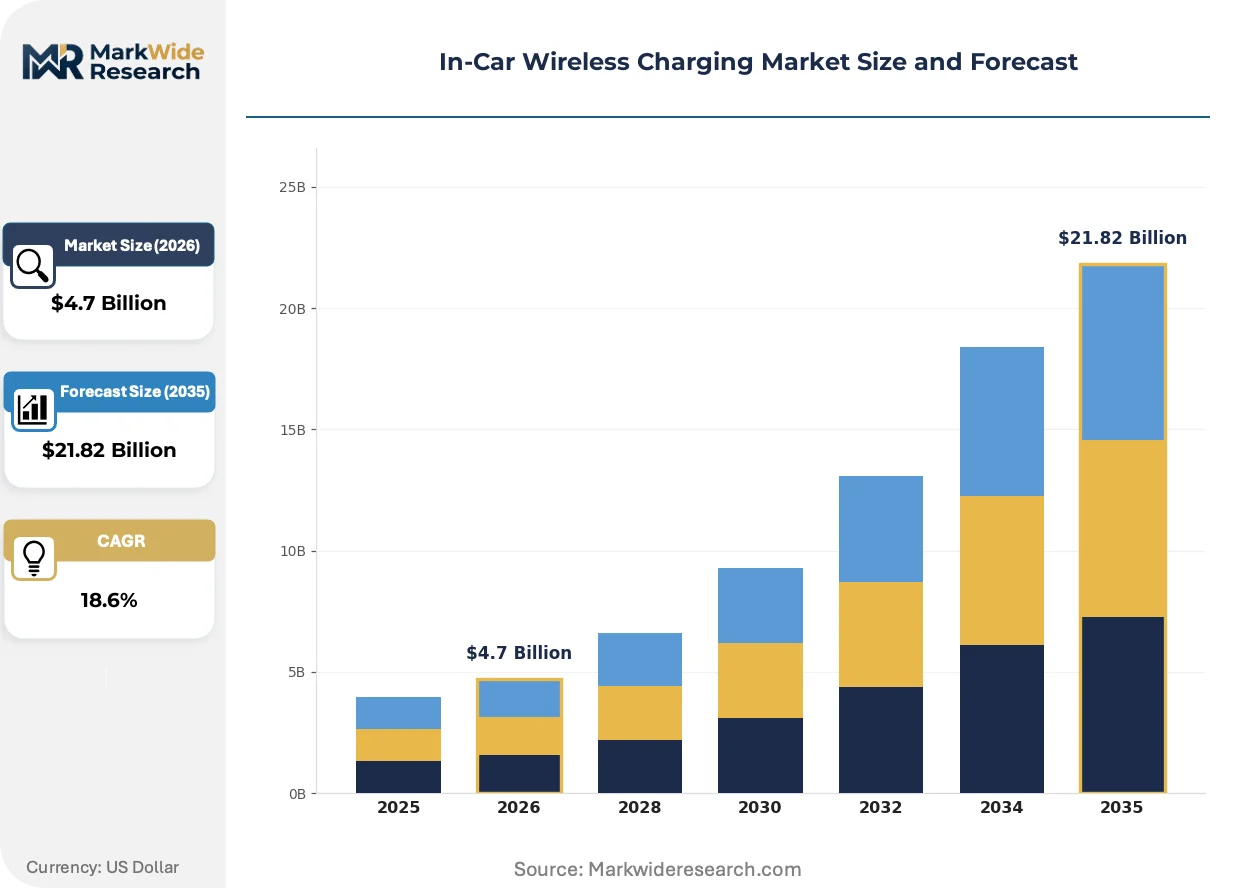
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding Chargers, Integrated Solutions, Charging Pads, Adapter Kits Technology: Inductive Charging, Resonant Charging, Capacitive Charging, Solar Charging End User: OEMs, Aftermarket Retailers, Fleet Operators, Rental Services Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | Electreon, ENRX, WiTricity Corporation, Qualcomm Technologies, BYD, Powermat, InductEV, Plugless Power, HEVO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Car Wireless Charging Market Strategic Shifts
Magnetic resonance architectures and intelligent coil arrays are displacing fixed-position inductive pads, enabling charging across larger spatial tolerances while integrating thermal sensing and foreign object detection into single semiconductor packages.
Multi-coil transmitter arrays with dynamic field shaping is miniaturizing charging pad footprints while maintaining 15W+ power delivery across 40mm Z-axis displacement. Tier-one cockpit integrators in Germany and Japan are adopting these modules for center console designs with curved or movable surfaces. The technology is compressing pad thickness requirements from 25mm to sub-12mm profiles, liberating packaging space for HVAC ducting and structural reinforcement.
EU Radio Equipment Directive 2014/53/EU enforcement is tightening electromagnetic compatibility testing for 110-205 kHz in-vehicle transmitters, requiring OEMs to submit full vehicle-level EMC documentation rather than component-level declarations. This regulatory shift is extending homologation timelines by 4-6 months for European-market vehicles. Suppliers with pre-certified module platforms are capturing incremental share from competitors forced into redesign cycles.
Automotive OEMs are consolidating wireless charging procurement under single-source cockpit electronics contracts, displacing standalone pad suppliers from RFQ processes. Tier-one integrators such as Continental and Bosch are absorbing coil manufacturing in-house, compressing the vendor base. This concentration is most visible in North American and German OEM programs, where cockpit domain controllers now bundle charging, NFC, and Bluetooth antenna functions into unified hardware stacks.
In-Car Wireless Charging Market Segmentation
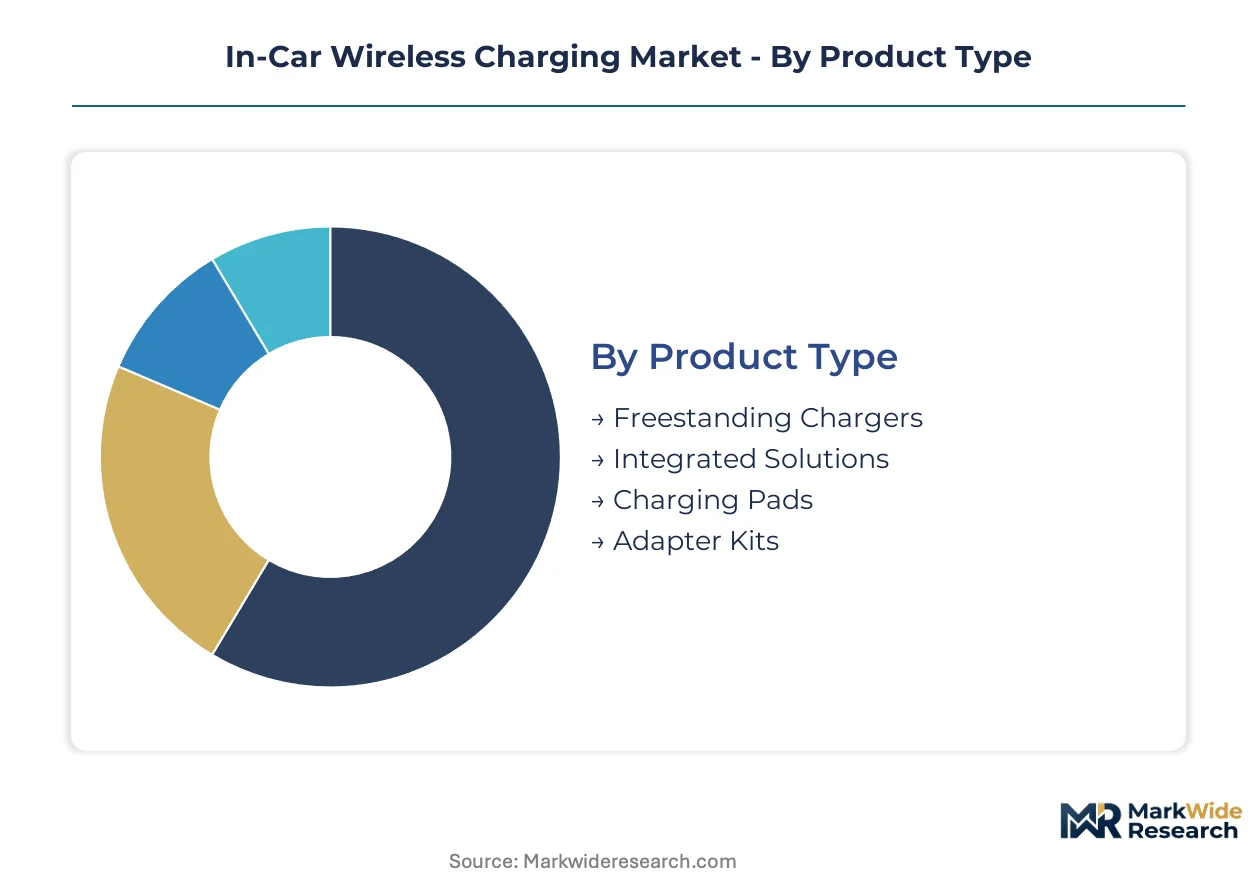
Segmentation in the in-car wireless charging market reveals how technology choices and installation methods determine pricing power and customer lock-in. Product architecture and power transfer physics create distinct competitive arenas with varying margin profiles and certification barriers.
Product Type:
Integrated solutions face the weakest substitution pressure due to factory-fit exclusivity and cockpit domain controller bundling, while freestanding chargers compete against cabled USB-PD alternatives in the accessory channel.
- Integrated Solutions:Factory-installed modules embed transmitter coils directly into center consoles and armrests during vehicle assembly, requiring tier-one cockpit integrator partnerships. German premium OEMs specify these as standard equipment across executive segments, locking out aftermarket alternatives through proprietary controller interfaces.
- Charging Pads:Surface-mounted transmitter assemblies with Qi2 magnetic alignment rings target retrofit applications and fleet refurbishment programs. China's MIIT type-approval streamlining accelerates domestic aftermarket distribution through Shenzhen electronics clusters.
- Freestanding Chargers:Portable units with adhesive or clip mounting mechanisms compete in the low-margin vehicle accessory channel.
- Adapter Kits:Receiver coil attachments enabling wireless charging on legacy devices without native support.
Integrated solutions anchor the volume base while charging pads gain share at the steepest rate.
Technology:
Cost tier stratification separates mature inductive platforms from premium resonant architectures requiring specialized ferrite core engineering and thermal management.
- Inductive Charging:Electromagnetic induction operating at 110-205 kHz dominates installed volumes through Qi standard compatibility and mature coil manufacturing infrastructure. FCC Part 18 emission compliance and EU Radio Equipment Directive harmonization sustain incumbent supplier positions.
- Resonant Charging:Magnetic resonance architectures enable spatially tolerant power transfer across larger Z-axis displacements, commanding premium positioning in luxury vehicle programs. WiTricity Corporation's intellectual property licensing structures create technology access barriers for unlicensed competitors.
- Capacitive Charging:Electric field coupling through conductive plates rather than magnetic coils.
- Solar Charging:Photovoltaic integration for trickle-charge auxiliary applications in sun-exposed mounting locations.
Inductive charging retains volume leadership while resonant charging expands most quickly in premium OEM programs.
End User:
Application concentration determines procurement scale, with OEMs consolidating wireless charging under single-source cockpit electronics contracts that exclude standalone suppliers.
- OEMs:Original equipment manufacturers specify wireless charging through tier-one cockpit integration contracts bundling NFC, Bluetooth antenna, and power management functions. North American and German OEM programs increasingly absorb coil manufacturing in-house through Continental and Bosch supply structures.
- Fleet Operators:Commercial vehicle and mobility service providers deploy standardized charging infrastructure across vehicle pools. India's PLI scheme for automotive electronics attracts tier-one suppliers to Chennai and Pune corridors for domestic fleet module production.
- Aftermarket Retailers:Electronics distributors and automotive parts chains serving retail replacement demand.
- Rental Services:Short-term vehicle providers equipping fleets with user-friendly charging amenities.
OEMs anchor the volume base while fleet operators gain share at the steepest rate.
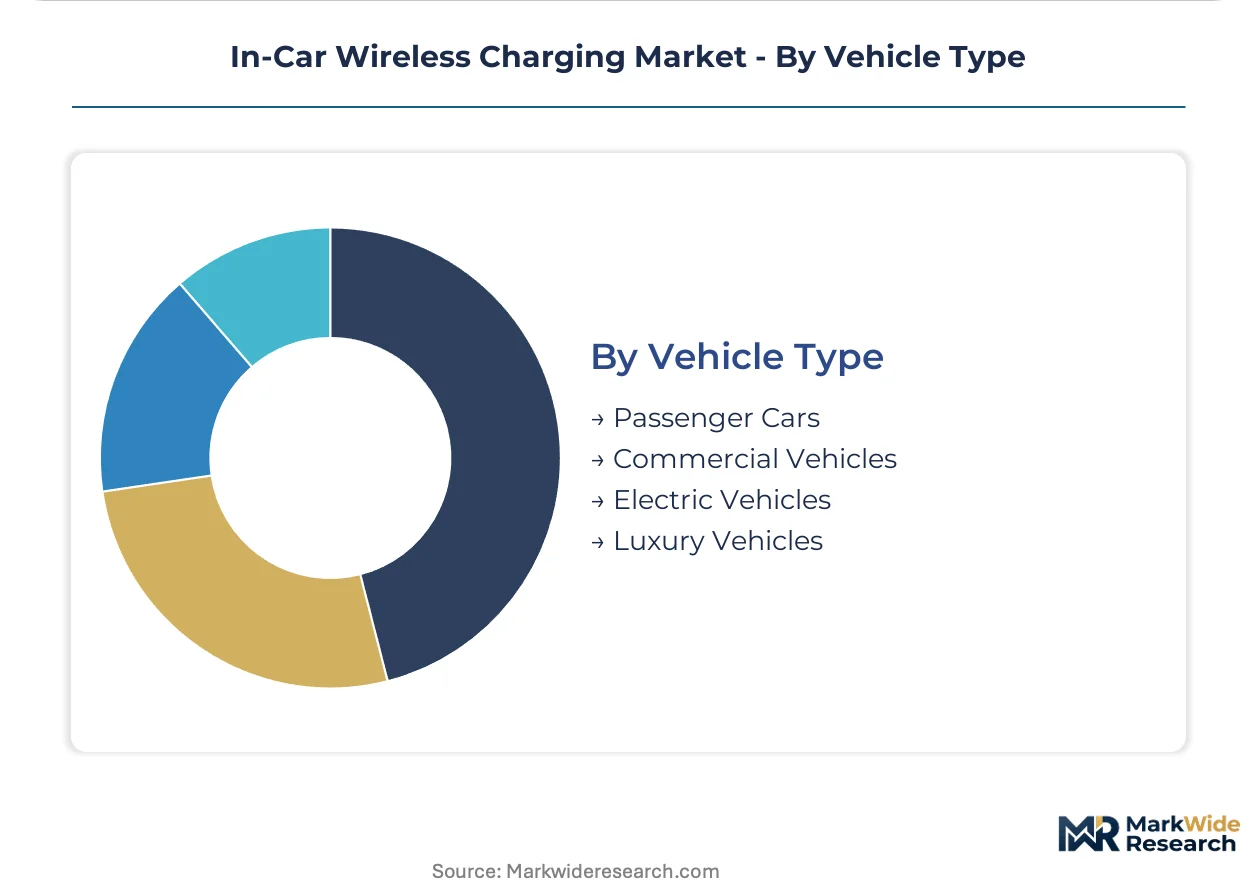
Vehicle Type:
Customer type stratification separates battery-electric architectures with native high-capacity auxiliary circuits from internal combustion platforms requiring DC-DC conversion hardware.
- Electric Vehicles:Battery-electric platforms ship with 48V and 400V auxiliary circuits supporting 15-50W wireless outputs without dedicated conversion hardware. Germany, China, and the United States concentrate EV penetration and cabin digitization investment.
- Luxury Vehicles:Premium segments specify wireless charging as standard equipment, pulling component demand through German automaker executive vehicle programs with curved or movable center console surfaces requiring multi-coil transmitter arrays.
- Passenger Cars:Mass-market light vehicle segments with cost-constrained feature availability.
- Commercial Vehicles:Heavy-duty and vocational applications with durability-focused specifications.
Passenger cars anchor the volume base while electric vehicles gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium automotive OEMs in Germany, China, and the United States drive procurement volume for factory-fit wireless charging modules. Battery-electric vehicle penetration and cabin digitization investment concentrate demand in these three markets. Regulatory harmonization efforts across FCC Part 18, EU Radio Equipment Directive, and China MIIT type-approval frameworks shape supplier qualification requirements.
Germany
Executive vehicle programs from BMW, Mercedes-Benz, and Audi specify wireless charging as standard equipment across curved center console designs. KBA homologation protocols enforce strict electromagnetic compatibility documentation for 110-205 kHz transmitters. Stuttgart and Munich industrial corridors host Continental and Bosch cockpit integration facilities absorbing coil manufacturing in-house.
China
Domestic OEMs BYD and NIO ship battery-electric platforms with 15-50W auxiliary circuits supporting native wireless outputs. MIIT consolidated wireless module certification into vehicle-level homologation, compressing time-to-market for integrated programs. Shenzhen electronics clusters accelerate aftermarket charging pad distribution through streamlined type-approval pathways.
United States
Detroit Three automakers bundle wireless charging into pickup truck and SUV interior packages targeting fleet and retail buyers. FCC Part 18 regulations govern electromagnetic field emissions from center console transmitters. Michigan and Ohio manufacturing corridors concentrate tier-one cockpit electronics production for North American vehicle programs.
Japan
Toyota and Honda integrate wireless charging into hybrid and battery-electric cabin architectures with multi-coil transmitter arrays. METI standards coordination with Qi2 protocols from the Wireless Power Consortium shapes component sourcing requirements. Nagoya and Tokyo industrial zones concentrate automotive electronics manufacturing for domestic and export vehicle fitment.
South Korea
Hyundai Motor Group and Kia specify resonant charging technology in Genesis luxury vehicle programs for spatial tolerance advantages. MFDS alignment with international electromagnetic compatibility standards streamlines module certification. Seoul Capital Area hosts Samsung and LG electronics manufacturing facilities supplying coil assemblies to tier-one integrators.
In-Car Wireless Charging Market Competitive Environment
Player mix skews toward technology licensors and tier-one cockpit integrators with in-house coil manufacturing capabilities. The vendor base compresses as automotive OEMs consolidate procurement under single-source domain controller contracts. Two strategic archetypes dominate: magnetic resonance IP holders licensing patented architectures, and diversified automotive electronics suppliers absorbing transmitter production. Competitive moves center on Qi2 certification pre-positioning and backward integration into ferrite core stamping operations.
Within the technology licensor archetype, WiTricity Corporation and Qualcomm Technologies occupy positions defined by magnetic resonance intellectual property and semiconductor integration capabilities respectively. ENRX represents the infrastructure heritage segment extending inductive charging expertise into passenger vehicle environments. These three companies exemplify how patent portfolios and regulatory pre-certification create defensive positioning against tier-two suppliers lacking capital for Qi2 retooling programs.
| Leading Market Players |
|---|
| Electreon |
| ENRX |
| WiTricity Corporation |
| Qualcomm Technologies |
| BYD |
| Powermat |
| InductEV |
| Plugless Power |
| HEVO |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at precision ferrite stamping facilities in East Asia sits above 85 percent, compressing available supply for Qi2 magnetic ring arrays while simultaneously elevating price floors for tier-two suppliers lacking volume commitments. This scale concentration rewards automotive OEMs with long-term offtake agreements while exposing smaller aftermarket pad manufacturers to spot-market volatility in copper winding stock.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate tier-one procurement, though Qi2 certification premiums now separate licensed suppliers from uncertified competitors. Price differentiation rests on magnetic alignment precision grades and thermal management integration levels. Cost compression in aftermarket charging pads is intensifying because Shenzhen electronics clusters flood distribution channels with unbranded alternatives. Fleet operators exhibit highest price sensitivity due to standardized volume procurement, while German premium OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Inventory buffers for automotive-grade ferrite cores stretch 14-20 weeks, exposing programs to disruption from any single-source stamping facility outage. Manufacturing concentrates in China, Japan, and South Korea, with high-purity copper winding stock drawing from Chilean and Indonesian smelter output. Single-source vulnerability concentrates in East Asian magnetic core processors capable of Qi2-compliant dimensional tolerances. Distribution runs through tier-one cockpit integrators rather than standalone module suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qi2 protocol adoption represents a high-growth disruption as magnetic alignment standardization forces wholesale supplier base consolidation across three major automotive production jurisdictions.
For Market Incumbents: Compound technology leadership through backward integration into ferrite core stamping operations and captive coil manufacturing capacity. Defend against resonant charging patent encroachment by accelerating WiTricity licensing negotiations. Prioritize Qi2 pre-certification investment to lock out capital-constrained tier-two competitors from RFQ processes. For New Entrants and Emerging Players: MIIT streamlined certification pathways offer fastest regulatory entry for domestic Chinese aftermarket distribution. Target India's PLI incentive corridors for manufacturing footprint establishment with 4-6 percent production offsets. Pursue fleet operator direct procurement relationships bypassing consolidated tier-one cockpit integration contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technology licensors with magnetic resonance IP portfolios and recurring royalty structures. Five-to-ten year viability favors suppliers with Qi2-certified module platforms and pre-established OEM qualification relationships. Monitor Wireless Power Consortium test lab capacity expansion as inflection indicator for certification bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Qi2 Certification Pre-Positioning | Early standard adoption secures tier-one cockpit integrator supply contracts ahead of MY2027 vehicle programs. |
| Backward Integration into Ferrite Core Stamping | In-house magnetic ring production eliminates single-source dependency on East Asian precision metal processors. |
| Magnetic Resonance IP Licensing Expansion | WiTricity patent portfolio monetization creates defensive moats against unlicensed resonant charging competitors. |
| India PLI Manufacturing Footprint | Chennai and Pune corridor production qualifies for 4-6 percent incentive offsets on domestic module assembly. |
| Fleet Operator Direct Procurement Relationships | Bypassing consolidated cockpit electronics contracts opens volume channels in commercial vehicle and mobility service segments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with tier-one cockpit integrators, automotive OEM platform engineers, aftermarket distribution channel managers, and Wireless Power Consortium certification specialists. Secondary validation drew from vehicle production databases, FCC Part 18 equipment authorization filings, EU Radio Equipment Directive compliance declarations, and MIIT type-approval registries. Bottom-up module shipment estimates were triangulated against top-down OEM fitment rate projections across propulsion architectures and vehicle classes.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation across product architecture, power transfer technology, end-user procurement type, and vehicle propulsion system. CAGRs were derived from fitted growth curves incorporating EV auxiliary power circuit penetration rates, cabin digitization investment trajectories, and regulatory harmonization timelines. Industry-specific inputs included Qi2 certification adoption curves and tier-two supplier consolidation patterns.
Decision-makers should treat outputs as directional under assumptions of sustained EV penetration and Qi2 standard adoption; material deviation in wireless power consortium protocol acceptance or copper commodity volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market
Automotive Electronics & Wiring
Automotive Ignition Coil Connector Market
Automotive Electronics & Wiring
Canada Automotive Camera Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Automotive Camera and Camera Module Market
Automotive Electronics & Wiring
UAE Automotive Sensors Market
Automotive Electronics & Wiring
North America Connected Car Market
Automotive Electronics & Wiring
Automotive Communication Technology Market
Automotive Electronics & Wiring
Global Automotive Junction Box Market
Automotive Electronics & Wiring
Asia Pacific in-Car Entertainment System Market
Automotive Electronics & Wiring
Automotive Wire Harness Tape Market
Automotive Electronics & Wiring
Automotive Oxygen Sensor Market
Automotive Electronics & Wiring
Locomotive Wiring Harness Market
Automotive Electronics & Wiring
Automotive Digital Cockpit Market
Automotive Electronics & Wiring
Voice Coil Motor Driver Market
Automotive Electronics & Wiring
Automotive Display Units Market