
 Global Freight Broker Software Market | 2026-2036
Global Freight Broker Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Freight Broker Software Market Foresight
ELD mandates across North American jurisdictions is consolidating compliance-driven procurement around platforms with native hours-of-service tracking. McLeod Software dominates the trucking company segment with specialized dispatch-to-accounting workflows. Descartes Systems Group extends its position through customs and trade compliance modules that anchor cross-border broker operations. MercuryGate International competes on multimodal optimization engines that sustain enterprise freight forwarder relationships.
Freight broker software constitutes digital platforms that automate load tendering, carrier procurement, shipment visibility, and financial settlement between shippers and transportation providers, typically integrating EDI, API, and telematics feeds to achieve real-time matching at sub-minute latency. Cloud-based deployment leads absolute spend as brokerages abandon server maintenance for elastic compute during peak seasons, while load matching solutions capture the fastest expansion as algorithmic pricing engines displace phone-and-email rate negotiation. Analytics dashboards now concentrate margin pools by converting historical lane data into predictive bidding models that third-party logistics providers deploy against contract volatility.
The Federal Motor Carrier Safety Administration shapes product roadmaps through ELD and hours-of-service enforcement, while the European Commission's CSRD and F-Gas Regulation force emissions transparency into carrier selection algorithms. The SEC's climate disclosure rules extend this pressure to U.S.-listed shippers, who now require Scope 3 transport data from broker partners. Stakeholders must decide whether to build carbon accounting natively or integrate specialized modules before regulatory thresholds harden into procurement requirements.
Market Dynamics
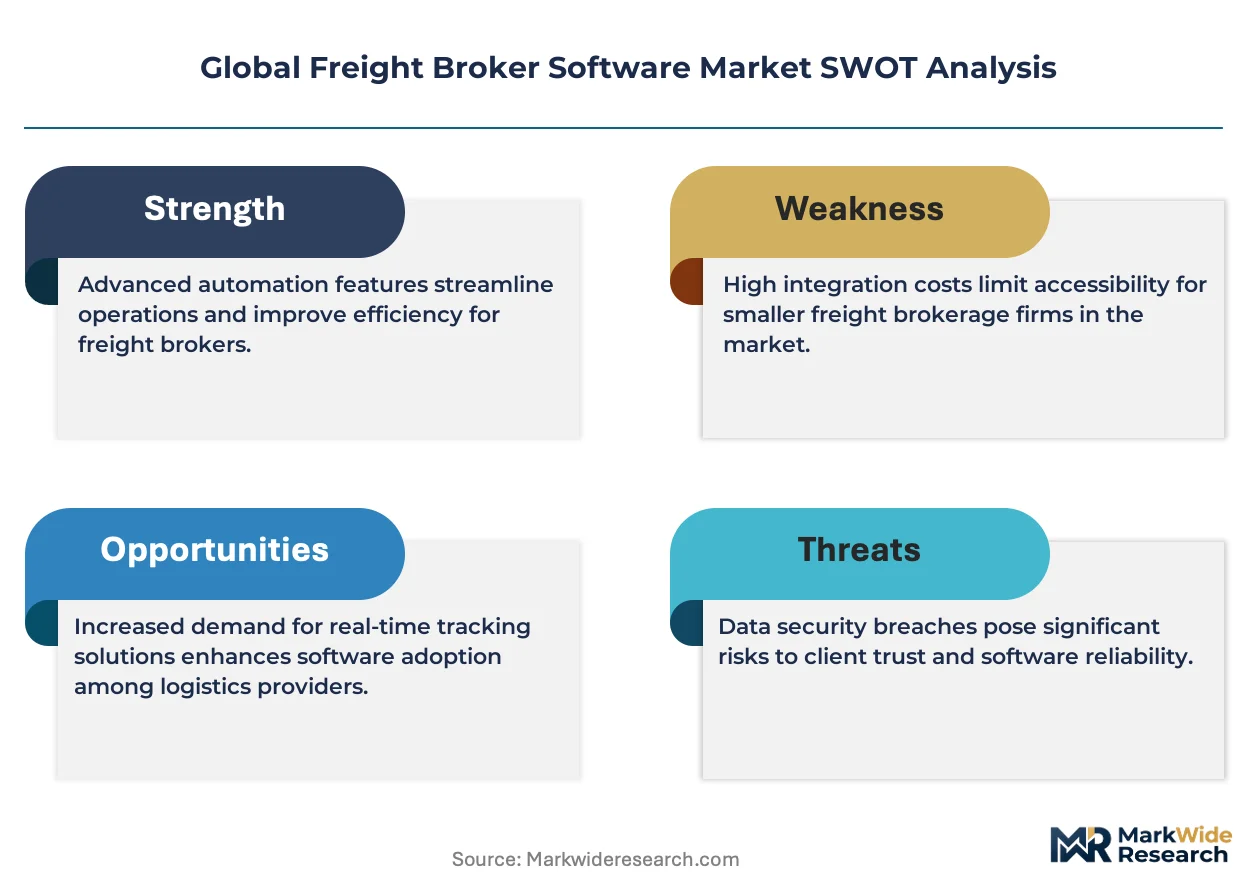
Algorithmic freight matching is compressing broker margins while simultaneously expanding transaction volumes, forcing incumbents to rebuild core platforms around sub-minute latency APIs or cede share to digital-native challengers.
Growth Catalysts
- EU Green Deal emissions mandates:Scope 3 transport reporting requirements are compelling European shippers to demand carbon-accounting modules from broker platforms, accelerating API-first procurement.
- ELD enforcement by FMCSA:Hours-of-service tracking integration has become non-negotiable for North American brokerages serving drayage corridors.
- Cloud elasticity:Third-party logistics providers are abandoning on-premise servers for auto-scaling compute during peak agricultural and retail seasons.
Market Restraints
- Telematics data fragmentation:Carrier ELD providers use incompatible protocols, forcing brokers to maintain multiple API integrations for single-lane coverage.
- Cyber insurance cost inflation:Ransomware attacks against transportation management systems have driven premiums up for mid-size brokerages.
- Driver shortage in US over-the-road segments:Capacity constraints limit the effectiveness of digital matching platforms regardless of software sophistication.
Strategic Opportunities
- India's logistics digitization:The country's national logistics policy and GST compliance requirements are creating first-mover advantages for API-native platforms entering freight aggregation.
- Predictive bidding engines:Machine learning models trained on historical lane volatility are enabling third-party logistics providers to capture margin from contract rate swings.
- Embedded finance integration:Real-time freight factoring and fuel advance products are opening new revenue streams within broker software interfaces.
Industry Challenges
- API standardization delays:The absence of universal data exchange protocols forces engineering teams to build and maintain custom connectors for each major carrier and shipper system.
- Legacy TMS migration friction:Decades-old dispatch databases resist cloud-native integration, requiring expensive middleware development for established brokerages.
- Data science talent scarcity:Algorithmic pricing and predictive analytics functions compete for scarce personnel against fintech and e-commerce sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Freight Broker Software Market |
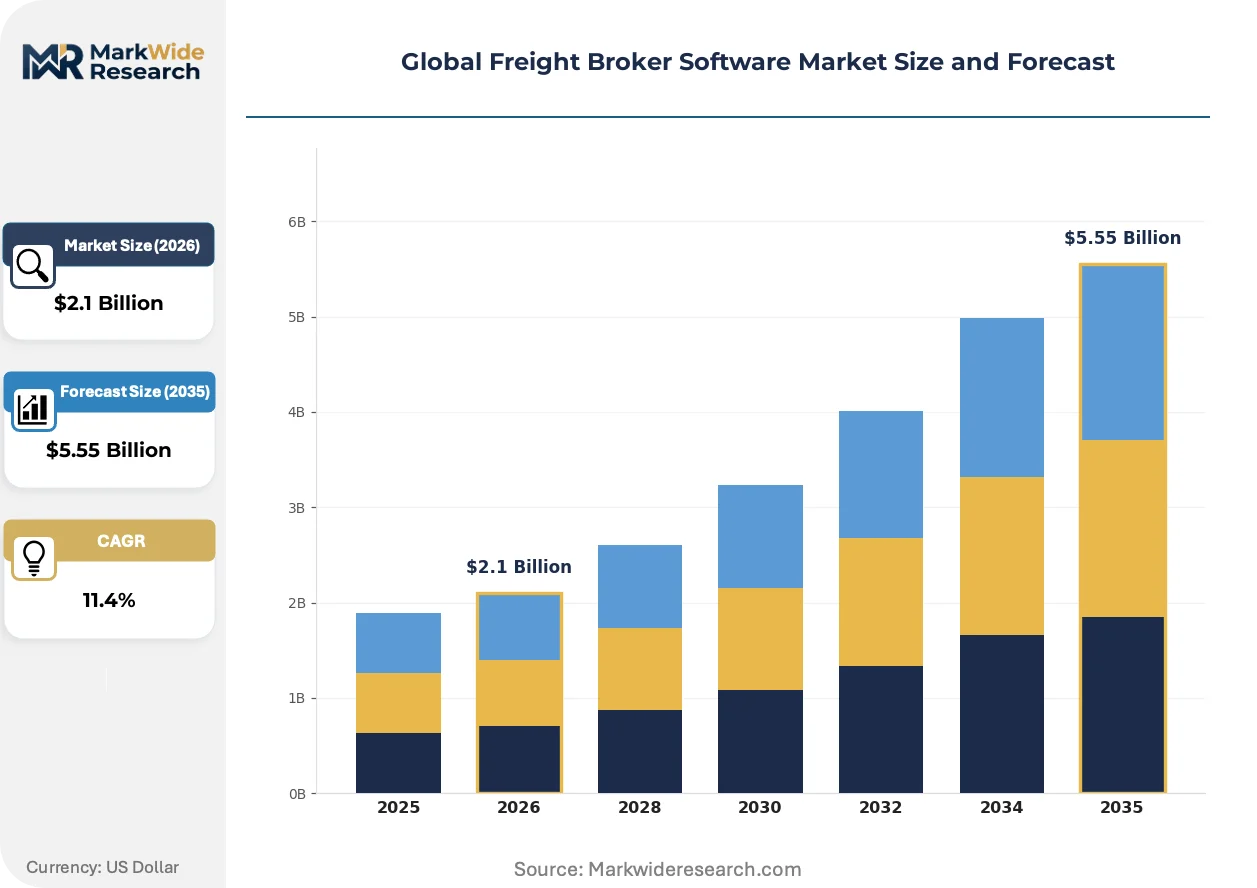
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Web-Based Solution Type: Load Matching, Shipment Tracking, Payment Processing, Carrier Management, Analytics Dashboard End User Sector: Third-Party Brokers, Freight Forwarders, Trucking Companies, Third-Party Logistics Providers Application: Route Optimization, Rate Negotiation, Carrier Selection, Freight Auditing, Customer Management |
| Companies Covered | McLeod Software, Descartes Systems Group, MercuryGate International, Oracle Transportation Management, SAP Transportation Management, Project44, Trimble Transportation, Manhattan Associates, Turvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Freight Broker Software Market Shifts & Advancements
Real-time visibility infrastructure is becoming the primary battleground for platform differentiation, with latency and data granularity now determining contract renewal rates among enterprise shippers.
Dynamic pricing engines powered by machine learning are overtaking static rate cards as the dominant tendering mechanism. Large third-party logistics providers deploy these systems to compress bid response times from hours to seconds. The structural consequence is a collapse in phone-and-email rate negotiation volumes across major US freight corridors.
The European Commission's CSRD and F-Gas Regulation are embedding emissions transparency into carrier selection workflows. Shippers listed on EU exchanges now require Scope 3 transport data from broker partners before contract award. German and Dutch chemical manufacturers have become the most aggressive adopters, using carbon intensity scores to filter carrier pools.
Shipper procurement teams are consolidating vendor relationships around platforms offering unified multimodal visibility. Discrete point solutions for trucking, ocean, and air are losing share to integrated suites. This consolidation is most visible among US retail and consumer packaged goods companies managing complex inbound supply chains.
Global Freight Broker Software Market Segmentation
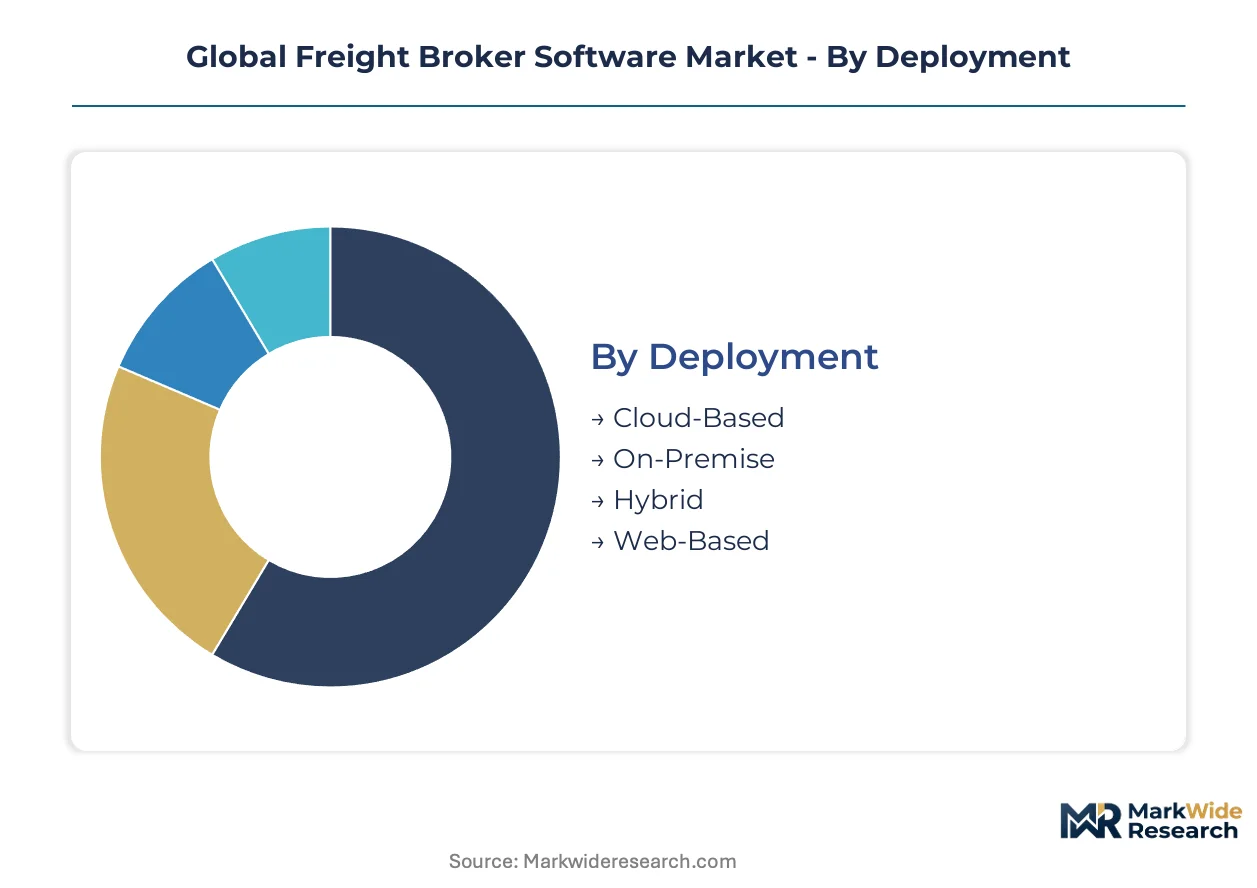
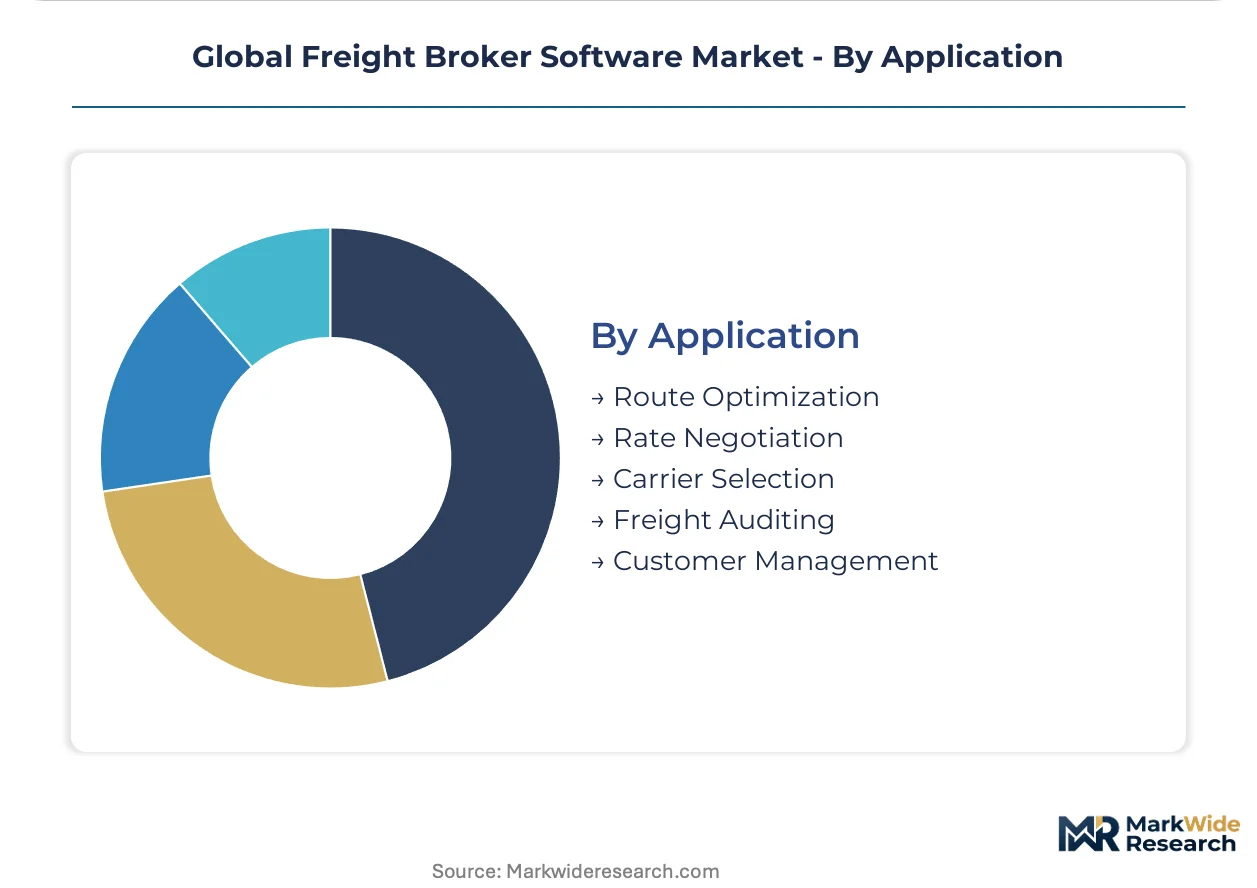
Freight broker software procurement patterns diverge sharply across deployment models, solution architectures, and buyer sophistication levels. Understanding these segment boundaries reveals where compliance burdens concentrate and where platform investments yield measurable operational leverage.
Deployment:
Cloud-native architectures face lighter certification overhead than on-premise installations, though SOC 2 Type II and ISO 27001 compliance remain table stakes for enterprise contracts.
- Cloud-Based:Elastic compute provisioning enables brokerages to scale processing capacity during peak agricultural harvests and retail holiday surges without capital expenditure. Demand concentrates among mid-size third-party logistics providers in the United States seeking to displace legacy server farms. The FMCSA's ELD data retention requirements have accelerated migration as cloud platforms offer automated backup compliance.
- On-Premise:Dedicated hardware installations persist where shippers mandate physical data sovereignty or where carrier integrations require sub-millisecond latency unreachable through internet transit. Large chemical manufacturers in Germany and the Netherlands specify on-premise deployments to satisfy EU Green Deal audit trail requirements for Scope 3 emissions verification.
- Hybrid:Split architectures run sensitive carrier contract data locally while pushing visibility feeds to cloud analytics layers. This model attracts established brokerages with decades of dispatch database history resisting full migration.
- Web-Based:Browser-delivered interfaces minimize IT overhead for small brokerages and owner-operator networks. Indian freight aggregators adopting the country's national logistics policy framework favor lightweight web deployments for rapid market entry.
Cloud-Based leads on scale; Web-Based leads on momentum.
Solution Type:
Margin capture potential varies dramatically across functional modules, with algorithmic engines commanding premium pricing against commoditized tracking layers.
- Load Matching:Real-time tendering platforms using machine learning to pair shipper freight with available carrier capacity at sub-minute latency. Third-party logistics providers in the United States deploy these systems to compress bid response times from hours to seconds, collapsing traditional phone-and-email rate negotiation volumes.
- Shipment Tracking:Visibility infrastructure aggregating ELD, telematics, and mobile driver app feeds into unified location streams. Retail and consumer packaged goods procurement teams consolidate vendor relationships around platforms offering multimodal tracking spanning drayage, over-the-road, and intermodal segments.
- Payment Processing:Automated freight settlement engines integrating factoring, fuel advances, and carrier quick-pay options. Embedded finance products are opening new revenue streams within broker software interfaces.
- Carrier Management:Onboarding, credential verification, and performance scoring workflows. Compliance with FMCSA safety ratings and insurance verification requirements drives procurement among US brokerages.
- Analytics Dashboard:Predictive bidding models converting historical lane volatility into margin capture opportunities. Third-party logistics providers deploy these against contract rate swings in volatile freight corridors.
Load Matching commands the steepest expansion trajectory; Shipment Tracking anchors the largest installed base.
End User Sector:
Buyer sophistication and integration complexity create distinct vendor selection criteria across brokerage archetypes.
- Third-Party Brokers:Independent intermediaries matching shipper freight with carrier capacity without asset ownership. These buyers prioritize rapid deployment and per-transaction pricing models over deep customization.
- Freight Forwarders:International logistics coordinators managing multimodal shipments across ocean, air, and surface networks. Customs and trade compliance modules anchor procurement decisions, with cross-border operations requiring integration with customs authorities in multiple jurisdictions.
- Trucking Companies:Asset-owning carriers expanding into brokerage services to backfill empty miles. Native hours-of-service tracking and dispatch-to-accounting workflows dominate their platform requirements under FMCSA enforcement regimes.
- Third-Party Logistics Providers:Integrated supply chain managers offering warehousing, transportation, and value-added services. These enterprise buyers demand API-first architectures that embed carbon accounting for EU CSRD compliance and SEC climate disclosure alignment.
Third-Party Logistics Providers lead on technology investment intensity; Third-Party Brokers lead on transaction volume growth.
Application:
Functional priority reflects underlying freight market structure, with automation potential highest in repetitive decision workflows.
- Route Optimization:Algorithmic planning engines minimizing empty miles and fuel consumption while respecting hours-of-service constraints. German chemical manufacturers apply carbon intensity scores from these tools to filter carrier pools under EU F-Gas Regulation mandates.
- Rate Negotiation:Dynamic pricing systems replacing static rate cards with machine learning-driven spot market responses. Digital-native challengers are displacing incumbent brokers through sub-second API tendering in major US freight corridors.
- Carrier Selection:Automated scoring of available capacity against cost, transit time, reliability, and emissions metrics. Scope 3 transport reporting requirements from the SEC and European Commission are embedding sustainability criteria into selection algorithms.
- Freight Auditing:Post-shipment verification of carrier invoices against contracted rates and actual service delivery. Mid-size brokerages facing cyber insurance cost inflation prioritize audit modules that detect billing anomalies indicating potential system compromise.
- Customer Management:Shipper portal interfaces for tender submission, visibility access, and performance reporting. Unified multimodal visibility is consolidating procurement around integrated suites rather than discrete point solutions.
Rate Negotiation shows the fastest technology displacement; Route Optimization delivers the most measurable cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering talent pools in Austin, Berlin, and Bangalore anchor platform development for freight matching algorithms, while regulatory enforcement in Washington, Brussels, and New Delhi shapes procurement priorities across broker networks.
United States
Third-party logistics providers in Chicago and Dallas-Fort Worth drive cloud migration as ELD mandates from the FMCSA harden hours-of-service compliance requirements. The SEC's climate disclosure rules now extend Scope 3 transport data obligations to broker partners of listed shippers. California's ports anchor drayage software demand where congestion intensifies real-time visibility procurement.
Germany
Chemical manufacturers in Ludwigshafen and Leverkusen filter carrier pools through carbon intensity scores mandated by the EU F-Gas Regulation. The EU Green Deal's emissions reporting requirements accelerate API-first platform investments across Rhine corridor freight networks. Berlin-based software vendors capture federal logistics digitization contracts.
India
Freight aggregators in Mumbai and Bengaluru adopt lightweight web deployments under the national logistics policy framework. GST compliance requirements create first-mover advantages for API-native platforms entering truckload matching. The DGFT's trade facilitation measures integrate broker software into port community systems.
United Kingdom
Cross-border brokers in London and Birmingham prioritize customs and trade compliance modules post-Brexit. The FCA's operational resilience requirements drive SOC 2 Type II certification among cloud platform providers. Manchester's inland freight terminals concentrate multimodal visibility procurement.
Netherlands
Rotterdam's port operators demand sub-millisecond latency APIs for container drayage matching. EU CSRD alignment forces Scope 3 transparency into carrier selection algorithms for Dutch chemical exporters. Amsterdam's logistics technology clusters specialize in predictive bidding engines for volatile Asia-Europe lanes.
Global Freight Broker Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment models and functional modules. The vendor base stratifies into three tiers: enterprise suites with multimodal coverage, mid-market platforms emphasizing rapid implementation, and niche providers targeting specific compliance verticals. Strategic differentiation concentrates on API latency performance and embedded finance integration. Incumbents defend position through middleware investments that bridge legacy dispatch systems, while challengers exploit cloud-native architectures to compress implementation timelines.
Within the enterprise suite tier, McLeod Software, Descartes Systems Group, and MercuryGate International occupy anchor positions. McLeod exemplifies the trucking-centric archetype with specialized dispatch-to-accounting workflows. Descartes represents cross-border compliance specialization through customs and trade module integration. MercuryGate sits within the multimodal optimization segment serving freight forwarder relationships. These three entities collectively illustrate how vendor selection maps to buyer operational profiles rather than undifferentiated scale advantages.
| Leading Market Players |
|---|
| McLeod Software |
| Descartes Systems Group |
| MercuryGate International |
| Oracle Transportation Management |
| SAP Transportation Management |
| Project44 |
| Trimble Transportation |
| Manhattan Associates |
| Turvo |
| Others |
Supply & Pricing Matrix
Cloud infrastructure costs from Amazon Web Services and Microsoft Azure flow through subscription tiers, compressing margins for mid-size brokerages while enabling elastic pricing for enterprise third-party logistics providers during peak agricultural seasons.
Pricing Analysis
Software vendors bundle load-matching engines with carrier management modules under tiered SaaS contracts, while unbundled API access commands premium per-transaction fees from digital-native challengers. Price differentiation rests on integration complexity and ELD protocol coverage breadth. Cost compression in the mid-market tier is intensifying because algorithmic matching is collapsing phone-negotiation volumes. Small brokerages and owner-operator networks exhibit highest price sensitivity; enterprise freight forwarders prioritize latency performance over license costs.
Supply Chain Analysis
Engineering talent scarcity in Austin, Berlin, and Bangalore constrains platform development velocity for real-time matching algorithms. Software engineering draws from computer science programs in these clusters, while implementation services feed from consulting networks in Chicago and Dallas-Fort Worth. Single-source vulnerability concentrates around hyperscaler cloud infrastructure. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as regulatory compliance mandates deepen software embedment into logistics workflows. The EU Green Deal and SEC climate disclosure rules create irreversible procurement tailwinds.
For Market Incumbents: Extend API latency capabilities through middleware investments that bridge legacy dispatch databases, defending against digital-native challengers exploiting cloud-native architectures. Deepen vertical integration into embedded finance products to capture freight factoring revenue streams. Certification investment in SOC 2 Type II and ISO 27001 anchors enterprise contract renewals.
For New Entrants and Emerging Players: Systems integrator partnerships offer the fastest path to shipper procurement teams consolidating around unified multimodal visibility platforms. Target India's freight aggregation sector where GST compliance requirements and national logistics policy frameworks create first-mover advantages for lightweight web deployments. API-native architectures compress implementation timelines against incumbent middleware dependencies.
For Investors and Strategic Acquirers: Consolidation pressure builds where telematics data fragmentation forces expensive custom connector maintenance across incompatible ELD protocols. Long-term viability favors platforms with native carbon accounting modules as Scope 3 reporting hardens into procurement requirements. Watch for algorithmic pricing engine differentiation as the inflection signal separating margin capture leaders from commoditized tracking providers.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Sub-minute latency tendering displaces phone-and-email rate negotiation in major US freight corridors. |
| Embedded Finance Integration | Real-time freight factoring opens recurring revenue streams within broker software interfaces. |
| Carbon Accounting Module Buildout | EU CSRD and SEC climate rules embed emissions transparency into carrier selection algorithms. |
| Legacy TMS Migration Services | Middleware development captures established brokerages resisting full cloud-native displacement. |
| Predictive Bidding Engine Deployment | Machine learning models trained on historical lane volatility capture margin from contract swings. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with freight broker operations directors, third-party logistics CTOs, carrier procurement managers, and ELD platform engineers combined with secondary validation against FMCSA enforcement data, EU Green Deal regulatory filings, SEC climate disclosure submissions, and cloud infrastructure spending reports. Bottom-up transaction volume estimates and top-down market sizing triangulated across deployment models and solution architectures.
Segment-weighting approaches distributed value across cloud-based, on-premise, hybrid, and web-based deployments, with further stratification by load matching, shipment tracking, payment processing, carrier management, and analytics dashboard solutions. CAGRs derived from logistic curve fitting to historical adoption patterns and regulatory enforcement timelines. Forecast inputs incorporated ELD mandate compliance deadlines and EU emissions reporting phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carrier ELD protocol standardization progress and cyber insurance market stability. Forecasts reflect documented assumptions around regulatory enforcement intensity and cloud infrastructure cost trajectories. Material deviation in FMCSA rulemaking or hyperscaler pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market
Logistics and Shipping
Mexico Last Mile Delivery Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Total Logistics Market
Logistics and Shipping
Intra-Asia Freight Forwarding Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Nigeria Air Freight Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Qatar Third-Party Logistics (3PL) Market
Logistics and Shipping
Inland Container Depot and Dry Port Market
Logistics and Shipping
Asia Pacific Event Logistics Market
Logistics and Shipping
US International Courier, Express, and Parcel (CEP) Market