
 Intake-Air Temperature Sensor Market | 2026-2036
Intake-Air Temperature Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Intake-Air Temperature Sensor Market Foresight
Asset-light leasing models for sensor testing and validation equipment is narrowing the capital barrier for mid-tier suppliers entering the intake-air temperature sensor value chain. Bosch Auto Parts leverages captive semiconductor fabrication to sustain margin control across thermistor and integrated circuit sensor lines. Delphi Corporation anchors its competitive stance through backward integration into ceramic substrate manufacturing. Sensata Technologies specializes in digital output architectures that reduce ECU calibration overhead for automotive OEMs.
An intake-air temperature sensor measures the thermal state of air entering an engine or climate system, typically employing thermistors with negative temperature coefficients of resistance ranging from −40°C to 150°C to signal engine control units for fuel mixture optimization. These devices serve the primary commercial purpose of enabling precise combustion control, emissions compliance, and thermal efficiency across powertrain and environmental management applications. Thermistor-based products dominate current automotive volumes due to proven durability and cost structure, while IoT-enabled sensor categories capture the fastest expansion as fleet operators and OEMs pursue predictive maintenance architectures. Digital sensor segments concentrate margin pools where electromagnetic compatibility certification and automotive-grade silicon supply create qualification barriers.
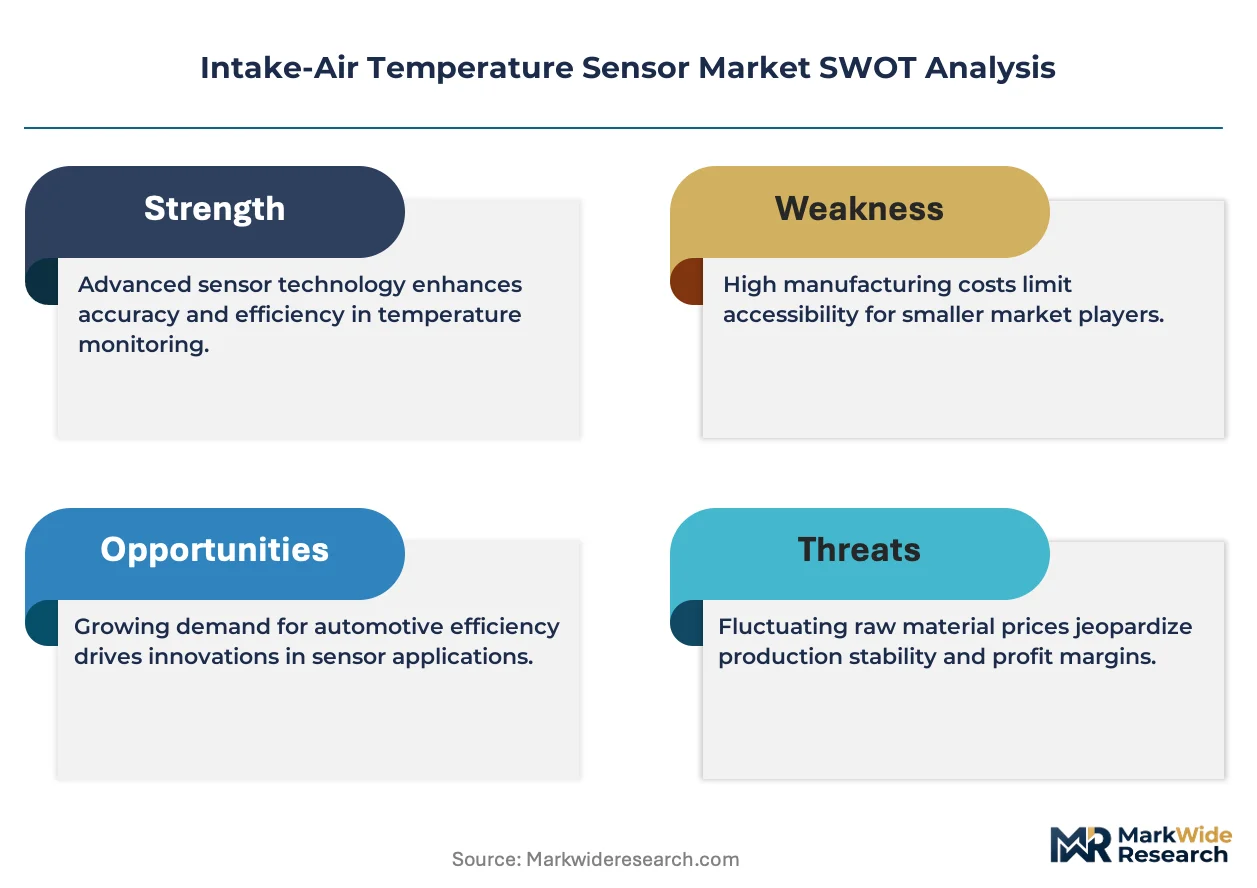
EPA tailpipe standards and Euro 7 emissions frameworks mandate tighter air-fuel ratio control, directly expanding specification requirements for intake-air temperature sensor accuracy and response time in gasoline and diesel powertrains. NHTSA fuel economy regulations in the United States and China's MIIT dual carbon goals further amplify sensor count per vehicle as hybrid systems multiply thermal monitoring nodes across engine and battery thermal loops. Stakeholders must monitor how software-defined vehicle architectures redistribute sensor value toward edge-computing modules and away from discrete analog components.
Market Dynamics
EPA tailpipe standards and Euro 7 emissions frameworks are compressing allowable engine-management tolerances, forcing automotive OEMs to specify intake-air temperature sensors with tighter accuracy bands and faster response curves across both combustion and hybrid powertrain architectures.
Growth Catalysts
- EPA Emissions Standards:Tighter air-fuel ratio control mandates in the United States expand specification requirements for sensor precision and thermal response time in gasoline and diesel powertrains.
- Hybrid Powertrain Proliferation:Dual combustion-electric architectures multiply thermal monitoring nodes across engine and battery thermal loops, increasing per-vehicle sensor counts.
- IoT-Enabled Predictive Maintenance:Fleet operators and OEMs pursue connected sensor architectures that enable real-time diagnostics and reduce unscheduled downtime.
Market Restraints
- Automotive-Grade Silicon Supply Concentration:Foundry capacity for qualified semiconductor substrates concentrates in East Asian manufacturing clusters, creating qualification bottlenecks for new sensor entrants.
- Electromagnetic Compatibility Certification Costs:OEM-tier qualification cycles for digital output architectures demand substantial upfront testing investment before volume procurement authorization.
- Thermistor Cost Floor:Mature negative temperature coefficient thermistor technology maintains pricing pressure on digital alternatives despite performance limitations.
Strategic Opportunities
- Software-Defined Vehicle Architectures:Edge-computing modules redistribute sensor value toward integrated digital outputs and away from discrete analog components, creating new design-win contests.
- Asset-Light Testing Equipment Leasing:Validation equipment leasing models narrow capital barriers for mid-tier suppliers seeking entry into automotive qualification pipelines.
- MIIT Dual Carbon Goals:China's Ministry of Industry and Information Technology decarbonization targets amplify sensor demand for thermal efficiency optimization in domestic hybrid production.
Industry Challenges
- Calibration Engineer Scarcity:Digital output architectures reduce but do not eliminate ECU calibration overhead, creating talent competition for embedded systems specialists capable of integrating multi-sensor thermal loops.
- Legacy Analog System Integration:Software-defined vehicle platforms must interface with existing powertrain control modules, complicating sensor firmware standardization across model years.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intake-Air Temperature Sensor Market |
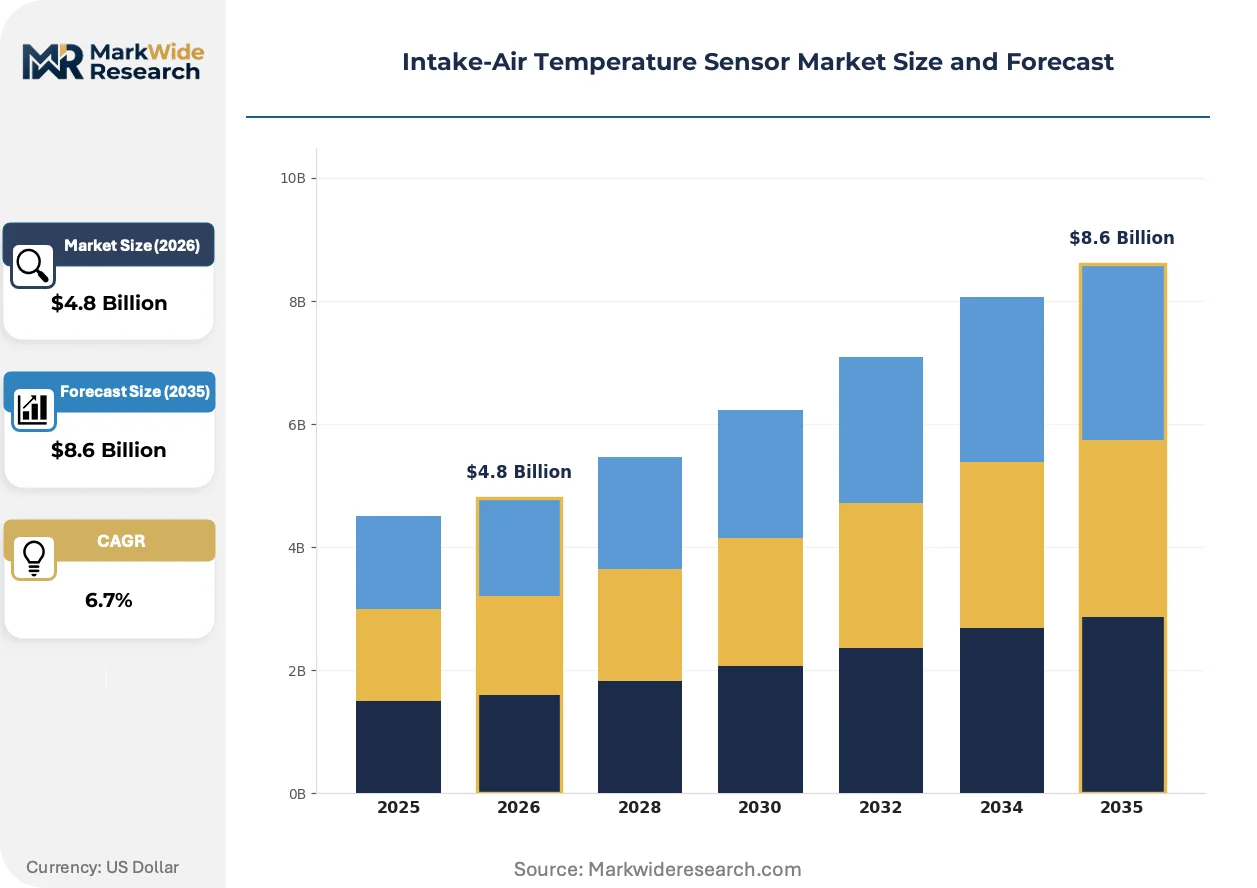
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermocouple, Thermistor, Resistance Temperature Detector, Integrated Circuit Sensor Application: Automotive, HVAC Systems, Industrial Equipment, Marine Engines End User: OEMs, Aftermarket Providers, Commercial Fleets, Logistics Companies Technology: Analog Sensors, Digital Sensors, Wireless Sensors, IoT-enabled Sensors |
| Companies Covered | Bosch Auto Parts, ACDelco Corporation, Hella Group, Delphi Corporation, Standard Motor Products Company, Federal-Mogul Motorparts Corporation, Amphenol Corporation, Sensata Technologies, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intake-Air Temperature Sensor Market Shifts & Advancements
Digital output architectures are compressing the traditional value chain for intake-air temperature sensing, collapsing the distinction between raw sensor production and calibrated subsystem supply while enabling new service-layer revenue for component vendors.
Silicon-based temperature sensing elements with integrated analog-to-digital conversion are collapsing the cost premium between thermistor and semiconductor approaches for automotive-grade applications. Tier-1 suppliers are adopting these devices for new hybrid platform launches at accelerated design cycles. The technology is collapsing the historical three-tier supplier structure into a consolidated landscape where captive silicon fabrication determines margin sustainability.
Euro 7 emissions frameworks mandate particulate and NOx monitoring with correlated intake-air thermal data, tightening sensor accuracy specifications to fractions of a degree Celsius. Powertrain engineers in Germany and France face recertification timelines that compress development windows. Diesel and lean-burn gasoline segments are responding with redundant sensor architectures that cross-validate thermal readings against mass-airflow calculations.
Fleet procurement departments are unbundling sensor supply from full engine-control-module contracts, creating direct component sourcing relationships previously intermediated by Tier-1 integrators. This disintermediation concentrates volume with sensor specialists capable of delivering digital outputs with embedded diagnostic protocols. North American heavy-duty truck operators are most visible in this shift, pursuing predictive maintenance contracts that require standardized sensor data streams across mixed OEM fleets.
Intake-Air Temperature Sensor Market Segmentation
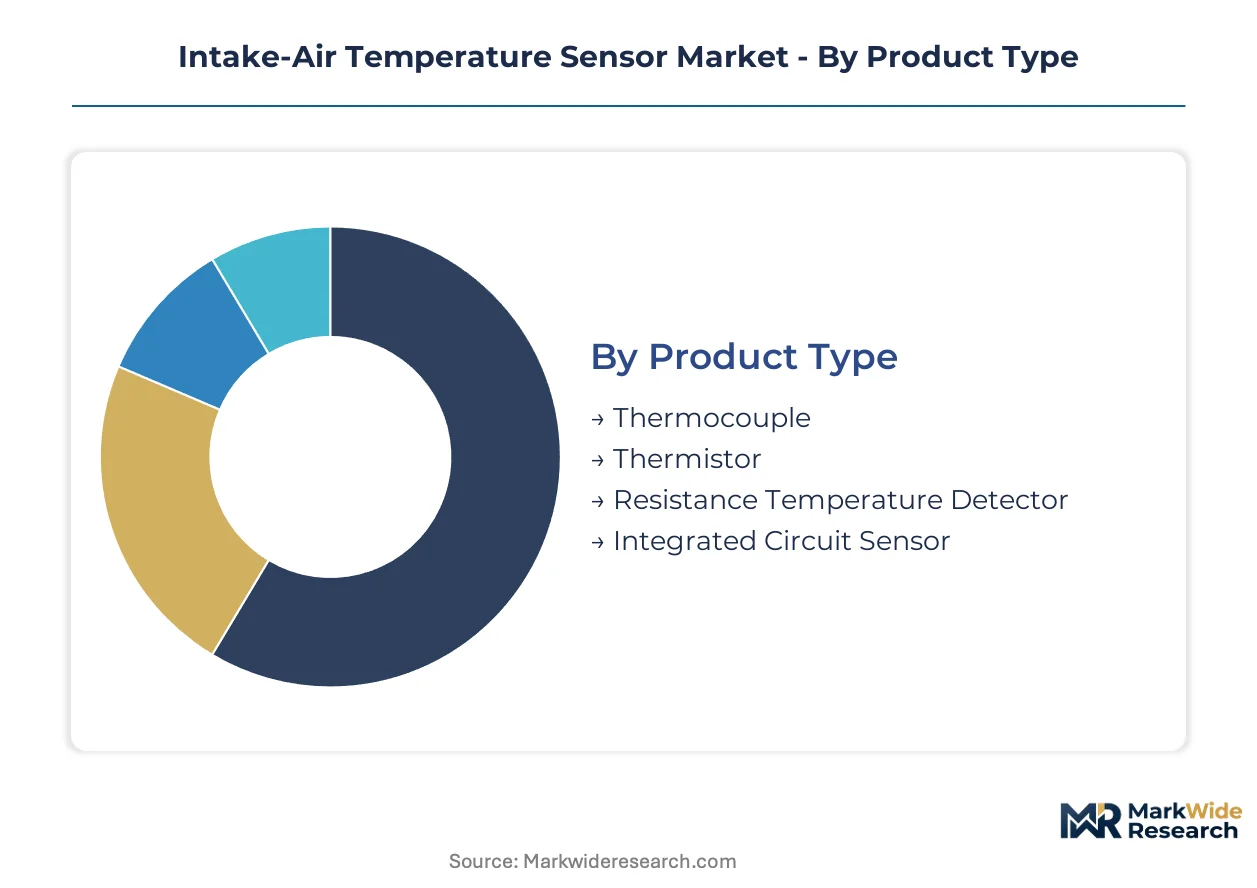
Intake-air temperature sensor procurement patterns diverge sharply across technical architectures and customer types. Cycle time variation between replacement-driven aftermarket channels and platform-locked OEM specifications creates distinct margin profiles and inventory strategies for component suppliers.
Product Type:
Thermistor and integrated circuit variants turn inventory fastest in high-volume automotive programs, while resistance temperature detectors and thermocouples anchor slower-moving industrial and marine replacement cycles.
- Thermistor:Negative temperature coefficient devices dominate automotive original equipment specifications with proven durability from −40°C to 150°C operating ranges. German and Chinese powertrain programs specify these for gasoline direct injection and hybrid thermal loops where cost sensitivity meets emissions compliance pressure.
- Integrated Circuit Sensor:Silicon-based elements with embedded analog-to-digital conversion collapse calibration overhead for ECU integration. United States hybrid platform launches specify these for battery thermal management nodes where response speed and diagnostic capability justify unit cost premiums.
- Thermocouple:Junction-based architectures serve exhaust gas recirculation monitoring and high-temperature industrial process control with wider thermal spans.
- Resistance Temperature Detector:Platinum or nickel thin-film elements deliver laboratory-grade precision for test bench and validation equipment applications.
Thermistor technology anchors the volume base while integrated circuit sensors gain share at the steepest rate.
Application:
Cost tier stratification separates precision-critical automotive powertrain specifications from price-sensitive commercial HVAC retrofit markets.
- Automotive:Engine management and battery thermal monitoring applications specify accuracy bands tightening under EPA and Euro 7 frameworks. OEM procurement concentrates in Germany, China, and the United States where hybrid architectures multiply sensor counts per vehicle platform.
- HVAC Systems:Climate control and refrigeration equipment demand centers on replacement cycles for commercial building infrastructure and residential heat pump installations.
- Industrial Equipment:Compressor monitoring and process thermal management applications favor resistance temperature detector precision for food processing and pharmaceutical manufacturing environments.
- Marine Engines:Salt-air corrosion resistance specifications drive material selection for commercial fishing vessel and pleasure craft propulsion systems.
Automotive applications command the margin premium tier while HVAC replacement demand provides the most predictable recurring revenue base.
End User:
Customer type determines contract structure complexity, with captive OEM supply agreements demanding longest qualification horizons and aftermarket channels rewarding fastest fulfillment responsiveness.
- OEMs:Volkswagen Group, Toyota Motor, and BYD specify intake-air temperature sensors through multi-year platform contracts with embedded volume commitments and zero-defect quality protocols.
- Aftermarket Providers:Bosch Auto Parts, Denso, and Continental distribute replacement sensors through distributor networks serving independent repair facilities.
- Commercial Fleets:North American heavy-duty truck operators pursue direct component sourcing to standardize predictive maintenance data streams across mixed manufacturer fleets.
- Logistics Companies:Refrigerated transport operators specify wireless-enabled cargo compartment monitoring for pharmaceutical and food cold chain compliance.
OEM contracts lock in the production volume base while commercial fleet direct sourcing is expanding most quickly as telematics integration deepens.
Technology:
Supply concentration in automotive-grade silicon fabrication creates qualification bottlenecks that stratify competitive access between analog legacy suppliers and digital architecture specialists.
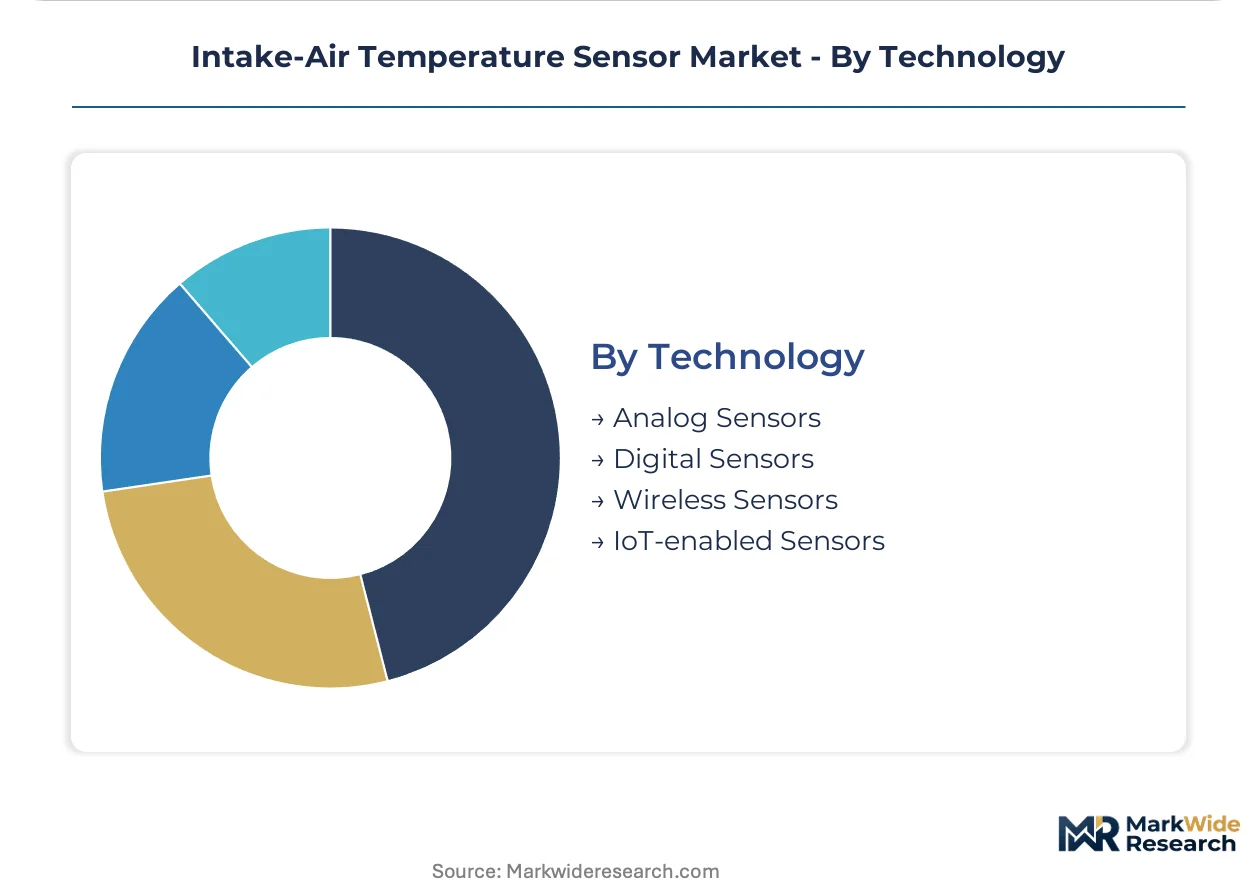
- Digital Sensors:Output architectures with embedded diagnostic protocols reduce ECU calibration engineering overhead. Sensata Technologies and similar specialists capture design wins in software-defined vehicle platforms where edge-computing modules redistribute sensor value.
- IoT-enabled Sensors:Connected architectures with predictive maintenance capability attract fleet procurement departments unbundling sensor supply from full engine-control-module contracts.
- Analog Sensors:Voltage-output thermistor circuits maintain cost floor advantage in mature powertrain platforms with legacy controller hardware.
- Wireless Sensors:Battery-powered or energy-harvesting architectures serve rotating equipment and sealed compartment applications where wired connectivity proves impractical.
Analog sensors retain the installed base volume while IoT-enabled architectures climb the fastest on fleet telematics investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA tailpipe standards and Euro 7 emissions frameworks are compressing allowable engine-management tolerances, forcing automotive OEMs across multiple jurisdictions to specify intake-air temperature sensors with tighter accuracy bands and faster response curves.
United States
NHTSA fuel economy regulations and EPA emissions mandates drive sensor precision requirements for gasoline direct injection and hybrid thermal loops. The Inflation Reduction Act accelerates domestic battery electric and hybrid platform investment. Detroit-Warren automotive cluster concentrates OEM procurement activity for next-generation powertrain programs.
Germany
KBA vehicle type approval processes enforce Euro 7 compliance timelines that compress sensor development windows. German powertrain engineers specify redundant thermal monitoring architectures for diesel and lean-burn gasoline segments. Stuttgart and Munich industrial corridors anchor supplier qualification pipelines for European OEM platform contracts.
China
MIIT dual carbon goals amplify sensor demand for thermal efficiency optimization across domestic hybrid production expansion. GB standards for vehicle emissions tighten allowable tolerances for air-fuel ratio control systems. Yangtze River Delta manufacturing clusters concentrate automotive-grade silicon fabrication capacity for qualified semiconductor substrates.
Japan
METI decarbonization roadmaps prioritize hybrid system deployment requiring precise thermal monitoring across dual combustion-electric architectures. JIS standards govern automotive sensor qualification protocols for domestic and export markets. Nagoya-Toyota industrial corridor sustains concentrated OEM procurement for integrated circuit sensor specifications.
South Korea
Ministry of Trade, Industry and Energy electric vehicle transition targets expand hybrid platform sensor counts per vehicle. Domestic emissions frameworks align with Euro 7-equivalent tolerances for powertrain thermal management. Seoul Capital Area and Busan-Ulsan manufacturing belts concentrate Tier-1 supplier engineering resources for digital output architectures.
Intake-Air Temperature Sensor Market Competitive Landscape
On the supply side, the industry is consolidating around semiconductor fabrication capabilities and automotive qualification expertise. Captive silicon production and backward integration into ceramic substrates distinguish margin-sustainable positions from commodity-dependent competitors. Three strategic archetypes dominate: diversified automotive component conglomerates with captive semiconductor fabrication, sensor specialists focused on digital output architectures, and aftermarket distributors leveraging brand recognition. Dominant competitive moves include strategic partnerships for IoT-enabled predictive maintenance platforms and geographic expansion into Chinese hybrid production corridors.
Among diversified automotive component conglomerates, Bosch Auto Parts and Delphi Corporation exemplify positions sustained through upstream control over critical material and fabrication inputs. Sensata Technologies occupies a specialist tier focused on digital sensor architectures that reduce ECU calibration overhead. These three anchors represent distinct competitive vectors: fabrication-integrated scale, substrate-integrated component supply, and digital architecture specialization.
| Leading Market Players |
|---|
| Bosch Auto Parts |
| ACDelco Corporation |
| Hella Group |
| Delphi Corporation |
| Standard Motor Products Company |
| Federal-Mogul Motorparts Corporation |
| Amphenol Corporation |
| Sensata Technologies |
| TE Connectivity |
| Others |
Supply & Pricing Matrix
Yangtze River Delta semiconductor fabrication clusters anchor global automotive-grade silicon capacity, concentrating upstream bargaining power among qualified substrate suppliers and compressing margin pools for downstream sensor assemblers without captive foundry access.
Pricing Analysis
Certification level creates the primary spread between automotive-grade and industrial-tier products, with AEC-Q100 qualified silicon commanding substantial premiums over commercial-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies the market, where OEM platform contracts with zero-defect protocols absorb the highest tier while aftermarket channels compete on fulfillment speed at thinner margins. Pricing pressure stems from thermistor cost floors in mature powertrain platforms, though digital sensor segments resist compression through embedded diagnostic value. Commercial fleet buyers exhibit the greatest price sensitivity as they unbundle sensor procurement from full engine-control-module contracts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for sensor manufacturers dependent on cross-border semiconductor substrate flows. Production gravity centers on China, Germany, and Japan, with Yangtze River Delta, Stuttgart industrial corridor, and Nagoya-Toyota belt feeding qualified component streams. Raw material dependencies include ceramic substrates, platinum thin-films for resistance temperature detectors, and specialized thermistor oxide formulations. Distribution runs through Tier-1 integrator channels for OEM volume, while direct component sourcing from fleet operators is disintermediating traditional aftermarket structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intake-air temperature sensor demand sits in early-cycle expansion as hybrid powertrain architectures multiply thermal monitoring nodes per vehicle platform beyond legacy combustion-only baselines.
For Market Incumbents: Build captive semiconductor fabrication moats to defend margin sustainability against digital architecture specialists. Bosch Auto Parts and Delphi Corporation exemplify this through upstream control over thermistor and ceramic substrate production. Incumbents must accelerate IoT-enabled sensor development before fleet procurement departments complete their unbundling of sensor supply from engine-control-module contracts. Certification investment in Euro 7 and EPA compliance protocols remains essential for platform-lock with Volkswagen Group, Toyota Motor, and BYD.
For New Entrants and Emerging Players: Mid-tier commercial fleet direct sourcing relationships in North America represent the most penetrable entry point, bypassing entrenched Tier-1 integrator relationships that dominate OEM channels. Asset-light leasing models for sensor testing and validation equipment narrow capital barriers for qualification pipeline entry. New entrants should pursue digital output architectures with embedded diagnostic protocols, targeting software-defined vehicle platforms where edge-computing modules redistribute sensor value away from established analog suppliers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor specialists with fleet telematics integration capabilities, as predictive maintenance contracts extend component lifecycles into service-layer revenue streams. Acquisition targets should display automotive-grade silicon qualification expertise or backward integration into ceramic substrate manufacturing. The signal to watch is hybrid platform sensor count expansion beyond current per-vehicle baselines, indicating sustained content growth across powertrain electrification cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Semiconductor Fabrication | Bosch Auto Parts sustains margin control through in-house thermistor and integrated circuit production. |
| Digital Output Architecture Development | Sensata Technologies reduces ECU calibration overhead for automotive OEM platform engineers. |
| Backward Integration into Ceramic Substrates | Delphi Corporation anchors competitive positioning through upstream control over critical material inputs. |
| IoT-Enabled Predictive Maintenance Platforms | Fleet operators unbundle sensor supply from full engine-control-module contracts for standardized data streams. |
| Geographic Expansion into Chinese Hybrid Production | MIIT dual carbon goals amplify sensor demand across Yangtze River Delta manufacturing clusters. |
Research Methodology
The analysis maps thermistor, integrated circuit, thermocouple, and resistance temperature detector sub-sectors, each validated through Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distribution channel heads, and commercial fleet operations managers. Primary interview intelligence combined with secondary validation from vehicle production databases, EPA regulatory filings, Euro 7 framework documents, and automotive-grade silicon foundry capacity disclosures. Bottom-up sensor unit economics triangulated against top-down powertrain production forecasts across gasoline direct injection, diesel, and hybrid architectures.
Assumptions held fixed include prevailing EPA tailpipe standards and Euro 7 emissions frameworks, while hybrid powertrain penetration rates and software-defined vehicle adoption curves were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product type, application, end user, and technology architecture, with propulsion system mix and regional production cluster providing additional stratification. CAGRs derived from unit volume trajectories and average selling price evolution across the projection horizon, incorporating battery thermal management node expansion and fleet telematics investment cycles as industry-specific inputs.
Practitioners should monitor automotive-grade silicon foundry capacity utilization, Euro 7 recertification timeline compressions, and fleet procurement unbundling velocity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Throttle Cable Market
Vehicle Components
Automotive Wheel Hub Bearing Aftermarket Market
Vehicle Components
Navigation Light Market
Vehicle Components
Piston Market
Vehicle Components
Forklift Seats Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Portable Wheel Jack Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Motor Monitoring Market
Vehicle Components
Italy Automotive Glass Fiber Composites Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Electric Forklifts Market