
 Germany Automotive 3PL Market | 2026-2036
Germany Automotive 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive 3PL Market Foresight
Market Context with Strategic Players
Automotive parts distribution in Germany is tilting toward integrated fourth-party logistics models that bundle sequencing, milk runs, and just-in-time yard management. DB Schenker leverages its rail-road intermodal backbone to dominate inbound supply to Volkswagen Group plants. Dachser sustains competitive density through its European Food and Network Logistics division adapted for automotive component flows. Rhenus Logistics anchors its position via specialized finished-vehicle logistics and plant-adjacent warehousing across Bavaria and Lower Saxony.
Technical Definition and Structural Segments
Germany automotive third-party logistics encompasses outsourced supply chain management for vehicle manufacturers and component suppliers, spanning transport coordination, inventory buffering, sequencing centers, and cross-docking facilities operating within tolerance windows as tight as two hours for production line delivery. The primary industrial purpose is to convert fixed logistics assets into variable costs while maintaining OEM production rhythm. Road freight within the transportation mode category retains the largest revenue pool but faces margin compression from driver shortages and emission compliance costs. Inventory management services are expanding fastest as OEMs push vendor-managed inventory programs onto Tier-1 suppliers. Strategic integration levels command premium pricing because they embed logistics providers into product development cycles and demand forecasting systems.
Regulatory Frame and Forward-Looking Close
Germany's Supply Chain Due Diligence Act (LkSG), enforced by the Federal Office for Economic Affairs and Export Control (BAFA), obliges automotive 3PL providers to audit subcontractor labor practices and environmental standards across their networks. The EU Green Deal's Fit for 55 framework and Germany's national CO2 pricing for transport fuels are accelerating fleet electrification mandates that reshape provider cost structures. Stakeholders must monitor whether battery-electric truck infrastructure deployment keeps pace with OEM decarbonization timelines for Scope 3 emissions reporting.
Market Dynamics
Germany's Supply Chain Due Diligence Act (LkSG) is forcing logistics providers to restructure subcontractor audit protocols and embed compliance costs into service pricing. Battery-electric vehicle production ramp-ups are simultaneously reshaping inbound material flows and warehouse specifications across the automotive corridor.
Growth Catalysts
- EU Green Deal Fit for 55 framework:Transport electrification mandates are accelerating fleet renewal programs among contract logistics operators serving OEM assembly plants.
- Baden-Württemberg manufacturing concentration:Stuttgart-centered vehicle production generates dense supplier networks that reward specialized sequencing and milk-run consolidation services.
- Lithium-ion battery logistics:Thermal-controlled transport and hazardous materials certification requirements are creating defensible service niches for qualified 3PL providers.
Market Restraints
- Professional driver shortage:Demographic contraction in Germany's commercial trucking workforce compresses fleet utilization rates and inflates wage costs.
- Diesel fuel price volatility:Unhedged exposure to mineral oil tax fluctuations erodes margin predictability for road-dominant operators.
- Battery-electric truck infrastructure gaps:Insufficient high-power charging corridors along autobahn freight routes limit zero-emission fleet deployment timelines.
Strategic Opportunities
- Bavaria battery gigafactory cluster:New cell production facilities near Munich and Nuremberg demand specialized inbound chemical logistics and outbound module distribution.
- Vendor-managed inventory expansion:OEMs are transferring finished goods ownership risk to Tier-1 suppliers, creating demand for consignment warehousing services.
- Rail-road intermodal integration:Combined transport subsidies under Germany's Federal Ministry for Digital and Transport guidelines favor terminal-adjacent 3PL facilities.
Industry Challenges
- LkSG subcontractor audit complexity:Tier-2 and Tier-3 supplier due diligence across Eastern European sourcing networks strains compliance resource allocation.
- Legacy warehouse management system integration:Proprietary OEM scheduling platforms require costly API development for real-time inventory synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive 3PL Market |
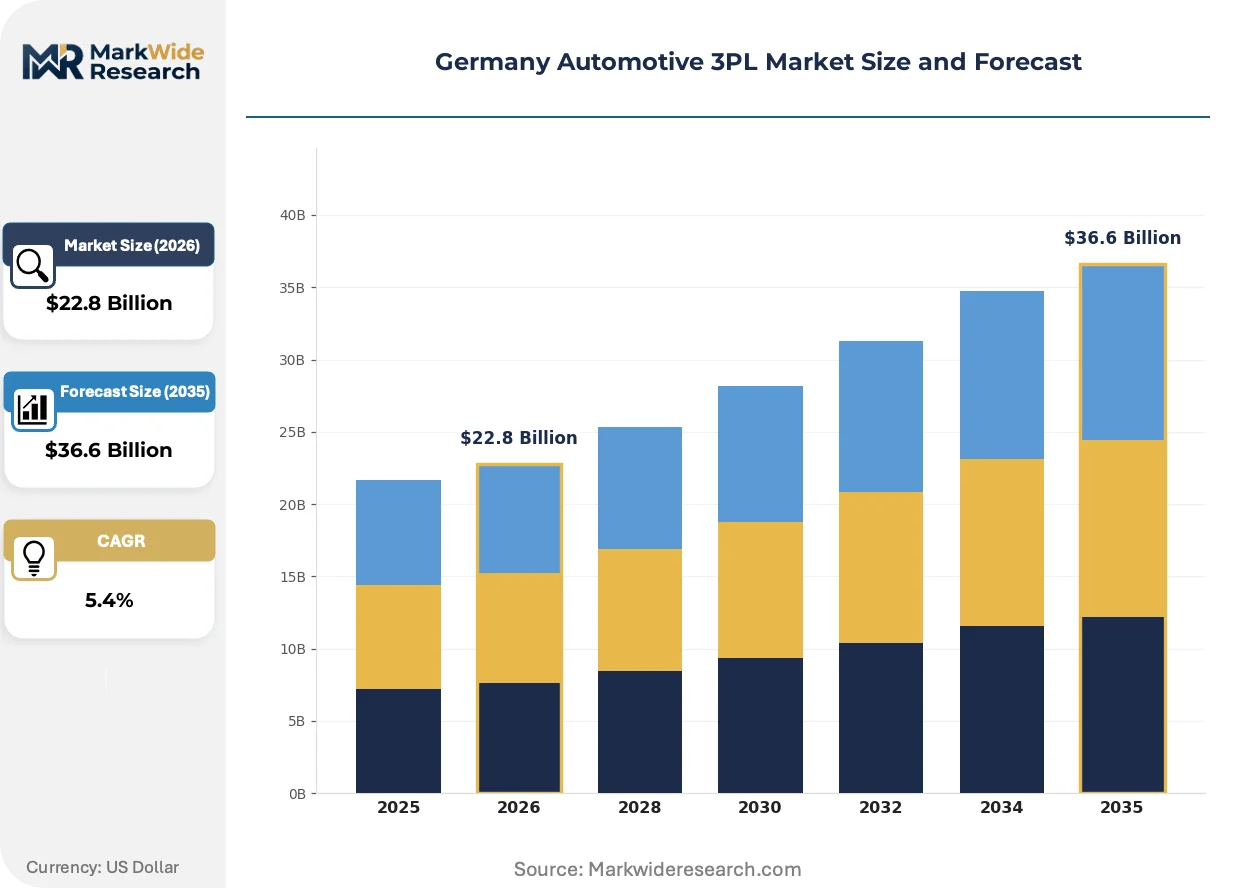
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $36.6 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Distribution Management, Inventory Management, Order Fulfillment Customer Type: Vehicle Assemblers, Tier-1 Suppliers, Dealerships, Aftermarket Providers Transportation Mode: Road Freight, Rail Freight, Inland Waterways, Air Cargo, Intermodal Integration Level: Operational, Tactical, Strategic, Collaborative |
| Companies Covered | Rhenus Logistics, Dachser, DB Schenker, DSV, Geodis, DHL Supply Chain, Hellmann Worldwide Logistics, Honold Logistik, Kuehne + Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive 3PL Market Shifts & Advancements
Digital twin technology is hybridizing physical warehouse operations with predictive simulation layers. Logistics providers are racing to embed artificial intelligence into demand forecasting while regulatory pressure accelerates decarbonization investments.
Autonomous mobile robots for automotive component sequencing are hybridizing manual pick operations with machine vision-directed automation. Tier-1 suppliers in Lower Saxony are piloting these systems for just-in-time battery module delivery to Volkswagen Group plants. The technology is hybridizing labor cost structures and compressing error rates in high-variability kitting operations.
Germany's national CO2 pricing for transport fuels is accelerating fleet electrification roadmaps among contract logistics operators. The Federal Ministry for Economic Affairs and Climate Action enforcement timeline pressures providers to secure battery-electric truck allocations ahead of infrastructure maturity. Road freight segments serving premium OEM brands face the steepest compliance cost absorption challenges.
Sequencing center location strategy is rotating toward plant-adjacent micro-fulfillment models. Procurement departments at BMW Group and Mercedes-Benz Group are consolidating supplier base geography to enable sub-50-kilometer delivery radii. This pattern is most visible in Baden-Württemberg and Bavaria, where land scarcity near assembly sites intensifies vertical development of automated storage facilities.
Germany Automotive 3PL Market Segmentation
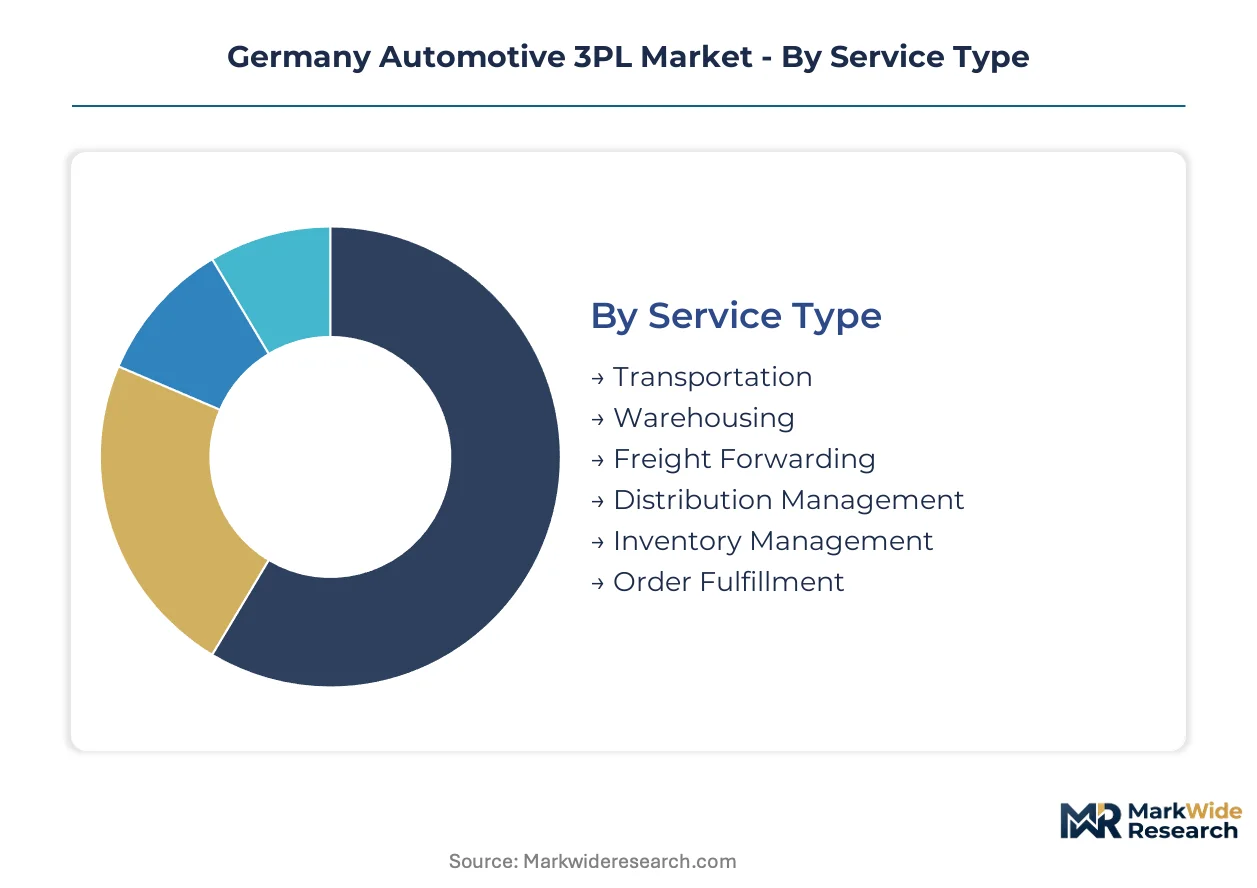
Automotive 3PL segmentation in Germany reflects divergent cost pressures and integration depths across the supplier hierarchy. Tier-1 suppliers demand hazardous materials certification for battery logistics, while vehicle assemblers prioritize sequencing precision over transport mode flexibility.
Service Type:
Cost tier differentiation separates commodity transport from value-added services that embed providers into production planning cycles.
- Transportation:Road-dominant fleet operations coordinate inbound material flows to Stuttgart and Munich assembly corridors under tight tolerance windows. Driver shortages and CO2 pricing compress margins for unhedged operators serving volume brands.
- Warehousing:Automated storage facilities adjacent to BMW Group and Mercedes-Benz Group plants buffer sequenced component kits for just-in-time delivery. Land scarcity near Baden-Württemberg assembly sites drives vertical development of multi-level distribution centers.
- Freight Forwarding:Customs brokerage and cross-border documentation management for Eastern European supplier networks.
- Distribution Management:Yard orchestration and milk-run consolidation across dense supplier geographies.
- Inventory Management:Vendor-managed inventory programs transfer finished goods ownership risk from OEMs to Tier-1 suppliers.
- Order Fulfillment:Aftermarket parts picking and dealer-direct shipment services.
Transportation commands the established base. The steepest expansion runs through inventory management.
Customer Type:
Application complexity escalates from standardized aftermarket flows to engineered solutions for production-integrated supply chains.
- Vehicle Assemblers:Volkswagen Group, BMW Group, and Mercedes-Benz Group contract logistics providers for plant-adjacent sequencing and inbound yard management. Procurement departments consolidate supplier base geography to enable sub-50-kilometer delivery radii.
- Tier-1 Suppliers:Battery module producers and powertrain specialists require thermal-controlled transport and LkSG-compliant subcontractor audits across their sourcing networks. These customers absorb the highest compliance cost premiums.
- Dealerships:Finished vehicle logistics and regional distribution center operations.
- Aftermarket Providers:Spare parts warehousing and emergency shipment services.
Vehicle assemblers anchor revenue concentration. Tier-1 suppliers are climbing the fastest as electrification reshapes material flows.
Transportation Mode:
Volume distribution across modes reflects infrastructure maturity and emission compliance timelines under Germany's national CO2 pricing framework.
- Road Freight:Flexible routing for sequenced component delivery dominates short-haul corridors around Stuttgart and Wolfsburg. Fleet electrification roadmaps accelerate as the Federal Ministry for Economic Affairs and Climate Action enforcement timeline pressures providers to secure battery-electric truck allocations.
- Rail Freight:Combined transport subsidies under the Federal Ministry for Digital and Transport guidelines favor terminal-adjacent 3PL facilities for bulk material movements.
- Inland Waterways:Rhine corridor barge transport for heavy powertrain components.
- Air Cargo:Emergency parts shipment for production line continuity.
- Intermodal:Rail-road integration for long-haul automotive component flows.
Road freight retains the volume base. Intermodal solutions are gaining share fastest as infrastructure subsidies mature.
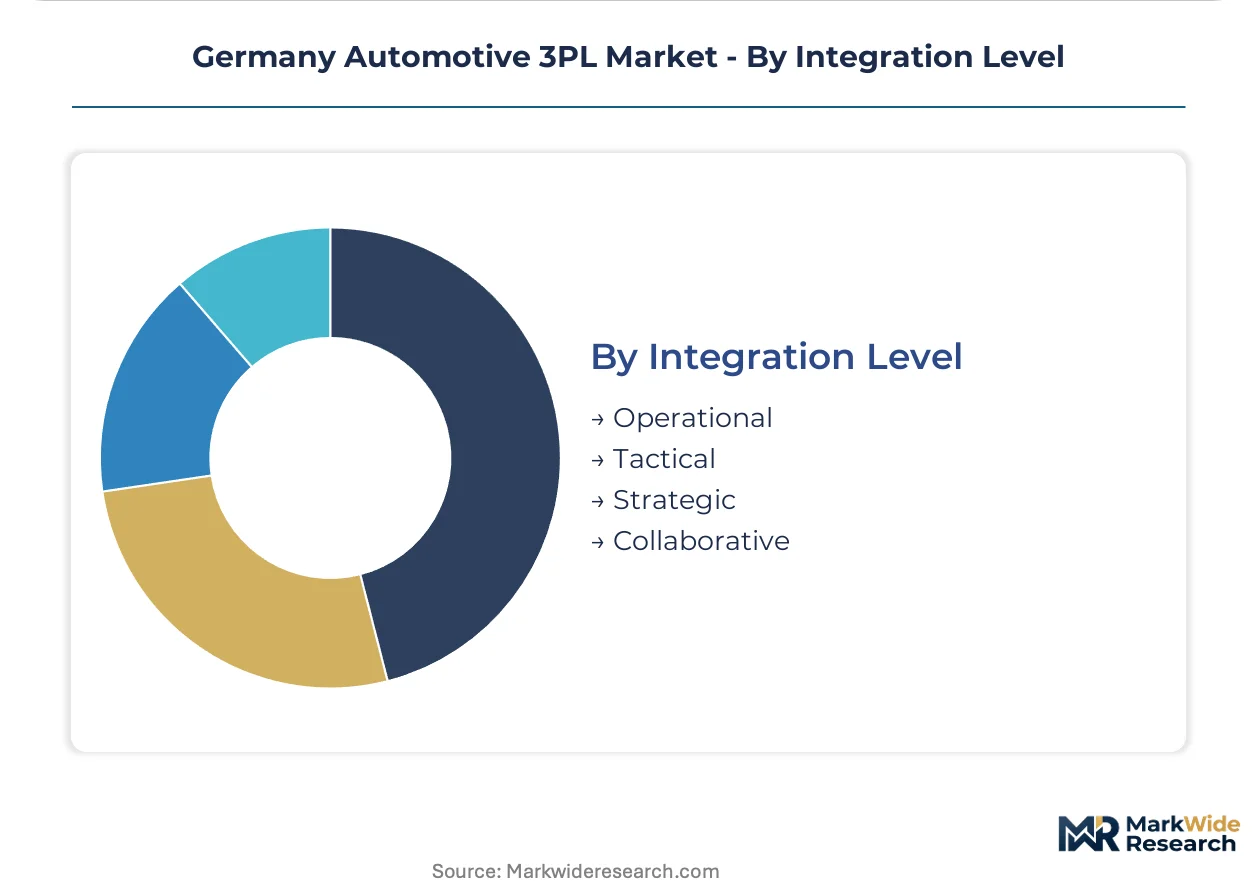
Integration Level:
Margin structure stratifies by how deeply providers embed into customer demand forecasting and product development cycles.
- Operational:Transactional transport execution with limited systems integration.
- Tactical:Route optimization and load consolidation across multiple customer networks.
- Strategic:Fourth-party logistics models that bundle sequencing, milk runs, and just-in-time yard management command premium pricing. DB Schenker and Rhenus Logistics anchor positions through embedded planning teams at OEM headquarters.
- Collaborative:Joint venture structures for captive battery logistics operations.
Strategic integration commands the highest margins. Collaborative arrangements are expanding most quickly around Bavaria's battery gigafactory cluster.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube inland waterway corridor and the A8 autobahn freight spine anchor Germany's automotive logistics infrastructure. Dense terminal networks around Stuttgart, Munich, and Wolfsburg convert raw material flows into sequenced production-line delivery.
Baden-Württemberg
Stuttgart-centered vehicle assembly generates the densest supplier networks in Europe. The Federal Ministry for Digital and Transport's combined transport subsidies favor rail-road terminals at Kornwestheim and Stuttgart-Zuffenhausen. Mercedes-Benz Group and Porsche AG procurement departments consolidate supplier geography within 50-kilometer radii, intensifying demand for plant-adjacent micro-fulfillment centers.
Bavaria
Battery gigafactory construction near Munich and Nuremberg reshapes inbound chemical logistics and outbound module distribution. BMW Group's Leipzig and Munich plants enforce vendor-managed inventory programs that transfer ownership risk to Tier-1 suppliers. The Bavarian state government's industrial cluster funding accelerates automated storage facility development around Ingolstadt and Dingolfing.
Lower Saxony
Volkswagen Group's Wolfsburg headquarters anchors Europe's largest captive logistics demand. The KBA enforces stringent hazardous materials certification for battery-electric vehicle component flows through Braunschweig and Hanover distribution corridors. Rhenus Logistics and DB Schenker maintain dedicated yard management operations at the Wolfsburg plant perimeter.
North Rhine-Westphalia
Ruhr industrial heritage infrastructure supports heavy powertrain component warehousing and cross-docking. Duisburg inland port terminals handle Rhine barge arrivals for transmission and axle assemblies. The state logistics cluster initiative funds battery-electric truck charging corridors along the A3 and A40 autobahn routes serving Ford Cologne and Opel Rüsselsheim plants.
Hesse
Frankfurt Rhine-Main air cargo capacity supports emergency parts shipment for production line continuity. DHL Supply Chain operates sequencing centers at Flörsheim and Obertshausen serving Opel Eisenach and BMW Group networks. The Frankfurt-Hanover rail freight corridor enables overnight component replenishment from northern supplier bases.
Germany Automotive 3PL Market Competitive Landscape
On the supply side, the industry is consolidating around integrated fourth-party logistics platforms that bundle sequencing, milk runs, and yard management. Three archetypes dominate: rail-road intermodal specialists leveraging combined transport subsidies, hazardous materials-certified battery logistics operators, and embedded planning teams co-located at OEM headquarters. Competitive intensity centers on M&A activity to secure terminal-adjacent real estate and strategic partnerships for captive battery supply chain operations.
Within the embedded-planning tier, DB Schenker anchors its position through rail-road intermodal dominance at Volkswagen Group plants. Rhenus Logistics occupies a specialized niche in finished-vehicle logistics and plant-adjacent warehousing across Bavaria and Lower Saxony. Dachser exemplifies network-density competition through its European logistics infrastructure adapted for automotive component flows. These three represent the strategic integration archetype that commands premium pricing through demand forecasting system embedding.
| Leading Market Players |
|---|
| Rhenus Logistics |
| Dachser |
| DB Schenker |
| DSV |
| Geodis |
| DHL Supply Chain |
| Hellmann Worldwide Logistics |
| Honold Logistik |
| Kuehne + Nagel |
| Others |
Supply & Pricing Matrix
Single-source dependency on Eastern European subcontractor networks under LkSG audit obligations compresses margin predictability while widening pricing spreads between compliance-certified Tier-1 specialists and commodity road haulers. This risk vector simultaneously inflates insurance and audit pass-through costs and accelerates consolidation around captive battery logistics operations that internalize liability exposure.
Pricing Analysis
Volume-discount tiering structures separate strategic integration providers embedding planning teams at OEM headquarters from transactional freight brokers competing on per-kilometer rates. Price differentiation hinges on hazardous materials certification grade for lithium-ion battery transport and the depth of vendor-managed inventory system integration. Cost compression in standard road freight segments is intensifying because diesel price volatility and driver wage inflation erode unhedged operator margins. Aftermarket parts distributors exhibit the highest price sensitivity, while battery module producers absorb premium pricing for thermal-controlled transport and LkSG-compliant audit trails.
Supply Chain Analysis
Extended payment terms from Volkswagen Group and BMW Group procurement departments strain working capital for mid-tier sequencing providers, pushing supply-chain finance facility adoption. Geographic supply concentration draws from Poland, Czech Republic, and Hungary for stamped metal components, while battery cell inputs rest on South Korean and Chinese chemical precursor flows. Single-source vulnerability permeates semiconductor chip allocations for vehicle control modules. Distribution runs through plant-adjacent micro-fulfillment centers within 50-kilometer radii of Stuttgart and Munich assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's automotive 3PL market functions as a service-attach opportunity where inventory management and vendor-managed inventory programs expand faster than commodity transportation revenue pools. Recurring-revenue layers from embedded planning teams and sequencing center operations now outpace transactional freight growth.
For Market Incumbents: Pre-empt margin erosion in standard road freight by securing terminal-adjacent real estate at Kornwestheim and Stuttgart-Zuffenhausen rail-road intermodal hubs before combined transport subsidy windows tighten. Deepen upstream control over battery-electric truck allocations through captive leasing structures with OEM fleet decarbonization mandates. Counter the threat from specialized battery logistics entrants by accelerating hazardous materials certification investments ahead of KBA enforcement timelines. For New Entrants and Emerging Players: Establish a beachhead in Bavaria's battery gigafactory cluster near Munich and Nuremberg, where inbound chemical logistics and outbound module distribution demand outpaces qualified provider supply. Target consignment warehousing services for Tier-1 suppliers absorbing vendor-managed inventory risk transfers from BMW Group and Mercedes-Benz Group procurement departments. Lead with digital twin-enabled demand forecasting as a differentiated entry wedge against legacy WMS-dependent incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors hazardous materials-certified operators with embedded OEM planning relationships over pure-play freight brokers. Long-term viability over the next decade hinges on exposure to electrification-driven inventory management expansion rather than diesel-dependent road haulage. Acquisition target archetypes combine battery logistics certification with plant-adjacent warehousing in land-constrained Baden-Württemberg corridors. Watch battery-electric truck infrastructure deployment pace along A8 autobahn corridors as the critical inflection signal for zero-emission fleet transition economics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Logistics Certification Investment | KBA hazardous materials compliance creates defensible moats against unqualified competitors in EV component flows. |
| Rail-Road Intermodal Terminal Expansion | Federal Ministry for Digital and Transport subsidies favor Kornwestheim-adjacent facilities for Stuttgart corridor dominance. |
| Vendor-Managed Inventory Platform Integration | API development for BMW Group and Mercedes-Benz Group scheduling systems embeds providers into demand forecasting cycles. |
| Battery-Electric Truck Fleet Transition | Federal Ministry for Economic Affairs and Climate Action CO2 pricing timelines pressure road-dominant operators toward electrification. |
| Plant-Adjacent Micro-Fulfillment Development | Vertical automated storage facilities within 50-kilometer radii capture land-scarcity premiums near Wolfsburg and Ingolstadt. |
Research Methodology
The analysis maps transportation mode segmentation, service type differentiation, and integration level stratification, each validated through Tier-1 supplier procurement directors, OEM platform logistics engineers, and aftermarket distribution managers. Primary fieldwork combined structured interviews with secondary validation against Federal Ministry for Digital and Transport subsidy disclosures, KBA hazardous materials certification registries, and BAFA LkSG enforcement documentation. Bottom-up triangulation across sequencing center operators and top-down reconciliation against vehicle production databases anchored volume estimates.
Assumption sets held fixed BAFA audit intensity trajectories and EU Green Deal Fit for 55 transport electrification mandates while varying diesel price volatility bands and battery-electric truck infrastructure deployment speeds across the projection horizon. Segmentation dimensions modeled include service type, customer tier, transportation mode, and geographic production cluster density. CAGRs derived from logistic curve adoption patterns for electrification-driven inventory management services and linear extrapolation for mature road freight segments. Industry-specific forecast inputs encompassed OEM decarbonization timelines and combined transport subsidy renewal probabilities.
Stress conditions across LkSG enforcement intensity, mineral oil tax fluctuation amplitude, and high-power charging corridor completion rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory continuity and infrastructure investment pacing. Macroeconomic contraction, accelerated BAFA penalty structures, or breakthrough autonomous trucking deployment would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China less than Truckload Road Freight Transport Market
Logistics and Shipping
Colombia Third-Party Logistics (3PL) Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
United Kingdom Freight and Logistics Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
Digital Freight Brokerage Market
Logistics and Shipping
China less than-Truck-Load (LTL) Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
Sustainable Logistics Market
Logistics and Shipping
United States Cold Chain Logistics Market
Logistics and Shipping
Global Dry Bulk Shipping Market
Logistics and Shipping
Germany Freight Forwarding Market
Logistics and Shipping
Global Connected Logistics Market