

Real-Time Inventory-in-Transit Positioning Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Real-Time Inventory-in-Transit Positioning Platforms Market Insights
Asset-light SaaS subscription models is tilting competitive dynamics toward platforms that minimize upfront infrastructure spend. FourKites leverages cloud-native architecture to reduce customer deployment costs and accelerate time-to-value. project44 anchors its position through deep carrier network density across North American and European lanes. Descartes Systems Group differentiates via proprietary customs and trade compliance data layered onto movement tracking.
Real-time inventory-in-transit positioning platforms combine GPS, cellular, and satellite telemetry with cloud analytics to deliver sub-five-minute location updates and exception alerts for goods moving through multimodal supply chains. These systems ingest sensor streams from refrigerated containers, dry vans, and parcel networks to compute estimated arrival times and flag temperature or security deviations before cargo spoils or diverts. Cloud-Based deployment dominates new implementations because it eliminates server maintenance and scales elastically during peak shipping seasons. IoT Sensor Integration represents the fastest-expanding solution type as lithium battery-powered trackers shrink and cellular LPWAN coverage broadens. GPS Tracking remains the mature revenue base but faces margin compression from commoditized hardware.
The US Department of Transportation's electronic logging device mandates and the EU Green Deal's corporate sustainability reporting requirements are accelerating investment in emissions-linked transit visibility across transatlantic trade lanes. FDA traceability rules for food and pharmaceutical distribution are compelling cold chain operators to adopt platforms that combine positioning with continuous temperature documentation. Stakeholders must weigh whether to consolidate around full-suite providers or assemble best-of-breed tracking, analytics, and compliance modules from specialized vendors.
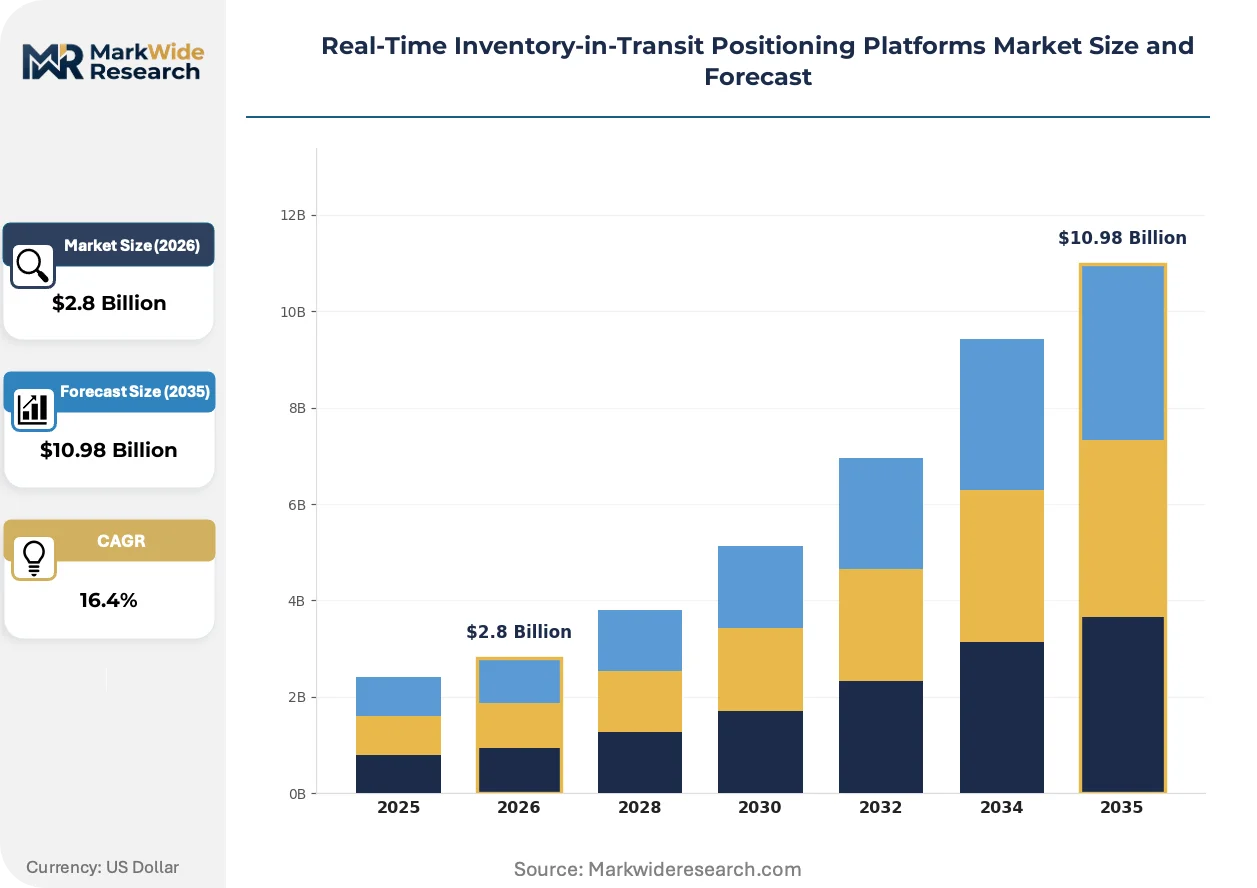
Market Dynamics
Cloud-native telemetry architectures are compressing deployment timelines from quarters to weeks, forcing incumbent hardware-heavy vendors to restructure cost bases or cede mid-market accounts to asset-light SaaS entrants.
Growth Catalysts
- EU Green Deal emissions mandates:Corporate sustainability reporting requirements compel logistics operators to install granular transit visibility tools that calculate Scope 3 emissions from multimodal movements.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution networks require live positioning dashboards fused with continuous thermal monitoring to prevent spoilage.
- German automotive JIT networks:Inbound parts coordination systems demand sub-minute location accuracy, pulling investment into high-frequency GPS refresh protocols.
Market Restraints
- Cellular module cost volatility:Lithium battery and semiconductor shortages for IoT trackers inflate hardware bills-of-materials unpredictably.
- LPWAN coverage gaps:Rural cellular dead zones in North American and Australian interior corridors force satellite backup dependencies that triple connectivity costs.
- FDA validation timelines:21 CFR Part 11 compliance documentation for pharmaceutical traceability extends platform certification cycles by 8-14 months.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO cold chain regulations for vaccine distribution create first-mover advantages for platforms integrating temperature and positioning data.
- AI-driven predictive ETA:Machine learning models consuming historical port congestion and weather patterns are compressing arrival window accuracy from hours to minutes.
- Blockchain-anchored provenance:Immutable ledger layers atop positioning streams address pharmaceutical counterfeiting risks in high-value lanes.
Industry Challenges
- Embedded systems integration:ERP and WMS legacy stacks at mid-tier 3PLs resist API-native telemetry ingestion without middleware investments.
- Data science talent scarcity:Geospatial analytics and sensor fusion expertise concentrates in coastal technology hubs, inflating compensation for supply chain technology teams.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real-Time Inventory-in-Transit Positioning Platforms Market Trends and Innovations
Telemetry hardware miniaturization and LPWAN protocol maturation are collapsing the cost floor for continuous cargo monitoring, enabling tracking economics that previously justified only high-value pharmaceutical or electronics shipments.
Edge-computing-enabled trackers are virtualizing the boundary between device and cloud, embedding anomaly detection algorithms directly on battery-powered units to reduce cellular data transmission costs. Pharmaceutical distributors in Benelux corridors are piloting these units for insulin shipments. The shift is virtualizing traditional platform architectures by pushing intelligence toward the sensor layer and reducing dependency on always-on connectivity.
CSRD disclosure requirements across European member states now mandate emissions attribution per shipment kilometer, compelling visibility platforms to integrate fuel-consumption models and modal carbon-intensity databases. Logistics operators serving French and German retail chains are retrofitting existing GPS deployments with emissions calculation modules rather than replacing hardware. Food and beverage distributors face the steepest compliance curves as they map refrigerated diesel consumption against renewable electricity alternatives.
Shippers are unbundling visibility from freight payment, procuring positioning capabilities through standalone SaaS subscriptions rather than accepting carrier-provided tracking as a bundled service. Automotive manufacturers in Stuttgart and Wolfsburg are mandating direct platform access independent of their logistics service providers. The separation is most advanced in German just-in-time networks where OEMs distrust carrier-consolidated data for production scheduling decisions.
Real-Time Inventory-in-Transit Positioning Platforms Market Segmentation
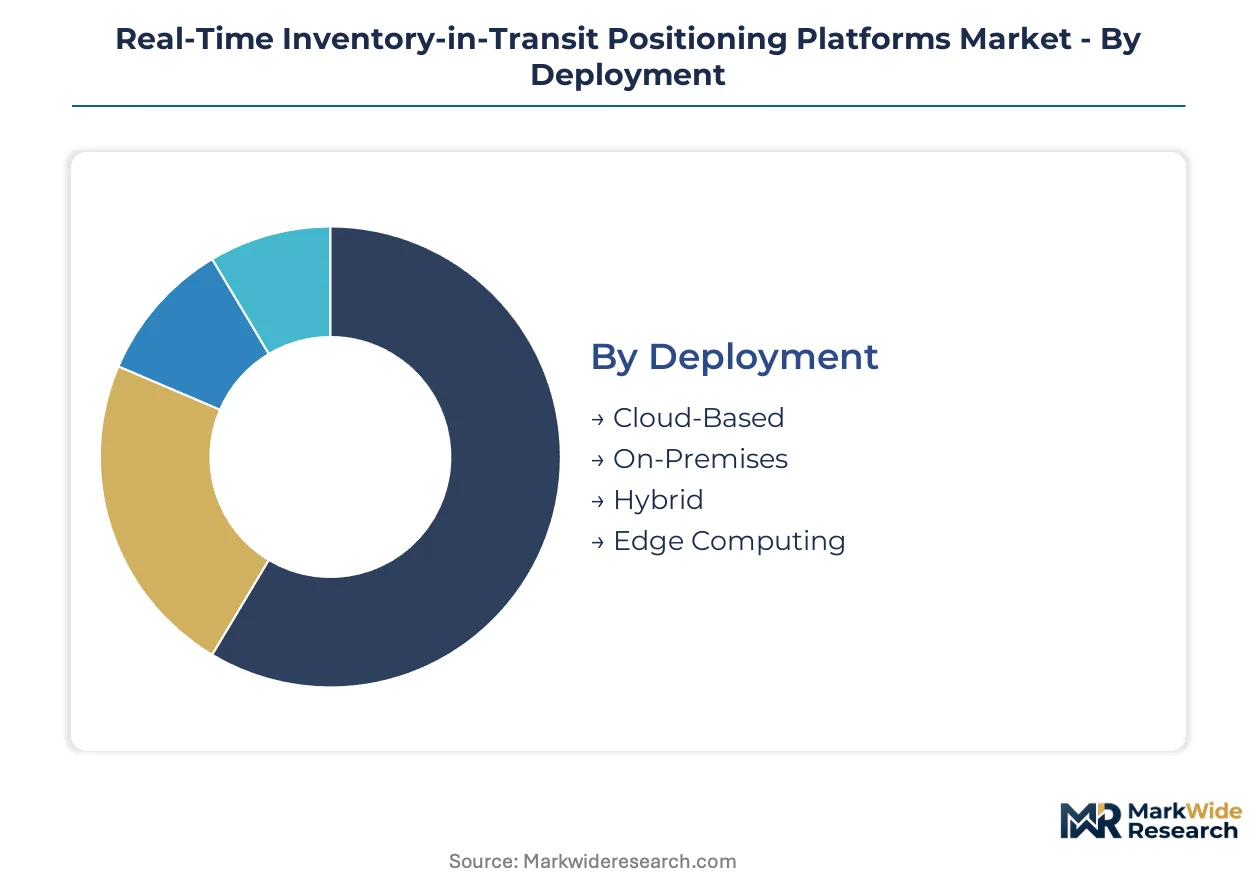
Segmentation in real-time inventory-in-transit positioning platforms reveals divergent technology refresh cycles. Deployment models and solution architectures cycle at different speeds, forcing vendors to balance R&D allocation between stable revenue bases and emerging growth vectors.
Deployment:
Cycle times vary dramatically: cloud-native deployments refresh quarterly through automatic updates, while on-premises installations lock customers into multi-year hardware depreciation schedules.
- Cloud-Based:Multi-tenant SaaS architectures deliver continuous feature deployment without customer-side infrastructure maintenance. Pharmaceutical distributors in Germany and logistics operators across Benelux corridors favor this model for elastic scaling during seasonal vaccine distribution peaks. The EU Green Deal's emissions reporting mandates accelerate migration as cloud platforms integrate carbon calculation modules faster than legacy stacks can retrofit.
- Edge Computing:Battery-powered trackers embed anomaly detection algorithms locally, slashing cellular data transmission costs for cross-border freight. Automotive OEMs in Stuttgart pilot these units for inbound parts coordination where sub-minute location accuracy demands immediate edge-side processing without cloud latency. Hardware miniaturization and LPWAN protocol maturation compress unit economics toward parity with conventional GPS trackers.
- On-Premises:Dedicated server installations persist in defense and classified cargo segments where data sovereignty requirements override cost considerations.
- Hybrid:Mixed architectures bridge sensitive customs data on local servers with telemetry analytics in cloud environments, common among freight forwarders handling dual-use goods.
Cloud-Based deployments anchor the volume base while Edge Computing gains share at the steepest rate.
Solution Type:
Cost tiers separate mature hardware commodities from premium sensor fusion platforms commanding subscription premiums.
- IoT Sensor Integration:Multi-sensor units combine GPS, temperature, humidity, and shock telemetry in lithium battery-powered form factors shrinking below 100 grams. Cold chain operators in India deploy these for CDSCO-compliant vaccine distribution, where integrated temperature-position documentation satisfies regulatory filing requirements. Cellular LPWAN coverage expansion across Indian pharmaceutical export corridors reduces satellite backup dependencies that previously tripled connectivity costs.
- GPS Tracking:Single-mode location hardware dominates installed base economics but faces margin compression from commoditized chipsets and open-source tracking software. Fleet operators in North American long-haul trucking accept carrier-provided GPS as table stakes, limiting pricing power for standalone positioning vendors. Differentiation shifts toward API richness and carrier network density rather than location accuracy alone.
- RFID Tracking:Passive and active radio-frequency systems excel in yard management and container gate automation at port terminals.
- Wireless Network Solutions:Mesh and private LTE deployments serve mining and energy extraction sites beyond cellular coverage.
GPS Tracking retains the largest installed base while IoT Sensor Integration climbs the fastest among new implementations.
Use Case:
Application criticality determines platform configuration complexity and customer willingness to pay for sub-five-minute refresh rates.
- Supply Chain Visibility:Multi-modal orchestration platforms ingest telemetry from ocean containers, rail wagons, and last-mile vans to compute predictive ETAs. Food and beverage distributors face CSRD disclosure requirements mandating emissions attribution per shipment kilometer, pulling investment into visibility layers that integrate fuel-consumption models. Machine learning models consuming historical port congestion data compress arrival window accuracy from hours to minutes.
- Fleet Management:Driver behavior analytics, route optimization, and compliance documentation for hours-of-service regulations dominate this segment. US Department of Transportation electronic logging device mandates created baseline penetration, but differentiation now centers on predictive maintenance integration and fuel efficiency algorithms.
- Asset Tracking:Construction equipment and intermodal chassis monitoring emphasize theft recovery and utilization optimization over transit speed.
- Warehouse Synchronization:Indoor positioning systems bridge yard-to-dock visibility gaps for just-in-sequence manufacturing supply.
Supply Chain Visibility commands the deepest platform investment while Fleet Management shows the steepest expansion trajectory among mid-market accounts.
End User Industry:
Customer type dictates procurement authority structures and platform integration complexity with legacy ERP stacks.
- Logistics Providers:Asset-light 3PLs and fourth-party logistics operators white-label visibility capabilities to shipper clients, requiring multi-tenant architecture and branded dashboard customization. German automotive just-in-time networks drive demand for sub-minute location accuracy as OEMs mandate direct platform access independent of carrier-consolidated data for production scheduling decisions.
- Manufacturing Firms:Discrete and process manufacturers internalize positioning platforms to protect inbound material flows and outbound finished goods. FDA traceability rules for pharmaceutical distribution compel cold chain adoption of platforms combining positioning with continuous temperature documentation.
- Third-Party Warehousing:Contract warehouse operators deploy yard management and dock door coordination systems tied to customer WMS integrations.
- Freight Forwarding:International consolidators prioritize customs and trade compliance data layered onto movement tracking for cross-border documentation.
Logistics Providers anchor platform volume while Manufacturing Firms gain share fastest as OEMs unbundle visibility from freight payment contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import intensity determines platform deployment patterns, with trade-heavy economies investing earliest in multimodal visibility infrastructure. Pharmaceutical cold chain corridors and automotive just-in-time networks concentrate demand in specific manufacturing clusters where sub-minute location accuracy commands premium pricing.
Germany
Automotive OEMs in Stuttgart and Wolfsburg mandate direct platform access independent of carrier data for inbound parts coordination. EU Green Deal CSRD disclosure requirements compel logistics operators to install emissions-calculation modules for Scope 3 reporting. The Baden-Württemberg automotive corridor leads European investment in high-frequency GPS refresh protocols.
United States
FDA traceability rules for pharmaceutical distribution drive cold chain operators toward platforms combining positioning with continuous temperature documentation. Department of Transportation electronic logging device mandates created baseline fleet visibility penetration. Chicago and Memphis logistics hubs concentrate demand for predictive ETA algorithms consuming historical port congestion data.
India
CDSCO cold chain regulations for vaccine distribution create first-mover advantages for platforms integrating temperature and positioning data. Cellular LPWAN coverage expansion across pharmaceutical export corridors reduces satellite backup dependencies. The Maharashtra-Gujarat pharmaceutical belt anchors South Asian demand for multi-sensor IoT trackers.
Netherlands
Benelux pharmaceutical distributors pilot edge-computing-enabled trackers for insulin shipments, embedding anomaly detection algorithms directly on battery-powered units. REACH chemical transport documentation requirements pull investment into customs-data-layered visibility platforms. The Rotterdam-Antwerp port corridor concentrates multimodal orchestration platform deployments.
Japan
METI supply chain resilience initiatives accelerate investment in blockchain-anchored provenance layers atop positioning streams. PMDA pharmaceutical distribution standards mandate granular transit documentation for temperature-sensitive biologics. The Kanto industrial corridor around Tokyo anchors Asia-Pacific demand for predictive maintenance-integrated fleet systems.
Real-Time Inventory-in-Transit Positioning Platforms Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct strategic tiers. Cloud-native SaaS specialists compete against legacy ERP-integrated suites and carrier-owned visibility networks. Strategic archetypes include asset-light telemetry platforms, customs-data-layered logistics software providers, and hardware-anchored fleet telematics vendors. Dominant competitive moves center on carrier network density expansion and middleware investments to bridge legacy ERP stacks.
Within the cloud-native tier, project44 and FourKites exemplify contrasting geographic anchoring strategies, with the former emphasizing North American and European lane density while the latter leverages cloud architecture to compress customer deployment timelines. Descartes Systems Group occupies a differentiated position among customs-data-layered providers, representing the archetype of proprietary trade compliance information fused onto movement tracking. These three companies illustrate how vendor selection increasingly hinges on whether shippers prioritize carrier network breadth, deployment velocity, or regulatory documentation depth.
| Leading Market Players |
|---|
| project44 |
| FourKites |
| Descartes Systems Group |
| Oracle |
| SAP |
| Manhattan Associates |
| Transporeon |
| Shippeo |
| Trimble |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in cloud-native SaaS platforms across North American and European logistics corridors is compressing subscription pricing while forcing hardware-dependent vendors toward asset-light restructuring or mid-market exit.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command subscription premiums through sub-minute GPS refresh protocols and FDA-validated temperature documentation, while standard tiers compete on API richness and carrier network density. Cost compression in economy tiers is intensifying because commoditized GPS chipsets and open-source tracking software erode hardware margins. Third-party logistics operators show the highest price sensitivity, whereas pharmaceutical cold chain operators accept premium pricing for compliance-integrated platforms.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Jabil, and Flex holding capacity for cellular IoT module production. Component supply draws from Taiwan for semiconductor fabrication, China for lithium battery cells, and Vietnam for final tracker assembly. Single-source vulnerability in GPS chipset supply from a dominant US-based vendor creates concentration risk. Distribution runs through carrier-direct channels for fleet telematics and SaaS marketplaces for cloud-native visibility platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as OEM unbundling of visibility from freight payment contracts creates specialized niches for best-of-breed sensor fusion and compliance documentation modules.
For Market Incumbents: Harden carrier network density in transatlantic lanes to defend against asset-light SaaS entrants compressing deployment timelines. Invest in middleware layers bridging legacy ERP stacks at mid-tier 3PLs resisting API-native telemetry ingestion. Prioritize FDA 21 CFR Part 11 certification investment to extend platform lock-in within pharmaceutical cold chain accounts facing extended validation timelines.
For New Entrants and Emerging Players: Mid-market food and beverage distributors in Benelux corridors represent the most penetrable entry point given CSRD disclosure mandates forcing rapid emissions-calculation module adoption without existing platform loyalty. Indian pharmaceutical export corridors offer secondary white-space as CDSCO cold chain regulations create first-mover demand for temperature-position integrated documentation. Lead with edge-computing-enabled hardware miniaturization as the go-to-market angle to differentiate against cloud-latency-dependent incumbents.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native SaaS specialists with multi-tenant architectures serving logistics provider white-label demand. Long-term viability over the projection horizon favors platforms combining positioning telemetry with proprietary customs and trade compliance data layers. Watch cellular LPWAN coverage expansion rates across Indian and Southeast Asian pharmaceutical corridors as the inflection signal for geographic growth acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Middleware investments bridge legacy ERP stacks at mid-tier 3PLs resisting API-native ingestion. |
| Acquisition of Specialist Firm | Edge-computing tracker developers accelerate hardware miniaturization and anomaly-detection virtualization. |
| Geographic Expansion | Indian pharmaceutical export corridors offer first-mover positioning as CDSCO regulations mandate cold chain visibility. |
| Strategic Partnership | Carrier network density agreements with European automotive OEMs secure sub-minute accuracy mandates. |
| Product Launch | Emissions-calculation modules address EU Green Deal CSRD disclosure requirements across Benelux logistics operators. |
Research Methodology
Desk research of customs and trade databases, SEC filings from logistics technology vendors, and EU regulatory disclosure records preceded structured interviews with supply chain technology CTOs, pharmaceutical distribution operations directors, automotive OEM inbound logistics managers, and cloud platform integration specialists. Primary fieldwork with these stakeholders combined with secondary validation against carrier network density reports and cold chain compliance documentation standards. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates across deployment models and solution architectures.
Assumptions held fixed include sustained EU Green Deal enforcement timelines and FDA traceability rule implementation pace, while variables included cellular LPWAN coverage expansion rates and lithium battery cost trajectories. The analytical framework modeled deployment model, solution type, use case criticality, and end-user industry procurement authority across the projection horizon. CAGRs derived from segment-level adoption curves weighted by pharmaceutical cold chain investment intensity and automotive JIT network coordination demands. Forecast inputs incorporated edge-computing hardware miniaturization timelines and emissions-calculation module integration velocity.
Macroeconomic conditions sit as an overlay; deviation in transatlantic trade lane volumes or semiconductor supply normalization would shift the trajectory. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory enforcement pace and carrier consolidation patterns. Quarterly review of cellular infrastructure deployment data and cold chain regulatory filing volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.