
 US Domestic Courier, Express, and Parcel (CEP) Market | 2026-2036
US Domestic Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
US Domestic Courier, Express, and Parcel (CEP) Market Insights
Multi-source fleet procurement is decoupling from the traditional single-carrier model that long defined enterprise shipping contracts. United Parcel Service sustains dominance through its integrated ground-air network and dense pickup-and-delivery infrastructure. FedEx competes through time-definite express services and specialized healthcare logistics capabilities. Amazon Logistics anchors its position through captive volume from its retail marketplace and proprietary sorting technology.
The US Domestic Courier, Express, and Parcel sector encompasses time-sensitive and non-time-sensitive shipment of documents and packages under standardized pricing, tracking, and liability frameworks, with operational parameters defined by weight thresholds, dimensional pricing algorithms, and service-level agreements measured in delivery windows. Same-day delivery commands premium rate structures and attracts disproportionate technology investment, while standard delivery occupies the mature volume base with thinner margins. E-commerce customers generate the dominant demand flow, though corporate accounts retain superior yield per piece through contracted rate cards and predictable shipping patterns.
The Federal Motor Carrier Safety Administration governs commercial driver qualifications and hours-of-service limits, while the Department of Transportation oversees hazardous materials transport certification and pipeline safety crossover rules for air cargo screening. The Postal Regulatory Commission shapes competitive dynamics through universal service obligations and pricing oversight for market-dominant products. Stakeholders must monitor how autonomous vehicle waivers and drone delivery rulemakings at the Federal Aviation Administration reshape network economics and labor requirements.
Market Dynamics
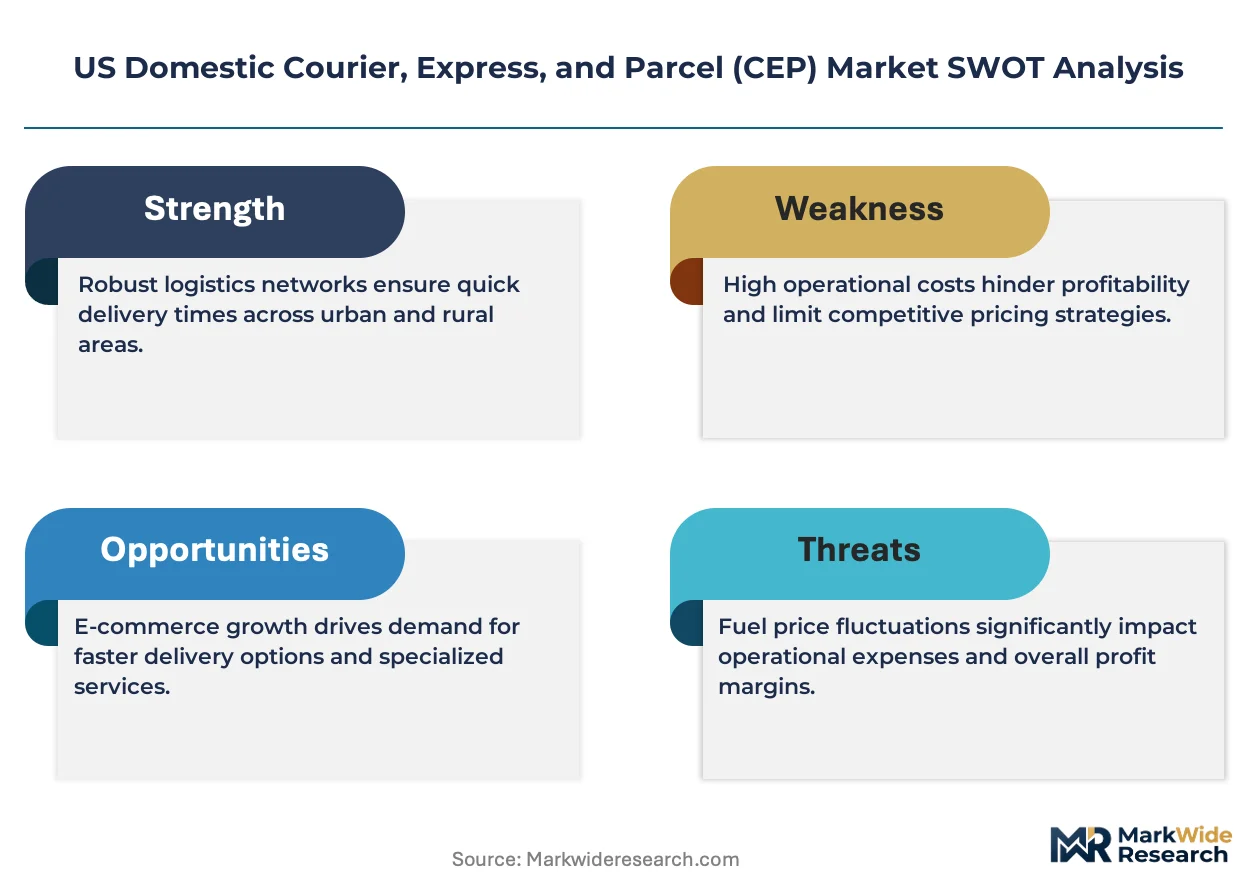
E-commerce fulfillment density is compressing delivery networks into hyperlocal micro-fulfillment zones, forcing carriers to reconfigure hub-and-spoke architectures around urban inventory positioning rather than traditional sortation economics.
Growth Catalysts
- FMCSA Hours-of-Service Flexibility:The Federal Motor Carrier Safety Administration's modified rest-break provisions for short-haul operations expand driver utilization windows during peak delivery windows.
- Healthcare Cold Chain Expansion:Temperature-controlled pharmaceutical distribution requires specialized express infrastructure that commands premium yield per shipment.
- Texas Triangle Density:The Dallas-Houston-Austin corridor concentrates population growth and warehouse development, creating scale economies for last-mile deployment.
Market Restraints
- Diesel Price Volatility:Fuel represents 25-30% of ground operating costs, with price spikes immediately compressing margins on contracted rate cards.
- Driver Supply Concentration:Commercial driver licensing bottlenecks and demographic retirements restrict fleet expansion regardless of equipment availability.
- Last-Mile Labor Cost Escalation:Urban delivery wages outpace inflation in dense metropolitan zones where route efficiency peaks.
Strategic Opportunities
- FAA Drone Integration:The Federal Aviation Administration's Beyond Visual Line of Sight rulemaking opens rural and suburban zones for autonomous aerial delivery at sub-ground costs.
- Reverse Logistics Monetization:E-commerce return volumes create incremental revenue streams through consolidated pickup networks and refurbishment partnerships.
- Same-Day Service Tiering:Premium delivery windows for perishables and urgent documents capture yield spreads unavailable in standard service tiers.
Industry Challenges
- Autonomous Vehicle Integration:Deploying self-driving ground units requires retraining dispatch and maintenance workforces while managing mixed-fleet safety protocols.
- Dimensional Pricing Complexity:Algorithmic rate calculations based on package density demand upgraded measurement equipment and customer education to prevent billing disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Domestic Courier, Express, and Parcel (CEP) Market |
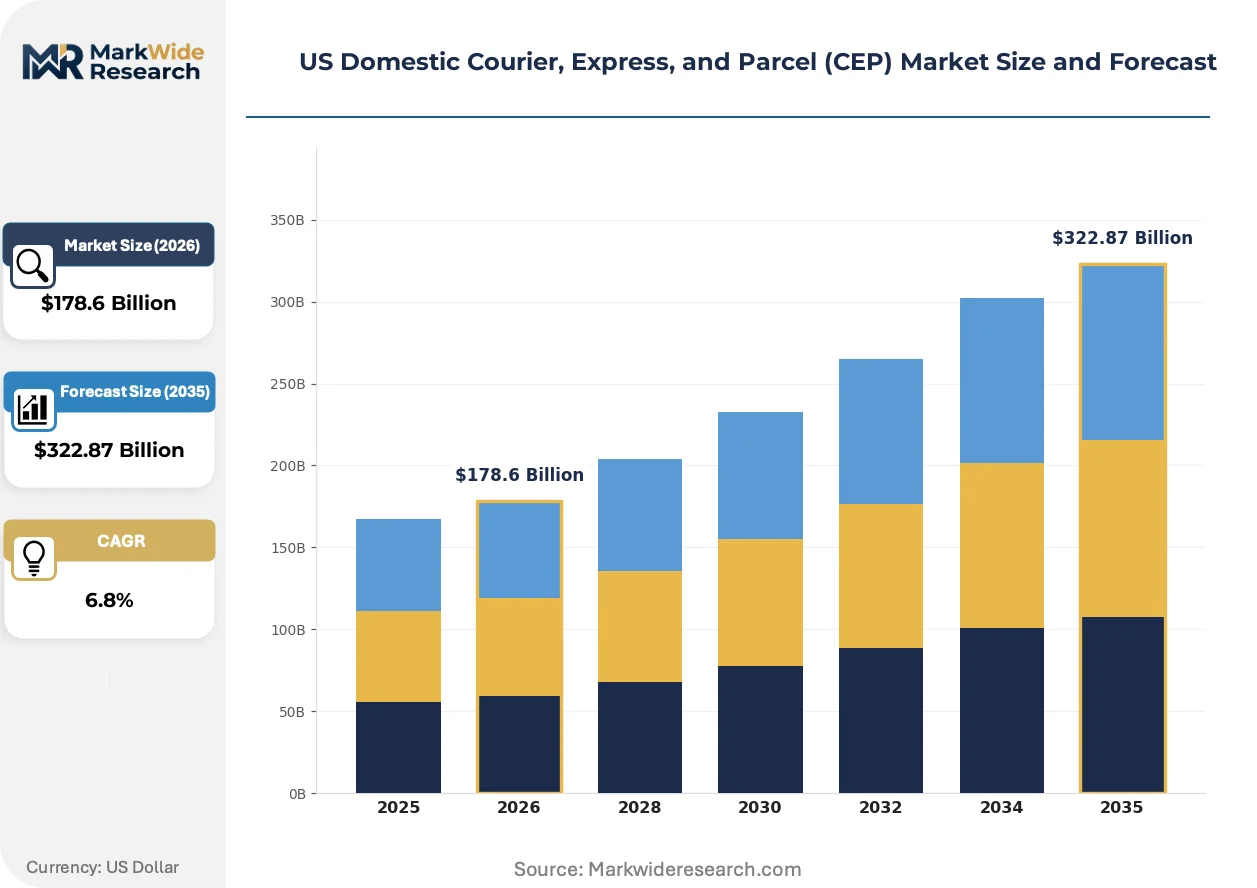
| Market Size in 2026 | $178.6 Billion |
| Market Size in 2035 | $322.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Same-Day Delivery, Standard Delivery, Next-Day Delivery Package Size: Small, Medium, Large, Extra Large Customer Type: E-Commerce, Retail, Corporate, Individual Delivery Mode: Air, Road, Rail, Intermodal |
| Companies Covered | United Parcel Service, FedEx, United States Postal Service, OnTrac, Amazon Logistics, DHL Group, LaserShip, Spee-Dee Delivery Service, LSO, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Domestic Courier, Express, and Parcel (CEP) Market Trends and Innovations
Automation is penetrating sortation and final-mile operations simultaneously, compressing labor dependency while raising capital intensity. Network design is pivoting from centralized hub dominance toward distributed micro-fulfillment positioning.
Robotic sortation systems are absorbing manual parcel handling tasks in high-throughput facilities. E-commerce fulfillment centers deploy these systems at accelerating pace to manage peak volume surges without proportional labor scaling. The technology is absorbing wage pressure while enabling 24-hour processing windows that compress delivery commitments.
The Federal Aviation Administration's drone delivery rulemaking is reshaping aerial logistics economics. Commercial operators now pursue type certification for autonomous aircraft carrying payloads under 55 pounds across suburban and rural zones. Healthcare and time-critical document segments are responding with pilot programs targeting 30-minute delivery windows unreachable by ground transport.
Buyer procurement patterns are fragmenting across multi-carrier platforms rather than consolidating under single-source contracts. Enterprise shippers now allocate volume dynamically based on real-time rate and service-level data, displacing annual rate negotiations. This behavior is most visible among retail and consumer electronics verticals with high shipment frequency and low per-package value density.
US Domestic Courier, Express, and Parcel (CEP) Market Segmentation
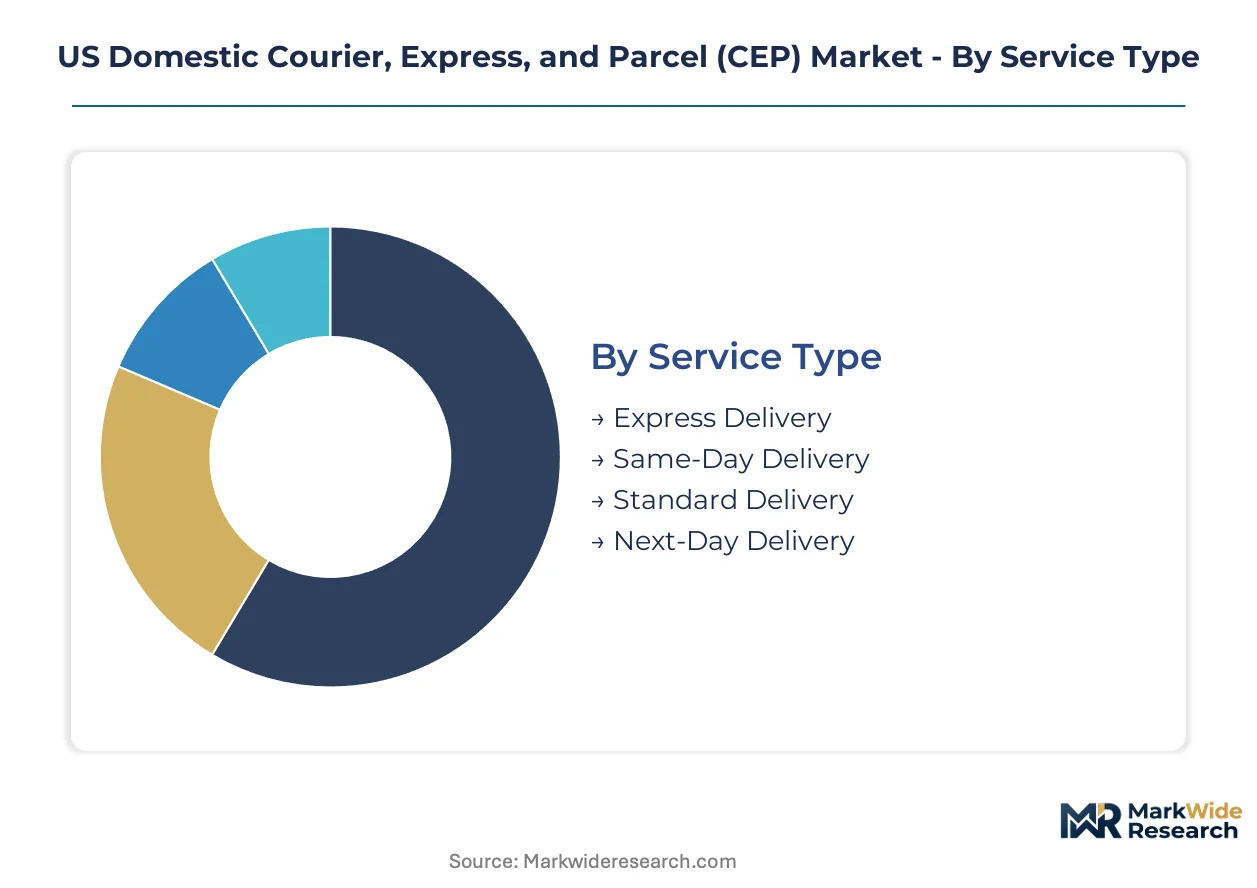
CEP segmentation reveals how carriers allocate capital across service tiers with divergent margin profiles. Package characteristics and customer concentration patterns determine network design choices, from hub automation levels to last-mile density investments.
Service Type:
Standalone express services operate as premium offerings with dedicated aircraft and sorting infrastructure, while embedded delivery tiers integrate into broader logistics contracts with thinner margins but stickier relationships.
- Express Delivery:Time-definite shipments utilizing integrated ground-air networks with guaranteed delivery windows and proactive exception management. Healthcare and financial services concentrate demand here, with FDA-regulated pharmaceutical shipments requiring temperature-validated chain-of-custody documentation.
- Same-Day Delivery:Hyperlocal fulfillment requiring urban micro-hub positioning and dynamic route optimization. Perishable grocery and urgent document segments drive adoption in the Texas Triangle, where Dallas-Houston-Austin density supports sub-three-hour commitments.
- Standard Delivery:Non-time-sensitive ground transport with flexible delivery windows and consolidated sortation.
- Next-Day Delivery:Overnight ground-air hybrid service balancing speed against express premiums.
Standard delivery leads volumes today; same-day delivery is gaining share fastest.
Package Size:
Cost tier segmentation separates automated sortation candidates from manual handling requirements, with dimensional pricing algorithms compressing margin differentials across weight thresholds.
- Small:Envelopes and padded mailers under one pound flowing through automated letter sorting systems. E-commerce apparel and electronics accessories dominate this tier, with USPS maintaining cost advantages in residential last-mile delivery.
- Medium:Standard corrugated boxes between one and thirty pounds fitting automated parcel sorters. Retail replenishment and consumer electronics drive volume concentration, with FedEx and UPS competing through dimensional weight pricing precision.
- Large:Bulky items requiring manual handling and specialized lift equipment.
- Extra Large:Freight-parcel hybrid shipments demanding dedicated truckload capacity and residential delivery appointment scheduling.
Medium packages anchor revenue today; small parcels are expanding most quickly.
Customer Type:
Application-based segmentation distinguishes predictable B2B patterns from volatile B2C demand, with contracted rate cards versus spot pricing creating divergent yield management challenges.
- E-Commerce:High-frequency, low-margin shipments from marketplace sellers and direct-to-consumer brands. Amazon Logistics and Shopify merchants concentrate volume here, with return logistics adding complexity to network economics.
- Corporate:Contracted accounts with negotiated service agreements and dedicated customer service tiers. Financial services and healthcare organizations generate superior yield per piece through predictable shipping patterns and compliance requirements.
- Retail:Store replenishment and buy-online-pickup-in-store fulfillment.
- Individual:Occasional shipper segment using retail access points and digital platforms.
E-commerce dominates shipment counts today; corporate accounts retain superior yield stability.
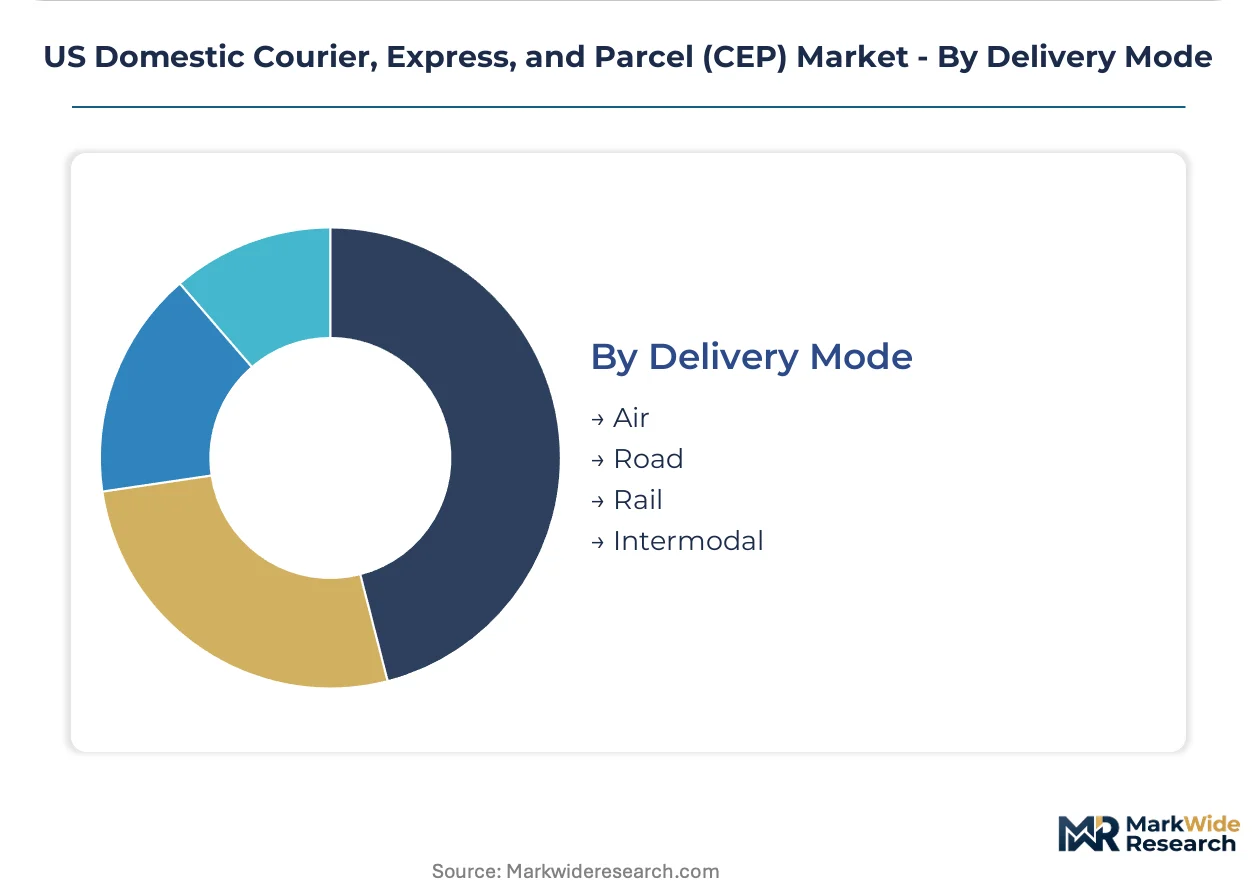
Delivery Mode:
Geography-driven mode selection reflects infrastructure availability and distance-band economics, with intermodal combinations emerging in specific corridor configurations.
- Air:Integrated freighter networks and belly cargo capacity connecting major sortation hubs. Express carriers deploy this mode for coast-to-coast next-day commitments, with FAA-regulated screening protocols adding operational complexity.
- Road:Ground line-haul and last-mile delivery forming the volume foundation. FMCSA hours-of-service rules constrain driver utilization, while diesel price volatility immediately impacts operating margins.
- Rail:Intermodal container movement for non-time-sensitive parcel flows.
- Intermodal:Optimized combinations of air, road, and rail segments.
Road transport handles majority volume today; intermodal solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics favor states with flexible labor classifications and lower commercial vehicle registration costs, accelerating warehouse migration toward jurisdictions with streamlined FMCSA compliance frameworks.
Texas Triangle
E-commerce fulfillment demand and cross-border manufacturing flows concentrate parcel volumes across Dallas-Fort Worth, Houston, and Austin. The Texas Department of Transportation prioritizes freight corridor upgrades along Interstate 35 and Interstate 45. Dallas anchors the densest last-mile deployment zone, with Amazon Logistics and regional carriers operating dedicated micro-fulfillment centers.
California
Tech-sector document flows and perishable grocery delivery sustain premium express demand across Los Angeles and San Francisco Bay Area corridors. The California Air Resources Board enforces stringent heavy-duty truck emissions standards through its Advanced Clean Trucks regulation. Southern California's Inland Empire warehouse cluster processes trans-Pacific import volumes for last-mile distribution throughout the Southwest.
Northeast Corridor
Financial services document security requirements and pharmaceutical cold-chain shipments generate specialized express demand from Boston through Washington DC. The Federal Motor Carrier Safety Administration coordinates with state DOTs on hours-of-service enforcement across interstate boundary zones. New York Metro's dense urban delivery environment commands the highest last-mile labor costs and attracts autonomous vehicle pilot programs.
Midwest Manufacturing Belt
Automotive parts replenishment and industrial B2B shipments sustain predictable ground transport demand across Illinois, Michigan, and Ohio. The Department of Transportation oversees hazardous materials routing for chemical and battery shipments through Chicago's intermodal hub. Detroit's resurgent logistics infrastructure supports just-in-time manufacturing supply chains with compressed delivery windows.
Southeast Growth Corridor
Population migration and port expansion at Savannah and Charleston redirect parcel flows toward Atlanta and Florida distribution networks. Georgia's Department of Transportation accelerates commercial vehicle lane expansions on Interstate 75 and Interstate 95. Miami anchors international express gateway operations, with DHL Group and FedEx maintaining dedicated customs-clearance facilities for Latin American trade lanes.
US Domestic Courier, Express, and Parcel (CEP) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue same-day and hyperlocal delivery specialization with asset-light gig-economy models. The market consolidates around three operational archetypes: integrated ground-air networks, captive retail logistics arms, and regional ground specialists. Dominant competitive moves include hub automation investments and last-mile density acquisitions. Strategic partnerships between carriers and e-commerce platforms reshape volume allocation away from traditional annual contracts.
Within the integrated carrier tier, United Parcel Service and FedEx anchor national ground-air networks with differentiated healthcare and time-definite capabilities. Amazon Logistics exemplifies the captive retail model, converting marketplace volume density into proprietary sorting infrastructure and delivery workforce. Regional specialists including LaserShip and OnTrac occupy positions between national scale and urban density, targeting specific corridor configurations with lower cost structures than integrated competitors.
| Leading Market Players |
|---|
| United Parcel Service |
| FedEx |
| United States Postal Service |
| OnTrac |
| Amazon Logistics |
| DHL Group |
| LaserShip |
| Spee-Dee Delivery Service |
| LSO |
| Others |
Pricing and Supply Chain Analysis
Diesel fuel costs cascade through ground line-haul operations into express rate premiums, with FMCSA hours-of-service constraints amplifying labor cost pass-through to time-definite service tiers. E-commerce shippers absorb standard delivery compression while healthcare and financial services segments retain pricing power through compliance-validated contracts.
Pricing Analysis
Input-cost pass-through from fuel and labor expenses flows disproportionately into same-day and express tiers where capacity constraints limit substitution options. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed delivery windows from flexible ground options, with dimensional weight algorithms compressing margin differentials across package density categories. Price differentiation hinges on service reliability documentation and temperature-validation certification for pharmaceutical flows. Pricing pressure stems from Amazon Logistics' captive volume absorption and gig-economy last-mile entrants undercutting urban delivery rates. Corporate accounts with contracted rate cards exhibit lowest price sensitivity; individual occasional shippers and marketplace sellers face highest spot-rate volatility.
Supply Chain Analysis
Dual-sourcing requirements from enterprise shippers mandate qualification across UPS, FedEx, and at least one regional carrier to mitigate single-network disruption exposure. Geographic supply concentration for sorting equipment and autonomous vehicle hardware draws from China, Germany, and domestic US manufacturing corridors. Raw material dependencies span aluminum airframe components, lithium battery cells for electric delivery fleets, and semiconductor chips for route optimization systems. Supply chain risk centers on FAA drone certification delays constraining autonomous aerial deployment timelines. Distribution runs through hub-and-spoke sortation nodes with increasing micro-fulfillment positioning in Dallas, Houston, and Austin urban cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as healthcare cold-chain specifications and FDA-validated pharmaceutical distribution displace commodity parcel economics toward premium yield stability.
For Market Incumbents: To counter Amazon Logistics' captive volume absorption and gig-economy last-mile compression, deepen backward integration into healthcare cold-chain infrastructure and secure dedicated sorting capacity in the Texas Triangle. Prioritize FMCSA compliance automation to expand driver utilization windows against labor supply constraints. Channel control through direct enterprise sales relationships defends contracted rate card stability. For New Entrants and Emerging Players: Capture rural and suburban drone delivery corridors where FAA Beyond Visual Line of Sight rulemaking enables cost structures below ground transport economics. Target pharmaceutical reverse logistics and perishable grocery segments with asset-light temperature-controlled partnerships. A go-to-market angle anchored in 30-minute delivery commitments for time-critical documents bypasses incumbent hub-and-spoke density advantages. For Investors and Strategic Acquirers: Consolidation pressure builds where regional carriers lack capital intensity for automation upgrades and healthcare certification investments. Long-term viability favors integrated ground-air networks with captive pharmaceutical volume or proprietary sorting technology. Acquisition target archetypes include regional specialists with Texas Triangle density and healthcare logistics certifications. Watch FAA drone integration timelines as inflection indicator for autonomous delivery economics.| Strategic Initiative | Industry Significance |
|---|---|
| Hub Automation Investment | Robotic sortation systems absorb wage pressure while enabling 24-hour processing windows at Dallas-Fort Worth facilities. |
| Healthcare Cold-Chain Certification | FDA-validated temperature control infrastructure commands premium yield per shipment from pharmaceutical distributors. |
| Micro-Fulfillment Positioning | Urban inventory placement compresses last-mile delivery commitments in Houston-Austin corridor density zones. |
| Multi-Carrier Platform Integration | Dynamic volume allocation based on real-time rate data displaces traditional annual contract negotiations. |
| Autonomous Vehicle Pilot Programs | Self-driving ground units in New York Metro test mixed-fleet safety protocols and dispatch retraining requirements. |
Research Methodology
Coverage spans the Texas Triangle, California, Northeast Corridor, Midwest Manufacturing Belt, and Southeast Growth Corridor, with primary inputs from each region combined with secondary validation. Primary interviews engaged fleet operations directors, pharmaceutical logistics managers, e-commerce supply chain executives, and FMCSA compliance officers. Secondary sources included Department of Transportation hazardous materials routing data, FAA drone integration rulemaking dockets, Postal Regulatory Commission pricing oversight reports, and SEC carrier filings. Bottom-up volume modeling triangulated against top-down macroeconomic demand indicators.
Rate-of-change decomposition separated volume growth drivers from yield compression factors across the projection horizon. Segmentation dimensions modeled include service type tiers, package size categories, customer application patterns, and delivery mode combinations. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Forecast inputs incorporated FMCSA hours-of-service rule modifications, FAA Beyond Visual Line of Sight certification timelines, and diesel price volatility scenarios.
Underlying measurement precision varies by segment; express delivery and healthcare cold-chain categories carry tighter precision than standard ground tiers due to concentrated carrier reporting. Forecasts reflect documented assumptions regarding e-commerce penetration rates and autonomous vehicle regulatory pathways. Deviation in FAA drone integration timelines or FMCSA driver supply regulations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Chile Third-Party Logistics (3PL) Market
Logistics and Shipping
Global Load Planning Services and Solutions Market
Logistics and Shipping
Italy Courier Market
Logistics and Shipping
United States Apparel Logistics Market
Logistics and Shipping
Illinois Freight and Logistics Market
Logistics and Shipping
Czech Republic Third-Party Logistics Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Timber Logistics Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Contract Logistics Market
Logistics and Shipping
Sri Lanka Freight and Logistics Market
Logistics and Shipping
Colombia Freight and Logistics Market