
 Acoustic Vehicle Alerting System Market | 2026-2036
Acoustic Vehicle Alerting System Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Vehicle Alerting System Market Analysis
Modular hardware-software bundles is decoupling from traditional integrated speaker units, letting buyers source sound generation modules and control electronics separately. Harman International leverages its audio engineering heritage to anchor premium configurable systems for luxury EV platforms. Continental AG competes through manufacturing scale across European and Asian assembly plants. Denso Corporation specializes in compact electromagnetic drivers suited to tight engine-bay packaging in hybrid architectures.
An acoustic vehicle alerting system generates synthesized external sound via loudspeakers or transducers mounted on electric and hybrid vehicles, typically producing 56-75 dB of pedestrian-warning output in the 160 Hz to 6.3 kHz band to compensate for absent engine noise. The technology serves the primary commercial purpose of reducing pedestrian collision risk while enabling manufacturers to brand vehicle sound signatures. Electric powertrain applications lead volume adoption given zero native engine noise, while AI-driven systems represent the fastest-expanding technology segment as algorithms enable dynamic sound profiles responding to vehicle speed and environment. OEM end users capture the dominant margin pool through factory-installed programs, though aftermarket providers are gaining share in retrofit markets for early-generation EVs lacking compliant equipment.
The US NHTSA Federal Motor Vehicle Safety Standard 141 mandates minimum sound requirements for hybrid and electric vehicles, directly compelling OEM installation rates and shaping product specifications for frequency range and loudness. EU REACH compliance and CE marking requirements govern material composition and electromagnetic compatibility of alerting hardware sold across member states. China's MIIT and GB standards for new energy vehicles add a third regulatory layer affecting export-oriented suppliers. Stakeholders must monitor divergence between regional sound-level thresholds and test protocols when planning platform standardization strategies.
Market Dynamics
Regulatory mandates from the US NHTSA and EU vehicle safety frameworks are forcing passenger vehicle OEMs to install external sound generators, decoupling procurement from traditional integrated speaker units toward modular hardware-software bundles.
Growth Catalysts
- Federal Motor Vehicle Safety Standard 141:The US NHTSA mandate requires minimum sound levels for hybrid and electric vehicles, compelling factory installation rates and standardizing frequency range specifications across OEM platforms.
- EU REACH compliance and CE marking:Material composition and electromagnetic compatibility requirements for alerting hardware sold across member states are concentrating supplier qualification efforts in Germany and France.
- Electric powertrain proliferation:Zero native engine noise in battery-electric architectures creates inherent demand for synthesized pedestrian-warning systems in California, Bavaria, and Guangdong province.
Market Restraints
- Neodymium magnet cost volatility:Rare-earth price swings in electromagnetic driver production compress margin predictability for compact transducer manufacturers serving hybrid engine-bay packaging constraints.
- Regional test protocol divergence:Differing sound-level thresholds between US NHTSA, EU frameworks, and China's MIIT GB standards fragment platform standardization strategies and inflate validation costs.
- Legacy internal combustion acoustic heritage:Established audio engineering workflows optimized for cabin entertainment resist reconfiguration toward external pedestrian-alerting frequency bands and directional radiation patterns.
Strategic Opportunities
- Retrofit aftermarket for early-generation EVs:First-wave electric models lacking compliant equipment present installation demand through independent service channels in Germany and Japan.
- AI-driven dynamic sound profiles:Algorithm-enabled systems responding to vehicle speed and environment represent technology convergence between automotive audio and environmental sensing.
- China MIIT new energy vehicle standards:Export-oriented suppliers can align production lines to third regulatory layer requirements, accessing domestic NEV procurement programs.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized expertise spanning psychoacoustics, automotive packaging, and regulatory compliance remains concentrated in Stuttgart, Tokyo, and Detroit metro clusters.
- Multi-jurisdiction certification timelines:Parallel NHTSA, KBA, and MIIT homologation processes extend product launch windows and strain program management bandwidth.
- Integration complexity with vehicle network architectures:Real-time speed and direction data requirements demand CAN bus and Ethernet compatibility that legacy audio subsystem suppliers must acquire.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Vehicle Alerting System Market |
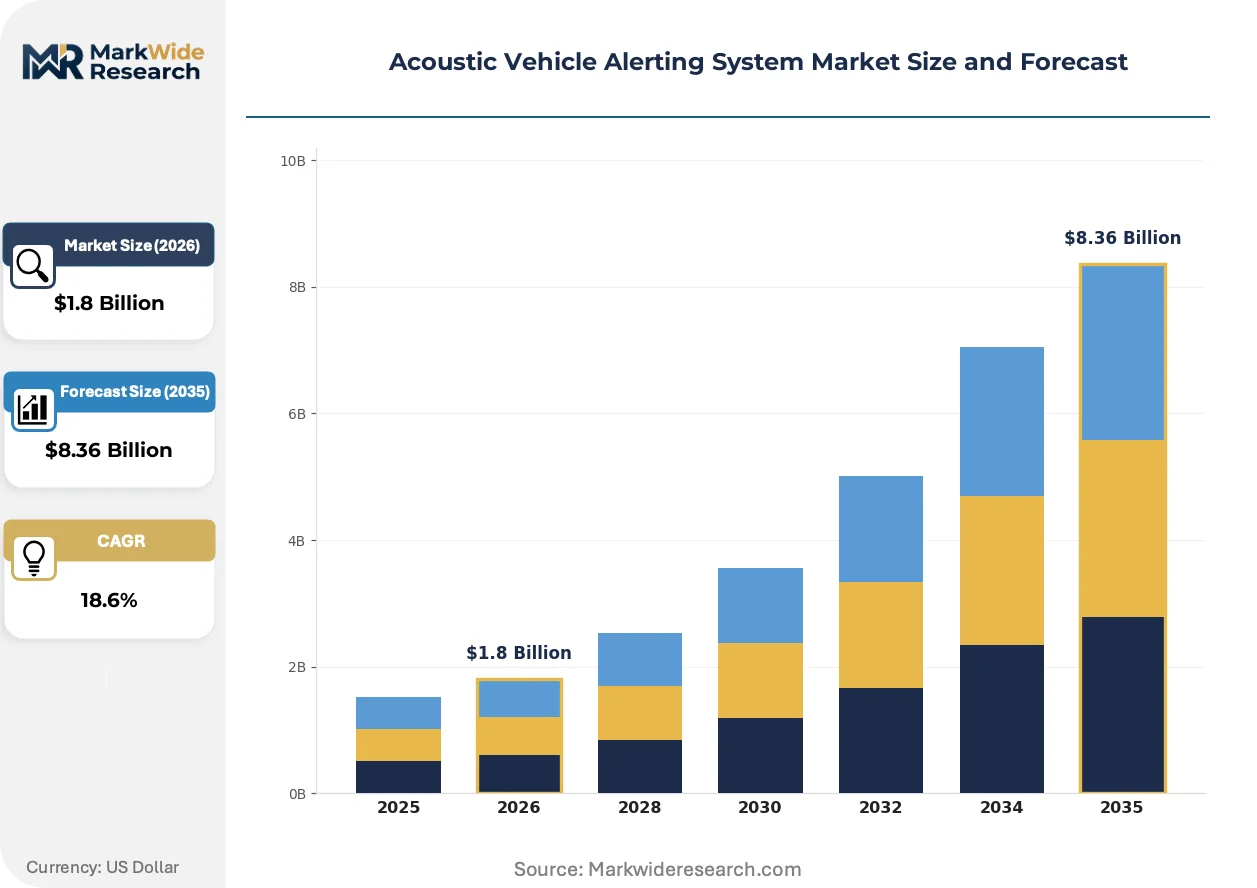
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Hybrid, Fuel Cell, Conventional Technology: Sound Generation, AI-Driven Systems, Sensors, Electromagnetic Technology Application: Passenger Vehicles, Commercial Vehicles, E-Scooters, Bicycles End User: OEMs, Aftermarket Providers, Transport Agencies, Fleet Managers |
| Companies Covered | Harman International, Robert Bosch GmbH, Continental AG, Thor, Texas Instruments Incorporated, Hella GmbH & Co. KGaA, Denso Corporation, Valeo S.A., Kendrion N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Vehicle Alerting System Market Emerging Trajectories
Algorithmic sound generation is displacing fixed-waveform systems across electric vehicle platforms, enabling dynamic pedestrian-alerting profiles that adapt to urban density and vehicle kinematics in real time.
Directional parametric array transducers are expanding into premium EV platforms by projecting highly localized acoustic beams that minimize noise pollution while maintaining pedestrian detectability. Luxury OEMs in Germany and California are adopting these systems to differentiate brand sound signatures without triggering regulatory non-compliance. The technology is expanding into adjacent applications including automated delivery robots and micro-mobility devices.
EU vehicle safety frameworks are tightening electromagnetic compatibility requirements for external sound generators, forcing control electronics redesigns that isolate high-voltage powertrain interference from audio signal paths. Suppliers serving Bavarian and Stuttgart-based OEMs are requalifying PCB substrates and shielding architectures to meet amended CE marking test protocols. The regulatory pressure is compressing development cycles for integrated speaker-controller modules.
Fleet procurement managers are unbundling factory-installed acoustic alerting systems from base vehicle specifications, creating direct supplier relationships for sound generation modules that bypass tier-1 audio integrators. Large ride-hail operators in California and Guangdong province are specifying configurable sound profiles that align with municipal noise ordinances across operating territories. This channel disintermediation is fragmenting traditional OEM-tier-1 supply hierarchies and concentrating volume with specialized electromagnetic driver manufacturers.
Acoustic Vehicle Alerting System Market Segmentation
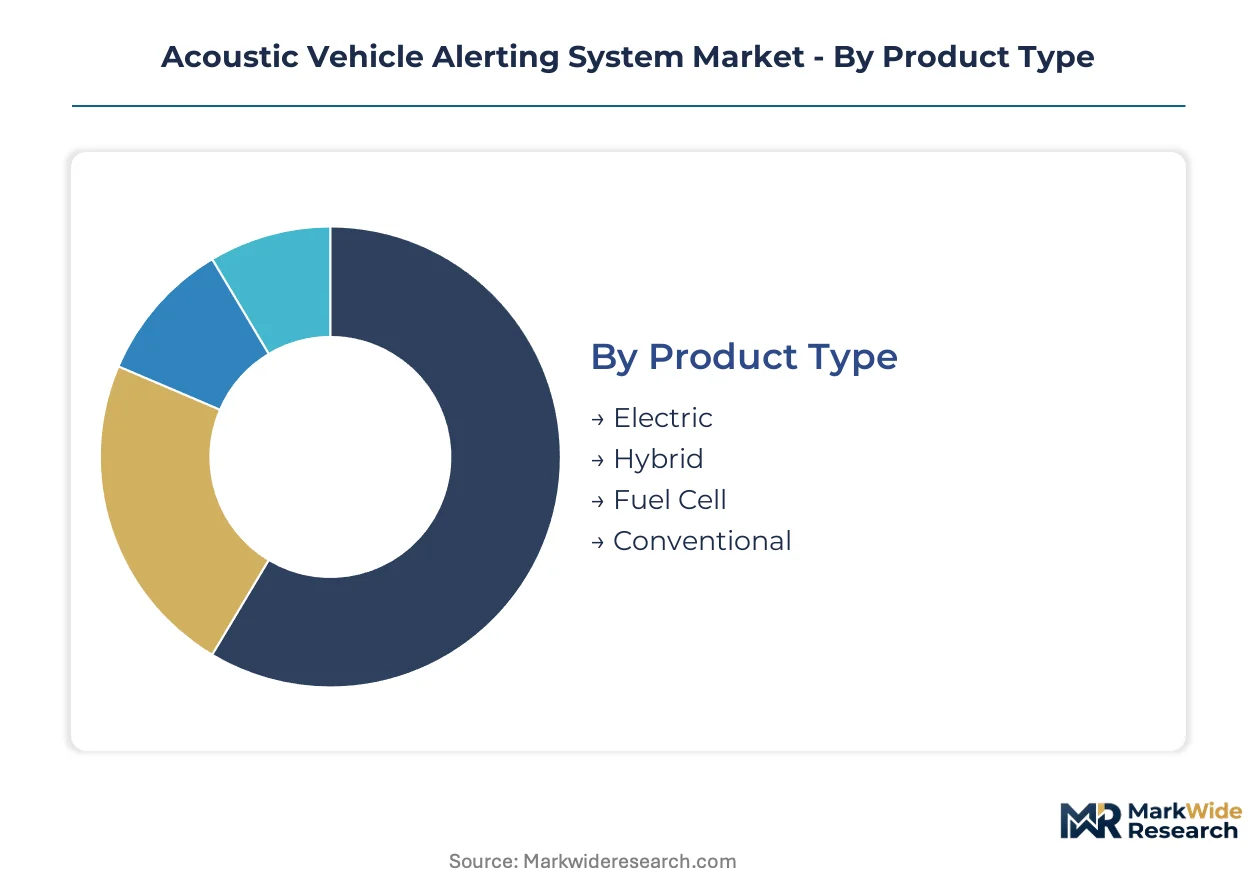
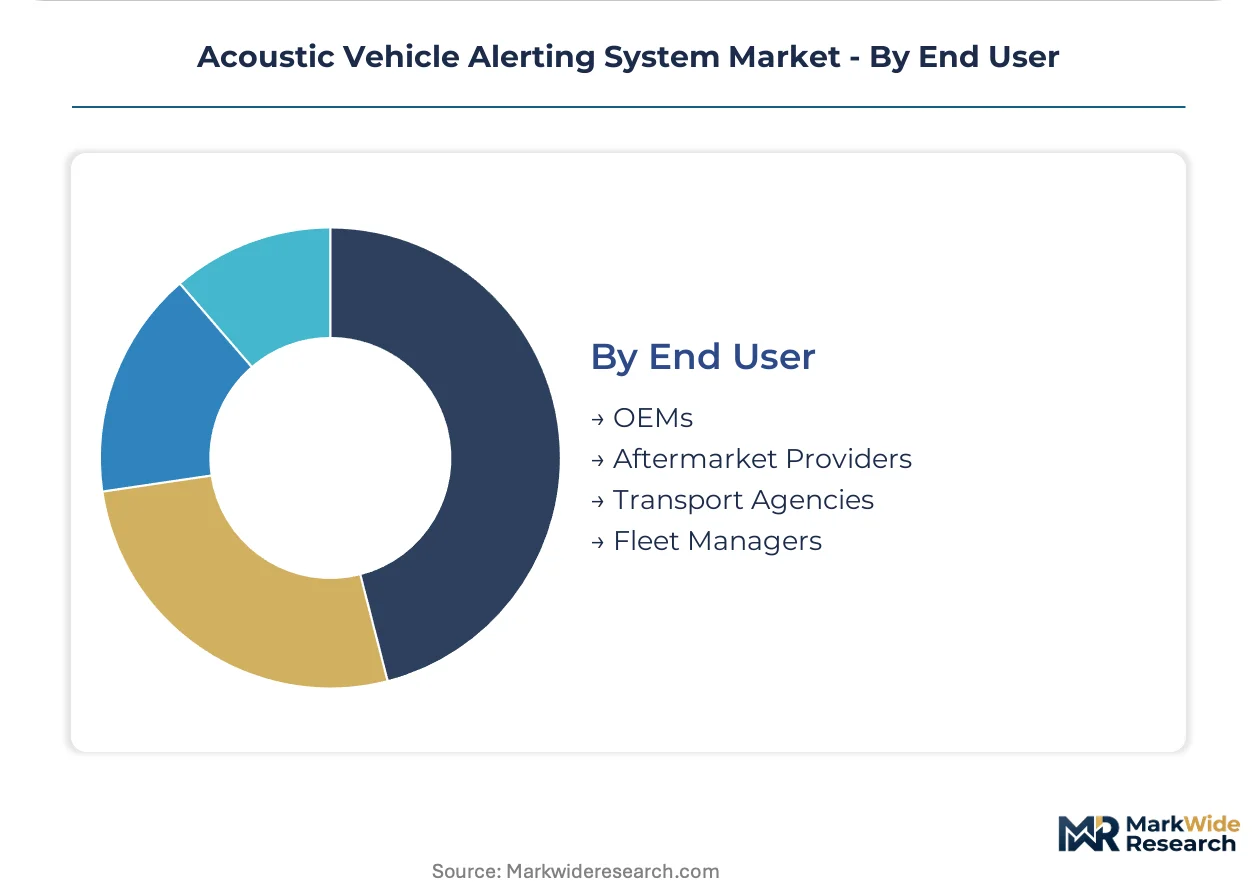
Segmentation in the acoustic vehicle alerting system market reveals divergent technology readiness and procurement authority across vehicle electrification levels and buyer types. Supply chain configuration varies sharply between factory-integrated OEM programs and fragmented aftermarket retrofit channels.
Product Type:
Supply concentration clusters around battery-electric architectures where zero native engine noise creates non-negotiable alerting requirements.
- Electric:Battery-electric powertrains demand synthesized external sound generation across all speed ranges, with procurement concentrated among California and Guangdong-based OEMs facing NHTSA and MIIT compliance deadlines. This segment anchors current manufacturing scale for electromagnetic driver suppliers.
- Hybrid:Dual-powertrain vehicles require intermittent alerting systems that activate during electric-only operation, with demand concentrating in Japanese and German OEM portfolios where engine-bay packaging constraints favor compact transducer designs. Supply qualification timelines here run shorter than full-electric programs.
- Fuel Cell:Hydrogen-electric architectures share acoustic signatures with battery EVs, with procurement emerging in South Korean and Japanese commercial vehicle trials.
- Conventional:Internal combustion engines retain sufficient native noise to exempt most applications, though regulatory harmonization discussions in EU frameworks occasionally revisit legacy fleet requirements.
Today's leader: Electric. Tomorrow's challenger: Hybrid.
Technology:
Cost tier differentiation separates established electromagnetic hardware from algorithm-intensive software-defined systems.
- AI-Driven Systems:Machine learning-enabled sound profiles adapt pedestrian-warning output to vehicle speed, urban density, and ambient noise conditions in real time. Premium OEMs in Germany and California are specifying these systems for luxury EV platforms where brand differentiation commands procurement priority.
- Sound Generation:Fixed-waveform synthesizers using pre-recorded audio loops dominate volume production for mid-market electric models, with manufacturing concentrated among established automotive audio suppliers serving high-volume OEM programs.
- Sensors:Environmental detection modules providing speed, direction, and proximity inputs to alerting controllers are gaining specification in integrated safety system bundles.
- Electromagnetic Technology:Compact driver designs using rare-earth magnets remain essential for tight packaging constraints in hybrid engine bays, though neodymium price volatility compresses margin stability.
AI-Driven Systems are climbing the fastest. Sound Generation retains volume dominance.
Application:
Volume concentration favors passenger vehicle OEM programs, while margin opportunity shifts toward micro-mobility and commercial fleet specifications.
- Passenger Vehicles:Light-duty electric and hybrid cars generate the dominant procurement volume, with factory installation rates compelled by NHTSA Federal Motor Vehicle Safety Standard 141 and EU vehicle safety frameworks across German, French, and Italian OEM assembly lines.
- Commercial Vehicles:Electric bus and delivery van fleets in California and Guangdong province are specifying configurable alerting profiles that align with municipal noise ordinances across operating territories.
- E-Scooters:Shared micromobility operators in European cities face emerging local regulations requiring pedestrian-warning systems on electric standing scooters.
- Bicycles:Electric bicycle alerting requirements remain fragmented across national jurisdictions, with procurement concentrated in aftermarket channels for premium urban mobility models.
Passenger Vehicles command current volume. Commercial Vehicles present the steepest expansion trajectory.
End User:
Customer type determines procurement authority, with OEMs retaining specification control and fleet managers emerging as direct buyers.
- OEMs:Original equipment manufacturers capture the dominant margin pool through factory-installed programs, integrating alerting systems into vehicle network architectures during platform development cycles in Stuttgart, Tokyo, and Detroit metro clusters.
- Fleet Managers:Large ride-hail and logistics operators in California and Guangdong are bypassing tier-1 audio integrators to specify direct supplier relationships for sound generation modules with territory-configurable profiles.
- Aftermarket Providers:Independent service channels serve early-generation EVs lacking compliant equipment, with demand concentrated in Germany and Japan for retrofit installations.
- Transport Agencies:Municipal procurement authorities are emerging as specification influencers for shared micromobility and public transit electrification programs.
OEMs defend current margin concentration. Fleet Managers are gaining procurement authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered automotive acoustic engineering for pedestrian safety, scaling production through Stuttgart and Munich supplier clusters before regulatory mandates spread to Asia-Pacific and North American markets.
United States
NHTSA Federal Motor Vehicle Safety Standard 141 compels OEM installation across hybrid and electric fleets. California's Advanced Clean Cars program accelerates procurement timelines for Detroit and Silicon Valley engineering centers. Ride-hail operators in Los Angeles and San Francisco now specify direct supplier relationships for territory-configurable sound profiles.
Germany
KBA homologation requirements concentrate supplier qualification efforts in Bavaria and Baden-Württemberg. EU REACH compliance and amended CE marking protocols force PCB substrate redesigns for electromagnetic compatibility. Stuttgart-based OEMs anchor premium-tier procurement for configurable brand signature systems.
China
MIIT new energy vehicle standards create a third regulatory layer for export-oriented suppliers. Guangdong province dominates domestic NEV procurement programs with Shenzhen and Guangzhou assembly plants scaling electromagnetic driver production. GB standards for minimum sound levels reshape product specifications for battery-electric architectures.
Japan
METI guidelines for quiet vehicle safety align with international harmonization efforts. Tokyo and Nagoya metro clusters concentrate acoustic engineering talent for compact transducer designs suited to hybrid engine-bay packaging. Domestic OEMs specialize in intermittent alerting systems for dual-powertrain portfolios.
South Korea
Ministry of Land, Infrastructure and Transport mandates for electric vehicle sound generation drive factory installation rates. Seoul Capital Area engineering centers develop algorithm-enabled dynamic profiles responding to vehicle kinematics. Busan-Ulsan manufacturing corridors scale production for export-oriented electromagnetic modules.
Acoustic Vehicle Alerting System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory compliance bundling. The vendor base organizes into three tiers: integrated audio conglomerates with vehicle network architecture expertise, specialized electromagnetic driver fabricators serving packaging-constrained applications, and semiconductor suppliers providing control electronics and signal processing. Consolidation pressures favor scale-driven manufacturers with multi-jurisdiction certification capabilities. Strategic moves center on backward integration into rare-earth magnet supply chains and technology licensing partnerships for AI-driven sound generation algorithms.
Within the integrated audio tier, Harman International and Continental AG exemplify premium-positioned suppliers leveraging manufacturing scale across European and Asian assembly plants. Denso Corporation occupies a compact-specialist position suited to tight engine-bay packaging constraints in hybrid architectures. These three anchors represent divergent competitive vectors: brand-signature configurability, production scale, and miniaturization expertise.
| Leading Market Players |
|---|
| Harman International |
| Robert Bosch GmbH |
| Continental AG |
| Thor |
| Texas Instruments Incorporated |
| Hella GmbH & Co. KGaA |
| Denso Corporation |
| Valeo S.A. |
| Kendrion N.V. |
| Others |
Supply Flow & Price Mechanics
Neodymium price index volatility cascades through electromagnetic driver production into three distinct pricing tiers, compressing margins for compact transducer manufacturers while amplifying procurement leverage for buyers qualifying multiple suppliers across German and Chinese assembly corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs acoustic alerting system procurement, with certification grade and volume scale as primary differentiation drivers. Premium-configurable AI-driven systems command substantial markups from Stuttgart-based luxury OEMs, while fixed-waveform synthesizers face intensifying cost compression in high-volume electric vehicle programs. Fleet managers in California exhibit highest price sensitivity through unbundled direct procurement, whereas German OEM platform engineers prioritize electromagnetic compatibility compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by NHTSA and KBA homologation protocols force OEMs to qualify electromagnetic driver suppliers across Germany, China, and Japan simultaneously. Rare-earth magnet feedstocks, PCB substrates, and compact speaker housings anchor component dependencies, with neodymium supply concentration in Chinese processing facilities creating tariff exposure vulnerability. Distribution runs through tier-1 audio integrators toward factory installation channels, though fleet procurement disintermediation is fragmenting traditional hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acoustic vehicle alerting system market functions as a stable compounder, with regulatory mandate expansion across NHTSA, EU frameworks, and MIIT standards providing non-discretionary demand visibility.
For Market Incumbents: Acquire AI-driven sound generation algorithm portfolios to defend against semiconductor suppliers encroaching on control electronics territory. Backward integration into rare-earth magnet supply chains mitigates neodymium price volatility threatening margin stability in compact transducer production. For New Entrants and Emerging Players: Begin with aftermarket retrofit channels for early-generation EVs in Germany and Japan, where independent service networks lack compliant equipment installation capacity. Municipal procurement for shared micromobility alerting systems in European cities offers the most penetrable white-space entry point. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized electromagnetic driver fabricators possessing multi-jurisdiction certification capabilities and hybrid engine-bay miniaturization expertise. Long-term viability hinges on platform standardization convergence across regulatory regimes, with MIIT-EU-NHTSA threshold harmonization as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Licensing Partnership | Enables dynamic sound profile differentiation for luxury EV platforms in Germany and California. |
| Rare-Earth Magnet Supply Security | Captive neodymium sourcing insulates margin stability against Chinese export restriction volatility. |
| Multi-Jurisdiction Certification Investment | Parallel NHTSA-KBA-MIIT homologation capability compresses OEM supplier qualification timelines. |
| Fleet Procurement Channel Development | Direct relationships with California and Guangdong ride-hail operators bypass tier-1 integrator capture. |
| Parametric Array Transducer Scale-Up | Directional acoustic beam technology addresses municipal noise ordinance compliance for premium OEMs. |
Methodological Framework
Direct dialogue with OEM platform engineers, tier-1 audio integrator procurement leads, aftermarket distributor operations heads, and electromagnetic driver R&D directors grounded qualitative findings in operational reality. Secondary validation drew from NHTSA FMVSS 141 docket filings, EU REACH amendment records, MIIT new energy vehicle standard publications, and vehicle production registration databases. Bottom-up unit shipment estimates and top-down regulatory mandate penetration rates underwent iterative triangulation.
Bottom-up modeling segmented volume across electric-hybrid-fuel cell propulsion architectures, AI-driven versus fixed-waveform technology tiers, and OEM-fleet-aftermarket end-user channels. Top-down analysis calibrated aggregate market expansion to NHTSA compliance deadline phasing and EU vehicle safety framework amendment timelines. CAGRs emerged from regression against electrification penetration curves and regulatory adoption lag patterns, with rare-earth price indices and semiconductor lead times as sensitivity inputs.
Caveats apply where regulatory threshold harmonization delays or neodymium supply disruption could materially shift the outlook. Forecasts embed assumptions regarding OEM installation rate trajectories and fleet procurement channel maturation. Deviation in MIIT-EU-NHTSA test protocol convergence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Speed Limiter Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Speed Bumps & Humps Market
Automotive Safety and Security Systems
United States Automotive Airbag Systems Market
Automotive Safety and Security Systems
Seat Belt Pretensioner and Load Limiter Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Automotive Whiplash Protection Equipment Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
China Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Side Guard Door Beam Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Anti-Fog Lights Market