
 Automatic Brake Pad Inspection System Market | 2026-2036
Automatic Brake Pad Inspection System Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Brake Pad Inspection System Market Analysis
The EU Green Deal is broadening compliance requirements for rail infrastructure maintenance across European networks. Siemens leverages its signaling heritage to anchor automated inspection contracts with Deutsche Bahn and SNCF. Kistler competes through piezoelectric sensor integration that sustains measurement accuracy under extreme thermal cycling in brake testing rigs.
An automatic brake pad inspection system comprises electromechanical assemblies, optical sensors, and software algorithms that evaluate brake pad thickness, thermal cracking, and material wear against manufacturer tolerances, typically resolving measurements to 0.1 millimeters for safety-critical rail and heavy-duty commercial vehicle applications. Automated inspection machines lead capital deployment as fleet operators replace manual caliper checks with conveyor-integrated stations that compress depot turnaround times. Machine vision systems represent the fastest-expanding technology segment because semiconductor improvements in CMOS line-scan cameras now resolve composite friction material textures at production-line speeds.
EMA medical device traceability standards and EU F-Gas Regulation compressor requirements indirectly shape inspection system calibration protocols through cross-sector quality system harmonization. REACH substance restrictions on copper in brake friction materials force OEMs to validate alternative formulations through enhanced automated testing cycles. Stakeholders must monitor how ECHA restriction proposals cascade into revised pad composition standards that demand recalibrated inspection algorithms.
Market Dynamics
Machine vision technology is displacing manual caliper measurements in rail depots and commercial vehicle service centers, compressing inspection cycles from hours to minutes while tightening tolerance compliance under stricter safety mandates.
Growth Catalysts
- EU Green Deal maintenance mandates:Railway operators across Germany, France, and Italy face accelerated procurement timelines for automated inspection equipment to meet carbon-neutral infrastructure targets.
- CMOS line-scan camera advances:Semiconductor improvements now resolve composite friction material textures at production-line speeds, enabling real-time defect detection in high-throughput depots.
- Copper-free brake pad formulations:REACH substance restrictions force OEMs to validate alternative materials through enhanced automated testing cycles, expanding inspection system deployment.
Market Restraints
- Piezoelectric sensor thermal drift:Extreme temperature cycling in brake testing rigs degrades measurement accuracy, requiring frequent recalibration that increases operational overhead.
- Specialized optics supply concentration:High-resolution line-scan cameras depend on concentrated semiconductor fabrication capacity in East Asian foundries, exposing procurement to geopolitical disruption.
- F-Gas Regulation compressor compliance:EU cooling requirements for inspection system electronics add certification complexity and extend equipment qualification timelines.
Strategic Opportunities
- Indian rail modernization:The Dedicated Freight Corridor and metro expansion projects create demand for automated depot equipment as the network scales beyond manual inspection capacity.
- Predictive maintenance convergence:Integration of thermal imaging with vibration analytics enables condition-based pad replacement, shifting revenue models toward subscription diagnostics.
- EMA medical device traceability spillover:Cross-sector quality system harmonization creates calibrated inspection protocols transferable to aerospace and defense brake applications.
Industry Challenges
- Multi-sensor fusion expertise:Shortage of engineers capable of integrating optical, electromechanical, and algorithmic subsystems delays commissioning of complex inspection lines.
- Legacy depot infrastructure retrofit:Existing maintenance facilities lack structural clearance and power distribution for conveyor-integrated inspection stations, requiring costly civil modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Brake Pad Inspection System Market |
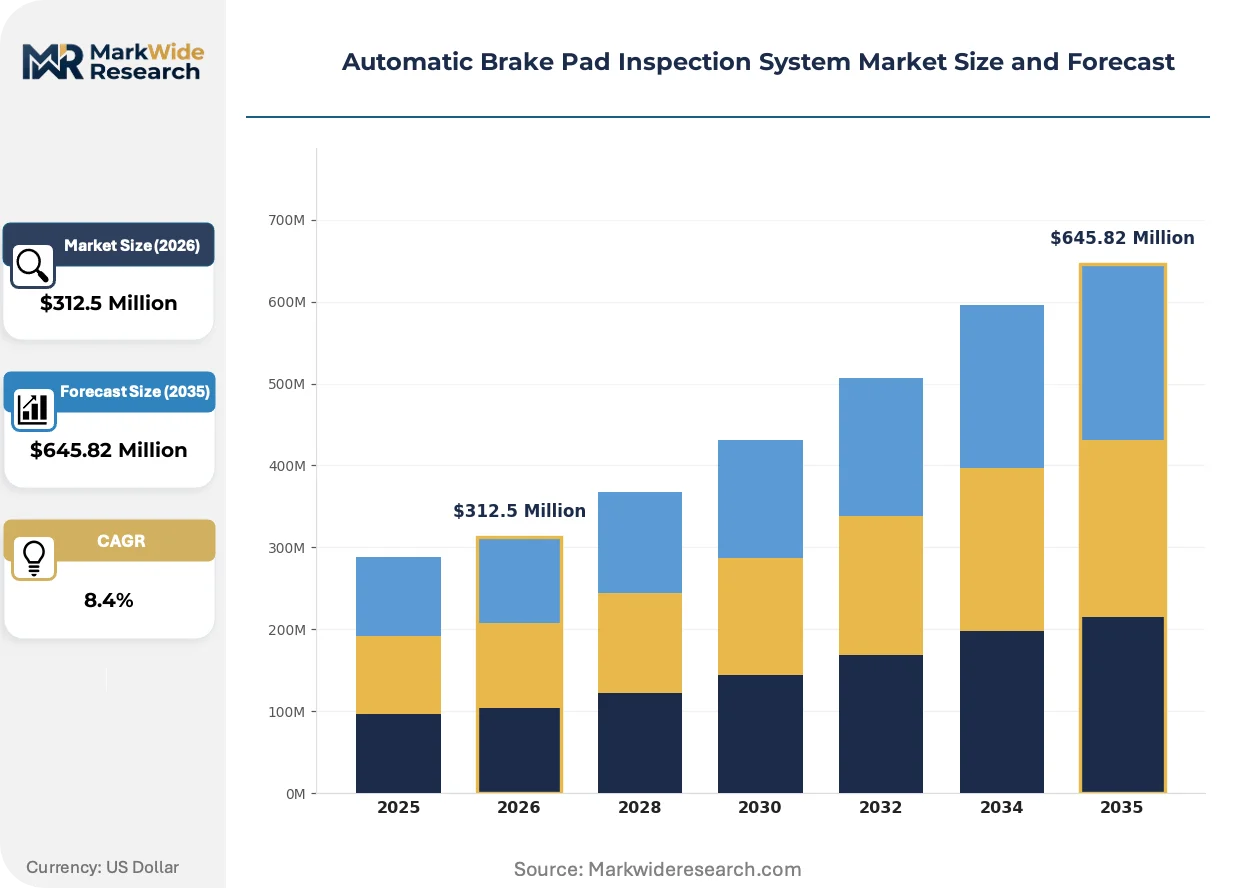
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Inspection Tools, Automated Inspection Machines, Software Solutions, Inspection Jigs End User: OEMs, Aftermarket Providers, Fleet Operators, Service Centers Technology: Machine Vision Systems, Ultrasonic Testing, Laser Measurement, RFID Tracking Application: Quality Control, Production Line Monitoring, Maintenance Inspection, Safety Compliance |
| Companies Covered | Alstom, Kistler, SELVISTIC, Australian Rail Technology, JLI Vision, NERMEC GROUP, Bombardier, Rail Vision Europe, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Brake Pad Inspection System Market Emerging Trajectories
Deep learning architectures are reshaping defect classification accuracy while regulatory pressure on friction material composition forces continuous algorithm recalibration. These forces are compressing equipment refresh cycles and redefining supplier value propositions.
Convolutional neural networks for crack detection are integrating thermal and visual data streams to distinguish surface scoring from critical structural fractures in composite brake pads. Deutsche Bahn and SNCF maintenance divisions deploy these systems in high-speed rail depots where manual inspection cannot match turnaround deadlines. The technology is integrating previously separate metrology functions into unified stations that consolidate capital deployment.
REACH copper restrictions and pending ECHA proposals on heavy metals in friction materials mandate reformulation validation protocols that automated inspection systems must accommodate. Brake pad manufacturers face expanded testing matrices to certify alternative compositions against performance benchmarks. European OEMs are responding by embedding adaptive algorithm frameworks that accept new material signatures without hardware replacement.
Service unbundling is fragmenting traditional equipment sales as fleet operators demand inspection-as-a-service models with guaranteed uptime. Independent maintenance providers in Italy and Spain now lease inspection capacity rather than owning capital-intensive stations. This pattern is most visible among regional bus operators where seasonal demand volatility makes fixed asset ownership economically unattractive.
Automatic Brake Pad Inspection System Market Segmentation
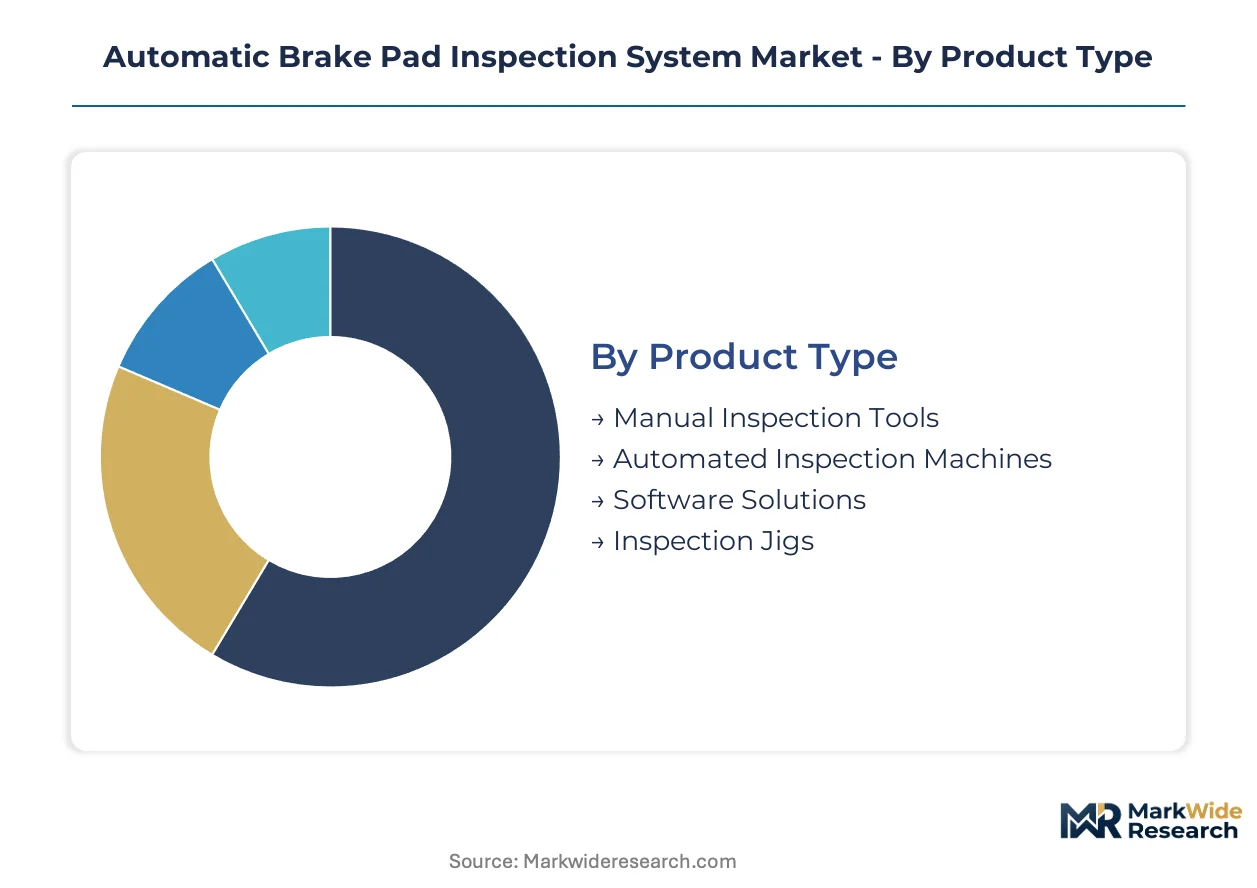
Brake pad inspection systems segment across product architectures, user procurement models, sensing technologies, and operational use cases. Each dimension carries distinct margin profiles, technical barriers, and regulatory exposure that shape supplier positioning and buyer decision criteria.
Product Type:
Capital intensity and labor substitution potential drive buyer selection across equipment tiers.
- Automated Inspection Machines:Conveyor-integrated electromechanical stations with optical sensors and algorithmic classification resolve pad thickness to 0.1 millimeters. Deutsche Bahn and SNCF depots deploy these systems to compress turnaround times under EU Green Deal maintenance mandates.
- Software Solutions:Algorithmic platforms for defect classification and predictive analytics integrate with existing hardware. Fleet operators in Italy and Spain increasingly adopt inspection-as-a-service models where software subscriptions replace capital ownership.
- Manual Inspection Tools:Caliper-based gauges and visual inspection kits serve legacy fleets with low throughput requirements.
- Inspection Jigs:Fixture-mounted measurement devices for production-line sampling in brake pad manufacturing facilities.
Automated Inspection Machines lead on scale; Software Solutions lead on momentum.
End User:
Procurement authority and volume concentration vary sharply across buyer categories.
- Fleet Operators:Rail and commercial vehicle fleets with centralized maintenance contracts drive volume procurement of conveyor-integrated stations. Indian rail modernization through Dedicated Freight Corridor projects expands addressable demand beyond European saturation.
- OEMs:Brake pad manufacturers require in-line inspection for REACH copper-free formulation validation and thermal cycling certification.
- Aftermarket Providers:Independent maintenance networks in Southern Europe lease inspection capacity rather than owning equipment.
- Service Centers:Decentralized commercial vehicle workshops with intermittent demand patterns favor manual or semi-automated tools.
Fleet Operators concentrate procurement volume; OEMs concentrate specification authority.
Technology:
Measurement accuracy requirements and environmental tolerance define technology selection.
- Machine Vision Systems:CMOS line-scan cameras resolve composite friction material textures at production-line speeds. Convolutional neural networks now integrate thermal and visual data streams to distinguish surface scoring from critical fractures in high-speed rail applications.
- Laser Measurement:Triangulation sensors deliver non-contact thickness profiling with immunity to thermal drift that degrades piezoelectric alternatives.
- Ultrasonic Testing:Subsurface crack detection in thick composite pads where optical methods face penetration limits.
- RFID Tracking:Pad lifecycle traceability for maintenance record compliance under cross-sector quality system harmonization.
Machine Vision Systems command installed base; Laser Measurement gains share fastest.
Application:
Regulatory exposure and throughput requirements shape functional deployment.
- Maintenance Inspection:Depot-based pad evaluation for in-service fleets where EU Green Deal carbon-neutral infrastructure targets accelerate automation procurement across Germany, France, and Italy.
- Quality Control:Manufacturing-line acceptance testing for alternative friction material formulations under REACH substance restrictions.
- Production Line Monitoring:Real-time process control in brake pad fabrication with adaptive algorithm frameworks for new material signatures.
- Safety Compliance:Certification testing against manufacturer tolerances for safety-critical rail and heavy-duty commercial vehicle applications.
Maintenance Inspection dominates revenue; Quality Control tightens specification control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automated brake pad inspection technology originated in European rail maintenance depots during the 1990s, where German and French operators pioneered machine vision systems to replace manual caliper measurements. This heritage established technical standards that now diffuse into commercial vehicle and emerging rail markets worldwide.
Germany
Deutsche Bahn operates Europe's densest high-speed rail network with mandatory depot automation under EU Green Deal carbon-neutral infrastructure targets. KBA vehicle safety regulations enforce 0.1-millimeter measurement tolerance compliance for brake pad certification. Siemens anchors automated inspection deployment from its Munich signaling heritage base, supplying conveyor-integrated stations across Bavaria and North Rhine-Westphalia maintenance facilities.
France
SNCF maintenance divisions face compressed turnaround deadlines on TGV lines where manual inspection cannot match operational tempo. ANSM quality system harmonization from medical device traceability spills into rail maintenance protocols, tightening calibration requirements. The Paris-Saclay rail technology cluster hosts algorithm development for convolutional neural networks that integrate thermal and visual crack detection data streams.
Italy
Regional bus operators and independent maintenance providers in Lombardy and Emilia-Romagna increasingly lease inspection capacity rather than owning capital-intensive stations. REACH copper restrictions on brake friction materials force OEMs to validate alternative formulations through enhanced automated testing cycles. Turin-based brake pad manufacturers deploy adaptive algorithm frameworks to accommodate new material signatures without hardware replacement.
India
The Dedicated Freight Corridor and metro expansion projects in Maharashtra and Gujarat create demand for automated depot equipment as the network scales beyond manual inspection capacity. BIS standards for rolling stock safety equipment accelerate procurement timelines for foreign inspection system suppliers. The Chennai-Bengaluru industrial corridor attracts technology transfer partnerships for machine vision integration into new maintenance facilities.
United States
Class I railroads and commercial vehicle fleet operators deploy automated inspection to compress depot turnaround times amid driver shortage pressures. NHTSA commercial vehicle safety mandates tighten brake system compliance documentation requirements. The Chicago rail hub and Texas freight corridors concentrate deployment of laser measurement systems that deliver non-contact thickness profiling with thermal drift immunity.
Automatic Brake Pad Inspection System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration depth, with algorithmic sophistication and multi-sensor fusion capabilities commanding pricing power. The vendor base stratifies into three tiers: integrated rail system suppliers with signaling heritage, specialized sensor technology firms with piezoelectric or optical expertise, and emerging software-centric challengers unbundling inspection-as-a-service models. Dominant competitive moves include strategic partnerships between hardware manufacturers and algorithm developers, plus geographic expansion through local depot retrofit contracts in Indian and Southeast Asian rail modernization programs.
Among European-anchored integrated suppliers, Alstom and Siemens exemplify the signaling-heritage archetype that leverages existing rail operator relationships to secure automated inspection contracts. Kistler occupies a position within the precision sensor specialist tier, with its piezoelectric measurement technology representing an alternative technical approach to optical systems. These three companies collectively illustrate how competitive positioning fragments across hardware integration depth, sensor modality specialization, and service model innovation vectors.
| Leading Market Players |
|---|
| Alstom |
| Kistler |
| SELVISTIC |
| Australian Rail Technology |
| JLI Vision |
| NERMEC GROUP |
| Bombardier |
| Rail Vision Europe |
| Siemens |
| Others |
Supply Flow & Price Mechanics
Performance-tier bifurcation between algorithm-intensive machine vision stations and commodity sensor packages manifests in both pricing power and supply chain geography. Premium systems commanding measurement precision to 0.1 millimeters source CMOS line-scan cameras from concentrated East Asian foundries, while standard-tier equipment draws from distributed electromechanical component networks across Eastern Europe and Mexico.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and after-sales service bundling. Price differentiation hinges on EU Green Deal compliance documentation and predictive maintenance software integration. Cost compression in the economy tier intensifies because fleet operators in Southern Europe favor inspection-as-a-service models over capital ownership. Regional bus operators exhibit highest price sensitivity; high-speed rail operators in Germany and France demonstrate lowest sensitivity due to mandated automation procurement timelines.
Supply Chain Analysis
High-resolution optical sensor supply rests on Taiwanese and South Korean semiconductor fabrication capacity, with secondary electromechanical assembly concentrated in Germany and Italy. Raw material dependencies include precision-grade aluminum alloys for inspection jigs, piezoelectric ceramics for thermal measurement modules, and specialty glass for line-scan camera optics. Single-source vulnerability in CMOS sensor wafers exposes procurement to geopolitical disruption. Distribution runs through OEM-direct contracts for large fleet operators and regional equipment lessors for aftermarket service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory compliance costs in Germany and France exceed Indian procurement budgets by multiples, creating margin expansion for suppliers with localized production footprints.
For Market Incumbents: Extend algorithm development partnerships with Paris-Saclay and Munich research clusters to maintain convolutional neural network leadership against software-centric challengers. Anchor Deutsche Bahn and SNCF relationships through predictive maintenance subscription bundling that raises switching costs. Counter inspection-as-a-service unbundling by embedding hardware-software lock-in through proprietary thermal-visual data fusion protocols. For New Entrants and Emerging Players: Independent maintenance providers in Spain and Italy represent the most penetrable buyer archetype given their lease-preference over ownership and fragmented supplier relationships. Target Indian Dedicated Freight Corridor depot retrofit contracts where European incumbents lack localized service infrastructure. Enter through software-only deployment with adaptive algorithm frameworks that accommodate REACH-mandated copper-free brake pad formulations without hardware redesign. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-sensor fusion engineering talent scarcity intersects with legacy depot infrastructure retrofit complexity. Long-term viability favors suppliers with captive algorithm development and established rail operator maintenance contracts. Watch ECHA restriction proposals on heavy metals in friction materials as the inflection signal triggering recalibration service revenue spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm-Hardware Integration Partnership | Convolutional neural networks from Paris-Saclay clusters embed into Siemens rail depot stations, tightening specification control. |
| Copper-Free Formulation Validation Service | Turin-based OEMs deploy adaptive testing protocols under REACH mandates, expanding recurring revenue from reformulation cycles. |
| Indian Technology Transfer Agreement | Chennai-Bengaluru corridor partnerships localize machine vision assembly for Dedicated Freight Corridor procurement timelines. |
| Predictive Maintenance Platform Launch | Thermal imaging-vibration analytics integration shifts SNCF and Deutsche Bahn contracts toward subscription diagnostics models. |
| Inspection-as-a-Service Regional Expansion | Lombardy and Emilia-Romagna leasing networks reduce capital barriers for seasonal bus operators in Southern Europe. |
Methodological Framework
Bottom-up fleet operator procurement modeling reconciled against top-down sensor technology shipment tracking forms the analytical core. Primary interviews with rail maintenance directors, brake pad manufacturing quality engineers, depot operations managers, and independent service center owners combined with secondary validation from BIS rolling stock safety filings, EU Green Deal implementation reports, REACH substance restriction databases, and customs trade data for automated inspection equipment. Triangulation between demand-side procurement timelines and supply-side component availability ensures cross-verified market sizing.
Historical trendline analysis of machine vision adoption rates in European rail depots established baseline penetration curves extended across the projection horizon. Segmentation dimensions modeled include product architecture tier, end-user procurement authority, sensing technology modality, and application regulatory exposure, with additional granularity on copper-free formulation testing intensity. CAGRs derive from equipment replacement cycle compression and algorithm recalibration frequency under evolving ECHA proposals. Forecast inputs incorporate CMOS camera semiconductor supply constraints and Indian rail network expansion capex allocations.
Inputs from rail operator maintenance departments and brake pad OEM quality systems were available through the study window; gaps in real-time Indian depot automation procurement data introduce uncertainty bands. Forecasts reflect documented assumptions on EU Green Deal mandate enforcement timing and REACH restriction finalization. Specific risk factors that could revise projections include geopolitical disruption to East Asian optical sensor supply and accelerated copper substitution timelines in friction materials. A small set of named triggers—ECHA heavy metal restriction finalization, Indian BIS standard harmonization progress, and CMOS foundry capacity expansion announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Surge Absorber Market
Automotive Safety and Security Systems
Automotive Whiplash Protection Equipment Market
Automotive Safety and Security Systems
Car Camera Cleaning Systems Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
Driver Assistance System Market
Automotive Safety and Security Systems
Ignition Interlock Devices Market
Automotive Safety and Security Systems
Road Speed Limiter Market
Automotive Safety and Security Systems
Lane Change Assist Systems Market
Automotive Safety and Security Systems
Africa and Middle East Airbag Systems Market
Automotive Safety and Security Systems
Global Automotive Defogger System Market
Automotive Safety and Security Systems
Biometric Vehicle Access System Market
Automotive Safety and Security Systems
Automotive Anti-Pinch Power Window System Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Germany Traffic Sign Recognition Market
Automotive Safety and Security Systems
Global Automotive Anti Pinch Window Market