
 Germany Contract Logistics Market | 2026-2036
Germany Contract Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Contract Logistics Market Foresight
Lightweight composite racking and modular aluminum framing is decoupling warehouse construction costs from traditional steel price volatility. DHL Supply Chain & Global Forwarding leverages its pan-European network density to anchor multi-client fulfillment campuses across the Rhine-Ruhr region. Dachser SE specializes in European groupage and industrial project logistics, occupying a defensible niche in temperature-controlled and high-value cargo segments. Fiege Logistik controls dedicated e-commerce fulfillment infrastructure, positioning its last-mile nodes to serve same-delivery demand from Berlin and Hamburg metropolitan zones.
Germany contract logistics encompasses the outsourced management of warehousing, transportation, inventory control, and value-added services under long-term service agreements, typically operating through facilities exceeding 10,000 square meters with WMS-integrated material handling systems designed to reduce client working capital cycles. The service type dimension shows warehousing and transportation commanding the largest revenue pools while supply chain consulting and reverse logistics represent the fastest-expanding margin opportunities as clients seek circular economy integration. Client type concentration tilts heavily toward automotive OEMs and electronics producers, where just-in-sequence delivery requirements and customs complexity sustain premium pricing power for providers with bonded warehouse status and VDA 6.3 quality certification.
Germany's Supply Chain Due Diligence Act and the EU CSRD disclosure rules are forcing logistics providers to document Scope 3 emissions and sub-tier supplier labor practices, raising compliance barriers for mid-tier competitors lacking integrated ESG data architectures. The KBA enforces vehicle emissions and safety standards that directly shape fleet renewal timelines and alternative drivetrain adoption across road-based contract logistics operations. Stakeholders must monitor how the EU AI Act's risk-classification framework will constrain automated decision-making in warehouse robotics and route optimization systems before committing capital to next-generation automation platforms.
Market Dynamics
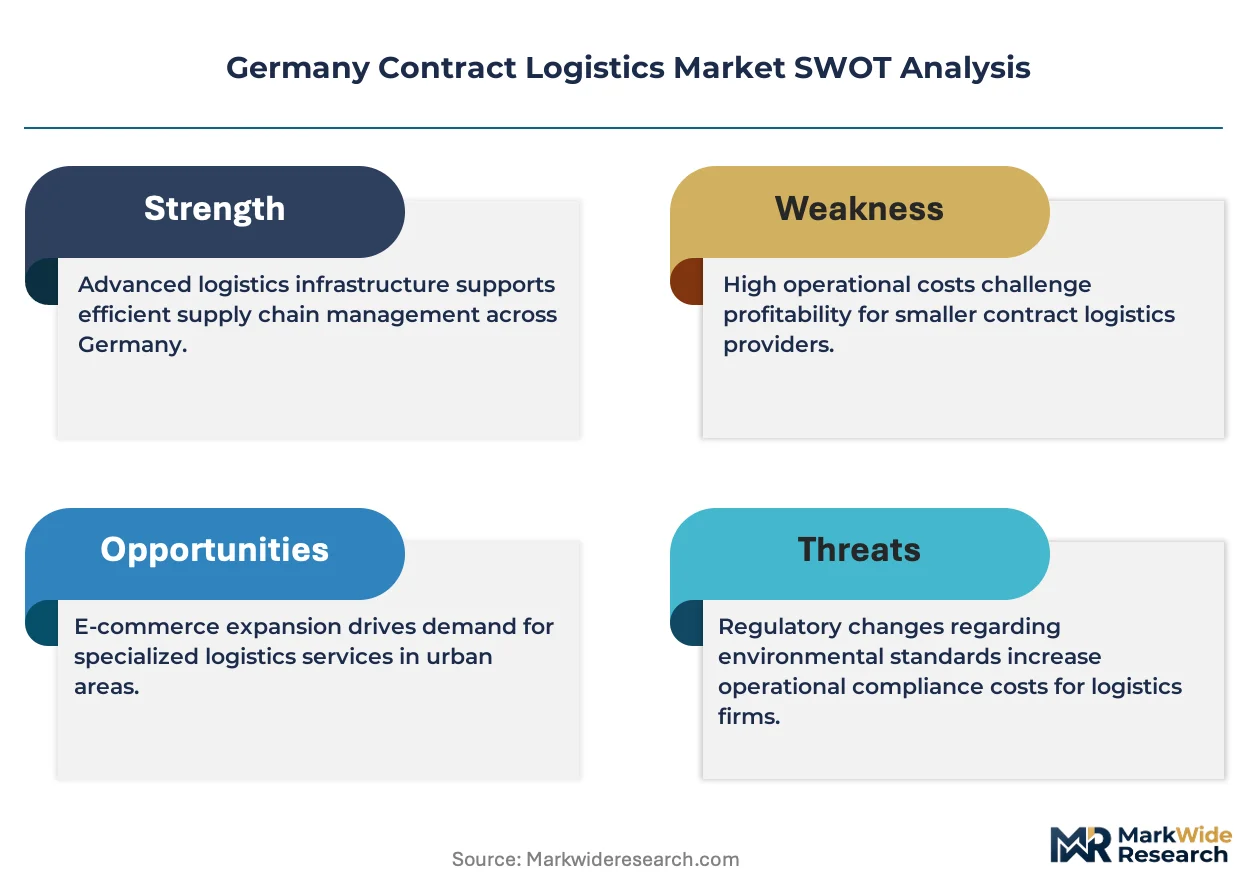
Germany's Supply Chain Due Diligence Act is forcing logistics providers to rebuild transparency infrastructure around sub-tier supplier monitoring and Scope 3 emissions documentation, compressing margins for mid-tier operators lacking integrated ESG data architectures.
Growth Catalysts
- Automotive OEM outsourcing:German automotive manufacturers are expanding reliance on third-party fulfillment networks to manage just-in-sequence delivery complexity and reduce fixed asset exposure.
- EU CSRD disclosure rules:Corporate sustainability reporting mandates are creating premium service tiers for providers with verified emissions tracking and circular economy integration capabilities.
- Baden-Württemberg cluster density:Concentrated electronics and automotive manufacturing in this industrial corridor sustains demand for bonded warehousing and VDA 6.3-certified operations.
Market Restraints
- Steel-aluminum input volatility:Lightweight composite racking and modular aluminum framing decouple warehouse construction from traditional steel price swings, yet material substitution costs strain capex planning.
- Mid-tier compliance barrier:The KBA's vehicle emissions standards and EU AI Act risk-classification frameworks raise technical and certification thresholds that smaller operators cannot absorb.
- Regional supply concentration:Rhine-Ruhr logistics capacity dominance creates bottleneck risk during peak automotive production cycles or customs processing surges.
Strategic Opportunities
- Bavaria corridor expansion:Underpenetrated high-value cargo and temperature-controlled segments in this southern manufacturing zone offer defensible niche positioning.
- EU Green Deal fleet incentives:Alternative drivetrain adoption subsidies are compressing payback periods for electric and hydrogen-powered last-mile vehicle investments.
- Same-day delivery infrastructure:Berlin and Hamburg metropolitan zones lack sufficient urban micro-fulfillment nodes to serve accelerating e-commerce service-level expectations.
Industry Challenges
- WMS-legacy system integration:Material handling automation requires costly middleware development to synchronize with client ERP platforms and proprietary inventory systems.
- VDA 6.3 certification timelines:Quality management audits for automotive sector entry consume 12-18 months, delaying revenue recognition for new market entrants.
- Sub-tier labor visibility:Documenting supplier labor practices across multi-country sourcing networks demands data architecture investments that exceed mid-tier IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Contract Logistics Market |
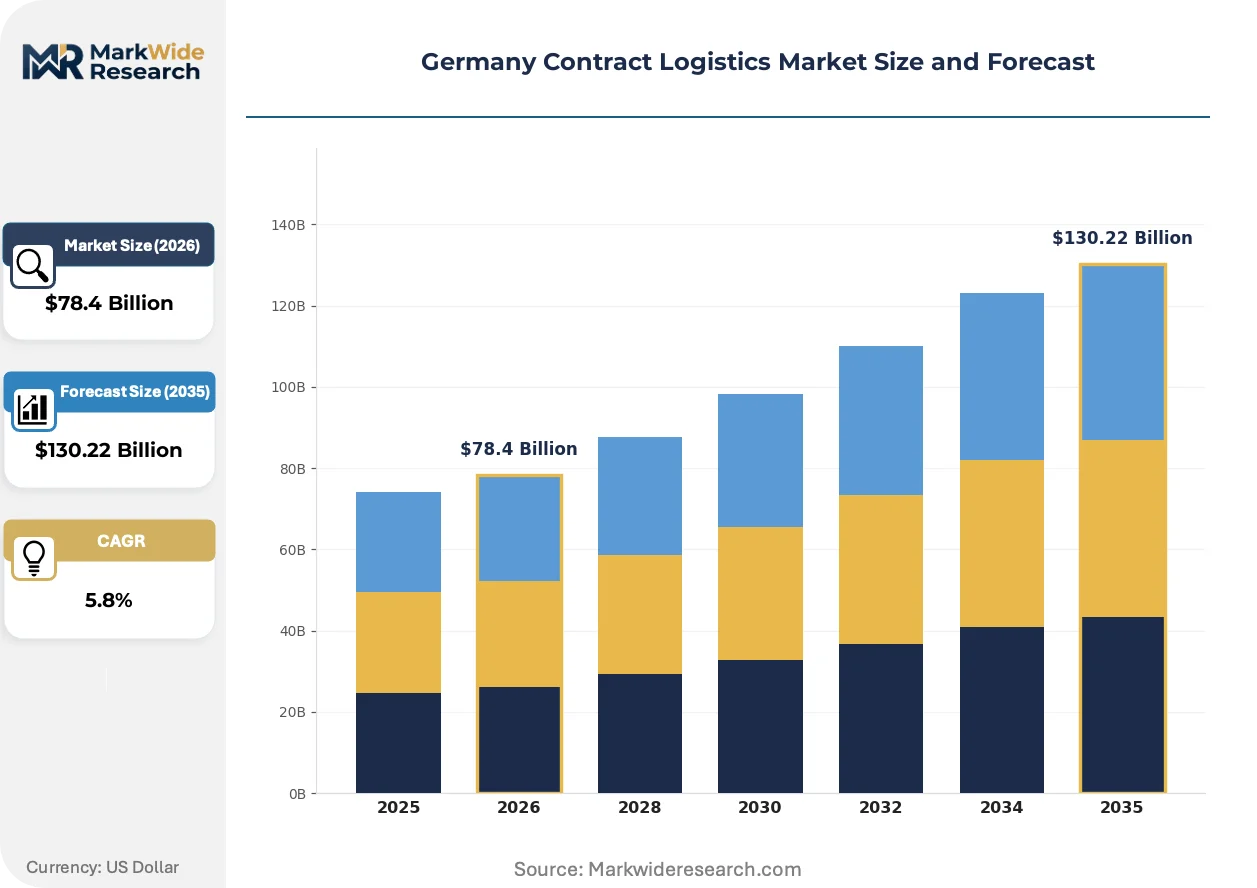
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Warehousing, Transportation, Freight Forwarding, Inventory Management, Supply Chain Consulting, Reverse Logistics Client Type: Manufacturers, E-commerce Companies, Wholesalers, Retail Chains, Automotive OEMs, Electronics Producers Distribution Channel: Direct Store Delivery, Third-party Logistics, Drop Shipping, Cross Docking, Parcel Delivery, Bulk Distribution Technology: Warehouse Management Systems, Transportation Management, Automated Guided Vehicles, RFID Tracking, Blockchain, Cloud-based Platforms |
| Companies Covered | Rhenus Logistics, BLG Logistics Group, DHL Supply Chain & Global Forwarding, GEODIS, CEVA Logistics, Dachser SE, DSV Solutions, Fiege Logistik, Kuehne + Nagel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Contract Logistics Market Shifts & Advancements
Automation architectures and transparency mandates are restructuring competitive advantage around data integration depth rather than physical asset scale alone.
Autonomous mobile robotics is decentralizing warehouse labor allocation by enabling dynamic zone-based picking rather than fixed workstation layouts. Automotive and electronics manufacturers are deploying these systems at pilot scale in Bavaria and Baden-Württemberg facilities. This technology is decentralizing operational control from centralized WMS command structures to edge-computing nodes that optimize routes in real-time.
The EU AI Act's risk-classification framework is constraining automated decision-making in route optimization and predictive maintenance systems. Logistics providers must now maintain human-in-the-loop protocols for high-risk AI applications affecting safety-critical transport operations. German contract logistics operators with cross-border European networks are most affected, requiring legal-technical review of existing algorithmic dispatch systems.
Buyer procurement models are compressing contract durations from traditional five-year frameworks to rolling 24-month agreements with performance-indexed pricing. Automotive OEMs and electronics producers are driving this shift, demanding quarterly KPI reviews and penalty clauses for service-level failures. This pattern is most visible in the Rhine-Ruhr automotive corridor where just-in-sequence delivery requirements dominate vendor selection criteria.
Germany Contract Logistics Market Segmentation
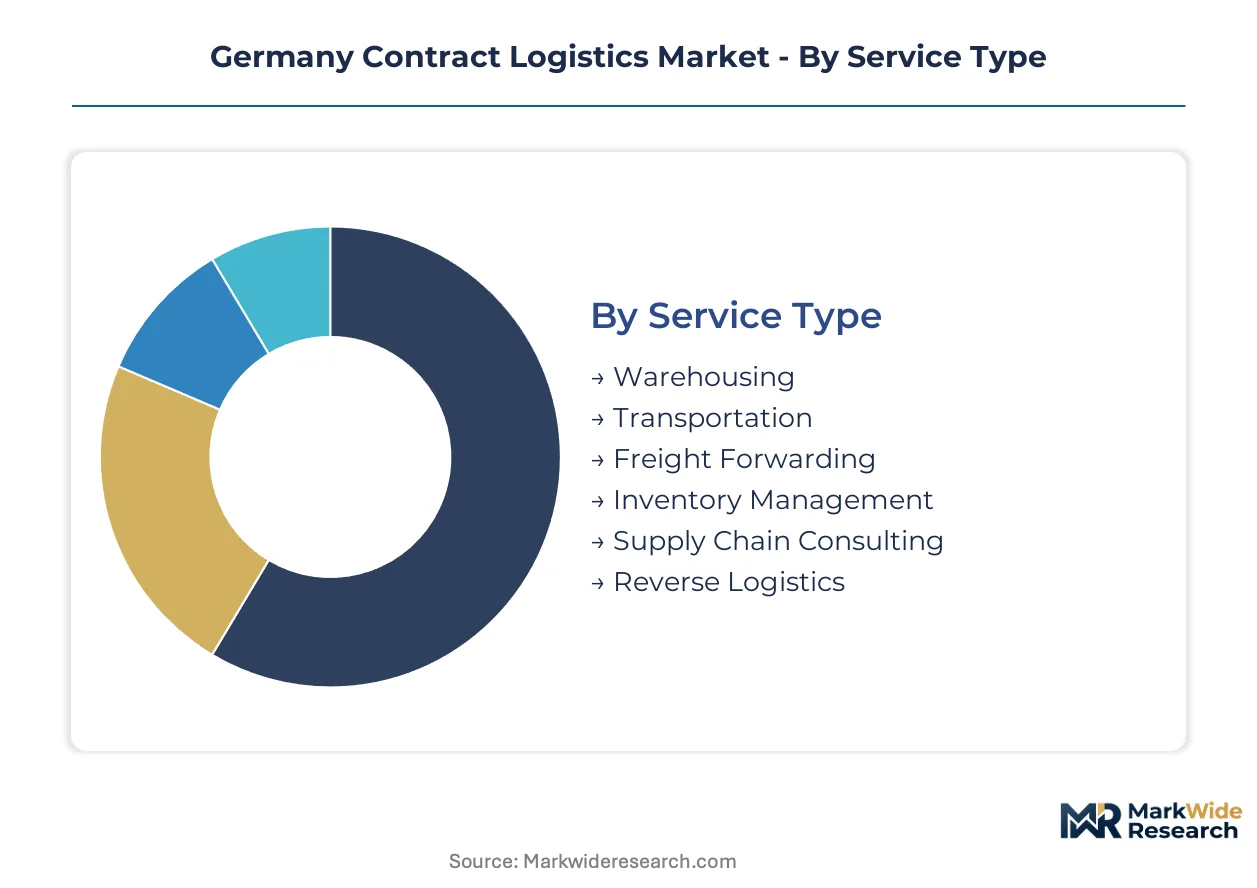
Germany's contract logistics market fragments across operational specializations that determine pricing power and capital intensity. Service mix and technology stack choices separate premium providers from commodity operators in this $78.4 billion market.
Service Type:
The customization-vs-standardization spectrum runs from commoditized transport execution to highly tailored consulting engagements requiring certified expertise.
- Warehousing:Multi-client fulfillment campuses exceeding 10,000 square meters dominate revenue concentration. Baden-Württemberg automotive clusters sustain demand for VDA 6.3-certified facilities with just-in-sequence capabilities.
- Transportation:Road-based fleet operations face KBA emissions compliance timelines that compress payback periods for alternative drivetrain investments. Rhine-Ruhr corridor density creates bottleneck risk during peak automotive production cycles.
- Freight Forwarding:Customs brokerage and bonded warehouse status differentiate mid-tier operators in cross-border European networks.
- Inventory Management:WMS-integrated material handling systems reduce client working capital cycles through real-time visibility.
- Supply Chain Consulting:Circular economy integration and Scope 3 emissions documentation command premium pricing under EU CSRD disclosure rules.
- Reverse Logistics:Electronics producers drive fastest expansion as warranty management and refurbishment networks require specialized handling infrastructure.
Leading the category by volume: Warehousing. Growing fastest: Reverse Logistics.
Client Type:
Cost tier separation is pronounced, with automotive and electronics manufacturers demanding certified quality management while retail and wholesale clients prioritize rate competitiveness.
- Automotive OEMs:Just-in-sequence delivery requirements and customs complexity sustain premium pricing. VDA 6.3 certification audits consume 12-18 months, delaying market entry for new providers.
- Electronics Producers:High-value cargo handling and temperature-controlled segments concentrate in Bavaria manufacturing corridors. Bonded warehouse status is table stakes for vendor selection.
- Manufacturers:Industrial project logistics span heavy machinery and capital equipment with specialized rigging requirements.
- E-commerce Companies:Same-day delivery expectations in Berlin and Hamburg metropolitan zones outpace existing urban micro-fulfillment node capacity.
- Wholesalers:Bulk distribution economics favor scale operators with Rhine-Ruhr network density.
- Retail Chains:Direct store delivery models compress inventory holding costs through frequent, smaller shipment patterns.
Highest margin concentration: Automotive OEMs. Fastest volume expansion: E-commerce Companies.
Distribution Channel:
Geographic application determines channel selection, with urban density favoring parcel networks and industrial corridors enabling bulk consolidation.
- Third-party Logistics:Full-service outsourcing agreements covering warehousing, transport, and value-added services under long-term frameworks. Multi-client campuses amortize fixed costs across rotating demand profiles.
- Cross Docking:Minimal inventory holding with rapid freight consolidation suits automotive just-in-sequence requirements in Baden-Württemberg production zones.
- Direct Store Delivery:Bypassing distribution centers reduces handling costs for temperature-sensitive retail categories.
- Drop Shipping:E-commerce fulfillment without inventory ownership shifts working capital burden to upstream suppliers.
- Parcel Delivery:Last-mile density in Hamburg and Berlin metropolitan areas requires urban micro-fulfillment infrastructure.
- Bulk Distribution:Full-truckload economics dominate Rhine-Ruhr industrial corridor flows.
Dominant by revenue: Third-party Logistics. Steepest expansion trajectory: Cross Docking.
Technology:
Margin structure separates legacy WMS operators from cloud-native platforms with AI-enabled optimization capabilities.
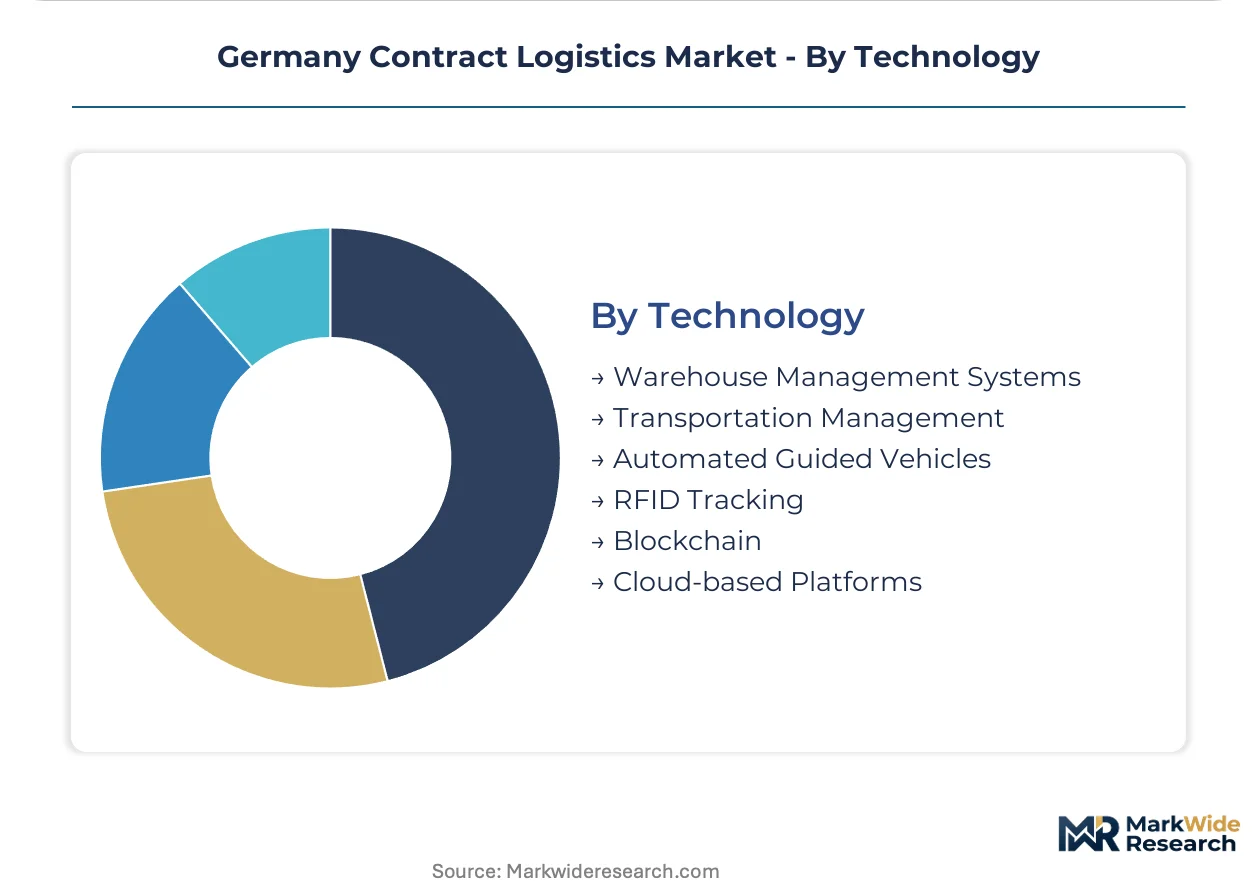
- Warehouse Management Systems:Middleware development costs for ERP synchronization strain mid-tier IT budgets. Legacy system integration consumes 18-24 month implementation timelines.
- Automated Guided Vehicles:Autonomous mobile robotics decentralize picking operations through dynamic zone-based allocation rather than fixed workstation layouts.
- Transportation Management:Route optimization algorithms face EU AI Act risk-classification constraints requiring human-in-the-loop protocols for safety-critical dispatch decisions.
- RFID Tracking:Real-time inventory visibility supports bonded warehouse compliance and customs documentation requirements.
- Cloud-based Platforms:Subscription pricing models reduce upfront capex barriers for mid-tier operators lacking integrated data architectures.
- Blockchain:Sub-tier supplier documentation for Supply Chain Due Diligence Act compliance pilots remain limited to high-value cargo segments.
Widest installed base: Warehouse Management Systems. Gaining share fastest: Automated Guided Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contract logistics demand concentrates in southern industrial corridors where automotive and electronics manufacturing clusters sustain premium fulfillment requirements. The KBA enforces vehicle emissions standards that reshape fleet renewal timelines across road-based operations. Regional differentiation follows manufacturing density rather than population distribution.
Baden-Württemberg
Automotive OEMs and electronics producers drive just-in-sequence delivery requirements across Stuttgart and Karlsruhe production zones. The Supply Chain Due Diligence Act compels providers to document sub-tier supplier practices throughout this corridor. VDA 6.3-certified facilities command pricing premiums as OEMs outsource fulfillment complexity to reduce fixed asset exposure.
Bavaria
High-value cargo and temperature-controlled segments remain underpenetrated despite Munich and Nuremberg manufacturing density. EU CSRD disclosure rules create service tier separation between providers with verified emissions tracking and commodity operators. Electronics producers in this southern zone increasingly demand bonded warehouse status for customs complexity management.
North Rhine-Westphalia
Rhine-Ruhr corridor density creates bottleneck risk during peak automotive production cycles or customs processing surges. DHL Supply Chain anchors multi-client fulfillment campuses across Düsseldorf and Cologne industrial zones. The EU AI Act's risk-classification framework constrains automated decision-making in warehouse robotics deployments throughout this capacity-constrained region.
Berlin-Brandenburg
E-commerce same-day delivery expectations outpace existing urban micro-fulfillment node capacity in metropolitan Berlin. Fiege Logistik positions last-mile infrastructure to serve accelerating service-level demands from digital retailers. KBA emissions compliance timelines compress payback periods for alternative drivetrain investments in last-mile fleet operations.
Hamburg
Port-centric logistics and northern distribution networks concentrate in this maritime gateway city. Customs brokerage capabilities and bonded warehouse status differentiate mid-tier operators serving Scandinavian and Baltic trade flows. EU Green Deal fleet incentives accelerate electric vehicle adoption in port drayage and metropolitan delivery operations.
Germany Contract Logistics Market Competitive Landscape
Capacity expansion dominates the current landscape as providers build multi-client fulfillment campuses to amortize fixed costs across rotating demand profiles. The vendor base organizes around three tiers: pan-European network operators with integrated ESG data architectures, regional specialists occupying defensible niches in temperature-controlled or high-value cargo, and mid-tier operators facing compliance barriers from the Supply Chain Due Diligence Act. Strategic archetypes include scale-driven campus developers, certification-heavy automotive specialists, and urban last-mile infrastructure builders. M&A activity and strategic partnerships concentrate among operators seeking to bridge ESG data gaps.
Within the pan-European network tier, DHL Supply Chain & Global Forwarding and GEODIS exemplify scale-driven operators leveraging cross-border density. Dachser SE occupies a position among European groupage specialists with defensible positioning in temperature-controlled segments. Fiege Logistik represents the e-commerce fulfillment archetype with dedicated infrastructure for same-delivery demand. These three anchors illustrate how competitive advantage increasingly derives from data integration depth and compliance infrastructure rather than physical asset scale alone.
| Leading Market Players |
|---|
| Rhenus Logistics |
| BLG Logistics Group |
| DHL Supply Chain & Global Forwarding |
| GEODIS |
| CEVA Logistics |
| Dachser SE |
| DSV Solutions |
| Fiege Logistik |
| Kuehne + Nagel |
| Others |
Supply & Pricing Matrix
EU CSRD disclosure rules gate qualified supply access and premium-tier pricing power for logistics providers lacking verified emissions tracking and circular economy integration capabilities. Mid-tier operators face exclusion from automotive OEM procurement lists as buyers demand documented Scope 3 transparency and sub-tier labor visibility.
Pricing Analysis
Volume concentrates in commoditized warehousing and transportation execution while margins accrue to supply chain consulting and reverse logistics. Three-tier pricing structure across premium, standard, and economy levels separates VDA 6.3-certified automotive specialists from bonded warehouse operators and generic transport providers. Cost compression in standard-tier road freight is intensifying because KBA emissions compliance timelines accelerate fleet renewal cycles. E-commerce companies exhibit highest price sensitivity due to thin delivery margins, while automotive OEMs accept premium rates for just-in-sequence certification.
Supply Chain Analysis
Single-source vulnerability sits with Chinese manufacturers of warehouse automation components and South Korean producers of lithium-ion battery systems for electric fleet vehicles. German contract logistics operations draw from steel and aluminum inputs subject to commodity volatility, alongside specialized WMS software licenses and autonomous mobile robotics hardware. Tariff exposure on Chinese automation equipment creates procurement risk for mid-tier operators expanding material handling capacity. Distribution runs through Rhine-Ruhr multi-client fulfillment campuses serving pan-European automotive networks, with last-mile nodes concentrated in Berlin and Hamburg metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as the Supply Chain Due Diligence Act forces weaker mid-tier operators lacking integrated ESG data architectures to exit or sell.
For Market Incumbents: To counter margin compression from compliance infrastructure investments, DHL Supply Chain and GEODIS should accelerate multi-client campus development across underpenetrated Bavaria corridors while acquiring mid-tier operators with bonded warehouse status to fill ESG data gaps. Certification investment in VDA 6.3 quality management systems defends automotive OEM relationships against European groupage specialists. For New Entrants and Emerging Players: Enter via temperature-controlled high-value cargo segments in Bavaria's Munich-Nuremberg manufacturing zone, where electronics producers demand bonded warehouse capabilities that incumbent pan-European networks underserve. Same-day delivery infrastructure in Berlin-Brandenburg offers white-space expansion as urban micro-fulfillment node capacity lags e-commerce service-level expectations. A specialized go-to-market angle targeting EU Green Deal fleet incentives for electric last-mile vehicle deployment compresses payback periods against established diesel operators. For Investors and Strategic Acquirers: Accelerating M&A activity among operators seeking ESG data architecture bridges is the leading indicator that consolidation value will accrue to platforms with integrated compliance infrastructure. Five-to-ten year viability favors pan-European network operators with verified emissions tracking over regional specialists lacking cross-border density. Acquisition targets should display defensible positioning in automotive certification or temperature-controlled segments alongside cloud-native WMS platforms. The signal to monitor is KBA enforcement actions against non-compliant fleet operators, which will trigger distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Client Campus Expansion | DHL Supply Chain amortizes fixed costs across rotating automotive demand profiles in Rhine-Ruhr corridors. |
| Backward Integration into WMS Platforms | Cloud-native software acquisitions reduce middleware development costs for ERP synchronization projects. |
| Alternative Drivetrain Fleet Transition | EU Green Deal subsidies compress payback periods for electric and hydrogen-powered last-mile vehicle investments. |
| VDA 6.3 Certification Investment | Quality management audits defend automotive OEM relationships against European groupage competitors. |
| Urban Micro-Fulfillment Node Buildout | Fiege Logistik positions last-mile infrastructure to serve same-day delivery demand in Berlin metropolitan zones. |
Research Methodology
Document review covered KBA emissions enforcement records, EU CSRD disclosure guidance, and customs trade data for warehouse automation equipment, complemented by interviews with contract logistics operations directors, automotive OEM procurement managers, and bonded warehouse compliance officers. Secondary validation drew from SEC filings of publicly traded logistics operators, German Supply Chain Due Diligence Act implementation reports, and VDA quality management audit databases. Bottom-up facility capacity assessments triangulated against top-down market sizing from pan-European network revenue disclosures.
Cross-referencing historical capacity expansion patterns against expert panel input on automotive outsourcing timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service type specialization, client industry vertical, certification tier, and regional manufacturing corridor density. CAGRs were derived from facility utilization rates and contract renewal pricing trends. Forecast inputs incorporated KBA fleet compliance timelines and EU AI Act risk-classification implementation for automated warehouse systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal subsidy withdrawal or extended VDA 6.3 certification backlogs. Automotive production cycle volatility and customs processing surge events in Rhine-Ruhr corridors could revise capacity utilization assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Automotive Logistics Market
Logistics and Shipping
Netherlands Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
South Africa Third-Party Logistics (3PL) Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Germany Same Day Delivery Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
Mexico 3PL Market
Logistics and Shipping
United States Chartered Air Freight Transport Market
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Japan Cross-Border E-Commerce Logistics Market
Logistics and Shipping
Multicarrier Shipping Software Market