
 Straddle Carrier Market | 2026-2036
Straddle Carrier Market Size, Share, and Industry Trends Forecast 2026-2036
Straddle Carrier Market Analysis
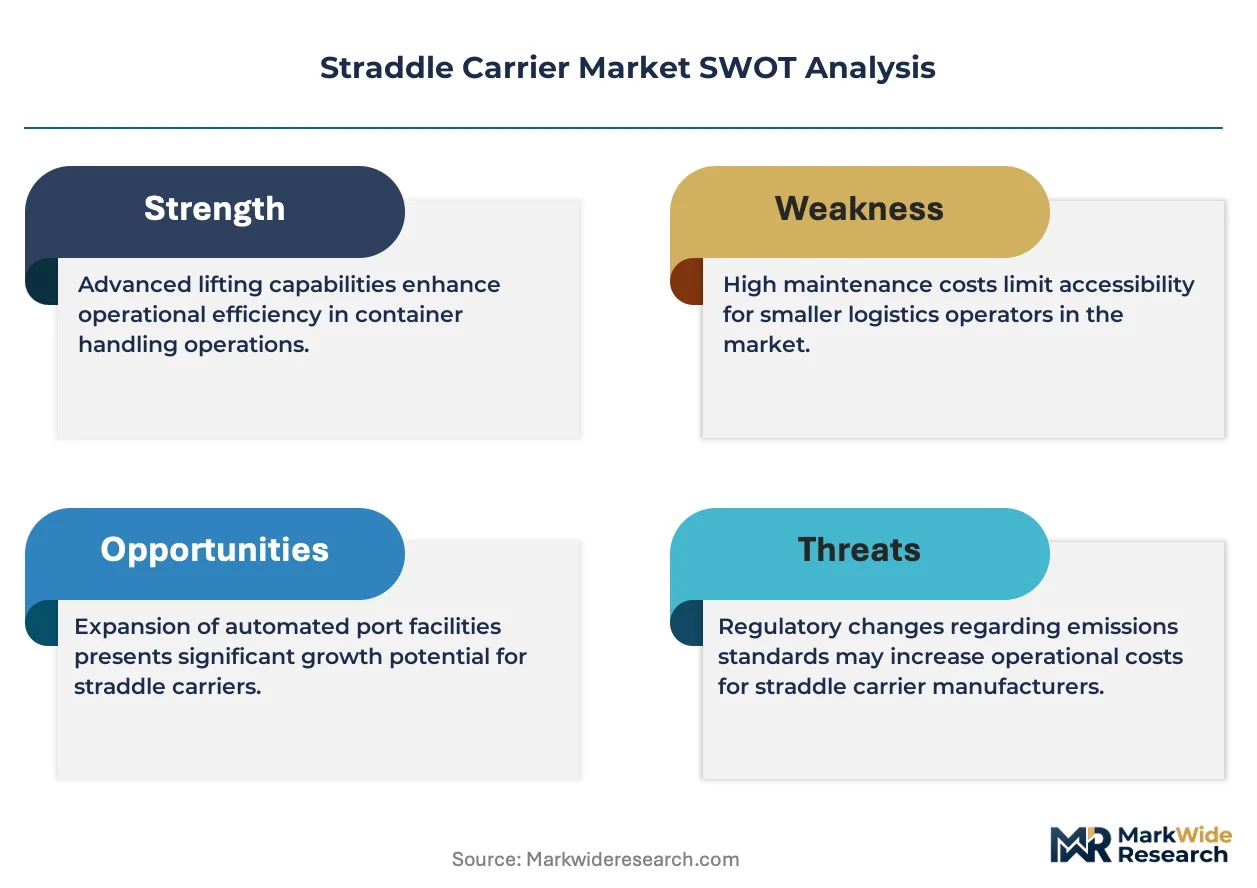
Aftermarket service revenue is reconfiguring margin pools away from pure equipment sales across the straddle carrier supply chain. Kalmar Corporation leverages its automation technology leadership to capture recurring software and maintenance contracts. Liebherr-International AG anchors its position through vertical integration into crane and port machinery ecosystems. Konecranes Oyj differentiates via telemetry-enabled fleet management platforms that extend customer lifetime value.
A straddle carrier is a rubber-tired gantry crane that spans its load, lifting containers by their corner castings for stacking and transport within terminal yards. Units typically span 1-over-3 or 1-over-4 container stacks and operate at lifting capacities exceeding 50 tonnes to maximize yard density. Electric straddle carriers now lead product type demand as port operators confront emission compliance costs and energy price volatility. Container terminals dominate application demand, while automation technology represents the fastest-expanding segment as remote-controlled and autonomous navigation systems reduce labor dependency and improve stacking precision.
EU F-Gas Regulation and REACH compliance reshape equipment specifications for European port operators, while EPA emission standards and OSHA workplace safety rules govern North American fleet procurement. China's GB standards and MEE environmental directives enforce domestic manufacturing conformity for electric drivetrains and battery systems. Stakeholders must monitor regulatory divergence between jurisdictions when configuring global product platforms and service architectures.
Market Dynamics
Container terminal operators are reconfiguring yard operations around automation density and emission compliance costs, forcing equipment procurement toward electric drivetrains and remote-control architectures that compress labor requirements while expanding stacking precision.
Growth Catalysts
- EU F-Gas Regulation:European port operators face mandatory phase-down of hydrofluorocarbon-based systems, accelerating fleet replacement with electric straddle carriers using battery thermal management.
- Container terminal densification:Major hubs in Germany, China, and the United States are expanding 1-over-4 stacking configurations to maximize land productivity against real estate constraints.
- Autonomous navigation systems:Lidar and machine-vision integration enables unmanned operation in controlled yard environments, reducing shift labor costs and collision incidents.
Market Restraints
- Lithium-ion battery supply concentration:Cell production for heavy-duty port equipment clusters in East Asian manufacturing bases, exposing European and North American operators to freight cost volatility and geopolitical supply risk.
- Specialized technician scarcity:Electrified straddle carriers require certified high-voltage maintenance skills that existing diesel-mechanic workforces lack, extending downtime windows and service contract premiums.
- Concrete infrastructure retrofit costs:Electric charging infrastructure demands reinforced grid connections and dedicated yard positioning that legacy terminals built for diesel refueling cannot accommodate without seven-figure civil works.
Strategic Opportunities
- India port modernization:Jawaharlal Nehru Port Trust and Mundra Port are expanding container throughput capacity under Sagarmala infrastructure programs, creating first-mover positioning for electrified equipment suppliers.
- Telematics-enabled predictive maintenance:Fleet management platforms that aggregate sensor data from spreader locks, drive motors, and battery thermal systems create recurring software revenue streams alongside hardware sales.
- Hybrid retrofit kits:Diesel-electric conversion architectures allow terminal operators to extend existing fleet service life while meeting interim emission targets before full battery-electric procurement.
Industry Challenges
- Multi-vendor automation integration:Terminal operating systems from different suppliers use incompatible data protocols, forcing custom middleware development that delays autonomous deployment timelines.
- Certification timeline compression:Functional safety validation under ISO 13849 and IEC 61508 for unmanned operation requires extensive field testing that conflicts with port operators' uptime guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Straddle Carrier Market |
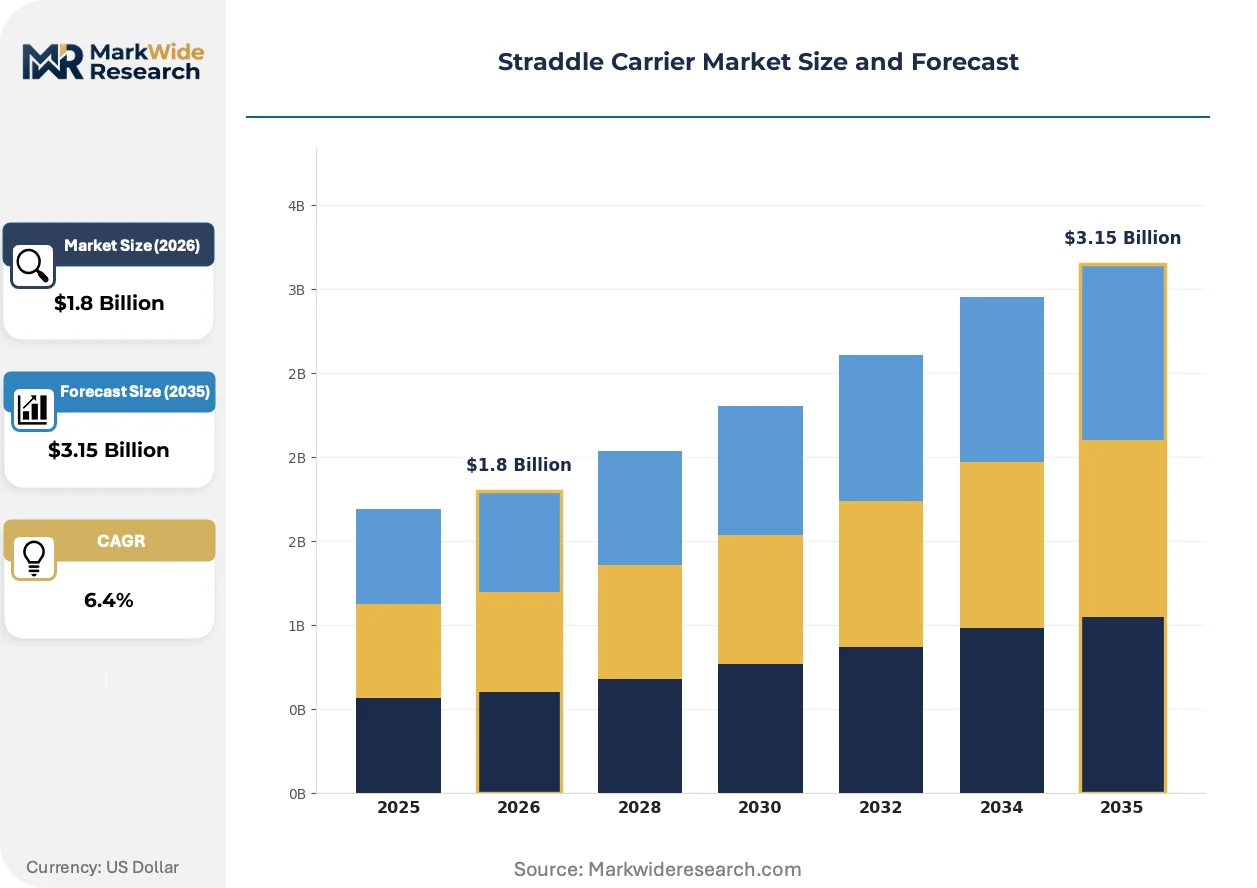
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Diesel, Hybrid, Manual Application: Container Terminals, Shipyards, Logistics Parks, Intermodal Facilities End User: Shipping Companies, Freight Forwarders, Warehousing Providers, Port Operators Technology: Automation, Telemetry, Navigation Systems, Remote Control |
| Companies Covered | Gerlinger Carrier, Shanghai Zhenhua Heavy Industries Company Limited, Kalmar Corporation, Huada Heavy Industry, Cimolai S.p.A., Konecranes Oyj, Liebherr-International AG, Mobicon Systems, Combilift, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Straddle Carrier Market Emerging Trajectories
Digital twin architectures and real-time sensor fusion are compressing the gap between physical yard operations and software-defined optimization, enabling dynamic container positioning that responds to vessel arrival patterns rather than static stacking rules.
Machine-vision-based container damage detection is digitizing quality assurance workflows that previously required manual inspector walk-arounds. Major terminals in Rotterdam and Shanghai are deploying camera arrays on spreader frames to capture top and side wall conditions during every lift cycle. This data stream feeds directly into shipping line liability systems, compressing dispute resolution timelines from weeks to hours.
China's GB standards for battery safety and electromagnetic compatibility are tightening certification requirements for imported electric port equipment. Domestic manufacturers under MIIT oversight gain accelerated type-approval pathways, while foreign suppliers face extended testing protocols at NMPA-recognized laboratories. European OEMs are responding by establishing joint-venture assembly operations within Shanghai and Ningbo free-trade zones.
Terminal operators are unbundling equipment procurement from long-term maintenance contracts, compressing supplier revenue recognition toward discrete hardware sales with separately negotiated service tiers. This pattern is most visible in German and Dutch ports where procurement departments now mandate three-bid separation for capital expenditure and operating expenditure line items, forcing OEMs to restructure sales organizations around distinct P&L accountability.
Straddle Carrier Market Segmentation
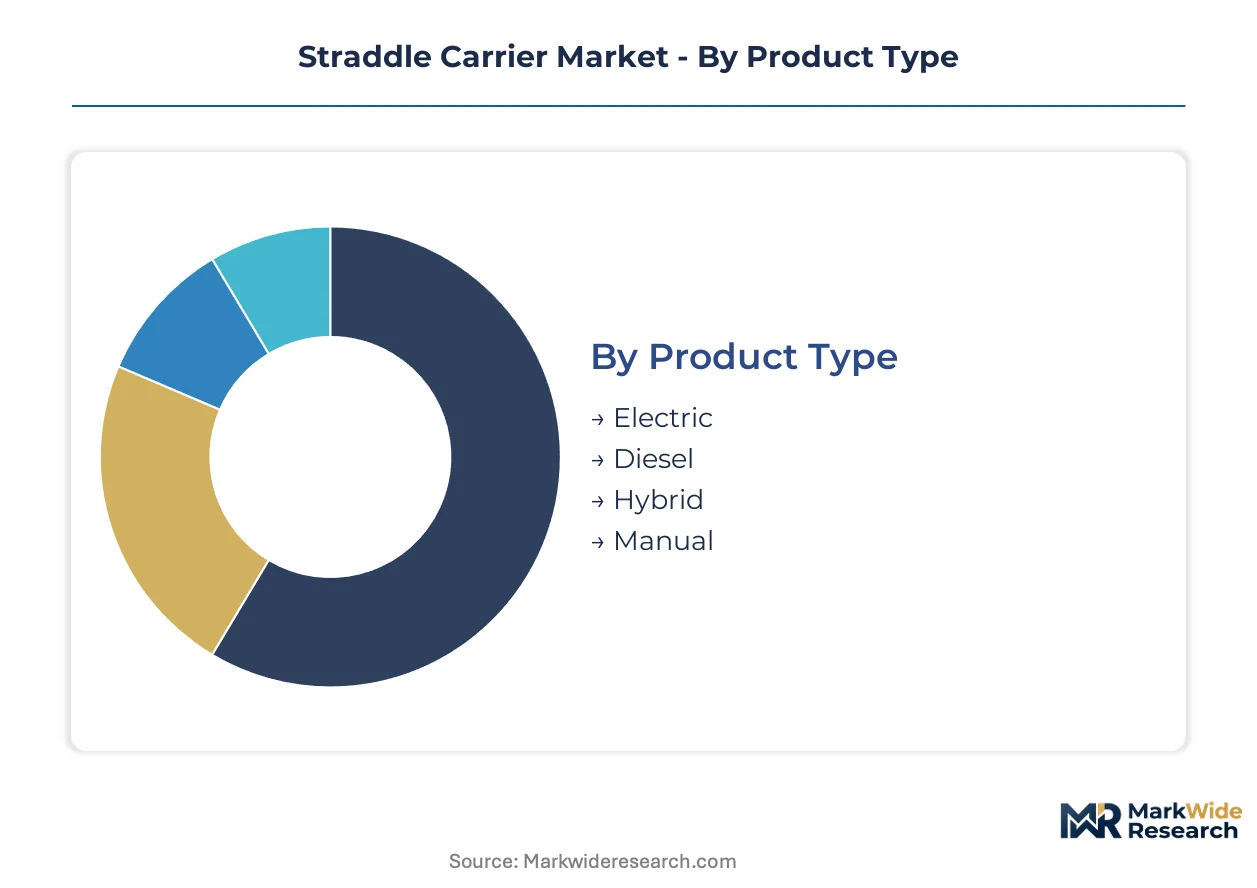
Segmentation in the straddle carrier market determines service contract structures and spare parts forecasting precision. Fleet operators configure procurement around duty cycles, emission zones, and automation readiness rather than lift capacity alone.
Product Type:
After-sales-service intensity varies sharply across powertrain architectures, with battery-electric units demanding thermal management expertise and high-voltage safety protocols that diesel platforms never required.
- Electric:Battery-powered drivetrains with regenerative braking and onboard thermal management dominate new orders from European terminals facing F-Gas Regulation compliance deadlines. German port operators in Hamburg and Bremerhaven are consolidating procurement around 800-volt architectures to minimize charging dwell time.
- Diesel:Conventional internal combustion units with Tier 4/Stage V emission controls retain residual demand in markets with unreliable grid infrastructure. African and Southeast Asian terminals prioritize diesel for operational continuity where shore power remains intermittent.
- Hybrid:Diesel-electric parallel systems enable emission reduction without full charging infrastructure commitment. Operators in transitional regulatory environments use hybrid configurations as bridge technology toward eventual full electrification.
- Manual:Operator-controlled units without automation interfaces serve low-throughput facilities with irregular container flows. Small-scale logistics parks in secondary Chinese ports deploy manual carriers where labor costs offset automation capital expenditure.
Electric holds the largest share; momentum sits with hybrid as interim compliance solutions.
Application:
Application context dictates stacking height requirements and automation density, with container terminals commanding premium equipment specifications that smaller facilities cannot amortize.
- Container Terminals:High-throughput facilities with 1-over-4 stacking configurations and 24/7 operations demand equipment with autonomous navigation readiness and predictive maintenance telemetry. Rotterdam and Shanghai terminals are retrofitting yard blocks for fully unmanned electric carrier operations.
- Shipyards:Vessel construction and repair facilities use straddle carriers for block handling and outfitting logistics rather than container stacking. Korean shipbuilders at Hyundai Heavy Industries Ulsan complex deploy modified carriers with spreader adaptations for hull section transport.
- Logistics Parks:Inland distribution centers with lower container velocity prioritize flexibility over density. Operators in the Dallas-Fort Worth metroplex use carriers for cross-dock consolidation where rail and truck modes intersect.
- Intermodal Facilities:Rail-truck transfer terminals require rapid repositioning capability across multiple track alignments. BNSF Logistics Park Chicago and UP Joliet Intermodal Terminal configure fleets for dual-cycle productivity metrics.
Container Terminals generate the highest equipment revenue per slot; intermodal facilities are expanding most quickly as inland port concepts proliferate.
End User:
End-user category determines financing structures and fleet management sophistication, with shipping lines favoring lease arrangements while port authorities capitalize equipment directly.
- Shipping Companies:Container lines including Maersk and MSC operate dedicated terminal subsidiaries with standardized fleet specifications. These users prioritize interoperability across multiple port concessions and centralized maintenance contracts.
- Freight Forwarders:Third-party logistics providers deploy carriers at contract logistics facilities where cargo ownership remains with beneficial cargo owners. Forwarders emphasize equipment utilization metrics and flexible lease terms.
- Warehousing Providers:Real estate investment trusts and industrial developers integrate carriers into build-to-suit distribution centers. Prologis and GLP facilities near Shanghai Yangshan and Los Angeles-Long Beach deploy carriers as tenant amenities.
- Port Operators:Public and quasi-public terminal authorities with concession agreements spanning 20-30 years amortize equipment over extended depreciation schedules. PSA International and DP World configure fleets for concession renewal competitiveness.
Port Operators command the installed base; shipping companies are driving standardization fastest through fleet harmonization mandates.
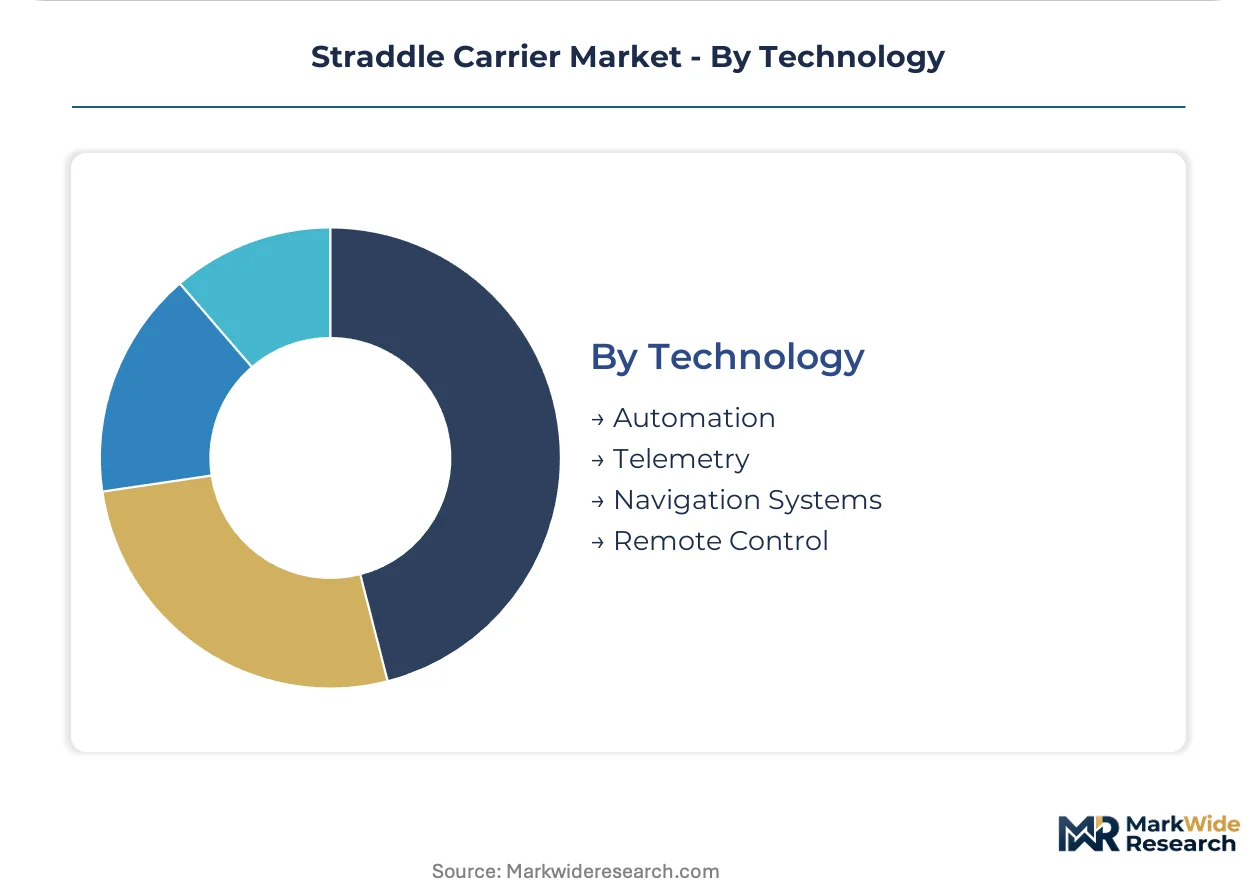
Technology:
Technology segmentation separates hardware revenue from recurring software and service streams, with automation platforms commanding margins that mechanical equipment cannot match.
- Automation:Autonomous navigation systems using lidar, radar, and machine vision enable unmanned operation within geofenced yard blocks. APM Terminals Maasvlakte II and Qingdao Qianwan Container Terminal operate fully autonomous electric carrier fleets with remote monitoring centers.
- Telemetry:Sensor networks transmitting spreader load, motor temperature, and battery state-of-charge enable predictive maintenance algorithms. Kalmar's Kalmar Insight and Konecranes' TRUCONNECT platforms aggregate fleet data for availability optimization.
- Navigation Systems:Differential GPS and inertial measurement units provide positioning accuracy for automated stacking in high-density configurations. Sub-decimeter precision enables 1-over-5 stacking trials at select Rotterdam terminals.
- Remote Control:Operator-assist or full teleoperation architectures transition labor from cab to control room, reducing shift fatigue and collision exposure. Remote control serves as intermediate step toward full autonomy in mixed-traffic yards.
Automation captures premium pricing; telemetry is penetrating fastest as retrofit option for existing fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts, with emerging-market terminals prioritizing diesel continuity while German and Chinese operators absorb premium electric pricing to secure emission compliance and automation readiness.
Germany
Terminal operators in Hamburg and Bremerhaven are consolidating 800-volt electric fleet orders ahead of EU F-Gas Regulation phase-down deadlines. The country's national environmental regulator enforces Stage V emission controls that render new diesel procurement uneconomical for major hubs. Equipment concentration centers on the Elbe River corridor, where HHLA and Eurogate facilities are retrofitting yard blocks for autonomous electric carrier operations.
China
Shanghai Yangshan and Ningbo Zhoushan terminals are expanding 1-over-4 stacking density to maximize throughput per hectare as transshipment volumes surge. MIIT oversight of GB standards for battery safety and electromagnetic compatibility accelerates domestic manufacturer certification timelines. Yangtze River Delta port clusters dominate procurement volume, with Qingdao Qianwan Container Terminal already operating fully autonomous electric fleets.
United States
Los Angeles-Long Beach and Savannah port authorities are balancing electrification mandates against grid reliability constraints at intermodal transfer facilities. EPA emission standards and OSHA workplace safety rules govern fleet procurement specifications for drayage-adjacent operations. Gulf Coast terminals in Houston and Mobile are prioritizing hybrid configurations as bridge technology toward eventual full electrification.
India
Jawaharlal Nehru Port Trust and Mundra Port are expanding container handling capacity under Sagarmala infrastructure programs with first-mover electrification trials. The country's national shipping regulator and port authority frameworks incentivize green equipment procurement through concession term extensions. West Coast port clusters around Mumbai and Gujarat are attracting supplier joint ventures for localized assembly and service infrastructure.
Netherlands
Rotterdam terminal operators are piloting 1-over-5 stacking configurations with sub-decimeter positioning precision from differential GPS and inertial measurement units. EU F-Gas Regulation compliance costs and REACH chemical safety protocols reshape equipment specifications for European-facing procurement. Maasvlakte II facilities at APM Terminals operate fully autonomous electric carrier fleets with remote monitoring centers serving as automation reference architecture.
Straddle Carrier Market Vendor Landscape
Full-line port equipment manufacturers and specialized straddle carrier fabricators split the market along automation capability and service integration depth. Consolidation pressure favors players with captive software development and predictive maintenance platforms. Three archetypes dominate: European automation-technology leaders with telemetry-enabled fleet management systems, Chinese heavy-industry conglomerates with integrated steel and port machinery supply chains, and regional specialists serving low-volume terminals with manual configurations. Competitive moves center on strategic partnerships for battery supply security and geographic expansion through joint-venture assembly operations in major demand clusters.
Among European automation-technology leaders, Kalmar Corporation and Konecranes Oyj exemplify the platform-archetype strategy, anchoring positions through recurring software and telemetry revenue streams rather than discrete hardware sales. Liebherr-International AG occupies a position within the diversified heavy-machinery tier, leveraging in-house production of crane and port equipment ecosystems. Shanghai Zhenhua Heavy Industries Company Limited represents the integrated Chinese heavy-industry archetype, with Zhengzhou-based fabricators and other domestic suppliers capturing volume in price-sensitive procurement contexts.
| Leading Market Players |
|---|
| Gerlinger Carrier |
| Shanghai Zhenhua Heavy Industries Company Limited |
| Kalmar Corporation |
| Huada Heavy Industry |
| Cimolai S.p.A. |
| Konecranes Oyj |
| Liebherr-International AG |
| Mobicon Systems |
| Combilift |
| Others |
Supply Flow & Price Mechanics
Lithium-ion battery supply concentration in East Asian manufacturing bases creates tariff exposure and freight cost volatility that compresses margin spreads between premium electric configurations and economy diesel alternatives while forcing terminal operators toward long-term service contracts that lock in aftermarket revenue streams.
Pricing Analysis
Aftermarket service contracts now generate the dominant lifetime value for OEMs, with predictive maintenance subscriptions and telemetry-enabled fleet management platforms commanding recurring revenue that hardware sales alone cannot match. Three-tier pricing structure across premium automation-ready, standard electric, and economy diesel levels reflects certification grade for EU F-Gas Regulation compliance and automation interface compatibility. Cost compression in the mid-tier electric segment is intensifying because domestic Chinese manufacturers under MIIT oversight gain accelerated type-approval pathways that foreign suppliers cannot match. Small-scale logistics parks in secondary Chinese ports exhibit the highest price sensitivity, while Rotterdam and Shanghai terminal operators absorbing premium automation pricing show the least.
Supply Chain Analysis
Contract manufacturing for straddle carrier assembly concentrates in Zhengzhou-based fabricators and Shanghai free-trade zone joint ventures that European OEMs have established to circumvent extended testing protocols at NMPA-recognized laboratories. Geographic supply concentration centers on China for battery cell production, Germany for precision drive systems and automation software, and South Korea for high-voltage power electronics. Raw material dependencies span lithium carbonate for thermal management systems, high-grade steel for chassis fabrication, and rare earth elements for permanent magnet motors. Single-source vulnerability in battery cell supply exposes European and North American operators to geopolitical disruption. Distribution runs through port authority procurement departments that now mandate three-bid separation for capital and operating expenditure line items.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated guided vehicles and autonomous yard tractors present a substitution threat that incumbent straddle carrier manufacturers must navigate through software-defined service architectures that AGV suppliers cannot easily replicate.
For Market Incumbents: Build switching-cost moats through telemetry-enabled predictive maintenance platforms that aggregate sensor data from spreader locks, drive motors, and battery thermal systems into proprietary fleet optimization algorithms. Kalmar Corporation and Konecranes Oyj exemplify this defensive positioning. Expand captive supply of high-voltage power electronics through backward integration into South Korean component partnerships to reduce battery supply risk. Counter emerging Chinese heavy-industry conglomerates by embedding automation software deeper into terminal operating system middleware.
For New Entrants and Emerging Players: Establish a beachhead in Indian port modernization programs at Jawaharlal Nehru Port Trust and Mundra Port where Sagarmala infrastructure incentives create first-mover electrification trials with less entrenched incumbent relationships. Target hybrid retrofit kits for diesel-electric conversion as the most penetrable segment, serving Gulf Coast terminals in Houston and Mobile that prioritize bridge technology toward eventual full electrification. Pursue joint-venture assembly operations within Shanghai and Ningbo free-trade zones to accelerate GB standards certification timelines.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down deadlines reshape the acquisition landscape toward electric drivetrain capability and battery thermal management expertise as premium valuation anchors. Long-term viability favors platform-archetype players with recurring software revenue streams over pure equipment fabricators. Target acquisition archetypes include telemetry-enabled fleet management specialists and high-voltage maintenance service providers. Monitor certification timeline compression under ISO 13849 and IEC 61508 as the signal for autonomous deployment inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Secures cell production capacity from East Asian manufacturing bases against freight volatility and tariff exposure. |
| Telemetry Platform Launch | Kalmar Insight and TRUCONNECT equivalents create recurring software revenue that extends customer lifetime value. |
| Joint Venture Assembly Operations | Shanghai and Ningbo free-trade zone facilities accelerate GB standards compliance for Chinese terminal procurement. |
| Hybrid Retrofit Kit Development | Diesel-electric conversion architectures capture interim emission compliance demand from transitional regulatory environments. |
| Autonomous Navigation Certification | Functional safety validation under ISO 13849 enables unmanned operation in geofenced yard blocks at Rotterdam and Qingdao. |
Methodological Framework
Desk research of customs and trade data, SEC filings from listed port equipment manufacturers, and terminal operator concession agreements preceded structured interviews with maintenance directors at European container terminals, procurement leads at Asian port authorities, aftermarket service heads at OEMs, and plant engineers at Korean shipbuilding complexes. Bottom-up triangulation of fleet order data from Hamburg, Bremerhaven, Shanghai, and Los Angeles-Long Beach was cross-validated against top-down market sizing from equipment revenue disclosures.
Assumptions around EU F-Gas Regulation compliance timelines, battery cost curves, and automation adoption rates were held fixed across baseline scenarios while tariff exposure and grid reliability constraints were varied for sensitivity testing. Segmentation dimensions modeled include powertrain architecture, application context, end-user financing structure, and automation technology tier. CAGRs were derived from equipment order backlogs and concession renewal schedules rather than macroeconomic extrapolation. Industry-specific forecast inputs span lithium-ion cell production capacity announcements and terminal densification investment pipelines.
Stress conditions across battery supply disruption, regulatory deadline acceleration, and autonomous navigation certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and could revise materially if MIIT accelerates domestic manufacturer preference or if OSHA mandates reshape North American workplace safety specifications. Quarterly review of equipment order backlogs, concession award announcements, and battery cell production capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Event Logistics Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Europe Contract Logistics Market
Logistics and Shipping
Nigeria Third-Party Logistics (3PL) Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Water Hauling Services Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Iraq Logistics Market
Logistics and Shipping
France Last Mile Delivery Market
Logistics and Shipping
Asia Pacific Automotive Logistics Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
Peru Cold Chain Logistics Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market