
 Middle East and Africa Advanced Wound Care Market | 2026-2036
Middle East and Africa Advanced Wound Care Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Advanced Wound Care Market Foresight
Home healthcare agencies are reorganizing their supply chains to prioritize advanced wound care products over traditional gauze and saline solutions. Smith & Nephew dominates the hydrocolloid and foam dressing categories across Gulf Cooperation Council markets. Mölnlycke Health Care AB leverages its barrier technology portfolio to sustain premium positioning in South African private hospital networks. Coloplast Corporation specializes in stoma and wound care convergence, anchoring its regional headquarters in Dubai for distribution across the Middle East.
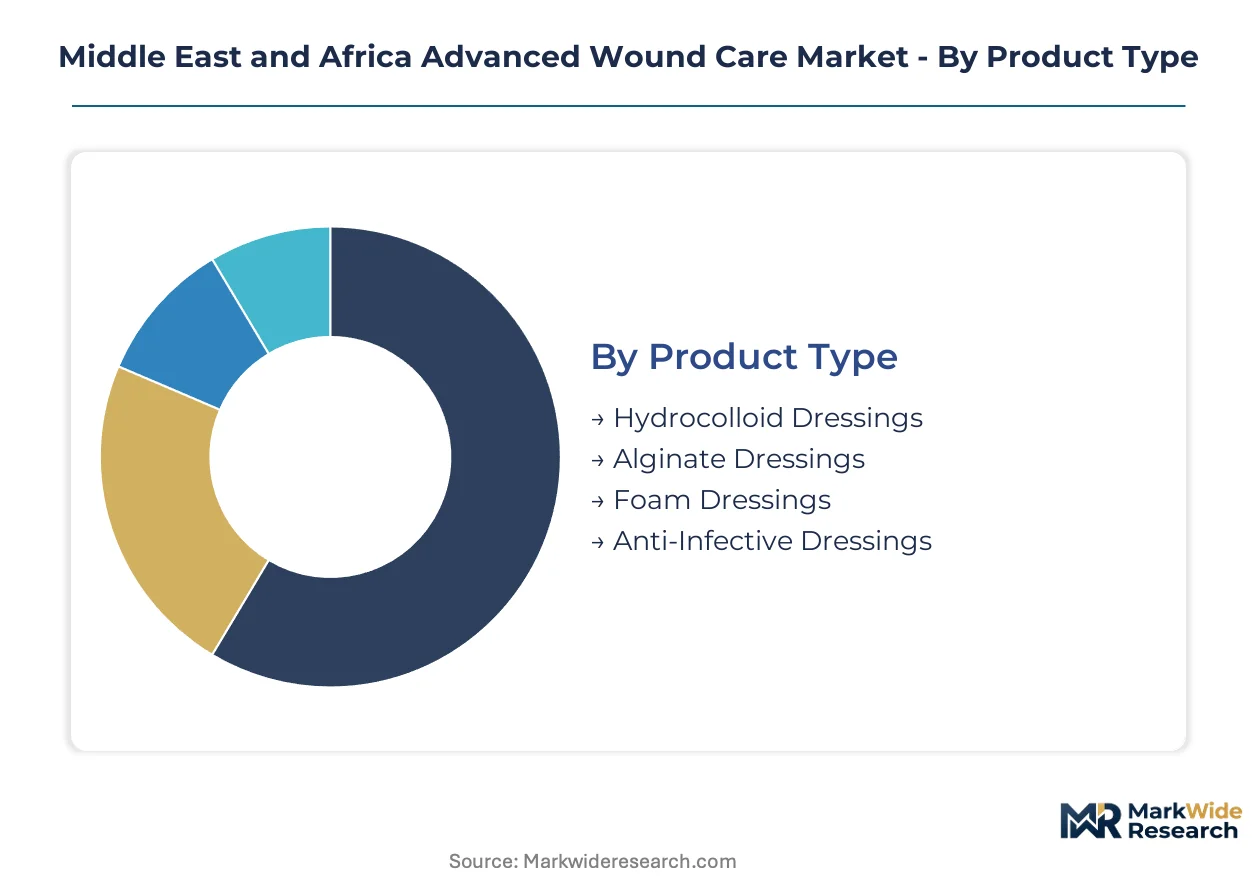
Advanced wound care encompasses therapeutic products engineered to maintain moist wound environments, facilitate autolytic debridement, and accelerate re-epithelialization through materials such as hydrocolloid polymers, calcium alginate fibers, and electrospun nanofiber matrices with pore sizes below 500 nanometers. These products serve primarily to reduce healing time for chronic wounds and minimize infection risk in post-surgical and diabetic patient populations. Foam dressings occupy the largest revenue share among product types due to their versatility across exuding wound categories, while nanofiber technology represents the fastest-expanding technology segment as manufacturers invest in electrospinning capacity for superior moisture vapor transmission rates. Burn treatment applications command elevated margins relative to pressure ulcer management, reflecting the complexity of eschar management and graft fixation requirements.
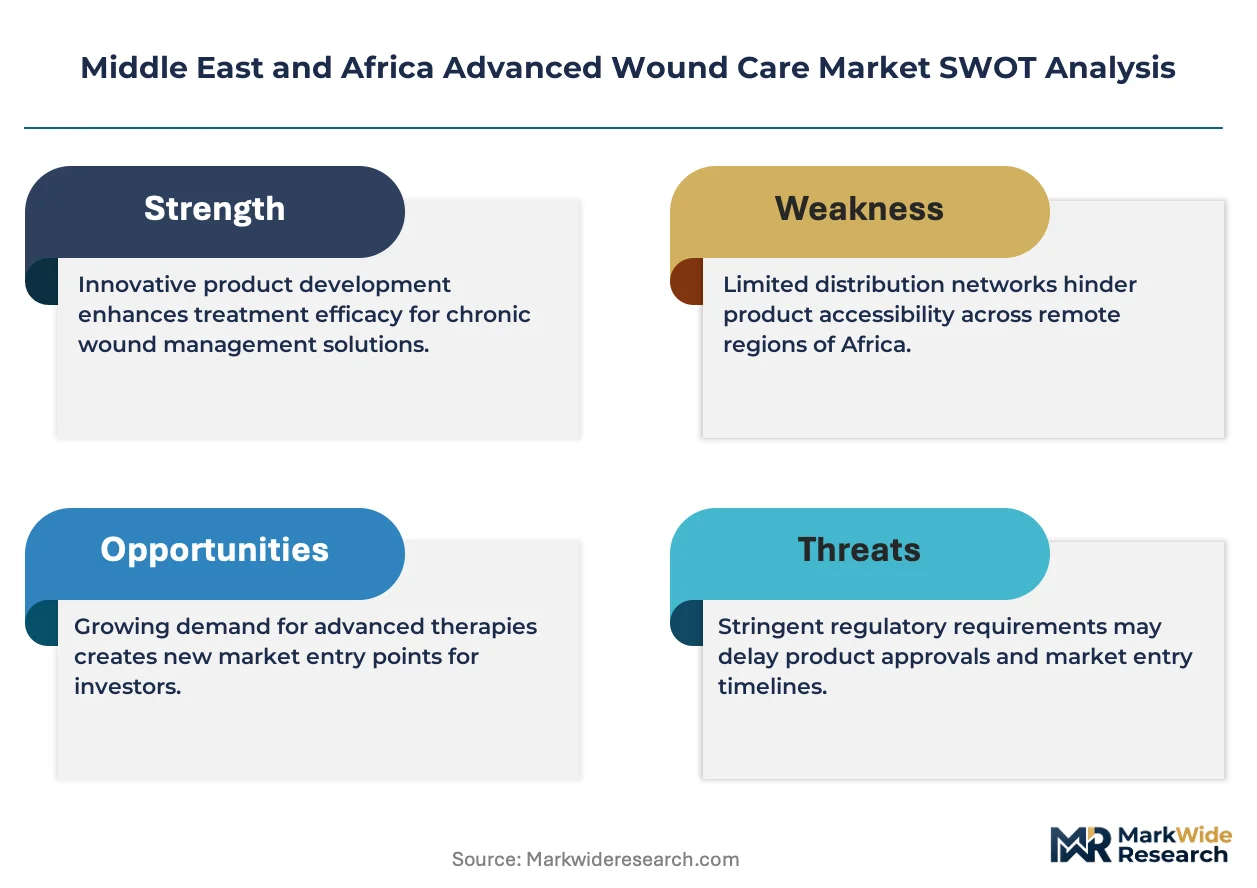
Saudi Food and Drug Authority and South African Health Products Regulatory Authority enforce registration requirements for medical device dressings, creating compliance barriers that favor established multinationals with dedicated regulatory affairs teams. The European Union Medical Device Regulation exerts indirect pressure through CE marking recognition patterns adopted by Gulf state import authorities. Stakeholders must monitor evolving reimbursement pathways for home-based wound management as Gulf health ministries expand chronic disease management outside hospital settings.
Market Dynamics
Hospital procurement departments across Saudi Arabia and South Africa are consolidating vendor relationships around advanced dressing portfolios, compressing supplier bases while elevating technical service requirements as a non-negotiable buying criterion.
Growth Catalysts
- SFDA Registration Harmonization:Saudi Food and Drug Authority streamlined medical device dossier requirements, accelerating market entry timelines for hydrocolloid and foam dressing categories.
- Diabetes Prevalence Trajectories:Diabetic foot ulcer incidence in tertiary hospital networks across the Gulf Cooperation Council drives sustained demand for moist wound healing technologies.
- Nanofiber Manufacturing Scale-Up:Electrospinning capacity investments by regional contract manufacturers enable localized production of sub-500 nanometer pore matrices.
Market Restraints
- Petrochemical Input Volatility:Polyurethane and silicone feedstock price swings compress margin stability for foam dressing producers dependent on Gulf petrochemical supply chains.
- Regulatory Fragmentation:Divergent registration pathways between South African Health Products Regulatory Authority and Gulf state import authorities force redundant clinical testing expenditures.
- Traditional Dressing Substitution:Low-cost gauze and saline solutions retain preference in underfunded public sector wound care protocols across Sub-Saharan Africa.
Strategic Opportunities
- Home Healthcare Expansion:UAE and Saudi health ministry reimbursement pilots for outpatient chronic wound management open channel diversification beyond hospital procurement.
- Burn Center Specialization:Eschar management and graft fixation applications in tertiary burn units command premium pricing relative to standard pressure ulcer protocols.
- Telemedicine Integration:Remote wound assessment platforms paired with smart dressing sensors enable outcomes-based contracting models in South African private networks.
Industry Challenges
- Specialized Nursing Shortages:Advanced dressing application protocols require trained wound care nurses, a workforce category concentrated in urban South African and Saudi hospital clusters.
- CE Marking Dependency:Gulf state import authorities reference European Union Medical Device Regulation conformity patterns, forcing manufacturers to maintain dual regulatory compliance tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Advanced Wound Care Market |
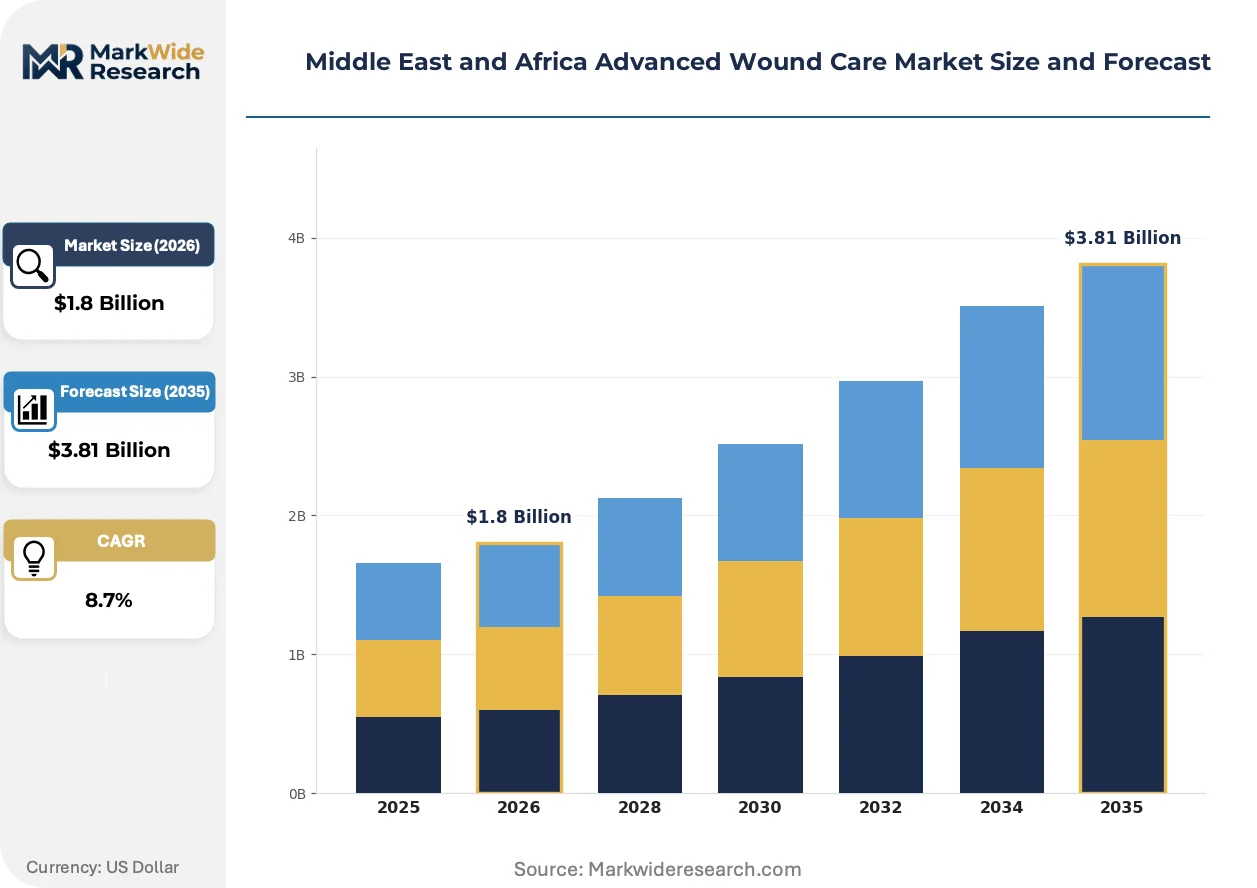
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Dressings, Alginate Dressings, Foam Dressings, Anti-Infective Dressings Application: Surgical Wounds, Diabetic Ulcers, Pressure Ulcers, Burn Treatment End User: Hospitals, Home Healthcare, Long-term Care Facilities, Clinics Technology: Hydrogel Technology, Cell-based Technology, Nanofiber Technology, Electrospun Technology |
| Companies Covered | Coloplast Corporation, Integra Life Sciences Corporation, Smith & Nephew, Organogenesis Inc., Oculus Innovative Sciences, Mölnlycke Health Care AB, Medtronic plc, 3M, ConvaTec Group PLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Advanced Wound Care Market Shifts & Advancements
Electrospun nanofiber architectures and smart sensor integration are compressing product development cycles while redefining performance benchmarks across moist wound healing categories.
Nanofiber wound dressing technology maintains precise moisture vapor transmission rates through electrospun matrices with engineered pore architectures. Saudi tertiary hospitals and South African private networks are adopting these platforms for diabetic foot and post-surgical applications at accelerated procurement velocities. The form factor is miniaturizing, enabling patch-scale delivery systems that displace bulk foam configurations in ambulatory settings.
South African Health Products Regulatory Authority updated medical device classification protocols for absorbent wound dressings, aligning technical documentation requirements with European Union Medical Device Regulation Annex VIII structures. This regulatory convergence elevates barriers for non-CE marked suppliers while streamlining pathway efficiency for established multinationals. Burn treatment and chronic wound segments in Johannesburg and Cape Town private hospital networks exhibit the most pronounced compliance response velocity.
Home healthcare agencies are unbundling wound care supply decisions from traditional hospital procurement hierarchies, establishing direct distributor relationships for advanced dressing categories. This channel disintermediation concentrates in Saudi Arabia's Ministry of Health chronic disease management pilots and South African private insurance network homecare extensions. The behavioral shift is most visible in Riyadh and Jeddah metropolitan clusters where outpatient wound protocols now exceed inpatient volumes for stable chronic cases.
Middle East and Africa Advanced Wound Care Market Segmentation
Advanced wound care purchasing decisions in the Middle East and Africa fragment across four distinct dimensions. Procurement departments prioritize product performance specifications while reimbursement pathways increasingly favor home-based delivery models.
Product Type:
Substitution pressure from traditional gauze and saline solutions weighs heaviest on commodity-adjacent segments, forcing advanced dressing manufacturers to sharpen clinical differentiation.
- Foam Dressings:Polyurethane or silicone-based absorbent layers manage moderate to heavy exudate across diverse wound etiologies. Saudi tertiary hospitals and South African private networks concentrate procurement volumes here, driven by versatility across post-surgical and traumatic wound protocols.
- Hydrocolloid Dressings:Gel-forming polymers like carboxymethylcellulose maintain moist environments for necrotic or granular wounds. Demand clusters in Riyadh and Jeddah metropolitan hospital systems where diabetic foot ulcer protocols emphasize autolytic debridement without mechanical disruption.
- Alginate Dressings:Calcium and sodium alginate fibers derived from brown seaweed form hydrophilic gels upon exudate contact. Burn centers in Johannesburg and Cape Town utilize these for cavity wound packing and donor site management.
- Anti-Infective Dressings:Silver, iodine, or polyhexamethylene biguanide impregnated matrices deliver antimicrobial action. SFDA registration requirements for antimicrobial claims create compliance barriers favoring established multinationals with dedicated regulatory affairs infrastructure.
Foam dressings anchor the volume base while nanofiber-enabled hydrocolloid variants gain share at the steepest rate.
Application:
Margin structure varies sharply by clinical complexity, with eschar management and graft fixation commanding premium pricing over standard moist wound healing protocols.
- Burn Treatment:Eschar management, autograft fixation, and donor site care require specialized moisture vapor transmission control. Tertiary burn units in Saudi Arabia and South Africa concentrate demand, with procurement prioritizing conformability and pain reduction during dressing changes.
- Diabetic Ulcers:Neuropathic foot lesions in Gulf Cooperation Council tertiary networks drive sustained demand for moisture-balanced healing environments. The South African national health laboratory service updated protocols specifically address offloading and moisture management integration.
- Surgical Wounds:Post-operative incision care spans clean closed wounds to dehisced complex cases. Procurement consolidation across Saudi and South African hospital systems favors suppliers with comprehensive portfolio breadth and technical service capabilities.
- Pressure Ulcers:Stage II through IV sacral and heel lesions in long-term care settings require cost-effective moisture management. Public sector budget constraints in Sub-Saharan Africa limit advanced dressing penetration despite established clinical efficacy.
Surgical wound applications generate the largest revenue pool while burn treatment delivers the highest per-unit margins.
End User:
Channel disintermediation is accelerating as supply chain control shifts from centralized hospital procurement toward distributed care settings.
- Hospitals:Tertiary and secondary acute care facilities across Saudi Arabia and South Africa remain the dominant procurement channel. Vendor consolidation trends compress supplier bases while elevating technical training and outcomes documentation requirements.
- Home Healthcare:Outpatient chronic wound management pilots by UAE and Saudi health ministries are reorganizing purchasing hierarchies. Direct distributor relationships now bypass traditional hospital supply chains for stable diabetic and pressure ulcer cases.
- Long-term Care Facilities:Nursing homes and rehabilitation centers manage pressure ulcer prevention and treatment protocols. South African private insurance network extensions into residential care are expanding reimbursement coverage for advanced dressings.
- Clinics:Primary care and specialized wound clinics handle debridement and dressing changes for ambulatory patients. Riyadh and Jeddah metropolitan clusters exhibit the most pronounced shift toward clinic-based chronic wound stabilization.
Hospitals retain procurement dominance while home healthcare channels expand most quickly.
Technology:
Manufacturing process differentiation is compressing product development cycles and redefining performance benchmarks for moisture management and biocompatibility.
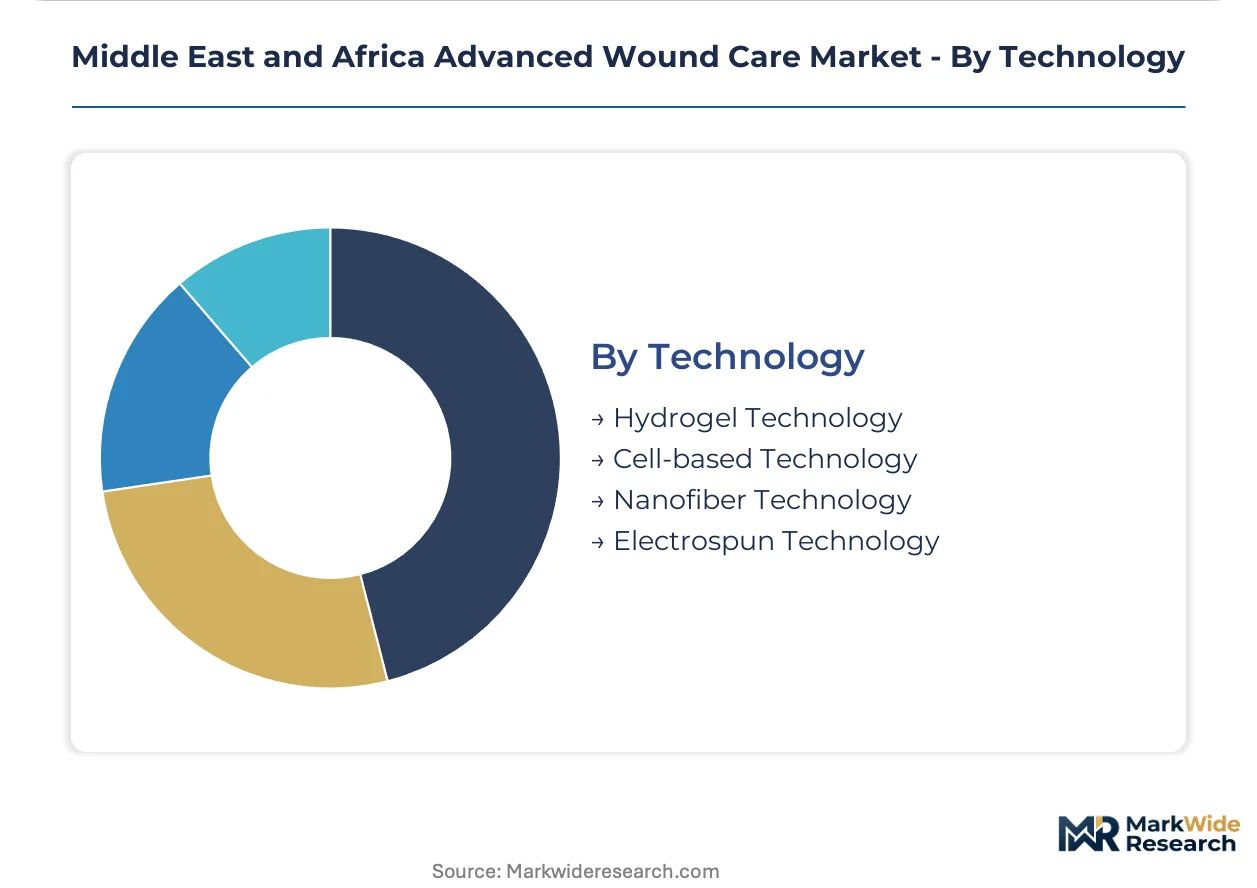
- Electrospun Technology:High-voltage fiber drawing produces sub-500 nanometer pore matrices with engineered moisture vapor transmission rates. Regional contract manufacturers in the Gulf are scaling capacity to serve Saudi tertiary hospital demand for diabetic foot and post-surgical applications.
- Nanofiber Technology:Electrospun and force-spun architectures enable miniaturized patch-scale delivery systems. South African private networks in Johannesburg and Cape Town are adopting these platforms at accelerated procurement velocities for ambulatory settings.
- Hydrogel Technology:Cross-linked polymer networks deliver cooling, hydrating, or debriding action. Amorphous and sheet hydrogels serve dry necrotic wounds and painful donor sites across hospital and home care channels.
- Cell-based Technology:Living cellular constructs including fibroblasts and keratinocytes support chronic wound closure. Regulatory complexity and cold chain requirements limit penetration to specialized tertiary centers with established regenerative medicine protocols.
Electrospun technology anchors current manufacturing investment while nanofiber form factors climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jeddah Islamic Port underwrites Saudi Arabia's distribution dominance for advanced wound care imports, with container throughput capacity enabling just-in-time replenishment across Gulf hospital networks.
Saudi Arabia
Tertiary hospital procurement in Riyadh and Jeddah drives foam dressing volumes for diabetic foot protocols. The Saudi Food and Drug Authority streamlined medical device dossier requirements in 2023, compressing registration timelines for hydrocolloid categories. King Faisal Specialist Hospital anchors demand concentration in Riyadh's metropolitan cluster.
South Africa
Private hospital networks in Johannesburg and Cape Town concentrate alginate dressing procurement for burn center applications. The South African Health Products Regulatory Authority updated medical device classification protocols, aligning documentation with European Union Medical Device Regulation Annex VIII structures. Groote Schuur Hospital's tertiary burn unit in Cape Town sets regional clinical standards.
United Arab Emirates
MOHAP reimbursement pilots for home-based chronic wound management are reorganizing supply chain hierarchies. Dubai's logistics free zones enable regional distribution hub positioning for multinational dressing manufacturers. Rashid Hospital's wound care center anchors tertiary demand in the emirate's metropolitan corridor.
Israel
Specialized wound care clinics in Tel Aviv and Haifa drive adoption of nanofiber-enabled platforms for ambulatory settings. The national health insurance system's technology assessment pathways influence procurement decisions across hospital networks. Sheba Medical Center's chronic wound unit in Ramat Gan concentrates clinical trial activity.
Egypt
Public sector hospital procurement in Cairo and Alexandria retains preference for traditional gauze solutions amid budget constraints. The country's national pharmaceutical regulator maintains import registration requirements for advanced dressings. Kasr Al Ainy Hospital's surgical departments in Cairo represent the largest concentrated demand for post-operative foam applications.
Middle East and Africa Advanced Wound Care Market Competitive Landscape
Concentration sits with diversified medical device conglomerates and specialized wound care pure-plays. The vendor base compresses around established multinationals with dedicated regulatory affairs infrastructure and Gulf distribution networks. Three archetypes dominate: diversified conglomerates with hospital supply breadth, wound care specialists with technology depth, and regional distributors with procurement relationships. Competitive moves center on vendor consolidation partnerships and electrospinning capacity investments.
Among diversified medical technology conglomerates, 3M and Medtronic plc occupy positions spanning hospital procurement categories beyond wound care. Smith & Nephew exemplifies the wound care specialist archetype with concentrated portfolio depth in hydrocolloid and foam technologies. Mölnlycke Health Care AB represents European-origin specialists leveraging barrier technology positioning in premium private hospital networks.
| Leading Market Players |
|---|
| Coloplast Corporation |
| Integra Life Sciences Corporation |
| Smith & Nephew |
| Organogenesis Inc. |
| Oculus Innovative Sciences |
| Mölnlycke Health Care AB |
| Medtronic plc |
| 3M |
| ConvaTec Group PLC |
| Others |
Supply & Pricing Matrix
Electrospinning capacity utilization rates at Gulf contract manufacturers establish minimum efficient scale thresholds that compress supplier margins while elevating price floors for nanofiber-enabled dressings. Saudi tertiary hospital procurement consolidation and South African private network vendor compression concentrate buying power, forcing mid-tier producers to absorb feedstock volatility or exit.
Pricing Analysis
Volume-discount tiering structures separate King Faisal Specialist Hospital-scale accounts from clinic-level purchasers, with polyurethane foam dressings commanding the widest spread. Certification grade—SFDA registration versus CE-marking equivalence—drives the second pricing wedge. Cost compression in standard hydrocolloid tiers intensifies as traditional gauze substitution pressure mounts from Egyptian public sector procurement. Long-term care facilities exhibit the highest price sensitivity; tertiary burn units the least.
Supply Chain Analysis
Just-in-time replenishment dominates Saudi hospital networks through Jeddah Islamic Port container throughput, while South African private chains maintain strategic stockpiles against logistics chokepoint exposure. Raw material flows draw from German polyurethane resin producers, Chinese silicone feedstock suppliers, and Saudi petrochemical derivatives. Single-source vulnerability concentrates in electrospinning equipment procurement. Distribution runs through Dubai logistics free zones for Gulf coverage and Johannesburg pharmaceutical wholesalers for Southern African penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced wound care incumbents face substitution defense imperatives as traditional saline-gauze protocols retain preference across underfunded Sub-Saharan public systems and Egyptian hospital procurement.
For Market Incumbents: Compound technical service capabilities into locked-in hospital procurement relationships, embedding wound care nurse training and outcomes documentation as non-negotiable contract terms. Backward integration into electrospinning capacity secures margin control against petrochemical feedstock volatility. SFDA registration harmonization investments raise compliance barriers for non-CE marked challengers. For New Entrants and Emerging Players: Technical service gaps in home healthcare channel management—where incumbents under-serve distributor relationship maintenance—offer white-space entry. Target UAE and Saudi Ministry of Health chronic disease management pilots with direct-to-agency distribution models bypassing hospital procurement hierarchies. Burn center specialization in Johannesburg and Cape Town tertiary networks presents the most penetrable premium segment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among wound care pure-plays with established GPO contracts and electrospinning manufacturing assets. Long-term viability hinges on regulatory affairs infrastructure depth and Gulf distribution network control. Watch SFDA antimicrobial claims registration velocity as inflection indicator for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Harmonization | Accelerates market entry timelines for hydrocolloid and foam dressing categories in Saudi tertiary networks. |
| Electrospinning Capacity Expansion | Captures nanofiber technology demand from diabetic foot and post-surgical applications in Riyadh clusters. |
| Home Healthcare Channel Diversification | Bypasses hospital procurement consolidation through direct distributor relationships with UAE and Saudi health ministries. |
| Burn Center Specialization Partnership | Secures premium pricing for eschar management protocols at Groote Schuur Hospital and King Faisal Specialist. |
| Telemedicine Integration Development | Enables outcomes-based contracting with South African private insurance networks using smart dressing sensors. |
Research Methodology
Operator-level perspectives from hospital procurement directors, wound care nurse specialists, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interview findings triangulated against SFDA registration databases, South African Health Products Regulatory Authority device filings, hospital procurement contract records, and customs import data for polyurethane and silicone feedstocks. Bottom-up segment sizing and top-down macroeconomic validation converged across product type, application, end user, and technology dimensions.
Sensitivity analysis tested forecast robustness across petrochemical price volatility scenarios, regulatory registration timeline variations, and diabetes prevalence trajectory assumptions. Segmentation modeling incorporated product type, application, end user archetype, and manufacturing technology. CAGRs derived from fitted growth curves applied to base-year market sizing. Key inputs included tertiary hospital bed expansion pipelines, home healthcare reimbursement pilot scaling, and electrospinning capacity buildout schedules.
Forecasts assume regulatory continuity in SFDA and South African Health Products Regulatory Authority regimes; material policy shifts would require re-modeling. Revision becomes warranted when antimicrobial claims registration rejection rates or petrochemical feedstock price volatility cross historical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Smart Bandages and Smart Wound Dressings Market
Wound Care
Advanced Wound Care Management Market
Wound Care
Saudi Arabia Wound Care Management Devices Market
Wound Care
Europe Advanced Wound Care Market
Wound Care
North America Negative Pressure Wound Therapy Market
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Autologous Wound Patches Market
Wound Care
Collagen Dressings Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Philippines Wound Care Market
Wound Care
Asia Pacific Wound Care Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Venous Leg Ulcer (VLU) Treatment Market
Wound Care
Global Traditional Wound Management Market
Wound Care
Advanced Wound Therapy Devices Market
Wound Care
Global Wound Dressings Market