
 North America Biguanide Market | 2026-2036
North America Biguanide Market Size, Share, and Industry Trends Forecast 2026-2036
North America Biguanide Market Analytics
USP-NF monograph compliance for metformin hydrochloride is bifurcating the competitive landscape between validated API suppliers and reformulation specialists. Merck & Co., Inc. leverages its historical manufacturing scale to sustain bulk supply contracts with major distributors. Bristol-Myers Squibb Company anchors its position through specialized R&D pipelines targeting metabolic syndrome combinations. Sanofi differentiates via integrated delivery networks that control hospital formulary access across the southeastern United States.
Biguanides comprise a class of oral hypoglycemic agents characterized by a guanidine-derived core structure, with metformin (dimethylbiguanide) serving as the dominant compound due to its superior safety margin and minimal risk of lactic acidosis compared to withdrawn analogs like phenformin. These agents function primarily by suppressing hepatic gluconeogenesis and improving peripheral insulin sensitivity in type 2 diabetes management. Among product types, metformin occupies the mature volume base while extended-release formulations capture expanding margin pools through patent-protected delivery mechanisms. The application landscape shows type 2 diabetes as the established revenue anchor, with polycystic ovary syndrome representing a faster-growing off-label expansion corridor. Hospital end users dominate procurement scale, though online platforms are gaining script fulfillment share through direct-to-patient subscription models.
FDA bioequivalence standards for generic metformin, coupled with Health Canada bioavailability requirements and USP dissolution testing protocols, collectively determine market access timelines and manufacturing qualification costs for new entrants. These regulatory frameworks elevate barriers for API sourcing from non-prequalified facilities while rewarding domestic tablet compression and coating investments. Stakeholders must monitor evolving FDA guidance on nitrosamine impurity thresholds, as this single specification shift could force batch recalls or supplier switches across the extended-release supply base.
Market Dynamics
FDA nitrosamine impurity thresholds for extended-release metformin are forcing wholesale supplier switches and batch recalls across the North American supply base. Manufacturers now face compressed qualification timelines as Health Canada and USP-NF monograph requirements tighten in parallel.
Growth Catalysts
- Type 2 diabetes prevalence:Rising patient volumes across the United States and Canada expand prescription volumes for first-line oral hypoglycemic therapy. Hospital formularies increasingly prioritize generic biguanides for cost containment.
- Polycystic ovary syndrome off-label expansion:Endocrinology practices in the southeastern United States are driving script growth for metformin in reproductive health applications. This indication corridor attracts reformulation investment.
- Extended-release delivery mechanisms:Patent-protected coating technologies enable margin capture beyond commodity immediate-release tablets. Specialized compression equipment investments reward early movers.
Market Restraints
- API sourcing concentration:Indian and Chinese active pharmaceutical ingredient suppliers dominate prequalified biguanide feedstock. FDA import alerts against specific facilities create supply vulnerability.
- Dissolution testing compliance costs:USP-NF apparatus qualification and method validation expenses burden mid-scale tablet manufacturers. Smaller entrants face capital barriers to entry.
- SGLT2 inhibitor substitution:Sodium-glucose cotransporter-2 inhibitors displace metformin monotherapy in cardioprotective protocols. Cardiology-driven prescribing patterns redirect volume.
Strategic Opportunities
- Direct-to-patient subscription platforms:Online pharmacies bypass traditional wholesale distribution to capture recurring revenue. This channel innovation reduces formulary gatekeeper dependence.
- Metabolic syndrome combination pipelines:Fixed-dose pairing of biguanides with GLP-1 receptor agonists opens new therapeutic positioning. R&D investment targets polypharmacy reduction.
- Mexico regulatory alignment:COFEPRIS bioequivalence pathway harmonization with FDA standards enables cross-border manufacturing consolidation. Multinational sponsors gain scale economies.
Industry Challenges
- Analytical chemist scarcity:Nitrosamine impurity method development and validation expertise concentrates at contract research organizations. In-house capability building faces recruitment bottlenecks.
- Legacy coating line retrofit costs:Immediate-release equipment conversion for extended-release production demands fluid bed dryer and spray system installation. Facility downtime compresses output during transition.
- Health Canada post-approval change management:Site transfer notifications and supplemental new drug submission timelines delay supplier diversification. Regulatory affairs capacity constraints extend project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Biguanide Market |
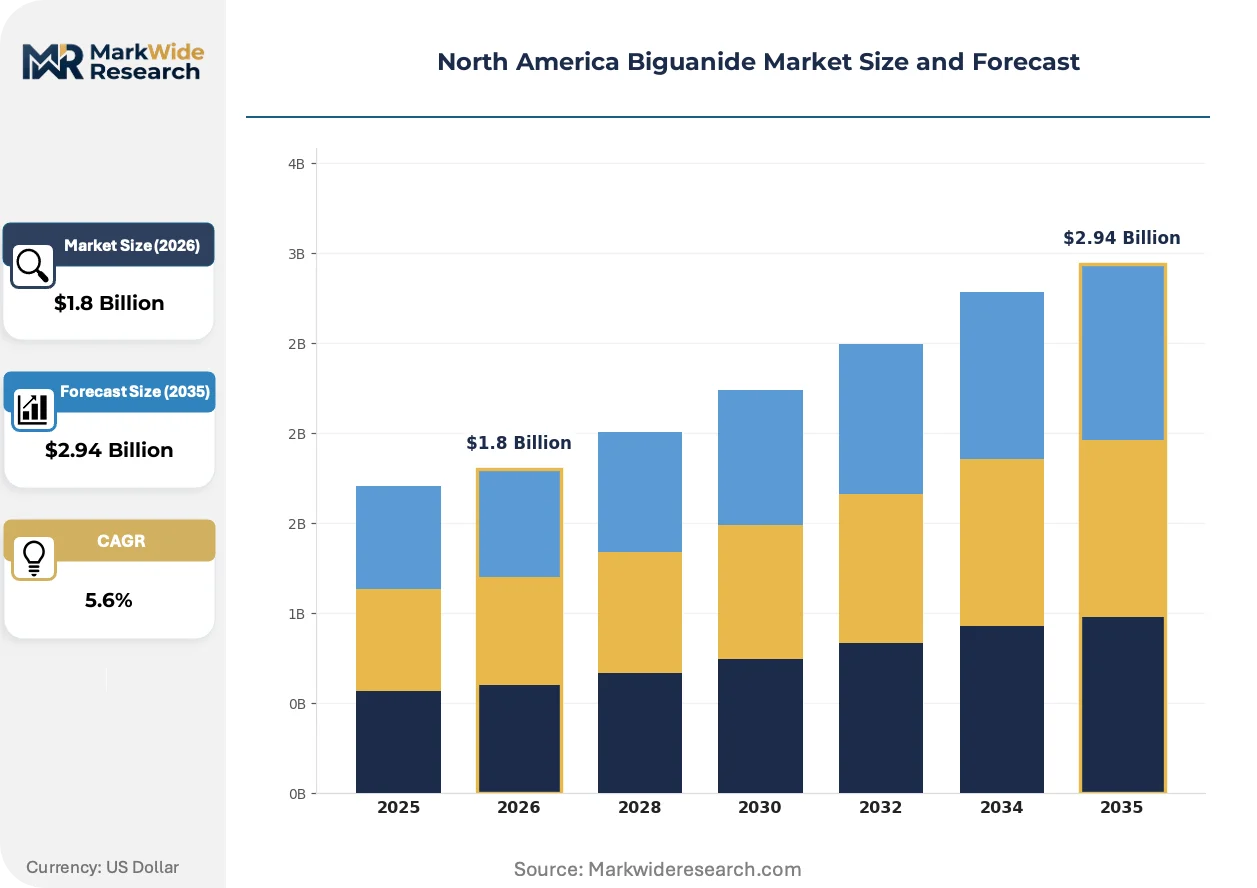
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Buformin, Phenformin, Others Application: Type 2 Diabetes, Polycystic Ovary Syndrome, Weight Management, Cardiovascular Health End User: Hospitals, Clinics, Pharmacies, Online Platforms Form: Tablets, Liquid, Capsules, Extended-Release |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb Company, Sanofi, Takeda Pharmaceutical Company Limited, Boehringer Ingelheim International GmbH, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Eli Lilly, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Biguanide Market Evolving Landscape
Continuous manufacturing adoption is decomposing batch-based production economics in biguanide tablet operations. Regulatory guidance evolution and equipment vendor maturation converge to reshape competitive cost structures.
Osmotic pump technology is decomposing conventional matrix-controlled release dominance in extended-release metformin. Specialty pharmaceutical manufacturers in New Jersey and North Carolina are retrofitting facilities at accelerated pace. This diffusion is compressing margins for legacy hydroxypropyl methylcellulose-based formulations while rewarding laser-drilled tablet precision.
FDA guidance on nitrosamine risk assessment for chemically synthesized APIs is mandating secondary amine scavenging and purge factor documentation across the extended-release supply chain. Manufacturers must redesign synthetic routes or implement confirmatory testing protocols. The extended-release segment bears disproportionate compliance burden due to higher API loading and processing temperatures.
Hospital procurement consolidation through group purchasing organizations is concentrating volume allocation decisions among fewer pharmacy directors. Integrated delivery networks in Texas and Florida now negotiate multi-year sole-source agreements. This concentration is visible most acutely in the southeastern United States where health system mergers have reduced independent hospital count substantially.
North America Biguanide Market Segmentation
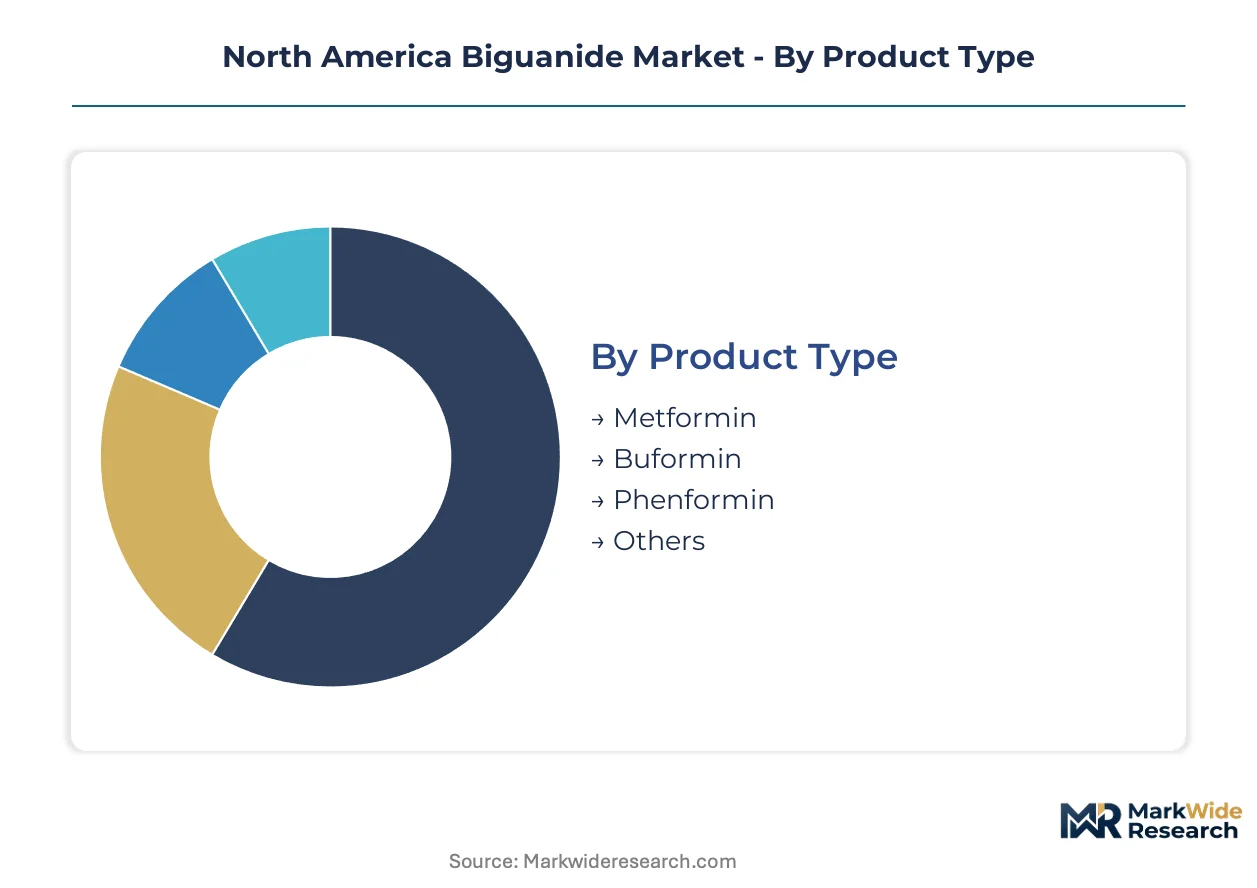
Biguanide market segmentation reveals divergent supply chain configurations across product chemistry, therapeutic positioning, and distribution channel. Each dimension carries distinct regulatory footprints and margin structures that reshape competitive priorities.
Product Type:
Domestic manufacturing concentration varies sharply across this category, with API sourcing patterns dictating regional production economics.
- Metformin:Dimethylbiguanide hydrochloride dominates prescription volumes through superior lactic acidosis safety margins versus withdrawn analogs. Hospital procurement in Texas and Florida concentrates demand for immediate-release and extended-release variants alike. FDA bioequivalence standards for generic formulations sustain domestic tablet compression investments.
- Buformin:Butylbiguanide compound retains limited niche utilization in select European-influenced prescribing protocols. Health Canada regulatory pathways restrict importation from non-prequalified API facilities. The compound's narrower therapeutic index constrains volume expansion.
- Phenformin:Withdrawn from US and Canadian markets due to fatal lactic acidosis risk. Historical regulatory action by FDA and Health Canada eliminated legitimate prescribing. Remaining analytical reference standard demand serves forensic and research applications exclusively.
- Others:Proguanil and investigational biguanide analogs occupy antimalarial and pipeline research segments. COFEPRIS-registered Mexican manufacturers supply limited regional feedstock for non-diabetes applications.
Metformin commands the established base. The steepest expansion runs through extended-release formulation investments.
Application:
Prescription volume distribution across indications reflects reimbursement tiering and prescriber specialty concentration.
- Type 2 Diabetes:First-line oral hypoglycemic positioning anchors hospital formulary placement and Medicare Part D coverage. Endocrinology practices in the southeastern United States drive script consolidation through integrated delivery networks. SGLT2 inhibitor substitution pressures monotherapy share in cardioprotective protocols.
- Polycystic Ovary Syndrome:Off-label reproductive endocrinology utilization expands fastest across fertility clinics and academic medical centers. Insulin sensitivity improvement drives metformin adoption prior to assisted reproduction interventions.
- Weight Management:Obesity medicine specialists prescribe metformin adjunctively for metabolic syndrome patients. GLP-1 receptor agonist co-therapy protocols reshape dosing patterns.
- Cardiovascular Health:Cardiology-driven prescribing for prediabetic populations with elevated coronary risk scores. Evidence synthesis from diabetes outcome trials supports expanded indication pursuit.
Type 2 Diabetes retains volume leadership. Polycystic Ovary Syndrome gains share fastest through reproductive health network expansion.
End User:
Channel economics diverge between institutional procurement scale and direct-to-patient subscription capture.
- Hospitals:Group purchasing organization consolidation in Texas and Florida concentrates multi-year sole-source agreements. Pharmacy directors control formulary access through integrated delivery network structures.
- Clinics:Federally qualified health centers and endocrinology specialty practices drive Medicaid and uninsured patient volume. 340B drug pricing program participation shapes procurement patterns.
- Pharmacies:Independent and chain retail fulfillment retains Medicare Part D majority share. Prior authorization requirements for branded extended-release variants create generic substitution pressure.
- Online Platforms:Direct-to-patient subscription models bypass wholesale distribution markups. Telehealth prescriber integration enables recurring revenue capture with reduced formulary gatekeeper dependence.
Hospitals anchor procurement scale. Online platforms climb the fastest through telehealth integration and subscription retention mechanics.
Form:
Manufacturing capital requirements stratify competitive entry across dosage form complexity.
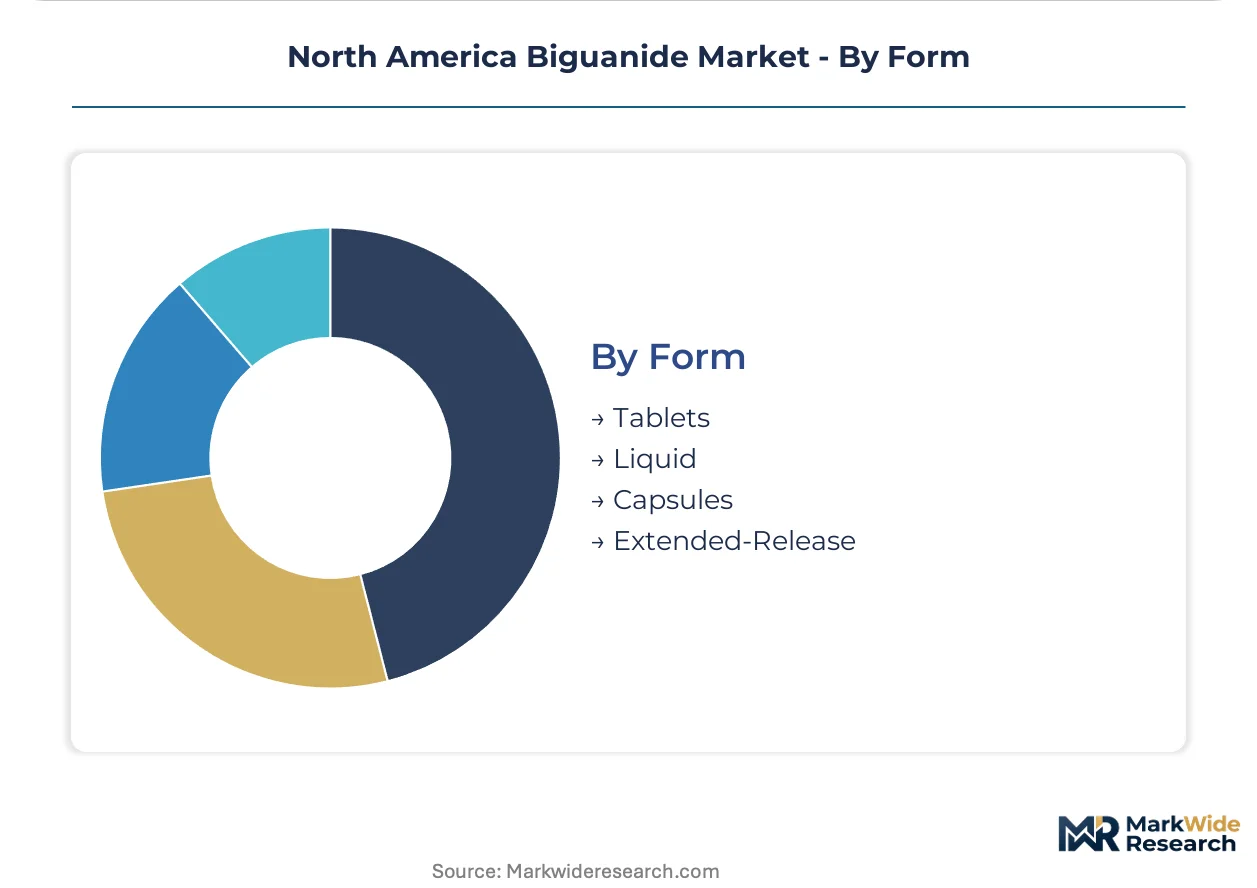
- Tablets:Immediate-release compression dominates generic manufacturing capacity in New Jersey and North Carolina facilities. USP-NF dissolution apparatus qualification burdens mid-scale entrants.
- Liquid:Pediatric and geriatric swallowing difficulty applications sustain niche compounding pharmacy demand. Stability and palatability formulation challenges limit commercial scale.
- Capsules:Powder-filled alternatives for patients with tablet excipient sensitivities. Limited differentiation versus immediate-release tablets constrains volume.
- Extended-Release:Osmotic pump and matrix-controlled technologies command patent-protected margin pools. Laser-drilled tablet precision and coating line retrofits demand specialized equipment investment.
Tablets retain the volume base. Extended-Release formulations capture margin expansion through delivery mechanism differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital pharmacy directors and integrated delivery network procurement officers concentrate purchasing power across the continent. Group purchasing organization consolidation reshapes volume allocation. Regulatory divergence between FDA, Health Canada, and COFEPRIS compliance pathways fragments supplier qualification timelines.
United States
Texas and Florida health system mergers concentrate formulary control among fewer pharmacy directors. FDA nitrosamine impurity thresholds for extended-release metformin force batch recalls and supplier switches. New Jersey and North Carolina manufacturing clusters absorb coating line retrofit investments for osmotic pump technology.
Canada
Health Canada bioavailability requirements and USP-NF dissolution testing protocols elevate barriers for API sourcing from non-prequalified facilities. Provincial drug plan reimbursement tiers prioritize generic biguanides for cost containment. Ontario and Quebec manufacturing investments reward domestic tablet compression and coating capabilities.
Mexico
COFEPRIS bioequivalence pathway harmonization with FDA standards enables cross-border manufacturing consolidation. Northern border states and Mexico City Metro pharmaceutical clusters supply regional feedstock for non-diabetes biguanide applications. Multinational sponsors capture scale economies through regulatory alignment.
North America Biguanide Market Competitive Landscape
Player mix skews toward historical manufacturing scale operators and reformulation specialists. The competitive structure bifurcates between validated API suppliers with bulk supply contracts and delivery mechanism innovators capturing patent-protected margins. Strategic archetypes include legacy pharmaceutical conglomerates with distributor relationships, specialty coating technology developers, and generic manufacturers with USP-NF monograph compliance capabilities. Dominant competitive moves encompass facility retrofitting for extended-release production and direct-to-patient subscription platform development.
Among established pharmaceutical conglomerates, Merck & Co., Inc. and Bristol-Myers Squibb Company occupy positions reflecting historical manufacturing scale and specialized R&D pipelines respectively. Sanofi sits within the integrated delivery network tier, exemplifying formulary access control across southeastern United States hospital systems. These three anchors represent distinct competitive vectors: bulk supply contracting, metabolic syndrome combination development, and regional distribution network concentration.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Sanofi |
| Takeda Pharmaceutical Company Limited |
| Boehringer Ingelheim International GmbH |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Eli Lilly |
| Pfizer |
| Others |
Value Network & Pricing Analysis
Capacity utilization at New Jersey and North Carolina tablet compression facilities shapes both API procurement scale economics and generic metformin price floors. Hospital group purchasing organization consolidation concentrates volume among fewer pharmacy directors, compressing margins for mid-scale manufacturers while rewarding integrated delivery network sole-source contractors.
Pricing Analysis
Cost-plus contracts with Indian and Chinese API suppliers index to acetone and dimethylamine commodity benchmarks, creating margin volatility for domestic tablet manufacturers. Three-tier pricing structure across osmotic pump extended-release, matrix-controlled formulations, and immediate-release generics separates patent-protected delivery mechanisms from commodity tablets. Pricing pressure stems from SGLT2 inhibitor substitution in cardioprotective protocols, eroding metformin monotherapy share. Federally qualified health centers and 340B program participants exhibit highest price sensitivity, while integrated delivery networks in Texas and Florida prioritize supply security over unit cost.
Supply Chain Analysis
Inventory lead times for extended-release coating excipients stretch to sixteen weeks, constraining production scheduling flexibility for osmotic pump retrofits. API sourcing draws from prequalified Indian and Chinese facilities, with Health Canada and FDA import alerts creating single-source vulnerability for specific dimethylbiguanide hydrochloride feedstock. Tariff exposure on pharmaceutical intermediates compounds cost uncertainty for New Jersey manufacturers. Distribution runs through McKesson and Cardinal Health wholesale networks to hospital systems, with direct-to-patient subscription platforms bypassing traditional channel markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analytical chemist scarcity for nitrosamine impurity method development constrains extended-release supplier qualification timelines, creating competitive advantage for contract research organization partnerships and in-house validation capabilities.
For Market Incumbents: Compound manufacturing scale advantages through backward integration into API sourcing from prequalified Indian facilities, while retrofitting North Carolina coating lines for osmotic pump production ahead of matrix-controlled release margin erosion. FDA nitrosamine threshold enforcement threatens batch recall exposure; prioritize secondary amine scavenging documentation and purge factor validation to defend hospital formulary positioning against supplier switches. For New Entrants and Emerging Players: Anchor in polycystic ovary syndrome reproductive endocrinology networks across southeastern United States fertility clinics, where off-label metformin utilization expands fastest and formulary gatekeeper dependence is weakest. Telehealth-integrated direct-to-patient subscription platforms offer the most penetrable channel, bypassing group purchasing organization volume concentration and capturing recurring revenue through automated refill mechanics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty coating technology developers with osmotic pump patent estates and validated FDA bioequivalence dossiers. Long-term viability over the next decade rests on delivery mechanism differentiation rather than commodity tablet scale. Target acquisition archetypes include reformulation specialists with Health Canada site transfer experience and laser-drilled tablet precision capabilities. Watch FDA guidance evolution on continuous manufacturing as inflection signal for competitive cost structure reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | FDA guidance evolution rewards fluid bed dryer investments with reduced batch failure rates and faster release testing. |
| Osmotic Pump Technology Retrofit | Laser-drilled tablet precision captures extended-release margin pools as matrix-controlled formulations face commoditization. |
| Direct-to-Patient Subscription Platform | Telehealth integration bypasses McKesson and Cardinal Health markups while reducing formulary gatekeeper dependence. |
| COFEPRIS Regulatory Alignment | Mexico bioequivalence pathway harmonization enables cross-border manufacturing consolidation for multinational sponsors. |
| Metabolic Syndrome Combination Pipeline | Fixed-dose GLP-1 receptor agonist pairing opens therapeutic positioning beyond diabetes monotherapy constraints. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital pharmacy directors, integrated delivery network procurement officers, regulatory affairs leads at generic manufacturers, and contract research organization analytical chemists. Secondary validation drew from FDA bioequivalence filings, Health Canada post-approval change management databases, USP-NF monograph revision histories, and group purchasing organization contract award records. Bottom-up prescription volume modeling triangulated against top-down hospital formulary placement assessments.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product chemistry, therapeutic indication, distribution channel, and dosage form complexity. CAGRs were derived from patient volume expansion trajectories and reimbursement tier evolution rather than price assumptions. Industry-specific inputs included endocrinology practice prescribing pattern surveys and 340B drug pricing program participation rates.
Decision-makers should treat outputs as directional under assumptions of stable FDA nitrosamine enforcement and continued Health Canada bioequivalence pathway alignment; material deviation in regulatory stringency or API import alert frequency would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Erectile Dysfunction Market
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market
Pharmaceuticals
Global Respiratory Drug Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Posaconazole Market
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
Subcutaneous Immunoglobulin Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market