
 Medical Tapes and Bandages Market | 2026-2036
Medical Tapes and Bandages Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Tapes and Bandages Market Intelligence
Modular wound care kits that bundle medical tapes with compression bandages and cohesive wraps is shifting how hospitals and surgical centers structure their procurement contracts. 3M leverages its materials science portfolio to anchor premium positioning across silicone and acrylic adhesive platforms. Johnson & Johnson sustains broad channel control through its Ethicon surgical supplies division and consumer first-aid reach. Medline Industries competes on private-label scale, occupying substantial share in the acute care distributor segment.
Medical tapes and bandages comprise pressure-sensitive adhesive systems and woven or non-woven substrates designed for securement, protection, and mechanical support of dermal injuries, typically specified by peel adhesion strength measured in ounces per inch and breathability rates in grams per square meter per day. Their primary commercial purpose spans post-operative incision management, chronic wound dressing fixation, and athletic injury stabilization across institutional and retail channels. Adhesive bandages and medical tapes command the largest revenue pools due to universal first-aid and surgical utilization, while compression bandages capture disproportionate margin strength in the lymphedema and venous ulcer therapy segments. The home care end user category is expanding fastest as post-acute discharge protocols and aging-in-place demographics redirect wound management from inpatient to residential settings.
The FDA governs biocompatibility and sterility standards for medical tapes and bandages under Class I and II device classifications, while ISO 10993 series standards govern cytotoxicity and sensitization testing for extended skin contact materials. The EU Medical Device Regulation imposes stricter clinical evidence requirements on adhesive wound care products entering European markets, reshaping documentation burdens for manufacturers. Stakeholders must monitor how evolving post-market surveillance mandates and sustainability-driven material restrictions will influence substrate selection and adhesive chemistry investments across their product development pipelines.
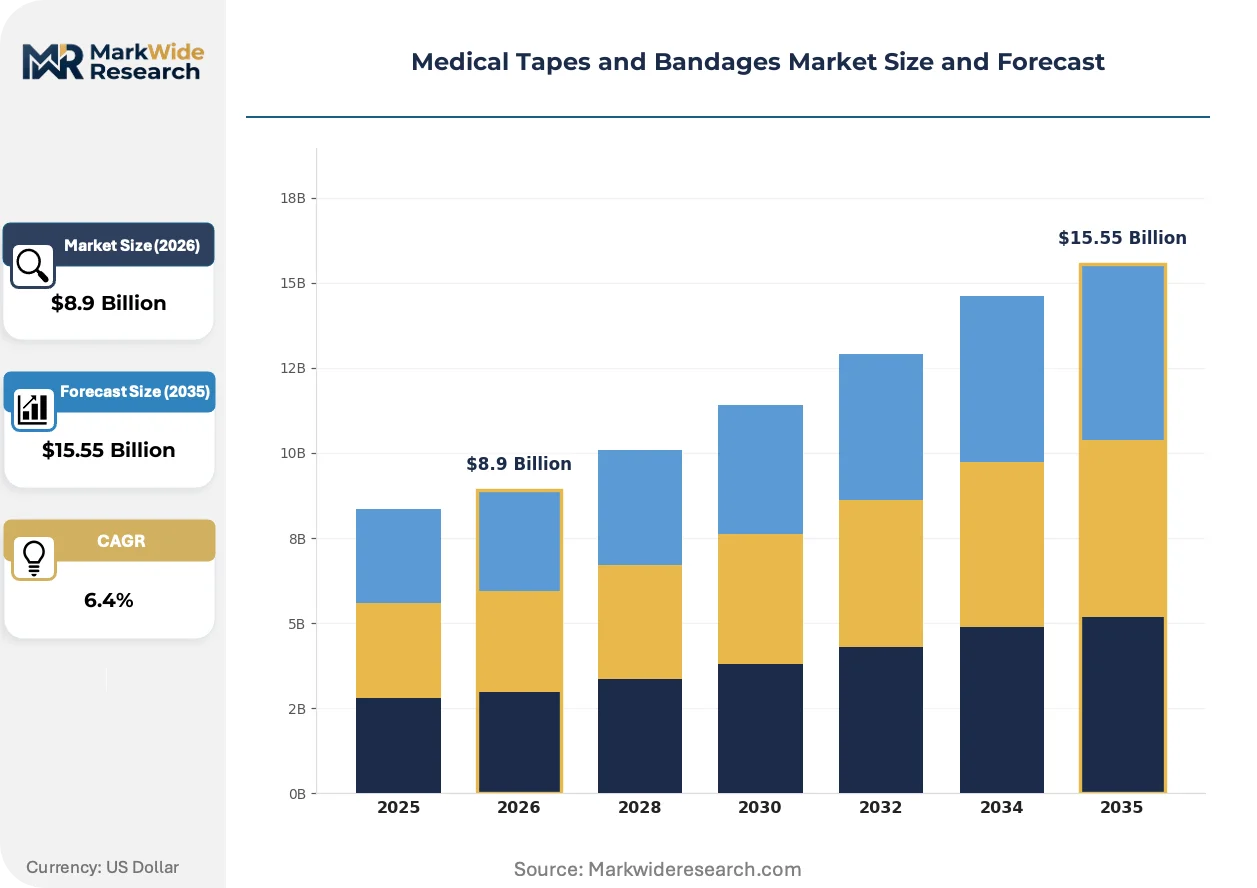
Market Dynamics
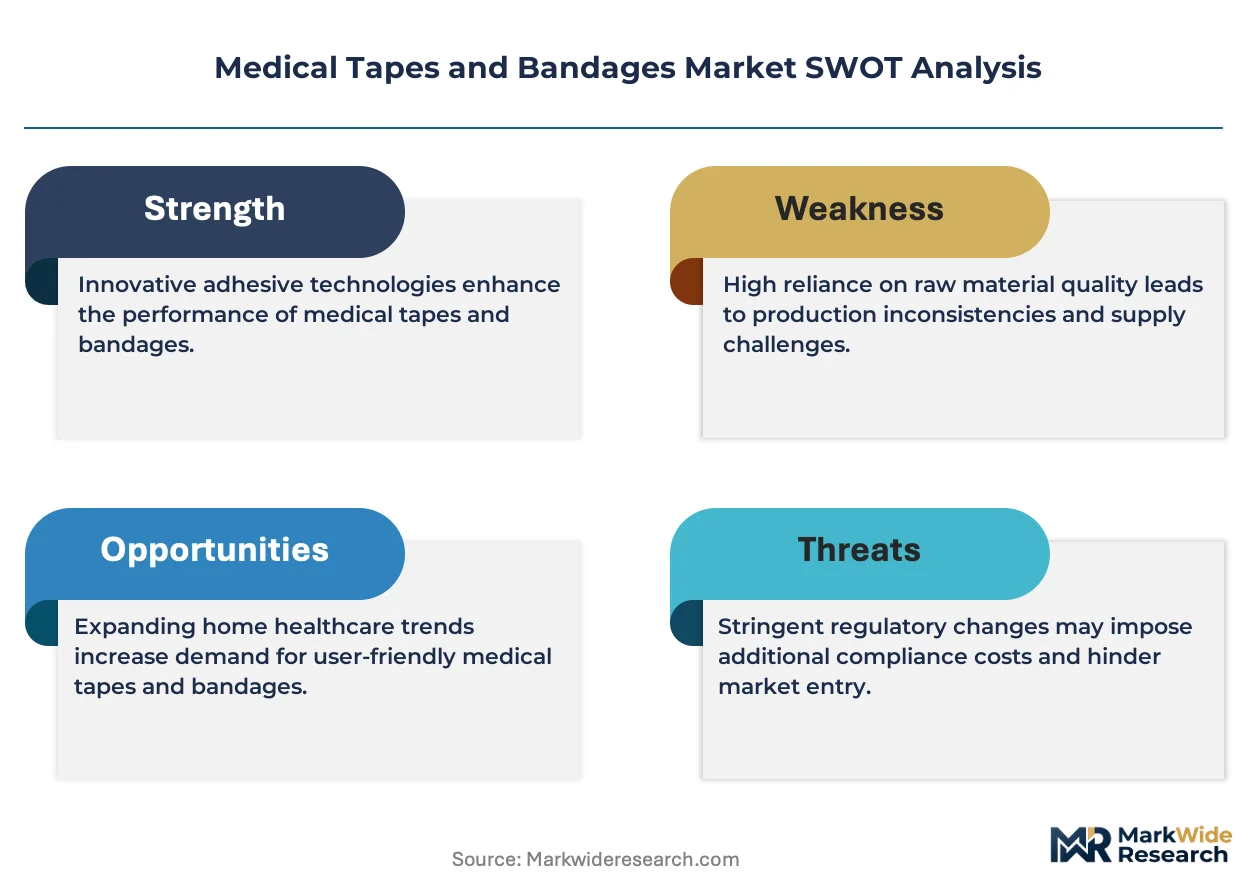
Silicone adhesive chemistry is displacing acrylic formulations in tertiary surgical settings as hospitals prioritize atraumatic removal protocols that reduce skin stripping and medical adhesive-related skin injuries during dressing changes.
Growth Catalysts
- MDR compliance deadlines:European hospitals are accelerating silicone tape procurement ahead of EU Medical Device Regulation clinical evidence requirements, creating inventory build cycles across German and French distributor networks.
- Ambulatory surgery center expansion:United States outpatient facility construction is concentrating demand for cohesive bandage systems that support same-day discharge protocols.
- Silicone chemistry maturation:Extended-wear adhesive platforms now achieve seven-day fixation without cytotoxicity tradeoffs, opening chronic wound applications previously reserved for sutures and staples.
Market Restraints
- Medical-grade silicone supply concentration:Specialty silicone resin production clusters in Germany and Japan, exposing tape manufacturers to petrochemical feedstock volatility and freight cost spikes.
- Biocompatibility testing timelines:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization protocols extend new product introductions by fourteen to eighteen months.
- Synthetic substrate substitution:Cotton and cellulose-based bandages retain cost advantages in emerging market price-sensitive procurement, compressing advanced non-woven penetration.
Strategic Opportunities
- Home care transition protocols:United States Medicare post-acute discharge mandates are redirecting compression therapy and negative pressure wound dressing fixation toward residential settings.
- Sustainability material mandates:EU Green Deal circular economy requirements are creating first-mover advantages for manufacturers developing bio-based adhesive backings and recyclable substrate laminates.
- Wearable device convergence:Continuous glucose monitor and cardiac patch adhesion requirements are pulling medical tape formulations into consumer electronics supply chains.
Industry Challenges
- Adhesive polymer formulation expertise scarcity:The intersection of pressure-sensitive rheology and dermatological safety requires chemists trained in both materials science and toxicology, a profile concentrated at legacy tape specialists.
- Cleanroom manufacturing capex intensity:Sterile medical tape production requires ISO Class 7 or better environments, with facility qualification timelines exceeding facility construction by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Tapes and Bandages Market |
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $15.55 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Bandages, Cohesive Bandages, Medical Tapes, Compression Bandages Application: Wound Care, Surgical Procedures, Sports Injuries, First Aid End User: Hospitals, Clinics, Home Care, Emergency Services Material: Fabric, Plastic, Foam, Paper |
| Companies Covered | 3M, Johnson & Johnson, B. Braun Melsungen AG, Molnlycke Health Care, Smith & Nephew, Cardinal Health, Medline Industries, McKesson Corporation, Paul Hartmann AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Tapes and Bandages Market Strategic Shifts & Innovations
Active material science investments are compressing the performance gap between premium silicone systems and mid-tier acrylic alternatives while regulatory documentation burdens reshape competitive entry costs.
Silicone gel adhesive technology is expanding into pediatric and geriatric wound care segments where fragile epidermal integrity demands low peel adhesion with secure fixation. Children's hospitals in the United States and long-term care facilities in Japan are standardizing silicone-first protocols for patients with comorbid skin conditions. This formulation shift is compressing acrylic tape share in price-insensitive clinical settings while creating formulation licensing opportunities between adhesive suppliers and finished goods manufacturers.
EU Medical Device Regulation post-market surveillance requirements are mandating clinical follow-up data for adhesive wound care products claiming extended wear durations. Manufacturers must now maintain vigilance systems capturing adverse event reports across distributed hospital networks. German and French notified bodies are applying heightened scrutiny to silicone tape biocompatibility claims, forcing reformulation documentation for products grandfathered under prior directives.
Hospital procurement departments are consolidating vendor lists around suppliers offering modular wound care kits rather than discrete tape and bandage SKUs. United States integrated delivery networks are negotiating three-year sole-source agreements for bundled securement products. This concentration is displacing spot-buy relationships with regional distributors and compressing price negotiation leverage for mid-tier manufacturers lacking kit assembly capabilities.
Medical Tapes and Bandages Market Segmentation
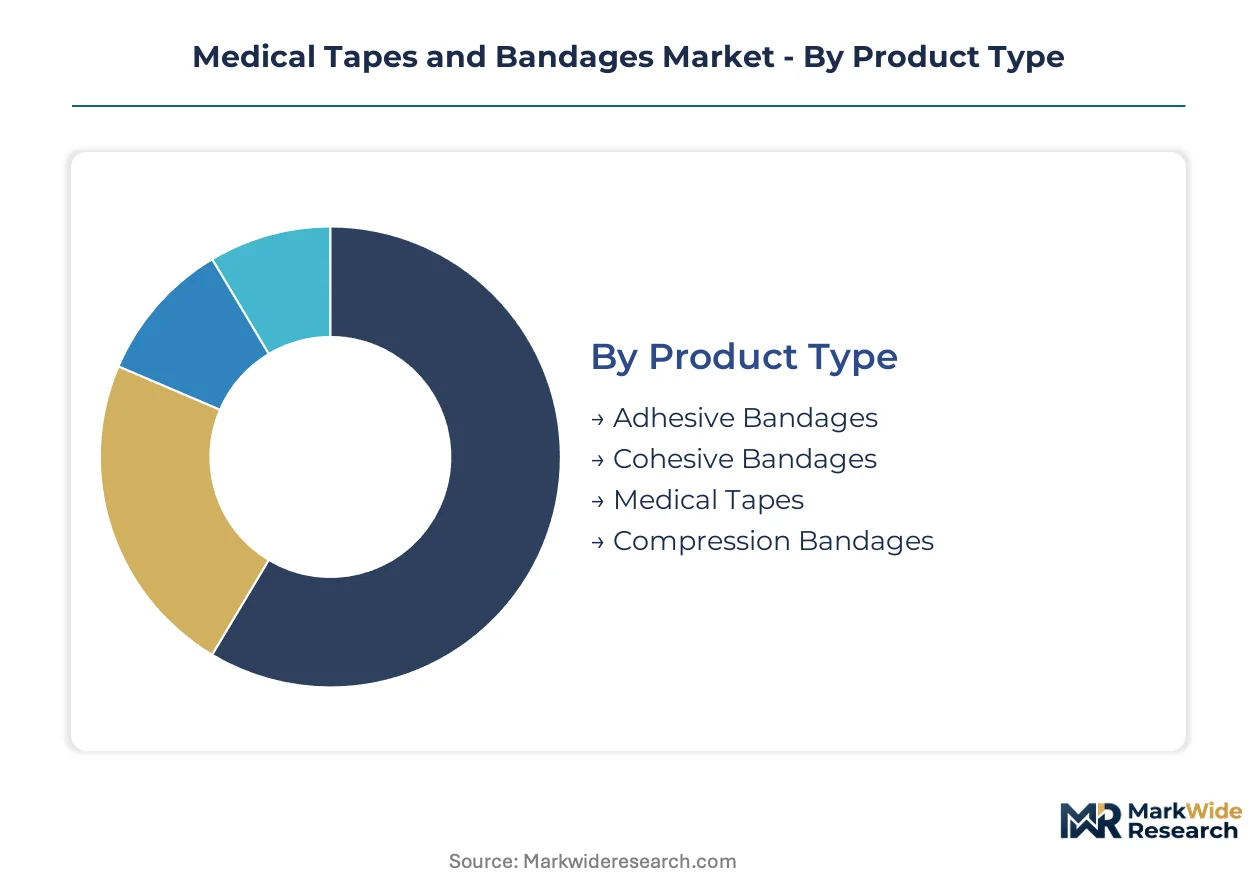
Segmentation in medical tapes and bandages reveals how adhesive chemistry, substrate selection, and care setting requirements create distinct procurement channels. Manufacturers configure product portfolios around peel adhesion specifications, breathability rates, and sterilization compatibility to match institutional versus retail demand patterns.
Product Type:
Pressure-sensitive adhesive systems differentiate primarily by substrate construction and intended wear duration, with silicone and acrylic chemistries partitioning the clinical premium tier from economy alternatives.
- Adhesive Bandages:Woven or non-woven substrates bonded to acrylic or zinc-oxide adhesives, specified by moisture vapor transmission rates. Demand clusters in United States retail pharmacy chains and Japanese convenience store networks where household first-aid stockpiling drives volume procurement.
- Medical Tapes:Silicone gel and hydrocolloid formulations engineered for seven-day wear without epidermal stripping. Tertiary surgical centers in Germany and France prioritize these for post-operative incision securement under MDR documentation requirements.
- Cohesive Bandages:Self-adherent elastic wraps that bond to themselves without underlying skin adhesion. United States ambulatory surgery centers standardize these for same-day discharge compression protocols.
- Compression Bandages:Multi-layer systems with calibrated pressure gradients measured in millimeters of mercury. Lymphedema therapy clinics and venous ulcer treatment centers in the United Kingdom and Australia generate disproportionate margin capture.
Adhesive bandages lead on scale; medical tapes lead on momentum.
Application:
Clinical outcome requirements and reimbursement pathways segment demand across acute intervention, chronic management, and preventive use cases.
- Wound Care:Chronic ulcer and diabetic foot management requiring moisture-balanced dressings. Home care nurses in the United States and community health workers in India drive adoption of advanced securement systems for extended-wear protocols.
- Surgical Procedures:Sterile field applications demanding ISO 10993-5 cytotoxicity compliance and documented peel adhesion consistency. German hospital procurement departments specify silicone-first protocols for patients with epidermal fragility.
- Sports Injuries:Athletic taping for joint stabilization and soft tissue support. Professional sports medicine facilities in Australia and collegiate athletic programs in the United States generate seasonal demand spikes.
- First Aid:Consumer-facing trauma management with minimal training requirements. Retail pharmacy chains in Japan and mass merchandisers in the United States dominate volume distribution.
Wound care commands the largest addressable base; surgical procedures extract the highest value per unit.
End User:
Facility certification standards and patient acuity levels determine adhesive performance specifications and packaging configurations.
- Hospitals:Tertiary care institutions requiring sterile tape production in ISO Class 7 cleanrooms. United States integrated delivery networks negotiate multi-year sole-source agreements for bundled securement products.
- Home Care:Post-acute discharge settings where patients or family members perform dressing changes. Medicare reimbursement shifts in the United States redirect compression therapy and negative pressure wound dressing fixation toward residential settings.
- Clinics:Outpatient facilities balancing cost containment with clinical efficacy. French and Italian primary care networks favor mid-tier acrylic formulations for routine wound management.
- Emergency Services:Pre-hospital trauma care requiring rapid application and reliable adhesion under field conditions. Ambulance services in Australia and emergency medical technicians in Germany prioritize cohesive bandages for immobilization.
Hospitals anchor revenue concentration; home care exhibits the steepest expansion trajectory.
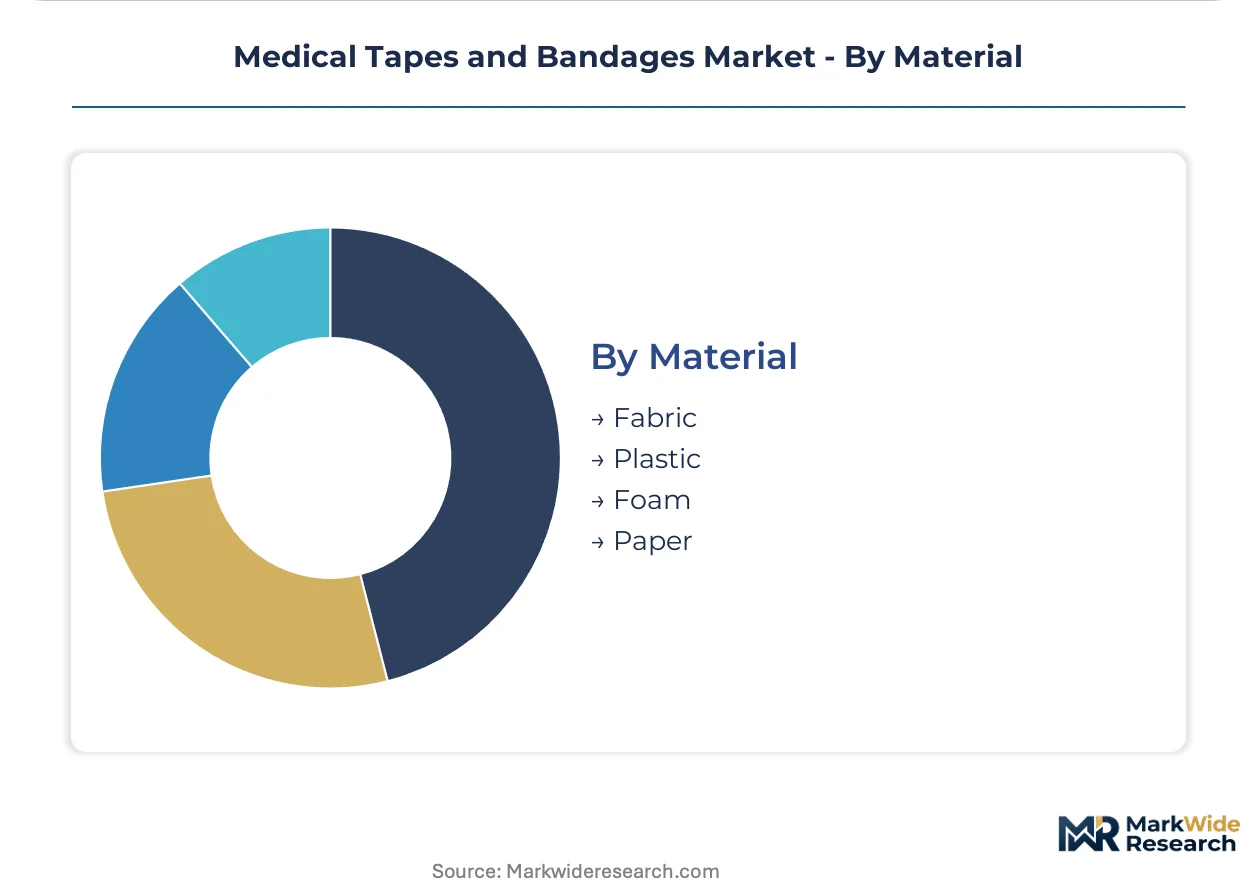
Material:
Substrate selection governs breathability, conformability, and sustainability profile, with bio-based alternatives gaining regulatory preference in European markets.
- Fabric:Cotton and viscose woven constructions offering conformability and patient comfort. Traditional wound care protocols in India and price-sensitive procurement in Brazil retain cotton-based bandages despite synthetic substitution pressure.
- Plastic:Polyurethane and polyethylene films providing moisture barrier properties. Japanese manufacturers lead in ultra-thin transparent film development for continuous glucose monitor adhesion.
- Foam:Polyurethane foam substrates cushioning bony prominences and absorbing exudate. Pressure injury prevention protocols in United States long-term care facilities standardize foam-backed silicone tapes.
- Paper:Microporous surgical tape constructions enabling moisture vapor exchange. Cost-conscious clinics in Italy and Spain favor paper tapes for short-duration securement.
Fabric retains volume leadership; foam gains share fastest on geriatric wound care demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johnson & Johnson pioneered modern adhesive bandage manufacturing in New Brunswick, New Jersey during the 1920s, establishing production protocols that spread to European and Asian markets through mid-century licensing agreements.
United States
Ambulatory surgery center construction and Medicare post-acute discharge mandates concentrate demand for cohesive bandages and silicone tapes. FDA biocompatibility testing standards under ISO 10993 series govern extended-wear adhesive approvals. New Brunswick, New Jersey retains historical significance as a wound care innovation cluster where foundational adhesive technologies first scaled.
Germany
Specialty silicone resin production clusters and tertiary hospital procurement networks drive premium tape demand ahead of MDR compliance deadlines. EU Medical Device Regulation clinical evidence requirements reshape documentation burdens for adhesive wound care products entering European markets. The Rhine-Ruhr industrial corridor hosts concentrated medical-grade polymer formulation expertise.
Japan
Aging-in-place demographics and long-term care facility standardization protocols accelerate silicone-first adoption for geriatric skin integrity. METI industrial standards and PMDA device classifications govern pressure-sensitive adhesive biocompatibility. Osaka-based manufacturers lead ultra-thin transparent film development for continuous glucose monitor adhesion applications.
United Kingdom
Lymphedema therapy clinics and venous ulcer treatment centers generate disproportionate margin capture for multi-layer compression systems. MHRA post-market surveillance aligns with EU MDR vigilance requirements for extended-wear claims. London procurement networks influence NHS standardization protocols across England and Wales.
India
Community health worker deployment and price-sensitive procurement sustain cotton-based bandage volume despite synthetic substitution pressure. CDSCO device classification standards and BIS textile specifications govern wound care product quality. Gujarat textile clusters supply woven substrates for domestic and export adhesive bandage manufacturing.
Medical Tapes and Bandages Market Key Industry Players
The competitive structure tilts toward diversified health care conglomerates with materials science capabilities. Market concentration reflects tiered positioning across premium silicone platforms and economy acrylic alternatives. Three archetypes dominate: adhesive chemistry specialists with polymer formulation depth, diversified medical device manufacturers leveraging surgical supply channels, and private-label scale operators serving acute care distributors. Capacity expansion and strategic portfolio diversification represent the dominant competitive moves as manufacturers respond to MDR documentation burdens and home care transition protocols.
Within the materials science tier, 3M exemplifies premium positioning across silicone and acrylic adhesive platforms through captive polymer development capabilities. Johnson & Johnson occupies a position bridging surgical supply divisions and consumer first-aid reach. Medline Industries represents private-label scale concentration in the acute care distributor segment. These three anchors illustrate how chemistry expertise, channel control, and manufacturing scale partition competitive advantage across institutional and retail procurement channels.
| Leading Market Players |
|---|
| 3M |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| Molnlycke Health Care |
| Smith & Nephew |
| Cardinal Health |
| Medline Industries |
| McKesson Corporation |
| Paul Hartmann AG |
| Others |
Cost & Logistics Intelligence
Silicone-acrylic formulation divergence separates premium clinical tiers from commodity bandage alternatives, with MDR certification requirements and seven-day wear claims commanding substantial price premiums while concentrating supply relationships around German polymer specialists and Japanese film manufacturers. This bifurcation funnels procurement contracts toward integrated suppliers capable of ISO 10993 documentation bundles, compressing spot-buy margins for distributors lacking cleanroom manufacturing partnerships.
Pricing Analysis
Three-tier pricing structure across premium silicone, standard acrylic, and economy zinc-oxide levels dominates institutional procurement, with FDA biocompatibility tier and seven-day wear certification as primary differentiation drivers. Price erosion runs through cotton-based economy segments as Indian textile clusters absorb margin compression from synthetic substitution campaigns. Ambulatory surgery centers exhibit highest price sensitivity due to bundled kit negotiations, while German tertiary hospitals demonstrate lowest sensitivity under MDR-driven specification mandates.
Supply Chain Analysis
EU Green Deal domestic-content mandates are reshaping sourcing patterns for bio-based adhesive backings, pressuring manufacturers to qualify European substrate suppliers ahead of circular economy deadlines. Medical-grade silicone resin production concentrates in Germany and Japan, with polyurethane foam substrates drawing from Chinese petrochemical feedstocks and cotton woven constructions resting on Gujarat textile clusters. Single-source vulnerability in specialty silicone resin exposes tape manufacturers to freight cost spikes. Distribution runs through integrated delivery network sole-source agreements rather than regional distributor spot-buy relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical tapes and bandages represent a late-cycle quality story as silicone-first protocols displace acrylic alternatives in tertiary surgical settings, with home care transition protocols redirecting premium securement demand toward residential compression therapy applications.
For Market Incumbents: To counter private-label scale concentration in acute care distribution, 3M and Johnson & Johnson should deepen captive silicone polymer development and secure multi-year sole-source agreements with United States integrated delivery networks. Backward integration into medical-grade silicone resin production mitigates German and Japanese supply concentration risks. CE marking pathway acceleration ahead of MDR vigilance deadlines protects grandfathered product positions. For New Entrants and Emerging Players: Silicone gel pediatric formulations offer a technology-first wedge into children's hospital procurement networks where fragile epidermal integrity demands command price-insensitive purchasing. White-space targets include long-term care facility standardization in Japan and community health worker deployment in India. A go-to-market angle emphasizing bio-based adhesive backings aligns with EU Green Deal circular economy requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack kit assembly capabilities and MDR documentation resources to serve hospital procurement consolidation trends. Five-to-ten year viability favors adhesive chemistry specialists with polymer formulation depth over pure-play distributors. The signal to watch is German notified body scrutiny intensity on silicone tape biocompatibility claims as an inflection indicator for reformulation cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| MDR CE Marking Pathway | Accelerated documentation protects market access across German and French hospital networks. |
| Silicone Polymer Backward Integration | Captive resin production insulates margin from petrochemical feedstock volatility in specialty supply. |
| Hospital System Partnership | Three-year sole-source agreements with United States IDNs lock out regional distributor competition. |
| Sustainability Repositioning | Bio-based adhesive backings secure first-mover advantage under EU Green Deal circular economy mandates. |
| Home Care Channel Expansion | Medicare post-acute discharge protocols redirect compression therapy demand toward residential settings. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and adhesive formulation chemists with secondary validation against FDA 510(k) filings, ISO 10993 test reports, CMS Medicare reimbursement data, and hospital procurement databases. Bottom-up SKU-level volume aggregation and top-down category spend analysis triangulated market sizing across the analysis window.
Comparable-period anchoring linked projection assumptions to historical silicone tape adoption curves and acrylic displacement patterns across German tertiary centers and United States ambulatory surgery facilities. Segmentation modeling spanned adhesive chemistry tier, substrate material, wear duration specification, end-user facility type, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to extended-wear protocol penetration rates, with inputs including MDR compliance deadline schedules and Medicare post-acute discharge mandate implementation trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal material restriction timelines and medical-grade silicone resin supply disruptions. Assumptions underlying volume projections reflect documented procurement pattern shifts rather than speculative technology substitution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Compression Garments and Stockings Market
Medical Supplies
Cataract Disposable Products Market
Medical Supplies
Tracheostomy Tray Market
Medical Supplies
Disposable Specimen Container Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Filter Needles Market
Medical Supplies
Disposable Lead Wires Market
Medical Supplies
Oral Syringes Market
Medical Supplies
Evacuated Drainage Bottles Market
Medical Supplies
US N95 Mask Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Global IV Flush Syringe Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Medical Plastics Market
Medical Supplies
Disposable Medical Gowns Market