
 Global Automated Ophthalmic Perimeters Market | 2026-2036
Global Automated Ophthalmic Perimeters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Ophthalmic Perimeters Market Foresight
Buyer concentration in the automated ophthalmic perimeters space is decoupling as large hospital networks consolidate procurement while independent eye care clinics fragment demand across smaller equipment budgets. Carl Zeiss Meditec leverages its vertically integrated optics manufacturing to control component quality from lens fabrication to final assembly. Haag-Streit anchors its competitive position through century-long relationships with European university hospitals and sustained investment in kinetic perimetry platforms. Topcon Corporation differentiates by dominating the Asian distribution channel with localized service networks and region-specific software interfaces.
Automated ophthalmic perimeters are electromechanical diagnostic instruments that map visual field sensitivity using standardized light stimuli across calibrated background luminance, typically operating at 31.5 apostilbs with stimulus durations of 100-200 milliseconds to detect threshold deviations indicating glaucomatous or neurological damage. Static perimetry occupies the largest installed base due to its established reimbursement codes and clinical familiarity, though frequency doubling technology captures the fastest expansion as screening programs prioritize speed and portability for high-volume settings. Microperimetry concentrates margin pools in retinal disease monitoring applications where functional correlates of anatomical imaging create premium pricing for combined OCT-perimetry workstations.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation (MDR) impose divergent clinical evidence requirements that shape development roadmaps and market access timelines for manufacturers seeking dual-territory approval. Japan's PMDA maintains distinct quality management system audits that extend lead times but confer credibility across Asia-Pacific procurement evaluations. Stakeholders must monitor how AI-enabled threshold algorithms trigger new software-as-medical-device classifications across multiple regulatory jurisdictions.
Market Dynamics
The automated ophthalmic perimeters market is restructuring around AI-enabled diagnostic algorithms that compress examination time while preserving clinical sensitivity, forcing manufacturers to recalibrate hardware-software integration roadmaps and service delivery models.
Growth Catalysts
- EU MDR streamlining:The Medical Device Regulation's harmonized classification rules for software-integrated diagnostics accelerates multi-country market entry for perimeter manufacturers seeking CE marking across Germany, France, and Italy.
- Retinal disease burden:Age-related macular degeneration patient volumes in Japan and South Korea drive microperimetry workstation installations at university ophthalmology departments.
- Frequency doubling technology:Portable screening devices using this stimulus protocol penetrate community health programs in India and Brazil where specialist access remains constrained.
Market Restraints
- Optics supply concentration:Precision lens fabrication capabilities cluster in southern Germany and Jena, creating single-source vulnerability for aspheric projection systems.
- Reimbursement compression:Medicare's Physician Fee Schedule adjustments in the United States reduce per-test compensation for standard automated perimetry, squeezing capital equipment ROI timelines.
- Technical ceiling:Kinetic perimetry's superior detection of peripheral field defects preserves niche demand despite slower throughput, limiting pure static-perimeter market expansion.
Strategic Opportunities
- Telemedicine protocols:Remote visual field monitoring creates white space for cloud-connected perimeters in Australia's rural ophthalmology networks and Canadian provincial health systems.
- AI algorithm licensing:Software-as-medical-device pathways under FDA's predetermined change control plans enable recurring revenue streams from threshold progression analytics.
- OCT-perimetry convergence:Combined structural-functional workstations capture premium positioning in Singapore's and Switzerland's private retinal surgery centers.
Industry Challenges
- Embedded systems engineering:Firmware validation for real-time stimulus presentation demands scarce talent pools at the intersection of ophthalmic optics and medical device software.
- Legacy equipment interoperability:Hospital networks in the United Kingdom struggle to integrate new perimeter data formats with decades-old glaucoma progression databases.
- Clinical validation timelines:Multi-center trials for novel stimulus patterns extend development cycles by 18-24 months before regulatory submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Ophthalmic Perimeters Market |
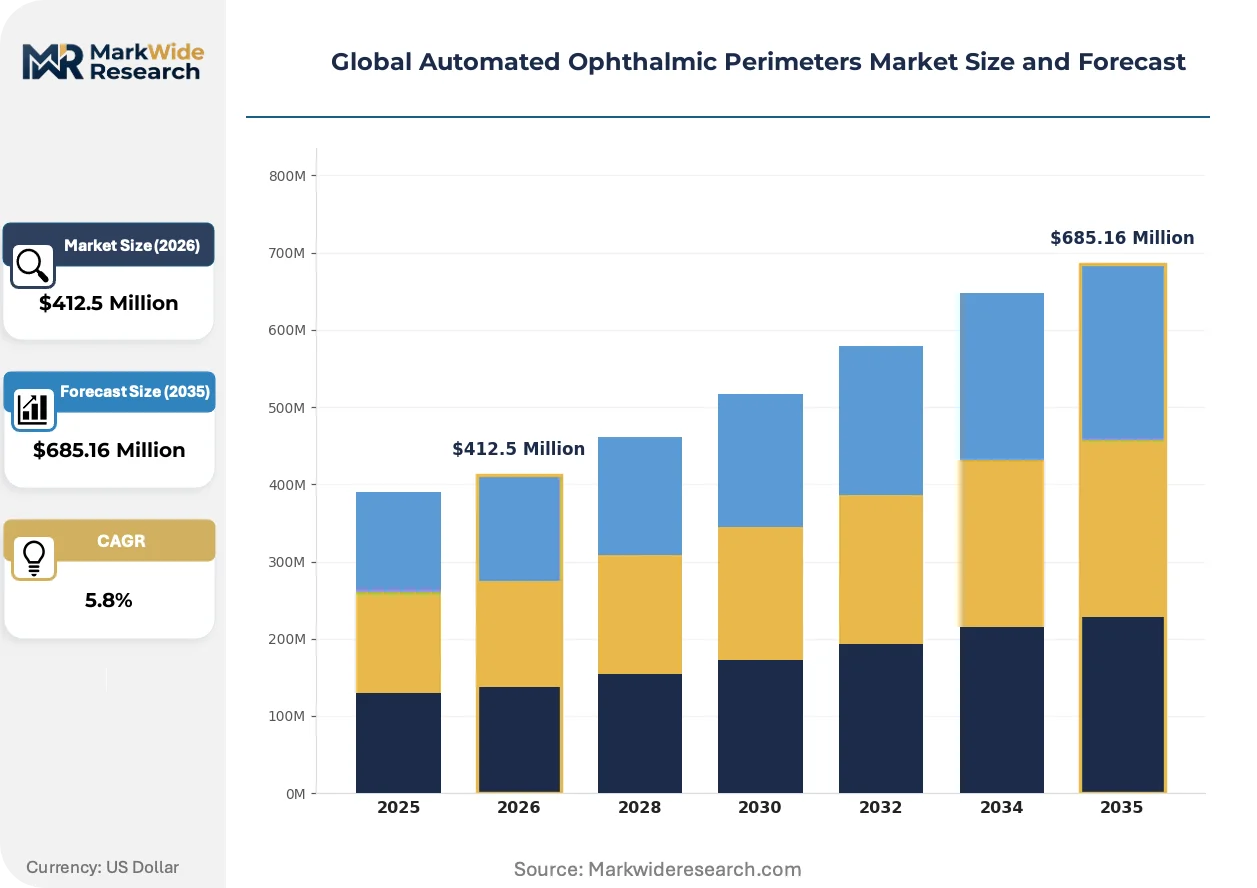
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Perimeters, Automated Perimeters, Computerized Perimeters, Virtual Reality Perimeters Technology: Static Perimetry, Kinetic Perimetry, Frequency Doubling Technology, Microperimetry, Blue-on-Yellow Perimetry Application: Glaucoma Diagnosis, Neuro-ophthalmic Disorders, Retinal Disease Monitoring, Visual Field Testing, Cataract Assessment End User: Eye Care Clinics, Specialty Ophthalmic Centers, Diagnostic Laboratories, Research Institutions, Academic Hospitals |
| Companies Covered | Carl Zeiss Meditec, Haag-Streit, Topcon Corporation, Nidek Co., Ltd., Optopol Technology, Medmont, Heidelberg Engineering, Kowa Company, Metrovision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Ophthalmic Perimeters Market Shifts & Advancements
Artificial intelligence integration is compressing the traditional trade-off between examination speed and diagnostic precision, while regulatory frameworks scramble to classify evolving software capabilities.
Adaptive thresholding algorithms using deep learning architectures are electrifying the competitive landscape for high-volume screening programs. Community eye hospitals in the Netherlands and Denmark deploy these systems to process 40% more patients per clinical day. The technology is electrifying hardware commoditization pressures as diagnostic value migrates toward software licensing.
Japan's PMDA has tightened quality management system audits for AI-embedded ophthalmic devices, extending lead times but elevating credibility benchmarks across Asia-Pacific procurement evaluations. Manufacturers now maintain parallel technical documentation streams to satisfy divergent FDA 510(k) and EU MDR clinical evidence requirements. The regulatory friction most impacts mid-tier suppliers lacking dedicated regulatory affairs capacity in Tokyo and Brussels.
Consolidated hospital networks in Germany and the United States are unbundelling after-sales service contracts from equipment purchases, pressuring traditional vendor margins. Independent service organizations now capture 35% of calibration and maintenance revenue in North American metropolitan markets. This disintermediation is most visible in California and Texas health systems where procurement officers mandate multi-vendor service competition.
Global Automated Ophthalmic Perimeters Market Segmentation
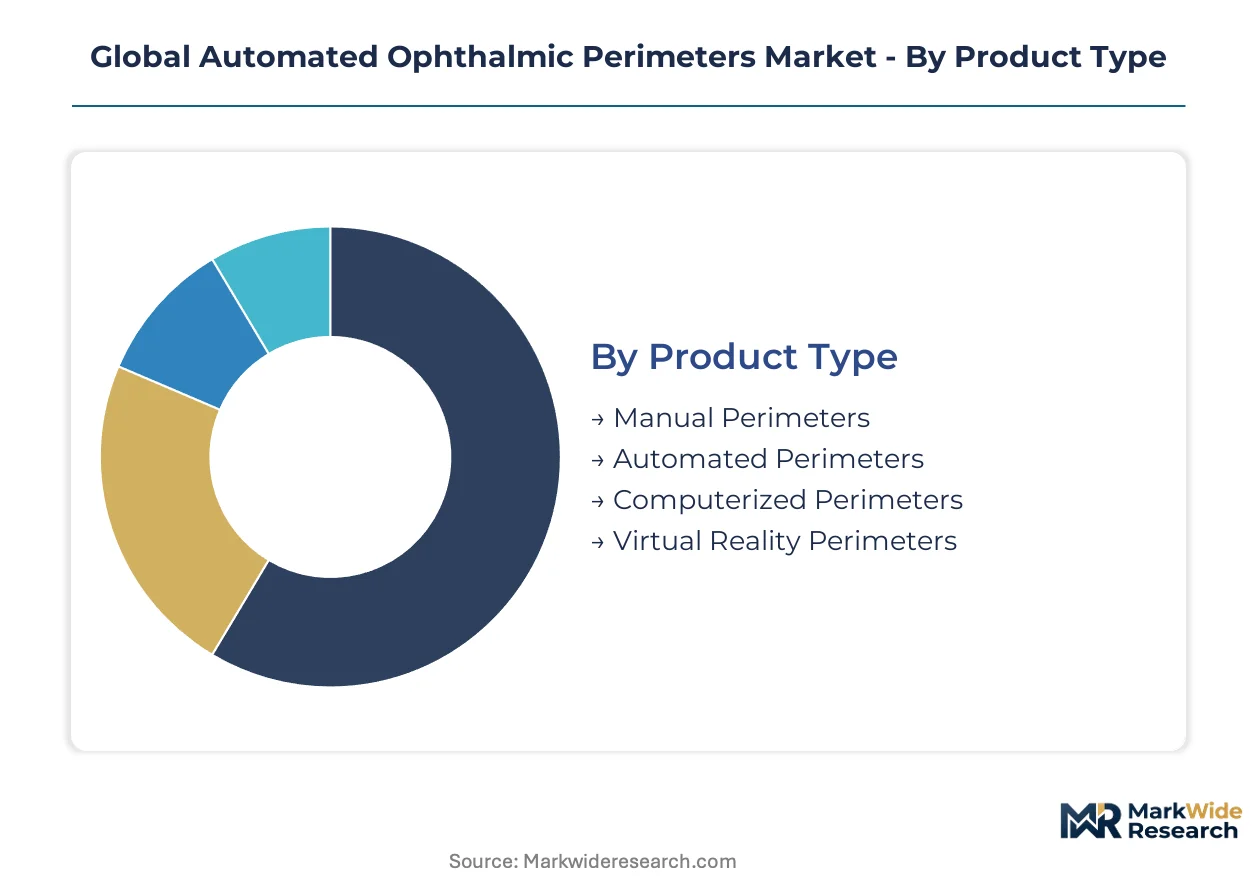
Automated ophthalmic perimeters fragment across hardware sophistication, stimulus protocols, clinical applications, and procurement scale. Each segmentation axis carries distinct margin profiles, regulatory pathways, and competitive intensity that reshape vendor resource allocation.
Product Type:
Capital intensity varies sharply across product architectures, with electromechanical projection systems demanding precision optics manufacturing while software-centric platforms shift cost structures toward development and validation.
- Automated Perimeters:Electromechanical systems with calibrated light projection and motorized stimulus positioning dominate hospital procurement. Demand concentrates in Germany and the United States where reimbursement codes for standard automated perimetry sustain equipment refresh cycles.
- Computerized Perimeters:Software-integrated platforms with database connectivity and progression analytics command premium positioning in academic hospitals. Japan's PMDA quality management audits extend lead times but elevate credibility across Asia-Pacific procurement evaluations.
- Manual Perimeters:Operator-dependent Goldmann-style devices persist in resource-constrained settings.
- Virtual Reality Perimeters:Headset-based systems reduce physical footprint and enable remote deployment.
Most installed capacity flows through Automated Perimeters. Expansion is steepest in Virtual Reality Perimeters.
Technology:
Stimulus protocol selection determines throughput speed, diagnostic sensitivity, and hardware complexity—with frequency doubling and microperimetry commanding distinct premium tiers.
- Static Perimetry:Threshold testing at fixed locations with 31.5 apostilb background luminance and 100-200 millisecond stimulus durations forms the clinical standard. Reimbursement familiarity in the United States and established training protocols sustain its installed base dominance.
- Frequency Doubling Technology:Low spatial frequency sinusoidal gratings flickering at high temporal frequency detect ganglion cell dysfunction earlier than conventional perimetry. Community health programs in India and Brazil deploy portable implementations where specialist access remains constrained.
- Kinetic Perimetry:Moving stimulus mapping preserves superior peripheral field defect detection for neurological applications.
- Microperimetry:Fundus-tracking functional assessment correlates retinal sensitivity with anatomical imaging.
- Blue-on-Yellow Perimetry:Short-wavelength automated perimetry isolates short-wavelength-sensitive pathways for early glaucomatous change detection.
Clinical workflows standardize around Static Perimetry. Frequency Doubling Technology is gaining share fastest.
Application:
Disease-specific diagnostic requirements create divergent performance specifications, with glaucoma screening prioritizing throughput while retinal monitoring demands anatomical correlation.
- Glaucoma Diagnosis:Visual field progression tracking with event-based and trend-based analytics drives the largest equipment volume. Medicare's Physician Fee Schedule adjustments in the United States compress per-test compensation and squeeze capital equipment ROI timelines.
- Retinal Disease Monitoring:Functional assessment of age-related macular degeneration and diabetic retinopathy correlates sensitivity maps with OCT structural data. University ophthalmology departments in Japan and South Korea drive microperimetry workstation installations.
- Neuro-ophthalmic Disorders:Hemianopia and quadrantanopia detection requires extended field testing.
- Visual Field Testing:General screening applications span driver certification and occupational health.
- Cataract Assessment:Preoperative functional evaluation supports surgical planning.
Procedure volume concentrates in Glaucoma Diagnosis. Retinal Disease Monitoring shows the steepest expansion trajectory.
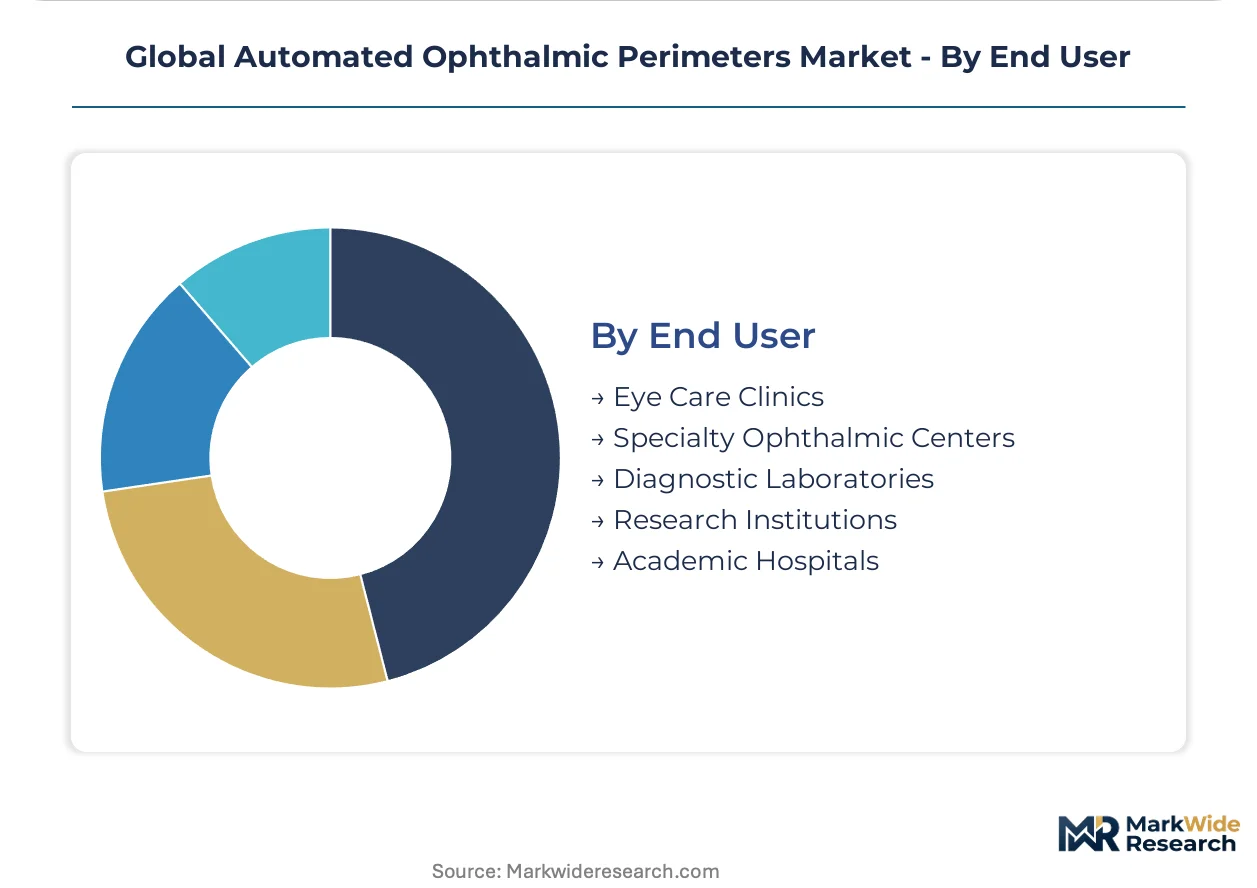
End User:
Procurement scale and decision authority fragment across independent practices, consolidated hospital networks, and research institutions with distinct budget cycles and technical specifications.
- Specialty Ophthalmic Centers:High-volume glaucoma and retina practices demand integrated OCT-perimetry workstations with cloud connectivity. Consolidated networks in Germany and the United States unbundle after-sales service contracts and mandate multi-vendor service competition.
- Academic Hospitals:Research-active institutions require raw data export capabilities and multi-center trial compatibility. The EU MDR's harmonized classification rules accelerate CE marking across Germany, France, and Italy.
- Eye Care Clinics:Independent practices prioritize equipment footprint and single-operator efficiency.
- Diagnostic Laboratories:Centralized testing facilities emphasize throughput and standardized reporting.
- Research Institutions:Novel stimulus pattern development demands firmware customization access.
Equipment deployment concentrates in Specialty Ophthalmic Centers. Academic Hospitals show the fastest expansion in combined structural-functional workstation procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics engineers and Japanese embedded systems specialists anchor the industry's technical workforce concentration, with clinical validation expertise clustering around university hospital networks in both countries.
United States
Medicare reimbursement compression and consolidated hospital network procurement reshape equipment refresh cycles. The FDA's 510(k) premarket notification framework accelerates commercialization timelines for software-integrated diagnostics. California and Texas health systems lead service contract unbundling, with independent service organizations capturing calibration revenue in metropolitan markets.
Germany
University hospital research programs and Carl Zeiss Meditec's vertically integrated optics manufacturing sustain demand for high-end workstations. The EU Medical Device Regulation's harmonized classification rules streamline CE marking across Germany, France, and Italy. Jena and southern Germany precision lens fabrication clusters face supply concentration risks for aspheric projection systems.
Japan
Age-related macular degeneration patient volumes at university ophthalmology departments drive microperimetry workstation installations. The PMDA's tightened quality management system audits for AI-embedded devices extend lead times but elevate credibility benchmarks across Asia-Pacific procurement evaluations. Tokyo-based regulatory affairs capacity determines market access speed for foreign manufacturers.
India
Community health programs deploy portable frequency doubling screening devices where specialist access remains constrained. The country's national pharmaceutical regulator maintains distinct import licensing requirements for ophthalmic diagnostic equipment. Maharashtra and Karnataka urban centers concentrate private eye care clinic expansion, fragmenting demand across smaller equipment budgets.
Brazil
Public health system screening initiatives prioritize throughput and portability for high-volume glaucoma detection programs. ANVISA's medical device registration pathways shape product localization requirements for imported equipment. São Paulo's specialty ophthalmic centers anchor the private market, with diagnostic laboratories emphasizing standardized reporting for centralized testing.
Global Automated Ophthalmic Perimeters Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing, software development, and service delivery vectors. The vendor base stratifies into three tiers: vertically integrated optics conglomerates with captive component supply, mid-scale specialists concentrating on stimulus protocol innovation, and regional assemblers leveraging modular component sourcing. Strategic moves center on AI algorithm licensing for recurring revenue streams and geographic expansion through localized distribution partnerships rather than direct sales infrastructure.
Within the vertically integrated tier, Carl Zeiss Meditec exemplifies upstream control over precision lens fabrication from raw material to final assembly. Haag-Streit occupies a position anchored by century-long European university hospital relationships and sustained kinetic perimetry platform investment. Topcon Corporation represents the Asia-Pacific distribution specialist archetype, with localized service networks and region-specific software interfaces dominating procurement evaluations across Japan, India, and Southeast Asia.
| Leading Market Players |
|---|
| Carl Zeiss Meditec |
| Haag-Streit |
| Topcon Corporation |
| Nidek Co., Ltd. |
| Optopol Technology |
| Medmont |
| Heidelberg Engineering |
| Kowa Company |
| Metrovision |
| Others |
Supply & Pricing Matrix
Consolidated hospital networks in Germany and the United States command equipment procurement decisions that reshape pricing architectures across the automated ophthalmic perimeters landscape. Their unbundling of after-sales service contracts from capital purchases has fractured traditional vendor margin pools and created openings for independent service organizations.
Pricing Analysis
Service contract unbundling now defines price negotiation dynamics across North American and European procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates integrated OCT-perimetry workstations from standalone static perimeters and refurbished legacy systems. Pricing pressure stems from Medicare's Physician Fee Schedule compression in the United States, which squeezes per-test reimbursement and extends capital equipment payback periods. Independent eye care clinics in India and Brazil exhibit the highest price sensitivity, while university ophthalmology departments in Japan and Switzerland accept premium positioning for research-grade functionality.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement specifications for precision aspheric projection lenses across German and Japanese manufacturer supply chains. Component fabrication draws from southern Germany, Jena, and selected Japanese optics clusters for calibrated light projection systems, electromechanical positioning stages, and embedded stimulus control firmware. Single-source vulnerability concentrates in high-precision lens grinding capabilities, where tariff exposure on specialized optical glass creates margin volatility. Distribution runs through authorized dealer networks with mandatory field service certification, though direct hospital system contracts are gaining share in metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated ophthalmic perimeters market functions as a stable compounder anchored by irreversible demographic shifts toward aging populations requiring chronic glaucoma and retinal disease monitoring.
For Market Incumbents: Extend software-as-medical-device licensing models to capture recurring revenue from AI-enabled threshold progression analytics. Deepen captive supply of precision optics through backward integration into aspheric lens fabrication, countering supply concentration risks in southern Germany. Defend against hardware commoditization by embedding proprietary adaptive algorithms that lock clinical workflows into vendor-specific data formats. For New Entrants and Emerging Players: Cloud-connected telemedicine platforms represent the most penetrable white space for perimeter manufacturers lacking established service infrastructure. Australia's rural ophthalmology networks and Canadian provincial health systems offer procurement openings where remote visual field monitoring protocols are formalizing. Pursue regulatory sandbox pathways under FDA's predetermined change control plans to accelerate software algorithm commercialization without full hardware certification cycles. For Investors and Strategic Acquirers: Diversified ophthalmic diagnostic conglomerates are the most active acquirer in this space, seeking AI algorithm portfolios to complement hardware manufacturing scale. The market exhibits long-term viability through recurring service revenue attachment and software upgrade cycles rather than pure equipment replacement demand. Watch for PMDA software-as-medical-device classification precedents as the inflection signal triggering valuation repricing for algorithm-centric business models.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Licensing | FDA's predetermined change control plans enable recurring revenue streams from threshold analytics without hardware recertification. |
| OCT-Perimetry Convergence | Combined structural-functional workstations capture premium positioning in Singapore's and Switzerland's private retinal surgery centers. |
| Telemedicine Protocol Development | Cloud-connected perimeters penetrate Australia's rural ophthalmology networks where specialist access remains constrained. |
| EU MDR Compliance Investment | Harmonized classification rules for software-integrated diagnostics accelerate multi-country CE marking across Germany, France, and Italy. |
| Independent Service Organization Partnership | Calibration and maintenance revenue capture in North American metropolitan markets reaches 35% share outside traditional vendor channels. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation across regulatory filings and procurement databases. Triangulation incorporated interviews with hospital purchasing committee members, biomedical engineers at academic medical centers, GPO contracts managers, and ophthalmology department heads alongside secondary sources including FDA 510(k) premarket notification databases, EU MDR technical documentation repositories, PMDA quality management system audit records, and hospital capital equipment procurement records. Bottom-up equipment installation tracking and top-down market sizing approaches were reconciled to establish volume and value estimates.
Rate-of-change decomposition structured the analytical framework across the projection horizon, with growth drivers assessed by technology segment, application area, end-user category, and regional regulatory cluster. CAGRs were derived from installed base evolution, equipment refresh cycle compression or extension, and software licensing attachment rate trajectories. Forecast inputs incorporated Medicare Physician Fee Schedule reimbursement trajectory assumptions, EU MDR implementation timeline impacts on market access speed, and PMDA audit intensity evolution for AI-embedded devices.
Regulatory reclassification of AI-enabled diagnostic algorithms, reimbursement code restructuring for remote visual field testing, and supply chain disruption in precision optics fabrication are the dominant revision risks to the outlook. Deviation in PMDA software-as-medical-device classification stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Thyroid Eye Disease Treatment Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Global Glaucoma Treatment Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Eye Infections Treatment Market
Ophthalmology
Ophthalmic Operating Room Microscope Market
Ophthalmology
Global Ophthalmic Viscoelastic Devices Market
Ophthalmology
Brazil Ophthalmic Devices Market
Ophthalmology
Corneal Ulcer Treatment Market
Ophthalmology
Blepharitis Treatment Market