
 Pressure Redistribution Pads Market | 2026-2036
Pressure Redistribution Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Redistribution Pads Market Analytics
The split between premium reactive surfaces and commodity foam overlays is realigning how procurement teams evaluate total cost of ownership against clinical outcomes. Stryker leverages its integrated bed-system portfolio to bundle pad replacements with capital equipment contracts. Arjo sustains differentiation through dedicated bariatric and microclimate management sub-lines that command higher service attach rates.
Pressure redistribution pads are engineered support surfaces constructed from viscoelastic foam, silicone gel bladders, or alternating air cells designed to reduce interface pressure below capillary closure thresholds, typically targeting sustained loads under 32 mmHg for at-risk tissue. Their primary purpose is preventing hospital-acquired pressure injuries in immobilized patients during acute and post-acute recovery. Gel segments occupy the highest margin pools in surgical and ICU settings where shear reduction justifies premium positioning, while hybrid constructions combining foam bases with air-cell toppers represent the fastest-growing configuration as facilities seek dual-performance without full air-mattress capital expenditure. Foam dominates unit volume in long-term care where reimbursement constraints limit per-pad spending.
FDA 510(k) requirements and EU MDR technical documentation obligations are extending validation timelines and favoring manufacturers with established quality management systems and clinical evidence libraries. ISO 10993 biocompatibility testing and EN 60601-1-2 electromagnetic compatibility standards further filter market access for imported products. Stakeholders must monitor how CMS Hospital-Acquired Condition penalty adjustments and Joint Commission accreditation surveys reshape facility-level compliance spending and replacement cycles.
Market Dynamics
Hospital procurement departments now bundle pressure redistribution pads with capital equipment contracts, compressing standalone pad margins while elevating total-system competition. This bundling dynamic favors manufacturers with integrated bed portfolios and punishes pure-play pad suppliers.
Growth Catalysts
- EU MDR compliance deadlines:Facilities across Germany and France are accelerating replacement cycles to meet technical documentation obligations, creating pull-through demand for validated gel and hybrid surfaces.
- ICU capacity expansion:United States health systems are adding specialized critical care units, each requiring pressure injury prevention protocols that specify reactive support surfaces.
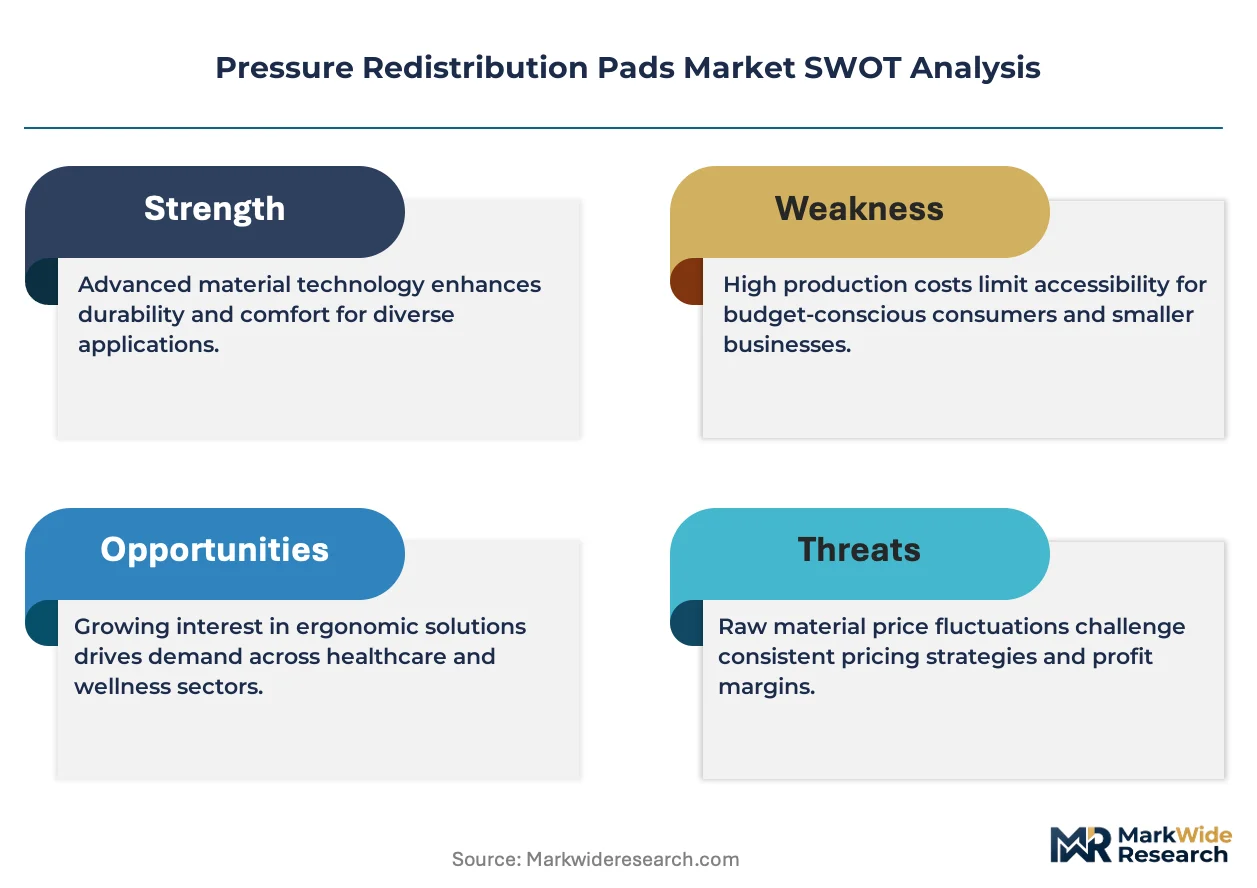
- Silicone gel bladder technology:Advances in multi-chamber gel construction reduce shear forces below 25 mmHg, justifying premium positioning in surgical recovery wards.
Market Restraints
- Polyurethane foam input volatility:Raw material costs for viscoelastic foam bases fluctuate with petrochemical feedstock prices, squeezing margin on commodity overlay segments.
- Supply concentration in East Asian contract manufacturers:A limited number of specialized foam fabricators control high-volume production, creating vulnerability to regional logistics disruptions.
- Reimbursement ceilings in long-term care:Medicaid per-diem rates in United States skilled nursing facilities cap allowable spending on pressure redistribution equipment.
Strategic Opportunities
- Home-based acute care expansion:United States Medicare waiver programs for hospital-at-home models create demand for portable, patient-owned pressure redistribution surfaces.
- Microclimate management integration:Convergence of moisture-wicking textiles with active cooling layers opens premium positioning for bariatric and burn unit applications.
- Japan's geriatric infrastructure buildout:METI-funded long-term care facility modernization mandates specify pressure ulcer prevention equipment, opening import channels for compliant manufacturers.
Industry Challenges
- ISO 10993 biocompatibility validation timelines:Extended cytotoxicity and sensitization testing protocols delay new material introductions by 14-18 months.
- Electromagnetic compatibility certification for powered hybrids:EN 60601-1-2 testing requirements for alternating air-cell systems add engineering overhead and third-party audit costs.
- Integration complexity with legacy nurse call systems:Smart pad connectivity protocols must interface with decade-old hospital IT infrastructure, requiring backward-compatible hardware design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Redistribution Pads Market |
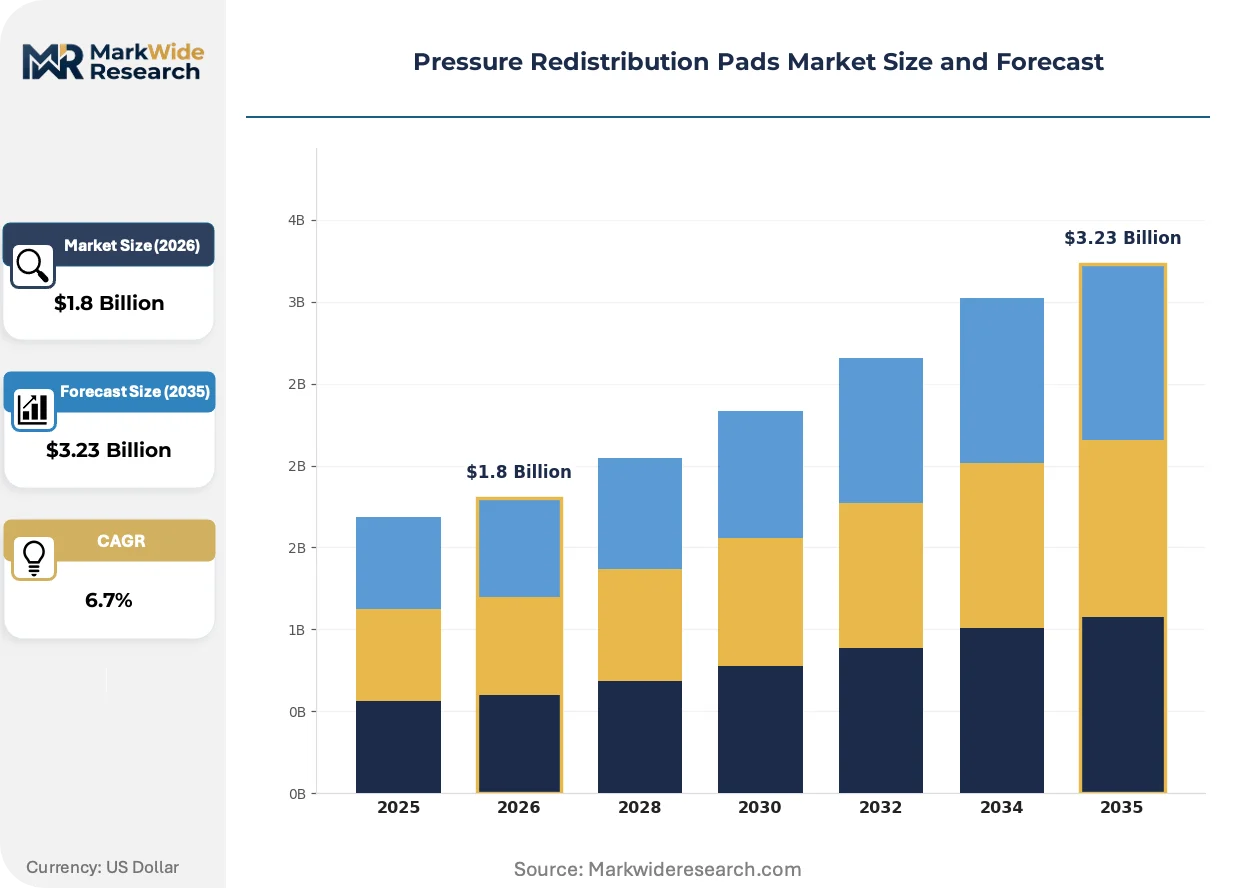
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Gel, Air, Hybrid End User: Healthcare Facilities, Homecare, Rehabilitation Centers, Long-term Care Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Wholesalers Application: Post-operative Care, Pressure Ulcer Prevention, Wound Management, Comfort Enhancement |
| Companies Covered | Getinge, Arjo, Stryker, EHOB, Action Products, Hill-Rom Holdings, Permobil, Talley Group, Invacare Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Redistribution Pads Market Evolving Landscape
Sensor-embedded pressure redistribution surfaces are transforming passive support into active monitoring infrastructure, generating real-time tissue perfusion data that feeds clinical decision support systems.
Capacitive pressure mapping arrays woven into gel pad substrates is automating the detection of sustained high-pressure zones, alerting nursing staff before tissue ischemia develops. United States academic medical centers are piloting these systems in neuro-ICU settings, where immobilized patients face elevated pressure injury risk. The technology is compressing response times from scheduled two-hour turns to immediate intervention, reducing reliance on manual skin assessment protocols.
EU MDR Article 10 technical documentation requirements are forcing manufacturers to maintain clinical evidence libraries for each product code, not merely device families. This obligation is extending design validation cycles and favoring incumbents with established post-market surveillance systems. German notified bodies are applying stricter scrutiny to foam formulations with additive flame retardants, pushing suppliers toward inherently fire-resistant silicone constructions.
Group purchasing organizations are consolidating contract awards for pressure redistribution equipment, reducing the number of approved suppliers per health system from six to two or three. United States hospital networks now negotiate multi-year enterprise agreements that bundle pads, mattresses, and service contracts, displacing spot purchasing by individual unit managers. This concentration is most visible in the Southeast, where regional GPOs cover multiple states under single sourcing frameworks.
Pressure Redistribution Pads Market Segmentation
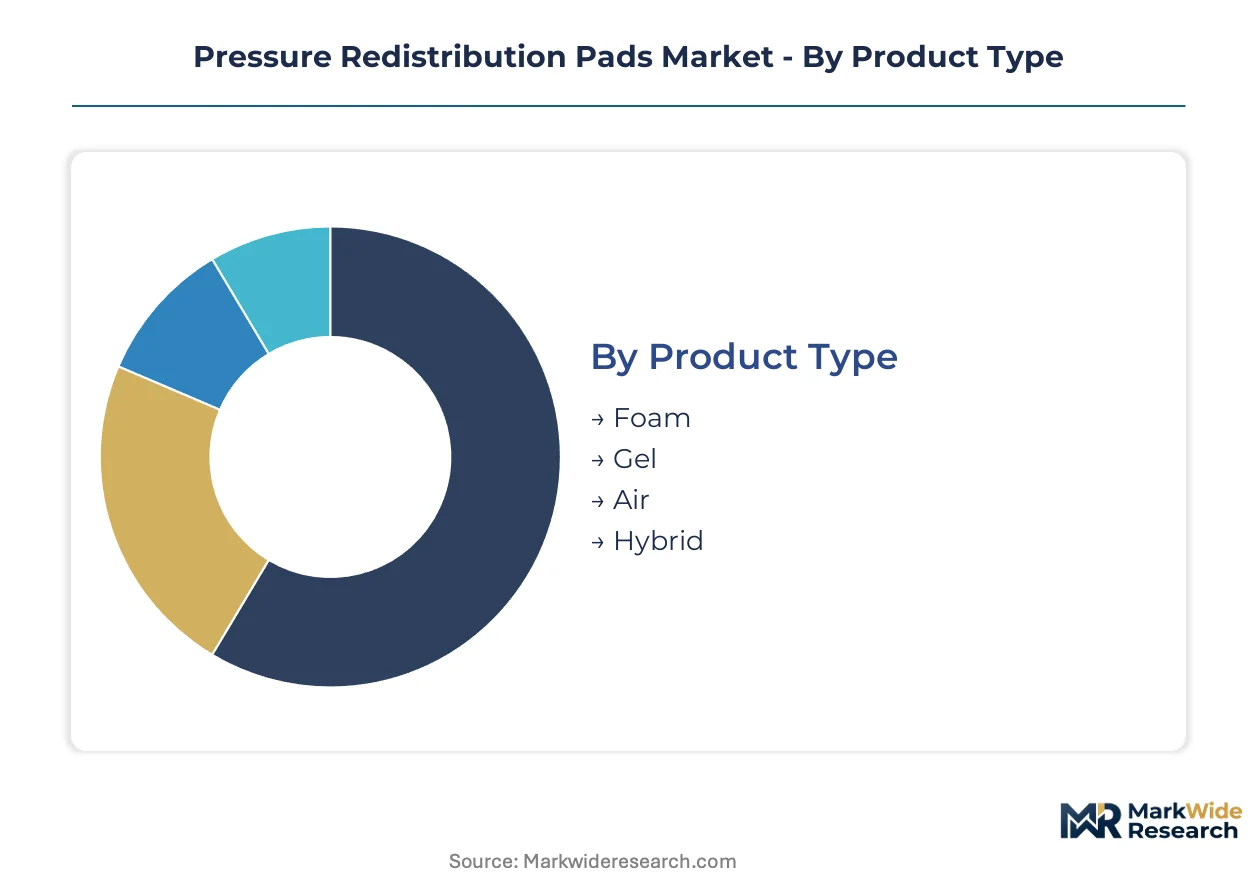
Pressure redistribution pads serve distinct clinical workflows ranging from embedded bed-system components to standalone overlays for rental programs. Segmentation reveals how material science, procurement channel, and care setting intersect to determine margin structure and replacement velocity.
Product Type:
Integration depth varies sharply across material platforms, with some segments designed as permanent bed attachments and others as portable, patient-transferable surfaces.
- Foam:Viscoelastic polyurethane constructions dominate long-term care procurement where per-unit cost ceilings constrain capital outlay. Medicaid reimbursement rates in United States skilled nursing facilities cap allowable spending, compressing margins on commodity overlays while sustaining high placement volumes.
- Gel:Multi-chamber silicone bladders reduce shear forces below 25 mmHg interface pressure, commanding premium positioning in surgical recovery and neuro-ICU settings where tissue perfusion monitoring justifies higher expenditure. German hospital procurement departments specify gel surfaces for bariatric wards under EU MDR technical documentation requirements.
- Air:Alternating-cell systems with powered pumps serve immobilized patients requiring active pressure cycling, though electromagnetic compatibility certification under EN 60601-1-2 adds engineering overhead.
- Hybrid:Foam-base constructions with air-cell toppers balance performance against capital constraints, gaining traction in United States health systems expanding ICU capacity without full air-mattress infrastructure investment.
Volume placements concentrate in foam; the faster expansion belongs to hybrid configurations bridging performance and procurement constraints.
End User:
Care setting determines regulatory exposure and replacement cycle length, with acute facilities facing Joint Commission scrutiny and home settings subject to Medicare waiver portability requirements.
- Healthcare Facilities:Hospital procurement departments bundle pad replacements with capital equipment contracts, compressing standalone margins while elevating total-system competition. FDA 510(k) clearance pathways shape validation timelines for new material introductions.
- Homecare:Portable surfaces for hospital-at-home programs require lightweight construction and patient-owned durability, creating demand for gel-over-foam laminates that withstand repeated cleaning without degradation.
- Rehabilitation Centers:Intermediate-acuity settings prioritize rapid patient turnover and surface sanitization, favoring seamless welded-bladder gel pads over sewn constructions with moisture ingress risk.
- Long-term Care:Medicaid per-diem rate structures in United States skilled nursing facilities limit equipment spending, channeling procurement toward basic foam overlays with extended replacement intervals.
Procurement scale peaks in healthcare facilities; reimbursement flexibility is expanding fastest in homecare.
Distribution Channel:
Channel selection reflects customer technical sophistication and contract consolidation trends reshaping supplier access.
- Online Retail:E-commerce platforms serve homecare patients and small clinical practices with standardized SKU offerings, though limited technical consultation capability constrains complex hybrid system sales.
- Medical Supply Stores:Regional distributors maintain local inventory for emergency replacement and rental programs, particularly in Japan's long-term care facility network.
- Direct Sales:Manufacturer field representatives negotiate enterprise agreements with United States hospital networks, bundling pads with bed systems and service contracts under multi-year frameworks.
- Wholesalers:Group purchasing organizations consolidate contract awards across Southeast regional health systems, reducing approved supplier counts from six to two or three per network.
Transaction velocity runs highest through wholesalers; margin preservation depends most critically on direct sales relationships.
Application:
Clinical purpose drives specification intensity, with prevention protocols commanding stricter performance validation than comfort-oriented placements.
- Post-operative Care:Surgical recovery wards specify gel surfaces with microclimate management layers to manage perspiration and shear during extended immobilization, particularly in bariatric patient populations.
- Pressure Ulcer Prevention:CMS Hospital-Acquired Condition penalty adjustments sharpen facility compliance spending on reactive support surfaces, with sensor-embedded pads generating real-time tissue perfusion data for clinical decision support.
- Wound Management:Existing pressure injury treatment requires offloading surfaces with documented interface pressure below 32 mmHg, validated through ISO 10993 biocompatibility testing for direct wound contact.
- Comfort Enhancement:General ward applications tolerate higher pressure thresholds, accepting basic viscoelastic foam where reimbursement constraints limit equipment expenditure.
Regulatory scrutiny intensifies around pressure ulcer prevention; comfort enhancement offers the most pricing latitude.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American procurement concentration for pressure redistribution equipment, with hospital networks headquartered there negotiating enterprise contracts that span multi-state coverage areas and bundle pad replacements with capital bed-system purchases.
United States
CMS Hospital-Acquired Condition penalty adjustments sharpen facility compliance spending on reactive support surfaces across Texas Medical Center corridors and Southeast regional networks. FDA 510(k) clearance pathways shape validation timelines for new gel and hybrid material introductions. Academic medical centers in Boston and Philadelphia pilot sensor-embedded pads generating real-time tissue perfusion data for clinical decision support systems.
Germany
EU MDR technical documentation obligations accelerate replacement cycles in Bavarian and North Rhine-Westphalian hospital systems seeking validated gel surfaces. German notified bodies apply stricter scrutiny to foam formulations with additive flame retardants, pushing suppliers toward inherently fire-resistant silicone constructions. Medical device clusters around Tübingen and Leipzig concentrate gel bladder fabrication and post-market surveillance operations.
Japan
METI-funded long-term care facility modernization mandates specify pressure ulcer prevention equipment, opening import channels for compliant manufacturers serving Osaka-Kobe and Nagoya manufacturing belts. Japan's geriatric infrastructure buildout concentrates procurement authority in prefectural health bureaus negotiating standardized equipment specifications. Regional distributors in Tokyo-Yokohama maintain inventory for emergency replacement across the homecare network.
United Kingdom
NHS England procurement frameworks consolidate pressure redistribution equipment awards under single-source agreements covering multiple trust regions, reducing approved supplier counts from six to two or three per network. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements extends validation timelines for new material introductions. Manufacturing concentration in Midlands medical device corridors supplies gel and hybrid surfaces for both domestic deployment and EU re-export channels.
Canada
Health Canada Medical Device License requirements parallel FDA 510(k) pathways, enabling cross-border regulatory efficiency for manufacturers serving Ontario and Quebec hospital procurement authorities. Provincial health ministry equipment standardization programs concentrate purchasing decisions in Toronto and Montreal administrative centers. Western Canada long-term care expansion in British Columbia and Alberta channels demand toward basic foam overlays constrained by per-diem reimbursement structures.
Pressure Redistribution Pads Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material sophistication and service attach rate dimensions. Integrated bed-system manufacturers command higher total contract values by bundling pad replacements with capital equipment purchases, while pure-play pad suppliers compete on replacement velocity and rental program flexibility. Three archetypes dominate: diversified medtech conglomerates with hospital bed portfolios, specialized surface manufacturers with dedicated bariatric and microclimate sub-lines, and regional contract fabricators serving long-term care procurement channels. Competitive moves concentrate on multi-year enterprise agreement negotiation and GPO contract consolidation across Southeast and Midwest health networks.
Among diversified medtech conglomerates, Stryker and Getinge represent the integrated-system archetype, leveraging capital equipment relationships to secure recurring pad replacement revenue. Arjo occupies a position within the specialized surface tier, with its corporate structure reflecting dedicated focus on patient handling and pressure injury prevention equipment. EHOB exemplifies the regional contract fabricator model, with its corporate designation suggesting concentrated operational footprint in specific geographic markets. These three anchors demonstrate how competitive positioning stratifies across bundled-system, specialized-performance, and cost-optimized procurement channels.
| Leading Market Players |
|---|
| Getinge |
| Arjo |
| Stryker |
| EHOB |
| Action Products |
| Hill-Rom Holdings |
| Permobil |
| Talley Group |
| Invacare Corporation |
| Others |
Value Network & Pricing Analysis
EU MDR technical documentation deadlines are forcing hospital procurement departments across Germany and France to accelerate replacement cycles for validated gel and hybrid surfaces, compelling contract manufacturers in East Asia to requalify foam formulations and extend lead times for silicone bladder components. This specification-driven demand surge is compressing margins on commodity foam overlays while elevating pricing power for suppliers with established clinical evidence libraries and fire-resistant material certifications.
Pricing Analysis
Value-based pricing anchored to pressure ulcer prevention outcomes dominates acute care procurement, with gel surfaces commanding premiums tied to documented interface pressure reduction below 25 mmHg. Three-tier pricing structure across premium, standard, and economy levels separates sensor-embedded reactive systems from basic viscoelastic foam, with FDA 510(k) clearance tier and ISO 10993 biocompatibility grade serving as primary differentiation drivers. Pricing pressure stems from GPO contract consolidation across Southeast United States health networks, compressing standalone pad margins. Long-term care facilities exhibit highest price sensitivity due to Medicaid per-diem rate ceilings, while neuro-ICU units demonstrate lowest sensitivity where clinical outcomes justify premium expenditure.
Supply Chain Analysis
Refurbishment and rental program flows for pressure redistribution pads concentrate in regional medical supply distributors across Japan's prefectural health networks and United States homecare channels, creating reverse-logistics revenue streams that subsidize new product pricing. Manufacturing gravity centers on China, South Korea, and specialized foam fabricators in Germany for silicone gel bladder production. Raw material dependencies include viscoelastic polyurethane feedstocks, medical-grade silicone, and antimicrobial textile coatings. Single-source vulnerability concentrates in East Asian contract manufacturers controlling high-volume foam fabrication. Distribution runs through group purchasing organizations consolidating multi-year enterprise agreements with United States hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-embedded pressure redistribution surfaces are displacing passive support pads across academic medical centers, with capacitive pressure mapping arrays automating tissue perfusion monitoring and compressing nursing response times from scheduled turns to immediate intervention.
For Market Incumbents: Deepen vertical integration into silicone gel bladder fabrication to secure supply continuity against East Asian manufacturing concentration, while expanding ISO 10993 biocompatibility testing capacity to accelerate EU MDR validation timelines. Defend position against pure-play sensor technology entrants by bundling smart pad connectivity with legacy nurse call system backward compatibility, leveraging installed base relationships across Midwest and Southeast hospital networks. For New Entrants and Emerging Players: Direct-to-patient e-commerce channels offer the most penetrable route for portable gel-over-foam laminates serving United States hospital-at-home Medicare waiver programs, where reimbursement flexibility exceeds institutional procurement constraints. Target bariatric and burn unit applications with microclimate-integrated surfaces, exploiting incumbent blind spots in premium sub-segments. Pursue white-label manufacturing partnerships with Japanese regional distributors to access METI-funded long-term care modernization procurement. For Investors and Strategic Acquirers: The window for entry favors specialized surface manufacturers with dedicated bariatric sub-lines and established post-market surveillance systems under EU MDR Article 10. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. Target acquisition profile centers on mid-cap gel bladder fabricators with German notified body relationships. Monitor CMS Hospital-Acquired Condition penalty adjustment announcements as inflection indicators for facility-level compliance spending acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market access for gel and hybrid surfaces across German hospital systems. |
| Sensor-Embedded Pad Development | Captures real-time tissue perfusion data for neuro-ICU clinical decision support. |
| Hospital System Partnership | Secures multi-year enterprise agreements bundling pads with bed system replacements. |
| Backward Integration into Silicone Supply | Reduces vulnerability to East Asian contract manufacturer concentration. |
| Hospital-at-Home Distribution Channel | Accesses Medicare waiver portability requirements for patient-owned surfaces. |
Research Methodology
FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract records formed the secondary backbone, supplemented by customs trade data for viscoelastic polyurethane and medical-grade silicone imports. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and long-term care facility administrators validated segmentation assumptions and replacement cycle estimates. Bottom-up and top-down triangulation reconciled unit placement data from regional distributors with capital equipment expenditure patterns reported in health system financial disclosures.
Bottom-up modeling projected segment-level expansion across material platforms, end-user settings, and distribution channels over the analysis window. Top-down validation cross-checked aggregate figures against CMS Medicare spending patterns and METI-funded equipment procurement disclosures. CAGRs derived from fitted growth curves incorporating ICU capacity expansion timelines, EU MDR compliance deadlines, and geriatric infrastructure buildout schedules in Japan. Industry-specific forecast inputs included polyurethane feedstock price volatility indices and Joint Commission accreditation survey frequency trends.
The model holds under stable regulatory enforcement intensity and continued hospital-at-home program expansion; deviation in CMS penalty adjustment severity or East Asian logistics disruption would shift replacement velocity assumptions. Practitioners should monitor FDA guidance document updates for sensor-embedded surfaces and German notified body flame retardant scrutiny for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Absorbable Surgical Sutures Market
Medical Supplies
Veterinary Suture Kit Market
Medical Supplies
Anti-Adhesion Barrier Gels Market
Medical Supplies
Japan Hospital Supplies Market
Medical Supplies
Pressure Relief Mattress Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Skin Traction Kits Market
Medical Supplies
Luer Lock Syringe Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Nitrile Gloves Market
Medical Supplies
Nasal Oxygen Cannula Market
Medical Supplies
Global Medical Waste Containers Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Global Hospital Supplies Market
Medical Supplies
Blood Bags Market
Medical Supplies
Antibacterial Haemostatic Gels Market