
 Patch Based Wound Healing Products Market | 2026-2036
Patch Based Wound Healing Products Market Size, Share, and Industry Trends Forecast 2026-2036
Patch Based Wound Healing Products Market Outlook
The EU Medical Device Regulation is restructuring demand for patch based wound healing products across European healthcare systems. Mölnlycke Health Care AB leverages its Nordic manufacturing base to sustain supply chain continuity for advanced dressings. Integra LifeSciences Corporation anchors its position through regenerative tissue expertise in chronic wound applications. Smith & Nephew plc competes on antimicrobial technology leadership in surgical wound segments.
Patch based wound healing products comprise adhesive-backed dressings engineered from hydrocolloid, foam, alginate, or transparent film substrates, typically measuring 5 to 20 cm in active surface area, designed to maintain moist wound environments while permitting controlled moisture vapor transmission. Hydrocolloid dressings dominate current volume due to established reimbursement codes and clinician familiarity across hospital settings. Alginate dressings represent the fastest-expanding category, driven by rising diabetic foot ulcer incidence and superior exudate management in heavily draining wounds. Chronic wounds command the largest application share, reflecting the sustained clinical burden of venous leg ulcers and pressure injuries in aging populations.
The FDA enforces biocompatibility and sterility standards under 21 CFR Part 820 quality system regulations, while the EMA's MDR transition demands enhanced clinical performance documentation for wound care device approvals. Japan's PMDA maintains distinct pharmaceutical affairs law requirements that shape product registration timelines for foreign manufacturers. Stakeholders must monitor evolving reimbursement thresholds for bioactive dressings and antimicrobial variants as health technology assessment bodies recalibrate cost-effectiveness criteria.
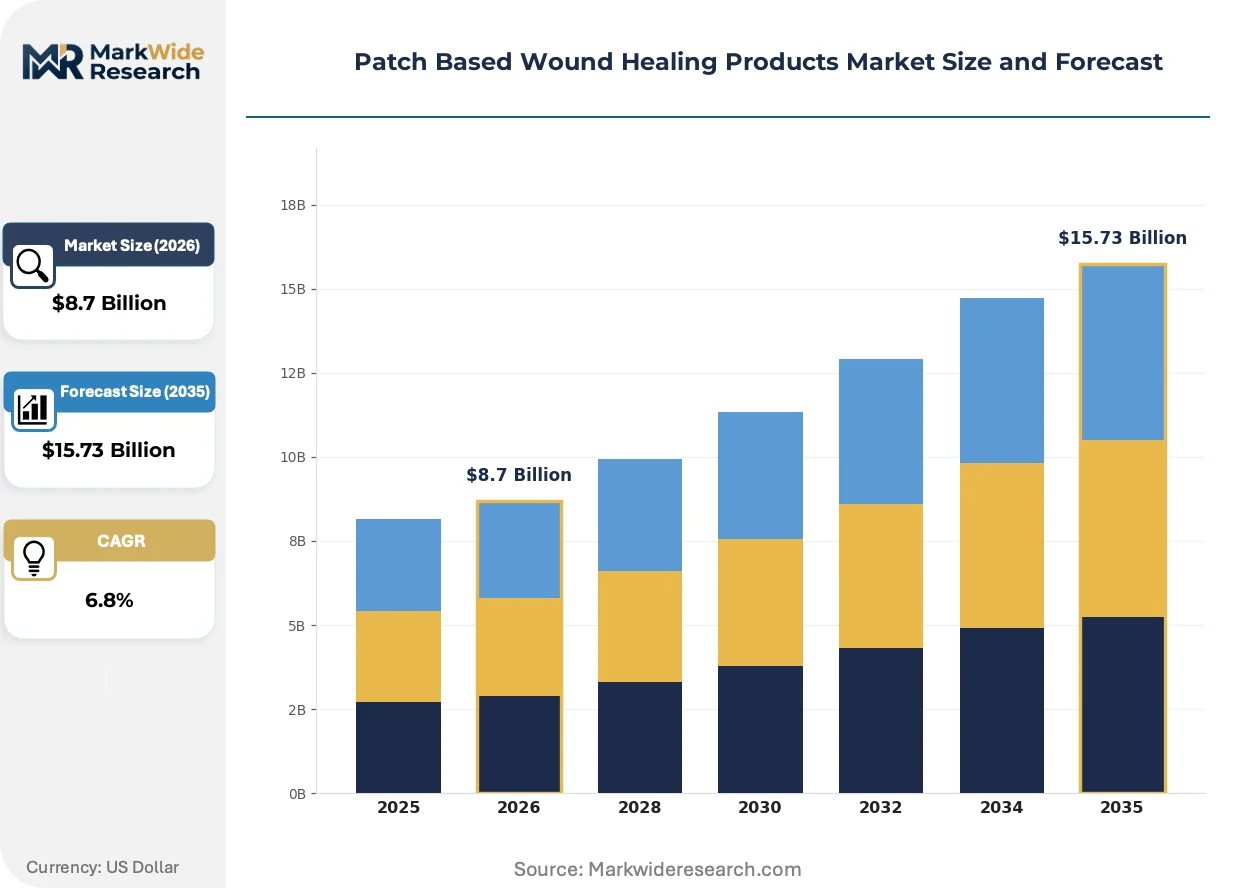
Market Dynamics
The EU Medical Device Regulation is compressing product approval timelines and forcing manufacturers to rebuild clinical evidence portfolios for existing wound care portfolios. This regulatory recalibration is redistributing competitive advantage toward firms with established notified body relationships and robust post-market surveillance infrastructure.
Growth Catalysts
- MDR Clinical Evidence Mandate:The European Union's tightened requirements for wound care device approvals are filtering out marginal competitors and consolidating market share among compliant manufacturers with established quality management systems.
- Diabetic Foot Ulcer Incidence:Rising diabetes prevalence in Germany, Japan, and the United States is expanding the addressable patient pool for advanced exudate-managing dressings across hospital and homecare channels.
- Silver-Ion Antimicrobial Integration:Wound care manufacturers are embedding ionic silver into hydrocolloid and foam substrates to address surgical site infection protocols in tertiary care facilities.
Market Restraints
- Alginate Raw Material Concentration:Seaweed harvesting for alginate production concentrates in coastal regions of France and Norway, exposing manufacturers to climate-related supply interruptions and price volatility.
- Reimbursement Compression:Health technology assessment bodies in Germany and England are narrowing coverage criteria for premium bioactive dressings, forcing price convergence toward standard hydrocolloid benchmarks.
- Silicone Adhesive Substitution:Acrylic-based alternatives in low-exudate applications are capturing volume in cost-sensitive homecare segments where moisture management requirements are less stringent.
Strategic Opportunities
- Japanese Homecare Expansion:METI's push for post-acute care decentralization is opening dedicated reimbursement channels for self-applied patch dressings in Tokyo and Osaka metropolitan corridors.
- Wearable Biosensor Convergence:Integration of pH and temperature sensing films with passive dressings is enabling real-time wound monitoring for venous leg ulcer patients in remote care settings.
- Antimicrobial Stewardship Tailwinds:NHS England's reduction targets for systemic antibiotics in wound management are elevating demand for topical antimicrobial dressings in chronic wound protocols.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity and sensitization studies face extended queue times at contracted laboratories, delaying MDR technical documentation submissions.
- Legacy Sterilization Requalification:Ethylene oxide facility closures in the United States are forcing manufacturers to validate gamma irradiation alternatives for moisture-sensitive hydrocolloid formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patch Based Wound Healing Products Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocolloid Dressings, Foam Dressings, Transparent Film Dressings, Alginate Dressings End User: Hospitals, Clinics, Homecare Settings, Nursing Facilities Application: Chronic Wounds, Surgical Wounds, Burns, Traumatic Injuries Material: Polyurethane, Cotton, Silk, Synthetic Polymers |
| Companies Covered | Mölnlycke Health Care AB, Integra LifeSciences Corporation, 3M Company, Johnson & Johnson, B. Braun Melsungen AG, ConvaTec Group plc, Coloplast A/S, Organogenesis, Inc., Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patch Based Wound Healing Products Market Strategic Shifts
Antimicrobial functionality is migrating from adjunct topical agents into primary dressing substrates, while regulatory data requirements are reshaping R&D investment allocation across the competitive landscape.
Electrospun nanofiber matrices are integrating antimicrobial peptides directly into wound contact layers, eliminating the need for separate silver or iodine applications. Academic medical centers in Boston and Heidelberg are piloting these materials for burn and trauma applications where infection control is paramount. This convergence of material science and pharmaceutical delivery is integrating sustained-release pharmacology into passive dressing categories previously defined by physical barrier properties.
The FDA's 21 CFR Part 820 quality system regulations are intensifying scrutiny of sterilization validation documentation for single-use wound care devices. Manufacturers must now demonstrate continuous process monitoring rather than batch-release testing alone. Surgical wound segments in the United States are responding by consolidating supplier relationships toward firms with vertically integrated sterilization assets.
Hospital procurement departments are unbundling wound care purchasing from broader surgical supply contracts, creating direct negotiation channels for dressing manufacturers. Group purchasing organizations are losing leverage as individual health systems develop category-specific clinical value analysis committees. This behavioral shift is most visible in the United States, where IDN consolidation has concentrated enough volume to justify dedicated sourcing infrastructure for advanced wound management products.
Patch Based Wound Healing Products Market Segmentation
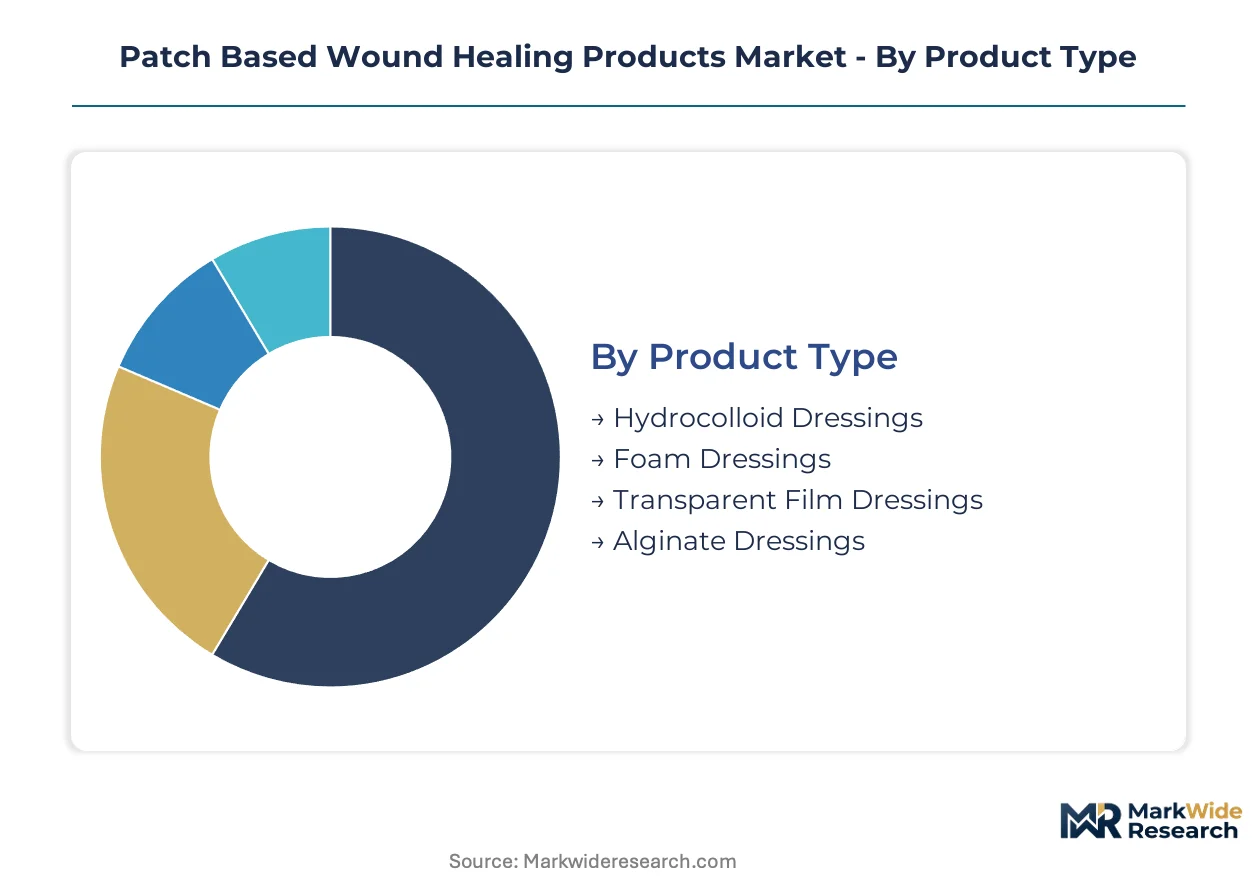
Segmentation in patch-based wound healing reveals how clinical requirements, reimbursement structures, and patient acuity reshape procurement priorities across healthcare delivery channels. Manufacturers configure product portfolios around end-use economics rather than uniform technical specifications.
Product Type:
Cost tier differentiation separates commodity hydrocolloid volumes from premium alginate margins in hospital formulary negotiations.
- Hydrocolloid Dressings:Gel-forming carboxymethylcellulose matrices bonded to polyurethane backings absorb exudate while maintaining moist wound interfaces. Demand concentrates in United States hospital outpatient departments where established CPT reimbursement codes accelerate procurement velocity. MDR compliance costs are compressing margins for mid-tier European suppliers lacking scale economies.
- Alginate Dressings:Calcium-sodium alginate fibers derived from Laminaria hyperborea seaweed create highly absorbent gels upon contact with wound fluid. German diabetic foot clinics in North Rhine-Westphalia are expanding alginate protocols for heavily exuding ulcers, driven by superior fluid retention versus hydrocolloid alternatives. Seaweed supply concentration in coastal Norway exposes manufacturers to climate-related harvest volatility.
- Foam Dressings:Hydrophilic polyurethane foam layers with silicone contact layers manage moderate-to-heavy exudate in pressure injury protocols.
- Transparent Film Dressings:Semi-permeable polyurethane membranes enable visual wound monitoring without dressing removal in autolytic debridement applications.
Hydrocolloid dressings lead volumes today; alginate dressings are gaining share fastest.
End User:
Procurement authority and clinical decision-making autonomy diverge sharply across institutional versus decentralized care settings.
- Hospitals:Tertiary care facilities with dedicated wound care centers drive specification for advanced antimicrobial and bioactive dressings through value analysis committees. United States integrated delivery networks in Texas and Florida are consolidating purchasing toward single-source agreements with vertically integrated suppliers. FDA 21 CFR Part 820 quality system documentation requirements favor established manufacturers with dedicated regulatory affairs infrastructure.
- Homecare Settings:Self-administered dressing changes by venous leg ulcer patients in Tokyo and Osaka metropolitan corridors are expanding under METI's post-acute care decentralization initiatives. Japanese reimbursement channels for self-applied patches are opening dedicated procurement pathways distinct from institutional purchasing. Remote monitoring integration is elevating technical requirements for patient-applied products.
- Clinics:Outpatient wound care centers balance clinical efficacy against Medicare reimbursement constraints for chronic wound episodes.
- Nursing Facilities:Long-term care operators in Germany face Bundestag-mandated pressure injury reduction targets that standardize dressing protocols across regional operator chains.
Hospitals anchor absolute demand; homecare settings are climbing the fastest.
Application:
Volume concentration and margin structure invert between acute episode management and chronic condition maintenance.
- Chronic Wounds:Venous leg ulcers and pressure injuries in aging populations sustain recurring demand cycles measured in months rather than days. England's NHS antimicrobial stewardship protocols are elevating topical dressing specifications over systemic antibiotic prescriptions for infected chronic wounds. Reimbursement compression through NICE health technology assessments is narrowing coverage for premium bioactive variants.
- Surgical Wounds:Tertiary care surgical site infection prevention protocols in Boston and Heidelberg academic medical centers are embedding antimicrobial functionality into primary dressing substrates. Silver-ion integration into hydrocolloid and foam matrices addresses institutional infection control mandates without separate topical applications.
- Burns:Specialized burn centers require conformable dressing architectures for irregular wound topography and high exudate management.
- Traumatic Injuries:Emergency department and field trauma applications prioritize rapid application and hemostatic performance over long-term moisture management.
Chronic wounds dominate absolute volumes; surgical wounds show the steepest expansion trajectory.
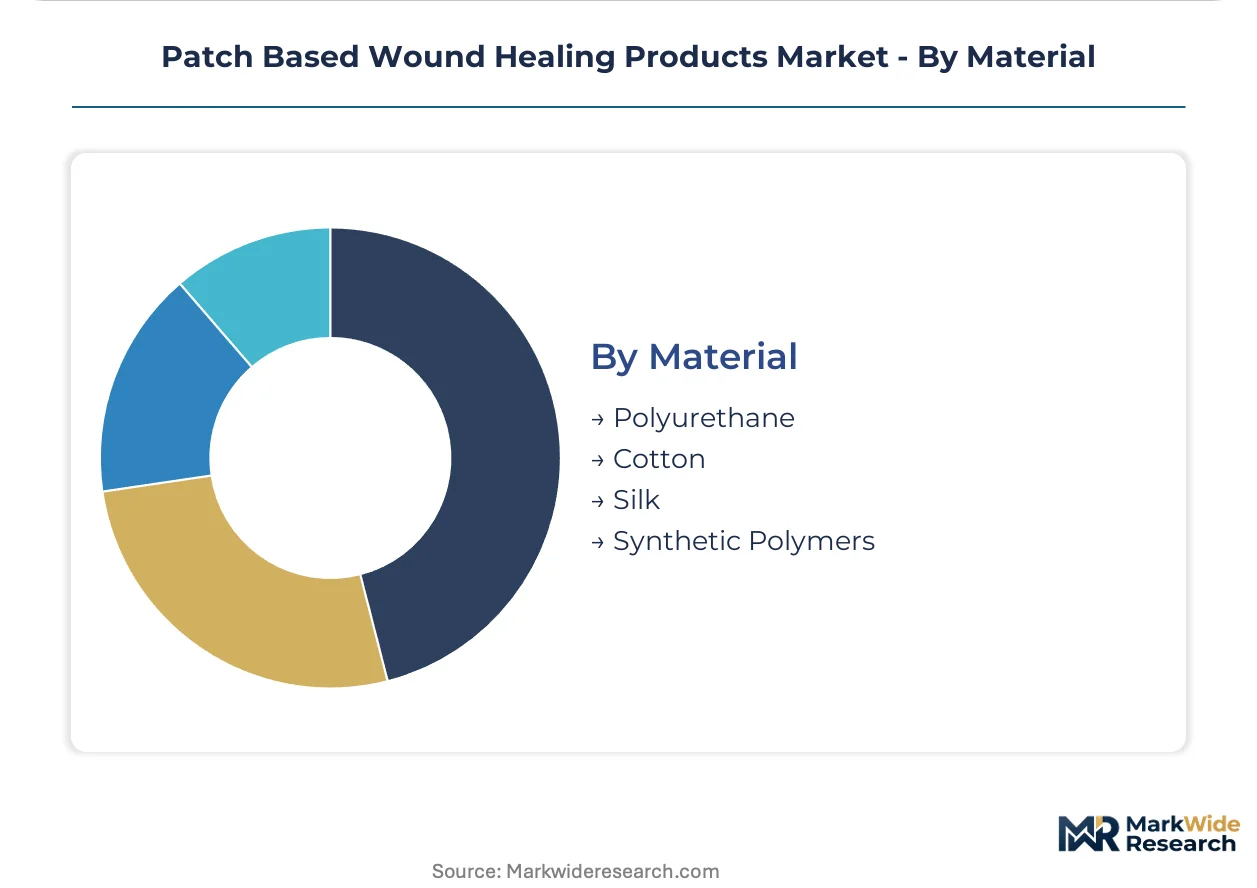
Material:
Supply chain geography and biocompatibility testing burden differentiate synthetic from natural substrate economics.
- Polyurethane:Backing films and foam matrices manufactured from aromatic or aliphatic polyurethane precursors dominate moisture vapor transmission rate engineering. United States ethylene oxide sterilization facility closures are forcing gamma irradiation validation for moisture-sensitive polyurethane foam formulations. ISO 10993 cytotoxicity study queue times at contracted laboratories are extending technical documentation timelines.
- Synthetic Polymers:Electrospun nanofiber matrices integrating antimicrobial peptides directly into wound contact layers eliminate separate silver or iodine applications. Academic medical center pilot programs in Boston are validating sustained-release pharmacology integration into passive dressing categories.
- Cotton:Woven and non-woven cotton substrates retain position in cost-sensitive applications where moisture management requirements are less stringent.
- Silk:Fibroin-based matrices offer biocompatible alternatives for patients with contact sensitization to synthetic substrates.
Polyurethane leads volumes today; synthetic polymers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern wound dressing technology traces its commercial origins to mid-20th century hydrocolloid innovations developed in British and Swedish laboratories, with subsequent scaling concentrated in North American and European manufacturing corridors. FDA's 21 CFR Part 820 quality system regulations and the EU MDR now govern the dominant production geographies, while Japanese and German demand centers drive specialized product evolution.
United States
Integrated delivery networks in Texas and Florida consolidate purchasing toward single-source agreements with suppliers possessing vertically integrated sterilization assets. FDA enforcement of biocompatibility documentation under ISO 10993-5 cytotoxicity standards extends technical submission timelines. Boston academic medical centers pilot electrospun nanofiber matrices integrating antimicrobial peptides for burn and trauma applications.
Germany
Diabetic foot clinics in North Rhine-Westphalia expand alginate protocols for heavily exuding ulcers, driven by superior fluid retention requirements. The Bundestag mandates pressure injury reduction targets that standardize dressing protocols across regional long-term care operator chains. Mölnlycke Health Care AB leverages its Nordic manufacturing base to sustain supply chain continuity for advanced dressings distributed through German hospital networks.
Japan
METI's post-acute care decentralization initiatives open dedicated reimbursement channels for self-applied patch dressings in Tokyo and Osaka metropolitan corridors. PMDA maintains distinct pharmaceutical affairs law requirements that shape product registration timelines for foreign manufacturers. Remote monitoring integration elevates technical specifications for patient-applied products in homecare settings.
United Kingdom
NHS England's antimicrobial stewardship reduction targets for systemic antibiotics elevate demand for topical antimicrobial dressings in chronic wound protocols. NICE health technology assessments narrow coverage criteria for premium bioactive variants, forcing price convergence toward standard benchmarks. Procurement unbundling from broader surgical supply contracts creates direct negotiation channels for dressing manufacturers.
France
Seaweed harvesting for alginate production concentrates in coastal regions, exposing manufacturers to climate-related supply interruptions and price volatility. ANSM oversight of medical device vigilance systems shapes post-market surveillance requirements for wound care portfolios. Academic research clusters in Paris and Lyon advance sustained-release pharmacology integration into passive dressing categories.
Patch Based Wound Healing Products Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory compliance capability and clinical evidence depth. The vendor base stratifies between multinational diversified healthcare conglomerates with dedicated wound care divisions and specialized mid-cap manufacturers with concentrated advanced dressing portfolios. Three archetypes dominate: diversified medical technology conglomerates with broad surgical portfolios, pure-play wound care specialists with Nordic or British heritage, and regenerative medicine platforms extending into chronic wound applications. Competitive dynamics center on M&A consolidation of antimicrobial technology assets and backward integration into captive alginate and polyurethane substrate production.
Among diversified healthcare conglomerates, 3M Company and Johnson & Johnson occupy positions spanning industrial materials through consumer health portfolios. Smith & Nephew plc exemplifies the wound care specialist archetype with British heritage and concentrated expertise in antimicrobial technology leadership. Integra LifeSciences Corporation anchors the regenerative medicine platform segment, extending tissue engineering capabilities into chronic wound applications. These three entities represent distinct strategic postures: materials science breadth, clinical segment focus, and biological platform extension.
| Leading Market Players |
|---|
| Mölnlycke Health Care AB |
| Integra LifeSciences Corporation |
| 3M Company |
| Johnson & Johnson |
| B. Braun Melsungen AG |
| ConvaTec Group plc |
| Coloplast A/S |
| Organogenesis, Inc. |
| Smith & Nephew plc |
| Others |
Value Chain & Pricing Dynamics
Backward integration into alginate substrate production anchors both supply security and margin defense for wound dressing manufacturers confronting raw material volatility. Captive seaweed processing capacity in Norway and France insulates premium-tier suppliers from climate-driven harvest interruptions while supporting price premiums against commodity hydrocolloid competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs hospital formulary negotiations, with antimicrobial alginate variants commanding spreads over basic hydrocolloid benchmarks based on clinical evidence depth and FDA 510(k) pathway differentiation. Reimbursement compression in Germany and England is narrowing coverage criteria for bioactive tiers, forcing convergence toward standard dressing benchmarks. Cost-sensitive homecare segments in Japan exhibit highest price elasticity, while United States integrated delivery networks prioritize clinical outcomes over unit cost in surgical wound protocols.
Supply Chain Analysis
Dual-sourcing qualification requirements from United States integrated delivery networks mandate redundant notified body relationships and sterilization asset validation across multiple geographies. Raw material flows concentrate on Norwegian and French coastal zones for alginate feedstock, Chinese and German polymer precursors for polyurethane foams, and Swedish cellulose matrices for hydrocolloid substrates. Climate-related seaweed harvest volatility poses structural supply risk. Distribution runs through group purchasing organizations in United States hospital networks, direct manufacturer contracts in German hospital systems, and specialized wound care distributors in Japanese homecare channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation operates as a regulatory compounder, consolidating market share toward compliant manufacturers as MDR transition deadlines filter out marginal competitors lacking clinical evidence portfolios.
For Market Incumbents: Cement MDR technical documentation advantages by accelerating ISO 10993 biocompatibility study queues at contracted laboratories ahead of competitor submissions. Deepen captive alginate processing capacity in Nordic coastal zones to defend margin position against climate-driven raw material volatility threatening mid-tier suppliers dependent on spot seaweed markets.
For New Entrants and Emerging Players: Homecare distributors in Tokyo and Osaka metropolitan corridors offer the most penetrable entry vector, as METI reimbursement channel expansion for self-applied patches outpaces established manufacturer coverage. Target wearable biosensor convergence applications where pH and temperature sensing film integration creates technical differentiation against commodity dressing incumbents.
For Investors and Strategic Acquirers: Roll-up economics work for antimicrobial technology specialists because NHS England antibiotic stewardship targets and FDA surgical site infection protocols are elevating topical dressing specifications faster than organic R&D timelines permit. Platform consolidation around ionic silver and antimicrobial peptide substrate integration offers five-to-ten year demand visibility. Watch MDR notified body capacity constraints as inflection signal for regulatory compliance scarcity premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Accelerates market access through EMA notified body relationships ahead of competitor queues. |
| Captive Alginate Processing Capacity | Secures Norwegian seaweed harvest supply against climate volatility compressing rival margins. |
| Hospital System Partnership | Locks in United States integrated delivery network volume through value analysis committee engagement. |
| Wearable Biosensor Integration | Captures Japanese homecare expansion under METI post-acute care decentralization reimbursement channels. |
| Antimicrobial Stewardship Alignment | Positions topical dressing protocols for NHS England systemic antibiotic reduction targets. |
Study Parameters
Coverage spans United States, Germany, Japan, and United Kingdom demand centers, with primary inputs from each geography balanced against secondary validation. Primary interviews engaged wound care clinicians, hospital purchasing committee members, biomedical engineers at dressing manufacturers, and group purchasing organization contracts managers. Secondary sources incorporated FDA 510(k) filings, EMA MDR technical documentation submissions, CMS Medicare reimbursement databases, and hospital procurement contract repositories. Bottom-up patient volume modeling triangulated against top-down manufacturer revenue estimates.
Granularity-level modeling disaggregated volume and value across product type, end user, application, and material substrate dimensions, with additional segmentation by regional regulatory cluster and reimbursement pathway. CAGRs derived from weighted average of historical growth trajectory and forward-looking demand driver elasticity across the projection horizon. Forecast inputs incorporated diabetic foot ulcer incidence projections, MDR compliance cost pass-through assumptions, and antimicrobial stewardship protocol adoption curves.
Revisions become necessary when MDR notified body capacity constraints intensify, alginate harvest disruptions exceed historical variance bands, or reimbursement authority coverage criteria shift materially. Deviation in EU regulatory enforcement intensity or Japanese homecare reimbursement channel expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
US Wound Irrigation System Market
Wound Care
Wound Irrigation Devices Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
Liquid Bandages Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Europe Compression Bandages Market
Wound Care
Advanced Wound Management Market
Wound Care
Italy Wound Care Market
Wound Care
Burn Care Centers Market
Wound Care
Autologous Wound Patches Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
Decubitus Ulcer Treatment Products Market
Wound Care
Hydrocolloid Dressing Market
Wound Care
Global Traditional Wound Management Market
Wound Care
US Burn Care Centers Market
Wound Care
Global Diabetic Foot Ulcers Market