
 Wound Retractor Market | 2026-2036
Wound Retractor Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Retractor Market Analysis
Ambulatory surgical centers is bifurcating hospital procurement patterns as outpatient volume shifts accelerate. Medtronic Plc leverages its integrated surgical portfolio to anchor premium retractor lines across North American distribution networks. B. Braun Melsungen AG competes through specialized European manufacturing scale and direct hospital contracting strength.
A wound retractor is a mechanical device, typically fabricated from stainless steel, medical-grade silicone, or reinforced polymers, designed to hold incision edges apart and maintain operative field exposure during open or laparoscopic procedures. Its primary commercial purpose is to reduce tissue trauma, minimize surgeon fatigue, and lower infection risk through atraumatic retraction. Disposable retractors command expanding share in ambulatory settings where sterilization economics favor single-use polymer designs, while self-retaining systems dominate orthopedic and cardiothoracic applications requiring sustained exposure without assistant support. Stainless steel retains institutional preference in emerging markets where reprocessing infrastructure limits per-procedure costs.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and commercial launch sequencing for manufacturers targeting both jurisdictions. ISO 13485 quality management certification operates as a baseline market access filter, particularly for suppliers entering German and Japanese procurement frameworks. Stakeholders must monitor evolving sterilization validation standards and polymer biocompatibility testing protocols as regulatory divergence between FDA and notified body interpretations widens.
Market Dynamics
Ambulatory surgical centers are dismantling traditional hospital-centric procurement hierarchies as outpatient volume migrates from inpatient settings, forcing manufacturers to reconfigure distribution networks and sterilization economics around single-use polymer platforms.
Growth Catalysts
- EU MDR technical documentation mandates:Stricter conformity assessment requirements for Class IIa medical devices accelerate hospital replacement cycles for aging stainless steel retractor inventories.
- Minimally invasive surgery infrastructure:Expansion of laparoscopic suites in the United States, Germany, and China generates sustained demand for self-retaining retractor systems with integrated insufflation ports.
- Polymer biocompatibility advances:Medical-grade silicone and reinforced thermoplastic formulations enable atraumatic retraction profiles that reduce tissue trauma markers in cardiac and orthopedic procedures.
Market Restraints
- Specialized polymer feedstock concentration:Medical-grade silicone supply chains cluster in German and Japanese chemical manufacturing corridors, exposing device makers to input cost volatility.
- Reprocessing infrastructure asymmetry:Emerging market hospitals retain stainless steel preference due to limited central sterile supply department capacity, constraining disposable penetration.
- FDA 510(k) predicate device saturation:Substantial equivalence pathways for incremental retractor designs face heightened scrutiny, extending clearance timelines.
Strategic Opportunities
- Direct-to-ASC distribution models:Bypassing traditional hospital group purchasing organizations through specialized ambulatory surgical center contracting unlocks margin recovery.
- ISO 13485 certification arbitrage:Quality management infrastructure investments enable entry into Japanese and German procurement frameworks that exclude uncertified suppliers.
- Dual-use retractor platforms:Convergence of open surgery and laparoscopic functionality in single devices addresses hybrid operating room expansion.
Industry Challenges
- Sterilization validation protocol divergence:FDA and notified body interpretations of polymer biocompatibility testing widen, forcing redundant study designs.
- Legacy stainless steel reprocessing workforce:Central sterile supply technicians require reskilling for single-use device logistics and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Retractor Market |
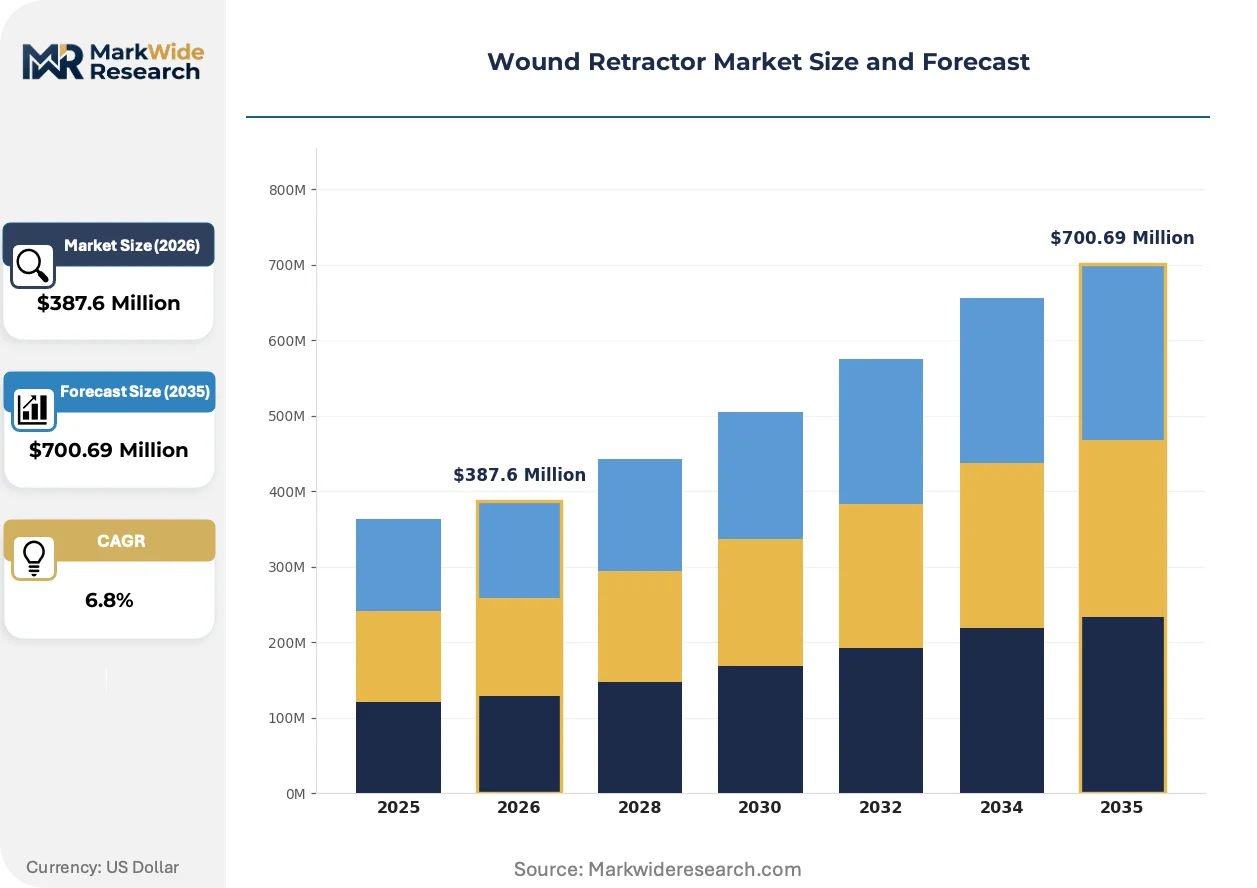
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Retractors, Automatic Retractors, Self-Retaining Retractors, Disposable Retractors End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Application: General Surgery, Orthopedic Surgery, Gynecological Surgery, Cardiothoracic Surgery Material: Stainless Steel, Plastic, Silicone, Carbon Fiber |
| Companies Covered | Applied Medical Resources Corporation, Medtronic Plc, CooperSurgical Inc., Teleflex Incorporated, B. Braun Melsungen AG, Stryker Corporation, Ethicon Inc., 3M Company, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Retractor Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are converging to reshape product development priorities, with manufacturers racing to validate next-generation platforms before compliance deadlines harden.
Reinforced polymer retractor designs are fragmenting the traditional stainless steel installed base. These platforms integrate radiolucent properties and atraumatic edge profiles for sustained tissue exposure. Ambulatory surgical centers adopt them aggressively where per-procedure sterilization economics favor disposability. The technology is fragmenting procurement decisions away from capital equipment committees toward supply chain directors focused on total cost-per-case metrics.
EU MDR Article 10 technical documentation requirements now demand clinical evidence for wound retractor claims previously supported by predicate equivalence. Manufacturers must generate proprietary performance data or risk notified body rejection. German and French hospitals accelerate supplier qualification audits to preempt supply disruption.
Outcome-based contracting is compressing traditional equipment lease structures. Hospital systems now negotiate retraction performance guarantees tied to surgical site infection rates and operative field visibility scores. United States integrated delivery networks lead this shift, unbundling device procurement from bundled payment accountability.
Wound Retractor Market Segmentation
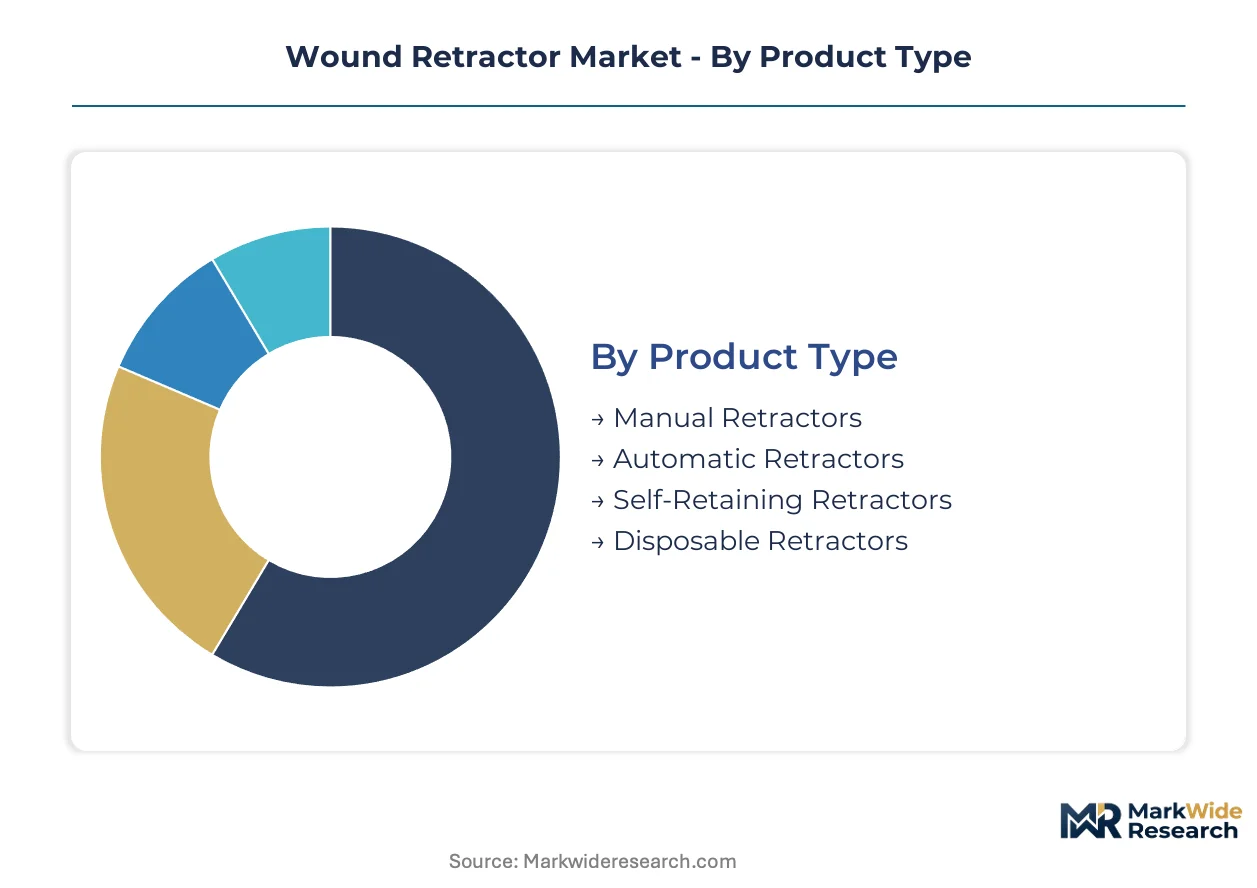
Wound retractor segmentation maps directly to procurement channel economics. Material choices determine sterilization infrastructure requirements, while product type dictates whether devices flow through capital equipment committees or supply chain directors managing per-case costs.
Product Type:
Channel mix varies sharply by mechanism of action. Self-retaining and automatic systems route through hospital value analysis committees as capital purchases, while disposable platforms bypass GPOs entirely via direct ASC contracting.
- Self-Retaining Retractors:Mechanical systems with integrated ratchet or cam mechanisms maintain exposure without assistant support. Demand concentrates in United States cardiothoracic suites where operative field stability directly impacts bypass graft visualization. German hospitals prioritize these for orthopedic trauma cases requiring sustained retraction force.
- Disposable Retractors:Single-use polymer platforms eliminate reprocessing logistics. Ambulatory surgical centers in the United States and China adopt these fastest where per-case economics favor elimination of CSSD overhead. FDA 510(k) clearance pathways for polymer biocompatibility dominate development timelines for this segment.
- Manual Retractors:Handheld stainless steel instruments requiring continuous assistant manipulation retain dominance in emerging markets with limited capital budgets.
- Automatic Retractors:Motorized or pneumatic systems with programmable retraction force profiles serve specialized neurosurgical and microvascular applications.
Self-Retaining Retractors dominate installed base. Disposable Retractors is where expansion concentrates.
End User:
Customer type determines pricing architecture and contract structure. Hospital systems negotiate multi-year equipment leases with performance guarantees, while ASCs purchase on spot markets with volume rebate tiers.
- Hospitals:Integrated delivery networks in the United States and Germany anchor volume through centralized procurement. These buyers demand ISO 13485 certification and EU MDR technical documentation as baseline qualification filters. Capital equipment committees evaluate total cost of ownership across 7-10 year depreciation cycles.
- Ambulatory Surgical Centers:Freestanding outpatient facilities in the United States bypass traditional GPO structures through direct manufacturer contracting. China’s expanding day-surgery centers drive polymer disposable adoption where sterilization infrastructure remains underdeveloped. Per-case pricing models dominate procurement negotiations.
- Specialty Clinics:Dermatologic and ophthalmologic surgery centers require miniature retractor formats for confined anatomical spaces.
- Research Laboratories:Academic medical centers and CROs purchase specialized configurations for preclinical device validation studies.
Hospitals retain volume leadership. Ambulatory Surgical Centers is climbing the fastest.
Application:
Surgical specialty dictates retraction force requirements and anatomical configuration. Orthopedic and cardiothoracic applications demand sustained high-force exposure, while gynecological procedures prioritize atraumatic tissue interfaces.
- Orthopedic Surgery:Joint replacement and trauma procedures require robust retraction against dense musculature. German and United States hospitals drive specification development for radiolucent carbon fiber variants that preserve intraoperative imaging. Self-retaining systems with integrated light sources command premium positioning in this segment.
- Cardiothoracic Surgery:Sternotomy and thoracotomy exposure demands stable retraction without cardiac compression. United States academic medical centers specify silicone-edged platforms to reduce sternal edge trauma. Outcome-based contracting tied to surgical site infection rates is reshaping procurement in this application.
- General Surgery:Abdominal and soft tissue procedures utilize the broadest range of retractor formats from handheld to self-retaining.
- Gynecological Surgery:Minimally invasive hysterectomy and myomectomy procedures favor disposable polymer retractors with integrated insufflation ports.
General Surgery holds broadest installed base. Cardiothoracic Surgery is gaining share fastest.
Material:
Supply concentration and regulatory validation burden differentiate material tiers. Stainless steel leverages established reprocessing infrastructure, while polymers require extensive biocompatibility testing under FDA and EU MDR protocols.
- Stainless Steel:Surgical-grade 316L and 17-4 PH alloys dominate reusable retractor fabrication. Chinese and Indian hospitals prefer this material where central sterile supply departments limit disposable adoption. Reprocessing workforce training and capital equipment depreciation anchor total cost economics.
- Silicone:Medical-grade formulations enable atraumatic edge profiles with Shore hardness tunable to tissue type. German chemical manufacturers concentrate supply of implant-grade silicone feedstock, exposing device makers to input cost volatility. FDA biocompatibility testing under ISO 10993 protocols extends development timelines.
- Plastic:Reinforced thermoplastic platforms serve cost-sensitive disposable applications in high-volume ASC settings.
- Carbon Fiber:Radiolucent composite structures preserve fluoroscopic and CT imaging clarity during orthopedic and spinal procedures.
Stainless Steel dominates installed base. Silicone is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone feedstock concentrates in German and Japanese chemical manufacturing corridors, exposing device makers to input cost volatility while shaping regional procurement patterns. United States integrated delivery networks and China's expanding day-surgery infrastructure anchor demand growth for self-retaining and disposable platforms respectively.
United States
FDA 510(k) clearance pathways and outcome-based contracting reshape procurement for integrated delivery networks prioritizing surgical site infection rate guarantees. Academic medical centers in Boston and New York Metro drive specification development for silicone-edged cardiothoracic retractors. Ambulatory surgical centers in the Southeast and Southwest bypass traditional GPO structures through direct manufacturer contracting.
Germany
EU MDR technical documentation mandates accelerate hospital replacement cycles for aging stainless steel inventories in Bavaria and North Rhine-Westphalia. Notified body conformity assessments under BfArM oversight harden supplier qualification requirements. Medical-grade silicone production clusters along the Rhine chemical corridor supply feedstock for atraumatic retractor edge formulations.
China
NMPA registration requirements and expanding day-surgery center infrastructure in the Yangtze River Delta and Pearl River Delta drive disposable polymer adoption. Shanghai and Beijing hospital systems prioritize cost-per-case economics where central sterile supply departments remain underdeveloped. Domestic manufacturers leverage GB standard compliance for tier-2 city market penetration.
Japan
PMDA quality management audits and METI healthcare technology assessment protocols filter market access for foreign suppliers. Osaka-Kobe and Nagoya industrial corridors concentrate precision polymer processing capabilities for miniature retractor formats. Academic medical centers in Tokyo specify radiolucent carbon fiber variants for orthopedic trauma applications.
India
CDSCO medical device rules and Ayushman Bharat expansion drive demand in Maharashtra and Karnataka hospital systems. Mumbai and Bangalore medical device clusters assemble stainless steel retractors for cost-sensitive tier-2 and tier-3 city procurement. Central sterile supply department infrastructure gaps sustain reusable instrument preference over disposable platforms.
Wound Retractor Market Vendor Landscape
Concentration sits with diversified surgical device conglomerates commanding integrated distribution networks and specialized European manufacturers with direct hospital contracting strength. Tier-one players anchor premium retractor lines through multi-year equipment leases with performance guarantees, while mid-scale specialists compete on polymer biocompatibility validation speed and ASC-focused logistics. Strategic moves center on ISO 13485 certification arbitrage for Japanese and German market entry and direct-to-ASC distribution model deployment bypassing traditional GPO structures.
Among diversified surgical device conglomerates, Medtronic Plc and Stryker Corporation exemplify scale-driven archetypes with integrated North American distribution networks, while B. Braun Melsungen AG represents European manufacturing-centric positioning with specialized hospital contracting depth. Applied Medical Resources Corporation occupies a position within the mid-scale specialist tier focused on polymer platform innovation.
| Leading Market Players |
|---|
| Applied Medical Resources Corporation |
| Medtronic Plc |
| CooperSurgical Inc. |
| Teleflex Incorporated |
| B. Braun Melsungen AG |
| Stryker Corporation |
| Ethicon Inc. |
| 3M Company |
| Becton, Dickinson and Company |
| Others |
Supply Flow & Price Mechanics
EU MDR Article 10 technical documentation requirements gate both supplier qualification and price differentiation simultaneously, forcing manufacturers to embed compliance costs into tiered product positioning while hospitals accelerate audits to preempt supply disruption. This regulatory architecture compresses margins for uncertified entrants while amplifying pricing power for incumbent holders of notified body approvals.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across the wound retractor market, separating premium silicone-edged platforms with proprietary clinical data from standard stainless steel instruments and economy polymer disposables lacking predicate equivalence. Price differentiation hinges on ISO 13485 certification grade and volume scale, with integrated delivery networks extracting rebates exceeding spot-market ASC purchasers. Cost compression in the disposable polymer tier is intensifying because medical-grade silicone feedstock volatility transfers directly to per-unit manufacturing. Ambulatory surgical centers exhibit highest price sensitivity due to per-case economics, while German hospital systems prioritize total cost-of-ownership over acquisition price.
Supply Chain Analysis
Rhine chemical corridor concentration in Germany underwrites global medical-grade silicone availability for atraumatic retractor edge formulations. Manufacturing draws from German silicone feedstock, Chinese thermoplastic compounding, and Japanese precision polymer processing capabilities. Single-source vulnerability concentrates in implant-grade silicone supply chains, exposing device makers to input cost spikes when chemical corridor production schedules tighten. Distribution runs through hospital group purchasing organizations in developed markets and direct manufacturer contracting in ambulatory surgical center channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The wound retractor market operates as a defensive-moat industry where regulatory entrenchment creates switching costs that lock hospital systems into validated supplier relationships spanning multi-year equipment depreciation cycles.
For Market Incumbents: Compound ISO 13485 certification arbitrage by accelerating notified body relationship investments ahead of EU MDR deadline hardening, while capturing ambulatory surgical center volume through direct contracting infrastructure that bypasses traditional GPO structures. Threat from polymer-focused emerging entrants demands backward integration into medical-grade silicone feedstock partnerships to secure margin stability.
For New Entrants and Emerging Players: Differentiate on biocompatibility validation speed for polymer platforms targeting Chinese day-surgery centers where NMPA registration requirements filter foreign competition but domestic manufacturers lag in clinical evidence generation. White-space sits in radiolucent carbon fiber orthopedic retractors for Japanese academic medical centers and disposable insufflation-integrated designs for United States gynecological ASCs. Go-to-market leverage rests on specialized distributor partnerships with regional GPOs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across EU MDR compliance infrastructure as clinical evidence generation demands expand development timelines and notified body audit costs. Long-term viability favors targets with established BSI or TÜV SÜD relationships and existing 510(k) predicate libraries. Signal to monitor: notified body capacity constraints extending conformity assessment queues beyond 18 months.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Notified body approval accelerates hospital replacement cycles for aging stainless steel inventories in Germany. |
| Direct-to-ASC Distribution Model Deployment | Bypassing GPO structures captures margin recovery in United States Southeast and Southwest outpatient markets. |
| Medical-Grade Silicone Feedstock Partnership | Rhine corridor supply security anchors atraumatic edge formulation costs for cardiothoracic retractor platforms. |
| ISO 13485 Certification Arbitrage | Quality management infrastructure enables entry into Japanese PMDA and German BfArM procurement frameworks. |
| Dual-Use Retractor Platform Development | Convergence of open surgery and laparoscopic functionality addresses hybrid operating room expansion in academic centers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and GPO contract disclosures to validate market sizing and competitive positioning assessments. Primary interviews engaged biomedical engineers, hospital purchasing committee chairs, ambulatory surgical center supply chain directors, and GPO contracts managers across United States, German, and Chinese markets. Bottom-up unit demand modeling triangulates against top-down revenue estimates from surgical procedure volume projections.
Segmentation dimensions modeled span product type, end user, application, material composition, and regional regulatory cluster across the analysis window. CAGRs derive from surgical procedure growth trajectories, ambulatory surgical center expansion rates, and material substitution elasticity coefficients. Industry-specific forecast inputs incorporate EU MDR transition timelines, NMPA registration velocity, and medical-grade silicone supply contract pricing indices.
Material uncertainties — sterilization validation protocol divergence between FDA and notified bodies, medical-grade silicone feedstock disruption, and ambulatory surgical center reimbursement policy shifts — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as regulatory interpretation harmonization efforts and polymer biocompatibility testing standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Care Sealants Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Vascular Dressings Market
Wound Care
Global Antimicrobial Dressings Market
Wound Care
Wound Healing Nutrition Market
Wound Care
Bioactive Wound Management Market
Wound Care
Next Generation Wound Closure Device Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Wound Care Centers Market
Wound Care
Antimicrobial Wound Dressings Market
Wound Care
Global Wound Irrigation System Market
Wound Care
Topical Wound Agents Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Japan Wound Care Management Devices Market
Wound Care
Global Wound Dressings Market