
 Dental Wound Dressings Market | 2026-2036
Dental Wound Dressings Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Wound Dressings Market Outlook
Germany is narrowing its position as a central European manufacturing hub for absorbable dental wound care materials. 3M leverages its polymer science heritage to sustain leadership in hemostatic dressing formulations. Integra LifeSciences anchors its competitive stance through specialized collagen-based matrices for soft tissue repair. Smith+Nephew competes by controlling distribution channels across European dental clinic networks.
Dental wound dressings comprise sterile barrier materials applied to oral surgical sites to control bleeding, prevent infection, and accelerate mucosal closure, typically incorporating resorbable polymers or oxidized regenerated cellulose with absorption rates calibrated to 24-72 hour degradation windows. Hemostatic dressings dominate current revenue pools given their universal deployment across extraction and implant procedures, while antimicrobial variants represent the fastest-expanding segment as peri-implantitis protocols tighten prophylactic standards. Alginate-based materials occupy a mature niche in periodontal packing applications where gel-forming properties manage moisture balance.
FDA 510(k) clearance pathways and EMA Medical Device Regulation conformity assessments shape product development timelines and market access costs for manufacturers targeting the United States and European Union. ISO 10993 biocompatibility testing series governs cytotoxicity and sensitization thresholds that determine material selection for intraoral contact applications. Stakeholders must monitor evolving reimbursement codes for outpatient oral surgery as payers recalibrate coverage for advanced dressing categories versus conventional gauze alternatives.
Market Dynamics
The Dental Wound Dressings Market is experiencing structural pressure from EMA Medical Device Regulation conformity assessments, which are elongating product development timelines and forcing manufacturers to reformulate absorbable polymer matrices to meet elevated biocompatibility thresholds.
Growth Catalysts
- Peri-implantitis Protocol Tightening:Dental clinics across Germany and Japan are expanding antimicrobial dressing deployment as prophylactic standards harden around implant procedures. EMA biocompatibility requirements are accelerating material innovation cycles.
- Aging Population Surgical Volume:Elevated rates of periodontal intervention and implant placement in the United States sustain procedural demand for hemostatic dressings in hospital outpatient departments.
- Absorbable Polymer Science:Oxidized regenerated cellulose formulations with calibrated 24-72 hour degradation windows are replacing conventional gauze in extraction protocols, driving category premiumization.
Market Restraints
- FDA 510(k) Pathway Costs:Pre-market notification requirements for intraoral contact applications impose substantial testing burdens on smaller manufacturers seeking United States market access.
- Collagen Raw Material Concentration:Supply of porcine and bovine-derived collagen matrices concentrates among limited European processors, creating input vulnerability for soft tissue repair formulations.
- Conventional Gauze Substitution:Cost-conscious outpatient clinics in price-sensitive markets continue defaulting to non-resorbable gauze alternatives for routine extractions.
Strategic Opportunities
- Alginate Moisture Management:Gel-forming alginate materials for periodontal packing applications remain underdeployed in Japanese dental networks relative to European penetration rates.
- Reimbursement Code Evolution:Payer recalibration of coverage for advanced dressing categories versus conventional alternatives in the United States creates margin expansion potential for differentiated products.
- ISO 10993 Certification Acceleration:Early alignment with cytotoxicity and sensitization testing series enables faster regulatory positioning as biocompatibility standards tighten across multiple jurisdictions.
Industry Challenges
- Polymer Reformulation Expertise Gap:Scarce talent pools in resorbable polymer chemistry constrain in-house R&D velocity for mid-tier manufacturers competing against integrated material science divisions.
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of FDA 510(k) clearance and EMA MDR conformity assessment stretches quality assurance bandwidth and delays revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Wound Dressings Market |
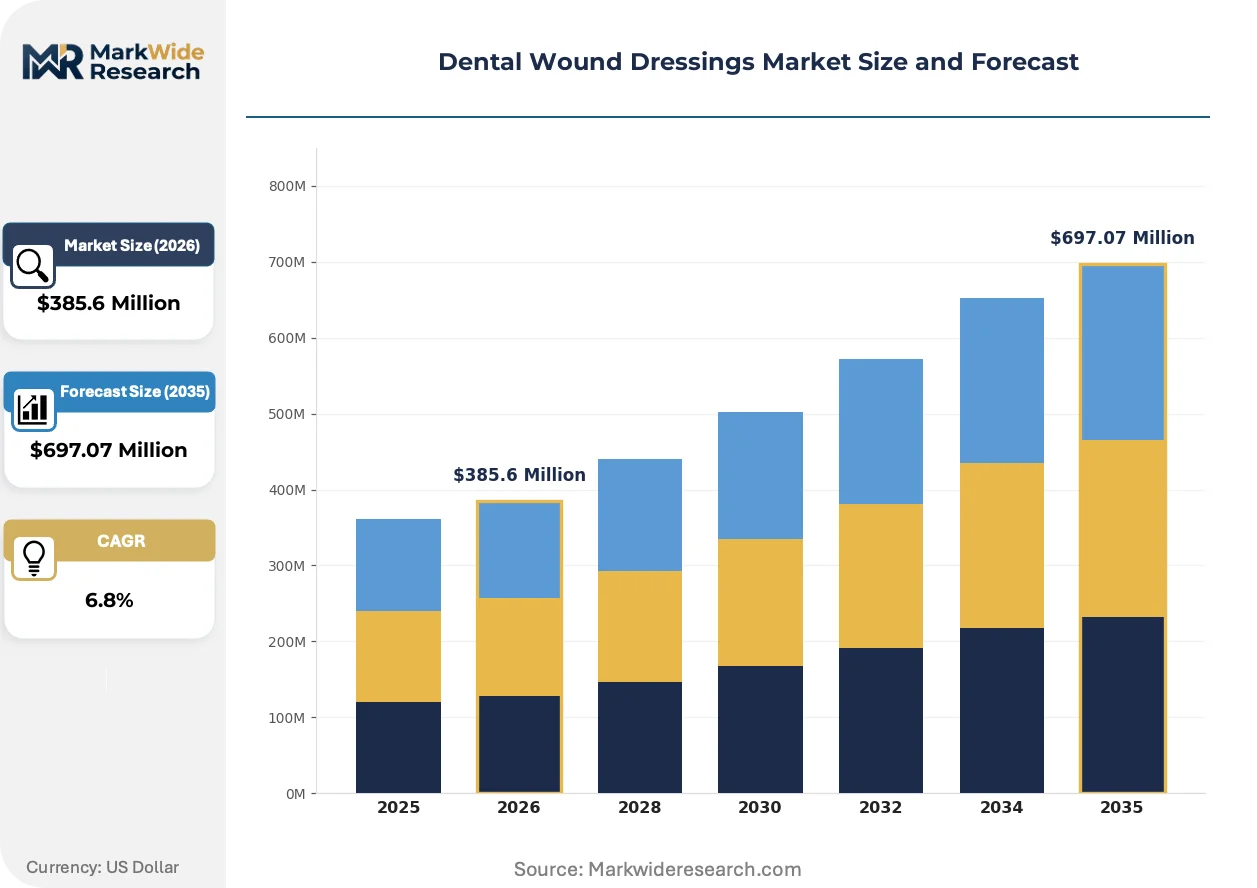
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemostatic Dressings, Absorbable Sutures, Antimicrobial Dressings, Non-Adherent Dressings Material: Polymer, Gelatin, Alginate, Cotton End User: Dental Clinics, Hospitals, Home Care, Research Institutions Application: Oral Surgery, Periodontal Treatment, Implant Surgery, Soft Tissue Repair |
| Companies Covered | 3M, Integra LifeSciences, Smith+Nephew, Braun SE, Medline Industries, Mölnlycke Health Care AB, Coloplast Corp, Johnson & Johnson, ConvaTec Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Wound Dressings Market Strategic Shifts
Material science advancement and regulatory harmonization pressures are compressing traditional product lifecycles while opening pathways for differentiated dressing categories that integrate antimicrobial and hemostatic functions in single formulations.
Oxidized regenerated cellulose is migrating from standalone hemostatic applications toward composite matrices that incorporate sustained-release antimicrobial agents. Oral surgery suites in German hospital outpatient departments are piloting these hybrid formulations at accelerated adoption rates compared to general dental clinics. This convergence is compressing the addressable market for single-function dressings while expanding premium pricing tiers for multifunctional alternatives.
EMA Medical Device Regulation biocompatibility requirements are mandating expanded ISO 10993 cytotoxicity documentation for all new intraoral contact materials. Manufacturers targeting European Union market access must now complete sensitization and irritation testing sequences that previously applied only to permanent implantables. Absorbable polymer matrix suppliers are responding by pre-certifying base materials to reduce downstream device-level compliance burdens.
Hospital outpatient departments are consolidating procurement authority for dental wound dressings away from individual surgeon preference toward centralized supply chain functions. Group purchasing organizations in the United States are displacing traditional dental distributor relationships for high-volume hemostatic categories. This concentration is most visible in metropolitan health systems where implant procedure volumes justify direct manufacturer contracting.
Dental Wound Dressings Market Segmentation
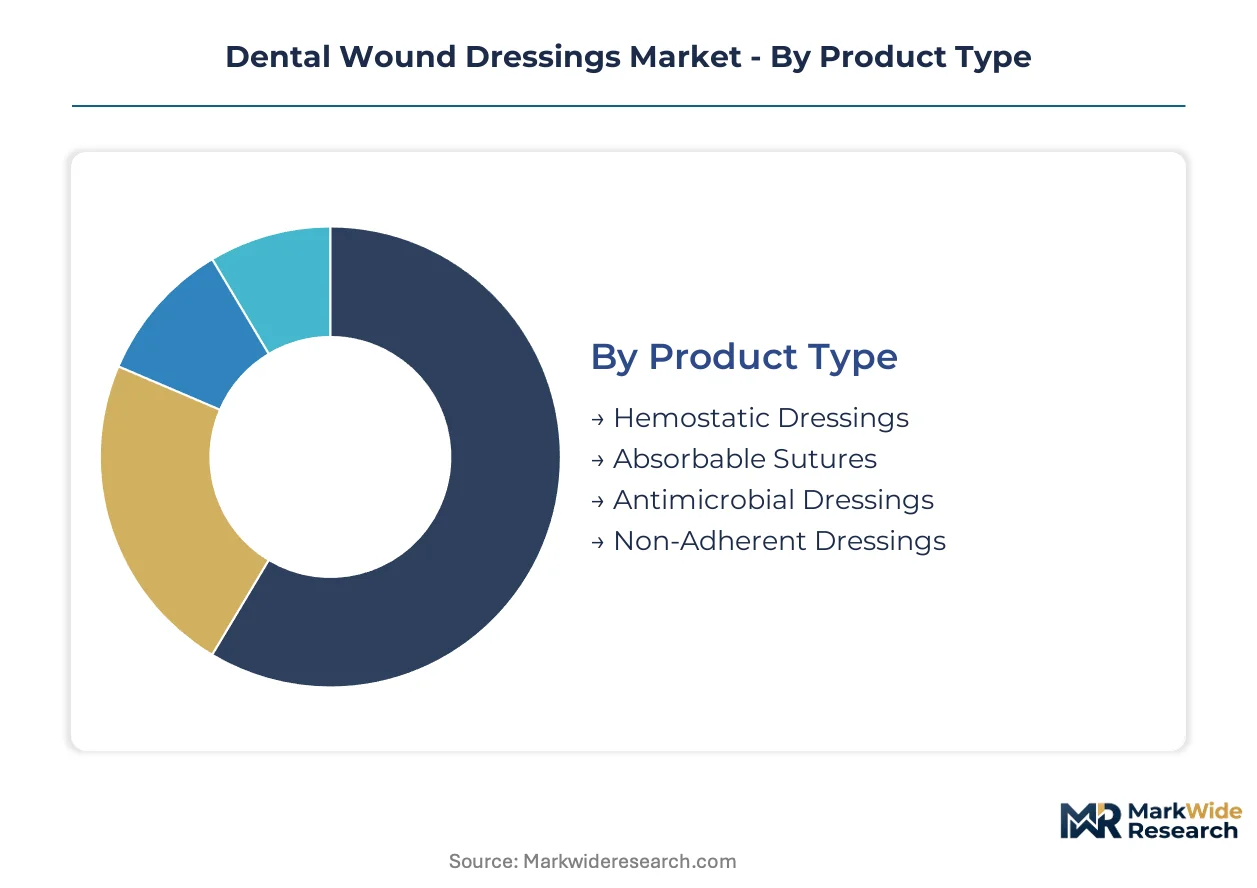
Dental wound dressing categories map directly to procedural workflows and reimbursement pathways. Each segment carries distinct regulatory burdens, material specifications, and pricing elasticity that determine competitive positioning.
Product Type:
Use-case spectrum spans immediate hemorrhage control through long-term infection prophylaxis, with formulation complexity escalating across functional categories.
- Hemostatic Dressings:Oxidized regenerated cellulose matrices with calibrated 24-72 hour degradation windows dominate extraction and implant protocols. Hospital outpatient departments in the United States sustain elevated procedural volumes for these formulations as aging populations drive periodontal intervention rates.
- Antimicrobial Dressings:Composite matrices incorporating sustained-release agents address tightening peri-implantitis protocols. German dental clinics deploy these at accelerated rates compared to general practice settings, compressing demand for single-function alternatives.
- Absorbable Sutures:Synthetic polymer threads for mucosal closure in complex extractions.
- Non-Adherent Dressings:Barrier materials protecting surgical sites without tissue adhesion.
The dominant share belongs to Hemostatic Dressings, while Antimicrobial Dressings is closing the gap fastest.
Material:
Cost tier stratification separates premium bioresorbable polymers from commodity natural fibers, with raw material provenance determining EMA MDR compliance burden.
- Polymer:Absorbable synthetic matrices engineered for predictable degradation kinetics. FDA 510(k) clearance pathways impose substantial testing burdens on manufacturers targeting United States market access for these formulations.
- Gelatin:Collagen-derived sponges for soft tissue repair applications. Supply concentrates among limited European processors, creating input vulnerability for mid-tier manufacturers.
- Alginate:Gel-forming materials managing moisture balance in periodontal packing.
- Cotton:Conventional non-resorbable gauze for cost-conscious outpatient clinics.
Polymer formulations command premium positioning, though Alginate penetration in Japanese networks trails European adoption significantly.
End User:
Customer type determines procurement authority concentration, with institutional buyers displacing individual surgeon preference in high-volume categories.
- Hospitals:Centralized supply chain functions in metropolitan United States health systems. Group purchasing organizations now contract directly with manufacturers for hemostatic categories, bypassing traditional dental distributors.
- Dental Clinics:Independent and group practice settings across Germany and Japan where antimicrobial deployment is expanding fastest.
- Home Care:Post-operative dressing changes for patients with limited mobility.
- Research Institutions:Clinical trial materials and protocol development sites.
Hospitals control the largest procurement volumes, while Dental Clinics represent the steepest expansion trajectory for advanced dressing categories.
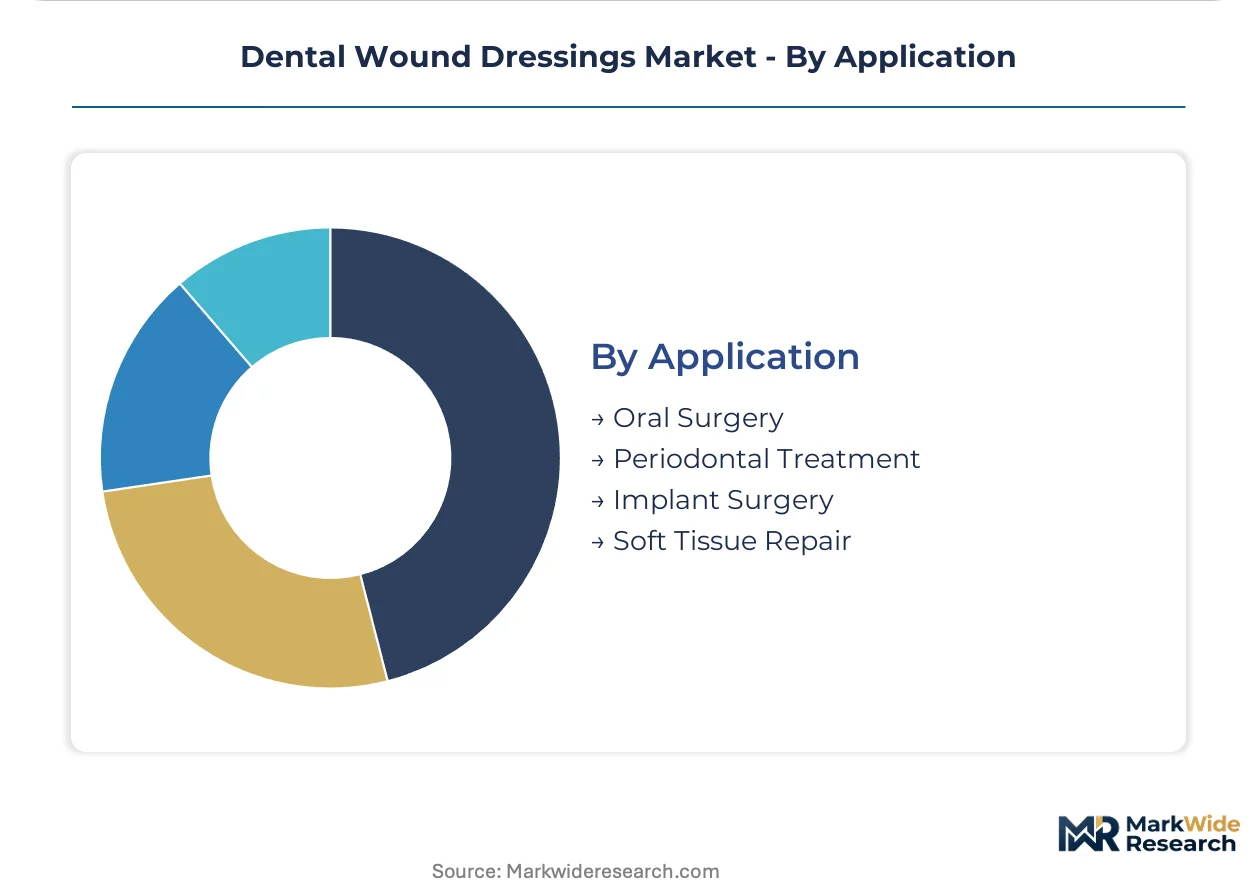
Application:
Procedure-specific requirements dictate material selection, with implant workflows generating the most stringent biocompatibility demands.
- Oral Surgery:Extraction sites requiring rapid hemostasis and mucosal coverage. ISO 10993 cytotoxicity testing governs all intraoral contact materials in this high-volume category.
- Implant Surgery:Peri-implantitis prevention protocols driving antimicrobial adoption. EMA Medical Device Regulation conformity assessments elongate development timelines for materials targeting these procedures.
- Periodontal Treatment:Packing materials for surgical site management.
- Soft Tissue Repair:Collagen matrices for gingival grafting and flap closure.
Oral Surgery generates the highest absolute demand, yet Implant Surgery exhibits the fastest share gain as prophylactic standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Absorbable polymer matrix production clusters in Germany, the United States, and Japan, with each hub serving distinct regulatory environments and procedural preferences. Raw material processing for collagen and oxidized regenerated cellulose concentrates near established medical device manufacturing corridors.
United States
Hospital outpatient departments drive hemostatic dressing volumes as aging populations sustain periodontal intervention rates. FDA 510(k) clearance pathways impose substantial testing burdens on manufacturers targeting intraoral contact applications. Minneapolis-St. Paul anchors polymer science R&D clusters where 3M leverages material heritage for formulation leadership.
Germany
Dental clinics deploy antimicrobial dressings at accelerated rates compared to general practice settings as peri-implantitis protocols tighten. EMA Medical Device Regulation conformity assessments elongate development timelines for absorbable matrices. Aachen and Stuttgart host specialized collagen processing facilities serving soft tissue repair formulation supply chains.
Japan
Metropolitan dental networks generate demand for alginate-based periodontal packing materials where gel-forming properties manage moisture balance. PMDA biocompatibility requirements align with ISO 10993 cytotoxicity testing series for intraoral applications. Osaka-Kobe manufacturing corridors concentrate resorbable polymer production for regional distribution.
United Kingdom
Hospital procurement consolidation shifts dressing purchasing authority toward centralized supply chain functions in metropolitan health systems. MHRA post-Brexit regulatory frameworks maintain alignment with EMA MDR biocompatibility standards. London and Cambridge medical technology clusters concentrate distribution channel control for advanced hemostatic categories.
Switzerland
Specialized dental clinics in Zurich and Geneva adopt premium composite matrices integrating antimicrobial and hemostatic functions. Swissmedic conformity assessments emphasize ISO 10993 sensitization documentation for absorbable polymer devices. Basel pharmaceutical-medical device corridors supply raw material innovation to European formulation manufacturers.
Dental Wound Dressings Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in polymer and collagen supply. The vendor base separates into three tiers: diversified medical device conglomerates with material science divisions, mid-tier wound care specialists with dental verticals, and regional distributors with private-label formulations. Dominant competitive moves include strategic partnerships with group purchasing organizations and ISO 10993 pre-certification of base materials to accelerate device-level compliance.
Within the diversified conglomerate tier, 3M and Johnson & Johnson occupy positions anchored by polymer science heritage and broad hospital supply relationships. Among wound care specialists, Integra LifeSciences and Smith+Nephew exemplify archetypes focused on collagen matrices and European distribution channel control respectively. Mölnlycke Health Care AB and Coloplast Corp represent Nordic and Danish GmbH-structured competitors with concentrated regional positioning.
| Leading Market Players |
|---|
| 3M |
| Integra LifeSciences |
| Smith+Nephew |
| Braun SE |
| Medline Industries |
| Mölnlycke Health Care AB |
| Coloplast Corp |
| Johnson & Johnson |
| ConvaTec Group PLC |
| Others |
Value Chain & Pricing Dynamics
Aachen and Stuttgart collagen processing clusters anchor European supply capacity for soft tissue repair formulations, translating raw material scarcity into sustained premium pricing power for integrated manufacturers while forcing mid-tier competitors toward commodity polymer alternatives.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across dental wound dressing categories. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993 pre-certified composite matrices from conventional oxidized regenerated cellulose and non-resorbable gauze alternatives. Cost compression in the economy tier is intensifying because German dental clinics consolidate procurement through group purchasing organizations. Hospital outpatient departments in the United States exhibit the least price sensitivity due to reimbursement code coverage, while independent dental clinics in price-sensitive markets default to cotton gauze.
Supply Chain Analysis
Contract manufacturing capacity for absorbable polymer matrices concentrates among specialized European medical device foundries with EMA MDR certification. Geographic supply concentration centers on Germany, the United States, and Japan for finished dressing production, with porcine and bovine collagen raw materials drawing from limited European processors. Single-source vulnerability in collagen supply chains creates input risk for soft tissue repair formulations. Distribution runs through group purchasing organizations in metropolitan United States health systems and traditional dental distributor networks across European and Japanese markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable barriers: ISO 10993 certification timelines and FDA 510(k) testing burdens lock in incumbent positions while excluding rapid follower entry.
For Market Incumbents: Harden regulatory moats by accelerating ISO 10993 pre-certification of base materials to reduce downstream device-level compliance burdens for customers. Deepen backward integration into porcine and bovine collagen processing to neutralize raw material concentration risk from limited European suppliers. Priority focus: defend against mid-tier manufacturers seeking EMA MDR fast-track pathways. For New Entrants and Emerging Players: Alginate-based periodontal packing applications in Japanese dental networks represent the most penetrable entry point given underdeployment relative to European penetration rates. Antimicrobial composite matrices for implant surgery workflows offer white-space expansion as peri-implantitis protocols tighten prophylactic standards. Go-to-market angle: partner with regional distributors possessing existing relationships with independent German dental clinics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with group purchasing organization contracts in United States hospital outpatient departments. Long-term viability over the projection horizon favors platforms with integrated polymer science capabilities and multi-jurisdiction regulatory dossiers. Acquisition target archetype: mid-tier wound care specialists with dental verticals and pending EMA MDR conformity assessments. Signal to watch: reimbursement code recalibration for advanced dressing categories versus conventional gauze alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Early clearance creates first-mover advantage in United States hospital procurement cycles. |
| CE Marking Pathway Investment | EMA MDR conformity assessments elongate timelines for competitors lacking pre-certified materials. |
| Hospital System Partnership | Direct contracting with metropolitan health systems displaces traditional dental distributor relationships. |
| Collagen Supply Integration | Captive processing of porcine and bovine matrices neutralizes European raw material concentration risk. |
| Reimbursement Strategy Development | Advanced coding coverage for antimicrobial categories expands margin potential versus conventional alternatives. |
Study Parameters
A spread of perspectives from oral surgeons, hospital purchasing committee members, biomedical engineers, and group purchasing organization contract managers converged on the working assumptions. Primary interview insights combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and ISO 10993 certification registries. Bottom-up procedural volume estimates and top-down market sizing triangulated on segment-level demand figures.
Demand-supply balance dynamics across the analysis window anchored the forecast framework. Segmentation dimensions modeled include product type, material composition, end-user category, and application workflow. CAGRs derived from procedural volume trajectories, pricing elasticity by customer tier, and material substitution rates. Industry-specific inputs incorporated peri-implantitis protocol adoption curves and reimbursement code evolution timelines.
Practitioners should monitor EMA MDR implementation pace, FDA 510(k) backlog fluctuations, and collagen raw material supply disruptions for early signals. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and procedural volume sustainability. Quarterly review of hospital procurement consolidation indicators and reimbursement code update bulletins is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Vascular Ulcer Treatment Market
Wound Care
Chronic Wound Care Market
Wound Care
Wound Measurement Devices Market
Wound Care
Wound Closure Strips Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Advanced Wound Care Market
Wound Care
Autologous Wound Patches Market
Wound Care
Wound Healing Market
Wound Care
Brazil Wound Care Management Devices Market
Wound Care
Infectious Wound Care Management Market
Wound Care
Moist Wound Dressings Market
Wound Care
Wound Evacuators Market
Wound Care
Global Negative Pressure Wound Therapy (NPWT) Devices Market
Wound Care
US Burn Care Centers Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Decubitus Ulcer Treatment Products Market