
 Wound Debridement (Wound Cleaning) Market | 2026-2036
Wound Debridement (Wound Cleaning) Market Size, Share, and Industry Trends Forecast 2026-2036
Wound Debridement (Wound Cleaning) Market Analytics
Hospital procurement networks is reconfiguring around value-based wound care contracts that bundle debridement supplies with outcomes guarantees. Smith & Nephew leverages its advanced wound management portfolio to anchor premium surgical debridement tool placements across integrated delivery networks. B. Braun competes through sterile single-use mechanical debridement kits that reduce cross-contamination risk in busy surgical wards. Medline Industries controls private-label distribution channels, extending cost-competitive enzymatic agent access to mid-tier health systems.
Wound debridement encompasses the selective removal of necrotic tissue, slough, and foreign material from wound beds to promote healing and reduce bioburden, typically employing sharp excision, enzymatic dissolution with collagenase formulations, or autolytic moisture-retentive dressings that leverage endogenous proteolytic activity. Autolytic dressings and enzymatic agents command expanding share as outpatient and home healthcare settings adopt less operator-dependent modalities that reduce specialist labor intensity. Surgical debridement tools retain dominant position in acute care for deep or infected wounds where rapid tissue removal remains clinically imperative. Ultrasound-based technology represents the fastest-advancing segment, attracting margin concentration from device manufacturers seeking differentiation through selective tissue lysis with reduced collateral damage.
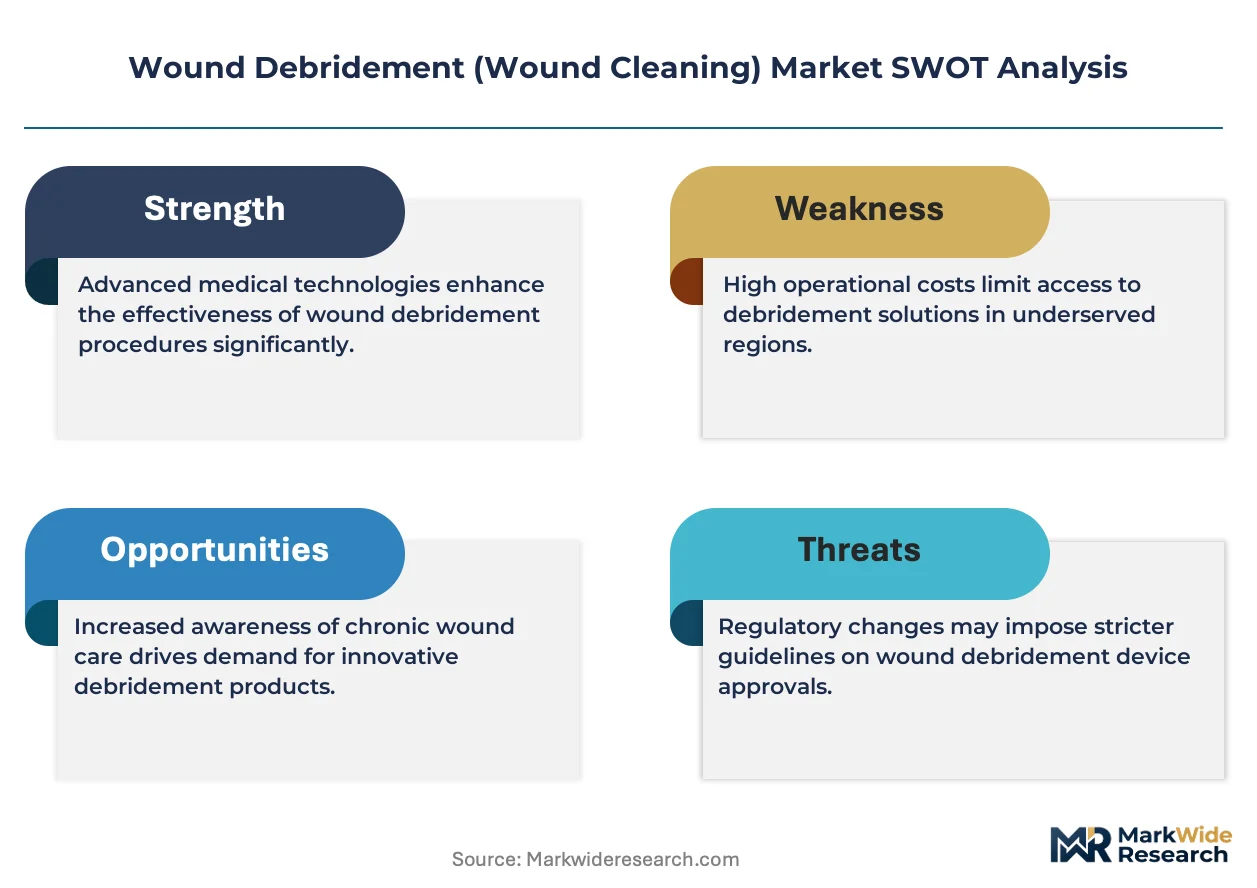
FDA 510(k) pathways and EMA MDR compliance requirements are elevating clinical evidence thresholds for novel debridement technologies, particularly biologics and energy-based devices seeking market authorization. ISO 13485 quality management standards govern manufacturing consistency across enzymatic and mechanical product categories, shaping supplier qualification criteria for hospital tenders. WHO wound care guidelines influence national reimbursement policies in emerging markets, affecting product access and pricing frameworks. Stakeholders must monitor evolving evidentiary demands from regulators and payors to align R&D investment with commercially viable approval timelines.
Market Dynamics
Hospital procurement networks are reconfiguring around value-based wound care contracts that bundle debridement supplies with outcomes guarantees, compressing margins for standalone product vendors while rewarding integrated solution providers.
Growth Catalysts
- Aging demographics:The United States, Germany, and Japan face elevated diabetic ulcer prevalence that drives procedure volumes across acute and post-acute settings.
- FDA 510(k) pathway evolution:Streamlined clearance for enzymatic debridement agents with established predicate devices accelerates product iterations.
- Ultrasound-based technology:Selective tissue lysis with reduced collateral damage attracts investment from device manufacturers seeking clinical differentiation.
Market Restraints
- Collagenase raw material concentration:Enzymatic agent production depends on specialized fermentation capacity concentrated among limited biologics suppliers.
- EMA MDR compliance costs:Elevated clinical evidence thresholds for novel biologic debridement products extend development timelines and capital requirements.
- Autolytic dressing substitution:Moisture-retentive alternatives leveraging endogenous proteolytic activity compete for outpatient cases with lower reimbursement.
Strategic Opportunities
- Home healthcare expansion:Less operator-dependent modalities reduce specialist labor intensity in United States outpatient settings.
- ISO 13485 certification acceleration:Quality management standardization enables mid-tier health system access to private-label distribution channels.
- WHO guideline alignment:Emerging market national reimbursement policies favor products meeting international wound care protocols.
Industry Challenges
- Specialized wound care nursing shortage:Sharp excision competency requirements limit surgical debridement tool utilization in community hospitals.
- Cross-contamination protocols:Sterile single-use mechanical kit validation demands continuous manufacturing quality investment.
- Biologics cold chain integrity:Temperature-sensitive enzymatic agent distribution requires specialized logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wound Debridement (Wound Cleaning) Market |
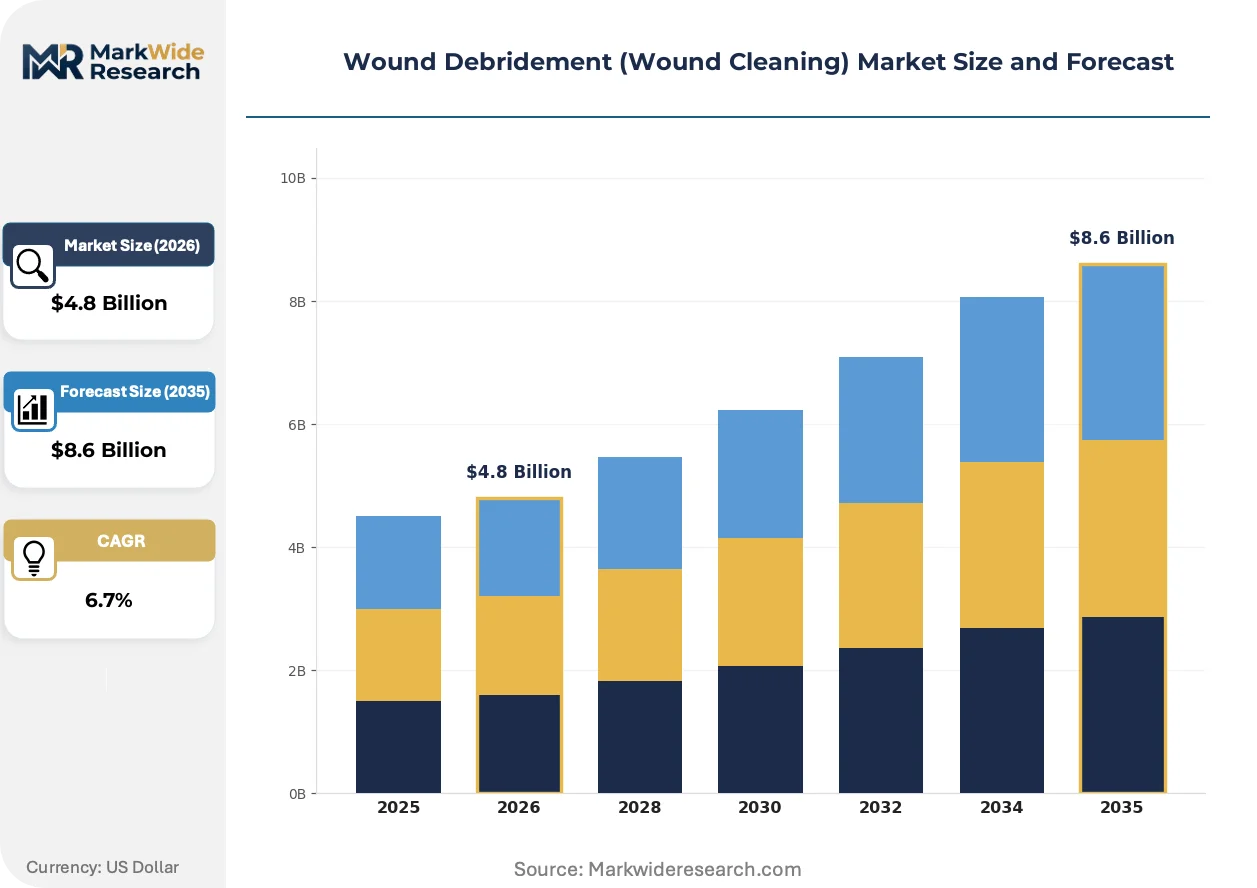
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autolytic Dressings, Surgical Debridement Tools, Enzymatic Agents, Mechanical Debridement Devices End User: Hospitals, Home Healthcare, Long-term Care Facilities, Outpatient Clinics Technology: Ultrasound-based, Laser Therapy, Hydrotherapy, Traditional Surgical Methods Application: Diabetic Ulcers, Pressure Sores, Burn Wounds, Surgical Wounds |
| Companies Covered | Smith & Nephew, B. Braun, Coloplast, ConvaTec Group, Molnlycke Health Care, Medline Industries, Integra LifeSciences, Lohmann & Rauscher, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wound Debridement (Wound Cleaning) Market Evolving Landscape
Digital integration and selective tissue interaction technologies are compressing the boundary between surgical precision and minimally invasive wound management across care settings.
Ultrasound-assisted debridement systems are digitizing tissue characterization through real-time impedance mapping, enabling selective necrotic tissue removal without adjacent viable tissue disruption. Academic medical centers in Germany and Japan are piloting these platforms for diabetic foot ulcer protocols. The technology is digitizing surgical decision-making by reducing operator-dependent variability in tissue margin assessment.
EMA MDR Article 10 post-market surveillance requirements are mandating extended clinical follow-up for energy-based debridement devices, forcing manufacturers to build registry infrastructure. This regulatory friction disproportionately affects smaller device firms seeking CE marking. European notified bodies are responding with structured consultation pathways to clarify evidentiary expectations.
Integrated delivery networks are consolidating debridement supply purchasing through multi-year risk-sharing agreements that tie reimbursement to healing outcomes. This purchasing consolidation displaces transactional vendor relationships in United States metropolitan markets. The shift is most visible in Medicare Advantage-covered populations where capitated payments align provider and supplier incentives.
Wound Debridement (Wound Cleaning) Market Segmentation
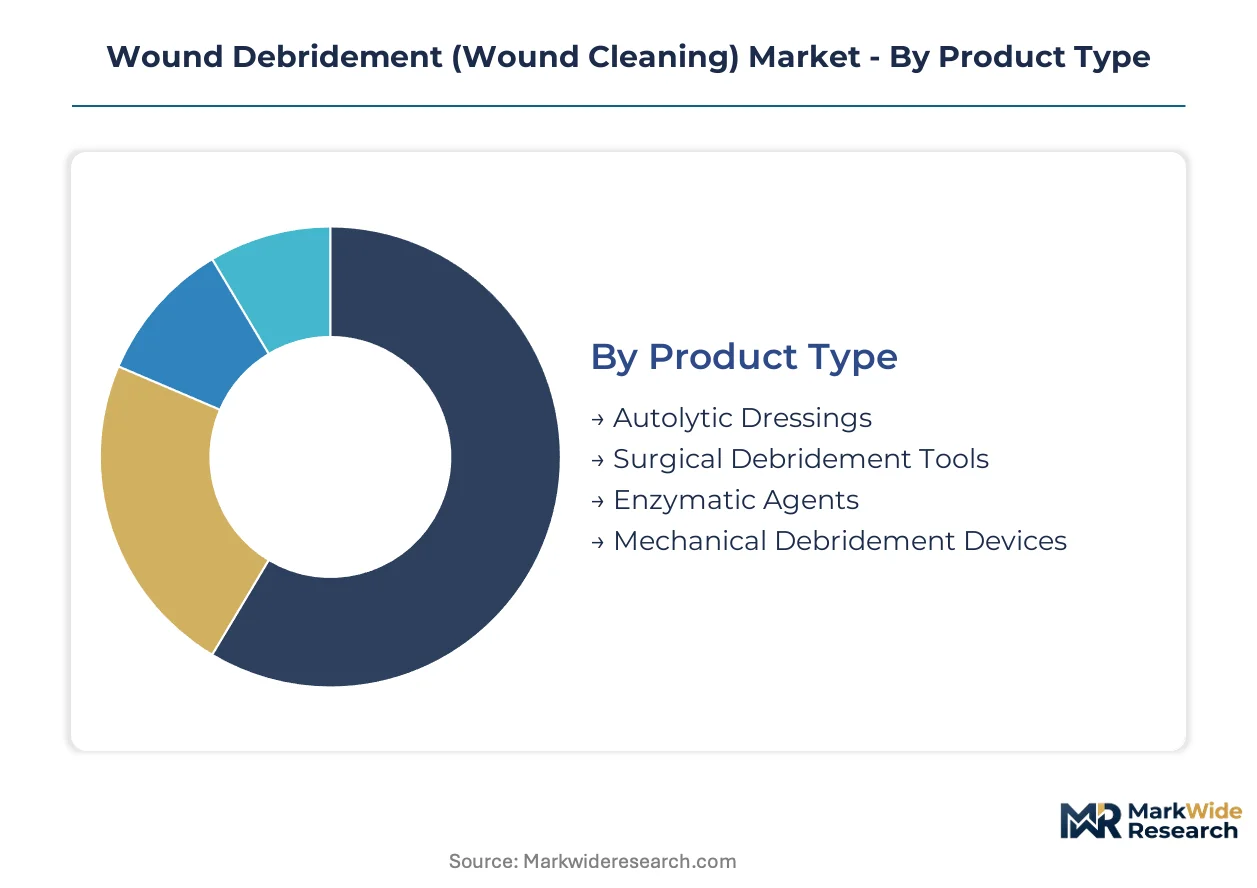
Segmentation in wound debridement reveals distinct procurement rhythms across product categories. Cycle times vary dramatically—enzymatic agents turn over monthly in high-volume hospitals while surgical tools depreciate over years—shaping inventory strategies and supplier relationships differently across each segment.
Product Type:
Autolytic dressings rotate through supply chains fastest due to single-use consumption patterns, while surgical instrument sets amortize over extended depreciation schedules.
- Autolytic Dressings:Moisture-retentive materials leverage endogenous proteolytic activity for gentle tissue dissolution. Demand concentrates in United States outpatient clinics where Medicare Advantage reimbursement favors lower-acuity interventions over surgical referral.
- Surgical Debridement Tools:Sharp excision instruments including scalpels, curettes, and forceps enable rapid necrotic tissue removal. German hospital networks anchor procurement volume for deep infected wounds where immediate bioburden reduction remains clinically imperative.
- Enzymatic Agents:Collagenase formulations from specialized fermentation processes dissolve devitalized tissue chemically. Japanese procurement networks prioritize these agents for patients with bleeding risks contraindicating sharp excision.
- Mechanical Debridement Devices:Monofilament pads and hydrosurgical systems physically detach slough and eschar. Single-use kit formats dominate United States surgical ward purchasing to satisfy Joint Commission cross-contamination protocols.
Surgical debridement tools anchor the volume base while autolytic dressings gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital installations from consumable-heavy home healthcare models with divergent margin structures.
- Hospitals:Acute care facilities deploy full modality portfolios across ICU, surgical, and wound care units. United States integrated delivery networks bundle debridement supplies into value-based contracts with healing outcome guarantees.
- Home Healthcare:Visiting nurse services favor operator-independent enzymatic and autolytic modalities. German statutory health insurance reimbursement codes increasingly cover home-based debridement to reduce hospital readmission penalties.
- Long-term Care Facilities:Nursing homes manage pressure sore populations with limited on-site surgical capability. Staffing constraints in Japan's elder care facilities drive preference for low-skill autolytic dressing protocols.
- Outpatient Clinics:Ambulatory wound centers perform selective sharp debridement with rapid throughput models. United States metropolitan markets see consolidation into multi-site clinic chains with centralized purchasing leverage.
Hospitals anchor the volume base while home healthcare expands most quickly.
Technology:
Application intensity varies by wound severity—ultrasound platforms target complex diabetic foot cases while traditional methods handle routine debridement volume.
- Ultrasound-based:Low-frequency energy systems achieve selective tissue lysis through cavitation mechanics. Academic medical centers in Germany pilot impedance-mapping variants for margin-controlled diabetic ulcer protocols.
- Laser Therapy:Selective photothermolysis ablates necrotic tissue with thermal precision. Japanese cosmetic and burn centers adopt these platforms for facial wound applications where scarring minimization drives purchasing decisions.
- Hydrotherapy:Pressurized saline irrigation systems mechanically debride through fluid shear forces. United States Veterans Health Administration facilities standardize on these modalities for combat-related wound protocols.
- Traditional Surgical Methods:Manual sharp excision with scalpel or curette remains the reference standard. Community hospitals across all geographies retain these techniques for immediate availability and minimal capital requirements.
Traditional surgical methods anchor the volume base while ultrasound-based platforms climb the fastest.
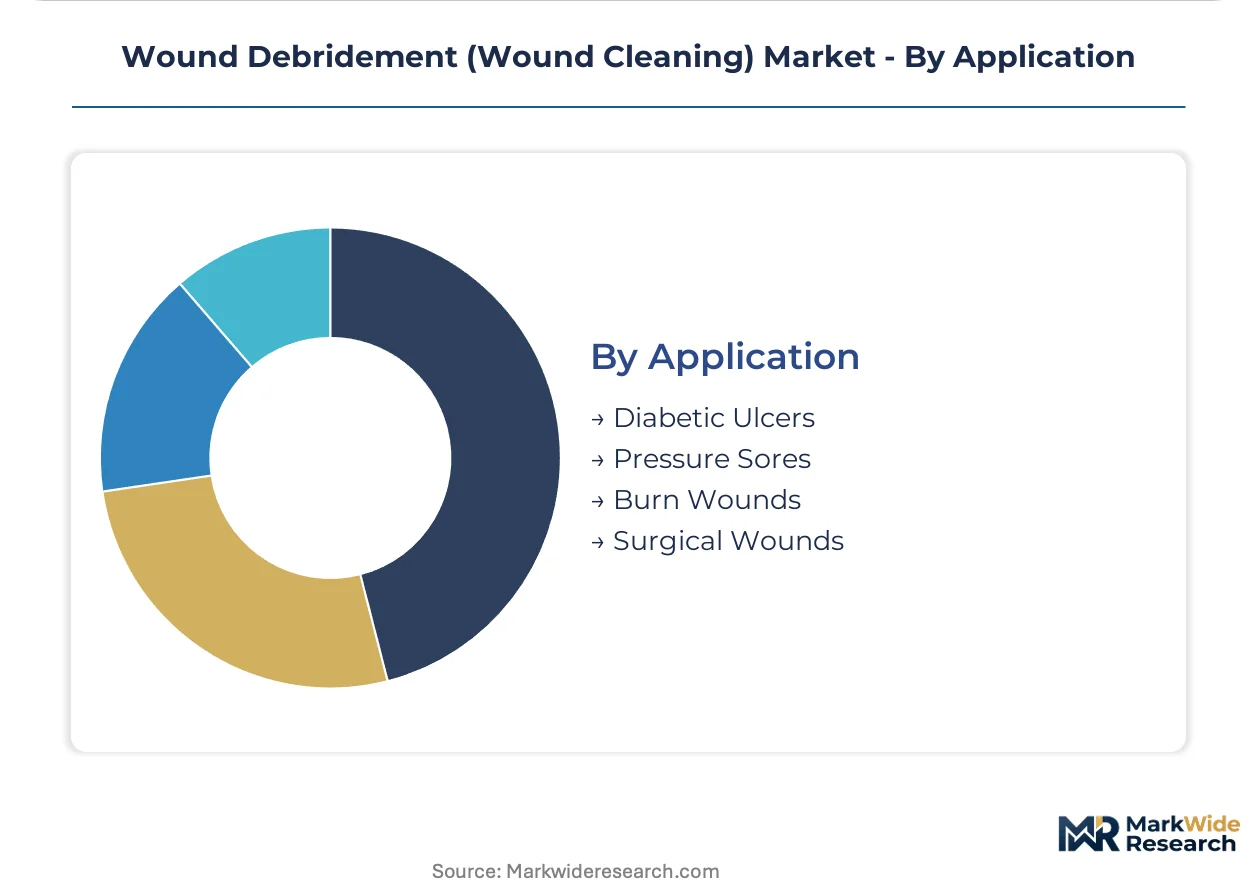
Application:
Wound etiology determines reimbursement tier and required intervention intensity across patient populations.
- Diabetic Ulcers:Neuropathic foot lesions in diabetic patients require recurrent debridement to prevent osteomyelitis progression. United States Medicare spending concentration in this category drives manufacturer R&D prioritization.
- Pressure Sores:Ischemic tissue damage in immobilized patients demands staged surgical intervention for Stage III-IV presentations. Japanese long-term care insurance claims data show rising prevalence correlating with super-aging demographic trends.
- Burn Wounds:Thermal injury eschar requires emergent excision to prevent toxic inflammatory cascade. German burn center networks maintain dedicated surgical debridement capabilities with 24-hour staffing protocols.
- Surgical Wounds:Postoperative dehiscence and infected sites need targeted bioburden reduction. United States hospital quality metrics penalizing surgical site infections intensify prophylactic debridement utilization.
Surgical wounds anchor the volume base while diabetic ulcers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital networks command premium pricing for advanced surgical debridement platforms while Indian procurement systems compress margins on commodity enzymatic agents through centralized tender mechanisms.
United States
Medicare Advantage capitation models and hospital value-based purchasing programs accelerate integrated delivery network consolidation of wound care supply contracts. FDA 510(k) clearance pathways for enzymatic debridement agents maintain streamlined predicate device frameworks. Academic medical centers in Boston and Cleveland pilot ultrasound-assisted debridement protocols for diabetic foot ulcer populations.
Germany
Statutory health insurance reimbursement codes for outpatient wound care and super-aging demographic pressures elevate procedure volumes across ambulatory settings. EMA MDR Article 10 post-market surveillance requirements mandate extended clinical follow-up for energy-based debridement devices. Medical technology clusters in Baden-Württemberg and Bavaria concentrate device manufacturing and specialized fermentation capacity for collagenase production.
Japan
Long-term care insurance claims data reveal escalating pressure sore prevalence correlating with elder care facility bed expansion. PMDA regulatory frameworks prioritize clinical evidence standards for novel biologic debridement products seeking market authorization. Wound care specialist networks in Tokyo and Osaka anchor demand for low-bleeding-risk enzymatic agents in aging patient populations.
India
Centralized government procurement through the National Health Mission and expanding private hospital chains drive volume demand for cost-competitive mechanical debridement kits. CDSCO medical device registration requirements are harmonizing with ISO 13485 quality management standards for supplier qualification. Manufacturing corridors in Gujarat and Maharashtra attract contract fermentation capacity for enzymatic agent production.
United Kingdom
NHS England integrated care system contracting shifts wound debridement supply purchasing toward multi-year framework agreements with outcomes-linked pricing. MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR technical standards for CE-marked devices. Specialist wound care centers in London and Manchester consolidate procurement leverage for advanced debridement technologies.
Wound Debridement (Wound Cleaning) Market Competitive Landscape
Integrated wound management conglomerates and specialized single-use device fabricators split the market into distinct capability tiers with divergent margin structures and customer access models. Hospital procurement consolidation favors vendors offering bundled supply-and-outcomes contracts over standalone product vendors. Three archetypes dominate: diversified medical technology portfolios anchoring premium placements, sterile disposable specialists capturing infection-control-driven demand, and private-label distributors serving cost-sensitive mid-tier systems. Competitive dynamics center on vertical integration into collagenase fermentation capacity and risk-sharing contract engineering with integrated delivery networks.
Among diversified medical technology portfolios, Smith & Nephew and B. Braun exemplify contrasting strategic positions within the premium-tier segment. Smith & Nephew occupies a position aligned with advanced wound management integration across acute care networks. B. Braun represents the sterile single-use fabrication archetype with emphasis on cross-contamination risk mitigation in surgical environments. Medline Industries anchors the private-label distribution tier, extending cost-competitive enzymatic agent access through established health system supply relationships.
| Leading Market Players |
|---|
| Smith & Nephew |
| B. Braun |
| Coloplast |
| ConvaTec Group |
| Molnlycke Health Care |
| Medline Industries |
| Integra LifeSciences |
| Lohmann & Rauscher |
| 3M |
| Others |
Value Network & Pricing Analysis
Single-source collagenase fermentation capacity concentrated in Baden-Württemberg and Bavaria determines both premium-mid-economy pricing differentiation and the three-tier supply structure tethered to ISO 13485 certification tiers. Hospital procurement consolidation into multi-year risk-sharing agreements compresses margins for standalone vendors while rewarding integrated solution providers with captive biologics production.
Pricing Analysis
Configured-to-order surgical debridement platforms command substantial premiums over standard enzymatic agent formats. The market operates through contract-based long-term offtake agreements bundling consumables with outcomes guarantees, with price differentiation driven by ISO 13485 certification tier and geographic delivery cost. Cost compression in mechanical debridement kits is intensifying because Indian centralized tender mechanisms aggregate volume leverage. Mid-tier health systems exhibit highest price sensitivity, while academic medical centers in Germany and Japan demonstrate lowest sensitivity due to reimbursement code alignment.
Supply Chain Analysis
Export-control regimes restricting advanced ultrasound-based debridement technology flows shape procurement access across emerging markets. Manufacturing concentrates in Germany, Japan, and India, with collagenase fermentation, precision surgical instrumentation, and contract mechanical kit fabrication as core inputs. Single-source vulnerability in specialized biologics fermentation creates structural risk. Distribution runs through integrated delivery networks in the United States, statutory health insurance channels in Germany, and long-term care insurance frameworks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wound debridement functions as a service-attach opportunity where outcomes-linked supply contracts and companion digital monitoring platforms expand faster than standalone device hardware. Recurring revenue from enzymatic agent replenishment and remote patient monitoring subscriptions outpaces capital equipment sales growth.
For Market Incumbents: Insulate premium positioning through backward integration into collagenase fermentation capacity and ISO 13485 certification acceleration. Threats from autolytic dressing substitution in outpatient settings demand defensive bundling of enzymatic agents with digital wound monitoring platforms. Capacity addition in Indian manufacturing corridors captures cost-sensitive tender volume while preserving margin in developed markets.
For New Entrants and Emerging Players: Establish a beachhead in home healthcare debridement modalities where operator-independent enzymatic and autolytic formats face limited incumbent saturation. The United States Medicare Advantage outpatient segment offers most penetrable access due to reimbursement code evolution favoring lower-acuity interventions. A direct-to-home distribution model bypassing hospital procurement gatekeepers enables rapid scale.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified wound management conglomerates with captive biologics supply and risk-sharing contract engineering capabilities. Long-term viability over the projection horizon rests on vertical integration depth and integrated delivery network relationship density. Watch EMA MDR Article 10 enforcement intensity as the signal indicating whether smaller device firms face forced exit or acquisition pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Collagenase Fermentation Capacity Expansion | Captive biologics production insulates margin from raw material concentration risk in German medical technology clusters. |
| Hospital System Risk-Sharing Partnership | Outcomes-linked contracts align supplier incentives with Medicare Advantage capitation models in United States metropolitan markets. |
| CE Marking Pathway Acceleration | EMA MDR compliance investment unlocks European ambulatory wound care procurement concentrated in German statutory insurance networks. |
| Software Companion Development | Digital wound monitoring platforms attach recurring revenue to enzymatic agent consumption in United States home healthcare expansion. |
| Reimbursement Strategy Alignment | WHO guideline certification enables access to National Health Mission tenders in India's centralized government procurement system. |
Research Methodology
A standing panel of wound care clinicians, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare claims data, and hospital procurement contract registries. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored segmentation estimates.
Scenario-bracketing around regulatory pathway evolution and reimbursement code revision shaped the analytical framework across the analysis window. Modeled dimensions span product type, end user facility tier, technology platform, wound etiology application, and regional regulatory cluster. CAGRs derived from procedure volume trajectories, pricing elasticity by segment, and technology substitution curves. Forecast inputs incorporated diabetic ulcer prevalence projections and integrated delivery network consolidation velocity.
Sensitivities concentrate around EMA MDR enforcement intensity, FDA 510(k) predicate device pathway modification, and Medicare Advantage capitation rate adjustment. Forecasts reflect assumptions regarding regulatory stability and reimbursement continuity. Material shifts in biologics cold chain logistics costs or statutory health insurance code coverage would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
South Korea Wound Care Market
Wound Care
Bioactive Wound Management Market
Wound Care
Antimicrobial Regenerative Wound Matrix Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Vascular Dressings Market
Wound Care
Global Silver Wound Dressing Market
Wound Care
Global Antimicrobial Dressings Market
Wound Care
LAMEA Surgical Dressing Market
Wound Care
Hemostats for Wound Closure Market
Wound Care
Europe Negative Pressure Wound Therapy Market
Wound Care
Interactive Wound Dressing Market
Wound Care
Wound Closure Market
Wound Care
Autologous Wound Patches Market
Wound Care
Surgery Medical Bandage Market
Wound Care
Advanced Wound Care and Dressings Market
Wound Care
Brazil Wound Care Management Devices Market