
 Missile Launching Systems Market | 2026-2036
Missile Launching Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Missile Launching Systems Market Analysis
India's defense industrial corridor is rewriting procurement geography for missile launching systems. Lockheed Martin leverages its Aegis combat system integration to dominate naval vertical launch contracts. RTX Corporation sustains propulsion and guidance tie-ins that anchor its launcher subsystem position. Boeing Company specializes in airborne launch platforms that extend its reach beyond traditional naval applications.
Missile launching systems encompass the mechanical, electrical, and control infrastructure that stores, elevates, and fires guided munitions from fixed, mobile, or submerged platforms, typically incorporating gas management, blast containment, and rapid-reload mechanisms rated for salvo intervals under ten seconds. Their primary purpose centers on delivering responsive strike capability while protecting launch crews and host platforms from exhaust impingement and thermal damage. Vertical launch systems command the largest revenue pool due to naval fleet modernization across multiple navies, while electromagnetic launch technology represents the fastest-expanding segment as railgun and coilgun research transitions from testbed to prototype deployment. Mobile launchers retain entrenched demand from land-based strategic deterrent forces requiring shoot-and-scoot survivability.
The US Department of Defense imposes MIL-STD-1760 and MIL-STD-1553 compliance that dictates electrical interface architecture for all launcher-weapon integrations, while NATO's STANAG 4170 establishes safety and interoperability benchmarks for member nation procurements. The US Navy's Naval Sea Systems Command certifies every surface and subsurface launcher through rigorous shock, vibration, and electromagnetic compatibility protocols that create substantial barriers to non-aligned suppliers. Stakeholders must monitor AUKUS technology-sharing implementation and its potential to reshape supplier eligibility for integrated launcher-missile packages across three allied defense industrial bases.
Market Dynamics
Naval modernization programs are compressing launcher procurement cycles as NATO members replace Cold War-era vertical launch systems with modular, multi-mission architectures capable of accommodating hypersonic weapons and electromagnetic munitions within unified magazine spaces.
Growth Catalysts
- STANAG 4170 Harmonization:NATO's safety and interoperability benchmarks are standardizing launcher-missile interfaces across member fleets, reducing integration costs for cross-alliance procurement.
- Hypersonic Weapon Integration:The US Department of Defense's push for prompt global strike capability is forcing launcher redesigns with reinforced thermal protection and extended barrel life.
- Submarine-Launched Ballistic Missile Expansion:AUKUS technology-sharing agreements are opening integrated launcher development across Australian, UK, and US defense industrial bases.
Market Restraints
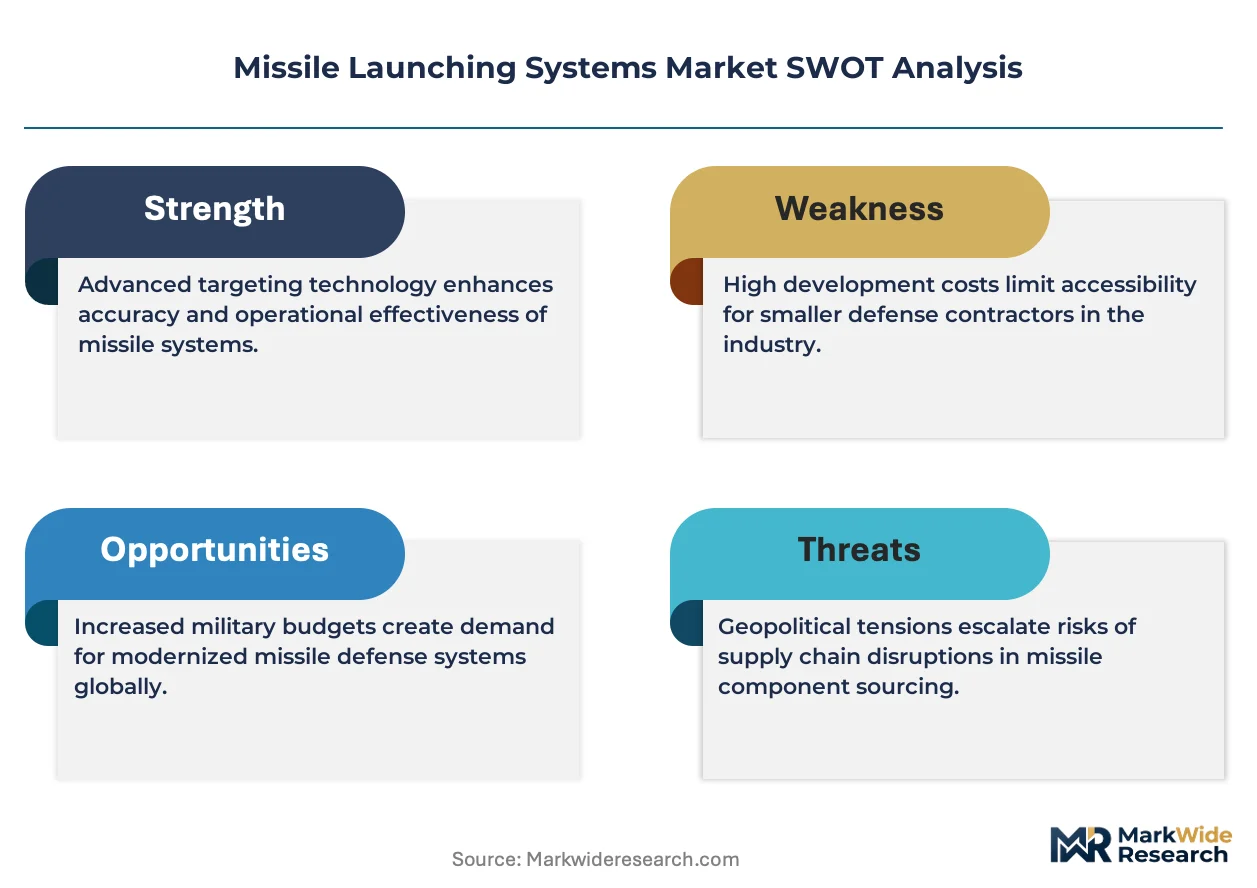
- Nickel Superalloy Supply Concentration:Blast containment systems depend on Inconel and Haynes alloys sourced primarily from US and Russian smelters, creating input vulnerability.
- MIL-STD-1760 Certification Burden:US electrical interface mandates impose multi-year validation timelines that exclude non-aligned suppliers from Navy contracts.
- Electromagnetic Launch Immaturity:Railgun and coilgun prototypes remain confined to land-based testbeds, delaying naval adoption by at least one procurement cycle.
Strategic Opportunities
- Indian Defense Industrial Corridor:India's PLI scheme for aerospace and defense is attracting foreign launcher subsystem vendors to establish captive production near missile integration facilities.
- Modular Canister Architecture:Converging mechanical and software interfaces enable single launch cells to accommodate anti-air, anti-ship, and land-attack munitions interchangeably.
- Japan's Counterstrike Capability:METI defense production incentives are funding mobile launcher platforms for island defense applications previously restricted by pacifist doctrine.
Industry Challenges
- Gas Management Engineering Talent:Exhaust plume modeling and blast suppression design require specialized computational fluid dynamics expertise concentrated at a handful of US and European defense laboratories.
- Legacy System Integration Friction:New vertical launch modules must interface with Aegis combat systems dating to the 1980s, forcing expensive middleware development for digital-analog translation.
- Electromagnetic Compatibility Recertification:Each launcher variant requires Naval Sea Systems Command shock and vibration testing that resets when platform electronics change.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Missile Launching Systems Market |
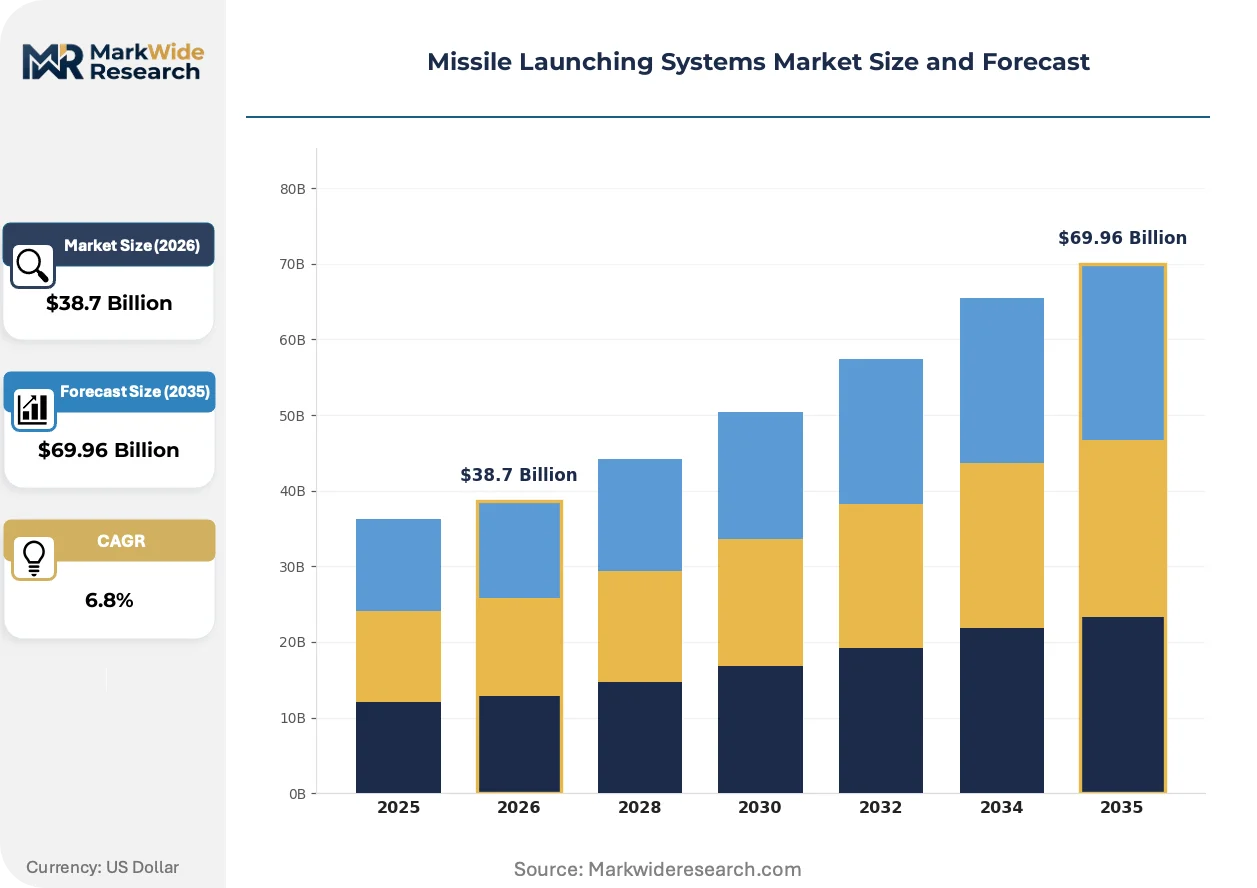
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Launch Systems, Mobile Launchers, Static Launchers, Submarine Launch Systems Technology: Ballistic Technology, Cruise Technology, Hybrid Technology, Electromagnetic Technology End User: Military Forces, Defense Contractors, Government Agencies, Research Institutions Deployment: Onshore, Offshore, Airborne, Ground-Based |
| Companies Covered | Boeing Company, General Dynamics Corporation, Lockheed Martin Corporation, L3Harris Technologies, BAE Systems, RTX Corporation, MBDA, Israel Aerospace Industries, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Missile Launching Systems Market Emerging Trajectories
Launcher architecture is pivoting from fixed-mission silos toward adaptable magazine systems that accommodate evolving munition form factors through software-defined configuration rather than mechanical refit.
Electromagnetic launch technology is migrating from laboratory railgun testbeds at Dahlgren and China Lake toward prototype naval mounts capable of accelerating projectiles without chemical propellant. The US Navy's Surface Warfare Directorate is funding integrated power systems that can divert megawatt-scale energy from ship propulsion to launcher capacitors. This shift is compressing the traditional propellant supply chain while demanding entirely new thermal management and barrel erosion mitigation subsystems.
The EU's proposed Defence Industrial Readiness Board is mandating cross-border component sourcing thresholds for member state naval procurements, forcing launcher integrators to dual-source critical electronics from French, German, and Italian suppliers. This restructuring fragments previously consolidated supply relationships. Surface combatant programs in Spain and Italy are now requiring STANAG-compliant interfaces that preempt US MIL-STD dominance in European waters.
Buyer consolidation around sovereign fleet operators is displacing the fragmented national procurement patterns that characterized Cold War launcher markets. Australia's AUKUS submarine program and Canada's Surface Combatant initiative are both specifying US-derived vertical launch systems, compressing vendor diversity. This concentration rewards integrators with established Naval Sea Systems Command certification histories while marginalizing second-tier suppliers lacking shock-test data archives.
Missile Launching Systems Market Segmentation
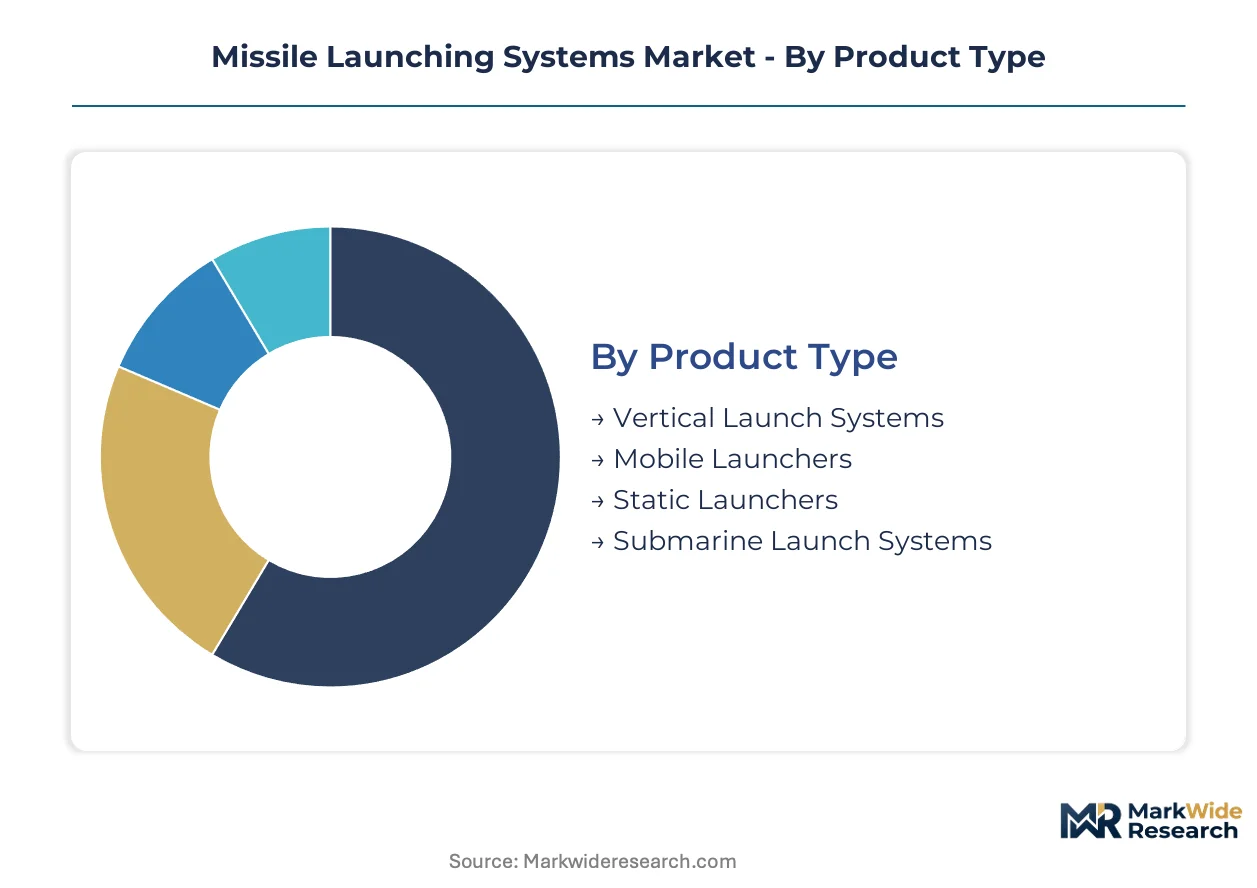
Missile launching systems fragment across four critical dimensions that determine procurement priorities, certification pathways, and technology roadmaps. Each segmentation axis reveals distinct competitive dynamics and buyer concentration patterns that shape vendor positioning strategies.
Product Type:
Mature naval architectures dominate procurement volumes while emerging electromagnetic platforms rewrite performance benchmarks.
- Vertical Launch Systems:Enclosed multi-cell magazines with gas management and blast containment rated for salvo intervals under ten seconds. NATO naval modernization programs concentrate demand in the US, UK, and Australia as AUKUS partners replace Cold War-era architectures with modular designs.
- Mobile Launchers:Road- and rail-transportable platforms with rapid emplacement and shoot-and-scoot survivability features. Strategic deterrent forces in India and Russia anchor procurement, driven by requirements for dispersal and concealment against counterforce targeting.
- Static Launchers:Fixed silo installations with hardened command and control infrastructure for land-based strategic systems.
- Submarine Launch Systems:Pressure-hull-integrated tubes with buoyant missile ejection mechanisms for submerged platforms.
Vertical launch systems handle the majority of throughput; mobile launchers are the fastest mover on share.
Technology:
Cost tier stratification separates proven propulsion methods from capital-intensive electromagnetic alternatives still confined to testbeds.
- Ballistic Technology:Rocket-propelled trajectories with exoatmospheric midcourse phases and terminal reentry vehicles. US Department of Defense prompt global strike initiatives concentrate development investment at Dahlgren and China Lake facilities.
- Cruise Technology:Air-breathing engines sustaining atmospheric flight with terrain-following guidance. Maritime strike applications across Indo-Pacific theater navies drive integration with vertical launch cells.
- Hybrid Technology:Combined cycle propulsion transitioning between rocket boost and ramjet sustainment.
- Electromagnetic Technology:Railgun and coilgun acceleration without chemical propellant, requiring megawatt-scale shipboard power systems.
Cruise technology commands the widest application footprint; electromagnetic platforms show the steepest expansion trajectory pending naval prototype maturation.
End User:
Customer type determines contract structure, with sovereign fleet operators consolidating procurement around integrated system-of-systems awards.
- Military Forces:Uniformed service branches operating launchers as organic weapons systems. US Navy Naval Sea Systems Command certification requirements create substantial barriers to non-aligned suppliers seeking surface and subsurface contracts.
- Defense Contractors:Prime integrators assembling launcher-missile packages for government clients. India's defense industrial corridor PLI scheme is attracting foreign subsystem vendors to establish captive production near missile integration facilities.
- Government Agencies:National laboratories and test ranges conducting evaluation and certification protocols.
- Research Institutions:Academic and applied research centers advancing electromagnetic launch physics and materials science.
Military forces absorb the dominant contract value; defense contractors are gaining procurement influence through offset and technology transfer mandates.
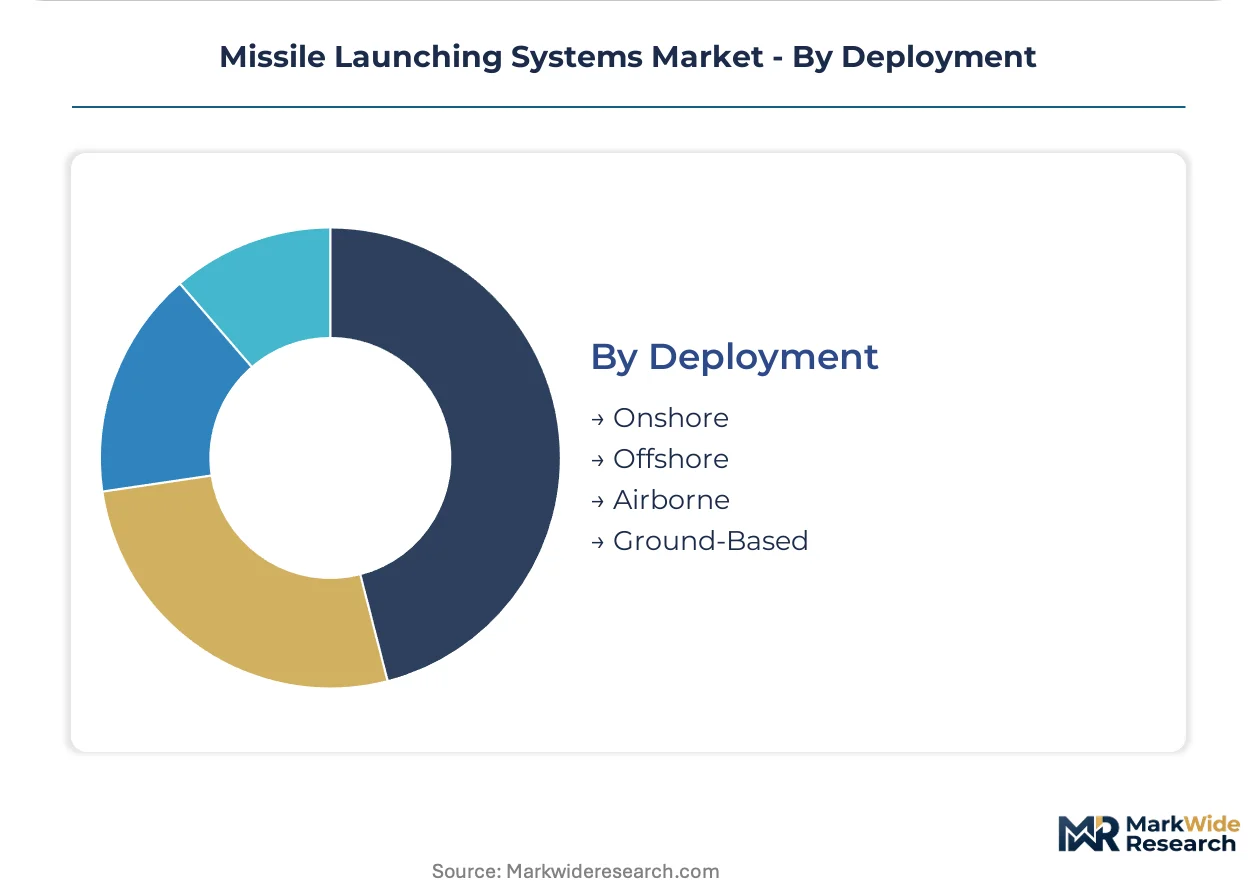
Deployment:
Geography of installation dictates environmental qualification standards and platform integration complexity.
- Onshore:Fixed and mobile installations on continental territory with established logistics infrastructure. Japan's METI-funded counterstrike programs are expanding mobile launcher procurement for island defense applications.
- Offshore:Surface combatant and submarine platforms operating in maritime environments. Canada's Surface Combatant initiative and Australia's AUKUS submarine program both specify US-derived vertical launch architectures.
- Airborne:Aircraft-integrated launch rails and internal bay systems for standoff weapons delivery.
- Ground-Based:Terrestrial fixed sites with hardened silos and distributed command networks.
Offshore deployment generates the largest certification expenditure; ground-based systems are climbing fastest as strategic modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Navy's Pacific Fleet infrastructure at Naval Base San Diego underwrites American dominance in naval vertical launch procurement. India's defense industrial corridor along the Chennai-Bengaluru axis is rewriting supplier geography for launcher subsystems.
United States
Naval Sea Systems Command certification requirements and AUKUS technology-sharing obligations drive procurement of modular vertical launch architectures. The Department of Defense's MIL-STD-1760 and MIL-STD-1553 mandates create multi-year validation barriers that exclude non-aligned suppliers. Dahlgren and China Lake test ranges anchor electromagnetic launch research, with railgun prototypes transitioning from land-based testbeds toward naval mounts.
United Kingdom
AUKUS submarine-launched ballistic missile expansion and Royal Navy surface combatant modernization concentrate demand for pressure-hull-integrated launch systems. The Ministry of Defence's integration with US Naval Sea Systems Command protocols ensures STANAG 4170 compliance across NATO interoperability benchmarks. Barrow-in-Furness submarine construction facilities and Glasgow shipyards host integrated launcher-missile package assembly for next-generation deterrent platforms.
Australia
AUKUS nuclear-powered submarine acquisition and Surface Combatant fleet replacement specify US-derived vertical launch architectures. The Department of Defence's technology-sharing implementation opens integrated launcher development across Australian, UK, and US industrial bases. Osborne naval shipyard in South Australia and Henderson maritime precinct in Western Australia are establishing captive production capabilities for launcher subsystem integration.
India
Defense industrial corridor PLI schemes and strategic deterrent modernization accelerate mobile launcher procurement for land-based forces. The Ministry of Defence's offset mandates attract foreign subsystem vendors to establish production near missile integration facilities. Tamil Nadu's aerospace cluster and Bengaluru's defense electronics corridor host emerging launcher component manufacturing for indigenous strategic programs.
Japan
METI defense production incentives and counterstrike capability expansion fund mobile launcher platforms for island defense applications. The Ministry of Economy, Trade and Industry's funding mechanisms support rapid emplacement systems previously restricted by pacifist doctrine. Nagoya's precision manufacturing belt and Kobe's heavy industrial zone concentrate launcher platform fabrication for maritime strike applications.
Missile Launching Systems Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in propulsion, guidance, and blast containment subsystems. The vendor base stratifies between prime contractors with Naval Sea Systems Command certification histories and second-tier suppliers lacking shock-test data archives. Two strategic archetypes dominate: combat system integrators leveraging Aegis integration relationships, and subsystem vendors sustaining propulsion and guidance tie-ins. Competitive moves center on modular canister architecture development and electromagnetic launch technology licensing.
Within the combat system integration tier, Lockheed Martin Corporation and RTX Corporation exemplify platform-level positioning through established naval certification pathways. Boeing Company occupies a distinct position in airborne launch platforms that extends reach beyond traditional naval applications. These three anchors represent divergent specialization vectors—naval vertical launch dominance, subsystem propulsion integration, and aerial platform extension—rather than direct overlap in contract competition.
| Leading Market Players |
|---|
| Boeing Company |
| General Dynamics Corporation |
| Lockheed Martin Corporation |
| L3Harris Technologies |
| BAE Systems |
| RTX Corporation |
| MBDA |
| Israel Aerospace Industries |
| Northrop Grumman Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in nickel superalloy smelting capacity across US and Russian facilities is compressing input availability for blast containment systems, forcing launcher integrators to absorb cost volatility while extending procurement timelines for NATO naval programs. This feedstock tightness amplifies pricing power for certified suppliers with Naval Sea Systems Command validation histories, while squeezing margins for second-tier vendors locked out of AUKUS technology-sharing channels.
Pricing Analysis
Volume-discount tiering structures separate prime contractors with multi-year fleet modernization awards from subsystem vendors bidding single-cell procurements. Pricing stratifies across STANAG 4170-certified integrators, MIL-STD-1760-compliant mid-tier suppliers, and non-aligned economy vendors excluded from US Navy contracts. Cost compression in electromagnetic launch subsystems is intensifying because megawatt-scale power system development remains confined to Dahlgren and China Lake test ranges. Sovereign fleet operators exhibit lowest price sensitivity due to AUKUS interoperability mandates, while India's defense industrial corridor buyers negotiate aggressively on offset-adjusted terms.
Supply Chain Analysis
Upstream feedstock for blast containment systems draws from Inconel and Haynes alloy production concentrated in US, Russian, and limited European smelters. Launcher mechanical infrastructure rests on high-grade steel forgings from Japan and Germany, while gas management electronics source from Taiwan and South Korean semiconductor fabs. Single-source vulnerability in nickel superalloy supply creates procurement risk for NATO vertical launch programs. Distribution runs through prime contractor assembly at Naval Sea Systems Command-certified facilities, with subsystem vendors delivering to Barrow-in-Furness, Osborne, and Newport News integration sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across electromagnetic launch readiness levels is creating specialist niches as railgun prototype maturation diverges from operational vertical launch demand. Modular canister architecture standardization is splintering procurement between software-configurable integrators and legacy mechanical refit vendors.
For Market Incumbents: Entrench Naval Sea Systems Command certification advantages by deepening shock-test data archives and expanding Aegis combat system integration relationships. Lockheed Martin and RTX Corporation should fortify positions against emerging electromagnetic launch specialists by capturing modular magazine contracts across AUKUS submarine and Canadian Surface Combatant programs. Vertical integration into nickel superalloy sourcing mitigates supply concentration risk. For New Entrants and Emerging Players: India's defense industrial corridor underpenetration by certified blast containment subsystem vendors offers the most accessible entry path. Tamil Nadu aerospace clusters and Bengaluru defense electronics corridors lack captive production for gas management electronics, creating white-space for STANAG 4170-compliant suppliers. Japan's METI-funded counterstrike mobile launcher programs present secondary opportunity through precision manufacturing partnerships in Nagoya and Kobe industrial zones. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subsystem vendors with MIL-STD-1760 certification entrenchment and multi-year NATO naval modernization backlog. Long-term viability favors electromagnetic launch technology licensors with China Lake prototype relationships and megawatt power system integration capabilities. The signal to monitor is AUKUS technology-sharing implementation velocity as inflection indicator for integrated launcher-missile package supplier eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Canister Architecture Development | Enables single launch cells to accommodate anti-air, anti-ship, and land-attack munitions interchangeably across AUKUS fleets. |
| Electromagnetic Launch Technology Licensing | Railgun and coilgun prototype maturation at Dahlgren redirects procurement from chemical propellant supply chains. |
| Naval Sea Systems Command Certification Investment | Shock-test data archives create exclusionary barriers for non-aligned suppliers seeking surface combatant contracts. |
| Indian Defense Industrial Corridor Establishment | PLI scheme incentives attract foreign subsystem vendors to captive production near missile integration facilities. |
| AUKUS Technology-Sharing Integration | Opens integrated launcher development across Australian, UK, and US defense industrial bases for submarine programs. |
Methodological Framework
A standing panel of naval program executives, launcher subsystem engineering directors, Naval Sea Systems Command certification officers, and defense procurement attachés provided ongoing calibration across primary interview cycles. Secondary validation drew from US Department of Defense budget justification documents, NATO STANAG publication registers, AUKUS implementation guidance releases, and customs trade data for nickel superalloy shipments. Bottom-up triangulation across platform-level procurement awards converged with top-down analysis of fleet modernization timelines.
Scenario-bracketing framed projections across the analysis window by modeling vertical launch system, mobile launcher, submarine launch system, and electromagnetic platform segments against technology readiness levels and end-user certification requirements. CAGRs were derived from procurement cycle compression analysis and platform replacement schedules across NATO, AUKUS, and Indo-Pacific theater navies. Hypersonic weapon integration timelines and electromagnetic launch prototype maturation curves served as industry-specific forecast inputs.
Practitioners should monitor AUKUS technology-sharing implementation velocity, nickel superalloy supply disruption indicators, and electromagnetic launch prototype naval mounting schedules for early signals of forecast revision. Cross-checking against Naval Sea Systems Command certification queue depth and STANAG 4170 harmonization progress is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Global Rockets and Missiles Market
Weapons and Ammunition
Sports Shotgun Market
Weapons and Ammunition
Non Lethal Projectiles Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Less Lethal Ammunition Market
Weapons and Ammunition
Ammunition Storage Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Cluster Munitions Market
Weapons and Ammunition
Space Weapons Market
Weapons and Ammunition
Global Artillery Systems Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market