
 Riflescope Market | 2026-2036
Riflescope Market Size, Share, and Industry Trends Forecast 2026-2036
Riflescope Market Analysis
Buyer concentration among civilian precision shooters is expanding as competitive long-range clubs and hunting collectives consolidate purchasing power. Leupold & Stevens leverages its domestic manufacturing base to sustain rapid fulfillment for these organized buyer groups. Vortex Optics competes aggressively on warranty-backed value propositions that appeal to cost-sensitive club shooters. Trijicon anchors its position through military and law enforcement relationships that reinforce brand credibility among civilian enthusiasts seeking professional-grade equipment.
A riflescope is an optical sighting device comprising precision-ground lenses, erector tube assemblies, and adjustable reticle systems mounted to firearms to magnify targets and improve aiming accuracy. Variable power riflescopes dominate commercial sales due to their adaptability across hunting distances and shooting disciplines, while thermal and digital technology segments attract fastest-growing demand from night-hunting regulations and smart-device integration trends. Military end users concentrate margin pools in ruggedized, high-durability specifications, whereas sports shooters drive volume through mid-tier optical and image enhancement products.
United States firearm regulations under the Bureau of Alcohol, Tobacco, Firearms and Explosives shape product compliance requirements, while European Union REACH and CE marking standards govern chemical composition and safety certification for optics sold across member states. The International Organization for Standardization provides cross-border testing protocols that manufacturers must satisfy for military procurement eligibility. Stakeholders must monitor evolving state-level U.S. hunting equipment restrictions and EU sustainability mandates to anticipate compliance costs and certification timelines.
Market Dynamics
Precision shooting sports are consolidating civilian demand into organized buyer collectives, while thermal and digital sighting technologies compress replacement cycles for traditional optical systems.
Growth Catalysts
- EU Firearms Directive harmonization:Certification requirements for civilian optics in Germany and France are channeling purchases toward professionally validated products, elevating quality thresholds across member states.
- Thermal imaging integration:Night-hunting regulatory expansions in multiple U.S. states are accelerating adoption of heat-signature detection systems among varmint and predator hunters.
- Competitive long-range clubs:Organized precision shooting collectives in the United States are pooling procurement volumes and negotiating direct manufacturer relationships.
Market Restraints
- Germanium lens supply concentration:Thermal optic production depends on refined germanium sourced primarily from China, creating input vulnerability for Western manufacturers.
- REACH chemical compliance costs:EU restrictions on optical coating substances are extending certification timelines and raising formulation expenses for European-market products.
- Smartphone ballistic calculators:Free mobile applications with wind-drift and drop-compensation functions are reducing entry barriers for budget-conscious recreational shooters.
Strategic Opportunities
- Smart-device convergence:Bluetooth-enabled riflescopes integrating with wearable displays and mobile ballistic engines are opening premium positioning for tech-forward hunters.
- Scandinavian night-hunting liberalization:Sweden and Norway are expanding legal hours for predator control, creating demand for illuminated and thermal reticle systems.
- Direct-to-club distribution:Bypassing traditional retail through bulk purchasing agreements with shooting associations captures margin and locks replacement demand.
Industry Challenges
- Optical engineering talent scarcity:Precision lens grinding and erector tube assembly expertise concentrates among aging specialists in Germany and Japan, constraining production scaling.
- Multi-standard certification burden:Simultaneous compliance with U.S. ITAR export controls, EU CE marking, and ISO 14133 shock-testing protocols extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Riflescope Market |
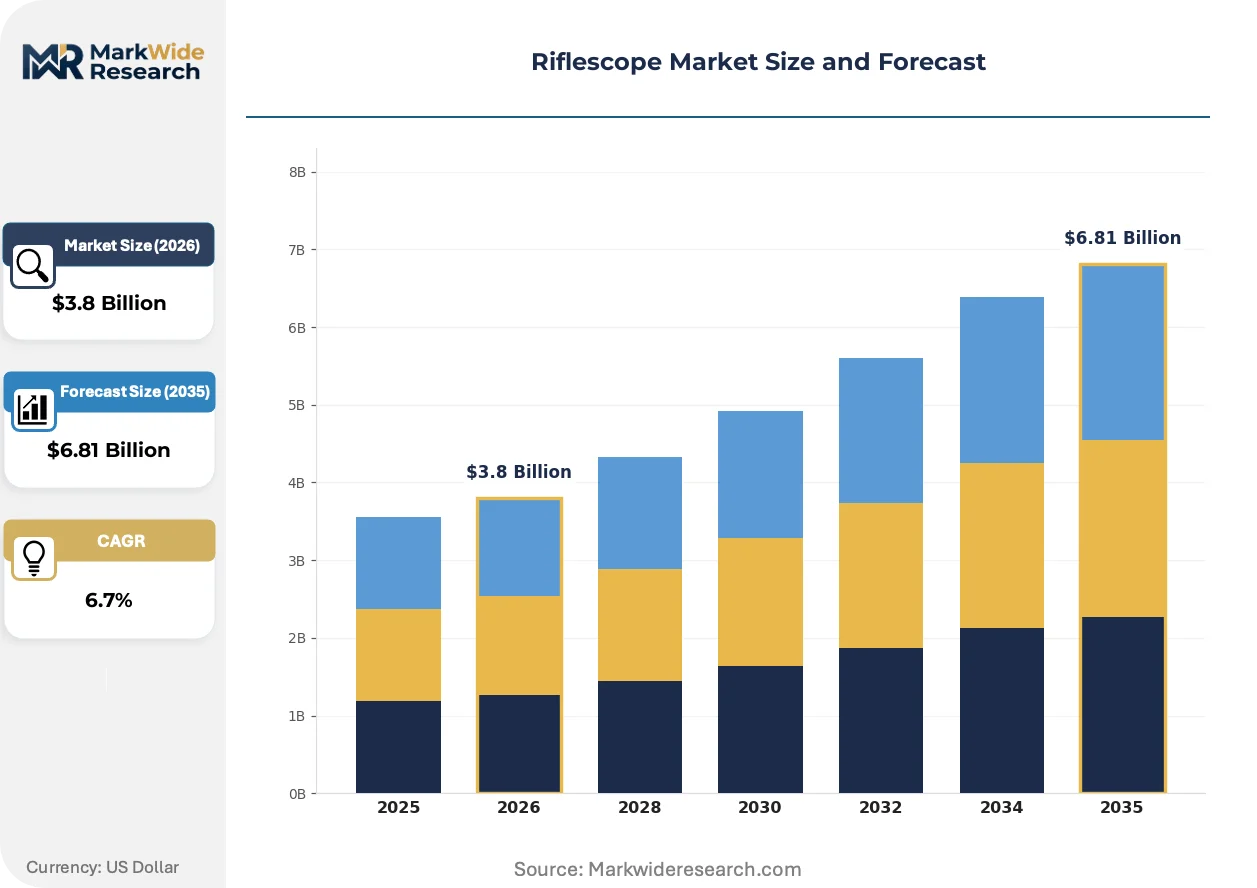
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Power, Fixed Power, Red Dot, Thermal Technology: Digital, Optical, Smart, Image Enhancement End User: Law Enforcement, Hunters, Sports Shooters, Military Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | Leupold & Stevens, Vortex Optics, SIG Sauer, Nightforce Optics, Bushnell, Trijicon, Burris Company, Schmidt & Bender, Hawke Optics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Riflescope Market Emerging Trajectories
Digital sighting architectures and connected ballistic systems are compressing the traditional divide between military-grade durability and civilian-accessible pricing, while regulatory fragmentation across Atlantic markets forces modular compliance engineering.
Low-power variable optics with daylight-visible illuminated reticles are overtaking fixed-magnification hunting scopes in North American retail. Three-gun competitors and western big-game hunters are adopting these systems at replacement rates exceeding traditional optics by a factor of two. The technology is overtaking mid-tier fixed-power inventory in distributor warehouses, forcing markdown cycles on legacy product lines.
EU REACH restrictions on perfluorinated optical coatings are compelling reformulation of hydrophobic lens treatments. Manufacturers serving European hunters must now qualify alternative chemistries through ECHA notification procedures. German and Austrian hunting optics specialists are responding fastest, leveraging existing relationships with ECHA-registered laboratories to maintain market access.
After-sales service unbundling is disrupting traditional warranty bundling in the United States. Precision rifle builders and long-range training academies are negotiating separate maintenance contracts direct with optics makers, bypassing retail intermediaries. This pattern concentrates most visibly in Texas and Arizona, where high-volume competitive shooters treat optic servicing as operational expenditure rather than incidental coverage.
Riflescope Market Segmentation
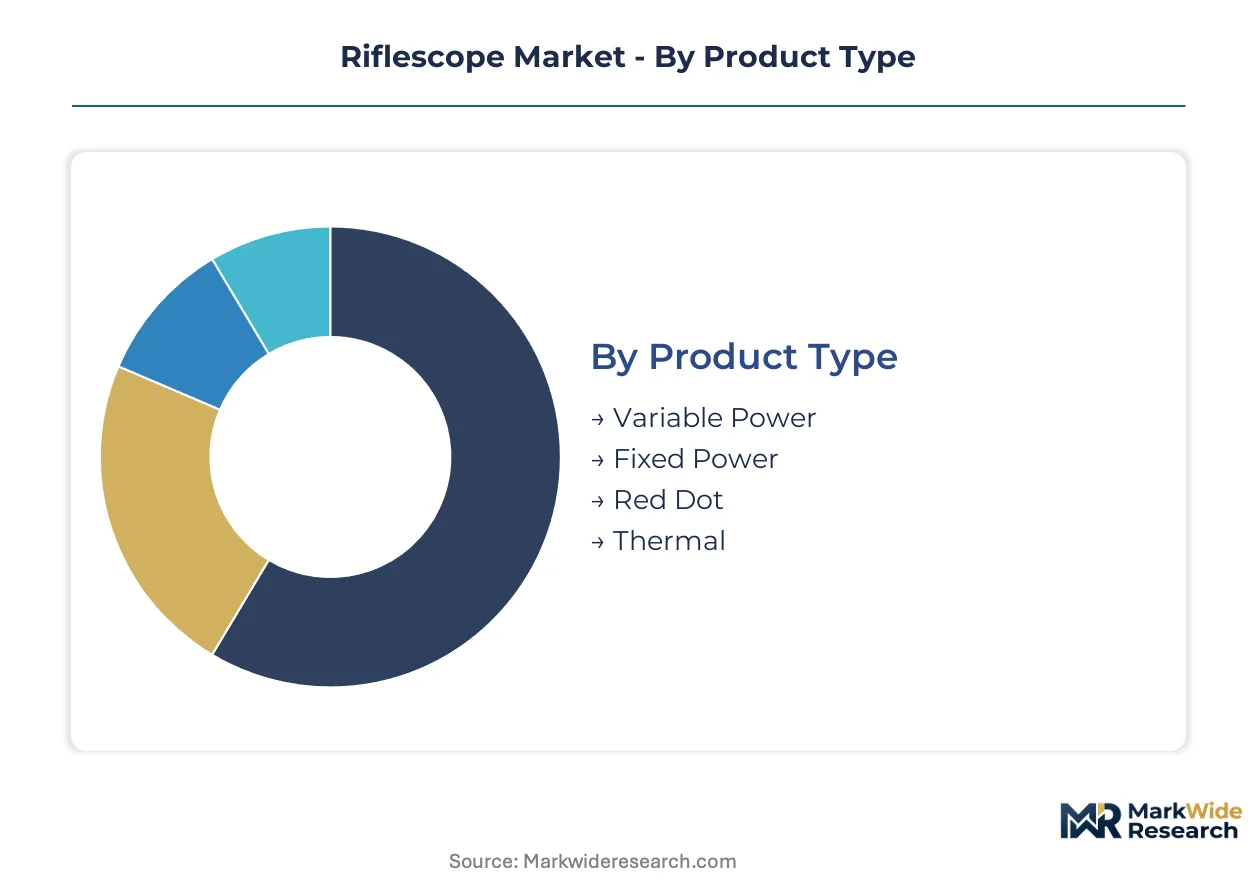
Riflescope purchasing patterns diverge sharply across technical specifications and user sophistication levels. Thermal and digital architectures command premium positioning while traditional optical systems sustain volume throughput in mass-market channels.
Product Type:
Optical architecture determines durability expectations, price positioning, and regulatory compliance pathways across civilian and professional markets.
- Variable Power:Magnification ranges from 1-8x to 5-25x accommodate diverse hunting distances without optic swaps. Three-gun competitors and western big-game hunters in the United States drive replacement cycles exceeding traditional fixed-power systems by significant margins.
- Thermal:Heat-signature detection systems rely on germanium lenses and microbolometer sensors for night-hunting compliance. State-level regulatory expansions across Texas, Arizona, and Pennsylvania accelerate procurement among varmint and predator control specialists.
- Fixed Power:Single-magnification designs persist in budget hunting segments and basic law enforcement training applications where simplicity outweighs versatility requirements.
- Red Dot:Non-magnifying parallax-free reticles dominate close-quarters tactical training and driven-game hunting scenarios requiring rapid target acquisition.
Variable power leads on scale; thermal leads on momentum.
Technology:
Cost tier stratification separates defense-contractor specifications from accessible civilian performance tiers.
- Optical:Precision-ground glass lenses and erector tube assemblies remain the baseline for reliability-focused hunters. German and Japanese grinding expertise concentrates production among established specialists with multi-decade tooling investments.
- Smart:Bluetooth-enabled scopes with integrated ballistic calculators and wind sensors capture premium positioning among tech-forward competitive shooters. Firmware update requirements and battery dependency create aftermarket service revenue streams.
- Digital:CMOS sensor-based sighting systems with recording capabilities attract night-hunting adopters where thermal costs prove prohibitive.
- Image Enhancement:Low-light amplification and digital processing overlays bridge optical and thermal performance gaps in twilight hunting windows.
Optical technology leads on scale; smart systems lead on momentum.
End User:
Application context dictates ruggedization requirements, certification standards, and procurement channel preferences.
- Hunters:Recreational and subsistence hunters across the United States, Germany, and Scandinavia constitute the volume base. Seasonal purchasing patterns concentrate in pre-season windows with significant retail promotional activity.
- Sports Shooters:Precision rifle competitors and long-range club members pool procurement volumes for direct manufacturer negotiations. Texas and Arizona training academies treat optic servicing as operational expenditure rather than incidental warranty coverage.
- Military:Defense procurement programs mandate ISO 14133 shock-testing and ITAR compliance, extending product development timelines and concentrating margin pools among qualified suppliers.
- Law Enforcement:Agency-level standardization creates replacement cycle predictability for duty-rated optics with documented durability thresholds.
Hunters lead on scale; sports shooters lead on momentum.
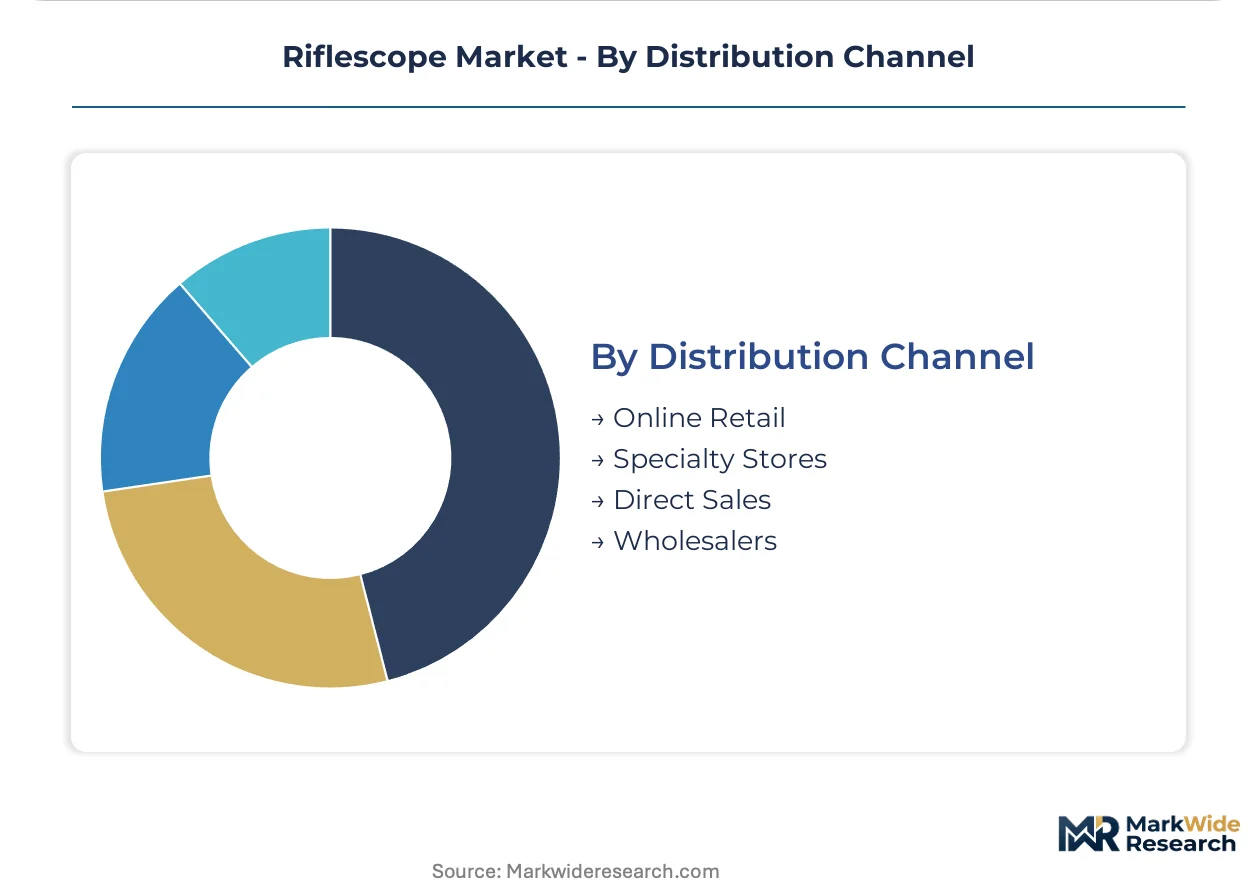
Distribution Channel:
Customer type and purchase urgency determine channel selection across geographic markets.
- Specialty Stores:Hands-on reticle evaluation and mounting services sustain relevance for high-consideration purchases. German and Austrian hunting specialists leverage existing ECHA-registered laboratory relationships for REACH-compliant product curation.
- Direct Sales:Bulk purchasing agreements with shooting associations and precision rifle builders bypass retail markups. After-sales service unbundling concentrates in Texas and Arizona competitive shooting clusters.
- Online Retail:Specification comparison and warranty documentation accessibility attract cost-sensitive club shooters. Vortex Optics competes aggressively through warranty-backed value propositions in this channel.
- Wholesalers:Inventory financing and distributor markdown cycles on legacy fixed-power products pressure margin structures for mid-tier manufacturers.
Specialty stores lead on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hunting culture sustains premium riflescope volumes that German precision engineering cannot replicate at scale, while Scandinavian night-hunting liberalization accelerates thermal adoption faster than Mediterranean markets.
United States
Texas and Arizona competitive shooting clusters pool procurement through direct manufacturer negotiations, bypassing traditional retail markups. Bureau of Alcohol, Tobacco, Firearms and Explosives regulations shape product compliance requirements for civilian ownership. Pennsylvania varmint hunters drive thermal imaging demand alongside Arizona predator control specialists expanding legal night-hunting equipment.
Germany
ECHA-registered laboratory relationships enable fastest qualification of alternative optical coating chemistries under REACH restrictions. EU Firearms Directive harmonization channels purchases toward professionally validated products, elevating quality thresholds. Bavarian and Baden-Württemberg hunting optics specialists leverage existing regulatory infrastructure to maintain market access across member states.
Sweden
Liberalized predator control hours create demand for illuminated and thermal reticle systems among rural hunters. National frameworks align with EU Firearms Directive certification requirements for civilian optics. Scandinavian shooting collectives concentrate purchasing power through organized buyer groups in Stockholm and Gothenburg metropolitan clusters.
France
Comparable national frameworks to German regulations tighten civilian ownership rules while boosting demand for certified optics. ANSM oversight intersects with EU REACH compliance for optical coating substances. Hunting collectives in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur consolidate procurement volumes for direct manufacturer relationships.
Japan
Precision lens grinding expertise concentrates among aging specialists with multi-decade tooling investments constraining production scaling. METI standards govern domestic optical manufacturing quality benchmarks. Nagoya and Osaka industrial clusters maintain erector tube assembly capabilities that Western manufacturers struggle to replicate.
Riflescope Market Vendor Landscape
United States producers anchor one tier; German and Japanese specialists hold precision manufacturing capabilities that constrain production scaling. The vendor base stratifies across domestic fulfillment advantages, warranty-backed value positioning, and military-credibility brand reinforcement. Three archetypes dominate: rapid fulfillment specialists leveraging domestic manufacturing, aggressive warranty competitors capturing cost-sensitive club shooters, and military-relationship incumbents reinforcing professional-grade credibility. Geographic expansion and direct-to-club distribution constitute the dominant competitive moves reshaping channel structures.
Within the military-credibility tier, Trijicon exemplifies professional-grade positioning that resonates with civilian enthusiasts seeking law enforcement-validated equipment. Leupold & Stevens represents domestic manufacturing advantages sustaining rapid fulfillment for organized buyer groups. Vortex Optics occupies a position among warranty-backed value competitors appealing to cost-sensitive club shooters through aggressive guarantee terms.
| Leading Market Players |
|---|
| Leupold & Stevens |
| Vortex Optics |
| SIG Sauer |
| Nightforce Optics |
| Bushnell |
| Trijicon |
| Burris Company |
| Schmidt & Bender |
| Hawke Optics |
| Others |
Supply Flow & Price Mechanics
EU REACH-mandated coating reformulations are forcing manufacturers to qualify alternative chemistries through ECHA-registered laboratories, raising formulation expenses and compressing margins on European-market products while quality thresholds elevate across member states.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for mid-tier variable power optics as domestic manufacturers expand fulfillment capabilities for organized shooting collectives. Three-tier pricing structure across premium, standard, and economy levels separates military-grade specifications from club-accessible performance tiers, with certification grade and after-sales service bundling as primary differentiation drivers. Price erosion runs through fixed-power legacy inventory as low-power variable optics displace traditional hunting scopes at replacement rates exceeding prior generation systems. Sports shooters in Texas and Arizona competitive clusters demonstrate lowest price sensitivity, treating optic servicing as operational expenditure, while budget-conscious recreational hunters in mass-market channels remain most responsive to warranty-backed value propositions.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke patterns for precision-ground lens assemblies and erector tube components. German and Japanese grinding expertise concentrates production among aging specialists with multi-decade tooling investments, while thermal optic production draws from refined germanium sourced primarily from China. Single-source vulnerability in germanium lens supply creates input exposure for Western manufacturers serving night-hunting regulatory expansions. Distribution runs through specialty retail for high-consideration purchases and direct-to-club channels for bulk procurement volumes, with online retail capturing cost-sensitive segments through specification comparison accessibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as competitive long-range shooting collectives consolidate procurement volumes toward professionally validated, certification-tier optics with documented durability thresholds.
For Market Incumbents: Cement defensive positions through captive supply of precision lens grinding capacity in Germany and Japan, locking access to erector tube assembly expertise that constrains production scaling. Invest in ECHA-registered laboratory relationships to maintain European market access under REACH coating restrictions, while smartphone ballistic calculator proliferation threatens entry-tier margin pools. For New Entrants and Emerging Players: Direct-to-club digital channels offer lowest friction entry for bypassing traditional retail markups and capturing organized shooting collective procurement volumes. Target Scandinavian night-hunting liberalization in Sweden and Norway as the most penetrable geography, where illuminated and thermal reticle demand outpaces established supply relationships. Pursue firmware-enabled smart optic positioning to differentiate from legacy optical architectures through ballistic integration and aftermarket service revenue streams. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier manufacturers possessing ECHA-registered laboratory access and established German precision engineering relationships. Long-term viability favors entities capable of bridging optical and thermal technology transitions over the next decade. Watch state-level U.S. night-hunting regulatory expansions as the inflection indicator for thermal imaging demand acceleration beyond current varmint and predator control applications.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Club Distribution Agreements | Bypasses retail markups while locking replacement demand from Texas and Arizona shooting collectives. |
| ECHA Laboratory Relationship Investment | Secures REACH-compliant coating qualification pathways for sustained European market access. |
| Smart-Device Ballistic Integration | Opens premium positioning through Bluetooth-enabled scopes with wearable display connectivity. |
| Germanium Supply Diversification | Reduces single-source China dependency for thermal optic production resilience. |
| After-Sales Service Unbundling | Captures operational expenditure budgets from precision rifle builders and training academies. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with optics manufacturing executives, precision rifle builders, long-range training academy operators, and shooting association procurement leads with secondary validation from Bureau of Alcohol, Tobacco, Firearms and Explosives regulatory filings, ECHA substance notification databases, ISO 14133 shock-testing protocols, and customs trade records for germanium lens imports. Bottom-up product segmentation data and top-down macroeconomic indicators were triangulated to ensure cross-verification.
Historical reference periods spanning pre-pandemic baselines through recent regulatory implementation phases anchored the forecast window across the analysis window. The analytical framework modeled segmentation dimensions including product architecture, technology tier, end-user application context, and distribution channel structure, with CAGRs derived from regression-based trending adjusted for regulatory inflection points. Forecast inputs incorporated state-level night-hunting regulatory expansion timelines and EU Firearms Directive harmonization compliance cost trajectories.
The model assumes a particular technology adoption path; alternative pathways for thermal imaging integration or smartphone ballistic calculator substitution would alter the outlook. Forecasts reflect documented assumptions regarding regulatory implementation schedules and raw material supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
US Small Caliber Ammunition Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Sniper Rifle Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
NATO Ammunition Market
Weapons and Ammunition
Global Ammunition Market
Weapons and Ammunition
Electromagnetic Weapons Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
APAC Ballistic Missile Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Global E Bomb Market
Weapons and Ammunition
Vehicle Mounted Anti-Tank Missile System Market