
 Close-In Weapon Systems Market | 2026-2036
Close-In Weapon Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Close-In Weapon Systems Market Outlook
Naval surface combatant procurement is broadening the addressable base for close-in defense suites beyond legacy destroyer classes into frigates and amphibious vessels. RTX Corporation leverages its Phalanx installed base to sustain recurring modernization revenue streams across allied fleets. BAE Systems anchors European supply through its Goalkeeper production line and regional support infrastructure. Leonardo S.p.A. competes in Mediterranean and Middle Eastern markets with integrated fire-control architectures.
Close-in weapon systems are automated, radar-directed defensive installations designed to detect, track, and engage incoming anti-ship missiles and aircraft at ranges typically under two nautical miles using high-rate-of-fire cannons or interceptor missiles. Their primary purpose is to provide a terminal layer of protection for naval vessels when outer and middle air-defense envelopes have been penetrated. Kinetic technology dominates current fleet deployments due to proven reliability against sea-skimming targets, while laser-based systems represent the fastest-growing segment as solid-state directed-energy sources achieve tactically relevant power thresholds. Naval Forces command the largest share of end-user demand, though Coast Guard adoption is expanding as patrol vessels face elevated asymmetric threats in contested littorals.
The U.S. Navy's Naval Sea Systems Command sets technical requirements through Aegis combat system integration standards, while NATO STANAG frameworks mandate interoperability across allied vessel classes. The U.S. Department of Defense and the U.K. Ministry of Defence both classify directed-energy weapon testing under accelerated acquisition pathways, compressing development-to-fielding timelines. Stakeholders must monitor whether congressional appropriations for shipbuilding sustain the hull-per-platform installation rate that underpins volume forecasts.
Market Dynamics
Directed-energy weapon maturation is compressing development cycles and forcing legacy kinetic system suppliers to accelerate laser integration roadmaps or risk displacement from naval modernization programs.
Growth Catalysts
- Anti-ship missile proliferation:Hypersonic and sea-skimming threats are driving layered defense procurement across NATO surface combatant fleets.
- NATO STANAG interoperability mandates:Standardized interface requirements are accelerating cross-border fleet modernization and system replacement cycles.
- Solid-state laser power scaling:Fiber and slab laser architectures are achieving tactically relevant output thresholds for terminal defense applications.
Market Restraints
- Directed-energy thermal management:Atmospheric attenuation and cooling infrastructure requirements limit effective engagement envelopes in maritime environments.
- Specialized gallium nitride foundry concentration:High-power radio frequency component supply concentrates among limited qualified semiconductor fabricators.
- Shipboard power budget competition:Laser systems draw from finite vessel electrical generation capacity, constraining simultaneous multi-system operation.
Strategic Opportunities
- Türkiye indigenous frigate programs:Domestic shipbuilding expansion creates demand for localized close-in defense integration and co-development partnerships.
- Coast Guard patrol vessel up-armoring:Littoral asymmetric threat elevation is extending addressable demand beyond blue-water naval forces.
- UK Dragonfire program acceleration:Ministry of Defence directed-energy testbed investments are compressing laser weapon fielding timelines.
Industry Challenges
- Combat system integration complexity:Aegis and comparable integrated air-defense architectures require extensive software validation for new weapon module incorporation.
- Directed-energy operator certification:Laser safety and engagement doctrine training lags behind hardware deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Close-In Weapon Systems Market |
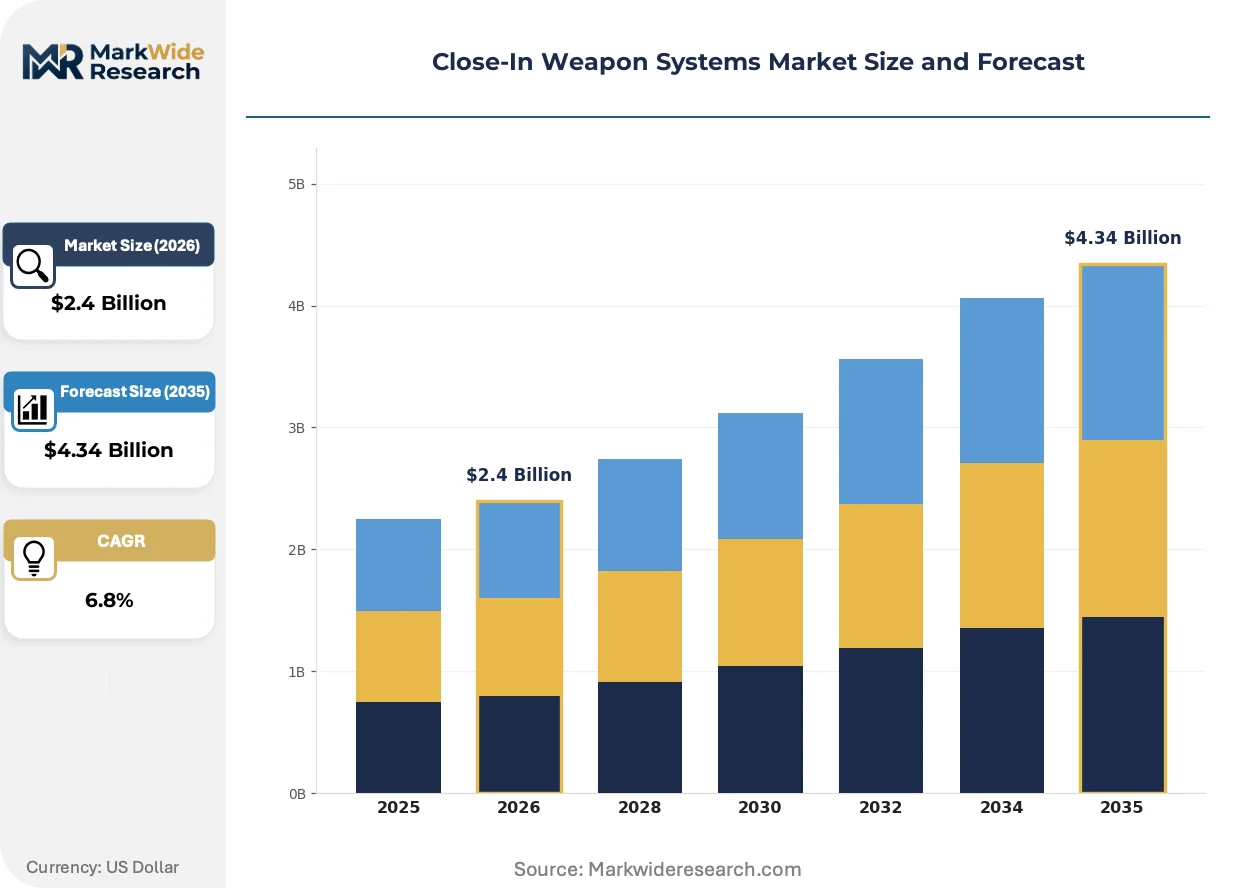
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phalanx CIWS, Goalkeeper, SeaRAM, LaWS Technology: Laser, Electromagnetic, Kinetic, Hybrid End User: Naval Forces, Air Force, Coast Guard, Defense Contractors Deployment: On-Ship, Land-Based, Mobile, Fixed |
| Companies Covered | RTX Corporation, BAE Systems, Leonardo S.p.A., Thales Group, Rheinmetall AG, General Dynamics Corporation, Northrop Grumman Corporation, ASELSAN A.S., Lockheed Martin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Close-In Weapon Systems Market Strategic Shifts
Naval terminal defense architectures are bifurcating between refined kinetic interceptors and emerging directed-energy suites, with procurement patterns increasingly favoring dual-capability platform designs.
Solid-state laser weapon systems are consolidating the directed-energy segment as chemical laser alternatives prove operationally impractical for shipboard deployment. Naval Sea Systems Command test programs are validating fiber laser architectures against representative anti-ship missile targets. This technology is consolidating supplier positions around firms with captive high-power beam control and thermal management expertise.
UK Ministry of Defence accelerated acquisition pathways are compressing directed-energy weapon development-to-fielding timelines for Dragonfire and follow-on programs. These frameworks bypass traditional procurement stages for mature subsystems. European naval forces are observing UK fielding results to inform parallel national laser weapon investments.
Service-life extension programs for existing Phalanx and Goalkeeper installations are unbundling from new-platform procurement, creating dedicated modernization revenue streams. Regional maintenance hubs are absorbing work previously centralized at original equipment manufacturer facilities. This pattern concentrates in United States and United Kingdom fleet support infrastructure where installed bases are largest.
Close-In Weapon Systems Market Segmentation
Segmentation reveals how procurement patterns diverge between legacy kinetic installations and emerging directed-energy platforms. Understanding these splits enables suppliers to align development roadmaps with fleet modernization priorities and interoperability mandates.
Product Type:
Technology specifications determine integration complexity and recurring revenue potential across naval modernization cycles.
- Phalanx CIWS:Radar-guided Gatling gun architecture firing tungsten penetrator rounds at rates exceeding 4,500 rounds per minute. The United States Navy sustains the largest installed base through service-life extension programs that unbundle hardware refresh from new hull procurement.
- Goalkeeper:30mm revolver cannon paired with integrated search-and-track radar for autonomous engagement. Royal Netherlands Navy and Royal Navy fleets anchor European demand for this Dutch-designed system.
- SeaRAM:Rolling Airframe Missile launcher combining Phalanx sensor suite with intercept missile firepower. Japan Maritime Self-Defense Force frigate programs represent concentrated adoption for layered terminal defense.
- LaWS:Fiber laser weapon system prototype validated against drone and small boat threats. U.S. Navy testbed deployments in the Persian Gulf inform solid-state laser scaling roadmaps.
Mature deployment sits with Phalanx CIWS. Newer deployment is concentrated in LaWS.
Technology:
Cost tiers separate field-proven kinetic systems from developmental directed-energy platforms requiring substantial shipboard power infrastructure.
- Kinetic:Gun-based and missile-based interceptors using chemical propellants or aerodynamic control surfaces. NATO STANAG interoperability mandates sustain cross-border procurement of these proven architectures.
- Laser:Solid-state fiber and slab laser generators achieving tactically relevant power densities for soft-kill and hard-kill applications. Atmospheric attenuation and thermal management constraints limit maritime engagement envelopes.
- Electromagnetic:Railgun and coilgun concepts leveraging Lorentz force for hypervelocity projectile acceleration. U.S. Navy research programs dominate funding concentration despite fielding delays.
- Hybrid:Dual-capability platforms combining kinetic backup with directed-energy primary engagement modes. United Kingdom Dragonfire program acceleration is compressing hybrid system development timelines.
Volume concentration favors Kinetic. Margin expansion concentrates in Laser.
End User:
Customer type dictates threat profile, procurement authority, and integration standards for combat system architects.
- Naval Forces:Blue-water surface combatant fleets requiring layered defense against anti-ship missile saturation attacks. U.S. Naval Sea Systems Command and U.K. Ministry of Defence procurement frameworks set technical requirements.
- Coast Guard:Littoral patrol vessels facing elevated asymmetric threats in contested near-shore environments. Turkish Coast Guard expansion programs represent emerging demand concentration.
- Air Force:Base air defense applications for expeditionary installations and fixed-site protection. Limited procurement scale relative to naval counterparts constrains supplier prioritization.
- Defense Contractors:System integrators and subsystem suppliers serving prime contractor supply chains. BAE Systems and Leonardo S.p.A. regional support infrastructure absorbs maintenance work from original equipment manufacturers.
Procurement authority sits with Naval Forces. Fastest addressable expansion is concentrated in Coast Guard.
Deployment:
Application context determines platform mobility requirements, power availability, and environmental hardening specifications.
- On-Ship:Integrated naval vessel installations with dedicated radar, fire control, and ammunition handling systems. Destroyer and frigate hull classes represent the primary installation substrate across allied fleets.
- Land-Based:Fixed-site terminal defense for critical infrastructure and expeditionary base protection. Limited procurement volume relative to maritime applications.
- Mobile:Vehicle-mounted or containerized systems for rapid repositioning. U.S. Army directed-energy prototyping programs explore ground-mobile laser configurations.
- Fixed:Permanent emplacements with hardened infrastructure and dedicated power generation. Coastal defense installations in the Eastern Mediterranean favor this deployment mode.
Installation scale sits with On-Ship. Technology maturation is concentrated in Mobile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of close-in weapon systems concentrates in defense-industrial bases with established naval supply chains, while fleet modernization demand distributes across NATO member states and Indo-Pacific allies expanding surface combatant procurement.
United States
Naval Sea Systems Command drives Phalanx modernization and directed-energy prototyping through Aegis integration standards. The U.S. Department of Defense accelerates laser weapon fielding via rapid acquisition pathways that compress development timelines. Consolidated manufacturing and test infrastructure clusters around naval shipyards in Virginia and California, where service-life extension programs absorb regional maintenance capacity.
United Kingdom
Royal Navy frigate replacement programs and the Dragonfire directed-energy testbed anchor procurement volume. The Ministry of Defence applies accelerated acquisition frameworks to compress laser weapon development-to-fielding cycles. Naval engineering concentration in Scotland and southern England supports Goalkeeper sustainment and hybrid system integration work.
Germany
Rheinmetall anchors European kinetic system supply through naval gun and ammunition production lines serving NATO fleets. Federal procurement offices coordinate cross-border STANAG interoperability compliance for frigate-class installations. Industrial concentration in North Rhine-Westphalia and Bavaria sustains component fabrication and combat system integration capabilities.
Japan
Japan Maritime Self-Defense Force frigate programs concentrate SeaRAM adoption for layered terminal defense against regional missile threats. The Ministry of Defense prioritizes indigenous integration with U.S.-origin sensor suites under bilateral alliance frameworks. Shipbuilding clusters in Nagasaki and Yokohama support domestic combat system installation and through-life support.
Türkiye
Indigenous frigate construction and Coast Guard fleet expansion create demand for localized close-in defense integration. ASELSAN drives co-development partnerships and domestic production capacity under national shipbuilding programs. Istanbul and Izmir harbor defense-industrial zones where system integration and regional support infrastructure are scaling.
Close-In Weapon Systems Market Competitive Environment
Top-tier vendors anchor platform-level integration, while subsystem specialists and regional integrators occupy supporting tiers. Market structure reflects defense procurement consolidation around primes with installed-base relationships and captive service networks. Two strategic archetypes dominate: legacy kinetic system incumbents with modernization revenue streams, and directed-energy entrants capturing next-generation procurement. Competitive moves concentrate on combat system integration partnerships and geographic licensing arrangements that secure fleet-wide sustainment contracts.
Within the legacy platform tier, RTX Corporation and BAE Systems occupy positions sustained by Phalanx and Goalkeeper installed bases across allied fleets. Leonardo S.p.A. represents the regional integration archetype, anchoring Mediterranean and Middle Eastern supply through fire-control architectures and maintenance infrastructure. These three exemplify how prime-contractor relationships with naval procurement authorities translate into recurring modernization and support revenue.
| Leading Market Players |
|---|
| RTX Corporation |
| BAE Systems |
| Leonardo S.p.A. |
| Thales Group |
| Rheinmetall AG |
| General Dynamics Corporation |
| Northrop Grumman Corporation |
| ASELSAN A.S. |
| Lockheed Martin Corporation |
| Others |
Value Chain & Pricing Dynamics
Gallium nitride wafer pricing indices cascade through close-in weapon system supply chains, compressing margins at component tiers while concentrating pricing power among foundries with qualified high-power RF fabrication capacity.
Pricing Analysis
Cost-down pressure on kinetic system suppliers accelerates as directed-energy prototypes divert procurement budgets toward solid-state laser development programs. Three-tier pricing structure across integrated platform, subsystem module, and component levels separates turnkey combat system installations from radar-only or fire-control-only procurements. Certification tier under NATO STANAG 4154 naval interoperability standards commands premium positioning against national-standard alternatives. Coast Guard patrol vessel buyers exhibit highest price sensitivity due to constrained capital budgets, while naval surface combatant programs prioritize performance over unit cost.
Supply Chain Analysis
Refurbishment flows for Phalanx and Goalkeeper installations create reverse-logistics revenue streams that sustain regional maintenance hubs in the United States, United Kingdom, and Netherlands. Gallium nitride substrates, high-power fiber laser generators, and precision radar components concentrate supply among qualified vendors in the United States, Germany, and Japan. Single-source vulnerability in specialized semiconductor foundries exposes prime contractors to allocation constraints during surge procurement cycles. Distribution runs through naval procurement authorities with captive service networks rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Close-in weapon system manufacturing is consolidating around primes with installed-base relationships as directed-energy maturation forces subscale kinetic suppliers toward exit or acquisition.
For Market Incumbents: Lock in fleet-wide sustainment contracts through regional maintenance hub expansion before laser weapon fielding displaces recurring modernization revenue. Deepen backward integration into gallium nitride component supply to defend against foundry allocation constraints during surge procurement cycles. Naval Sea Systems Command accelerated acquisition pathways compress windows for incumbent repositioning. For New Entrants and Emerging Players: Turkish Coast Guard patrol vessel programs represent an underserved buyer archetype with localized integration requirements and co-development partnership appetite. Indigenous shipbuilding expansion in Türkiye offers the most penetrable entry point against entrenched NATO supply relationships. Position around hybrid kinetic-laser architectures to capture procurement committees hedging between proven reliability and next-generation capability. For Investors and Strategic Acquirers: Distressed-cycle entries favor subsystem specialists with captive beam-control or thermal management expertise in Germany and the United Kingdom. Solid-state laser weapon scaling over the next decade will determine which mid-tier vendors achieve prime-contractor status versus component supplier capture. Monitor UK Ministry of Defence Dragonfire program fielding results as the inflection indicator for directed-energy procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Directed-Energy Integration Partnership | BAE Systems and Rheinmetall collaborations with UK Dragonfire compress hybrid system development timelines. |
| Regional Maintenance Hub Expansion | RTX Corporation Virginia and California facilities absorb service-life extension work previously centralized at OEM sites. |
| Indigenous Co-Development Agreement | ASELSAN partnerships with Turkish naval procurement authorities localize Goalkeeper-class integration under national frigate programs. |
| Gallium Nitride Foundry Qualification | Lockheed Martin captive semiconductor investments reduce allocation risk for high-power RF component supply. |
| Coast Guard Fleet Up-Armoring Contract | Leonardo S.p.A. Mediterranean support infrastructure captures Turkish patrol vessel demand beyond traditional naval channels. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with naval program executives, combat system integration engineers, and procurement officers at NATO member defense ministries. Secondary sources included U.S. Naval Sea Systems Command technical directives, UK Ministry of Defence accelerated acquisition pathway documentation, and STANAG interoperability standard revisions. Bottom-up hull installation forecasts triangulated against top-down defense budget appropriation analysis.
Segment-level granularity modeled technology type, deployment platform class, and end-user authority across the projection horizon. Kinetic versus directed-energy splits incorporated solid-state laser power scaling curves and thermal management maturation assumptions. CAGR derivation weighted shipbuilding procurement cycles against service-life extension program timing. Forecast inputs included congressional shipbuilding appropriation trajectories and directed-energy weapon testbed validation schedules.
Revisions become necessary when solid-state laser atmospheric attenuation thresholds shift, gallium nitride foundry capacity constraints intensify, or NATO STANAG interoperability mandates expand to include directed-energy interface standards. Practitioners should monitor UK Dragonfire program operational test results and U.S. Navy LaWS Persian Gulf deployment assessments for early signals of procurement acceleration or delay.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
Command Fuzes Market
Weapons and Ammunition
Large Caliber Ammunition Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Military Helmet Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Asia-Pacific Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Shoulder Fixed Weapons Market
Weapons and Ammunition
Decoy Flares Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Sonobuoy Launcher Market
Weapons and Ammunition
Airsoft Guns Market
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
Nuclear Bomb Market
Weapons and Ammunition
Martial Art Weapon Market