
 Mortar Ammunition Market | 2026-2036
Mortar Ammunition Market Size, Share, and Industry Trends Forecast 2026-2036
Mortar Ammunition Market Analysis
Modular payload configurations is consolidating buyer choice across the mortar ammunition landscape. Elbit Systems leverages integrated fire-control systems to differentiate its precision mortar offerings. Rheinmetall AG anchors European supply through scaled production of 120mm programmable rounds. Nammo AS specializes in insensitive munition formulations that meet evolving safety standards.
Mortar ammunition comprises fin-stabilized, high-angle projectiles fired from smoothbore tubes, typically containing high-explosive, smoke, illumination, or practice payloads with calibers ranging from 60mm to 120mm for indirect fire support. High Explosive rounds dominate procurement volumes, yet Illumination and precision-guided variants capture expanding margin pools as night operations and reduced collateral damage requirements intensify. Vehicle-Mounted delivery systems are displacing man-portable configurations in mechanized units, while 120mm caliber segments absorb the majority of modernization budgets across NATO forces.
The U.S. Department of Defense, NATO Standardization Office, and EU REACH frameworks collectively govern propellant chemistry, transport safety, and environmental discharge standards for mortar systems. These bodies restrict mercury-based primers and mandate insensitive munition compliance, forcing reformulation investments and certifying only qualified suppliers. Stakeholders must monitor divergence between U.S. military specification pathways and European environmental compliance timelines to anticipate qualification bottlenecks.
Market Dynamics
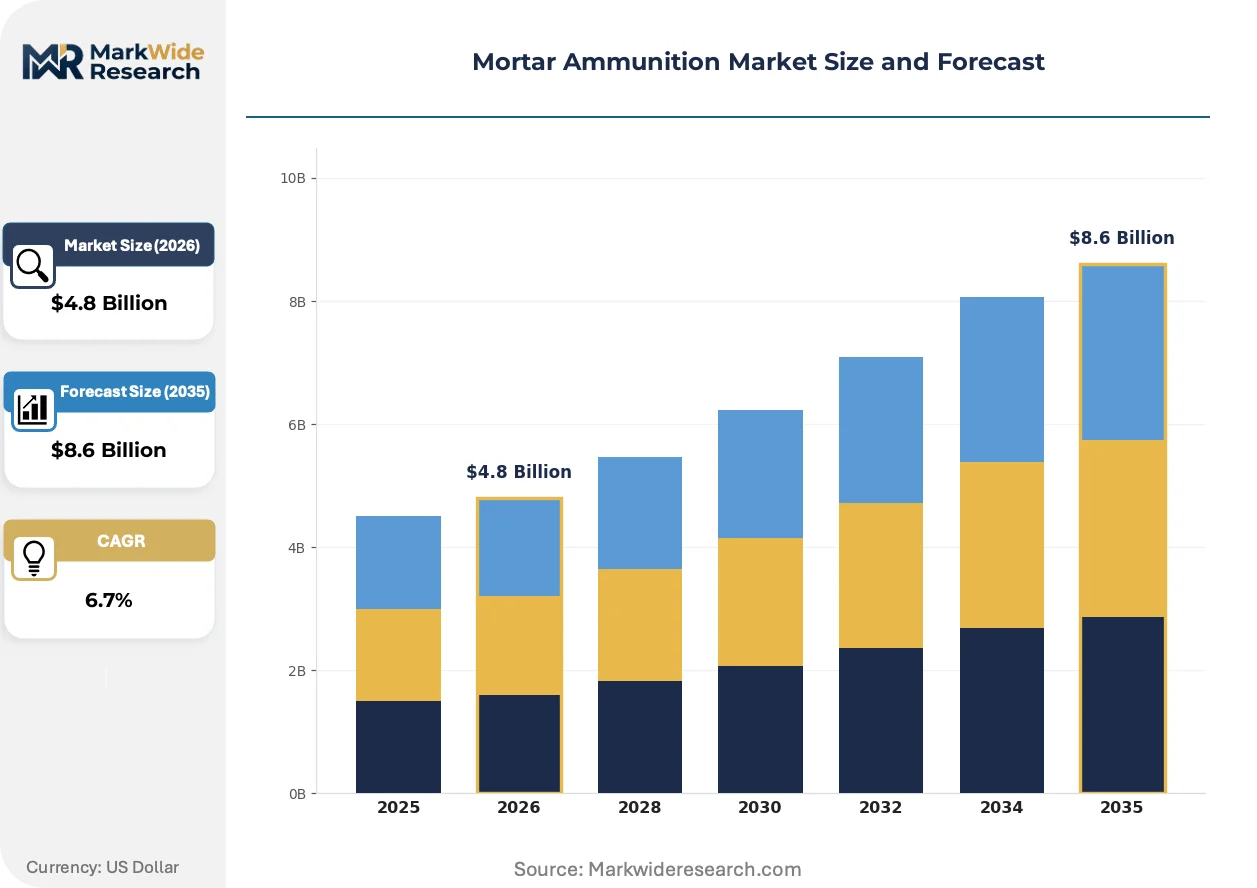
Precision-guided mortar rounds are compressing procurement cycles as NATO forces prioritize first-round effects over volume-based saturation fire, forcing manufacturers to reconfigure production lines toward smart fuze integration and reduced collateral damage payloads.
Growth Catalysts
- EU Green Deal environmental mandates:REACH-compliant propellant reformulation is opening qualification pathways for contractors who achieve mercury-free primer certification ahead of compliance deadlines.
- Vehicle-mounted 120mm systems:Mechanized infantry units across NATO are standardizing on turreted mortar carriers, creating sustained demand for ammunition optimized for automated loading and digital fire-control interfaces.
- Insensitive munition standards:IM compliance requirements under STANAG 4439 are pulling investment toward polymer-bonded explosives and reduced-sensitivity formulations that withstand cook-off scenarios.
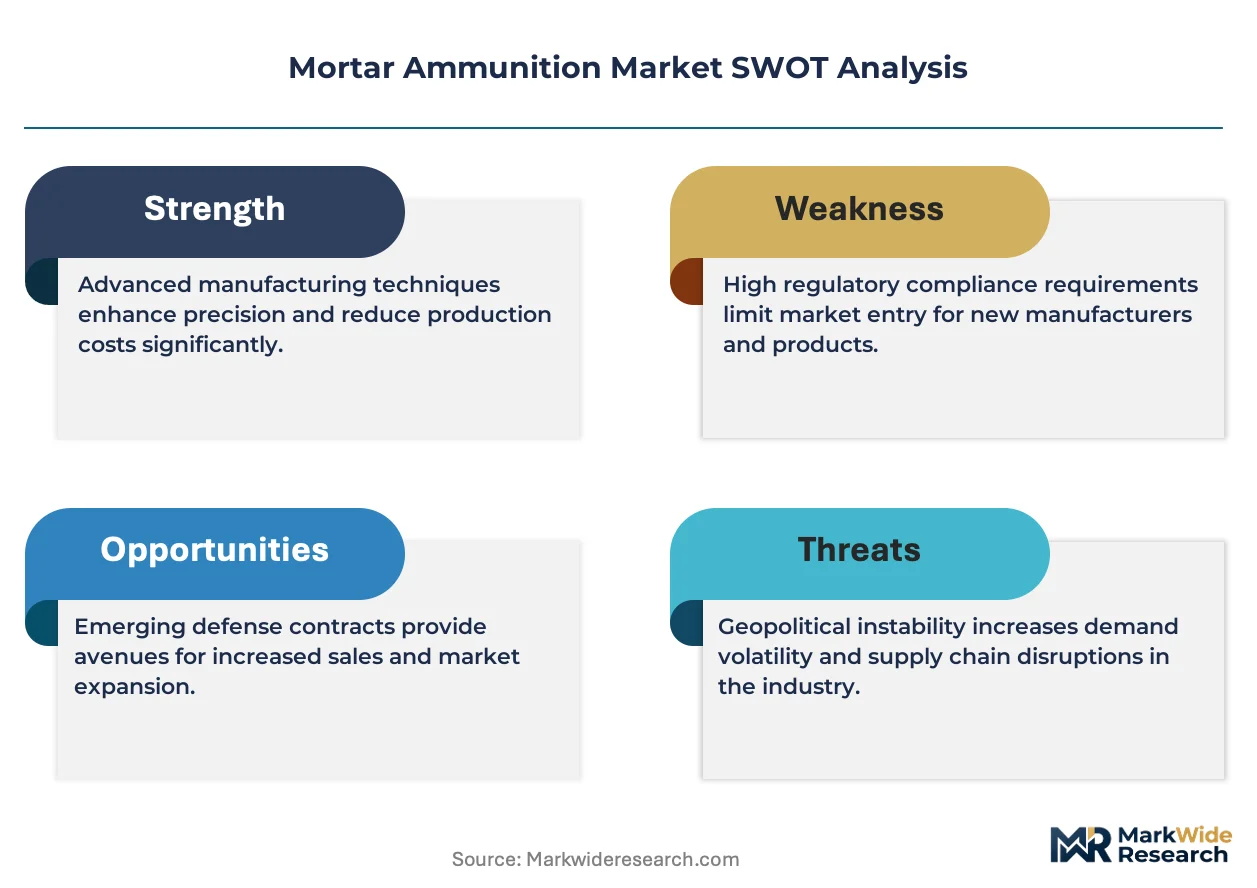
Market Restraints
- Nitrocellulose supply concentration:Single-source dependency on cotton linters and specialty cellulose from specific geographic clusters creates propellant cost volatility during agricultural commodity swings.
- Dual-use export control friction:ITAR and EU Common Position 2008/944/CFSP licensing timelines extend delivery schedules by 8-14 months for non-NATO customers, limiting addressable demand.
- Laser-guided round substitution:Precision artillery rockets with comparable range and accuracy are capturing missions previously assigned to extended-range mortar systems in brigade-level fires portfolios.
Strategic Opportunities
- Poland's territorial defense modernization:The country's accelerated 120mm procurement under its Homar program creates entry points for qualified suppliers meeting Polish Armed Forces technical requirements.
- AI-enabled target handoff:Convergence of drone-based spotting networks with mortar fire-control systems enables beyond-line-of-sight engagement against time-sensitive targets.
- US Army's Next Generation Indirect Fires:This program mandate for extended-range precision effects is incentivizing development of ramjet-assisted and glide-enabled mortar projectiles.
Industry Challenges
- Insensitive munition chemist scarcity:Formulation expertise in polymer-bonded explosive synthesis resides with a narrow cohort of specialists approaching retirement, constraining R&D throughput.
- Legacy fuze integration complexity:Smart mortar rounds must maintain compatibility with existing NATO inventory firing platforms, forcing redundant mechanical backup systems that add cost and failure modes.
- STANAG qualification timelines:NATO Standardization Office testing protocols for new ammunition variants require 18-24 months of live-fire validation, compressing product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mortar Ammunition Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Explosive, Smoke, Illumination, Practice Caliber: 60mm, 81mm, 120mm, 155mm End User: Military, Defense Contractors, Law Enforcement, Private Security Delivery Method: Man-Portable, Vehicle-Mounted, Shipborne, Aerial |
| Companies Covered | Elbit Systems Ltd, Northrop Grumman Corporation, General Dynamics Corporation, Thales Group, Nammo AS, BAE Systems plc, Saab AB, Leonardo S.p.A., Rheinmetall AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mortar Ammunition Market Emerging Trajectories
Digital fuze programming and net-centric fire control are converging to transform mortar systems from area weapons into precision strike assets, compressing sensor-to-shooter timelines and reshaping training and logistics requirements.
Multi-mode programmable fuzes are electrifying terminal effects selection. These devices combine proximity, point-detonation, and delay functions in a single package, selectable via induction programming at the muzzle. US Marine Corps expeditionary units are fielding these fuzes for urban operations where collateral damage constraints are absolute. The technology is electrifying demand for ammunition that adapts to target type without round substitution, compressing magazine diversity and simplifying supply chains.
EU REACH Annex XVII restrictions on lead styphnate primers are forcing chemistry transitions across European supply chains. The regulation mandates elimination of toxic initiator compounds in ammunition components by specified phase-out windows. Manufacturers serving French and German defense ministries are most affected, responding with diazodinitrophenol and tetrazene-based alternative formulations that require requalification under ECHA substance authorization procedures.
Consolidated multi-year framework agreements are displacing annual spot purchasing across NATO procurement offices. Defense ministries in Norway, Denmark, and the Netherlands are pooling ammunition orders through NSPA cooperative procurement mechanisms, reducing transaction costs but compressing supplier margins through volume concentration. This pattern is most visible in Nordic-Baltic defense cooperation structures where interoperability standardization precedes joint acquisition.
Mortar Ammunition Market Segmentation
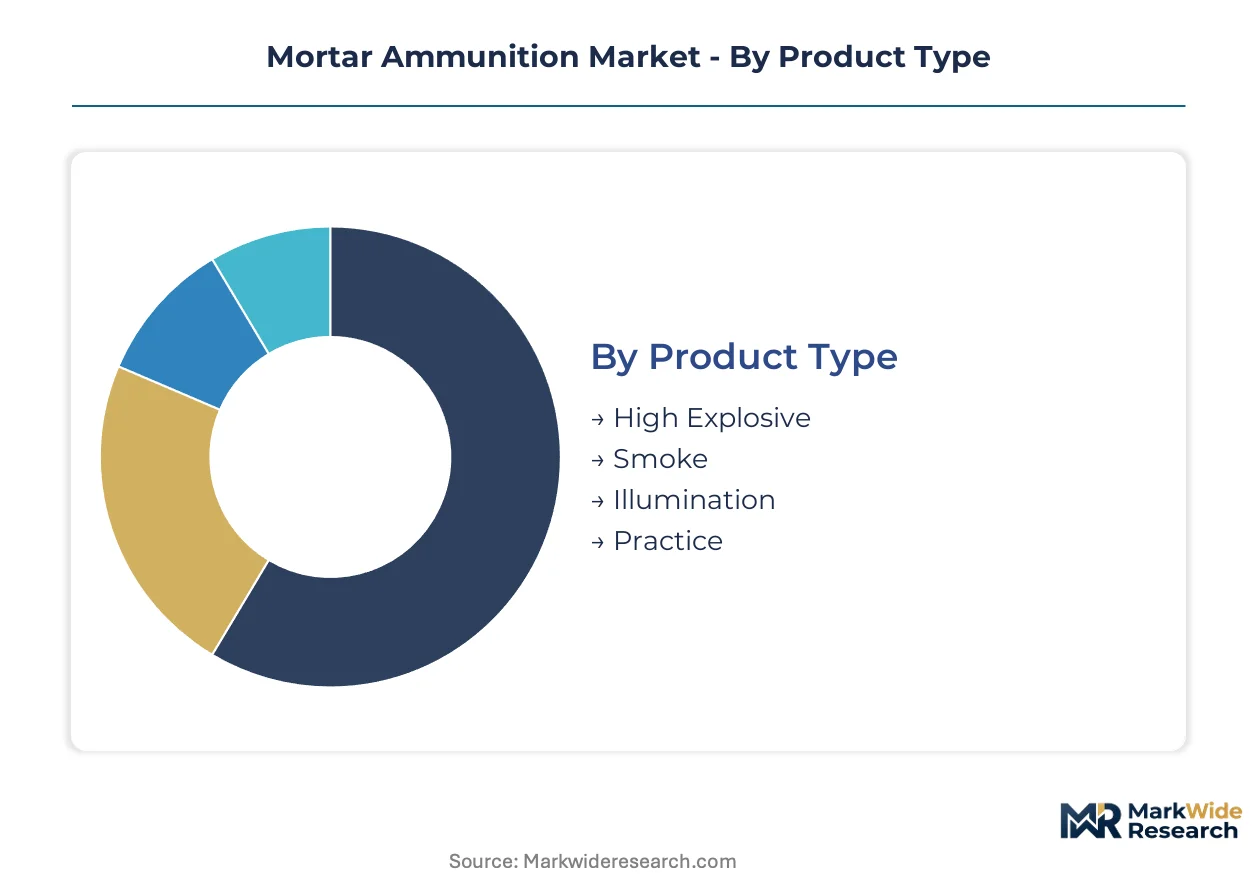
Mortar ammunition procurement follows distinct qualification pathways for each segment, with NATO STANAG standards and national military specifications creating divergent certification burdens across product categories. Defense ministries prioritize segments offering the clearest compliance routes to operational deployment.
Product Type:
STANAG 4172 and national insensitive munition certifications impose tiered validation requirements: High Explosive rounds face the most extensive live-fire protocols, while Practice variants qualify through abbreviated safety demonstrations.
- High Explosive:These fragmentation-optimized projectiles contain Composition B or TNT-based bursting charges designed for personnel and materiel destruction. U.S. Army and Marine Corps recapitalization programs concentrate procurement of 120mm HE rounds with programmable fuzes, driven by urban warfare requirements for reduced collateral damage. STANAG 4439 cook-off testing adds 18-24 months to qualification timelines.
- Illumination:Parachute-suspended magnesium flare payloads provide 60-90 second battlefield illumination at 600-800 meter deployment heights. NATO night operation tempo accelerates demand in Poland and Baltic states, where territorial defense exercises emphasize sustained nocturnal engagement capability. ECHA authorization requirements for pyrotechnic compositions complicate European supply.
- Smoke:White phosphorus or HC compound payloads generate visual obscuration for maneuver cover.
- Practice:Inert or reduced-range training rounds replicate ballistic profiles without explosive fill.
Leading the category by volume: High Explosive. Growing fastest: Illumination.
Caliber:
Production economics stratify sharply across bore diameters, with tooling amortization and propellant load scales determining viable supplier participation at each tier.
- 120mm:The NATO standard for mechanized infantry delivers maximum payload efficiency through automated loading systems. U.S. Army Next Generation Indirect Fires program and Polish Homar procurement anchor demand, with ramjet-assisted extended-range variants capturing development investment. Single-lot production runs exceed 10,000 units for major programs.
- 60mm:Lightweight platoon-level systems prioritize rapid emplacement and displacement for light infantry and special operations forces. U.S. Marine Corps expeditionary units and British Army airborne formations drive procurement of improved conventional munitions with enhanced fragmentation patterns. Man-portable weight constraints limit fuze sophistication.
- 81mm:Intermediate caliber serving company-level fire support in NATO and partner nation structures.
- 155mm:Artillery-class diameter occasionally adapted to heavy mortar platforms for extended range applications.
120mm absorbs the majority of modernization capital. 60mm climbing the fastest among expeditionary force structures.
End User:
Contractual vehicles and security clearance requirements segment addressable markets, with direct military procurement offering volume concentration and defense contractor channels providing technology insertion pathways.
- Military:National armed forces constitute the primary demand pool through defense ministry single-source and competitive awards. U.S. Army Program Executive Office Ammunition and NATO Support and Procurement Agency consolidate multi-year requirements, favoring suppliers with established NATO codification and existing security agreements.
- Defense Contractors:Prime system integrators and subsystem suppliers procure ammunition for platform integration testing, training package inclusion, and foreign military sale bundling. Rheinmetall and Elbit Systems maintain captive ammunition supply for vehicle-mounted mortar system deliveries, creating qualified supplier preference.
- Law Enforcement:Specialized tactical units in paramilitary organizations employ reduced-range illumination and smoke configurations.
- Private Security:Government-contracted protective services in high-threat environments access limited ammunition categories through licensed intermediaries.
Military channels dominate procurement value. Defense contractors expanding most quickly through platform-integrated ammunition bundling.
Delivery Method:
Platform integration requirements determine ammunition packaging, handling automation compatibility, and environmental sealing specifications for each deployment mode.
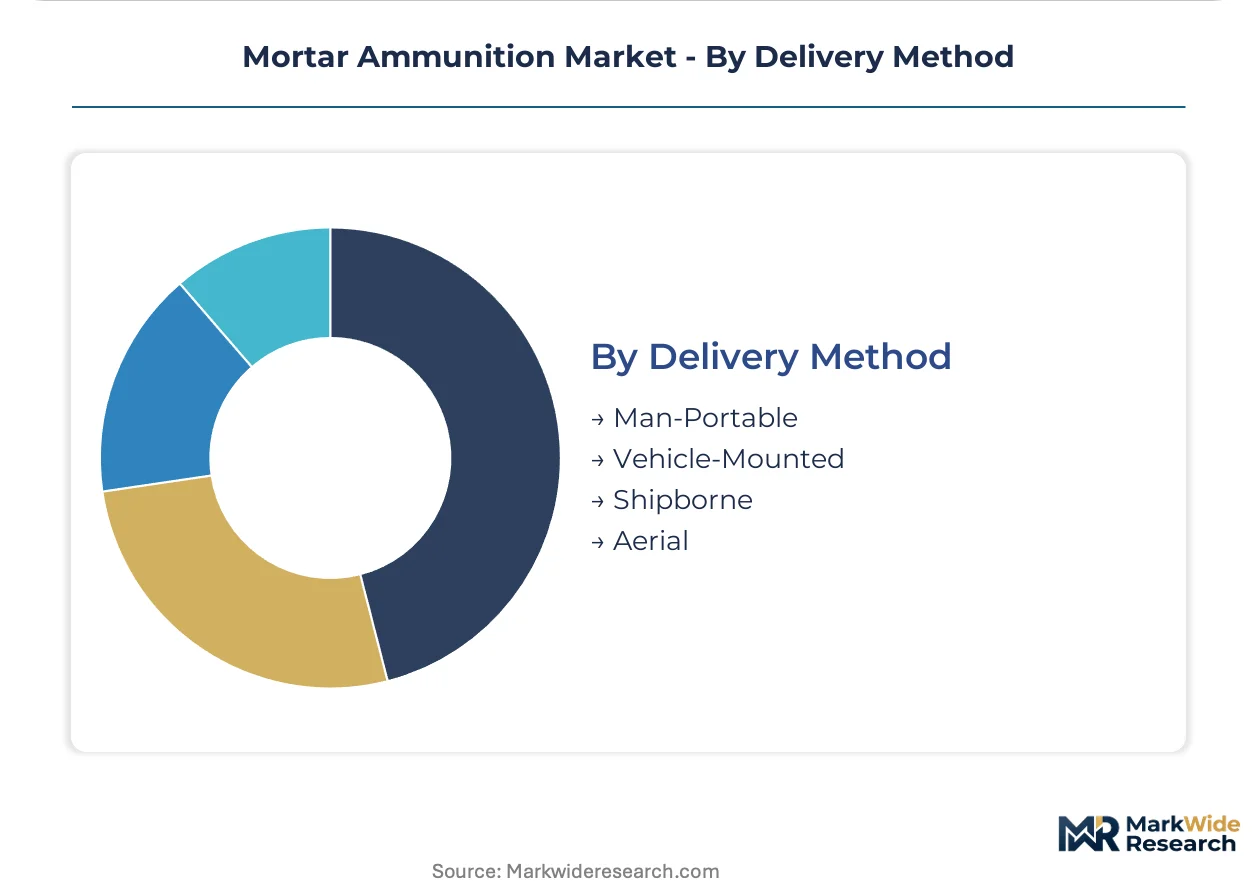
- Vehicle-Mounted:Turreted mortar carriers with automated ammunition handling systems demand packaging optimized for mechanical feed chutes and digital fire-control interface. NATO mechanized infantry standardization on 120mm turreted systems in Germany, France, and Poland creates sustained demand for qualified ammunition with NATO standardization agreement compliance.
- Man-Portable:Individual soldier transportable systems require lightweight packaging with manual handling compatibility for dismounted operations. U.S. Army light infantry and special operations forces maintain procurement of 60mm and 81mm configurations with reduced weight propellant charges and simplified fuze options.
- Shipborne:Naval amphibious platforms employ stabilized mountings with magazine-fed ammunition storage.
- Aerial:Helicopter and UAV delivery of precision mortar rounds remains developmental with limited operational deployment.
Vehicle-Mounted systems absorb the steepest procurement expansion. Man-Portable retaining foundational demand in light force structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of mortar ammunition concentrates in established defense industrial bases while procurement demand distributes across NATO member states and select partner nations. Manufacturing capacity clusters in countries with legacy propellant chemistry expertise and NATO standardization agreement compliance infrastructure. Consumption patterns track military modernization cycles and territorial defense investments.
United States
U.S. Army Program Executive Office Ammunition and Marine Corps Systems Command drive sustained procurement of 120mm precision-guided rounds. ITAR licensing frameworks restrict technology transfer to non-NATO customers. Tennessee and Iowa host propellant manufacturing clusters where contractors reformulate mercury-free primers under EPA discharge monitoring requirements.
Germany
Rheinmetall AG anchors European supply through scaled production of programmable 120mm rounds for Bundeswehr mechanized units. KBA vehicle safety regulations and EU REACH Annex XVII restrictions on lead styphnate primers force chemistry transitions across supply chains. Bavaria and Lower Saxony concentrate insensitive munition R&D facilities serving NATO standardization requirements.
Poland
Polish Armed Forces accelerate 120mm procurement under the Homar program for territorial defense modernization. National military specifications diverge from STANAG standards in fuze interface requirements. Warsaw and Łódź industrial zones attract qualified suppliers establishing localized production for NATO eastern flank commitments.
France
French Army vehicle-mounted mortar programs prioritize turreted 120mm systems with automated ammunition handling. ANSM and ECHA substance authorization procedures govern alternative primer formulations replacing lead-based initiators. Auvergne-Rhône-Alpes hosts pyrotechnic research clusters developing diazodinitrophenol-based ignition systems.
United Kingdom
British Army airborne formations sustain demand for 60mm man-portable configurations with enhanced fragmentation patterns. Ministry of Defence procurement consolidates multi-year framework agreements through NSPA cooperative mechanisms. Midlands defense industrial base maintains qualification pathways for STANAG 4439 insensitive munition compliance.
Mortar Ammunition Market Vendor Landscape
The competitive structure tilts toward integrated defense conglomerates with captive ammunition supply and established NATO codification. Tiered specialization separates precision-guided system integrators from commodity round manufacturers. Three archetypes dominate: platform-integrated suppliers bundling ammunition with vehicle systems, propellant chemistry specialists achieving REACH compliance ahead of deadlines, and insensitive munition formulators with polymer-bonded explosive expertise. Capacity expansion and strategic partnerships constitute the primary competitive moves as contractors position for Poland's Homar program and U.S. Next Generation Indirect Fires awards.
Among Israeli defense contractors, Elbit Systems Ltd exemplifies the platform-integrated archetype through fire-control system bundling. Rheinmetall AG occupies a central position in European 120mm programmable round supply. Nammo AS represents the chemistry-specialist tier with insensitive munition formulations meeting evolving safety standards.
| Leading Market Players |
|---|
| Elbit Systems Ltd |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| Thales Group |
| Nammo AS |
| BAE Systems plc |
| Saab AB |
| Leonardo S.p.A. |
| Rheinmetall AG |
| Others |
Supply Flow & Price Mechanics
Precision-guided and insensitive munition certification tiers bifurcate procurement economics, with STANAG 4439-compliant rounds commanding substantial premiums over conventional HE formulations while concentrating qualified supply among polymer-bonded explosive specialists in Germany, Norway, and the United States. This tier divergence compresses margins for commodity round manufacturers while rewarding REACH-compliant chemistry investments with sole-source positioning in Polish and Baltic defense tenders.
Pricing Analysis
Margin tightening in programmable fuze tiers reflects multi-mode induction programming costs and redundant mechanical backup systems required for NATO platform compatibility. Three-tier pricing structure across precision-guided, insensitive munition, and conventional HE levels tracks certification burden and volume scale, with Polish Homar program contractors least price-sensitive due to territorial defense urgency while Nordic NSPA pooled procurement exerts sustained cost-down pressure.
Supply Chain Analysis
Nitrocellulose propellant supply rests on cotton linters from specific agricultural clusters in the United States and China, with mercury-free primer chemistry drawing from diazodinitrophenol specialists concentrated in Germany and France. Single-source vulnerability in specialty cellulose feeds propellant cost volatility, while distribution runs through NATO Support and Procurement Agency cooperative mechanisms and direct defense ministry contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insensitive munition chemist scarcity and 18-24 month STANAG qualification timelines constrain capacity expansion, propping pricing power for qualified suppliers while compressing refresh windows for product development.
For Market Incumbents: Anchor market position through captive polymer-bonded explosive R&D facilities in Bavaria and Lower Saxony, defending against laser-guided artillery rocket substitution by accelerating ramjet-assisted mortar projectile development under U.S. Next Generation Indirect Fires specifications. Prioritize backward integration into mercury-free primer chemistry ahead of EU REACH Annex XVII phase-out deadlines. For New Entrants and Emerging Players: Launch via Polish Homar program localization partnerships, targeting Warsaw and Łódź industrial zones where national military specifications diverge from STANAG standards and create qualification entry points. Prioritize 60mm expeditionary force segments where man-portable weight constraints limit incumbent fuze sophistication and open margin capture for simplified illumination and smoke configurations. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-integrated defense conglomerates bundling fire-control systems with captive ammunition supply, with long-term viability hinging on REACH compliance infrastructure and NATO codification status. Watch for ramjet-assisted mortar projectile test results as inflection indicator for extended-range precision effects investment prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| Insensitive Munition Certification Investment | STANAG 4439 compliance unlocks sole-source positioning in NATO mechanized infantry tenders. |
| REACH-Compliant Primer Reformulation | Diazodinitrophenol chemistry transitions secure ECHA authorization for French and German defense ministry supply. |
| Polish Production Localization | Warsaw industrial zone facilities satisfy Homar program technical requirements and NATO eastern flank commitments. |
| Multi-Mode Programmable Fuze Integration | Induction programming at muzzle differentiates offerings for U.S. Marine Corps urban operations requirements. |
| NSPA Cooperative Procurement Alignment | Nordic-Baltic pooled ammunition orders reduce transaction costs but demand volume-scale manufacturing efficiency. |
Methodological Framework
Independent corroboration across defense ministry procurement officers, insensitive munition formulation chemists, and NATO Standardization Office qualification engineers underwrites the qualitative findings, validated against STANAG certification documentation, EU REACH Annex XVII regulatory filings, and U.S. Army Program Executive Office Ammunition budget justifications. Bottom-up segment sizing triangulates with top-down defense expenditure allocation analysis across the analysis window.
Comparable-period anchoring to historical NATO recapitalization cycles and U.S. Army modernization program timelines structures the projection horizon, with segmentation modeling across caliber tier, fuze sophistication level, delivery method, and national military specification cluster. CAGRs derive from propellant chemistry investment trajectories and vehicle-mounted system procurement rates, incorporating ITAR licensing timeline friction and ECHA substance authorization throughput as industry-specific forecast inputs.
Regulatory phase-out acceleration, nitrocellulose supply disruption, and precision artillery rocket mission capture are the dominant revision risks to the assumptions underlying these projections. A concentrated set of REACH enforcement actions, STANAG qualification backlog developments, and Polish territorial defense budget execution warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Automatic Weapons Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Asia-Pacific Cruise Missile Market
Weapons and Ammunition
Aircraft Weapons Market
Weapons and Ammunition
Americas Ballistic Missile Market
Weapons and Ammunition
Light Weapons Market
Weapons and Ammunition
Asia-Pacific Ammunition Market
Weapons and Ammunition
Small and Medium Caliber Ammunition Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Mortar Artillery System Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Man-Portable Rocket Launcher Market
Weapons and Ammunition
Directed Energy Weapons Market
Weapons and Ammunition
North America Small Arms Market